
 US Resilient Flooring Market | 2026-2036
US Resilient Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
US Resilient Flooring Market Intelligence
Premium wear-layer specifications above 20 mil is redrawing competitive positioning among domestic suppliers. Mohawk Industries leverages its integrated vinyl substrate production to control input costs across the Southeast manufacturing corridor. Tarkett SA anchors its position through specialized commercial-grade rubber flooring for healthcare and education end users. Shaw Industries Group differentiates via proprietary digital printing technology that expands design replication fidelity at scale.
Resilient flooring comprises engineered polymer-based surfacing materials, typically incorporating PVC, plasticizers, stabilizers, and wear-layer coatings, manufactured through calendering or extrusion processes to achieve defined thickness tolerances and dimensional stability under load. Luxury vinyl tile leads product type value generation due to superior water resistance and click-lock installation adaptability, while vinyl plank captures the fastest growth trajectory in residential replacement cycles. Glue-down installation dominates commercial new construction where subfloor preparation standards are controlled, though floating systems gain share in renovation applications requiring minimal surface disruption.
EPA regulations on formaldehyde emissions from composite wood products and OSHA workplace exposure limits for vinyl chloride monomer shape material sourcing and plant ventilation investments. California Air Resources Board standards extend influence beyond state boundaries through de facto national compliance by major manufacturers. The Federal Trade Commission's Green Guides constrain environmental marketing claims, requiring substantiated recycled content disclosures. Stakeholders must monitor evolving state-level extended producer responsibility legislation that could mandate post-consumer collection infrastructure and alter cost structures for imported versus domestically produced material.
Market Dynamics
California's Title 24 building energy standards and phthalate-free material mandates are compressing formulation timelines for domestic manufacturers while redrawing supply chain requirements across the Southeast production corridor.
Growth Catalysts
- Healthcare facility expansion:Hospital renovation cycles in Texas and Florida are specifying commercial-grade rubber flooring with enhanced infection control properties, pulling volume from traditional vinyl sheet alternatives.
- OSHA workplace exposure limits:Tighter vinyl chloride monomer thresholds are accelerating capital deployment toward closed-loop extrusion systems that reduce atmospheric emissions and liability exposure.
- Sun Belt multifamily construction:Luxury vinyl tile specifications are concentrating in Georgia and Arizona residential developments where moisture resistance and rapid installation offset labor cost premiums.
Market Restraints
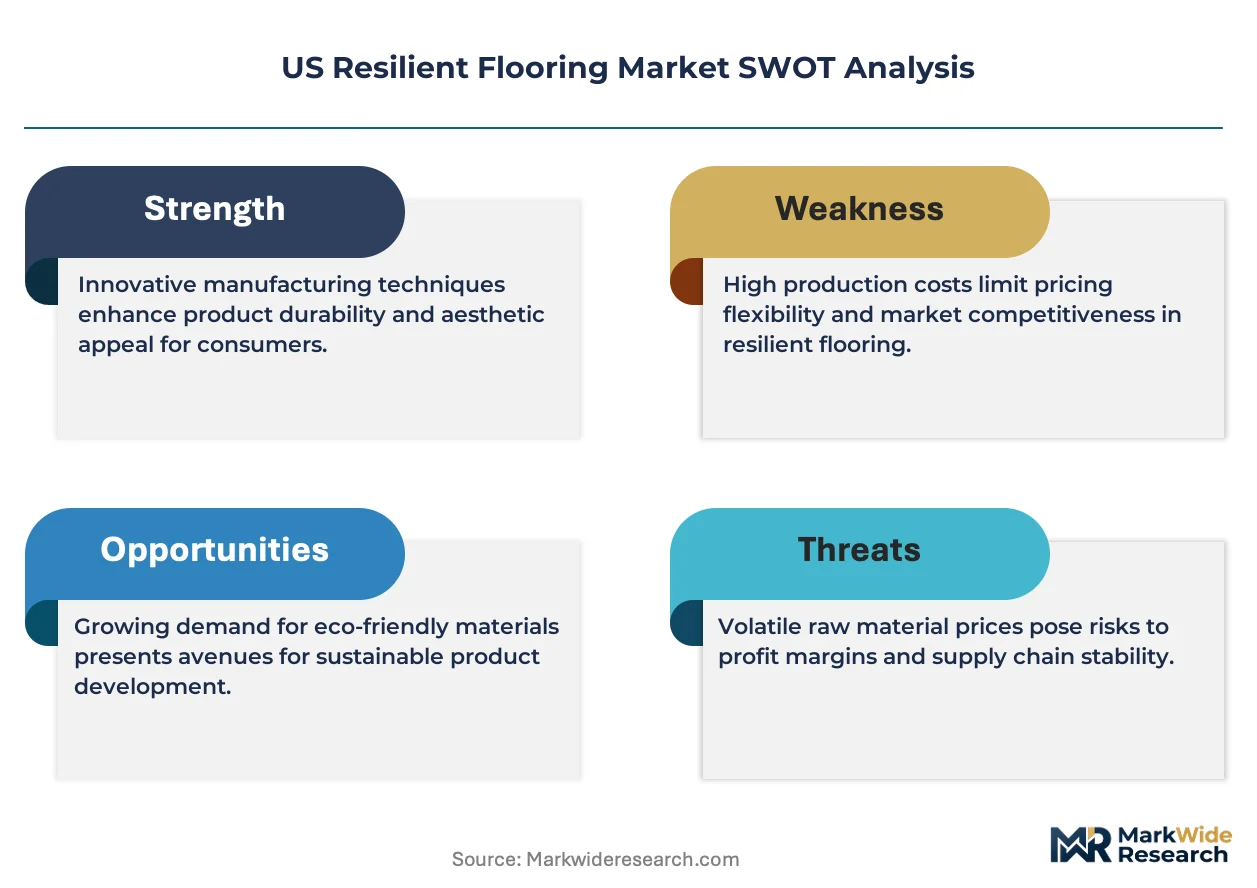
- Plasticizer cost volatility:DINP and DOTP feedstock prices tied to propylene supply swings are compressing margin stability for calendering operations dependent on external chemical sourcing.
- Southeast manufacturing concentration:Over 60% of domestic vinyl substrate capacity clusters within a 400-mile radius, creating hurricane exposure and logistics chokepoint vulnerability.
- Formaldehyde emission standards:EPA composite wood product regulations extend compliance burdens to flooring underlayment and substrate materials, raising testing and certification overhead.
Strategic Opportunities
- Post-consumer collection infrastructure:Extended producer responsibility legislation advancing in New York and Illinois could create first-mover advantages for domestic producers with closed-loop recycling capabilities.
- Digital printing convergence:Integration of high-resolution ceramic inkjet systems with rigid core extrusion lines is enabling batch-size-one customization for hospitality and retail specification channels.
- Renovation channel penetration:Floating click-lock systems are capturing share in residential replacement cycles where subfloor condition uncertainty discourages glue-down specification.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for phthalate-free plasticizer alternatives is concentrating among a narrow cohort of specialists, extending R&D cycle timelines.
- FTC Green Guides compliance:Substantiated recycled content documentation requirements are forcing reconfiguration of supplier audit protocols and marketing claim verification systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Resilient Flooring Market |
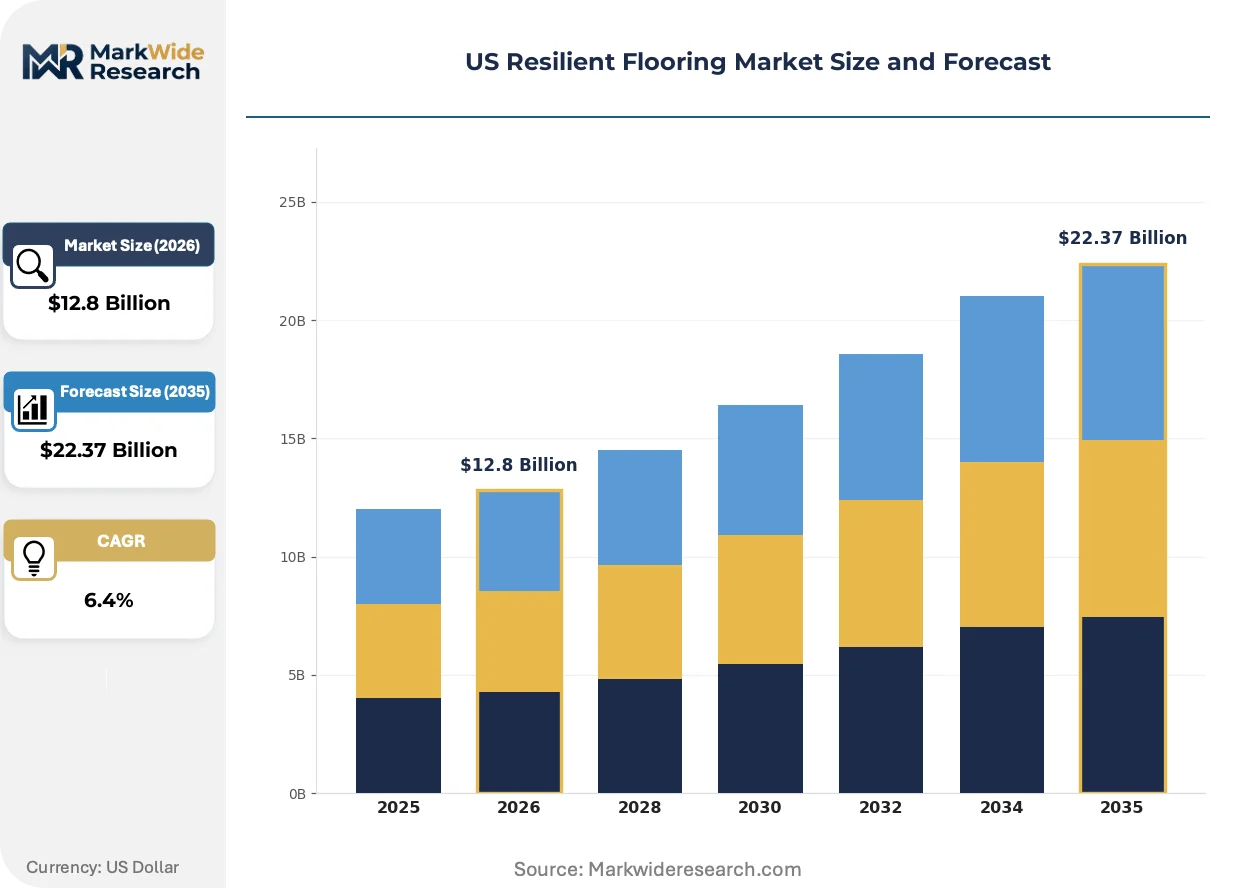
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Vinyl Tile, Vinyl Sheet, Vinyl Plank, Rubber Flooring Installation Type: Glue-down, Floating, Loose Lay, Interlocking End User: Residential, Commercial, Institutional, Industrial Thickness: 2mm, 3mm, 4mm, 5mm |
| Companies Covered | Mohawk Industries, Tarkett SA, Shaw Industries Group, Mannington Mills, Forbo Flooring Systems, Interface, Armstrong Flooring, Gerflor, AHF Products, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Resilient Flooring Market Strategic Shifts & Innovations
Material science advances and regulatory compression are simultaneously enabling performance tier fragmentation and shortening product development cycles across residential and commercial specification channels.
Photoinitiator-cured UV coatings are decomposing the traditional 20-mil wear-layer threshold as a meaningful quality signal. Healthcare and education specifiers are adopting 12-mil systems with ceramic bead reinforcement at comparable abrasion resistance. This technology is decomposing premium pricing power for legacy suppliers invested in conventional high-mil calendering equipment.
California Air Resources Board standards are extending de facto national compliance boundaries through manufacturer consolidation decisions. Major producers are standardizing to CARB thresholds rather than maintaining dual formulation streams. Flooring products destined for Texas and Florida markets now routinely incorporate California-mandated low-VOC adhesives and substrates.
Specification influence is migrating from general contractors to facilities management departments with total-cost-of-ownership modeling capabilities. Institutional buyers in Georgia and North Carolina are unbundling installation from material procurement, compressing distributor margin capture. This pattern is most visible in healthcare systems executing multi-site standardization programs across Sun Belt metropolitan clusters.
US Resilient Flooring Market Segmentation
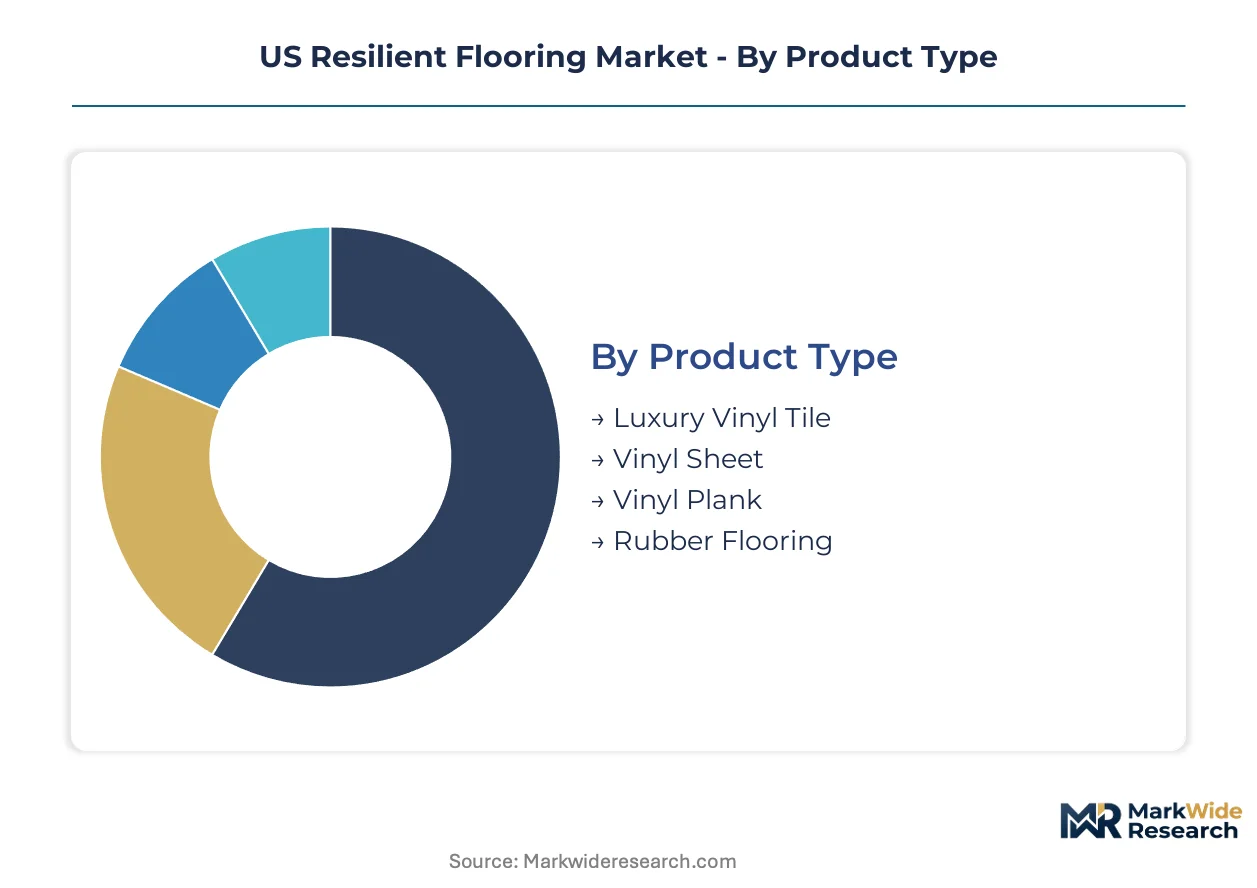
Segmentation in the US Resilient Flooring Market reveals how product specifications, installation methods, and end-use requirements fragment procurement decisions across distinct value tiers. Understanding these divisions exposes where substitution pressures and margin compression concentrate.
Product Type:
Substitution pressure from ceramic tile and engineered hardwood is reshaping competitive dynamics most acutely in residential-facing segments where water resistance and installation speed determine specification outcomes.
- Luxury Vinyl Tile:Multi-layer construction incorporates a rigid core, printed design layer, and protective wear coating. Hospital renovation cycles in Texas and Florida are specifying luxury vinyl tile with enhanced infection control properties, pulling volume from traditional vinyl sheet alternatives in healthcare corridors.
- Vinyl Plank:Elongated plank format mimics hardwood aesthetics through high-fidelity digital printing. Sun Belt multifamily construction in Georgia and Arizona is concentrating specifications here where moisture resistance and rapid click-lock installation offset labor cost premiums.
- Vinyl Sheet:Continuous roll format delivers seamless surfacing for moisture-prone environments.
- Rubber Flooring:Polymer-bound composition offers superior impact absorption and slip resistance for high-traffic institutional settings.
Luxury vinyl tile retains volume leadership; vinyl plank holds the steepest expansion curve.
Installation Type:
Cost tier stratification separates premium specification channels from mass-market residential replacement, with labor intensity and subfloor preparation requirements driving the wedge.
- Glue-down:Permanent adhesive bonding demands rigorous subfloor preparation and skilled application. Commercial new construction in controlled subfloor environments dominates this specification tier where dimensional stability under load is paramount.
- Floating:Click-lock edge profiles enable installation without adhesive attachment. Renovation applications across Sun Belt states are capturing share here where subfloor condition uncertainty discourages glue-down commitment.
- Loose Lay:Friction-backed systems rely on perimeter anchoring and dimensional mass for stability.
- Interlocking:Mechanical connection systems accommodate rapid deployment and future reconfiguration.
Glue-down systems command premium specification in new construction; floating installations are expanding most quickly in renovation channels.
End User:
Application maturity varies sharply, with established commercial specification protocols contrasting against emerging industrial performance requirements.
- Commercial:Office, retail, and hospitality environments prioritize wear-layer durability and design flexibility. Healthcare facility expansion in Texas and Florida is specifying commercial-grade systems with enhanced infection control properties.
- Residential:Single-family and multifamily housing emphasizes water resistance and installation speed. California's Title 24 building energy standards are compressing formulation timelines for products destined for this channel.
- Institutional:Education and government facilities demand extended lifecycle performance under heavy traffic loads.
- Industrial:Manufacturing and warehouse environments require chemical resistance and static control properties.
Commercial applications retain volume leadership; residential replacement cycles hold the steepest expansion curve.
Thickness:
Supply concentration in Southeast manufacturing corridors links thickness specification directly to substrate sourcing economics and freight optimization.
- 4mm:Mid-range specification balances dimensional stability with material efficiency. Georgia and Arizona residential developments are standardizing on this thickness for luxury vinyl tile installations where subfloor irregularities require accommodation.
- 5mm:Maximum rigidity specification supports extended wear-layer integration. Healthcare and education specifiers in North Carolina are adopting these systems for total-cost-of-ownership modeling across multi-site standardization programs.
- 2mm:Economy-tier specification for cost-sensitive applications with minimal subfloor challenges.
- 3mm:Entry-level rigid core format for residential replacement cycles with moderate traffic expectations.
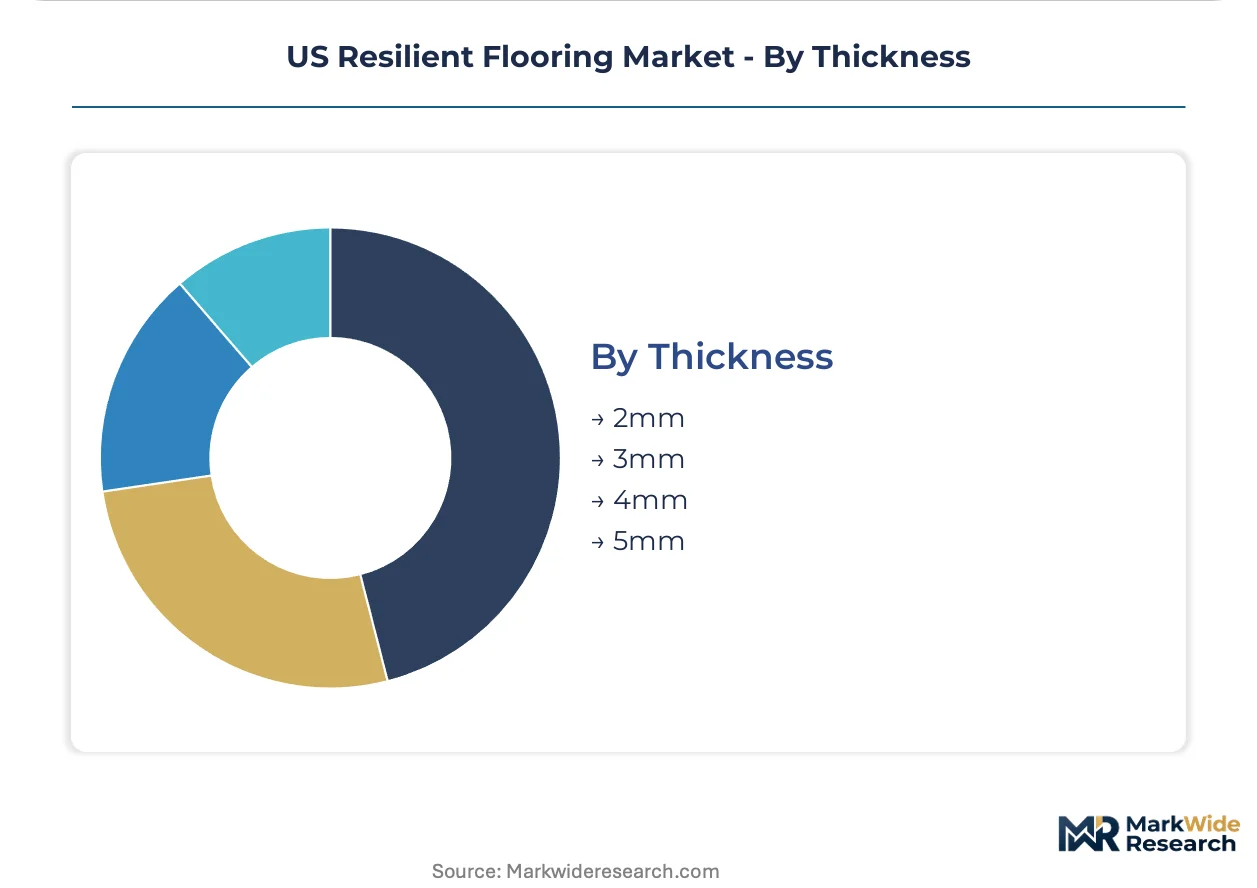
4mm specifications retain volume leadership; 5mm systems hold the steepest expansion curve in institutional channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast manufacturing corridors concentrate over sixty percent of domestic vinyl substrate capacity within a four-hundred-mile radius, creating hurricane exposure and logistics chokepoint vulnerability that shapes regional procurement patterns.
Texas
Hospital renovation cycles in Dallas-Fort Worth and Houston are specifying commercial-grade rubber flooring with enhanced infection control properties, pulling volume from traditional vinyl sheet alternatives. EPA formaldehyde emission standards extend compliance burdens to flooring underlayment materials. The I-35 corridor from San Antonio to Dallas anchors distribution networks serving healthcare systems executing multi-site standardization programs.
Florida
Healthcare facility expansion in Tampa and Orlando is outpacing national averages for commercial-grade resilient flooring specifications. OSHA workplace exposure limits for vinyl chloride monomer are accelerating capital deployment toward closed-loop extrusion systems. Miami-Dade logistics hubs handle imported substrate materials for regional calendering operations.
Georgia
Sun Belt multifamily construction in Atlanta and Savannah is concentrating luxury vinyl tile specifications where moisture resistance and rapid installation offset labor cost premiums. California Air Resources Board standards extend de facto national compliance through manufacturer consolidation decisions. The Dalton manufacturing cluster processes rigid core substrates for distribution throughout the Southeast.
California
Title 24 building energy standards and phthalate-free material mandates are compressing formulation timelines for products destined for residential replacement cycles. The Federal Trade Commission's Green Guides constrain environmental marketing claims, requiring substantiated recycled content disclosures. Los Angeles and San Diego metropolitan areas drive specification influence toward facilities management departments with total-cost-of-ownership modeling capabilities.
Arizona
Residential developments in Phoenix and Tucson are standardizing on four-millimeter luxury vinyl tile thickness where subfloor irregularities require accommodation. Extended producer responsibility legislation advancing in neighboring states is creating first-mover advantages for producers with closed-loop recycling capabilities. The I-10 corridor connects manufacturing inputs from Texas with western distribution networks.
US Resilient Flooring Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with integrated substrate producers controlling input costs while specialized commercial-grade suppliers anchor premium specification channels. The market structure consolidates around three to five dominant domestic manufacturers with captive vinyl production, surrounded by fragmented import-dependent distributors serving renovation channels. Strategic archetypes include integrated polymer producers, specialized healthcare-education specifiers, and digital printing technology differentiators. Dominant competitive moves center on backward integration into vinyl substrate production and proprietary coating technology licensing.
Among the integrated manufacturing tier, Mohawk Industries and Shaw Industries Group represent the scale-driven archetype with captive supply chain control, while Tarkett SA occupies a position exemplifying specialized commercial-grade positioning for institutional end users.
| Leading Market Players |
|---|
| Mohawk Industries |
| Tarkett SA |
| Shaw Industries Group |
| Mannington Mills |
| Forbo Flooring Systems |
| Interface |
| Armstrong Flooring |
| Gerflor |
| AHF Products |
| Others |
Cost & Logistics Intelligence
California Air Resources Board standards gate both supplier qualification and price differentiation simultaneously, forcing domestic manufacturers to absorb compliance costs that separate certified premium tiers from uncertified imports while compressing margin buffers across all specification levels.
Pricing Analysis
EPA formaldehyde emission standards dictate the pricing tier structure by imposing certification overhead that stratifies products across premium certified, standard compliant, and economy import tiers. Price differentiation rests on wear-layer thickness specifications and CARB compliance status rather than brand positioning alone. Cost compression in the economy tier is intensifying because Southeast manufacturing concentration limits alternative sourcing options. Residential replacement buyers exhibit highest price sensitivity, while healthcare facility procurement departments with total-cost-of-ownership modeling show lowest sensitivity.
Supply Chain Analysis
Just-in-time inventory preferences dominate raw material procurement for vinyl substrate and plasticizer feedstocks, though strategic stockpiling of rigid core materials is emerging among manufacturers hedging against propylene supply swings. Supply concentrates in the United States, with over sixty percent of domestic vinyl substrate capacity clustering within Southeast manufacturing corridors. Raw material dependencies center on PVC resin, DINP and DOTP plasticizers, and calcium carbonate fillers. Single-source vulnerability from hurricane exposure in the Gulf Coast region threatens logistics continuity. Distribution runs through Dalton, Georgia-based manufacturing clusters serving regional distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
US Resilient Flooring Market expansion represents a high-growth disruption as phthalate-free formulation mandates and UV-cured coating technologies simultaneously compress development cycles and fragment performance tiers.
For Market Incumbents: Shield market position by deepening captive vinyl substrate production to offset plasticizer cost volatility, and accelerate closed-loop recycling capability investment ahead of extended producer responsibility legislation in New York and Illinois. Prioritize certification maintenance against evolving CARB and OSHA thresholds to preserve specification access in healthcare and education channels. For New Entrants and Emerging Players: Differentiate on digital printing customization capabilities for hospitality and retail specification channels where batch-size-one production is displacing conventional high-volume runs. Target renovation channel penetration in Sun Belt states where floating click-lock systems are capturing share from glue-down alternatives. Pursue direct facilities management relationships to bypass consolidated distributor networks. For Investors and Strategic Acquirers: Extended producer responsibility legislation reshapes the acquisition landscape by privileging domestic producers with post-consumer collection infrastructure over import-dependent distributors. Long-term viability favors integrated manufacturers with captive substrate production and proprietary coating technology. Monitor state-level EPR adoption velocity as the primary inflection indicator for recycling asset valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vinyl Substrate Production | Mohawk Industries and Shaw Industries control input costs through captive Southeast manufacturing corridor capacity. |
| Closed-Loop Recycling Infrastructure Deployment | First-mover advantages accrue to domestic producers ahead of New York and Illinois extended producer responsibility mandates. |
| Digital Printing Technology Licensing | Proprietary ceramic inkjet systems enable batch-size-one customization for hospitality specification channels. |
| Phthalate-Free Formulation Transition | California Title 24 compliance creates de facto national standardization, compressing dual-formulation maintenance costs. |
| Floating Click-Lock System Expansion | Renovation channel penetration in Sun Belt states captures residential replacement cycles with minimal subfloor preparation. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with plant managers at Southeast manufacturing facilities, procurement leads at healthcare systems, distribution channel partners, and technical R&D directors specializing in polymer formulation; and secondary validation against EPA regulatory filings, OSHA exposure limit documentation, CARB standard updates, and SEC 10-K disclosures from listed flooring manufacturers. Bottom-up volume estimates from substrate production capacity and top-down demand triangulation from construction permit data were cross-referenced for convergence.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product type, installation method, end-user application, thickness specification, and regional construction activity patterns. CAGRs were derived from trend extrapolation of historical replacement cycle data and new construction permit trajectories. Key inputs included healthcare facility renovation pipeline tracking, multifamily housing starts in Sun Belt metropolitan clusters, and plasticizer feedstock price correlation models.
The analysis sits within stated boundaries; outcomes outside sustained commercial real estate development velocity or accelerated EPR legislative adoption would require recalibration. Forecasts reflect assumptions regarding regulatory enforcement consistency and raw material supply continuity. Revision becomes warranted when vinyl chloride monomer exposure threshold modifications or hurricane-related manufacturing disruptions cross materiality thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Global Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Textured Variegates Market
Flooring, Carpets, and Rugs
Wood Plastic Composite (WPC) Floorings Market
Flooring, Carpets, and Rugs
United Kingdom Floor Covering Market
Flooring, Carpets, and Rugs
GCC Flooring Market
Flooring, Carpets, and Rugs
India Vinyl Flooring Market
Flooring, Carpets, and Rugs
US Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
China Wood Flooring Market
Flooring, Carpets, and Rugs
ASEAN Laminate Flooring Market
Flooring, Carpets, and Rugs
Indoor Flooring Market
Flooring, Carpets, and Rugs
Wooden Floor Market
Flooring, Carpets, and Rugs
Turkey Carpet and Rugs Market
Flooring, Carpets, and Rugs
Bath Rugs and Mats Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tile (LVT) Flooring Market
Flooring, Carpets, and Rugs
Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Decorative Rugs Market