
 Brazil Returnable Transport Packaging Market | 2026-2036
Brazil Returnable Transport Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Returnable Transport Packaging Market Insights
ANVISA's strengthened traceability mandates for pharmaceutical distribution is rebalancing procurement priorities toward returnable container systems with embedded tracking capabilities. CHEP leverages its pooled pallet network to sustain fleet density across Brazilian automotive assembly plants. Schoeller Allibert anchors its position through specialized foldable large containers designed for tropical humidity cycles. ORBIS Corporation competes with injection-molded totes engineered for electronics cleanroom environments in Manaus Free Trade Zone operations.
Brazil returnable transport packaging comprises durable, multi-trip containers, pallets, and dunnage fabricated from high-density polyethylene, galvanized steel, or treated hardwood, designed to withstand repeated logistics cycles between suppliers and manufacturing facilities. Plastics dominates volume due to lower tare weight and washability compliance with food safety protocols, while metal commands premium positioning in automotive powertrain component loops where load ratings exceed 1,500 kilograms. Food & Beverage end users drive replacement frequency through sanitation-intensive wash cycles, whereas Electronics demand concentrates in custom container sizes fitted with electrostatic discharge protection for semiconductor component handling.
ANVISA regulates pharmaceutical packaging integrity standards, while CONMETRO oversees metrological certification for reusable load carriers in commercial trade. The Brazilian Association of Technical Standards (ABNT) publishes voluntary specifications for plastic pallet dimensional tolerances that major buyers increasingly mandate in procurement tenders. Stakeholders must monitor pending federal legislation on extended producer responsibility for packaging waste, as this could accelerate conversion from single-use corrugated solutions to pooled returnable assets across Brazilian supply chains.
Market Dynamics
ANVISA's pharmaceutical traceability mandates are forcing pharmaceutical distributors to replace single-use corrugated boxes with RFID-enabled returnable containers, compressing procurement cycles and reshaping supplier qualification criteria across Brazilian supply chains.
Growth Catalysts
- Automotive powertrain consolidation:Brazilian OEMs are mandating galvanized steel racks for engine block loops exceeding 1,500 kilogram load ratings, eliminating wooden alternatives from supplier parks in São Paulo's ABC industrial corridor.
- CONMETRO metrological certification:Mandatory recalibration protocols for reusable load carriers in commercial trade are standardizing fleet replacement schedules and locking in multi-year service contracts with pooling providers.
- Manaus Free Trade Zone electronics clustering:Semiconductor assembly operations are specifying electrostatic discharge-protected totes, creating dedicated container pools for cleanroom environments.
Market Restraints
- High-density polyethylene resin volatility:Feedstock price swings of 30-40% within fiscal quarters compress molding margins and destabilize rental rate forecasting for plastic pallet fleets.
- São Paulo industrial corridor supply concentration:Over 60% of pooled container assets concentrate within 200 kilometers of the state capital, creating vulnerability to regional logistics disruptions and port congestion.
- Galvanized steel corrosion in tropical cycles:Humidity-induced degradation limits metal rack lifespan in northern coastal states, forcing premature retirement before depreciation schedules complete.
Strategic Opportunities
- Minas Gerais dairy processing expansion:Sanitation-intensive wash-cycle container demand from cheese and yogurt producers remains underpenetrated relative to São Paulo's saturated protein processing sector.
- Extended producer responsibility legislation:Pending federal packaging waste laws would impose fees on single-use corrugated, accelerating conversion to pooled returnable assets across food retail distribution.
- RFID-embedded tracking convergence:Integration of passive sensor tags with blockchain verification protocols is opening pharmaceutical cold chain applications requiring temperature-logged container histories.
Industry Challenges
- Container fleet balancing mathematics:Pooling operators struggle to maintain asset availability ratios across seasonal agricultural harvests when soybean and orange juice export volumes create asymmetric container flows.
- ABNT dimensional tolerance enforcement:Voluntary plastic pallet specifications are hardening into de facto procurement mandates, requiring mold retooling investments that strain mid-tier fabricator balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Returnable Transport Packaging Market |
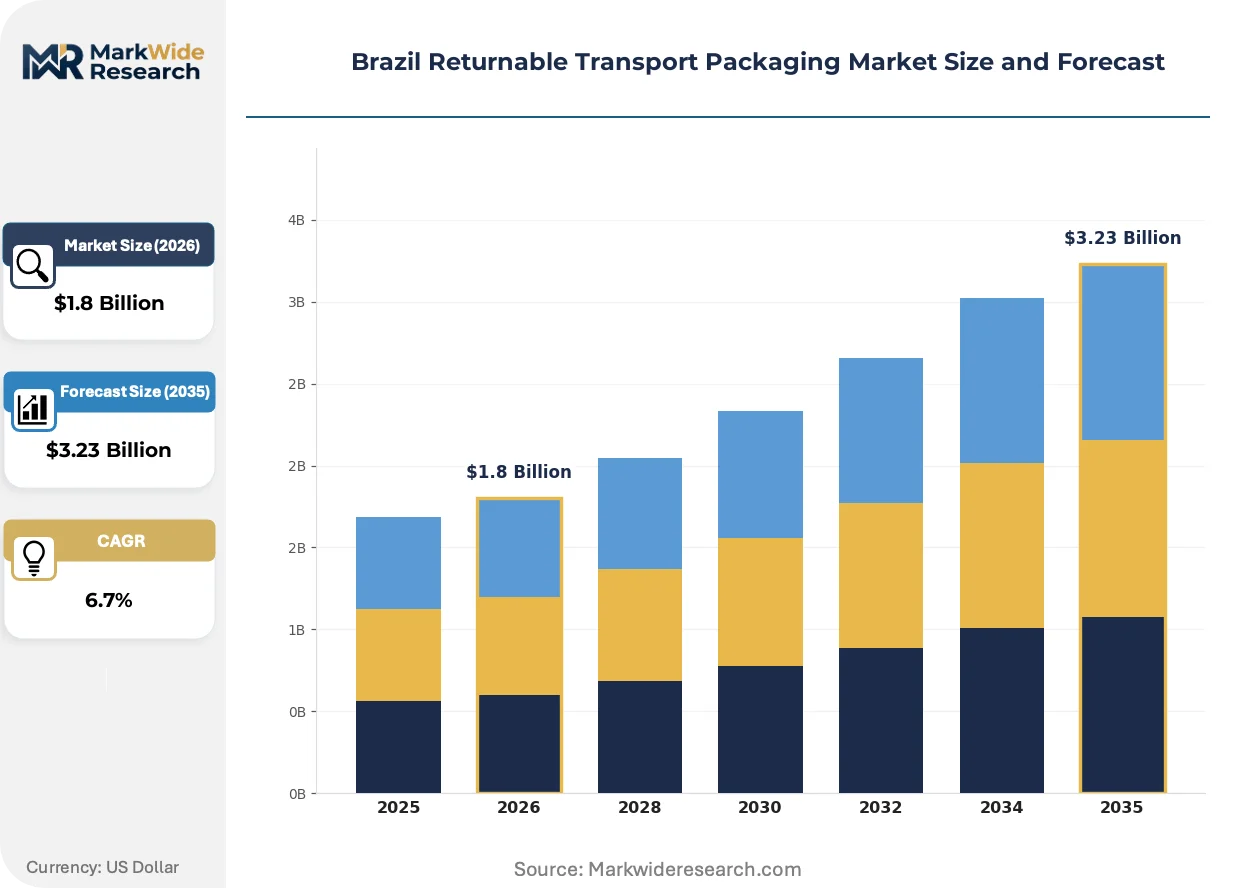
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastics, Metal, Wood, Fabric End User: Food & Beverage, Automotive, Pharmaceuticals, Electronics Container Size: Small, Medium, Large, Custom Distribution Channel: Direct Sales, Retail, Online, Others |
| Companies Covered | CHEP, Schoeller Allibert, ORBIS Corporation, Nefab Embalagens, IFCO Systems, Kuehne-Nagel Serviços Logísticos, Signode Brasileira, SSI Schaefer, George Utz, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Returnable Transport Packaging Market Trends and Innovations
Embedded sensor technology and tropical climate engineering are converging to differentiate container performance specifications, while regulatory pressure on pharmaceutical integrity is accelerating tracking infrastructure deployment across Brazilian logistics networks.
RFID-tagged container systems are decentralizing pharmaceutical distribution accountability by enabling real-time location verification without centralized depot scanning. ANVISA-regulated distributors in Rio de Janeiro and São Paulo are piloting passive UHF tags at pallet level, with adoption timelines compressing from five-year planning horizons to eighteen-month procurement cycles. This tracking infrastructure is decentralizing quality assurance responsibility from warehouse checkpoints to in-transit monitoring, reducing batch quarantine incidents.
Pending extended producer responsibility legislation is restructuring packaging procurement incentives by imposing waste fees on single-use corrugated equivalent to 15-20% of material value. Food retail chains operating national distribution centers are pre-positioning returnable container fleets ahead of regulatory enactment, with ABNT certification emerging as a tender prerequisite. Electronics manufacturers in Manaus are responding fastest, integrating container return clauses into supplier contracts that shift financial liability upstream.
Buyer consolidation among Brazilian protein processors is compressing container specification diversity toward standardized foldable large containers. JBS and BRF procurement teams are mandating Schoeller Allibert-compatible footprints across their supplier bases, displacing proprietary container formats that previously locked in regional fabricators. This standardization is most visible in Paraná's poultry processing belt, where third-party pooling services are displacing captive container fleets.
Brazil Returnable Transport Packaging Market Segmentation
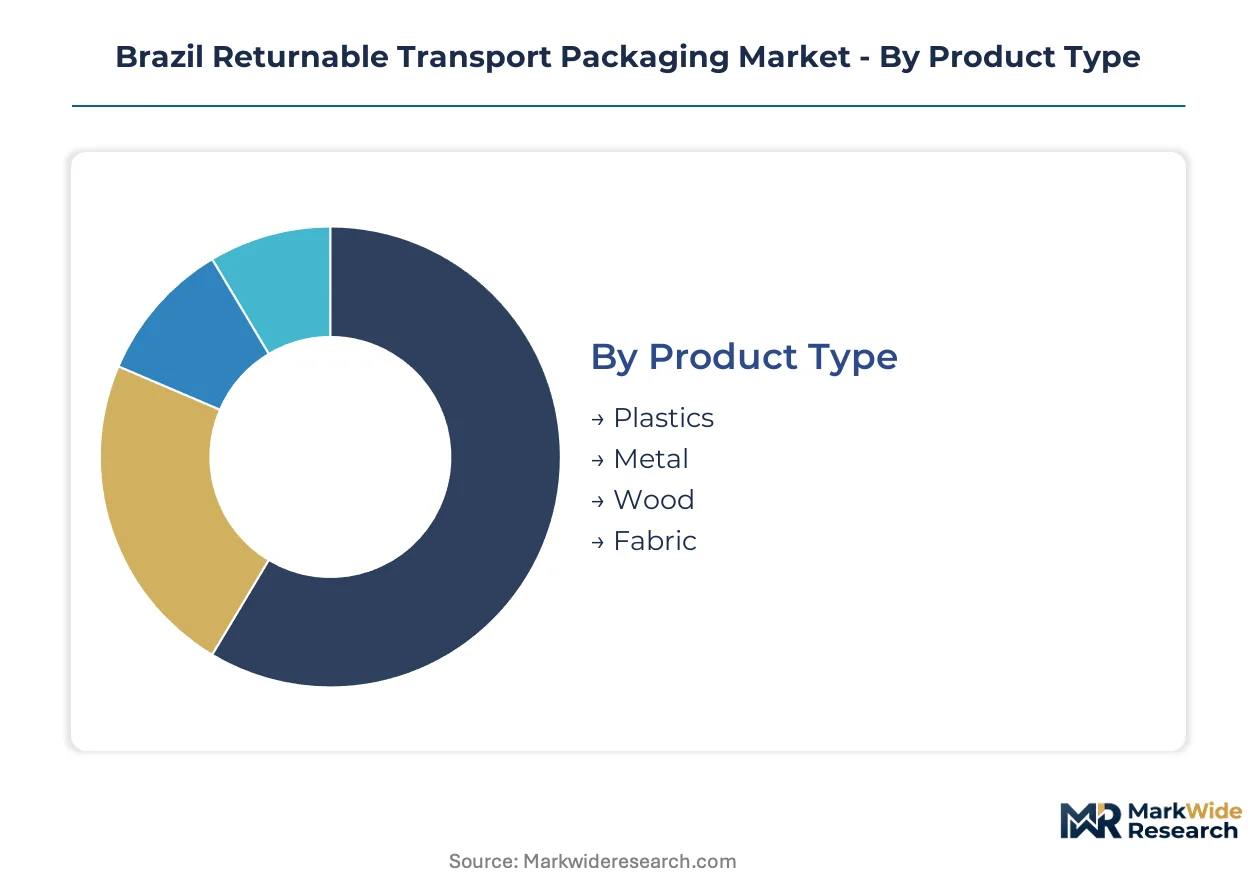
Segmentation in Brazil's returnable transport packaging market reveals how material specifications, end-use sanitation requirements, and container sizing interact with regional industrial clustering. Procurement patterns diverge sharply between São Paulo's automotive corridors and Minas Gerais dairy operations, forcing suppliers to maintain parallel fleet configurations.
Product Type:
Replacement cycles vary dramatically across material categories, with tropical humidity accelerating corrosion timelines for metal assets while extending plastic fleet depreciation schedules.
- Plastics:High-density polyethylene and polypropylene containers dominate volume through lower tare weight and washability compliance with ANVISA food safety protocols. São Paulo protein processors drive replacement frequency through sanitation-intensive cycles that degrade polymer integrity faster than automotive applications.
- Metal:Galvanized steel racks command premium positioning in automotive powertrain loops where load ratings exceed 1,500 kilograms. Northern coastal states force premature retirement due to humidity-induced degradation before depreciation schedules complete.
- Wood:Treated hardwood pallets retain niche presence in agricultural export corridors where single-trip economics persist despite pooling penetration elsewhere.
- Fabric:Collapsible textile bulk containers serve seasonal harvest surges in soybean and orange juice export flows where rigid asset deployment proves uneconomical.
Volume placements concentrate in Plastics; the faster expansion belongs to Metal as automotive OEMs consolidate supplier park specifications.
End User:
Customer procurement maturity spans captive fleet ownership, third-party pooling contracts, and hybrid models that shift financial liability upstream.
- Food & Beverage:Sanitation protocols mandate wash-cycle-intensive container utilization that accelerates asset degradation. JBS and BRF procurement teams are standardizing foldable large container footprints across supplier bases in Paraná's poultry belt.
- Automotive:Powertrain component loops require galvanized steel racks with precise dimensional tolerances. ABC industrial corridor OEMs are eliminating wooden alternatives through supplier park mandates.
- Pharmaceuticals:ANVISA traceability mandates are compressing procurement cycles toward RFID-enabled returnable systems with embedded temperature logging capabilities.
- Electronics:Semiconductor assembly operations in Manaus Free Trade Zone specify electrostatic discharge-protected totes for cleanroom environments.
Procurement scale peaks with Food & Beverage; contract velocity is climbing fastest in Pharmaceuticals as regulatory deadlines approach.
Container Size:
Standardization pressures from buyer consolidation are compressing specification diversity toward interoperable footprints compatible with third-party pooling networks.
- Small:Handheld totes and component bins serve electronics subassembly operations requiring frequent line-side replenishment cycles.
- Medium:Mid-scale containers balance manual handling ergonomics with cubic efficiency for mixed SKU distribution.
- Large:Foldable large containers anchor protein processor procurement specifications through stack density optimization in refrigerated transport.
- Custom:Engineered dimensions fitted with electrostatic discharge protection or pharmaceutical cold chain insulation command project-based pricing with extended qualification timelines.
Fleet deployment concentrates in Large formats; specification growth is steepest in Custom sizes as electronics and pharmaceutical applications proliferate.
Distribution Channel:
Channel selection reflects customer scale and technical specification complexity, with direct relationships dominating industrial accounts and transactional routes serving fragmented agricultural buyers.
- Direct Sales:Multi-year service contracts with pooling providers lock in fleet availability ratios and CONMETRO recalibration protocols for major automotive and protein processing accounts.
- Retail:Distributor networks extend reach to mid-tier fabricators lacking capital for captive fleet investment.
- Online:Digital procurement platforms are emerging for standardized pallet and tote specifications with rapid fulfillment timelines.
- Others:Cooperative purchasing arrangements aggregate demand among regional agricultural cooperatives.
Revenue concentration sits with Direct Sales; channel experimentation is expanding most aggressively through Online platforms targeting standardized specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's ABC industrial corridor concentrates the majority of pooled container demand, with automotive assembly plants and protein processors driving specification standardization across supplier networks.
São Paulo
Automotive powertrain loops and food processing operations dominate procurement volumes. ANVISA traceability mandates for pharmaceutical distribution are compressing RFID-enabled container adoption timelines. The ABC industrial corridor hosts JBS and BRF supplier parks where foldable large container specifications are hardening into procurement mandates.
Minas Gerais
Dairy processing expansion in cheese and yogurt production is creating underpenetrated demand for sanitation-intensive wash-cycle containers. CONMETRO metrological certification requirements are standardizing fleet replacement schedules for regional cooperatives. Belo Horizonte's logistics hub is emerging as a secondary pooling depot to reduce São Paulo concentration risk.
Paraná
Poultry processing belt operations are displacing captive container fleets with third-party pooling services. ABNT dimensional tolerance specifications are hardening into de facto procurement requirements across regional protein processors. Maringá and Londrina industrial zones are consolidating supplier base specifications toward interoperable footprints.
Rio de Janeiro
Pharmaceutical distributors are piloting passive UHF RFID tags at pallet level under ANVISA regulatory pressure. Temperature-logged container histories are opening cold chain applications for biotechnology shipments. Duque de Caxias logistics corridor is attracting pooling provider depot investments to serve port-linked distribution.
Manaus Free Trade Zone
Semiconductor assembly operations are specifying electrostatic discharge-protected totes for cleanroom environments. Electronics manufacturers are integrating container return clauses into supplier contracts that shift financial liability upstream. The free trade zone's isolated geography is creating dedicated container pools with distinct asset management economics.
Brazil Returnable Transport Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and fleet density dimensions. The vendor structure concentrates around three strategic archetypes: multinational pooling networks with established depot infrastructure, specialized container fabricators with tropical climate engineering capabilities, and logistics integrators bundling packaging with freight services. Competitive positioning is hardening through multi-year service contract lock-ins and ABNT certification pre-qualification requirements.
Within the multinational pooling tier, CHEP and IFCO Systems exemplify fleet density strategies built on depot network coverage. Schoeller Allibert and ORBIS Corporation occupy positions among specialized fabricators engineering containers for humidity cycles and cleanroom specifications. Nefab Embalagens anchors a regional logistics integrator archetype combining packaging assets with value-added services. These three groupings represent distinct margin structures and capital intensity requirements.
| Leading Market Players |
|---|
| CHEP |
| Schoeller Allibert |
| ORBIS Corporation |
| Nefab Embalagens |
| IFCO Systems |
| Kuehne-Nagel Serviços Logísticos |
| Signode Brasileira |
| SSI Schaefer |
| George Utz |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between CONMETRO-validated pooling contracts and unvalidated spot-market transactions splits pricing power across Brazilian logistics networks. Premium service tiers capture multi-year fleet availability guarantees while commodity tiers compete on per-trip transactional rates.
Pricing Analysis
Throughput-linked pricing anchors returnable container economics, with pooling providers charging per-rotation fees tied to guaranteed asset availability rather than unit ownership. Three-tier pricing structure across premium, standard, and economy levels separates RFID-enabled pharmaceutical-grade containers from basic food-grade totes and untreated wooden pallets. Cost compression in plastic resin-dependent tiers is intensifying because high-density polyethylene feedstock swings destabilize rental rate forecasting. Food retail chains show highest price sensitivity due to thin margins in protein processing, while pharmaceutical distributors under ANVISA deadline pressure accept premium positioning.
Supply Chain Analysis
Reverse-logistics infrastructure determines container economics, with depot density and refurbishment throughput capacity separating viable pooling operators from capital-constrained competitors. Manufacturing concentration in São Paulo, Minas Gerais, and Paraná feeds from domestic injection-molding capacity and imported steel coil for galvanized rack fabrication. Single-source vulnerability in resin supply creates exposure to petrochemical price cycles. Distribution runs through third-party pooling networks with dedicated depot infrastructure rather than direct manufacturer-to-user shipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's returnable transport packaging sector sits in a sensor-technology transition, with RFID-tagged containers replacing barcode-scanned legacy assets under regulatory pressure.
For Market Incumbents: Cement fleet density advantages through CONMETRO recalibration contract lock-ins across São Paulo's ABC corridor. Extend depot infrastructure into Minas Gerais dairy clusters before regional competitors establish pooling footholds. Threat substitution from single-use corrugated alternatives under pending extended producer responsibility legislation demands preemptive standardization of foldable large container footprints. For New Entrants and Emerging Players: Digital procurement platforms offer lowest-friction entry into standardized pallet and tote segments lacking incumbent service coverage. White-space concentration in Minas Gerais cheese and yogurt processing remains underpenetrated relative to São Paulo saturation. Direct online sales to mid-tier fabricators bypasses CHEP and IFCO depot network advantages. For Investors and Strategic Acquirers: Re-rating potential sits with specialized fabricators possessing tropical humidity engineering capabilities given ANVISA pharmaceutical traceability mandates accelerating RFID adoption timelines. Long-term viability favors asset-light pooling operators with reverse-logistics density over capital-intensive captive fleet owners. Monitor pending federal extended producer responsibility legislation passage as inflection signal for corrugated-to-returnable conversion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| RFID Infrastructure Deployment | ANVISA traceability mandates compress pharmaceutical container procurement cycles toward sensor-enabled assets. |
| Backward Integration into Resin Supply | Captive high-density polyethylene sourcing shields molding margins from petrochemical price volatility. |
| Depot Network Expansion | Belo Horizonte and Maringá logistics hubs reduce São Paulo concentration risk for pooling operators. |
| ABNT Certification Investment | Dimensional tolerance pre-qualification hardens into de facto procurement mandate across protein processors. |
| Pharmaceutical Cold Chain Partnership | Temperature-logged container histories open biotechnology distribution under ANVISA integrity standards. |
Research Methodology
Multi-period observation of container fleet depreciation schedules and pooling contract renewal rates anchored the trend analysis, supplemented by interviews with logistics procurement officers at protein processors, pharmaceutical distribution managers, automotive Tier 1 supplier quality leads, and pooling network operations directors. Secondary validation drew from ANVISA regulatory filings, CONMETRO certification databases, ABNT technical specifications, and Brazilian customs trade records. Bottom-up segment sizing triangulated against top-down industrial production indices.
Segment-weighting across material type, end-use industry, container size class, and distribution channel shaped the analytical framework. CAGRs derived from logistic curve fitting to historical fleet penetration rates, adjusted for regulatory deadline acceleration effects. Forecast inputs incorporated automotive production schedules from São Paulo's ABC corridor and pharmaceutical distribution volume projections under traceability mandate compliance deadlines.
The model holds under stable resin pricing and regulatory implementation timelines; deviation in extended producer responsibility legislation enactment or petrochemical supply disruptions would shift conversion velocity assumptions. Practitioners should monitor ANVISA enforcement intensity and federal packaging waste law progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Reusable Corrugated Plastic Boxes Market
Reusable Packaging
Europe Refillable and Reusable Packaging Market
Reusable Packaging
Reusable Transport Packs Market
Reusable Packaging
Reusable Water Bottle Market
Reusable Packaging
Reusable Consumer Packaging Market
Reusable Packaging
North America and Europe Reusable Corrugated Boxes Market
Reusable Packaging
Re-Sealable Packaging Bags Market
Reusable Packaging
United States and Europe Reusable Plastic Returnable Transport Packaging Market
Reusable Packaging
Europe Reusable Water Bottle Market
Reusable Packaging
Reverse Logistics for Reusable Packaging and Containers Market
Reusable Packaging
Refillable Packaging Market
Reusable Packaging
Reconditioned Packaging Market
Reusable Packaging
Recyclable Cups Market
Reusable Packaging
Reusable Barrels Market
Reusable Packaging
Reusable Egg Containers Market
Reusable Packaging
Micro-Packaging Market