
 Reusable Consumer Packaging Market | 2026-2036
Reusable Consumer Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Consumer Packaging Market Analytics
Food industry end-use is consolidating as the dominant demand vertical for reusable consumer packaging, displacing slower-growing household segments. Schoeller Allibert dominates returnable container logistics through its European manufacturing network. ORBIS Corporation anchors North American supply with rigid plastic pooling systems. Brambles Limited leverages its CHEP brand to control shared pallet and container infrastructure across retail channels.
Reusable consumer packaging comprises durable containers, bags, liners, and jars engineered for multiple use cycles through standardized dimensions, stackable geometries, and material resilience exceeding fifty rotations. Primary commercial purpose centers on closed-loop distribution systems that replace single-use alternatives in retail and food service supply chains. Rigid form factors lead unit volume due to structural integrity in automated handling environments, while flexible and collapsible designs capture faster growth in last-mile delivery applications where space optimization drives economics. Glass and recycled plastic materials command premium positioning in personal care and premium food segments where transparency and sustainability credentials justify higher per-unit investment.
The EU Packaging and Packaging Waste Regulation and REACH chemical compliance frameworks mandate extended producer responsibility and material traceability, directly shaping product design specifications and market access conditions. FDA food-contact material standards in the United States and China's GB national standards for plastic recyclability create divergent compliance pathways that fragment global product platforms. Stakeholders must monitor regulatory harmonization progress between major economies to determine whether regional customization or unified design architectures deliver superior returns.
Market Dynamics
Closed-loop logistics infrastructure is consolidating control over reusable consumer packaging economics, with pooling system operators capturing margin through standardized container fleets and reverse logistics networks that penalize single-use alternatives.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory reuse targets for food service and e-commerce sectors force retailer adoption of returnable container programs across Germany, France, and the Netherlands.
- Food service automation:Quick-service chains deploy rigid plastic containers compatible with automated dishwashing and sorting systems, cutting labor costs per rotation cycle.
- Polypropylene compound advances:High-density formulations withstand fifty-plus industrial wash cycles without degradation, extending asset life and improving unit economics.
Market Restraints
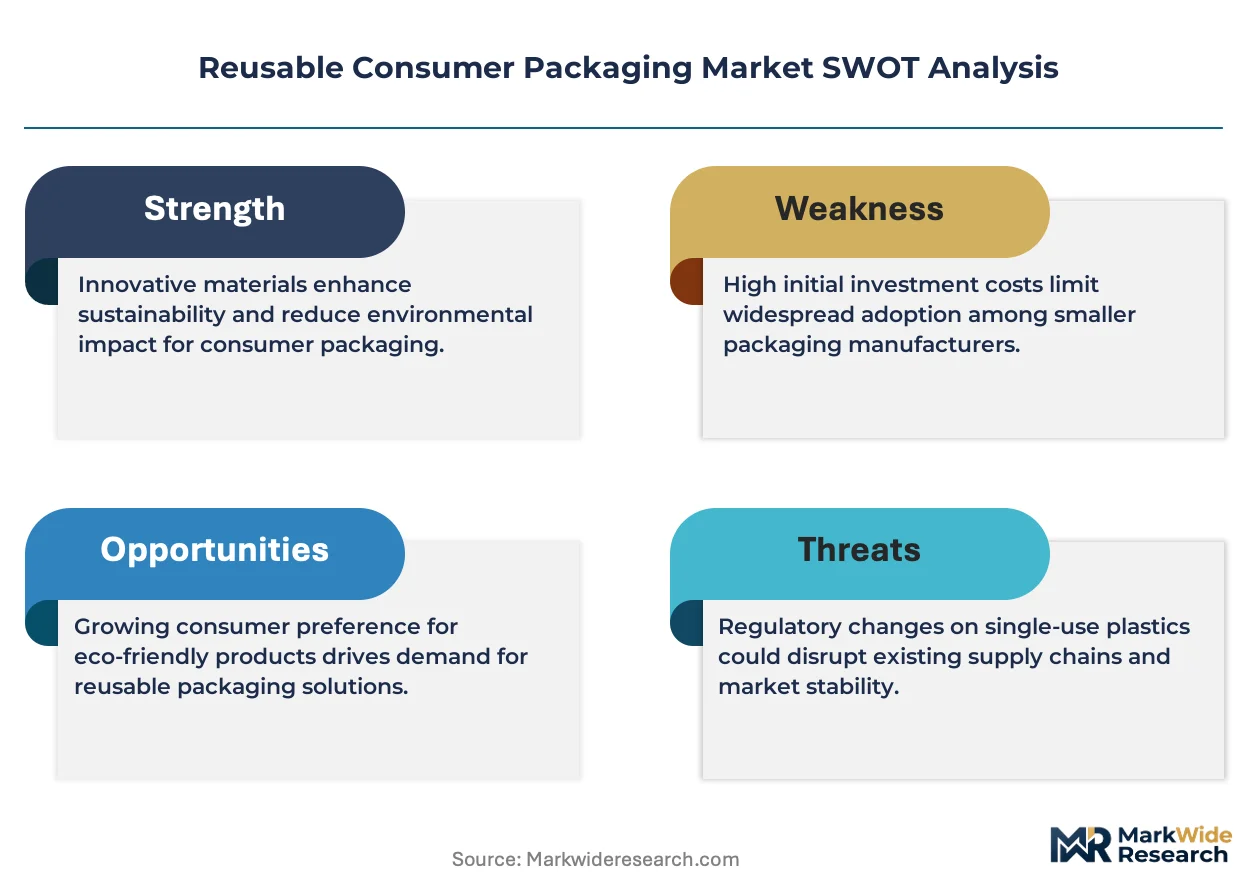
- Petrochemical feedstock volatility:Virgin polypropylene prices swing with crude oil indices, compressing margins for rigid container manufacturers during cost spikes.
- Reverse logistics infrastructure gaps:Rural and suburban zones lack collection point density, limiting program viability outside urban corridors in France and Germany.
- Compostable bioplastic substitution:Polylactic acid alternatives capture single-use segments where washing infrastructure proves uneconomical.
Strategic Opportunities
- Last-mile grocery delivery:Collapsible totes reduce vehicle cube utilization by sixty percent on return trips, unlocking density economics for dark-store operators.
- Personal care refill stations:Premium cosmetic brands pilot glass jar return systems in Dutch retail, building loyalty through deposit-based circularity.
- Digital product passports:RFID-embedded containers enable rotation tracking and carbon accounting, satisfying CSRD disclosure requirements for EU corporates.
Industry Challenges
- Sanitation certification timelines:FDA food-contact approvals for novel recycled content streams extend eighteen to twenty-four months, delaying product launches.
- Legacy ERP integration:Pooling operators struggle to synchronize container tracking data with shipper warehouse management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Consumer Packaging Market |
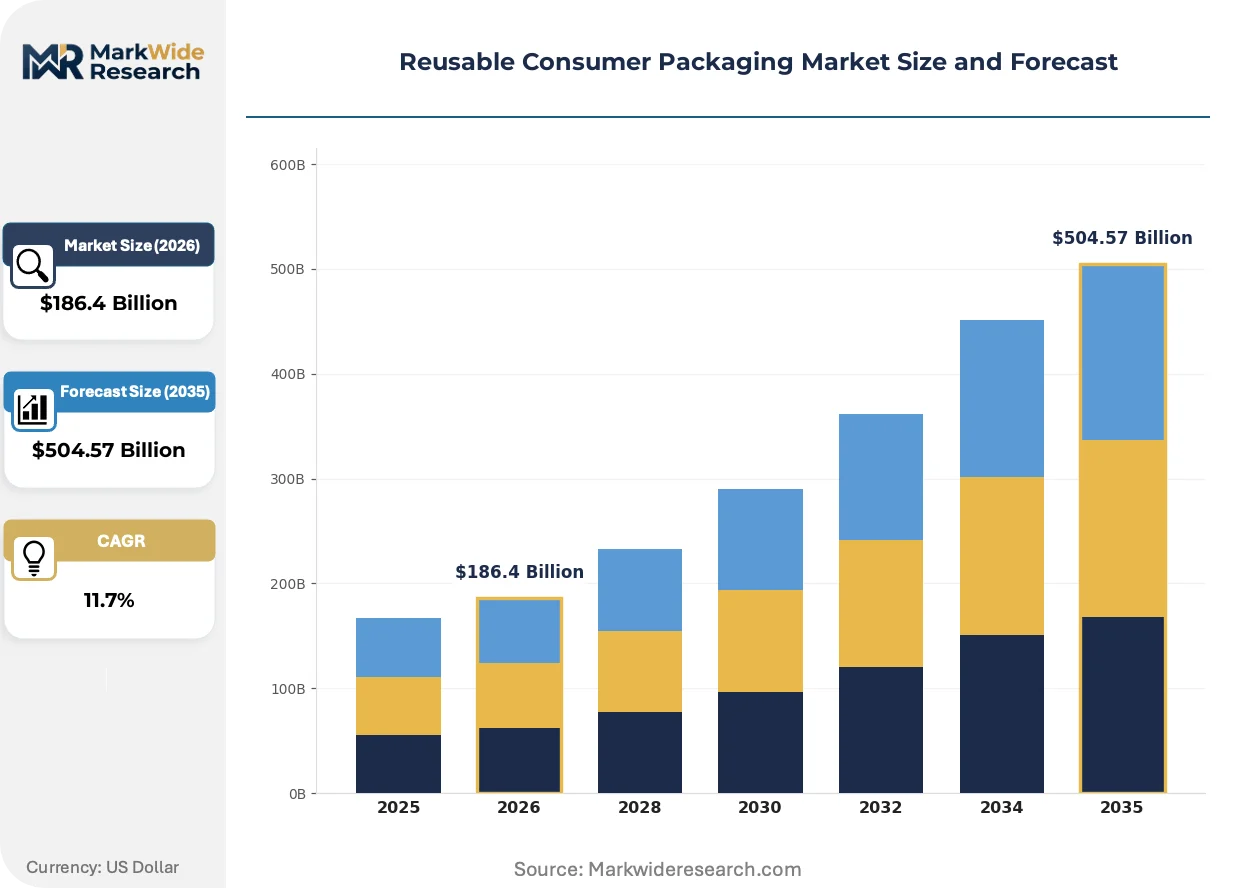
| Market Size in 2026 | $186.4 Billion |
| Market Size in 2035 | $504.57 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Bags, Liners, Jars Material: Glass, Metal, Silicone, Recycled Plastic Form: Flexible, Rigid, Semi-Rigid, Collapsible End User: Food Industry, Retail, Personal Care, Household |
| Companies Covered | Schoeller Allibert, Rehrig Pacific Company, ORBIS Corporation, IFCO Systems, DS Smith, Mauser Packaging Solutions, Menasha Corporation, SSI Schaefer, Brambles Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Consumer Packaging Market Evolving Landscape
Material science breakthroughs and regulatory compliance architectures are compressing design cycles while expanding the addressable use-case perimeter for durable packaging systems.
Embedded RFID and QR-code tracking is unifying container lifecycle data across manufacturers, logistics providers, and retailers into single-source-of-truth platforms. Food service operators in Germany now mandate chip-enabled returnables for automated deposit refunds. This convergence is compressing settlement timelines between pooling networks and end-users from monthly to real-time reconciliation.
REACH chemical compliance frameworks now mandate full material disclosure for substances of very high concern in reusable food-contact articles. The European Chemicals Agency enforcement is pushing manufacturers toward non-phthalate plasticizers and recycled content traceability systems. Personal care brands targeting Dutch and French markets are accelerating glass-to-recycled-polymer substitutions to preempt authorization deadlines.
Deposit-return schemes are displacing voluntary take-back programs as the dominant consumer-facing collection mechanism. Grocery retailers in the Netherlands now operate consolidated return points accepting multiple competing container formats. Quick-service chains report higher return rates under mandatory deposit structures versus loyalty-point incentives, shifting investment toward unified collection infrastructure rather than brand-specific systems.
Reusable Consumer Packaging Market Segmentation
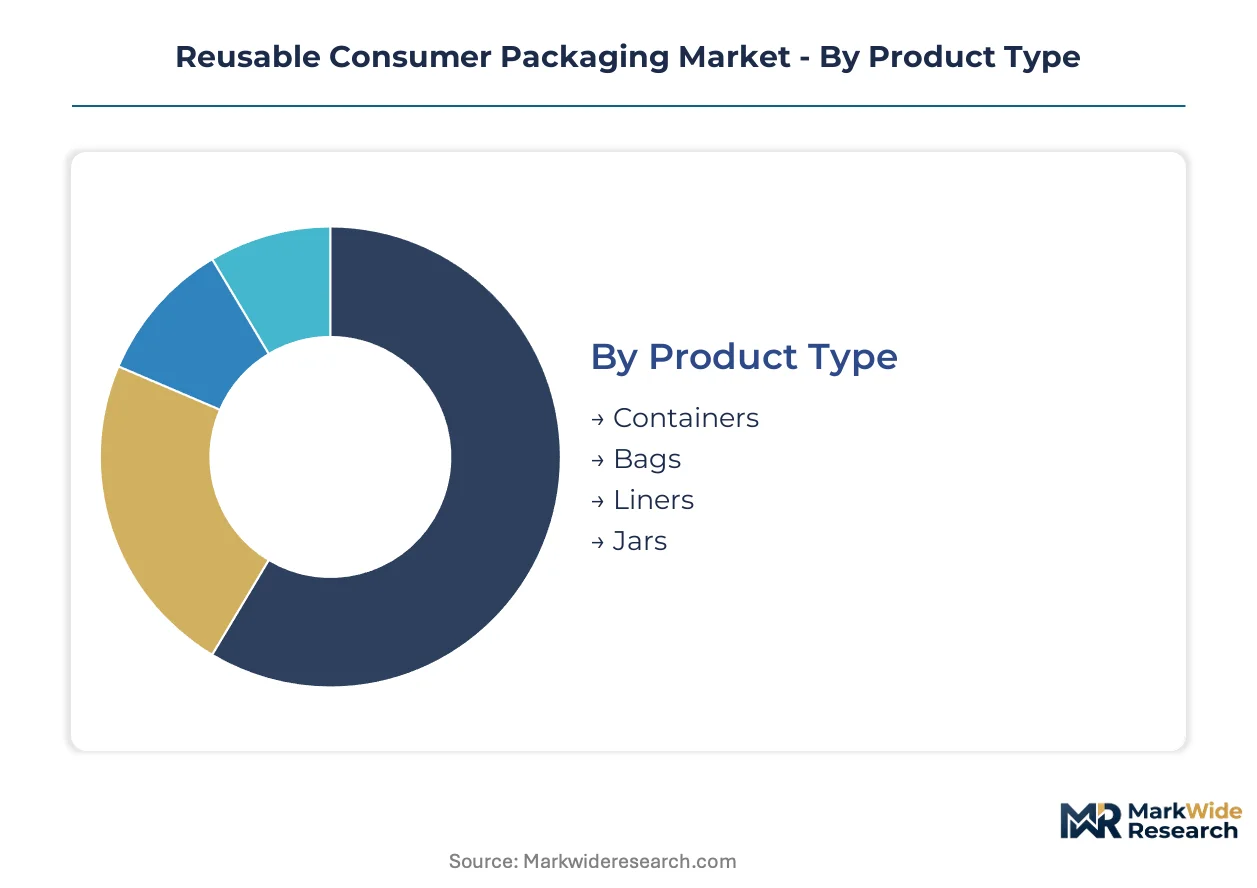
Reusable consumer packaging segments diverge sharply by structural properties and washing infrastructure requirements. Product geometry and material resilience dictate rotation cycle economics and determine which end-use verticals can sustain closed-loop operations profitably.
Product Type:
Dimensional standardization and nesting efficiency separate commercially viable formats from niche applications.
- Containers:Rectangular and cylindrical designs with reinforced corners withstand automated handling in food service distribution. Quick-service chains in Germany and France mandate standardized footprints for dishwashing compatibility, locking in multi-year procurement contracts.
- Bags:Woven polypropylene and silicone-coated fabric constructions collapse flat for return-trip density. Last-mile grocery operators in the Netherlands report sixty percent cube reduction versus rigid alternatives, though washing infrastructure limits deployment to urban corridors.
- Liners:Flexible inserts protect rigid outer shells from contamination, extending primary asset life across fifty-plus rotation cycles. Demand concentrates in bulk food and industrial ingredient handling where liner replacement costs fractionally against full container refurbishment.
- Jars:Threaded glass and wide-mouth polymer designs serve personal care refill stations and premium food preservation. Dutch retailers pilot deposit-return schemes for cosmetic jars, building consumer loyalty through circularity credentials.
Mature deployment sits with containers. Newer deployment is concentrated in bags.
Material:
Feedstock selection balances chemical compliance thresholds against per-rotation depreciation rates.
- Glass:Borosilicate and soda-lime formulations deliver transparency and inertness for personal care and premium food segments. REACH authorization pressures are accelerating substitution toward recycled polymers in Dutch and French markets ahead of phthalate restriction deadlines.
- Metal:Stainless steel and aluminum alloys provide structural integrity for industrial bulk handling and outdoor beverage containers. Higher unit costs restrict adoption to premium positioning where durability justifies investment across hundred-plus rotation cycles.
- Silicone:Platinum-cured formulations offer temperature resistance and collapsibility for food storage and culinary applications. FDA food-contact approval timelines for novel recycled content streams extend eighteen to twenty-four months, constraining supply expansion.
- Recycled Plastic:Post-consumer polypropylene and PET compounds achieve fifty-plus wash cycles through high-density formulations. EU Packaging and Packaging Waste Regulation mandates are forcing retailer adoption across German food service supply chains.
Glass commands premium positioning. Recycled plastic is climbing the fastest on regulatory compulsion.
Form:
Structural behavior under mechanical stress and space-constrained return logistics determines format selection.
- Flexible:Fabric and film constructions fold flat for reverse logistics efficiency. E-commerce grocery dark-stores in France prioritize collapsible totes for vehicle cube optimization on return trips from suburban delivery zones.
- Rigid:Injection-molded and thermoformed shells maintain dimensional stability through automated sorting and high-temperature washing. Food industry end-use dominates volume due to compatibility with existing supply chain infrastructure.
- Semi-Rigid:Hybrid constructions combine structural ribs with flexible panels for moderate nesting ratios. Personal care brands evaluate semi-rigid formats for refill station programs requiring consumer handling durability without full rigid investment.
- Collapsible:Hinged and fold-flat designs reduce return shipping volume by seventy percent versus fixed geometries. Last-mile operators in dense Dutch urban corridors report favorable unit economics where collection point density supports reverse logistics.
Rigid formats anchor industrial deployment. Collapsible designs are gaining share fastest in consumer-facing delivery.
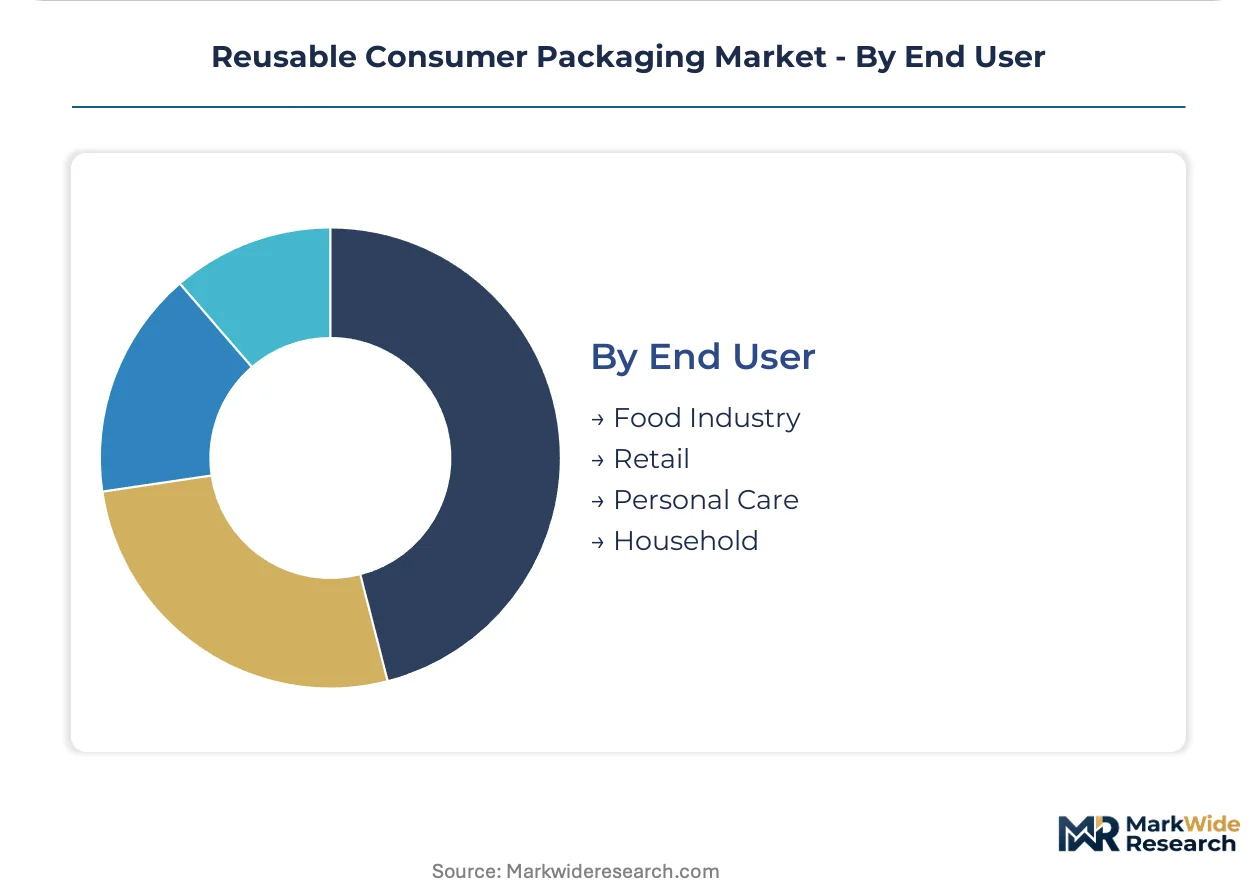
End User:
Operational scale and washing infrastructure access segment addressable market boundaries.
- Food Industry:Central kitchens, quick-service chains, and institutional catering drive standardized container pooling. Automation compatibility requirements in German and French food service are consolidating procurement around rigid plastic formats with chip-enabled tracking.
- Retail:Grocery chains and department stores operate return point infrastructure for multi-brand container acceptance. Dutch retailers now consolidate competing formats at unified collection points, shifting investment from brand-specific systems.
- Personal Care:Premium cosmetic and hygiene brands pilot glass jar return systems and refill stations. ECHA enforcement on substances of very high concern is accelerating material substitutions ahead of authorization deadlines.
- Household:Direct-to-consumer durable storage captures slower growth due to washing burden displacement to end-users. Silicone food bags and glass storage sets serve sustainability-motivated segments without closed-loop infrastructure.
Food industry deployment is most mature. Personal care represents the steepest expansion trajectory on premium circularity positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and the Netherlands while consumption spreads across Western European retail corridors. The EU Packaging and Packaging Waste Regulation creates uniform compliance obligations that mask divergent national implementation timelines. Urban density variations produce starkly different reverse logistics economics across national markets.
Germany
Quick-service chains and institutional catering drive rigid container demand through automated dishwashing infrastructure. The national packaging ordinance implements EU reuse targets with mandatory deposit structures for food service containers. Berlin and Hamburg host the densest pooling network consolidation, with operators reporting superior rotation economics in these metropolitan zones.
France
Grocery retailers and dark-store operators deploy collapsible totes for last-mile delivery optimization. ANSM enforces REACH-aligned material disclosure for food-contact articles, accelerating substitution away from legacy plasticizers. The Paris metropolitan corridor dominates pilot program deployment, with suburban collection point gaps limiting rural scalability.
Netherlands
Personal care brands and premium food retailers pilot glass jar return systems through deposit-return schemes. The national waste management framework mandates extended producer responsibility with traceability requirements for reusable packaging. Rotterdam and Amsterdam operate unified collection points accepting competing container formats, consolidating infrastructure investment.
United States
Food service distributors and retail chains adopt rigid plastic pooling systems compatible with existing supply chain automation. FDA food-contact material standards create eighteen-to-twenty-four month approval timelines for novel recycled content streams. The Midwest manufacturing belt anchors domestic container production, with Chicago and Detroit serving as distribution hubs for national pooling networks.
China
E-commerce grocery platforms and quick-service chains test collapsible formats for dense urban delivery optimization. GB national standards for plastic recyclability and MIIT circular economy mandates shape material specifications for export-oriented manufacturers. The Yangtze River Delta cluster concentrates molding capacity, with Shanghai-based fabricators supplying regional pooling operators.
Reusable Consumer Packaging Market Competitive Landscape
Top-tier vendors anchor European pooling infrastructure, while mid-scale fabricators compete on regional customization and material specialization. The vendor base stratifies across three tiers: multinational pooling operators controlling shared fleets, rigid container specialists serving automated food service supply chains, and flexible format innovators targeting last-mile density economics. Consolidation pressure intensifies as standardization requirements favor scale-driven players with integrated reverse logistics capabilities. M&A activity targets regional pooling networks, while capacity expansion concentrates in high-wash-cycle polypropylene compounding.
Within the multinational pooling tier, Schoeller Allibert and ORBIS Corporation exemplify divergent geographic anchoring strategies. Schoeller Allibert occupies a position representing European-centric manufacturing network consolidation, while ORBIS Corporation exemplifies North American supply chain integration. Brambles Limited sits within the shared infrastructure control archetype, leveraging its CHEP brand across retail channel standardization. These three entities represent the dominant competitive positioning patterns visible across the named player set.
| Leading Market Players |
|---|
| Schoeller Allibert |
| Rehrig Pacific Company |
| ORBIS Corporation |
| IFCO Systems |
| DS Smith |
| Mauser Packaging Solutions |
| Menasha Corporation |
| SSI Schaefer |
| Brambles Limited |
| Others |
Value Network & Pricing Analysis
Quick-service chains and institutional food service operators concentrate procurement power through multi-year container pooling contracts, anchoring a subscription-based pricing model where per-rotation fees replace capital expenditure. This buyer consolidation allows Schoeller Allibert and ORBIS Corporation to enforce standardized rate cards across German and French metropolitan zones while penalizing single-use alternatives through deposit-return economics.
Pricing Analysis
Margin tightening in rigid container tiers reflects virgin polypropylene feedstock volatility tied to crude oil indices, compressing manufacturer returns during cost spikes. Three-tier pricing structure across premium glass, standard recycled polymer, and economy virgin plastic levels separates personal care brands seeking REACH compliance from budget food service operators. Cost-down pressure on flexible bag formats accelerates as last-mile grocery operators demand sixty percent cube reduction without commensurate fee premiums. Quick-service chains exhibit highest price sensitivity due to thin per-meal margins, while premium cosmetic brands absorb glass jar premiums for circularity credentials.
Supply Chain Analysis
EU Packaging and Packaging Waste Regulation domestic-content mandates are reshaping sourcing toward European compounding facilities for high-wash-cycle polypropylene. Manufacturing gravity centers on Germany, the Netherlands, and China's Yangtze River Delta, with Rotterdam and Hamburg serving as consolidation hubs for reverse logistics networks. Feedstock supply draws from petrochemical complexes in Belgium and the US Gulf Coast, creating tariff exposure on imported virgin resin. Distribution runs through pooling operator fleets rather than direct manufacturer-to-retailer channels, with RFID-enabled tracking infrastructure controlling container lifecycle data.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-wash-cycle polypropylene compounding capacity constraints prop pricing power for incumbent pooling operators, creating supply-constrained conditions that favor early-mover consolidation over greenfield expansion.
For Market Incumbents: Cement control over reverse logistics infrastructure through acquisition of regional pooling networks in France and the Netherlands, locking in collection point density that new entrants cannot replicate. Expand captive compounding capacity for fifty-plus wash cycle formulations to offset petrochemical feedstock volatility. Compostable bioplastic substitution threats from polylactic acid alternatives demand accelerated R&D investment in non-phthalate plasticizers ahead of ECHA authorization deadlines. For New Entrants and Emerging Players: Suburban and rural grocery retailers in France represent an underserved buyer archetype where collection point gaps exclude incumbent pooling economics. Personal care refill stations in Dutch retail corridors offer white-space penetration with lower automation requirements than food service verticals. A deposit-return scheme partnership with unified collection point operators provides faster route-to-market than building proprietary reverse logistics from zero. For Investors and Strategic Acquirers: The window for entry favors mid-scale regional pooling operators with established municipal collection contracts and RFID tracking integration capabilities. Long-term viability hinges on regulatory enforcement durability across EU member states, with CSRD disclosure requirements expanding addressable market for carbon-accounting-enabled container fleets. Watch ECHA substance authorization timelines as inflection signals for material substitution capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Reverse Logistics Network Acquisition | Consolidates collection point density in Dutch and French urban corridors against competitor replication. |
| High-Wash-Cycle Polypropylene Compounding Expansion | Captive supply of fifty-plus rotation formulations insulates margin from petrochemical price volatility. |
| RFID-Enabled Container Fleet Deployment | Satisfies CSRD disclosure requirements for EU corporates tracking carbon per rotation cycle. |
| Deposit-Return Scheme Partnership | Unlocks unified collection infrastructure in Netherlands without brand-specific system investment. |
| Non-Phthalate Plasticizer R&D Investment | Preempts ECHA authorization deadlines accelerating glass-to-recycled-polymer substitutions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with food service procurement directors, pooling network operations managers, and ECHA compliance officers. EU Packaging and Packaging Waste Regulation implementation documents, FDA food-contact material standards, and REACH substance authorization databases provided regulatory boundary conditions. Bottom-up container rotation modeling triangulated against top-down market sizing from rigid plastic pooling system disclosures.
Data-stream reconciliation across product type, material grade, form factor, and end-use vertical dimensions shaped the analytical framework throughout the projection horizon. CAGRs derived from wash-cycle depreciation curves and regulatory mandate phase-in schedules, with sensitivity analysis on polypropylene feedstock price scenarios and reverse logistics infrastructure buildout rates. Segmentation splits incorporated automation compatibility requirements for German quick-service chains and collapsible tote adoption curves in French dark-store grocery.
Revisions become necessary when ECHA enforcement timelines accelerate, EU member state reuse target implementation diverges, or compostable bioplastic cost curves disrupt rigid container economics. Forecasts reflect assumptions on collection point density scaling and deposit-return scheme legislative expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Reusable Packaging
Europe Refillable and Reusable Packaging Market
Reusable Packaging
Recyclable Cups Market
Reusable Packaging
Reusable Transport Packs Market
Reusable Packaging
Reusable Tumblers Market
Reusable Packaging
Returnable Transport Packaging (RTP) Market
Reusable Packaging
Resealable Cans Market
Reusable Packaging
Reusable Egg Containers Market
Reusable Packaging
Recyclable Ovenable Trays Market
Reusable Packaging
Returnable Packaging Systems Market
Reusable Packaging
Reusable Food Wrap Market
Reusable Packaging
Europe Reusable Water Bottle Market
Reusable Packaging
Recycled Envelopes Market
Reusable Packaging
Reusable Wrap Market
Reusable Packaging
Reusable Ice Packs Market
Reusable Packaging
North America and Europe Reusable Corrugated Boxes Market
Reusable Packaging
Reverse Logistics for Reusable Packaging and Containers Market