
 Middle East and Africa Digital Oilfield Market | 2026-2036
Middle East and Africa Digital Oilfield Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Digital Oilfield Market Foresight
Edge-to-cloud architecture is fragmenting across upstream operations as operators disperse compute between wellhead sensors and centralized platforms. Schlumberger Limited leverages its integrated subsurface software stack to anchor high-complexity reservoir digital twin deployments. Baker Hughes Company sustains competitive pressure through specialized turbomachinery diagnostics married to predictive analytics. Microsoft dominates cloud infrastructure contracting with national operators seeking sovereign data residency.
A digital oilfield deploys networked sensors, edge computing nodes, and machine learning algorithms to automate reservoir characterization, production surveillance, and equipment maintenance across hydrocarbon extraction operations. IoT sensor networks transmit pressure, temperature, and flow data at sub-second intervals to enable real-time choke optimization and artificial lift control. Production optimization applications command the largest deployment share as mature fields require decline-curve management, while cloud-based deployment models are gaining share fastest among independents seeking capital expenditure flexibility without on-premise infrastructure commitments.
SFDA cybersecurity standards for Saudi critical infrastructure, UAE's NCEMA operational technology guidelines, and Nigeria's DPR digital reporting mandates collectively shape procurement specifications and vendor qualification pathways across the region. Compliance with these frameworks determines market access for foreign technology providers and influences local partnership requirements. Stakeholders must evaluate sovereign data localization commitments against hybrid cloud architectures as regulatory scrutiny of cross-border hydrocarbon data intensifies.
Market Dynamics
Edge computing architectures are fragmenting upstream operations as Gulf operators disperse real-time processing between wellhead sensors and centralized platforms to reduce latency for artificial lift optimization.
Growth Catalysts
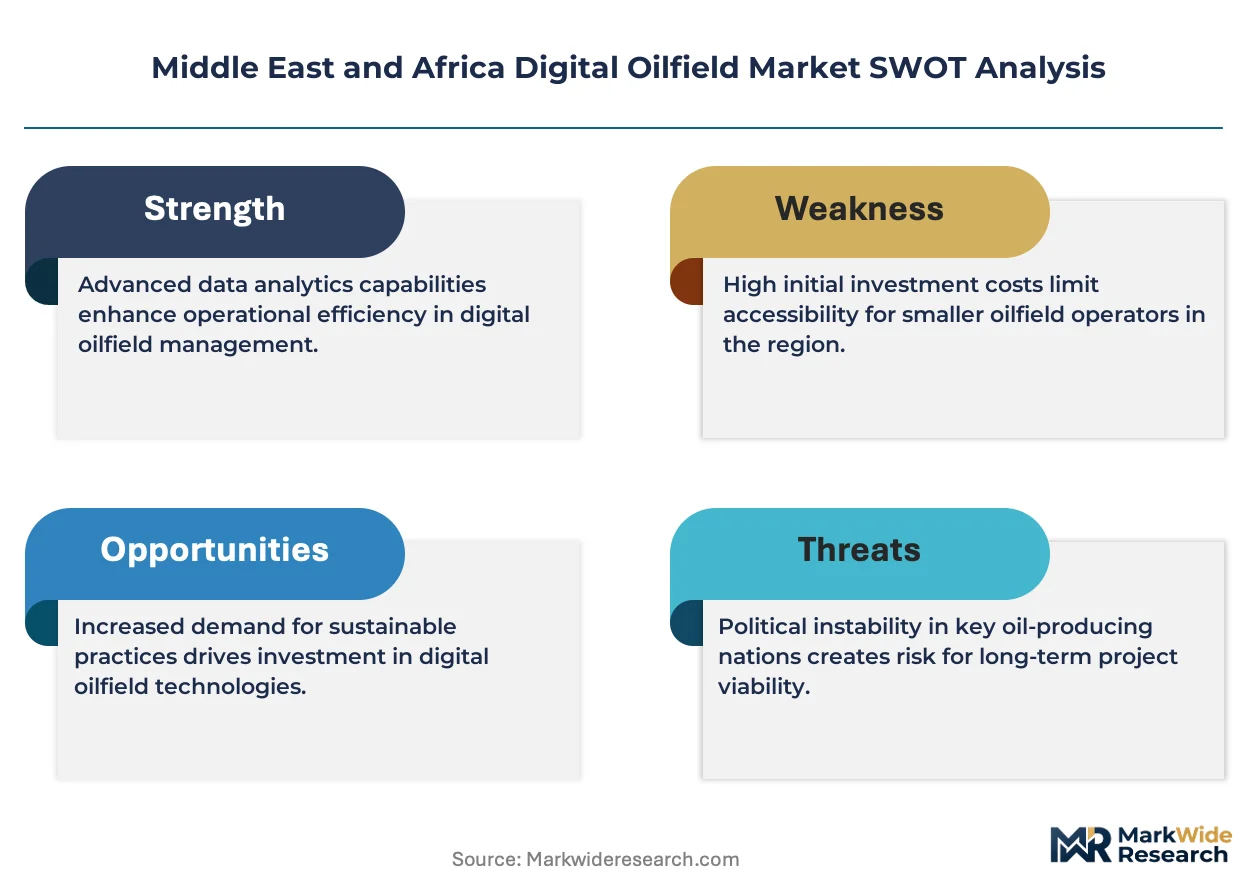
- SFDA Cybersecurity Mandates:Saudi Arabia's critical infrastructure standards are compelling national oil companies to upgrade operational technology networks, creating procurement pull for compliant automation vendors.
- AI-Driven Production Optimization:Machine learning algorithms for decline-curve management are penetrating mature fields across the Eastern Province as reservoir complexity exceeds conventional modeling capacity.
- Dual-Carbon Technology Incentives:Abu Dhabi's policy framework subsidizes digitization investments that reduce flaring intensity, accelerating cloud-based deployment models among independents seeking capital flexibility.
Market Restraints
- Semiconductor Supply Concentration:Edge device manufacturing depends on concentrated Asian foundry capacity, exposing field sensor rollout timelines to geopolitical disruption risks.
- Legacy SCADA Integration Friction:Brownfield installations face protocol incompatibility between decades-old distributed control systems and modern IoT architectures.
- Specialized Talent Scarcity:Reservoir engineering expertise in subsurface digital twin deployment remains concentrated with a limited pool of integrated service providers.
Strategic Opportunities
- Nigerian Deepwater Digitization:DPR digital reporting mandates are creating first-mover advantage for vendors establishing local partnerships in underpenetrated offshore blocks.
- Predictive Turbomachinery Analytics:Convergence of vibration sensing with machine learning opens white space in compressor and pump maintenance scheduling across mature Gulf fields.
- Sovereign Cloud Infrastructure:Data localization requirements are stimulating domestic hyperscale facility construction, enabling hybrid architectures that satisfy NCEMA guidelines.
Industry Challenges
- Cyber-Physical Security Integration:IT-OT convergence demands unified threat monitoring capabilities that most operators lack in-house, stretching implementation timelines.
- Subsurface Data Standardization:Proprietary seismic and well log formats from multiple decades prevent seamless reservoir model federation across joint venture partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Digital Oilfield Market |
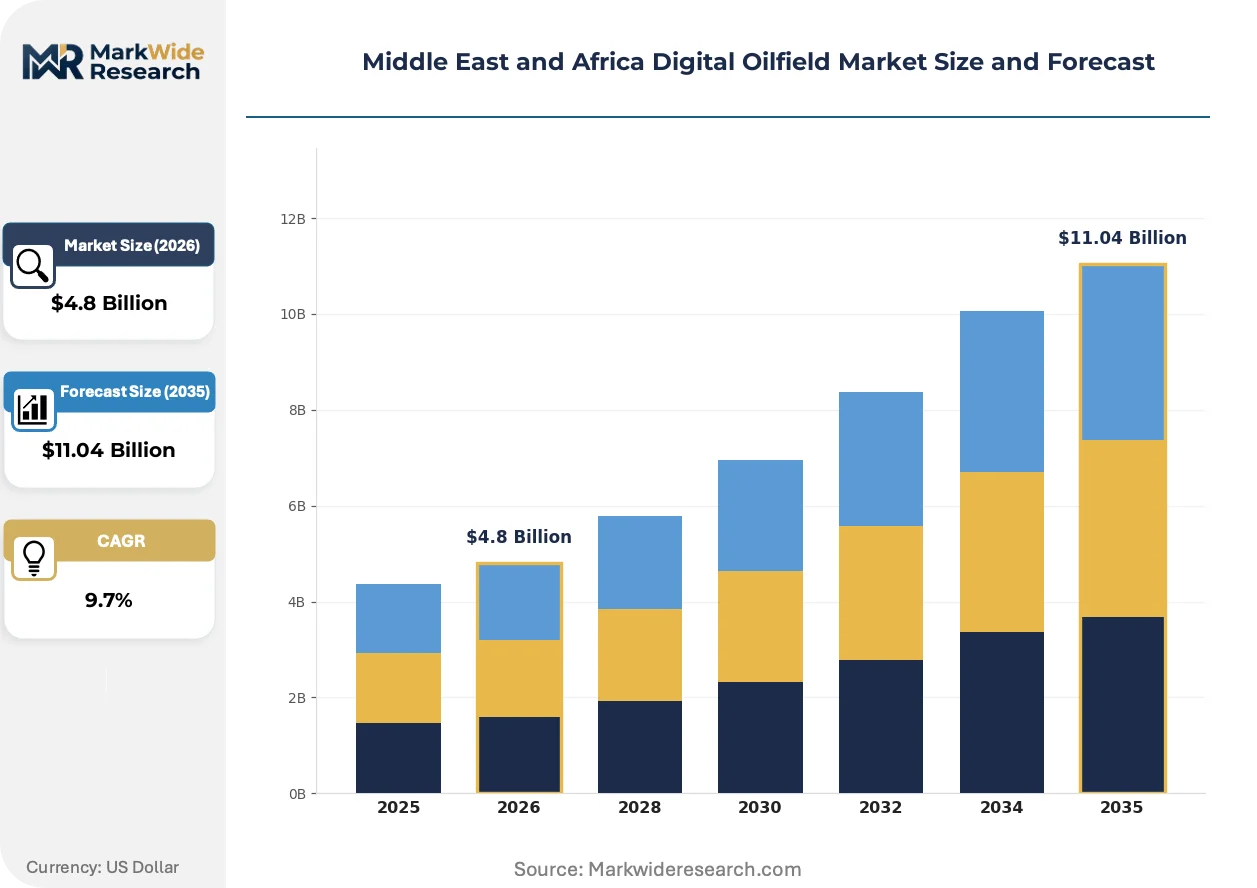
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, AI, Cloud Computing, Data Analytics Application: Production Optimization, Reservoir Management, Asset Management, Remote Monitoring End User: Oil & Gas Operators, Service Providers, Energy Companies, Independent Producers Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services |
| Companies Covered | Schlumberger Limited, Baker Hughes Company, Halliburton, Weatherford, NOV Inc., IBM Corporation, Microsoft, Emerson Electric Co., ABB, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Digital Oilfield Market Shifts & Advancements
Real-time reservoir characterization is compressing decision cycles from quarterly to daily intervals, forcing vendors to rearchitect software delivery models and pricing structures around continuous optimization workflows.
Digital twin technology is collapsing the distinction between subsurface simulation and surface operations planning. Saudi Aramco and ADNOC are deploying unified physics-based models that integrate geomechanical analysis with production scheduling. National operators are collapsing vendor silos by demanding single-platform accountability for reservoir-to-export optimization.
SFDA cybersecurity standards for Saudi critical infrastructure are mandating air-gapped operational networks with encrypted telemetry pathways. Compliance deadlines are accelerating procurement cycles for zero-trust architecture implementations. Vendors are restructuring service contracts to include continuous monitoring obligations rather than discrete installation deliverables.
Performance-based contracting is displacing capital expenditure models among independents with constrained balance sheets. Service providers are assuming reservoir outcome risk in exchange for production uplift shares. This structure concentrates in Abu Dhabi's marginal field redevelopment programs where technical service agreements align vendor compensation with barrel recovery metrics.
Middle East and Africa Digital Oilfield Market Segmentation
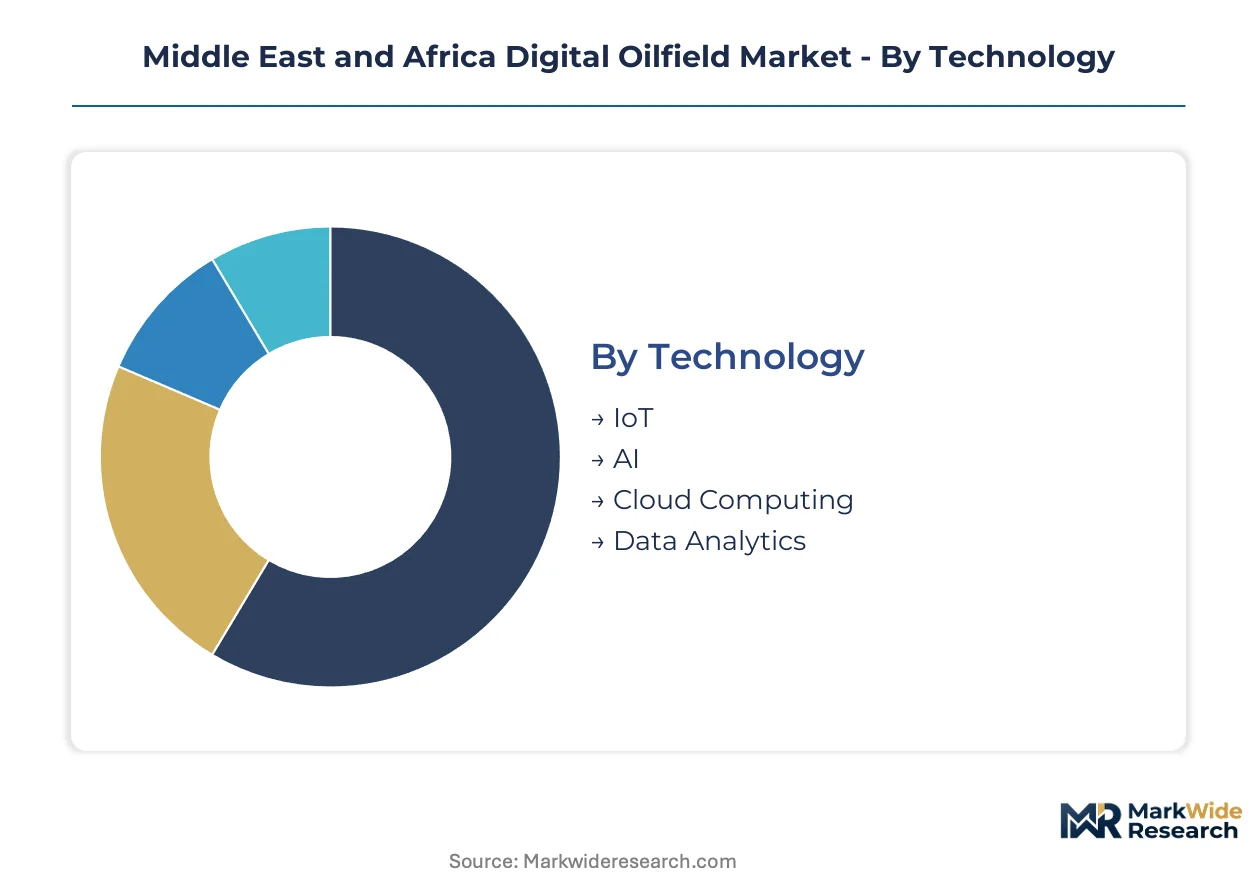
Digital oilfield procurement patterns diverge sharply across technology maturity, operational application, and deployment economics. Understanding these fault lines clarifies where vendor specialization creates sustainable margin pools versus commodity pressure zones.
Technology:
Mature industrial automation platforms now coexist with emerging cognitive systems, creating a bifurcated supplier landscape.
- IoT:Sensor networks capturing pressure, temperature, and flow metrics at sub-second intervals form the physical substrate for real-time choke optimization. Demand concentrates in Saudi Arabia's Eastern Province mega-fields where wellhead density justifies dense telemetry infrastructure against SFDA cybersecurity compliance costs.
- AI:Machine learning algorithms for decline-curve management and artificial lift control are penetrating mature reservoirs as conventional modeling reaches predictive limits. Abu Dhabi's dual-carbon technology incentives accelerate adoption among independents seeking production uplift without capital-heavy facility upgrades.
- Cloud Computing:Hyperscale infrastructure enables sovereign data residency for national operators.
- Data Analytics:Visualization platforms aggregate multi-source operational intelligence.
IoT retains volume leadership; AI holds the steepest expansion curve.
Application:
Cost tier stratification separates high-value reservoir engineering from commoditized equipment surveillance.
- Production Optimization:Real-time choke adjustment and artificial lift control systems command premium pricing due to direct barrel-recovery impact. Deployment concentrates in mature Gulf fields where decline-curve management determines joint venture economics and performance-based contracting structures.
- Reservoir Management:Subsurface digital twins integrating seismic, well log, and production data require specialized geoscience expertise. Nigeria's DPR digital reporting mandates are stimulating first-mover procurement in underpenetrated deepwater blocks.
- Asset Management:Predictive maintenance for rotating equipment spans compressors and pumps.
- Remote Monitoring:Distributed surveillance of unmanned facilities reduces personnel exposure.
Production Optimization retains volume leadership; Reservoir Management holds the steepest expansion curve.
End User:
Customer type determines procurement sophistication and contract structure flexibility.
- Oil & Gas Operators:National oil companies across the Gulf Cooperation Council anchor demand through mega-field digitization programs. Saudi Aramco and ADNOC are collapsing vendor silos by demanding single-platform accountability for reservoir-to-export optimization.
- Independent Producers:Capital-constrained players favor performance-based contracting with production uplift sharing. Abu Dhabi's marginal field redevelopment programs concentrate technical service agreements linking vendor compensation to barrel recovery metrics.
- Service Providers:Integrated vendors bundle digital capabilities with conventional field services.
- Energy Companies:Diversified utilities with hydrocarbon assets seek operational technology convergence.
Oil & Gas Operators retain volume leadership; Independent Producers hold the steepest expansion curve.
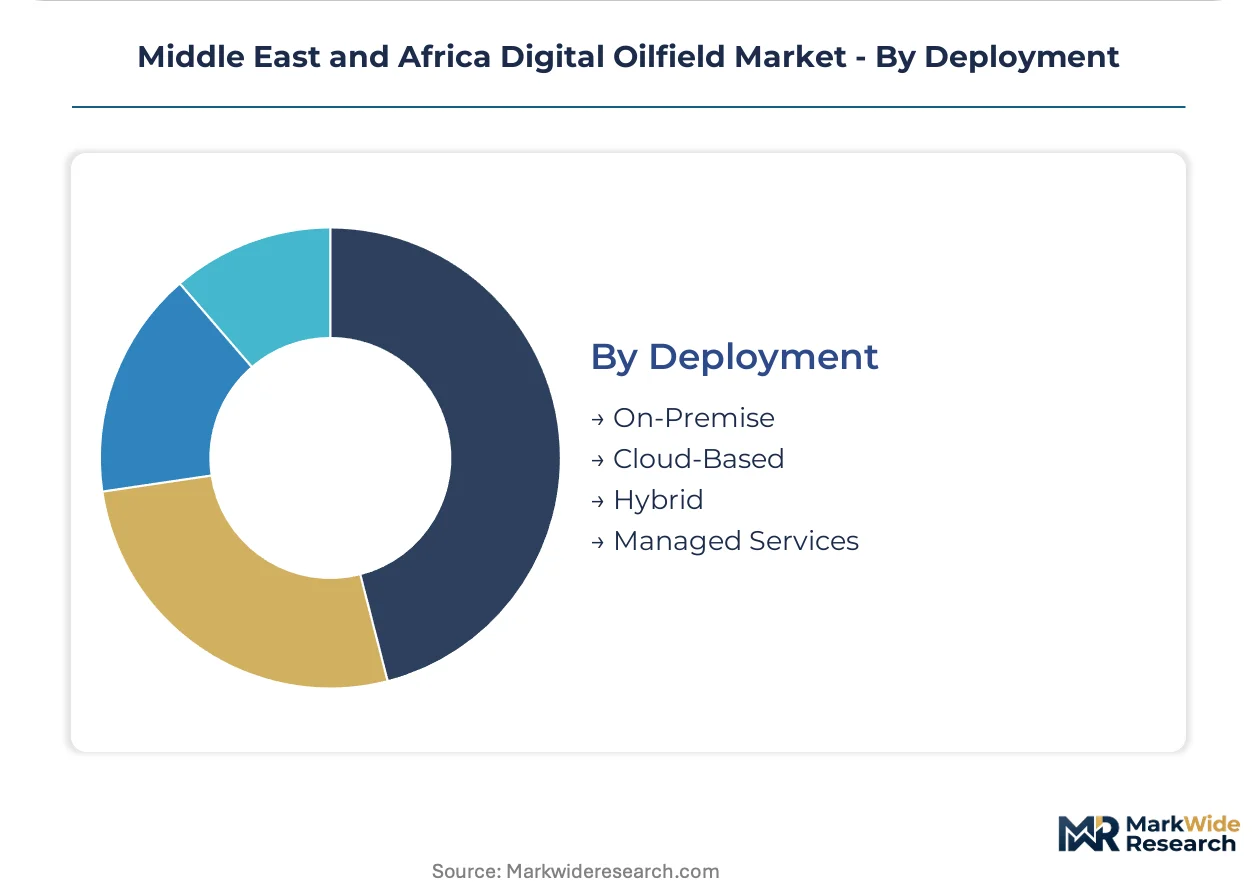
Deployment:
Supply concentration in cloud infrastructure shapes hybrid architecture adoption timelines.
- Cloud-Based:Sovereign data residency requirements are stimulating domestic hyperscale facility construction in Saudi Arabia and the UAE. Microsoft dominates contracting with national operators seeking NCEMA guideline compliance without on-premise infrastructure commitments.
- Hybrid:Edge-to-cloud architectures disperse compute between wellhead sensors and centralized platforms to reduce latency for artificial lift optimization. Gulf operators are fragmenting processing across wellhead nodes and regional data centers.
- On-Premise:Air-gapped operational networks satisfy SFDA cybersecurity mandates for critical infrastructure.
- Managed Services:Continuous monitoring obligations replace discrete installation deliverables under zero-trust requirements.
Cloud-Based retains volume leadership; Hybrid holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technology exports from the United States and Europe flow into Saudi Arabia and the UAE as primary demand anchors, with secondary procurement corridors extending into Nigeria and South Africa. Gulf national oil companies absorb the majority of foreign digital oilfield investment through mega-field development programs.
Saudi Arabia
SFDA cybersecurity mandates for critical energy infrastructure are accelerating operational technology network upgrades across Saudi Aramco's Eastern Province installations. The Kingdom's dual-carbon technology framework subsidizes digitization investments that reduce flaring intensity. Dhahran and Jubail industrial clusters concentrate AI-driven production optimization deployments at Ghawar and Safaniya mega-fields.
United Arab Emirates
ADNOC's unified physics-based digital twin programs integrate geomechanical analysis with production scheduling across offshore and onshore assets. NCEMA operational technology guidelines shape procurement specifications for sovereign data residency compliance. Abu Dhabi emirate hosts the region's densest concentration of cloud-based deployment models among independents seeking capital expenditure flexibility.
Nigeria
DPR digital reporting mandates are stimulating first-mover procurement in underpenetrated deepwater blocks operated by international joint ventures. The country's petroleum regulator requires standardized production data submission through integrated digital platforms. Lagos and Port Harcourt serve as commercial gateways for vendors establishing local partnerships in offshore digitization.
South Africa
Mature onshore fields in the Karoo and offshore blocks along the southern coast require decline-curve management systems as reservoir complexity exceeds conventional modeling capacity. The country's energy regulator emphasizes operational technology convergence with grid infrastructure planning. Cape Town's technology services sector supports regional implementation of remote monitoring architectures for unmanned facilities.
Qatar
North Field expansion programs are embedding IoT sensor networks at sub-second intervals for real-time choke optimization across the world's largest non-associated gas reservoir. QatarEnergy's procurement frameworks prioritize single-platform accountability for reservoir-to-export optimization. Ras Laffan Industrial City concentrates edge computing deployments that disperse processing between wellhead nodes and regional data centers.
Middle East and Africa Digital Oilfield Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a consolidated vendor landscape anchored by integrated oilfield service conglomerates. National operators in the Gulf Cooperation Council are collapsing vendor silos by demanding unified platform accountability. Three archetypes dominate: full-stack subsurface software providers, specialized turbomachinery diagnostics vendors, and sovereign cloud infrastructure contractors. Competitive moves concentrate on strategic partnerships with national oil companies and technology licensing arrangements that satisfy data localization requirements.
Among Houston-based integrated service providers, Schlumberger Limited and Baker Hughes Company exemplify the full-stack archetype through subsurface digital twin and predictive analytics positioning. Microsoft occupies a distinct position as the dominant sovereign cloud infrastructure contractor with national operators. These three anchors represent the primary competitive vectors through which procurement specifications flow into the Middle East and Africa market.
| Leading Market Players |
|---|
| Schlumberger Limited |
| Baker Hughes Company |
| Halliburton |
| Weatherford |
| NOV Inc. |
| IBM Corporation |
| Microsoft |
| Emerson Electric Co. |
| ABB |
| Others |
Supply & Pricing Matrix
Undercapacity in Asian semiconductor foundries is tightening sensor lead times and compressing margins for Gulf operators deploying dense IoT networks across mega-fields. This utilization squeeze feeds directly into procurement posture, forcing national oil companies toward longer-term service contracts that lock in vendor capacity.
Pricing Analysis
Current-generation edge computing hardware commands premium positioning against prior-generation SCADA retrofit kits and next-generation sovereign cloud infrastructure still under construction. Three-tier pricing structure across premium AI-driven optimization platforms, standard telemetry bundles, and economy-grade remote monitoring separates vendor tiers by certification level and after-sales service depth. Pricing pressure stems from concentrated buyer power among Saudi Aramco and ADNOC procurement frameworks that consolidate vendor accountability. Independent producers exhibit highest price sensitivity due to capital constraints, while national operators absorb premium tiers for compliance-certain deployments.
Supply Chain Analysis
Export-control restrictions on advanced AI accelerators and encryption technologies are constraining flows into Saudi Arabia and the UAE, forcing localization of edge-device assembly. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, while sensor manufacturing draws from China, Germany, and Japan. Supply chain vulnerability rests on single-source dependencies for subsea fiber-optic cables and specialized vibration sensors. Distribution runs through integrated service provider channels anchored by Schlumberger and Baker Hughes logistics networks across Dhahran, Abu Dhabi, and Lagos hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping competitive positioning as national operators collapse vendor silos around unified reservoir-to-export accountability, with interoperability mandates forcing ecosystem consolidation.
For Market Incumbents: Insulate high-complexity reservoir digital twin deployments through captive geoscience talent pools and backward integration into subsurface software stacks. Threat substitution from hyperscaler cloud platforms demands certification investment in SFDA and NCEMA compliance pathways. Prioritize channel control over marginal field service contracts where independents seek performance-based pricing. For New Entrants and Emerging Players: Establish a beachhead in Nigerian deepwater digitization where DPR reporting mandates create first-mover windows without entrenched incumbent relationships. Underpenetrated offshore blocks operated by international joint ventures offer lowest competitive density. Pursue local partnership structures with Lagos-based implementation firms as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-based deployment models as sovereign hyperscale facilities reduce infrastructure ownership requirements. Long-term viability favors vendors with recurring revenue streams from continuous monitoring obligations under zero-trust architectures. Acquisition targets should demonstrate NCEMA or SFDA certification completion. Watch for inflection signals in Abu Dhabi marginal field technical service agreement volumes.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Architecture Deployment | SFDA compliance deadlines accelerate procurement cycles for encrypted telemetry pathways across Saudi critical infrastructure. |
| Sovereign Cloud Facility Construction | Domestic hyperscale buildouts in Riyadh and Abu Dhabi satisfy NCEMA data residency without foreign infrastructure dependency. |
| Performance-Based Contracting Expansion | Vendor compensation tied to barrel recovery metrics concentrates in Abu Dhabi marginal field redevelopment programs. |
| Subsurface Digital Twin Integration | Unified physics-based models collapse distinction between geomechanical analysis and production scheduling at Saudi mega-fields. |
| Predictive Turbomachinery Analytics | Vibration sensing convergence with machine learning opens maintenance scheduling white space across mature Gulf compressor fleets. |
Research Methodology
A standing panel of reservoir engineering directors, OT cybersecurity leads at national oil companies, cloud procurement officers, and integrated service provider account executives provided ongoing calibration against market developments. Primary interview intelligence combined with secondary validation from SEC filings of listed oilfield service providers, Saudi Aramco and ADNOC procurement disclosure frameworks, and DPR regulatory circulars. Bottom-up deployment tracking across technology segments triangulated against top-down hydrocarbon production forecasts.
Scenario-bracketing framed low, base, and high cases around semiconductor supply disruption severity and Gulf Cooperation Council fiscal commitment trajectories. The analytical framework modeled technology adoption curves, application penetration rates, and deployment model shifts across the projection horizon. Segmentation dimensions included technology generation, operational application maturity, end-user procurement sophistication, and cloud sovereignty requirements. CAGRs derived from deployment run-rate analysis and vendor contract value disclosures.
Sensitivities concentrate around semiconductor foundry utilization rates, SFDA enforcement intensity, and Abu Dhabi dual-carbon subsidy renewal. Forecasts reflect documented assumptions on edge-device cost curves and national operator digitization budget allocations. Material shifts in Gulf sovereign wealth fund energy technology investment priorities or export-control regime expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Workover Rigs Market
Oil & Gas
Perforating Gun Market
Oil & Gas
Oilfield Air Drilling Market
Oil & Gas
Wellhead and Christmas Tree Special Parts Market
Oil & Gas
Saudi Arabia Oil and Gas Midstream Market
Oil & Gas
Liner Hanger System Market
Oil & Gas
Sand Screen Sales Market
Oil & Gas
Oilfield Drill Bits Sales Market
Oil & Gas
Vietnam Oil and Gas Market
Oil & Gas
Blowout Preventers (BOP) Market
Oil & Gas
Oil and Gas Storage Market
Oil & Gas
Tricone Bits Market
Oil & Gas
Iran Oil and Gas Exploration and Production Market
Oil & Gas
Land Drilling Rig Market
Oil & Gas
Bunker Liners Market
Oil & Gas
Rig and Oilfield Mats Market