
 Oilfield Casing Spools Market | 2026-2036
Oilfield Casing Spools Market Size, Share, and Industry Trends Forecast 2026-2036
Oilfield Casing Spools Market Analysis
API 6A qualification cycles for wellhead equipment is redrawing competitive boundaries across the supply base. Baker Hughes leverages integrated manufacturing networks to sustain certification breadth across pressure classes. Schlumberger anchors its position through technology leadership in automated spool installation systems. The Weir Group Plc differentiates via specialized alloy casting capabilities that meet NACE MR0175 sour service requirements.
Oilfield casing spools are forged or cast steel wellhead components, typically manufactured from low-alloy chromium-molybdenum grades with rated working pressures from 2,000 to 20,000 psi, designed to suspend casing strings and seal annular spaces between casing intervals. Hydraulic casing spools command premium positioning due to integrated seal-activation mechanisms that reduce rig-up time during high-pressure completions. Remote monitoring technology represents the fastest-expanding segment as operators deploy pressure-transmitting spools to support digital wellhead architectures.
API standards, NACE sour service specifications, and national petroleum regulators in the US, Brazil, and Norway govern material selection, pressure testing protocols, and traceability documentation for casing spool deployment. These frameworks elevate compliance costs for entrants while reinforcing incumbent positions among qualified manufacturers. Stakeholders must weigh capital allocation between conventional spool capacity and digitally enabled product lines as operator procurement criteria evolve.
Market Dynamics
API 6A certification tightening is restructuring supplier hierarchies as material traceability requirements force foundries to retool quality systems. Operators now disqualify uncertified vendors from deepwater tenders regardless of price position.
Growth Catalysts
- Deepwater exploration expansion:Offshore Brazil and West Africa development programs are mandating 15,000-20,000 psi rated spools for pre-salt formations. Petrobras procurement specifications prioritize stackable configurations.
- Digital wellhead architectures:Pressure-transmitting spools with embedded sensors enable real-time annular monitoring. Operators deploy these in Permian Basin horizontal completions to reduce intervention frequency.
- NACE MR0175 sour service standards:Hydrogen sulfide-resistant alloy specifications create premium product tiers for high-H2S basins. Compliance opens access to Middle East and Caspian contracts.
Market Restraints
- Chromium-molybdenum alloy price volatility:Raw material cost swings compress margin predictability for foundries maintaining API-qualified heat lots. Inventory carrying costs rise with certification batch requirements.
- Supply concentration in specialty forging:North American and European qualified foundries control high-pressure large-bore capacity. Lead times extend when single-source dependencies emerge.
- Extended API 6A recertification cycles:Design validation testing for new pressure classes requires 18-24 month engineering timelines. Product development velocity slows relative to operator demand signals.
Strategic Opportunities
- Remote monitoring integration:IoT-enabled spool systems converge with SCADA platforms to automate pressure alerts. Early deployments in Norwegian North Sea fields demonstrate maintenance cost reduction.
- Subsea tieback standardization:Modular spool designs compatible with subsea production trees address Brazil's pre-salt cluster development. Simplified interfaces reduce installation vessel time.
- Refurbishment and recertification services:Secondary markets for reconditioned high-pressure spools emerge as capital discipline constrains greenfield equipment budgets. Third-party inspection protocols from DNV support asset life extension.
Industry Challenges
- Welding inspector certification scarcity:ASME Section IX qualified welders for sour service alloys command premium wages. Training pipeline gaps constrain foundry expansion plans.
- Legacy wellhead compatibility:New spool geometries must interface with 30-year-old flange specifications in mature basins. Retrofit engineering consumes disproportionate design resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oilfield Casing Spools Market |
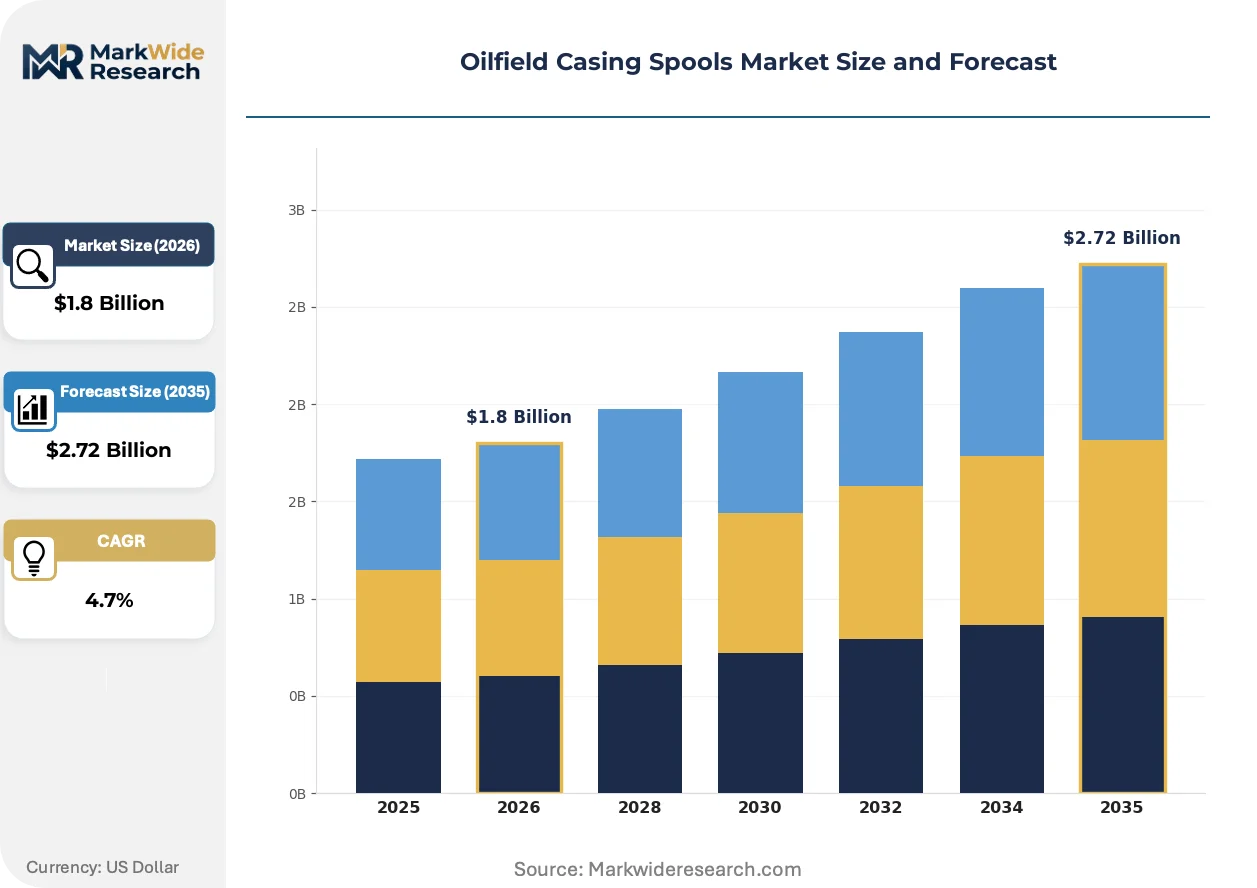
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Casing Spools, Hydraulic Casing Spools, Stackable Casing Spools, Dual-Bore Casing Spools Service Type: Installation Services, Inspection Services, Maintenance Services, Rental Services End User: Oil Production Companies, Gas Exploration Firms, Contractors, Service Providers Technology: Conventional Technology, Remote Monitoring, Automation Technology, Advanced Materials |
| Companies Covered | Baker Hughes, Schlumberger, The Weir Group Plc, Uztel SA, Sentry Wellhead Systems LLC, Delta US Corp. LLC, Worldwide Oilfield Machine Inc., Jiangsu HongFei Petroleum Machinery Manufacturing Co. Ltd., Yantai Jereh Oilfield Services Group Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oilfield Casing Spools Market Emerging Trajectories
Additive manufacturing of nickel-alloy spool components is disrupting conventional casting economics for complex geometries. Powder-bed fusion techniques now achieve pressure-containing properties previously requiring wrought forgings.
Directed energy deposition is fragmenting the traditional foundry-to-machining supply chain. Supermajor operators in the Gulf of Mexico pilot printed replacement flanges for emergency repairs, compressing lead times from 16 weeks to 72 hours. This capability is fragmenting procurement patterns as regional print-service bureaus displace centralized manufacturing for non-critical path components.
Brazil's ANP technical regulations for wellhead equipment now mandate third-party verification of burst and collapse ratings for all subsea spool applications. The industrial consequence elevates documentation burdens on suppliers while creating specialized niche for accredited testing laboratories. European manufacturers with pre-existing DNV-ST-F101 qualification protocols capture disproportionate share of pre-salt supply contracts.
Operator purchasing consortia are consolidating spool procurement across multiple drilling programs. Independent producers in the Permian Basin pool volumes through supply cooperatives, displacing individual rig-level contracting. This concentration is most visible in West Texas where three buying groups now represent 40% of horizontal completion spool demand, forcing vendors to restructure pricing and service models around aggregate volume commitments rather than single-well transactions.
Oilfield Casing Spools Market Segmentation
Casing spool procurement patterns diverge sharply across operator profiles and well complexity tiers. API 6A certification requirements create distinct product hierarchies that reshape vendor selection criteria for each segment cluster.
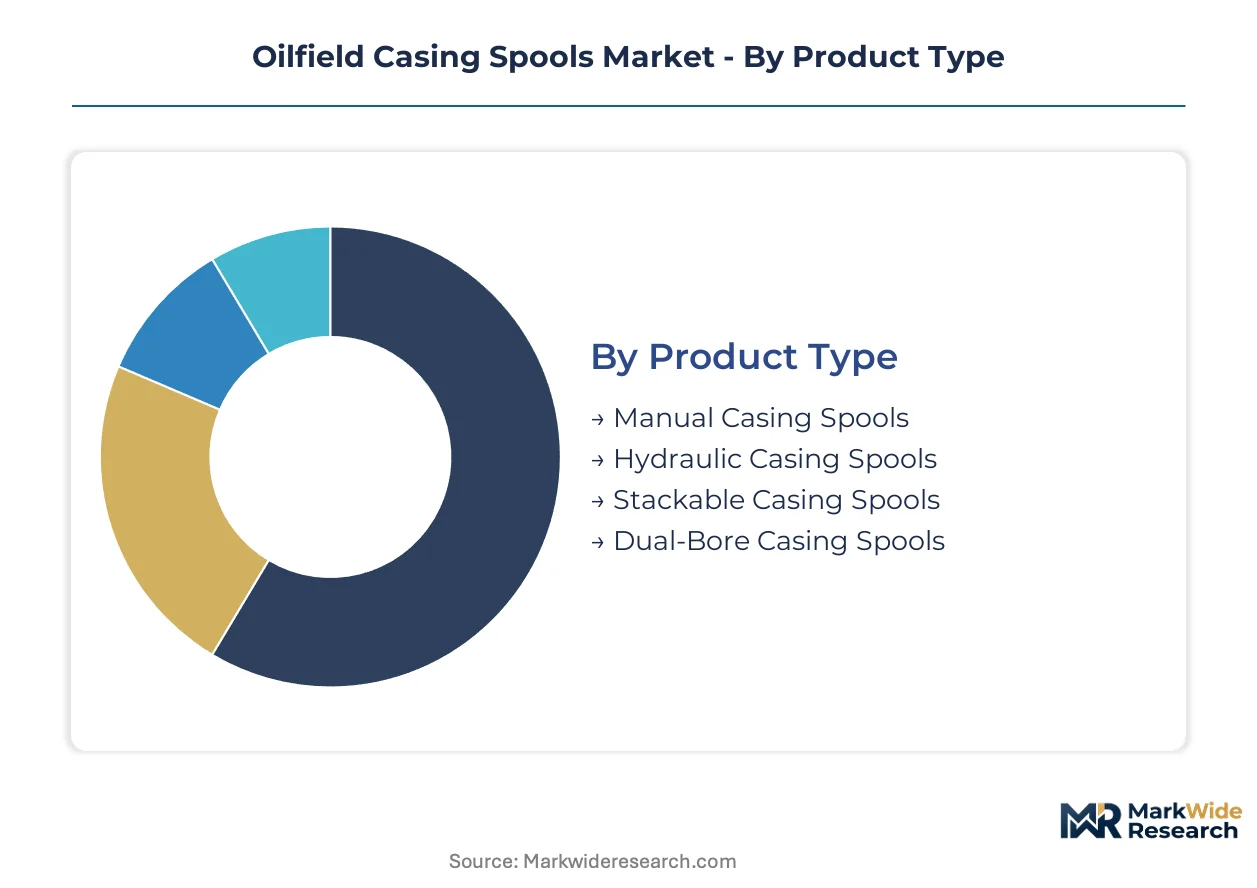
Product Type:
API 6A pressure class ratings differentiate commercial positioning across product categories, with 15,000-20,000 psi qualifications commanding tender eligibility for deepwater work.
- Manual Casing Spools:Bolted flange designs with metal-to-metal seals serve conventional land completions where rig-up time carries lower cost weight. Permian Basin independents specify these for vertical well programs where pressure ratings stay below 5,000 psi.
- Hydraulic Casing Spools:Integrated seal-activation mechanisms reduce connection time during high-pressure completions. Petrobras pre-salt procurement specifications prioritize these for stackable wellhead configurations where annular isolation reliability is non-negotiable.
- Stackable Casing Spools:Modular geometries enable multi-casing suspension in horizontal completions. Demand concentrates in West Texas where laterals require three or more casing intervals.
- Dual-Bore Casing Spools:Parallel flow paths accommodate simultaneous production and intervention access. Norwegian North Sea operators deploy these for subsea tiebacks where vessel day rates amplify installation cost sensitivity.
Manual casing spools handle the majority of throughput; hydraulic casing spools are gaining share fastest as deepwater specifications tighten.
Service Type:
Service economics track capital discipline cycles, with rental and refurbishment offerings expanding as operators defer greenfield equipment purchases.
- Installation Services:Rig-site assembly and pressure testing of spool stacks requires ASME Section IX qualified welders. West African offshore projects source these through integrated drilling contractors to manage single-point accountability.
- Inspection Services:Magnetic particle and ultrasonic examination protocols verify continued fitness for service. DNV-ST-F101 accredited laboratories capture pre-salt contract flow as Brazil's ANP mandates third-party verification.
- Maintenance Services:Seal replacement and flange re-machining extend asset life in mature basins. Gulf of Mexico shelf operators favor these programs to defer replacement capital.
- Rental Services:Short-term spool deployment for exploration drilling reduces inventory carrying costs. Permian Basin supply cooperatives aggregate demand to negotiate fleet access across multiple operators.
Installation services anchor revenue stability; rental services are climbing the fastest as capital allocation tightens.
End User:
Procurement authority concentrates differently across organizational types, with national oil companies driving standardization and independents prioritizing flexibility.
- Oil Production Companies:Integrated majors maintain qualified vendor lists spanning full API 6A pressure classes. Their tender specifications shape foundry investment priorities for high-pressure large-bore capacity.
- Gas Exploration Firms:Sour service requirements dominate material selection for high-H2S basins. NACE MR0175 compliance opens access to Middle East and Caspian development programs.
- Contractors:Drilling and completion contractors specify spool configurations based on well design parameters. Their procurement decisions bridge operator requirements and manufacturer capabilities.
- Service Providers:Wellhead service companies maintain refurbished inventory for emergency replacement. Their regional stocking strategies reduce lead times for critical path components.
Oil production companies direct the largest procurement volumes; gas exploration firms are expanding most quickly as sour gas developments accelerate.
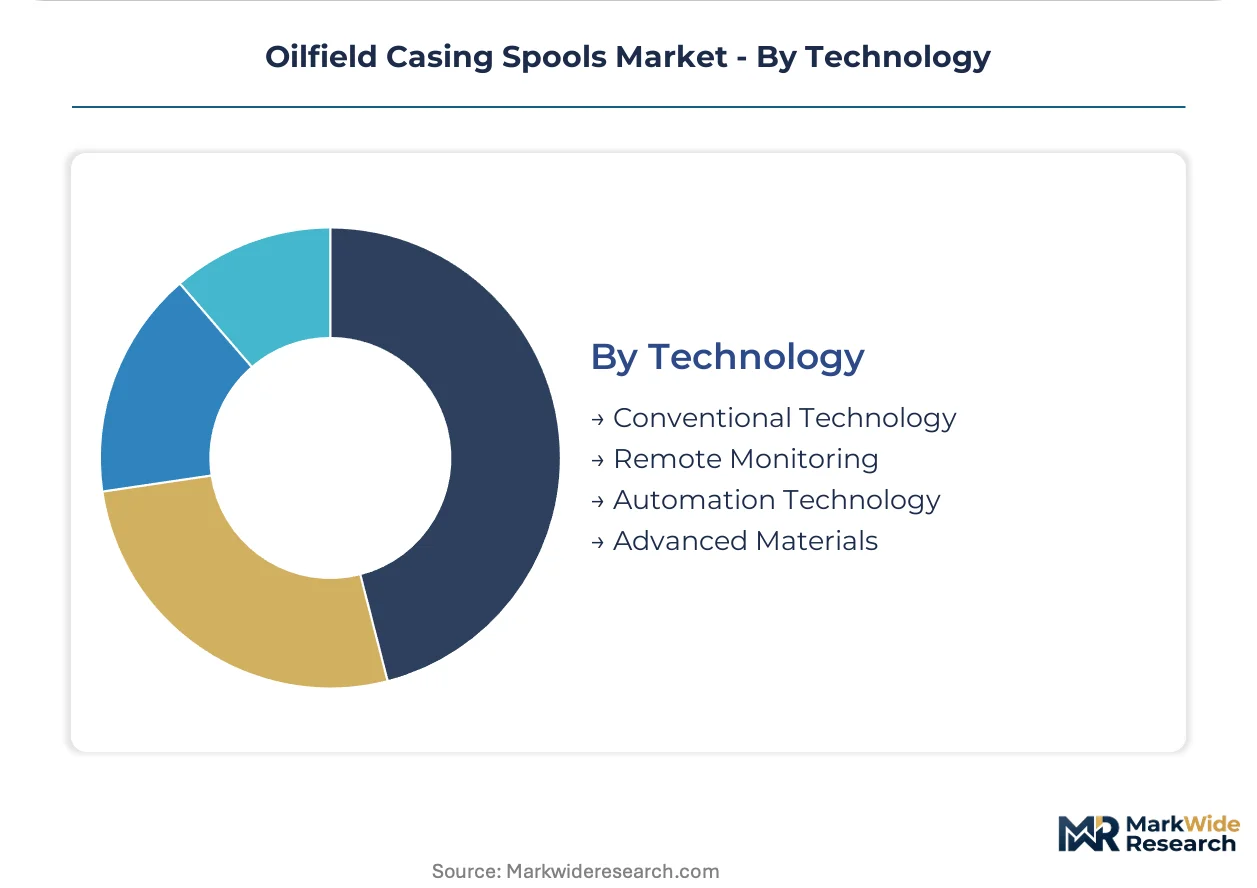
Technology:
Technology tiering reflects operator digital maturity, with sensor integration creating premium positioning against conventional mechanical designs.
- Conventional Technology:Mechanical seal systems without instrumentation serve cost-sensitive land markets. These retain share in basins where digital infrastructure investment lags drilling activity.
- Remote Monitoring:Pressure-transmitting spools with embedded sensors enable real-time annular monitoring. Norwegian operators deploy these to reduce platform intervention frequency and support unmanned facility concepts.
- Automation Technology:Actuated seal systems enable remote pressure control during managed pressure drilling. Gulf of Mexico deepwater trials demonstrate reduced non-productive time during connection sequences.
- Advanced Materials:Nickel-alloy and titanium grades address extreme corrosion environments. Additive manufacturing of these components is fragmenting traditional foundry economics for complex geometries.
Conventional technology retains the installed base; remote monitoring is the fastest mover on share as digital wellhead architectures spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deepwater operators and shale independents concentrate procurement authority in distinct geographic clusters. National oil companies anchor high-pressure specification demand while independents drive volume through supply cooperatives.
United States
Permian Basin shale plays generate stackable spool demand for multi-casing horizontal completions. FERC pipeline safety regulations indirectly shape wellhead equipment standards through pressure containment expectations. Houston-Galveston industrial corridor hosts qualified foundries serving Gulf of Mexico deepwater programs.
Brazil
Pre-salt formation development mandates 15,000-20,000 psi rated spools for subsea tieback configurations. ANP technical regulations require third-party verification of burst and collapse ratings for all subsea applications. Macaé-Rio de Janeiro manufacturing cluster concentrates specialized alloy casting capacity for Petrobras procurement.
Norway
North Sea unmanned platform concepts drive pressure-transmitting spool deployment for remote annular monitoring. Petroleum Safety Authority well integrity regulations mandate real-time pressure surveillance for subsea installations. Stavanger-Bergen technology corridor leads digital wellhead architecture integration with SCADA platforms.
China
Sour gas developments in Sichuan and Tarim basins require NACE MR0175 compliant alloy specifications. MIIT industrial standards for petroleum equipment align with API 6A certification frameworks for domestic manufacturers. Shanghai-Suzhou manufacturing belt develops additive manufacturing capabilities for nickel-alloy spool components.
Saudi Arabia
High-H2S carbonate reservoir development creates premium demand for hydrogen sulfide-resistant spool materials. Saudi Aramco engineering standards exceed API baseline requirements for sour service applications. Eastern Province industrial cities anchor high-pressure large-bore forging capacity for Middle East contract eligibility.
Oilfield Casing Spools Market Vendor Landscape
Player mix skews toward integrated energy technology conglomerates with certified manufacturing networks across multiple pressure classes. Foundry specialists and regional fabricators occupy mid-tier positions serving land-based shale markets. Two strategic archetypes dominate: API-qualified integrated suppliers capturing deepwater tenders, and alloy-casting specialists commanding sour service premiums. Competitive moves concentrate on certification breadth expansion and additive manufacturing capability acquisition.
Among integrated technology providers, Baker Hughes and Schlumberger represent the certification-breadth archetype across global deepwater markets. The Weir Group Plc occupies a specialist position within alloy-casting capabilities for corrosive environments. Regional fabricators including Uztel SA, Sentry Wellhead Systems LLC, and Delta US Corp. LLC exemplify the mid-tier structure serving land-based procurement through qualified vendor relationships.
| Leading Market Players |
|---|
| Baker Hughes |
| Schlumberger |
| The Weir Group Plc |
| Uztel SA |
| Sentry Wellhead Systems LLC |
| Delta US Corp. LLC |
| Worldwide Oilfield Machine Inc. |
| Jiangsu HongFei Petroleum Machinery Manufacturing Co. Ltd. |
| Yantai Jereh Oilfield Services Group Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements with API-qualified foundries lock in chromium-molybdenum alloy supply access while providing 12-18 month price visibility for operators budgeting deepwater wellhead packages. Petrobras and Saudi Aramco procurement frameworks exemplify this structure, where volume commitments to certified suppliers insulate against spot market volatility in specialty steel grades.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange chromium and molybdenum price benchmarks dominate high-pressure spool procurement, with API 6A certification grade and sour service NACE compliance as primary price differentiation drivers. Pricing pressure stems from alloy cost volatility compressing foundry margins on fixed-price legacy contracts. Permian Basin independents exhibit highest price sensitivity through supply cooperative aggregation, while deepwater operators prioritize certification breadth over unit cost.
Supply Chain Analysis
The United States, Brazil, and Norway anchor specialized alloy casting and high-pressure forging capacity for oilfield casing spools. Supply chains draw from chromium-molybdenum steel mills, nickel-alloy additive manufacturing feedstock, and ASME-qualified welding consumables. Single-source vulnerability concentrates in large-bore forging presses exceeding 10,000-ton capacity. Distribution runs through integrated drilling contractors and wellhead service companies maintaining regional stocking positions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
API 6A certification requirements create a defensive moat rooted in regulatory entrenchment, where 18-24 month qualification cycles and material traceability mandates protect incumbent positions against price-based disruption.
For Market Incumbents: Consolidate certification breadth across 15,000-20,000 psi pressure classes to capture pre-salt and sour service contract flow. Acquire additive manufacturing capabilities for nickel-alloy components to offset foundry capacity constraints. Baker Hughes and Schlumberger demonstrate this trajectory through integrated manufacturing network expansion. For New Entrants and Emerging Players: API 6A fast-track partnerships with accredited testing laboratories offer entry pathway into refurbishment and recertification services. Target Permian Basin supply cooperatives with rental fleet offerings to bypass greenfield equipment certification barriers. White-space exists in IoT-enabled pressure-transmitting spools for unmanned platform applications. For Investors and Strategic Acquirers: The market sits at a certification-concentration phase that favors alloy-casting specialists with pre-existing NACE MR0175 protocols. Long-term viability hinges on digital wellhead architecture integration capability. Watch for inflection in additive manufacturing adoption rates for emergency replacement components.| Strategic Initiative | Industry Significance |
|---|---|
| API 6A Certification Expansion | Unlocks tender eligibility for Petrobras pre-salt and Saudi Aramco sour service programs. |
| Additive Manufacturing Capability | Compresses emergency replacement lead times from 16 weeks to 72 hours for Gulf of Mexico operators. |
| Remote Monitoring Integration | Converges pressure-transmitting spools with Norwegian North Sea SCADA platforms. |
| Refurbishment Service Buildout | Captures capital-constrained demand through DNV-accredited asset life extension programs. |
| Supply Cooperative Partnership | Aggregates Permian Basin independent volumes into multi-year fleet access agreements. |
Methodological Framework
A standing panel of wellhead engineering directors, drilling contractor procurement leads, foundry quality managers, and petroleum regulator technical specialists provided ongoing calibration throughout the study. Primary interviews combined with secondary validation against API specification databases, ANP regulatory filings, DNV-ST-F101 accreditation records, and operator tender documentation. Bottom-up spool unit demand estimates triangulated against top-down capital expenditure projections for deepwater and shale development programs.
Consistency checks validated volume and value outputs against external benchmarks including EIA drilling activity reports, IEA upstream investment trackers, and national oil company procurement disclosures across the analysis window. Segmentation modeling incorporated pressure class ratings, service type economics, end-user procurement authority structures, and technology adoption patterns. CAGRs derived from unit demand trajectories weighted by pressure rating premiums and regional cost differentials, with alloy price indices and drilling rig count forecasts as key inputs.
Decision-makers should treat outputs as directional under sustained deepwater exploration commitment and API certification continuity assumptions; material deviation in chromium-molybdenum supply availability or regulatory relaxation would warrant model refresh. Recalibration cycles align with material shifts in pre-salt development pace and additive manufacturing qualification protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Flare Gas Recovery System Market
Oil & Gas
Mineral Oil and Mineral Spirit Market
Oil & Gas
Middle East and Africa Pipeline Maintenance Market
Oil & Gas
Wireline Logging Services Market
Oil & Gas
Drilling Mud Desander and Desilter Market
Oil & Gas
Netherlands LNG Bunkering Market
Oil & Gas
Natural Gas Market
Oil & Gas
GCC Natural Gas Market
Oil & Gas
Oil and Gas Logistics Market
Oil & Gas
Colombia Oil and Gas Downstream Market
Oil & Gas
Rotary Steerable System Market
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
Land Drilling Rig Market
Oil & Gas
Oilfield Equipment Rental Services Market
Oil & Gas
Microbial Enhanced Oil Recovery Market
Oil & Gas
Europe Seismic Services Market