
 Mexico Road Freight Transport Market | 2026-2036
Mexico Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Road Freight Transport Market Foresight
Certified freight capacity is bifurcating the competitive landscape as shippers demand validated cold-chain and hazardous-material credentials. Traxión leverages its integrated fleet platform to dominate dedicated contract logistics across Mexico's manufacturing belts. FedEx sustains cross-border express infrastructure through its bonded warehouse network. Schneider National competes on specialized flatbed and temperature-controlled segments serving automotive and pharmaceutical clients.
Mexico road freight transport encompasses the movement of goods via highway networks using commercial vehicles ranging from light-duty vans to heavy-duty tractor-trailers, typically governed by gross vehicle weight ratings and axle-load limits under federal standards. The sector serves as the backbone of domestic supply chains, connecting manufacturing clusters to ports, border crossings, and consumption centers across Mexican territory. Full Truck Load services anchor revenue stability through long-haul manufacturing contracts, while Refrigerated Transport captures expanding margin pools as perishable exports to the US multiply. Heavy-Duty Trucks dominate asset-intensive operations on the Mexico-Querétaro highway corridor, though Vans are gaining ground in last-mile e-commerce fulfillment around Mexico City and Guadalajara.
Mexico's Secretariat of Infrastructure, Communications and Transportation (SICT) enforces NOM-012-SCT-2-2017 dimensional and weight standards that directly shape fleet replacement cycles and trailer specifications. The Federal Economic Competition Commission (COFECE) monitors route concentration and tariff coordination among carriers to preserve market access for new entrants. Environmental regulations under SEMARNAT are tightening emissions testing for diesel fleets operating in metropolitan zones. Stakeholders must weigh asset renewal timing against evolving compliance thresholds while monitoring how nearshoring-driven volume surges strain highway capacity at critical chokepoints.
Market Dynamics
Nearshoring-driven manufacturing expansion is compressing highway capacity along Mexico's central corridor while NOM-012-SCT-2-2017 weight enforcement accelerates fleet turnover among asset-heavy operators.
Growth Catalysts
- NOM-044-SEMARNAT-2017 emissions standards:Diesel particulate filter mandates are forcing pre-2018 tractor retirements, creating replacement demand for Euro VI-compliant heavy-duty units across SICT-regulated corridors.
- Automotive supplier clustering:BMW, Kia, and Tesla supplier parks in Nuevo León and Baja California are generating dedicated contract volumes that absorb excess capacity on the Monterrey-Saltillo route.
- Refrigerated trailer telematics:Real-time temperature logging is expanding cold-chain certification eligibility, opening pharmaceutical and fresh produce lanes previously restricted to asset-heavy incumbents.
Market Restraints
- Diesel price volatility:PEMEX transport fuel pricing remains politically administered, exposing operators to margin compression when international crude benchmarks diverge from domestic pump rates.
- Driver supply concentration:Licensed heavy-vehicle operators cluster in Guanajuato and Jalisco, creating recruitment bottlenecks for carriers expanding into southeastern states.
- Axle-load enforcement variance:SICT checkpoint calibration inconsistencies between federal and state jurisdictions generate compliance uncertainty on cross-border lanes.
Strategic Opportunities
- Yucatán Peninsula manufacturing:Progreso port expansion and Mérida industrial parks remain underserved by dedicated fleet operators, offering first-mover contract logistics positioning.
- Cross-dock automation convergence:Warehouse management systems integrating with trailer telematics enable dynamic load matching, reducing empty backhaul rates on Mexico City-Guadalajara lanes.
- PROSEC tariff programs:Sector-specific export incentives for automotive and electronics manufacturers are expanding bonded warehouse requirements, favoring carriers with customs certification infrastructure.
Industry Challenges
- Telematics integration complexity:Legacy dispatch systems at mid-sized carriers resist API connectivity with shipper ERP platforms, delaying real-time visibility deployments.
- Hazmat certification timelines:SCT hazardous materials endorsements require 90-day processing windows, constraining rapid response to chemical manufacturing spot demand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Road Freight Transport Market |
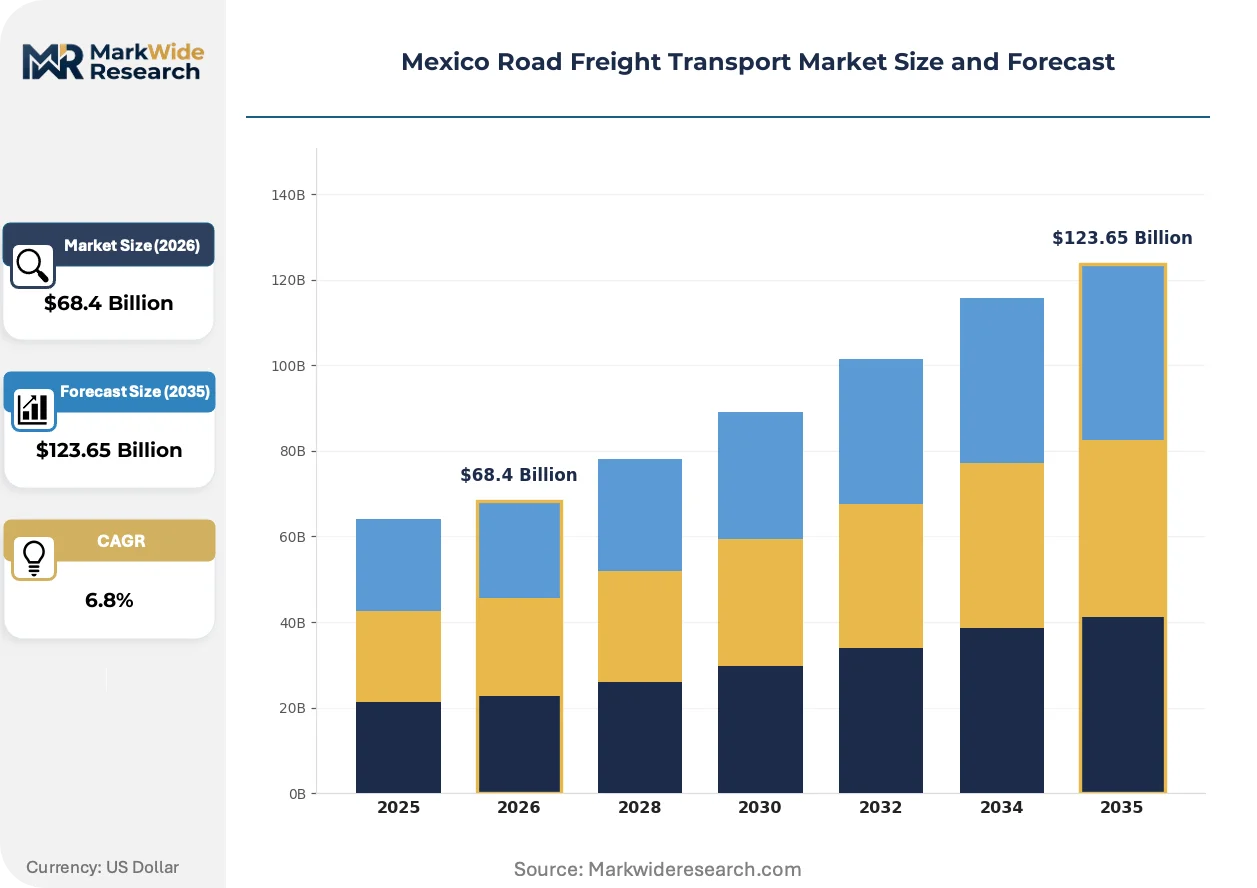
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truck Load, Less Than Truck Load, Refrigerated Transport, Hazardous Goods Transport Vehicle Type: Light-Duty Trucks, Heavy-Duty Trucks, Vans, Trailers End User: Retail Sector, Industrial Goods, Food & Beverage, Construction Delivery Mode: Direct Delivery, Scheduled Routes, On-Demand Delivery, Intermodal Transport |
| Companies Covered | FedEx, C.H. Robinson, Fletes Mexico, Correos de México, DHL Group, Traxión, Transportes Castores, Uber Freight, Schneider National, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Road Freight Transport Market Shifts & Advancements
Digital freight matching platforms are disintermediating traditional broker networks while compressed delivery windows from e-commerce fulfillment centers force asset repositioning strategies.
Telematics-enabled predictive maintenance is fragmenting traditional fleet management economics. Automotive manufacturers operating just-in-time assembly lines are adopting sensor-based axle and brake monitoring to prevent unplanned downtime. This capability is fragmenting the contract logistics market into performance-guaranteed tiers, separating telematics-mature carriers from asset-only competitors.
NOM-044-SEMARNAT-2017 diesel emissions testing is tightening metropolitan zone access for pre-2014 engines. SICT enforcement in Mexico City and Guadalajara is accelerating scrappage subsidies for compliant replacements. Heavy-duty segments serving these corridors face accelerated depreciation schedules, compressing replacement cycle economics.
Shippers are consolidating lane awards around certified cold-chain operators. Pharmaceutical distributors and fresh produce exporters are disqualifying carriers lacking real-time temperature documentation. This concentration is visible in Querétaro and Sinaloa agricultural corridors, where validated fleet operators capture multi-year contract extensions.
Mexico Road Freight Transport Market Segmentation
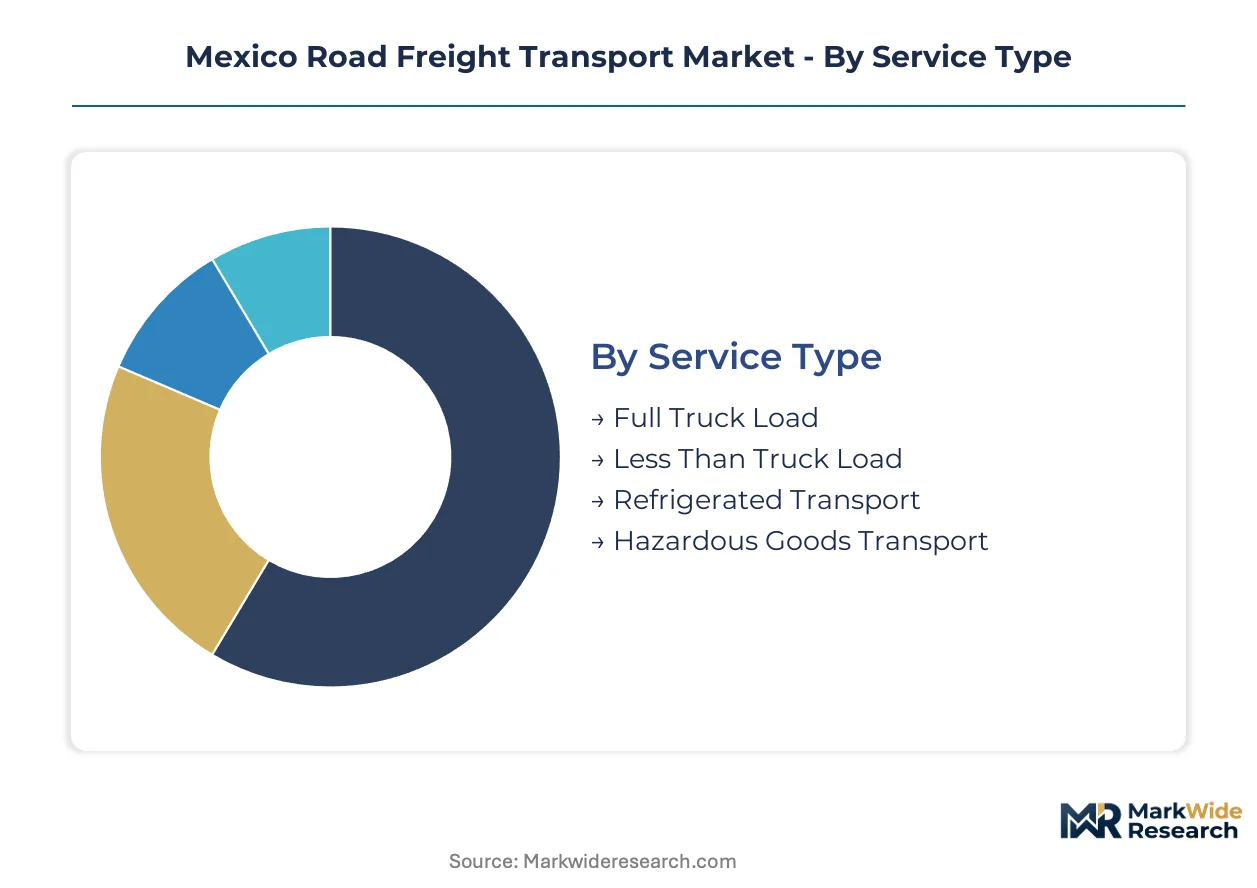
Road freight segmentation in Mexico reveals distinct operational economics across service tiers, with regulatory compliance and nearshoring-driven manufacturing volumes reshaping which segments capture margin expansion. Fleet operators must align asset configuration against specific corridor demands and SICT enforcement patterns to optimize utilization.
Service Type:
Rail intermodal and dedicated private fleets exert the strongest substitution pressure on traditional truckload services along the Monterrey-Saltillo and Mexico City-Querétaro corridors.
- Full Truck Load:Dedicated tractor-trailer units moving single-shipper cargo from manufacturing clusters to border crossings or maritime ports. Demand concentrates in Nuevo León automotive supplier parks where BMW, Kia, and Tesla operations generate predictable long-haul volumes with minimal empty backhaul.
- Refrigerated Transport:Temperature-controlled trailers with real-time telematics logging for perishable cargo integrity. Sinaloa fresh produce exporters and Querétaro pharmaceutical distributors are consolidating lane awards around carriers with validated cold-chain certification, disqualifying asset-light competitors.
- Less Than Truck Load:Consolidated shipments from multiple shippers requiring cross-dock sorting and multi-stop routing. Mexico City-Guadalajara corridors absorb the highest LTL density as e-commerce fulfillment centers force compressed delivery windows.
- Hazardous Goods Transport:Specialized tankers and ventilated trailers for chemical and flammable materials under SCT hazardous materials endorsements. Petrochemical manufacturing in Coatzacoalcos and Tampico generates spot demand constrained by 90-day certification processing windows.
Full Truck Load retains volume leadership; Refrigerated Transport holds the steepest expansion curve.
Vehicle Type:
Cost tier stratification separates asset-intensive heavy-duty operations from flexible van-based last-mile services, with emissions compliance timelines driving replacement cycle divergence.
- Heavy-Duty Trucks:Tractor units above 15 tonnes gross vehicle weight serving manufacturing belt corridors. NOM-044-SEMARNAT-2017 diesel particulate filter mandates are forcing pre-2018 unit retirements, accelerating Euro VI-compliant replacement demand.
- Vans:Light commercial vehicles under 3.5 tonnes gross vehicle weight for urban parcel and express delivery. Mexico City and Guadalajara e-commerce fulfillment centers are expanding van fleet absorption as same-day delivery windows compress.
- Trailers:Unpowered cargo units including dry van, refrigerated, and flatbed configurations governed by NOM-012-SCT-2-2017 dimensional standards. SICT weight enforcement variance between federal and state jurisdictions generates compliance uncertainty on cross-border lanes.
- Light-Duty Trucks:Rigid chassis vehicles between 3.5 and 15 tonnes serving regional distribution and construction material transport. Bajío industrial corridor expansion is absorbing capacity for intra-state manufacturing supplier movements.
Heavy-Duty Trucks dominate asset investment; Vans are expanding most quickly in fleet additions.
End User:
Application-specific requirements fragment service offerings, with pharmaceutical and automotive sectors demanding certified capabilities that exclude generalist carriers.
- Industrial Goods:Machinery, automotive components, and raw materials moving on dedicated contract terms. Northern Mexico manufacturing belt expansion under nearshoring is absorbing excess capacity on scheduled routes.
- Food & Beverage:Temperature-sensitive and dry grocery products requiring hygiene-validated equipment. Fresh produce exports to the US are multiplying refrigerated trailer demand through Sinaloa and Jalisco agricultural corridors.
- Retail Sector:General merchandise and consumer goods for distribution centers and stores. Mexico City metropolitan zone congestion is forcing nighttime delivery windows and urban access permit compliance.
- Construction:Bulk materials, prefabricated components, and heavy equipment on project-based schedules. Infrastructure investment in the Yucatán Peninsula is generating spot demand underserved by dedicated fleet operators.
Industrial Goods anchors contract stability; Food & Beverage is gaining share fastest through export lane expansion.
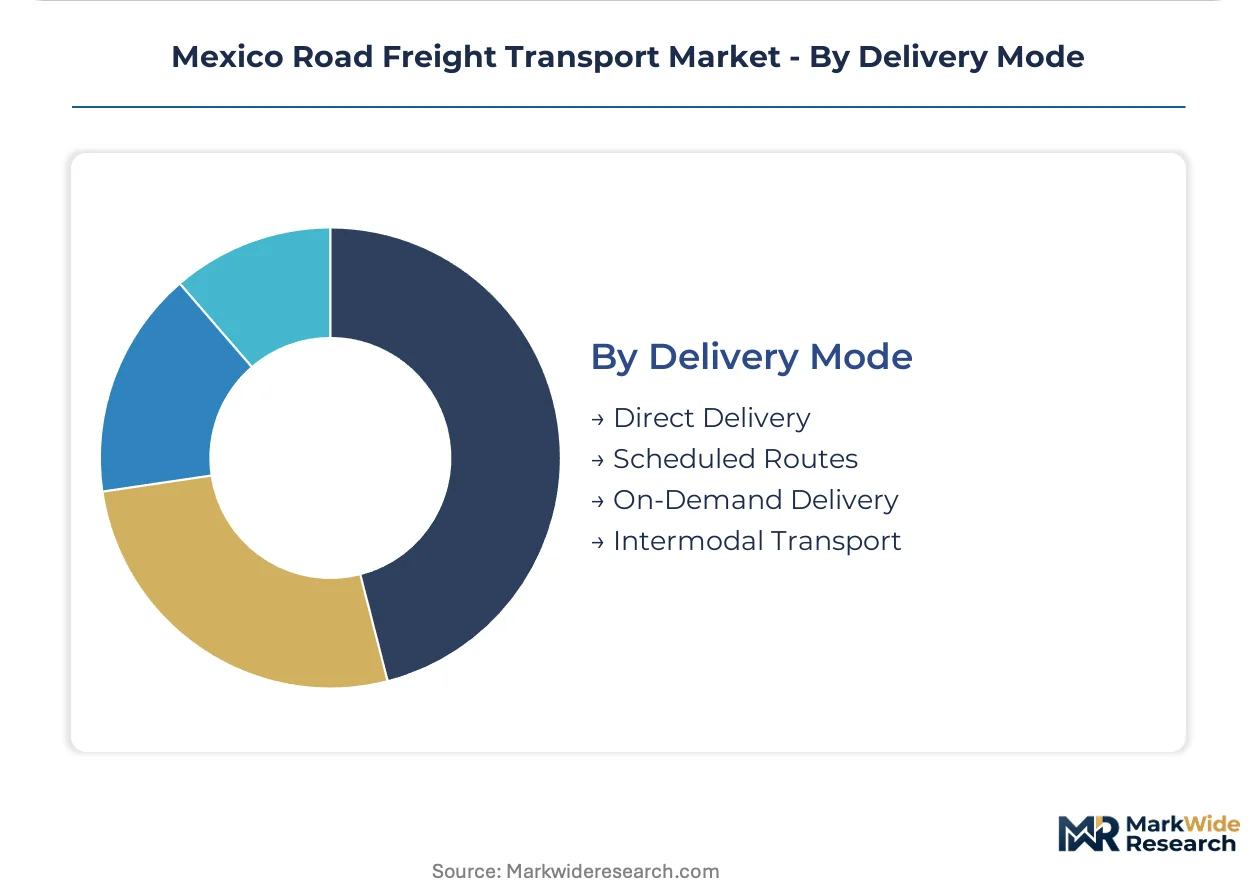
Delivery Mode:
Customer type stratification separates enterprise shippers with predictable routing needs from fragmented spot market demand, with technology integration determining competitive access.
- Scheduled Routes:Recurring lane assignments with fixed timing for manufacturing supply chains. Automotive just-in-time assembly lines in Aguascalientes and Guanajuato require sensor-based axle monitoring to prevent unplanned downtime penalties.
- Direct Delivery:Point-to-point shipment without intermediate handling for time-critical cargo. Pharmaceutical distributors are consolidating awards around carriers with real-time visibility integration.
- Intermodal Transport:Coordinated truck-rail or truck-maritime handoffs for long-distance efficiency. Lázaro Cárdenas port rail connections are absorbing intermodal growth for Asia-Pacific import distribution.
- On-Demand Delivery:Expedited response to unplanned shipment requests through digital freight matching. Platform disintermediation is fragmenting traditional broker networks on Mexico City-Guadalajara lanes.
Scheduled Routes maintains revenue predictability; On-Demand Delivery shows the steepest technology-driven growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators concentrate capacity along Mexico's central manufacturing spine where nearshoring-driven volume surges strain highway infrastructure. SICT enforcement patterns and state-level permitting variance create operational friction across sub-regional corridors.
Mexico City Metro
E-commerce fulfillment centers and automotive just-in-time assembly lines absorb heavy-duty capacity on Mexico-Querétaro highway corridors. SEMARNAT emissions testing restricts pre-2014 engine access to metropolitan zones, accelerating Euro VI-compliant fleet turnover. Tlalnepantla and Cuautitlán Izcalli distribution clusters generate van-intensive last-mile demand as same-day delivery windows compress.
Nuevo León
BMW, Kia, and Tesla supplier parks generate dedicated contract volumes with minimal empty backhaul on Monterrey-Saltillo routes. SICT NOM-012-SCT-2-2017 weight enforcement at federal checkpoints shapes trailer specifications for cross-border lanes. Apodaca industrial corridor anchors refrigerated transport demand for pharmaceutical distributors requiring real-time temperature documentation.
Bajío Region
Querétaro, Guanajuato, and Aguascalientes automotive clusters concentrate scheduled route contracts for sensor-based axle monitoring. SCT hazardous materials endorsement processing creates 90-day bottlenecks for chemical manufacturing spot demand. Silao and Irapuato supplier parks absorb excess capacity as nearshoring accelerates.
Jalisco
Licensed heavy-vehicle operator concentration in Guadalajara generates recruitment competition for carriers expanding southeast. Guadalajara-Mexico City LTL density peaks as cross-dock automation converges with trailer telematics. El Salto industrial zone attracts refrigerated trailer investment for Sinaloa fresh produce export consolidation.
Yucatán Peninsula
Progreso port expansion and Mérida industrial parks remain underserved by dedicated fleet operators. Infrastructure investment generates spot construction material demand lacking scheduled route coverage. Cancún and Mérida distribution corridors offer first-mover contract logistics positioning for telematics-mature entrants.
Mexico Road Freight Transport Market Competitive Landscape
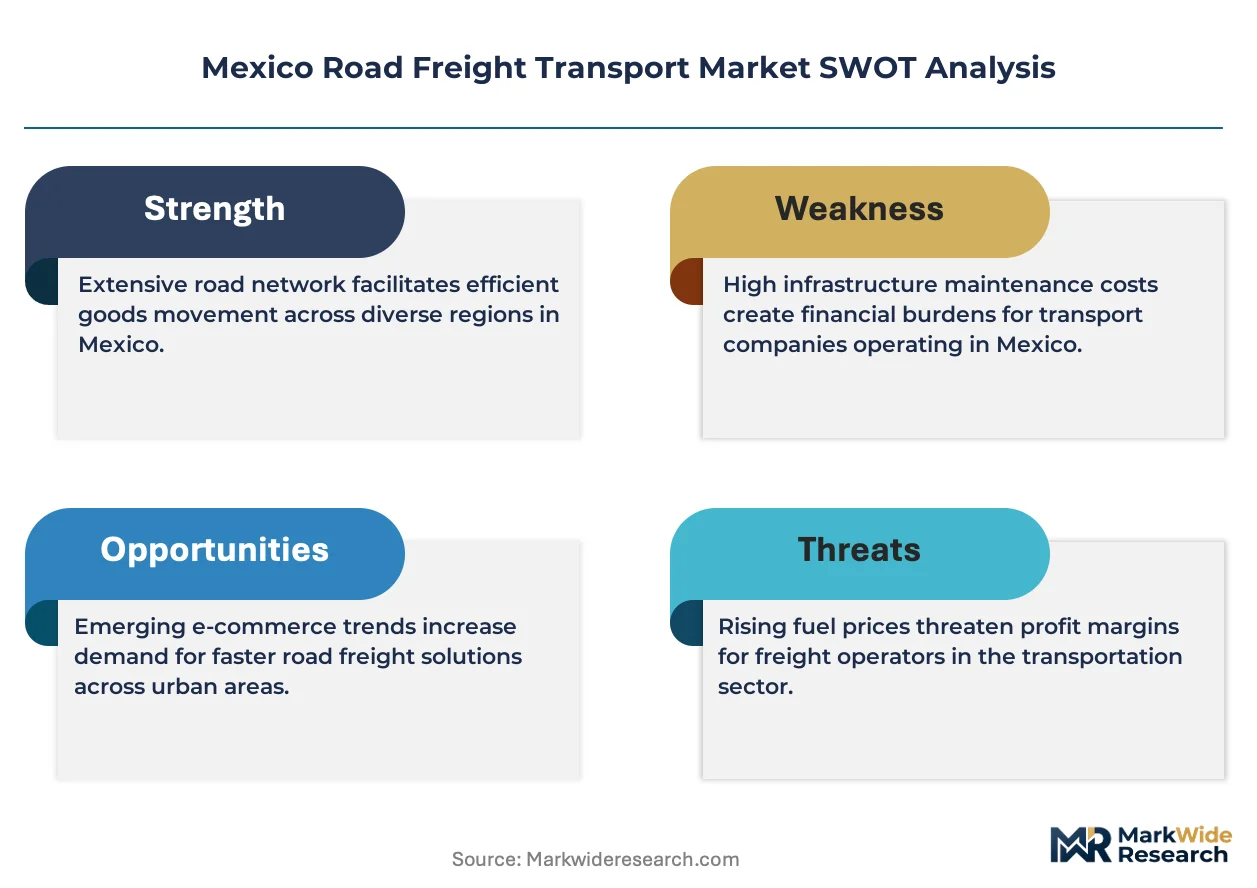
Technology leadership and cost leadership are held by different player archetypes across Mexico's road freight sector. Asset-heavy operators with integrated fleet platforms dominate dedicated contract logistics, while digital-native platforms fragment spot market brokerage. Three archetypes define competitive positioning: telematics-mature carriers capturing certified cold-chain awards, integrated logistics providers controlling manufacturing belt corridors, and platform-based intermediaries disintermediating traditional freight matching. Capacity expansion and customs certification infrastructure represent the dominant competitive moves as PROSEC tariff programs expand bonded warehouse requirements.
Among integrated logistics providers, Traxión occupies a position exemplifying fleet platform dominance across manufacturing belts. FedEx and DHL Group represent cross-border express infrastructure archetypes with bonded warehouse networks. Schneider National anchors specialized segment positioning for temperature-controlled and flatbed services. These three exemplify how certification depth and corridor control determine contract award consolidation.
| Leading Market Players |
|---|
| FedEx |
| C.H. Robinson |
| Fletes Mexico |
| Correos de México |
| DHL Group |
| Traxión |
| Transportes Castores |
| Uber Freight |
| Schneider National |
| Others |
Supply & Pricing Matrix
NOM-044-SEMARNAT-2017 emissions compliance gates both fleet qualification and rate differentiation simultaneously, separating Euro VI-certified operators from legacy diesel competitors while SICT weight enforcement variance across federal and state jurisdictions fragments pricing power along cross-border corridors.
Pricing Analysis
NOM-012-SCT-2-2017 dimensional standards dictate the pricing tier structure across Mexico's road freight sector. Three-tier pricing stratifies across certified cold-chain, standard dry van, and non-compliant legacy fleet levels, with telematics maturity and hazardous materials endorsements driving premium capture. Cost compression in standard dry van segments is intensifying because digital freight platforms fragment broker margins. Small and mid-sized shippers exhibit highest price sensitivity, while automotive OEMs with just-in-time assembly lines prioritize uptime guarantees over rate minimization.
Supply Chain Analysis
Inventory positioning and lead-time compression anchor competitive positioning as nearshoring accelerates. Heavy-duty tractor manufacturing draws from the United States, Germany, and China, while diesel particulate filter technology sources from European and Japanese suppliers. Single-source vulnerability concentrates in telematics hardware modules for refrigerated trailers. Distribution runs through bonded warehouse networks at Lázaro Cárdenas and Progreso ports, with cross-dock automation converging trailer telematics and warehouse management systems on Mexico City-Guadalajara lanes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's road freight sector faces high-growth disruption as NOM emissions mandates force pre-2018 fleet obsolescence and nearshoring manufacturing expansion strains highway capacity beyond current asset deployment.
For Market Incumbents: Consolidate corridor control through Euro VI-compliant fleet renewal and telematics platform integration. Acquire mid-sized carriers in Guanajuato and Jalisco to secure licensed driver pools before recruitment bottlenecks intensify. Defensive positioning against digital freight matching platforms requires real-time visibility API connectivity with shipper ERP systems. For New Entrants and Emerging Players: Lead with Yucatán Peninsula contract logistics where Progreso port expansion and Mérida industrial parks remain underserved by dedicated fleet operators. Target pharmaceutical cold-chain certification in Querétaro and Sinaloa agricultural corridors where validated operators capture multi-year extensions. Go-to-market through PROSEC tariff program customs certification infrastructure. For Investors and Strategic Acquirers: NOM-044-SEMARNAT-2017 diesel particulate filter mandates reshape the acquisition landscape toward telematics-mature carriers with validated cold-chain credentials. Long-term viability centers on asset-light platform models or integrated fleet platforms with manufacturing belt corridor dominance. Watch SICT enforcement calibration standardization across federal-state jurisdictions as inflection indicator for compliance cost predictability.| Strategic Initiative | Industry Significance |
|---|---|
| Euro VI Fleet Renewal Program | SICT emissions enforcement accelerates pre-2018 tractor retirement and replacement demand. |
| Telematics Platform Integration | Real-time temperature logging opens pharmaceutical lanes previously restricted to incumbents. |
| Yucatán Corridor Expansion | Progreso port growth and Mérida industrial parks offer first-mover contract positioning. |
| Cold-Chain Certification Investment | Sinaloa fresh produce exporters consolidate awards around validated fleet operators. |
| Cross-Dock Automation Convergence | Warehouse management systems integrating trailer telematics reduce empty backhaul rates. |
Research Methodology
Desk research of SICT regulatory filings, SEMARNAT emissions databases, and automotive production statistics preceded structured interviews with fleet operations directors, shipper procurement managers, customs brokerage leads, and telematics platform engineers. Secondary validation drew from carrier financial disclosures, port authority throughput data, and industrial park development records. Bottom-up volume triangulation across vehicle type and service tier segments converged with top-down macroeconomic anchoring.
Variance decomposition across the projection horizon isolates volume, mix, and pricing contributions to value expansion. Segmentation dimensions modeled include service type, vehicle category, end-user industry, and delivery mode complexity. CAGRs were derived from regression-based trend extrapolation calibrated against fleet replacement cycle timing and nearshoring manufacturing absorption rates. Forecast inputs incorporate SICT enforcement intensity scenarios and PROSEC tariff program expansion patterns.
The analysis sits within stated boundaries; outcomes outside sustained nearshoring momentum or accelerated emissions compliance timelines would require recalibration. Forecasts reflect documented assumptions regarding diesel price administration continuity and driver supply geographic concentration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Asia Pacific International Express Service Market
Logistics and Shipping
Courier, Express and Parcel Services Market
Logistics and Shipping
Asia Pacific Sea Freight Forwarding Market
Logistics and Shipping
Chile Freight and Logistics Market
Logistics and Shipping
Vietnam Logistics Market
Logistics and Shipping
Qatar Freight and Logistics Market
Logistics and Shipping
Saudi Arabia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asia Pacific Freight and Logistics Market
Logistics and Shipping
UAE Logistics Market
Logistics and Shipping
Asia-Pacific Pharmaceutical Logistics Market
Logistics and Shipping
California Freight and Logistics Market
Logistics and Shipping
Egypt Third Party Logistics (3PL) Market
Logistics and Shipping
Malaysia Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Digital Logistics Market
Logistics and Shipping
ASEAN Warehousing and Distribution Logistics Market
Logistics and Shipping
Digital Freight Brokerage Market