
 Romania Power Market | 2026-2036
Romania Power Market Size, Share, and Industry Trends Forecast 2026-2036
Romania Power Market Analytics
The premium-to-commodity split in Romanian electricity is shifting along the renewable-versus-conventional axis. Hidroelectrica SA leverages its dominant hydro portfolio to anchor supply in the regulated segment. PPC Energie competes aggressively on price in the liberalized retail tier. Nuclearelectrica SA differentiates through baseload nuclear output that commands capacity premiums.
Romania power encompasses electricity generated, transmitted, distributed, and sold across voltage levels from 0.4 kV to 400 kV, serving industrial loads, commercial buildings, and residential consumers. Generation splits across renewable, non-renewable, nuclear, and hydroelectric sources, with photovoltaic and wind turbine installations expanding fastest in the technological mix. Service type segmentation shows distribution and retail capturing margin concentration due to regulated tariff structures, while generation faces merchant price exposure.
ANRE enforces grid codes and unbundling rules that shape market access for new entrants. Romania's alignment with EU Green Deal targets and F-Gas Regulation compliance requirements drives capital allocation toward low-carbon generation assets. Stakeholders must monitor regulatory timing on capacity market design and renewable support scheme auctions to position procurement and investment decisions.
Market Dynamics
ANRE's unbundling mandates and EU Green Deal alignment are forcing capital reallocation across generation portfolios, while industrial buyers in automotive manufacturing lock in contracted capacity ahead of grid code revisions.
Growth Catalysts
- EU Green Deal compliance:Binding decarbonization targets under the F-Gas Regulation are redirecting investment toward photovoltaic and wind installations. Developers accelerate permitting timelines to capture auction windows.
- Muntenia-South demand concentration:Bucharest's consumption cluster anchors load growth, with transmission upgrades reducing congestion penalties for distributors serving the capital region.
- Grid code modernization:ANRE's technical standards for frequency response and reactive power are qualifying newer renewable assets for priority dispatch, improving project economics.
Market Restraints
- Interconnection bottlenecks:Limited 400 kV cross-border capacity with Bulgaria and Hungary traps surplus generation, depressing spot prices during high renewable output periods.
- Lignite transition costs:State-owned coal complexes in Oltenia require expensive remediation and workforce restructuring, straining public balance sheets without private capital relief.
- Gas price volatility:Romania's dependence on Black Sea imports and regional hub pricing exposes combined-cycle operators to margin compression when TTF spikes.
Strategic Opportunities
- Offshore Black Sea wind:Untapped maritime zones offer 30-meter depth contours suitable for fixed-bottom turbines, with grid connection studies advancing near Constanța.
- Green hydrogen offtake:Ammonia and synthetic fuel producers in the Port of Constanța industrial zone are piloting electrolyzer-fed supply chains for export-oriented chemical manufacturing.
- Behind-the-meter solar:C&I rooftops in Cluj-Napoca and Timișoara remain underpenetrated relative to Western European saturation rates, offering installer margin expansion.
Industry Challenges
- Skilled technician shortage:Grid automation and inverter maintenance expertise concentrates in Bucharest and Cluj, leaving secondary cities dependent on outsourced service contracts with extended response times.
- Legacy metering infrastructure:Rural distribution zones retain electromechanical meters that block time-of-use tariff implementation and demand-response program enrollment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Romania Power Market |
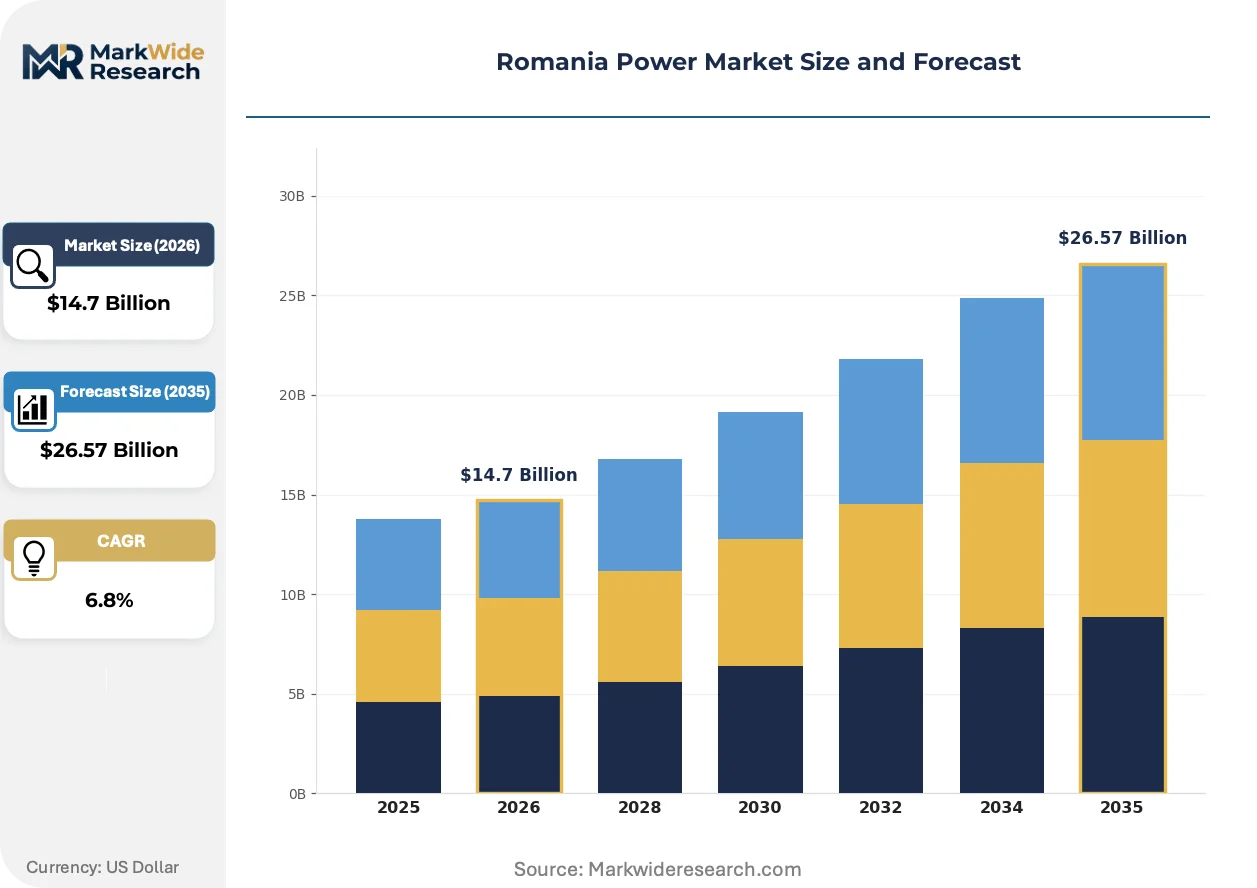
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable, Non-Renewable, Nuclear, Hydroelectric Service Type: Generation, Transmission, Distribution, Retail Technological Type: Photovoltaic, Wind Turbine, Biomass, Gas Turbine End User: Residential, Commercial, Industrial, Government |
| Companies Covered | PPC Energie, Engie Romania, Hidroelectrica SA, Electrica Furnizare, E.ON Energie Romania, OMV Petrom SA, CEZ Romania, Enel S.p.A, Nuclearelectrica SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Romania Power Market Evolving Landscape
Battery energy storage systems are bridging the dispatchability gap for variable renewable assets, while digital substations and peer-to-peer trading platforms reconfigure how electrons are valued and exchanged.
Grid-scale lithium-ion battery installations are integrating frequency regulation and arbitrage services into single asset configurations. Transmission operators in Muntenia and Transylvania are procuring four-hour duration systems to manage evening ramp events. This hybrid revenue stacking is integrating storage into capacity market design discussions at ANRE.
The EU Green Deal's delegated acts on renewable hydrogen are tightening emission thresholds for electrolyzer-powered molecules. Romanian project developers must document grid carbon intensity hourly to qualify for subsidy tiers. Industrial offtakers in chemicals and steel are responding by sourcing dedicated renewable PPA sleeves rather than grid-mix power.
Automotive manufacturers with operations in Argeș and Dâmbovița are consolidating supplier lists around energy partners offering 24/7 carbon-free matching, not annual renewable energy certificates. Tier-1 battery cell plants are driving this specification change, rejecting conventional green tariff products. The shift is most visible among export-oriented suppliers facing Scope 3 disclosure pressure from German OEM customers.
Romania Power Market Segmentation
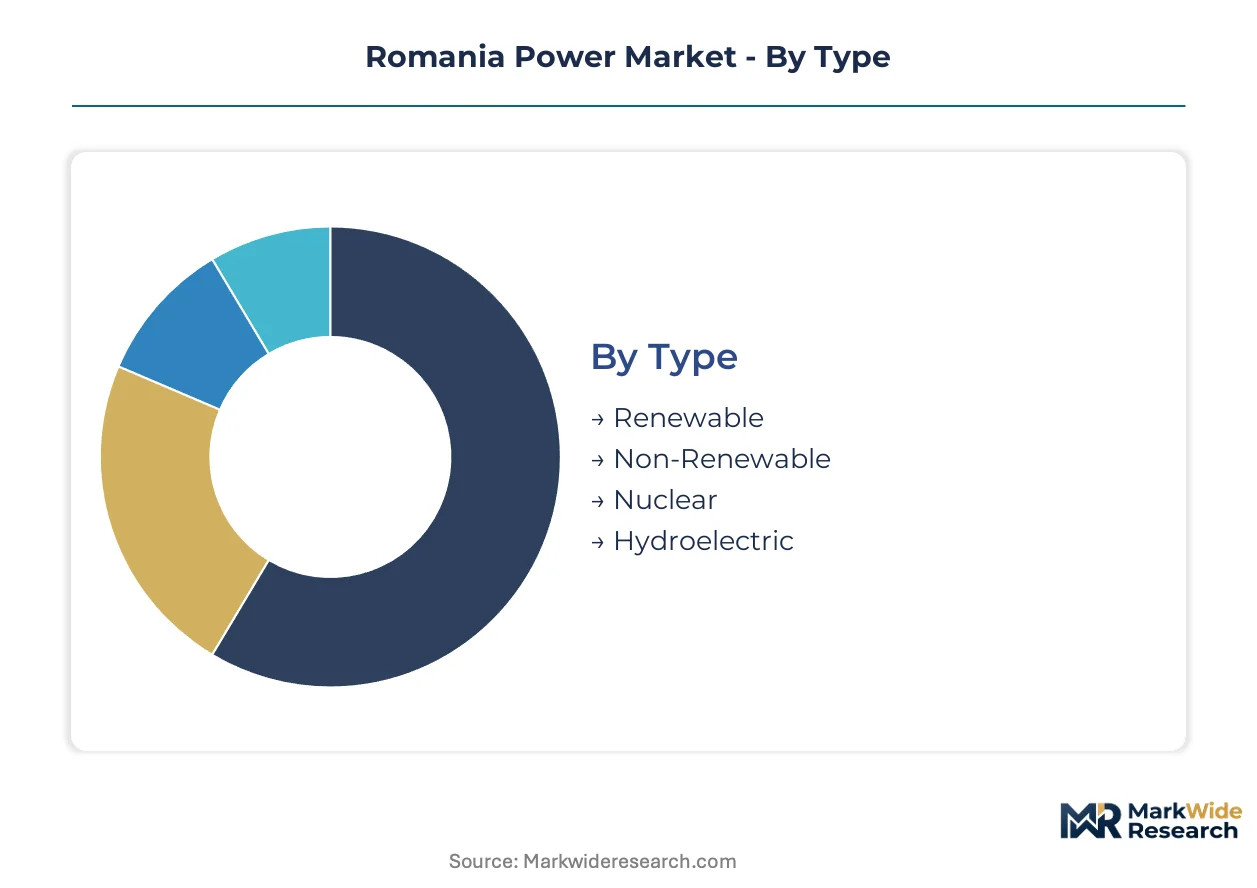
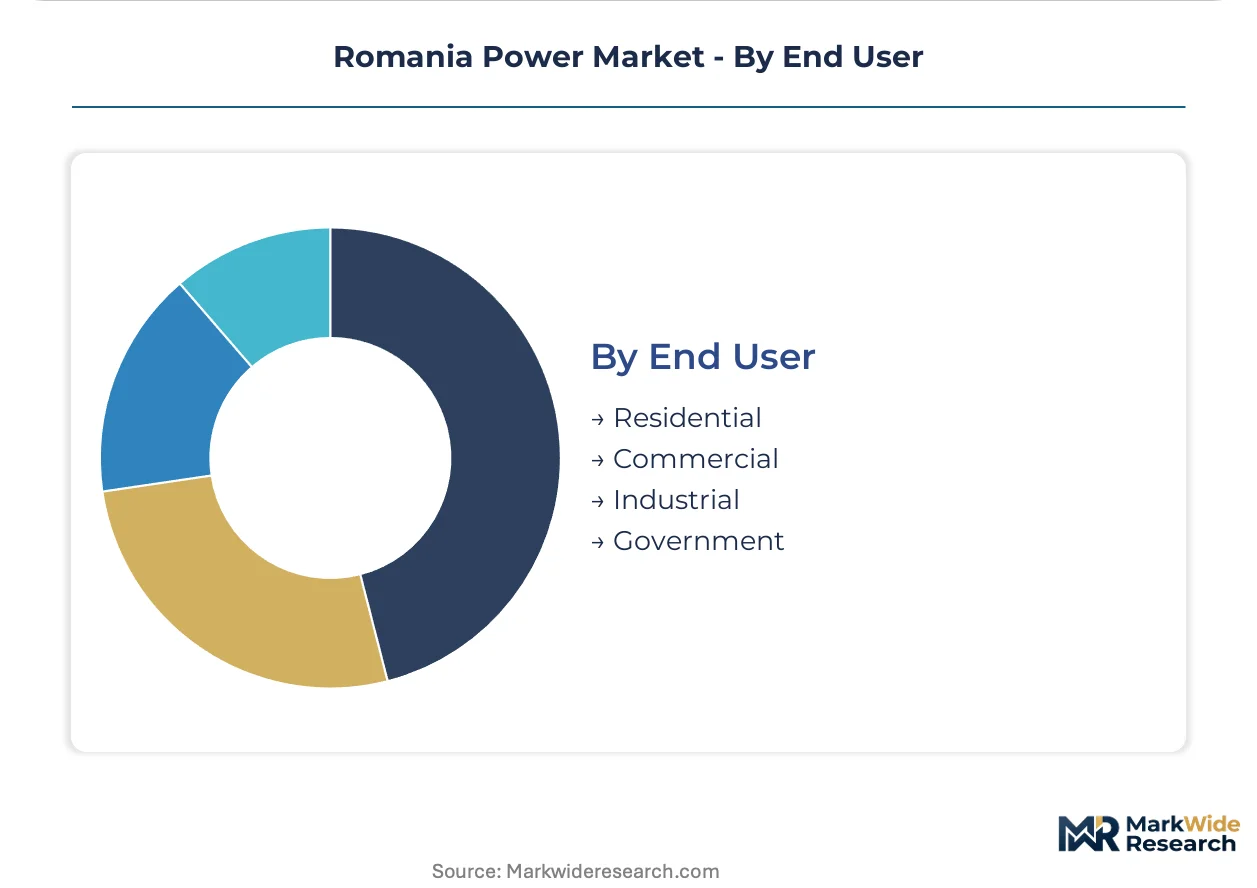
Segmentation in Romania's power sector reveals where capital commitments concentrate and which customer groups drive tariff negotiations. ANRE's unbundling rules create distinct competitive arenas across generation technologies and service layers.
Type:
Capital intensity varies dramatically across generation technologies, with nuclear and hydroelectric demanding the longest construction timelines and largest upfront outlays.
- Renewable:Photovoltaic and wind assets deploy fastest with modular construction, attracting private equity flows to Muntenia-South and Dobrogea zones where irradiance and wind resource density peak.
- Non-Renewable:Natural gas combined-cycle plants offer intermediate capital requirements and dispatch flexibility, though TTF-linked fuel costs compress margins during price spikes.
- Nuclear:Cernavodă's pressurized heavy water reactors require decade-long construction cycles and state-backed financing, delivering baseload output with minimal carbon intensity.
- Hydroelectric:Run-of-river and reservoir configurations dominate Transylvania's mountain catchments, with Hidroelectrica SA controlling the bulk of installed capacity through legacy assets.
Hydroelectric absorbs the bulk of installed capacity; renewable is expanding most quickly.
Service Type:
Margin capture differs sharply across the value chain, with regulated distribution and retail segments offering predictable returns while generation faces merchant price exposure.
- Generation:Power plants convert primary energy into electricity across voltage levels, with revenue tied to day-ahead market prices and bilateral contract premiums negotiated with industrial offtakers.
- Transmission:Transelectrica operates the 400 kV backbone grid, collecting regulated tariffs for wheeling services while managing cross-border interconnection constraints with Bulgaria and Hungary.
- Distribution:Regional operators in Muntenia, Transylvania, and Moldova maintain medium and low-voltage networks, with smart metering rollouts accelerating in urban zones.
- Retail:Suppliers compete for commercial and industrial accounts in the liberalized tier, while regulated tariffs protect residential consumers from price volatility.
Distribution commands the steadiest cash flows; generation offers the highest upside variance.
Technological Type:
Equipment selection determines project economics, with technology maturity curves affecting financing terms and O&M cost structures.
- Photovoltaic:Silicon module prices have collapsed, enabling utility-scale parks in southern Romania to achieve grid parity without subsidy support during peak insolation months.
- Wind Turbine:Onshore installations in Dobrogea and Moldova benefit from consistent wind regimes, though grid code compliance costs for frequency response have risen.
- Biomass:Agricultural residue and forestry waste fuel small-scale cogeneration plants serving district heating networks in rural Transylvania towns.
- Gas Turbine:Flexible peaking units compensate for renewable intermittency, with Black Sea domestic production improving supply security versus import dependence.
Photovoltaic claims the largest share of new capacity additions; offshore wind turbine development is climbing the fastest.
End User:
Load profiles and price sensitivity diverge across customer categories, shaping product design and contracting structures.
- Residential:Household consumption clusters in Bucharest and secondary cities, with universal service obligations requiring suppliers to offer regulated tariffs regardless of credit risk.
- Commercial:Office buildings and retail chains in Cluj-Napoca and Timișoara seek behind-the-meter solar to hedge against distribution tariff escalation.
- Industrial:Automotive manufacturers in Argeș and Dâmbovița negotiate 24/7 carbon-free matching clauses, rejecting annual certificate-based green products.
- Government:Public buildings and military installations procure through centralized frameworks, with EU-funded efficiency retrofits reducing aggregate demand.
Industrial offtakers absorb the deepest volume concentration; commercial segment procurement is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bucharest's consumption cluster anchors Romanian power demand, with Muntenia-South absorbing the deepest industrial load concentration. Regional disparities in grid infrastructure and resource availability shape investment allocation across the country.
Muntenia-South
Automotive manufacturers in Argeș and Dâmbovița counties are locking in contracted capacity ahead of ANRE grid code revisions. The region's transmission upgrades reduce congestion penalties for distributors serving Bucharest's metropolitan load. Industrial parks near Ploiești are piloting behind-the-meter solar installations to hedge distribution tariff escalation.
Transylvania
Run-of-river hydroelectric assets in the Carpathian catchments supply baseload power to Cluj-Napoca's expanding tech sector. ANRE unbundling mandates have accelerated private investment in distribution automation across Brașov and Sibiu. Rural zones retain legacy electromechanical meters that block time-of-use tariff implementation.
Dobrogea
Onshore wind installations near Constanța benefit from consistent Black Sea wind regimes and proximity to grid interconnectors. Port of Constanța industrial offtakers are piloting electrolyzer-fed green hydrogen supply chains for ammonia production. Maritime zones offer 30-meter depth contours suitable for fixed-bottom offshore turbine development.
Oltenia
State-owned lignite complexes require expensive remediation and workforce restructuring as EU Green Deal compliance deadlines approach. No private capital relief has materialized for coal transition liabilities. Grid code modernization is qualifying newer renewable assets in Gorj and Dolj counties for priority dispatch.
Moldova
Agricultural residue fuels small-scale biomass cogeneration plants serving district heating networks in rural towns. Skilled technician shortages for inverter maintenance concentrate response capabilities in Iași, leaving secondary cities dependent on extended outsourced service contracts. Photovoltaic deployment lags southern regions due to lower irradiance levels.
Romania Power Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the regulated-versus-liberalized service tier. The market structures around three dominant positions: state-backed incumbents controlling hydro and nuclear baseload, European integrated utilities competing on retail price, and independent renewable developers capturing auction premiums. Strategic moves concentrate on portfolio diversification into storage and green hydrogen offtake, alongside vertical integration into distribution networks.
Within the state-backed incumbent tier, Hidroelectrica SA and Nuclearelectrica SA anchor baseload supply through hydro and nuclear assets respectively. PPC Energie occupies a position in the aggressive retail price competition segment. European integrated utilities including Engie Romania and E.ON Energie Romania exemplify the multi-service operator archetype spanning generation through retail.
| Leading Market Players |
|---|
| PPC Energie |
| Engie Romania |
| Hidroelectrica SA |
| Electrica Furnizare |
| E.ON Energie Romania |
| OMV Petrom SA |
| CEZ Romania |
| Enel S.p.A |
| Nuclearelectrica SA |
| Others |
Value Network & Pricing Analysis
Automotive manufacturers in Argeș and Dâmbovița counties anchor the largest volume concentration and negotiate long-term offtake contracts that set the reference price for industrial power procurement across Muntenia-South.
Pricing Analysis
Value-based pricing tied to carbon-free matching uptime anchors industrial contract negotiations, with premium tiers commanding spreads for 24/7 renewable traceability versus annual certificate products. Price differentiation separates baseload nuclear from merchant renewable output, with Hidroelectrica SA's regulated hydro offering tariff stability. Pricing pressure stems from TTF-linked gas volatility compressing combined-cycle margins. Industrial offtakers show lowest price sensitivity, prioritizing supply security and Scope 3 compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Bucharest and Cluj-Napoca coordinate hub-and-spoke logistics for transformer equipment and inverter components serving secondary cities. Manufacturing concentration rests on Germany, China, and Poland for switchgear and protection systems. Silicon modules draw from Chinese tier-1 producers, while turbine nacelles source from Denmark and Spain. Single-source vulnerability concentrates in high-voltage transformer cores. Distribution runs through Transelectrica's 400 kV backbone with last-mile handoff to regional operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Romania power market functions as a cost-of-compliance arena where EU Green Deal alignment and ANRE grid code mandates erect capital barriers that favor incumbent players with existing certification pathways and licensed capacity positions.
For Market Incumbents: Cement baseload positioning by extending Cernavodă nuclear maintenance contracts and securing priority dispatch qualifications for hydro assets ahead of ANRE's revised technical standards. Counter emerging independent renewable developers by capturing distribution network automation contracts in Transylvania's secondary cities, locking in decade-long service relationships that block entrant access.
For New Entrants and Emerging Players: Begin with behind-the-meter solar installations for commercial buildings in Cluj-Napoca and Timișoara, where rooftop penetration lags Western European saturation and incumbent utilities lack dedicated C&I sales forces. Pursue direct PPA origination with automotive tier-1 suppliers facing German OEM Scope 3 pressure, offering 24/7 carbon-free matching products that state-backed incumbents cannot replicate without portfolio restructuring.
For Investors and Strategic Acquirers: The window for entry favors developers with permitted offshore wind sites in Black Sea maritime zones near Constanța, where grid connection studies advance ahead of auction windows. Monitor ANRE capacity market design consultations as the inflection signal determining whether storage-hybrid assets qualify for capacity payments or remain merchant-exposed.
| Strategic Initiative | Industry Significance |
|---|---|
| Offshore Wind Capacity Buildout | Black Sea fixed-bottom projects near Constanța access untapped 30-meter depth contours with advancing grid interconnection studies. |
| Green Hydrogen Supply Agreement | Port of Constanța ammonia producers pilot electrolyzer-fed chains for export-oriented chemical manufacturing offtake. |
| Behind-the-Meter Solar Expansion | C&I rooftops in Cluj-Napoca and Timișoara offer installer margin expansion below Western European saturation rates. |
| Battery Storage Integration | Four-hour duration systems in Muntenia and Transylvania manage evening ramp events and stack frequency regulation with arbitrage revenues. |
| Distribution Network Automation | Smart metering rollouts in Brașov and Sibiu respond to ANRE unbundling mandates and create captive service relationships. |
Research Methodology
Multi-period observation of ANRE regulatory filings, auction outcomes, and grid code revision timelines anchored the trend analysis, supplemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators. Secondary validation drew from Transelectrica transmission data, ANRE market reports, EU Green Deal delegated acts, and project development databases. Bottom-up capacity addition tracking triangulated against top-down demand forecasts from industrial load projections.
Segment-weighting applied generation technology splits, service type margin structures, and regional demand concentration across the modeling period. CAGRs derived from unit economics modeling of photovoltaic, wind, and gas turbine deployments under varying carbon price assumptions. Forecast inputs incorporated EU ETS price trajectories and Black Sea gas production timelines without specifying year-bound milestones.
Underlying measurement precision varies by segment; renewable capacity additions carry tighter precision than nuclear refurbishment timelines due to construction uncertainty. Forecasts reflect documented assumptions on regulatory timing and interconnection completion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Azerbaijan Renewable Energy Market
Renewable Energy
Turkey Renewable Energy Market
Renewable Energy
Global Organic Rankine Cycle Market
Renewable Energy
Renewable Energy Contractor Market
Renewable Energy
Europe Power to Gas Market
Renewable Energy
Singapore Renewable Energy Market
Renewable Energy
Norway Renewable Energy Market
Renewable Energy
Africa Solar E-Bike Market
Renewable Energy
Russian Federation Renewable Energy Market
Renewable Energy
Renewable Energy Policy Fit Analysis Market
Renewable Energy
South Africa Wind Energy Market
Renewable Energy
Global Renewable Energy Market
Renewable Energy
Renewable Naphtha Market
Renewable Energy
LAMEA Wave and Tidal Energy Market
Renewable Energy
Solar Balloon Market
Renewable Energy
Italy Renewable Energy Market