
 Middle East and Africa Heart Valve Repair and Replacement Market | 2026-2036
Middle East and Africa Heart Valve Repair and Replacement Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Heart Valve Repair and Replacement Market Foresight
Hospital procurement consortia across the Middle East and Africa heart valve repair and replacement market is reshaping how manufacturers secure long-term supply contracts. Edwards Lifesciences leverages its transcatheter platform to anchor premium positioning in Gulf State cardiac centers. Medtronic sustains broad portfolio breadth across mechanical and tissue valve categories. Abbott Laboratories differentiates through structural heart device integration with diagnostic imaging systems.
Heart valve repair and replacement encompasses prosthetic devices and surgical interventions that restore or substitute damaged cardiac valves, with transcatheter valves typically constructed from bovine or porcine pericardial tissue mounted on nickel-titanium alloy frames delivered via catheter-based systems. These devices correct hemodynamic dysfunction caused by stenosis or regurgitation, reducing heart failure progression and mortality in patients unsuitable for open surgery. Transcatheter valves command the fastest expansion trajectory as minimally invasive alternatives displace surgical procedures in aging populations with elevated surgical risk profiles. Mechanical valves retain durable share in younger patients requiring long-term implant longevity despite lifelong anticoagulation requirements. Valve repair devices capture growing interest among surgeons seeking to preserve native valve anatomy in select mitral and tricuspathologies.
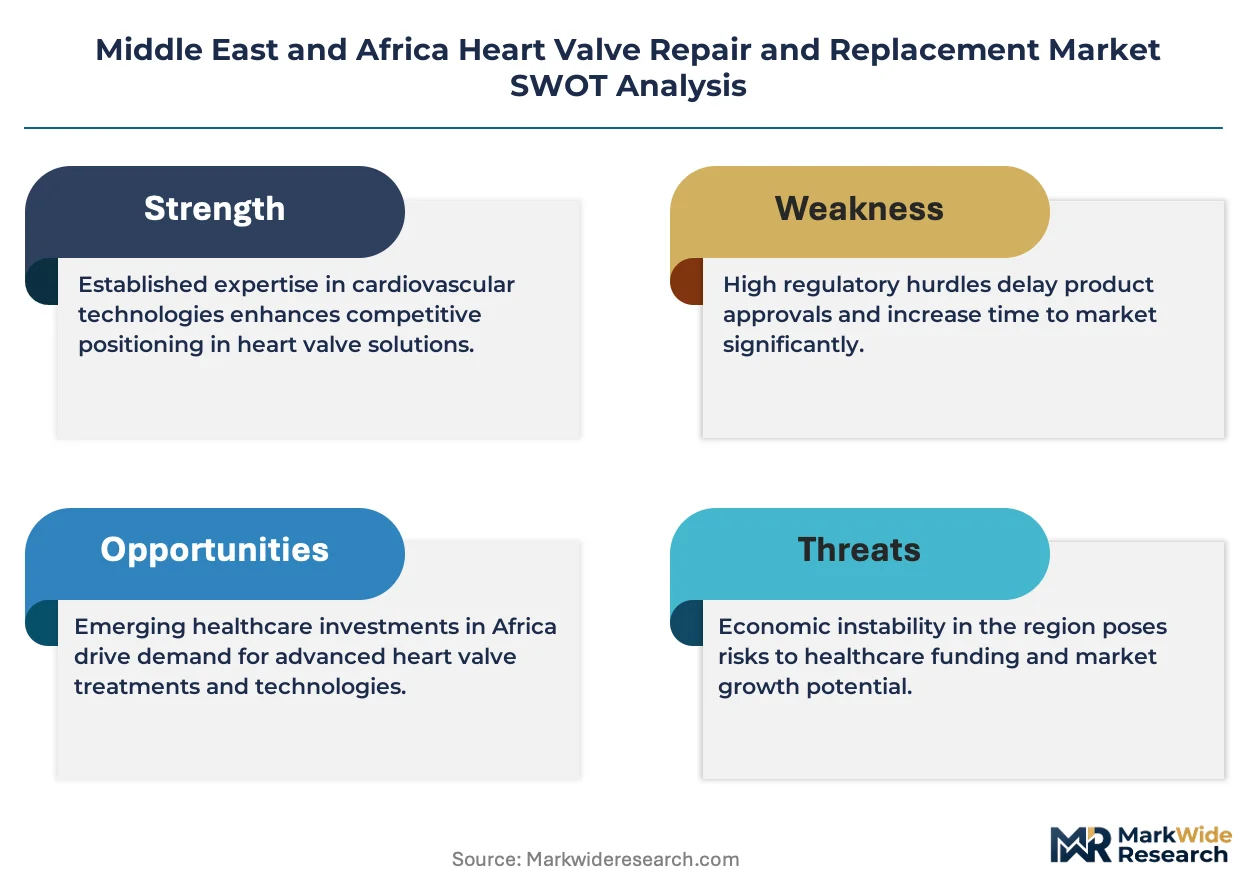
South Africa's Health Products Regulatory Authority, Saudi Arabia's Saudi Food and Drug Authority, and the UAE's Ministry of Health and Prevention collectively govern device approval, clinical evidence standards, and post-market surveillance across the region's major markets. These frameworks elevate barriers for new entrants while reinforcing established manufacturers with robust quality management systems and local regulatory expertise. Stakeholders must monitor evolving reimbursement pathways and localization incentives as Gulf governments expand domestic healthcare manufacturing capacity.
Market Dynamics
Transcatheter valve technology is compressing surgical volumes across Gulf State cardiac centers while procurement consortia consolidate purchasing power, forcing manufacturers to restructure pricing and service architectures around long-term supply agreements rather than per-procedure transactions.
Growth Catalysts
- Aging Demographics:Saudi Arabia's tertiary hospital clusters face rising volumes of patients over 75 with elevated surgical risk profiles, creating addressable demand for minimally invasive valve interventions.
- SFDA Streamlined Pathways:Saudi Arabia's Food and Drug Authority has implemented accelerated review tracks for breakthrough cardiac devices, reducing time-to-market for novel transcatheter platforms.
- Bioprosthetic Tissue Advances:Bovine and porcine pericardial tissue processing improvements are extending valve durability, expanding candidacy to younger patients previously channeled toward mechanical alternatives.
Market Restraints
- Nickel-Titanium Alloy Concentration:Nitinol frame supply concentrates among a limited set of specialty metallurgy suppliers, exposing manufacturers to input cost volatility and geopolitical supply disruptions.
- Anticoagulation Infrastructure Gaps:Mechanical valve recipients require lifelong warfarin monitoring, yet specialized coagulation clinics remain scarce outside South Africa's urban centers and Gulf State capital cities.
- Reimbursement Fragmentation:National health insurance schemes across the Middle East and Africa lack standardized transcatheter valve coverage codes, creating payment uncertainty that delays hospital adoption decisions.
Strategic Opportunities
- Valve-in-Valve Procedures:Degraded surgical bioprostheses in Egypt's growing cohort of prior valve recipients create a secondary intervention market requiring specialized transcatheter sizing and delivery systems.
- Structural Heart Convergence:Integration of transcatheter valve platforms with real-time intracardiac echocardiography is enabling single-operator procedures, reducing staffing requirements for resource-constrained centers.
- Domestic Manufacturing Incentives:Gulf governments are expanding localization mandates and joint venture requirements, creating pathways for regional production facilities serving Middle East and Africa distribution networks.
Industry Challenges
- Interventional Cardiology Talent Pipeline:Transcatheter valve programs require specialized training in structural heart imaging and catheter manipulation, yet accredited fellowship slots remain concentrated in South Africa and select Gulf institutions.
- Post-Market Surveillance Infrastructure:Long-term valve performance registries require decades of patient follow-up, straining hospital data systems and creating compliance gaps under evolving SFDA and SAHPRA reporting mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Heart Valve Repair and Replacement Market |
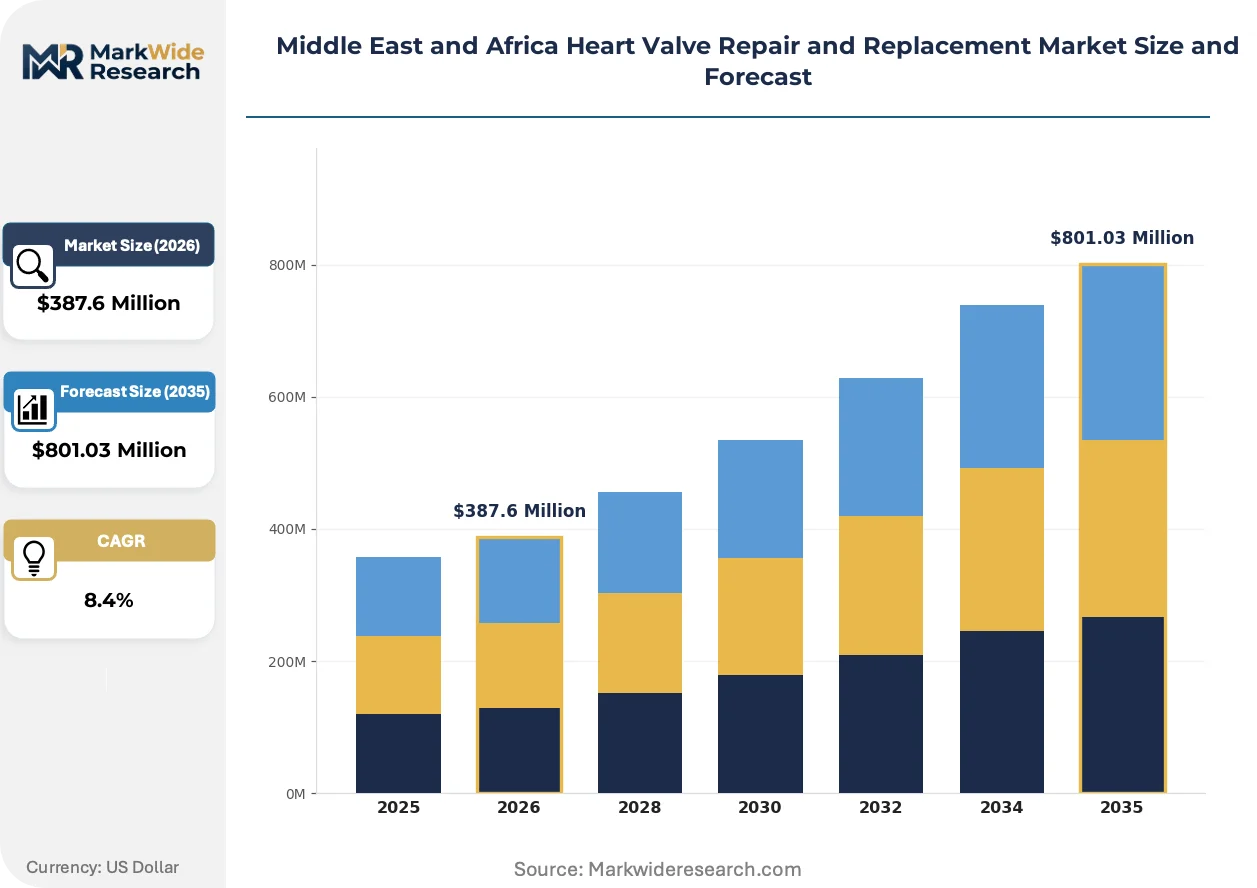
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $801.03 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Valves, Tissue Valves, Transcatheter Valves, Valve Repair Devices End User: Hospitals, Cardiology Clinics, Ambulatory Surgical Centers, Specialty Clinics Delivery Mode: Transfemoral, Transapical, Transaortic, Surgical Technology: Balloon Expandable, Self-Expanding, Sutured, Sutureless |
| Companies Covered | Edwards Lifesciences Corporation, Medtronic plc, Abbott Laboratories, Boston Scientific Corporation, LivaNova PLC, Terumo Corp, JenaValve Technology Inc., Artivion Inc., Colibri Heart Valve LLC, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Heart Valve Repair and Replacement Market Shifts & Advancements
Computational modeling and procedural analytics are transforming how cardiac centers select valve types, size implants, and predict outcomes, compressing the gap between diagnostic imaging and therapeutic intervention.
Artificial intelligence-assisted echocardiographic analysis is digitizing pre-procedural planning workflows. Cardiologists at tertiary centers in Dubai and Riyadh are deploying automated annular measurement tools to reduce sizing errors. This capability is digitizing the traditional manual assessment protocols that previously required multiple specialist consultations.
South Africa's Health Products Regulatory Authority has tightened clinical evidence requirements for novel valve platforms, mandating extended follow-up data from local patient populations. Manufacturers must now generate region-specific safety and efficacy documentation beyond their core FDA and CE mark submissions. Transcatheter valve sponsors are responding by establishing dedicated South African trial sites and local clinical affairs teams.
Hospital procurement consortia across the Gulf Cooperation Council are consolidating valve purchasing into multi-year framework agreements with bundled service components. Traditional distributor networks are losing ground to direct manufacturer relationships with centralized purchasing bodies. This restructuring is most visible in Saudi Arabia's Ministry of Health hospital clusters, where standardized valve specifications now dominate over physician-driven brand preferences.
Middle East and Africa Heart Valve Repair and Replacement Market Segmentation
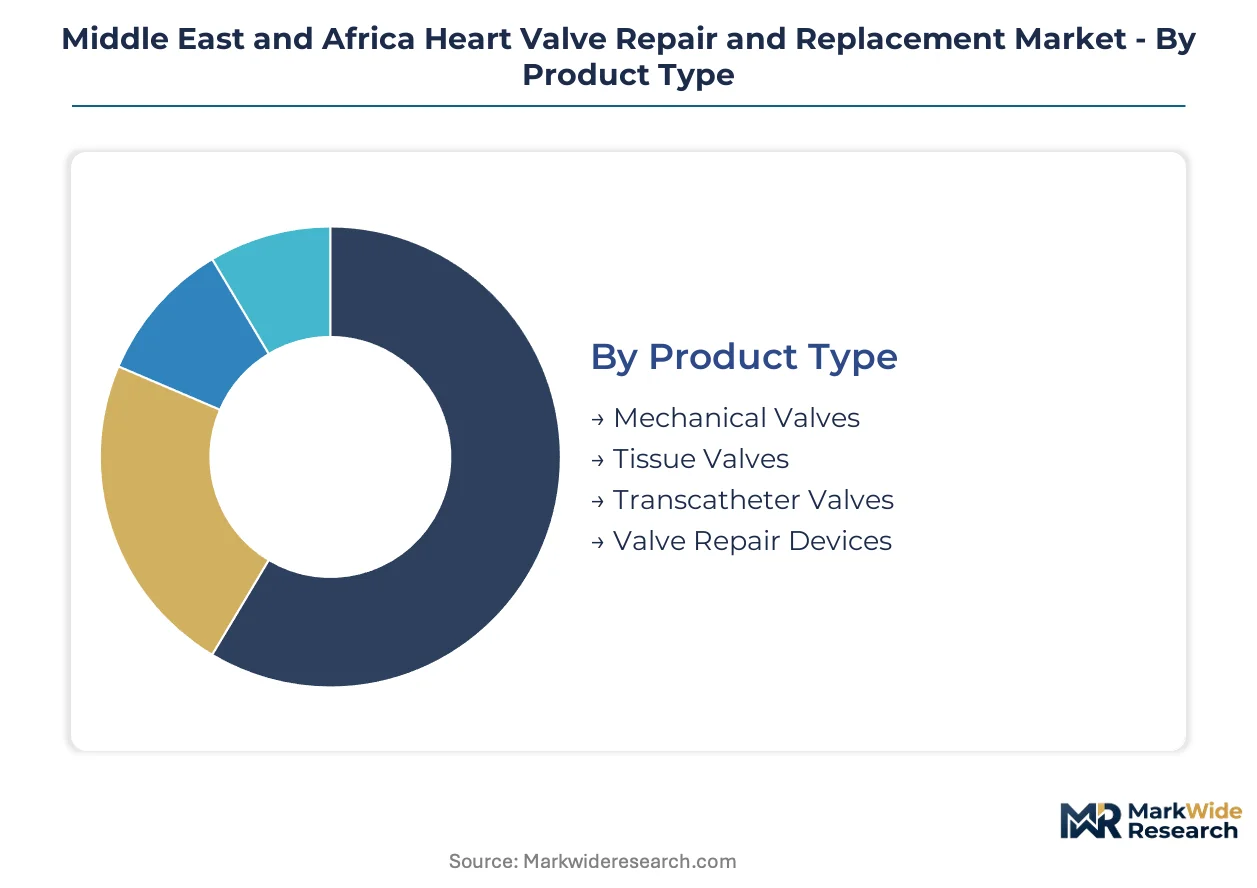
Segmentation reveals how valve replacement technologies stratify across patient risk profiles and healthcare infrastructure tiers. Product architecture, access route, and procedural setting each reshape competitive dynamics and pricing architecture differently across Gulf State cardiac centers and South African hospital networks.
Product Type:
Use-case spectrum spans lifelong durability demands in younger patients through minimally invasive alternatives for surgical ineligibles.
- Mechanical Valves:Pyrolytic carbon occluders housed in titanium or cobalt-chrome alloy frames deliver indefinite functional lifespan. Demand clusters in Saudi Arabia's Ministry of Health hospitals serving patients under 60, constrained by anticoagulation clinic availability outside Riyadh and Jeddah.
- Tissue Valves:Bovine pericardial or porcine aortic leaflets mounted on polymer or metal stents eliminate chronic anticoagulation. Egypt's private hospital chains favor these for patients aged 60-75 seeking lifestyle flexibility, though structural valve deterioration limits durability to 10-15 years.
- Transcatheter Valves:Nitinol or stainless steel frames support bioprosthetic leaflets delivered via catheter. Dubai's tertiary centers deploy these for high-risk surgical candidates.
- Valve Repair Devices:Annuloplasty rings and neochordae systems preserve native valve anatomy. South African academic medical centers apply these in select mitral regurgitation cases.
The dominant share belongs to Tissue Valves, while Transcatheter Valves is closing the gap fastest.
End User:
Facility type determines capital equipment requirements and reimbursement pathways across the region's fragmented payment landscape.
- Hospitals:Tertiary centers with hybrid operating suites and on-site cardiac surgery backup dominate complex valve procedures. Saudi Arabia's hospital clusters concentrate transcatheter volumes in facilities with 24-hour interventional cardiology coverage.
- Cardiology Clinics:Outpatient diagnostic and follow-up services support post-implant surveillance. UAE's Dubai Healthcare City hosts specialized structural heart clinics handling patient selection and longitudinal monitoring.
- Ambulatory Surgical Centers:Limited penetration due to emergency bypass capability requirements.
- Specialty Clinics:Focused cardiac practices in South Africa's urban centers manage warfarin therapy for mechanical valve recipients.
Hospitals capture the majority of procedure value, though Cardiology Clinics are expanding their share through pre-procedural assessment centralization.
Delivery Mode:
Anatomical access route selection hinges on iliofemoral vessel caliber, aortic arch geometry, and operator training pathways.
- Transfemoral:Percutaneous femoral artery access represents the least invasive delivery pathway. Gulf State cardiac centers prioritize this approach for patients with favorable vascular anatomy, reducing length of stay versus surgical alternatives.
- Transapical:Mini-thoracotomy with direct left ventricular apex puncture accommodates patients with peripheral vascular disease. South African surgeons retain this capability for complex anatomies unsuited to femoral delivery.
- Transaortic:Direct aortic access via mini-sternotomy or right anterior thoracotomy serves as fallback when iliofemoral and apical routes are compromised.
- Surgical:Median sternotomy with cardiopulmonary bypass remains standard for mechanical valve implantation and concomitant procedures.
Transfemoral delivery holds the largest procedure volume, while Transapical maintains strategic importance for vascular-compromised cohorts.
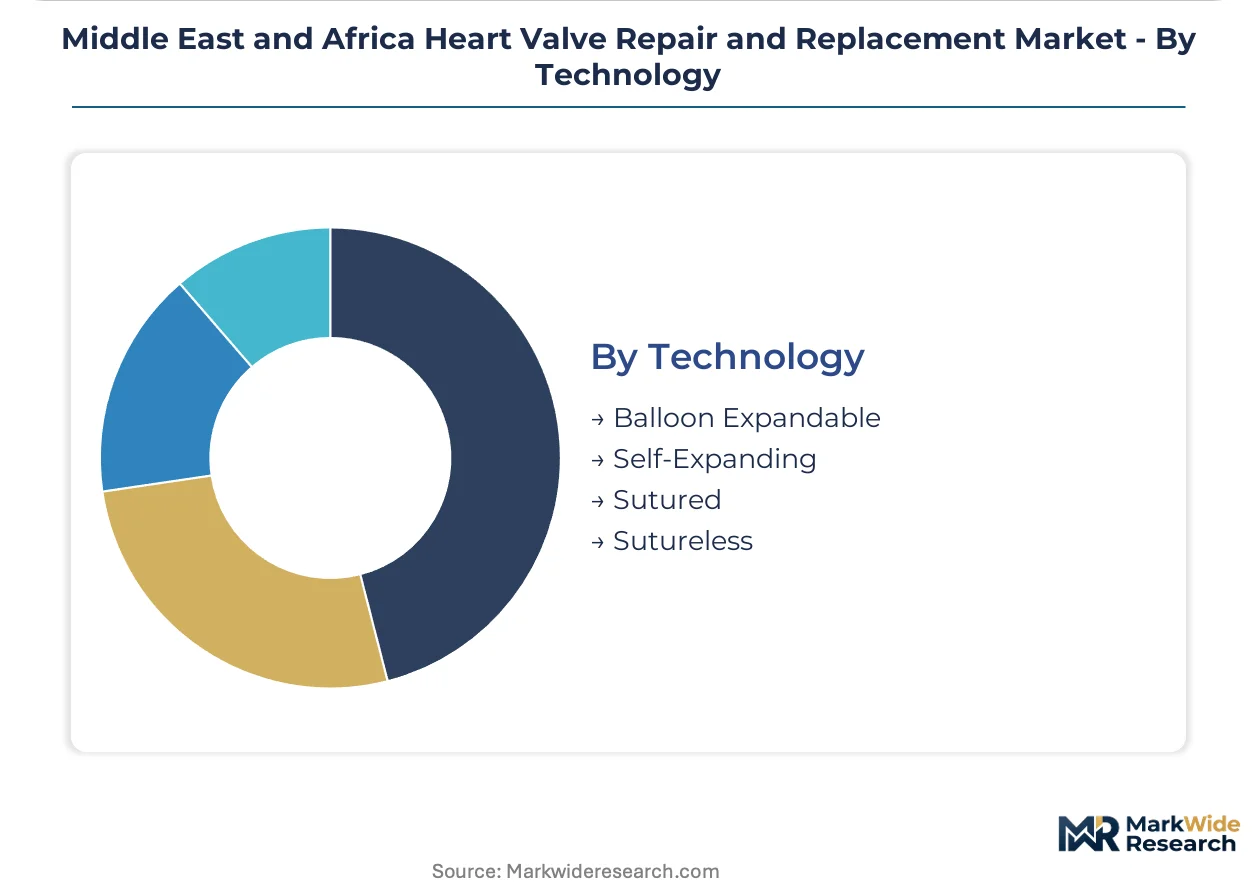
Technology:
Deployment mechanism and fixation method differentiate capital requirements, learning curves, and revision flexibility.
- Balloon Expandable:Crimped valves mounted on balloon catheters enable precise annular positioning under rapid pacing. Edwards Lifesciences' SAPIEN platform anchors this category in Gulf State premium segments.
- Self-Expanding:Nitinol frames deploy via sheath withdrawal without balloon inflation, conforming to irregular annular geometries. Medtronic's CoreValve systems dominate this segment across broader Middle East and Africa price tiers.
- Sutured:Traditional hand-sewn implantation with pledgeted mattress sutures remains mandatory for mechanical valves and complex tissue valve replacements.
- Sutureless:Nitinol or titanium anchoring systems enable rapid implantation without circumferential suturing, compressing cardiopulmonary bypass time.
Self-Expanding technology leads transcatheter deployment volumes, while Sutureless platforms are gaining traction fastest in hybrid surgical suites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The King Fahd Causeway connects Saudi Arabia and Bahrain, enabling rapid medical device logistics across the Gulf while Jebel Ali Port in Dubai anchors distribution networks serving cardiac centers from Cairo to Johannesburg.
Saudi Arabia
Tertiary hospital clusters in Riyadh and Jeddah absorb the majority of transcatheter valve procedures as the population over 75 expands. The Saudi Food and Drug Authority operates accelerated review tracks for breakthrough cardiac devices, compressing regulatory timelines. King Faisal Specialist Hospital anchors the kingdom's structural heart program with 24-hour interventional cardiology coverage.
United Arab Emirates
Dubai Healthcare City hosts specialized structural heart clinics handling patient selection and longitudinal monitoring for high-risk surgical candidates. The Ministry of Health and Prevention governs device approval and post-market surveillance, elevating quality management requirements. Cleveland Clinic Abu Dhabi operates as the emirate's premier cardiac referral center for complex valve interventions.
South Africa
Academic medical centers in Cape Town and Johannesburg manage warfarin therapy for mechanical valve recipients while applying repair devices in select mitral regurgitation cases. The Health Products Regulatory Authority tightened clinical evidence requirements for novel valve platforms, mandating extended follow-up data from local populations. Groote Schuur Hospital anchors the country's interventional cardiology training pipeline.
Egypt
Private hospital chains in Cairo favor tissue valves for patients aged 60-75 seeking lifestyle flexibility despite structural valve deterioration limits. The country's national pharmaceutical regulator oversees medical device registration with evolving clinical evidence standards. As-Salam International Hospital concentrates volumes among patients with degraded surgical bioprostheses requiring secondary intervention.
Israel
Specialized coagulation clinics in Tel Aviv and Haifa support mechanical valve recipients with lifelong anticoagulation monitoring infrastructure. The national health regulator maintains alignment with CE marking standards while requiring supplemental local safety documentation. Sheba Medical Center anchors the country's transcatheter valve research and physician training programs.
Middle East and Africa Heart Valve Repair and Replacement Market Competitive Landscape
On the supply side, the industry is consolidating around manufacturers with integrated structural heart portfolios and established regulatory pathways across Gulf State authorities. Edwards Lifesciences and Medtronic anchor premium positioning through transcatheter platforms, while Abbott Laboratories differentiates via diagnostic imaging integration. Three archetypes dominate: diversified cardiovascular conglomerates with broad mechanical and tissue valve offerings; transcatheter specialists leveraging minimally invasive technology; and emerging players targeting valve-in-valve niches. Competitive moves concentrate on long-term supply agreements with procurement consortia and localization partnerships under Gulf government manufacturing incentives.
Within the diversified cardiovascular tier, Edwards Lifesciences Corporation and Medtronic plc exemplify scale-driven manufacturers with established Gulf State cardiac center relationships. Abbott Laboratories occupies a position bridging device and diagnostic platforms. These three represent the archetype of integrated structural heart suppliers capable of anchoring multi-year framework agreements with Saudi Arabia's Ministry of Health hospital clusters and similar procurement bodies across the UAE and Qatar.
| Leading Market Players |
|---|
| Edwards Lifesciences Corporation |
| Medtronic plc |
| Abbott Laboratories |
| Boston Scientific Corporation |
| LivaNova PLC |
| Terumo Corp |
| JenaValve Technology Inc. |
| Artivion Inc. |
| Colibri Heart Valve LLC |
| Others |
Supply & Pricing Matrix
Nitinol frame production concentrates in a limited set of specialty metallurgy suppliers across the United States and Germany, anchoring margin capture upstream while Gulf State hospital procurement consortia compress downstream pricing power through multi-year framework agreements.
Pricing Analysis
Volume-discount tiering structures dominate transcatheter valve procurement across Saudi Arabia's Ministry of Health hospital clusters, with premium Edwards SAPIEN platforms commanding differential positioning against Medtronic CoreValve systems in standard tiers. Price differentiation hinges on CE marking tier and after-sales service bundling, while cost compression in economy mechanical valve segments intensifies due to localization mandates. Public hospital consortia exhibit highest price sensitivity; private cardiac centers in Dubai and Riyadh demonstrate lowest sensitivity to per-unit valve costs.
Supply Chain Analysis
Upstream feedstock for nitinol frames draws from titanium mining operations in Australia and nickel processing in Indonesia, with final alloy production concentrated in United States and German specialty metallurgy facilities. Bovine pericardial tissue sources from New Zealand and Australian agricultural operations, while porcine tissue hinges on European Union abattoir networks. Single-source vulnerability in nitinol frame supply exposes manufacturers to geopolitical disruption. Distribution runs through Jebel Ali Port hub-and-spoke networks serving cardiac centers from Cairo to Johannesburg.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Gulf Cooperation Council procurement consortia consolidate valve purchasing into centralized framework agreements, fragmenting physician-driven brand preferences and shifting margin pressure onto manufacturers.
For Market Incumbents: Harden regulatory pathway advantages by deepening SFDA and SAHPRA clinical affairs capabilities before emerging transcatheter specialists establish local trial infrastructure. Anchor long-term supply agreements with Saudi Arabia's Ministry of Health clusters through bundled service components including operator training and real-time procedural support, defending against price erosion from procurement consolidation. For New Entrants and Emerging Players: Mid-tier Egyptian private hospital chains with degraded surgical bioprosthesis cohorts represent the most penetrable entry point for valve-in-valve specialization. South African academic medical centers seeking repair device alternatives for select mitral regurgitation cases offer secondary white-space. Go-to-market through direct clinical specialist relationships bypasses entrenched distributor networks. For Investors and Strategic Acquirers: Capital is best deployed toward transcatheter platform specialists with established CE marking and progressing SFDA submissions, positioned for Gulf State localization partnerships. Long-term viability over the five-to-ten year window favors manufacturers integrating diagnostic imaging capabilities with therapeutic delivery systems. Watch for inflection when Saudi domestic manufacturing joint venture mandates crystallize into enforceable procurement preferences.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Accelerated Review Pathway | Compresses time-to-market for nitinol-frame transcatheter platforms in Riyadh clusters. |
| Hospital System Partnership | King Faisal Specialist Hospital anchors training pipelines and procedure volume commitments. |
| Localization Joint Venture | Gulf government mandates create captive production capacity serving regional distribution networks. |
| Software Companion Development | AI-assisted echocardiographic sizing tools reduce annular measurement errors in Dubai centers. |
| Reimbursement Strategy | Standardized transcatheter valve coverage codes unlock hospital adoption decisions across fragmented national schemes. |
Research Methodology
Operator-level perspectives from interventional cardiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base. Primary interviews combined with secondary validation against SFDA device registration databases, SAHPRA clinical evidence filings, hospital procurement records, and GPO contract repositories. Bottom-up procedure volume estimates triangulated against top-down healthcare expenditure flows.
Scenario-bracketing framed the analytical approach across the projection horizon, modeling patient risk stratification, valve type preference by age cohort, delivery mode adoption curves, and technology deployment mechanisms. CAGRs derived from segmented procedure volume builds and average selling price trajectories. Forecast inputs incorporated bioprosthetic tissue durability improvements and Gulf State localization incentive evolution.
Macroeconomic conditions sit as an overlay; deviation in Gulf State healthcare budget allocations, nickel-titanium alloy commodity prices, or regional currency stability would shift the trajectory. Cross-checking against SFDA device approval timelines and Ministry of Health procurement award announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Resuscitation Devices Market
Cardiovascular Devices
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market
Cardiovascular Devices
Cardiovascular CT Systems Market
Cardiovascular Devices
Abdominal Stent Graft System Market
Cardiovascular Devices
Arterial Stabilization Device Market
Cardiovascular Devices
Global Transcranial Doppler Ultrasound Market
Cardiovascular Devices
Tricuspid Valve Repair Market
Cardiovascular Devices
Global PTA Balloon Catheter Market
Cardiovascular Devices
Global Vascular Patch Market
Cardiovascular Devices
Peripherally Inserted Central Catheters Market
Cardiovascular Devices
Global Artificial Heart Market
Cardiovascular Devices
Cardiovascular Ultrasound Market
Cardiovascular Devices
Cardiac Assist Devices Market
Cardiovascular Devices
Atherectomy Devices Market
Cardiovascular Devices
Cardiovascular Catheter Market
Cardiovascular Devices
Single-Use Hemoperfusion Device Market