
 North America Stick Packaging Market | 2026-2036
North America Stick Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Stick Packaging Market Insights
Polyethylene is realigning toward post-consumer recycled grades as CPG brands face compliance deadlines under extended producer responsibility frameworks. Amcor plc leverages its North American film extrusion network to supply certified recycled-content stick-pack webs to supplement brands. Sonoco Products anchors its position through captive paperboard and flexible composite operations that reduce resin exposure. ProAmpac differentiates via specialized high-barrier laminations for hygroscopic pharmaceutical actives.
Stick packaging denotes a narrow, sealed pouch format typically 10–40 mm wide, produced on vertical form-fill-seal lines with longitudinal fin or lap seals and transverse crimp closures, designed for single-serve dispensing of powders, liquids, or gels. The format serves industries requiring precise unit dosing, portability, and shelf-space efficiency. Material segmentation shows composite structures leading in pharmaceuticals where oxygen and moisture barriers protect effervescent and probiotic formulations. Plastic remains dominant in beverage applications for cost and clarity, though paper-based alternatives are gaining share in personal care sachets as brands target plastic-reduction commitments. Flexible packaging type occupies the largest volume share across all end-use categories.
The U.S. Food and Drug Administration enforces Current Good Manufacturing Practice regulations that dictate seal integrity and label accuracy for stick-packaged dietary supplements. Health Canada and Mexico's COFEPRIS maintain parallel registration requirements that shape cross-border product formulations and barrier specifications. The EPA's evolving guidance on per- and polyfluoroalkyl substances is pressuring converters to validate non-fluorinated barrier coatings for food-contact stick packs. Stakeholders must monitor state-level extended producer responsibility legislation in California, Oregon, and Colorado, as these programs will determine acceptable material compositions and recycling infrastructure access before the forecast horizon concludes.
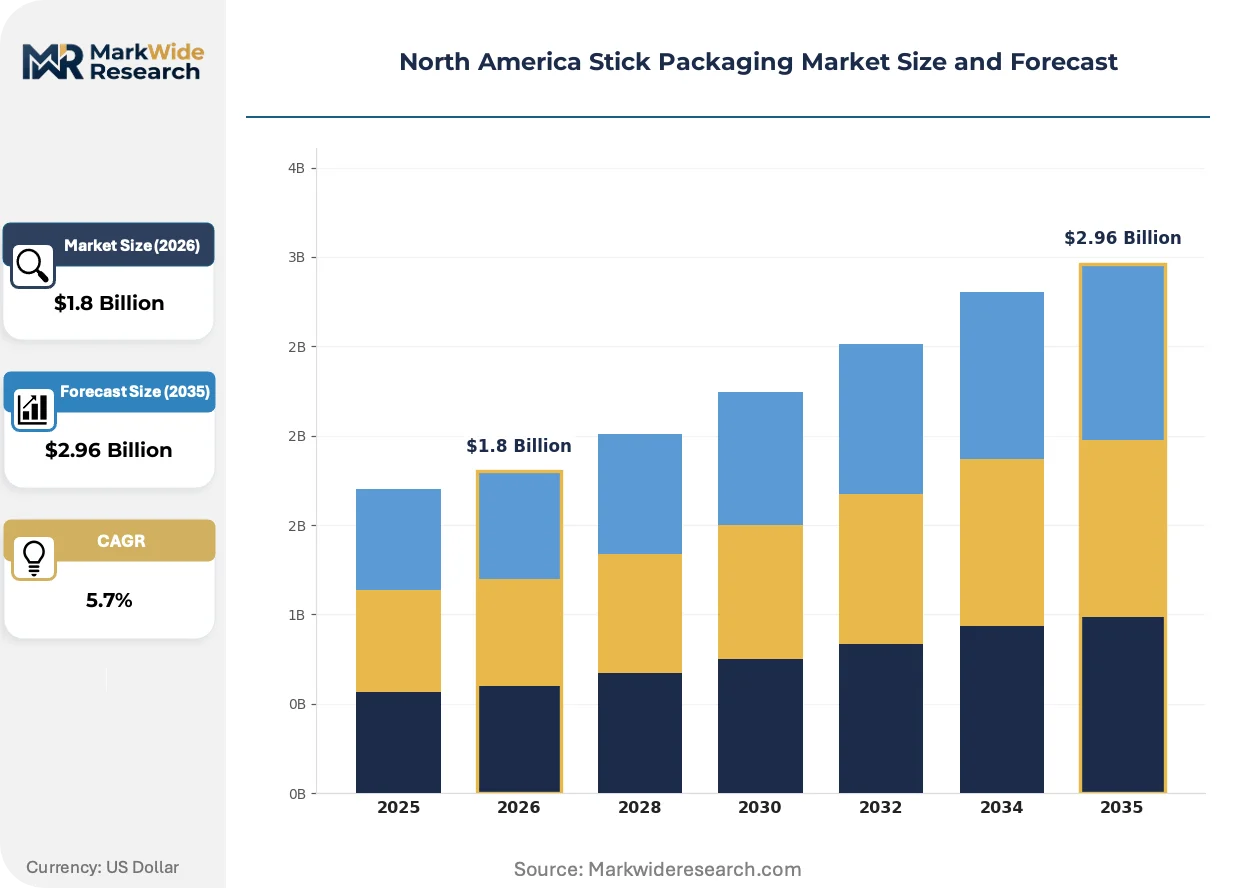
Market Dynamics
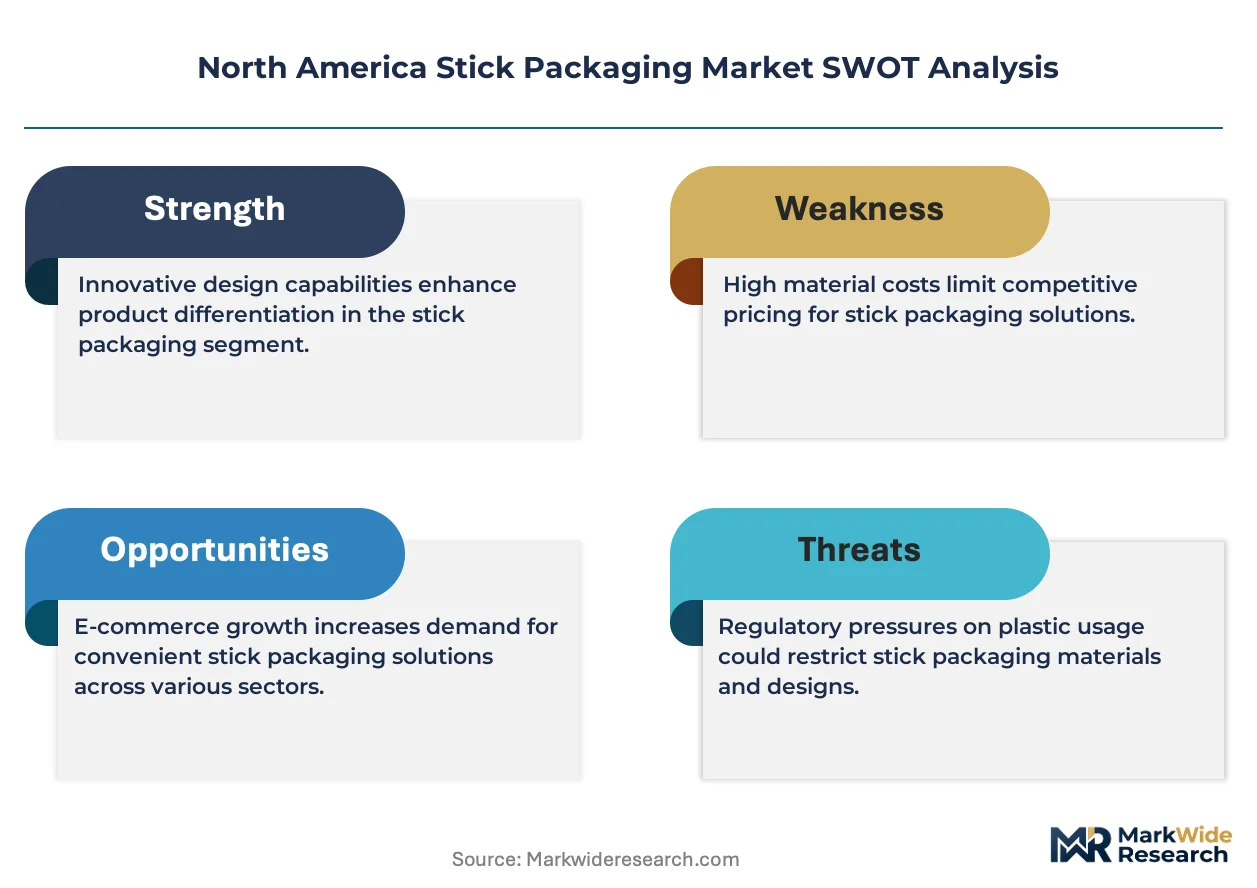
Extended producer responsibility frameworks in California, Oregon, and Colorado are forcing converters to reengineer material compositions and recycling pathways before compliance deadlines arrive.
Growth Catalysts
- FDA Labeling Evolution:Current Good Manufacturing Practice regulations for dietary supplements mandate seal integrity and label accuracy, pushing contract packagers toward precision stick-pack equipment and validated barrier structures.
- Single-Serve Beverage Expansion:Portion-controlled powders and concentrates in stick formats address consumer portability demands while reducing per-unit material intensity versus bottles or cans.
- Northeast Pharmaceutical Clustering:Contract packaging concentration in New Jersey and Pennsylvania generates sustained demand for high-precision stick-pack volumes serving effervescent and probiotic formulations.
Market Restraints
- Resin Cost Volatility:Virgin polyethylene and polypropylene pricing fluctuations compress converter margins, particularly for commodity beverage applications where brand owners resist pass-through.
- Fluorinated Barrier Phase-Out:EPA guidance on per- and polyfluoroalkyl substances forces validation of non-fluorinated oxygen and moisture barriers, extending development cycles for food-contact applications.
- Paper-Based Performance Gap:Fiber alternatives lack the clarity and hermetic seal integrity required for hygroscopic pharmaceutical actives, limiting substitution in high-barrier segments.
Strategic Opportunities
- Post-Consumer Recycled Integration:Certified recycled-content webs command premium positioning as CPG brands face 2025-2027 extended producer responsibility compliance milestones.
- Mexico COFEPRIS Alignment:Harmonized registration requirements with Health Canada and FDA standards enable cross-border formulation standardization for supplement brands seeking North American scale.
- Personal Care Plastic Reduction:Paper-based stick alternatives gain share in sachet formats as beauty brands deploy plastic-reduction commitments across retail and direct-to-consumer channels.
Industry Challenges
- High-Barrier Lamination Expertise Scarcity:Specialized knowledge for pharmaceutical-grade multi-layer structures concentrates among limited converter groups, constraining capacity expansion.
- State-Level EPR Fragmentation:Divergent material composition rules and recycling infrastructure access requirements across California, Oregon, and Colorado complicate national product platform strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Stick Packaging Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food, Beverage, Pharmaceuticals, Personal Care Material: Plastic, Paper, Aluminum, Composite End User: Household, Restaurants, Cafés, Retailers Packaging Type: Flexible, Rigid, Vacuum-Sealed, Eco-Friendly |
| Companies Covered | Amcor plc, Constantia Flexibles, Sonoco Products, Catalent, Inc, Huhtamaki, Glenroy, Inc., Fres-co System Inc, ProAmpac, ePac Holdings, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Stick Packaging Market Trends and Innovations
Material science advances and regulatory pressure on fluorinated chemistries are converging to reshape barrier technology roadmaps across pharmaceutical and food-contact segments.
Non-fluorinated high-barrier coatings is electrifying oxygen and moisture protection for hygroscopic actives. Pharmaceutical contract packagers in the U.S. Northeast are adopting these structures at accelerated pace to meet EPA guidance timelines. The technology is compressing validation cycles while opening compliant pathways for effervescent and probiotic stick-pack formats previously dependent on fluorinated chemistries.
California's extended producer responsibility legislation mandates post-consumer recycled content thresholds and producer-funded recycling infrastructure. Converters must certify material compositions and secure recycling access before program effective dates. The U.S. West Coast supplement and personal care segments are responding with accelerated recycled-content web qualification and supplier consolidation.
Direct-to-consumer subscription models are fragmenting order patterns into smaller, more frequent batch runs. E-commerce supplement brands demand shorter lead times and SKU proliferation versus traditional retail palletization. This shift is most visible in the U.S. Northeast and West Coast corridors where digitally native brands bypass wholesale distribution entirely.
North America Stick Packaging Market Segmentation
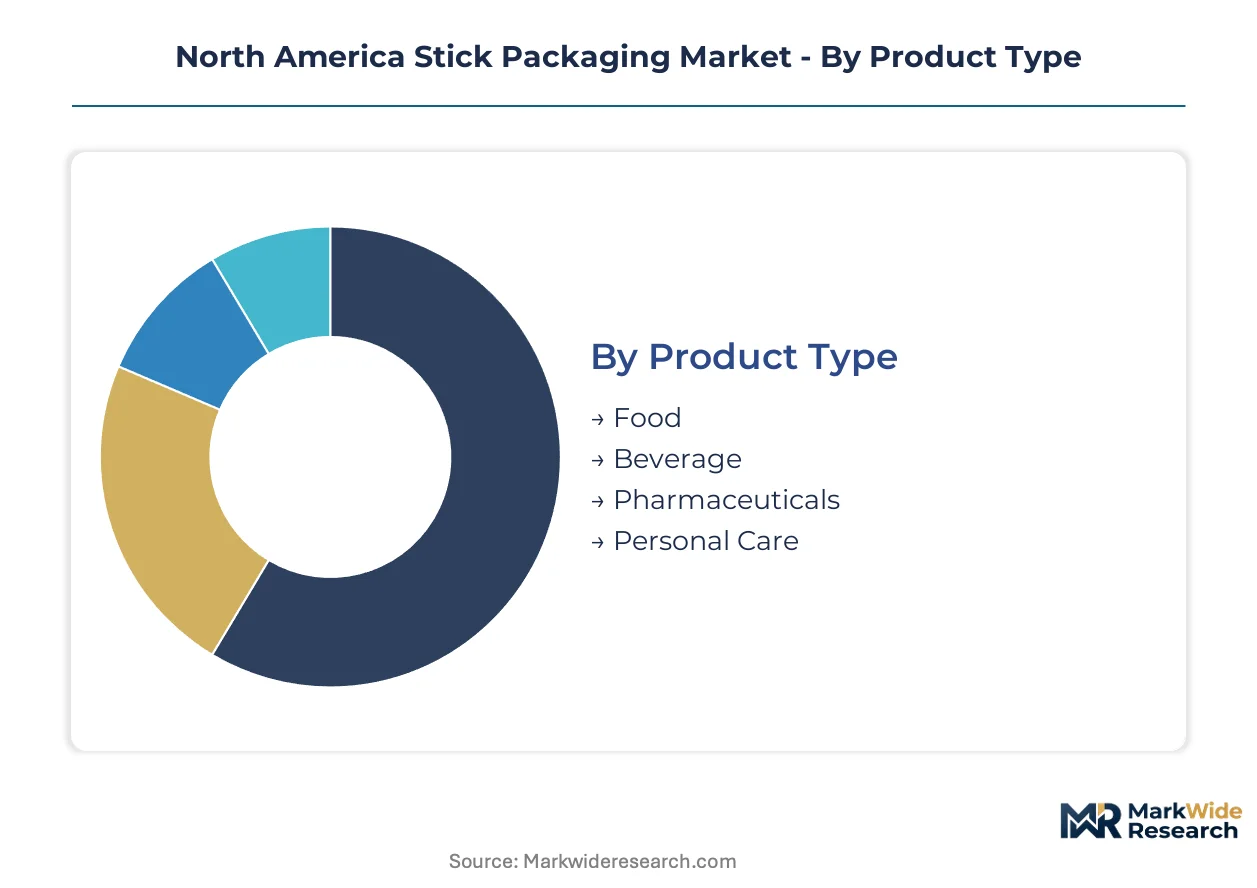
Stick packaging segmentation reveals distinct material-performance trade-offs across end-use applications. Product type and material selection directly determine barrier requirements, regulatory pathways, and converter specialization in the North American market.
Product Type:
Standalone single-serve formats dominate portable consumption occasions, while embedded multi-unit systems serve institutional and subscription channels.
- Food:Dry seasoning blends and instant soup powders utilize stick packs for portion-controlled distribution. Northeast contract packaging clusters in New Jersey process high volumes for quick-service restaurant supply chains, though moisture sensitivity limits applications for hygroscopic ingredients.
- Beverage:Concentrate sticks and powdered drink mixes represent the format's highest-volume deployment. Single-serve energy and hydration brands across the U.S. West Coast are converting from rigid bottles to flexible sticks, reducing per-unit material intensity while meeting California extended producer responsibility thresholds.
- Pharmaceuticals:Effervescent tablets and probiotic powders require validated barrier structures under FDA Current Good Manufacturing Practice regulations.
- Personal Care:Serum and lotion sachets target travel and trial-size segments with premium positioning.
Volume placements concentrate in Beverage; the faster expansion belongs to Pharmaceuticals.
Material:
Cost tiers stratify from commodity resins through specialized laminations, with sustainability premiums widening spreads between virgin and certified recycled grades.
- Plastic:Polyethylene and polypropylene webs dominate beverage applications for clarity and heat-seal reliability. Virgin resin cost volatility compresses converter margins, particularly where brand owners resist price pass-through in commodity segments.
- Paper:Fiber-based alternatives serve personal care sachets where plastic-reduction commitments drive substitution. Pennsylvania-based converters are qualifying kraft-based structures for dry food applications, though hermetic seal integrity gaps exclude hygroscopic pharmaceutical use.
- Aluminum:Foil laminations provide absolute oxygen and light barriers for pharmaceutical actives.
- Composite:Multi-layer structures combining plastic, foil, and paper deliver tailored barrier profiles for effervescent and probiotic formulations.
Plastic retains dominant volume share; composite structures command the steepest expansion trajectory as pharmaceutical precision requirements intensify.
End User:
Customer type determines order pattern fragmentation, with direct-to-consumer subscriptions demanding shorter runs versus palletized retail supply.
- Household:Individual consumers purchase single-serve sticks through retail and e-commerce channels. Digitally native supplement brands in the U.S. Northeast bypass wholesale distribution entirely, fragmenting batch sizes and accelerating SKU proliferation.
- Restaurants:Quick-service operators deploy portion-controlled condiment and seasoning sticks for consistency and waste reduction.
- Cafés:Coffee concentrate sticks serve specialty beverage preparation with premium positioning.
- Retailers:Private-label programs demand scale efficiencies and consistent supply security.
Household channels generate the highest absolute volumes; Restaurants are gaining share fastest as foodservice automation expands stick-format condiment dispensing.
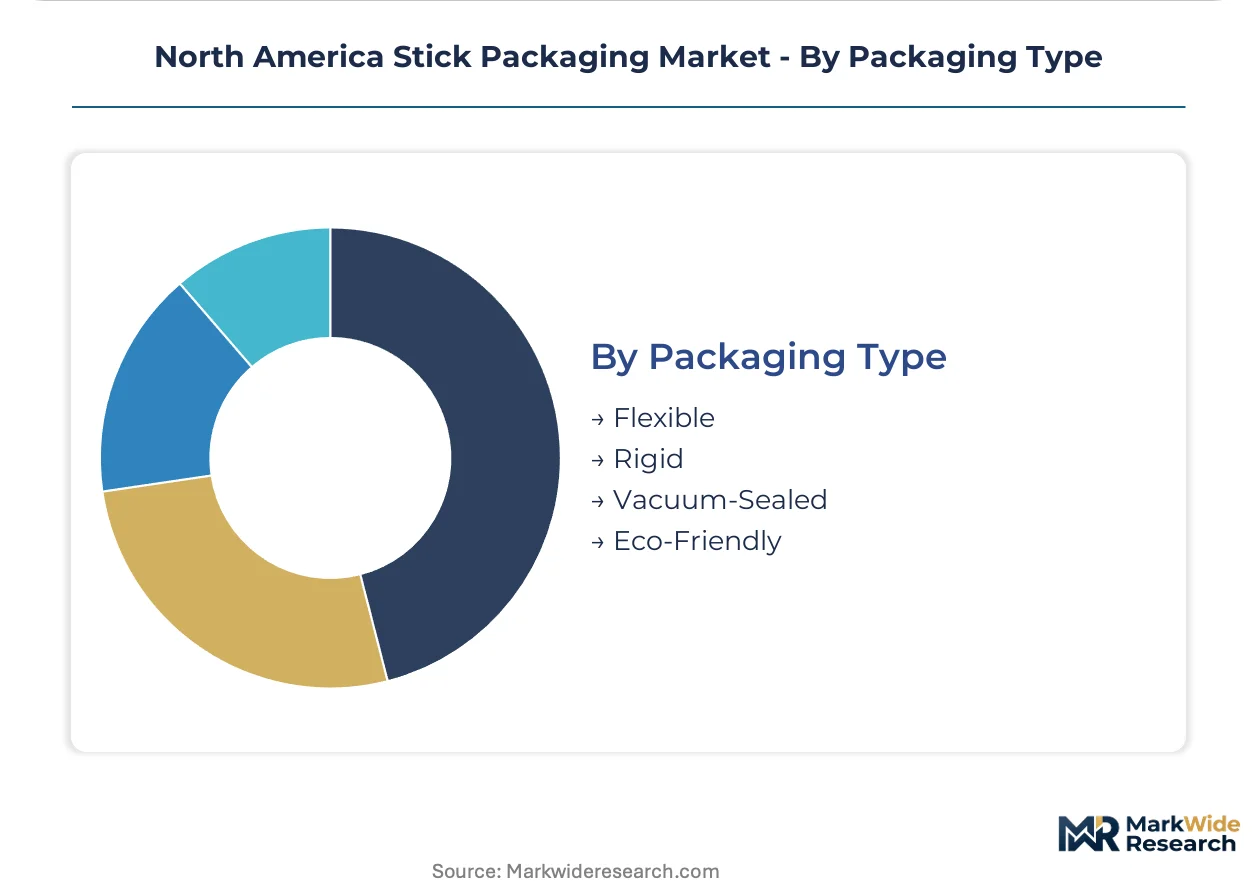
Packaging Type:
Structural rigidity versus flexibility trade-offs align with product protection requirements and supply chain handling intensity.
- Flexible:Pouch-based stick formats occupy the largest volume share across all end-use categories. Vertical form-fill-seal production lines in Pennsylvania and New Jersey achieve economies of scale for pharmaceutical and beverage applications.
- Rigid:Semi-structural sticks provide crush protection for fragile tablet formulations.
- Vacuum-Sealed:Oxygen evacuation extends shelf life for oxidation-sensitive actives.
- Eco-Friendly:Certified recyclable and compostable structures address California, Oregon, and Colorado extended producer responsibility compliance deadlines.
Flexible packaging commands volume concentration; eco-friendly alternatives are climbing the fastest as state-level mandates approach effective dates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the U.S. Northeast corridor where pharmaceutical contract packaging clusters generate sustained precision stick-pack volumes. The U.S. West Coast drives recycled-content adoption through state-level extended producer responsibility mandates. Mexico and Canada complete the regional footprint with cross-border regulatory alignment and distinct end-use specializations.
United States
New Jersey and Pennsylvania anchor pharmaceutical stick-pack production for effervescent and probiotic formulations. FDA Current Good Manufacturing Practice regulations dictate seal integrity standards that shape converter equipment investments. The Northeast corridor processes high volumes for quick-service restaurant supply chains and dietary supplement brands.
California
Single-serve beverage brands across the state convert rigid bottles to flexible stick formats to meet extended producer responsibility thresholds. The state's recycling infrastructure mandates drive accelerated qualification of post-consumer recycled-content webs. West Coast digitally native supplement brands fragment batch sizes through direct-to-consumer subscription models.
Mexico
COFEPRIS registration requirements harmonize with FDA and Health Canada standards to enable cross-border formulation standardization. The Mexico City Metro area serves as a hub for contract packaging serving North American supplement brands. Northern border states process volumes for U.S. quick-service restaurant supply chains.
Canada
Health Canada maintains parallel registration requirements to FDA that shape barrier specifications for cross-border pharmaceutical products. Ontario-based converters supply certified recycled-content structures for personal care and supplement applications. Quebec's flexible packaging sector serves specialty beverage concentrate brands with premium positioning.
North America Stick Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical precision requirements favoring integrated converters and beverage commodity applications fragmenting toward regional players. The market exhibits tiered concentration where high-barrier laminations concentrate among limited specialists while standard polyethylene structures face margin compression. Three archetypes dominate: multinational film extruders with recycled-content certification, captive paperboard and composite operators, and specialized pharmaceutical-grade laminators. Competitive moves center on post-consumer recycled web qualification and non-fluorinated barrier validation.
Among Australia-based multinational packaging groups, Amcor plc anchors the recycled-content supply tier through North American film extrusion networks. Sonoco Products occupies a position within captive material operations that reduce resin price exposure. ProAmpac exemplifies the specialized high-barrier segment serving hygroscopic pharmaceutical actives.
| Leading Market Players |
|---|
| Amcor plc |
| Constantia Flexibles |
| Sonoco Products |
| Catalent, Inc |
| Huhtamaki |
| Glenroy, Inc. |
| Fres-co System Inc |
| ProAmpac |
| ePac Holdings, LLC |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up contract packaging specialists in the U.S. Northeast and Midwest have consolidated regional capacity, tightening pricing discipline on pharmaceutical-grade laminations while fragmenting commodity polyethylene pricing power among smaller beverage converters. This ownership concentration enables coordinated capacity investments that buffer margin pressure from virgin resin volatility, yet leaves independent converters exposed to brand-owner price resistance in high-volume beverage segments.
Pricing Analysis
Volume splits between commodity beverage sticks and precision pharmaceutical laminations, with the latter commanding substantial premiums due to FDA Current Good Manufacturing Practice certification requirements and validated barrier performance. Pricing stratifies across premium certified-recycled tiers, standard virgin-resin structures, and economy-grade polyethylene formats, with differentiation driven by barrier complexity and California extended producer responsibility compliance status. Cost compression in standard beverage tiers is intensifying because brand owners resist pass-through of polyethylene and polypropylene fluctuations. Quick-service restaurant supply chains exhibit highest price sensitivity due to procurement scale, while effervescent supplement brands show lowest sensitivity given regulatory non-negotiability.
Supply Chain Analysis
Specialty barrier film supply rests on Japanese and German coating technology licensors, U.S. Gulf Coast polyethylene producers, and Canadian aluminum foil rolling mills serving the North American laminating base. Raw material dependencies include virgin and post-consumer recycled polyethylene resins, metallized and plain aluminum foils, and solvent-based or waterborne adhesive systems. Single-source vulnerability concentrates in fluorinated barrier coating alternatives where EPA guidance has accelerated validation demand beyond qualified supplier capacity. Distribution runs through converter-direct relationships with pharmaceutical contract packagers in New Jersey and Pennsylvania, supplemented by distributor networks serving West Coast beverage brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as extended producer responsibility compliance deadlines force smaller converters without recycled-content certification or non-fluorinated barrier capabilities toward exit or acquisition.
For Market Incumbents: Anchor defensive positioning through backward integration into post-consumer recycled web extrusion and captive high-barrier lamination capacity in the U.S. Northeast corridor. FDA labeling evolution and EPA fluorinated chemistry phase-out threaten converters lacking validated alternative barrier structures; securing Health Canada and COFEPRIS parallel registrations creates cross-border moats against regional challengers. For New Entrants and Emerging Players: Direct-to-consumer subscription fulfillment partners represent the most accessible channel wedge for digitally native supplement brands fragmenting order patterns into short-run, high-SKU production. Personal care paper-based sachets in California offer white-space penetration before extended producer responsibility mandates fully mature, with go-to-market positioning centered on plastic-reduction credentials and rapid lead-time flexibility. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized pharmaceutical-grade laminators in Pennsylvania and New Jersey with captive FDA validation histories and established effervescent tablet contract packaging relationships. Long-term viability over the next decade hinges on non-fluorinated barrier technology transition completion and state-level extended producer responsibility program integration; the signal to watch is California recycling infrastructure certification approval timelines as inflection indicator for national platform scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Recycled Web Certification | California extended producer responsibility thresholds now mandate verified recycled content for market access. |
| Non-Fluorinated Barrier Validation | EPA guidance on per- and polyfluoroalkyl substances accelerates pharmaceutical-grade coating replacement cycles. |
| COFEPRIS Registration Harmonization | Mexico regulatory alignment with FDA and Health Canada enables cross-border supplement formulation standardization. |
| Direct-to-Consumer Fulfillment Integration | Northeast digitally native brands bypass wholesale distribution, demanding short-run flexible production capacity. |
| High-Precision Equipment Investment | Current Good Manufacturing Practice seal integrity requirements push contract packagers toward validated stick-pack lines. |
Research Methodology
Document review covered FDA Current Good Manufacturing Practice guidance documents, EPA per- and polyfluoroalkyl substances advisories, and state-level extended producer responsibility legislation in California, Oregon, and Colorado, complemented by interviews with contract packaging operations directors, pharmaceutical regulatory affairs managers, flexible packaging procurement leads, and recycling infrastructure program administrators. Secondary validation drew from SEC filings of publicly traded converters, North American flexible packaging association technical reports, and customs trade data on polyethylene and aluminum foil imports. Bottom-up volume estimates from individual converter capacity and utilization rates were triangulated against top-down demand projections from end-use segment consumption patterns.
Cross-referencing historical pricing spreads between virgin and recycled-content grades against panel input from resin procurement specialists and brand-owner sustainability officers shaped the analytical framework. Segmentation dimensions modeled include material type, barrier performance tier, end-use application, and geographic regulatory cluster. CAGRs were derived from trend extrapolation of single-serve beverage conversion rates and pharmaceutical precision packaging growth, incorporating FDA submission volume trajectories and West Coast extended producer responsibility compliance acceleration as industry-specific forecast inputs.
Caveats apply where EPA fluorinated chemistry enforcement timelines, state-level extended producer responsibility implementation delays, or resin price volatility spikes could materially shift the outlook. Forecasts reflect assumptions regarding barrier technology validation cycle completion and recycling infrastructure certification scalability. A small set of named triggers—California recycling access approval rates, COFEPRIS registration processing speeds, and polyethylene futures curve movements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
PET Packaging Market
Packaging Materials
Cork Packaging Market
Packaging Materials
Foil Laminates Market
Packaging Materials
Cupcake Wrappers Market
Packaging Materials
Honeycomb Packaging Market
Packaging Materials
Absorbent Tray Liners Market
Packaging Materials
Refrigerator Door Seal Gaskets Market
Packaging Materials
Europe Single-Use Packaging Market
Packaging Materials
PCR Thermoforms Market
Packaging Materials
Sealed Wax Packaging Market
Packaging Materials
France Packaging Market
Packaging Materials
Finish Foils Market
Packaging Materials
Carded Packaging Market
Packaging Materials
Transit Packaging Market
Packaging Materials
Construction Films Market
Packaging Materials
Middle East and Africa Single-Use Packaging Market