
 US Business Jet Market | 2026-2036
US Business Jet Market Size, Share, and Industry Trends Forecast 2026-2036
US Business Jet Market Outlook
Ultra-long-range cabin specifications is rotating the US business jet market toward higher-margin deliveries. Gulfstream Aerospace Corporation dominates the super-large segment with Savannah-based manufacturing scale. Textron Aviation leverages its Wichita industrial footprint to sustain light-jet volume leadership. Bombardier Aviation differentiates through Global-series cabin altitude and noise suppression engineering.
A business jet is a fixed-wing aircraft certified under Part 25 or Part 135 regulations, typically featuring pressurized cabins, turbofan propulsion with thrust ratings from 2,000 to 19,000 pounds, and maximum operating altitudes of 41,000 to 51,000 feet, purpose-built to transport small groups of passengers on-demand outside scheduled airline networks. The aircraft type dimension shows large jets and ultra-long-range jets capturing disproportionate margin pools as transoceanic route flexibility becomes a purchasing priority, while light jets face pressure from turboprop alternatives in sub-1,500-nautical-mile missions. End user segmentation reveals charter operators expanding fractional and jet-card membership bases faster than traditional corporate flight departments, shifting aftermarket service revenue toward utilization-based contracts.
FAA airworthiness standards under Part 25 certification govern structural integrity and system redundancy requirements, while EPA emission regulations and the IRA sustainable aviation fuel tax credits are steering OEM engine roadmaps and operator fuel purchasing decisions. NHTSA-equivalent crashworthiness standards through FAA emergency evacuation rules shape cabin layout and egress system design. Stakeholders must weigh the capital allocation trade-off between incremental airframe efficiency gains and propulsion architecture bets on hybrid-electric or hydrogen combustion pathways.
Market Dynamics
FAA NextGen mandates and IRA sustainable aviation fuel tax credits are forcing fleet modernization decisions. Corporate flight departments weigh airframe efficiency against propulsion architecture bets on hybrid-electric pathways.
Growth Catalysts
- IRA SAF Tax Credits:The Inflation Reduction Act's sustainable aviation fuel incentives redirect operator fuel purchasing toward certified SAF blends. This steers OEM engine development roadmaps.
- Transcontinental Executive Travel:Corporate flight departments expand ultra-long-range jet utilization for nonstop US coast-to-coast and transoceanic missions. Sun Belt corridor demand concentrates in Texas, Florida, and Arizona.
- Part 25 Certification Standards:FAA airworthiness requirements for structural integrity and system redundancy elevate entry barriers. This protects incumbent OEM margins on super-large cabin deliveries.
Market Restraints
- SAF Supply Scarcity:US production capacity for certified sustainable aviation fuel trails fleet demand. Fuel cost volatility constrains operator budget certainty.
- Powertrain Development Timelines:Hybrid-electric and hydrogen combustion architectures face unresolved energy density limitations. Battery weight penalties restrict range-equivalent payload.
- Airframe Development Costs:Clean-sheet business jet programs demand capital commitments exceeding light-jet segment revenue pools. This consolidates R&D among super-large specialists.
Strategic Opportunities
- Fractional Membership Expansion:Charter operators build jet-card and fractional ownership bases faster than traditional corporate flight departments. Utilization-based service contracts capture recurring aftermarket revenue.
- Gulf Coast MRO Clusters:Texas and Florida maintenance facilities position for NextGen avionics retrofit volumes. Regional labor pools support specialized technician training pipelines.
- Cabin Altitude Engineering:Lower-pressurization cabin systems differentiate ultra-long-range offerings. This commands premium positioning on transoceanic routes.
Industry Challenges
- Avionics Technician Shortage:FAA-certified repair stations compete for specialized labor capable of NextGen system integration. Training pipeline capacity lags fleet modernization schedules.
- Propulsion Certification Complexity:Novel engine architectures face extended FAA validation timelines. This delays product launch windows against competitive responses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Business Jet Market |
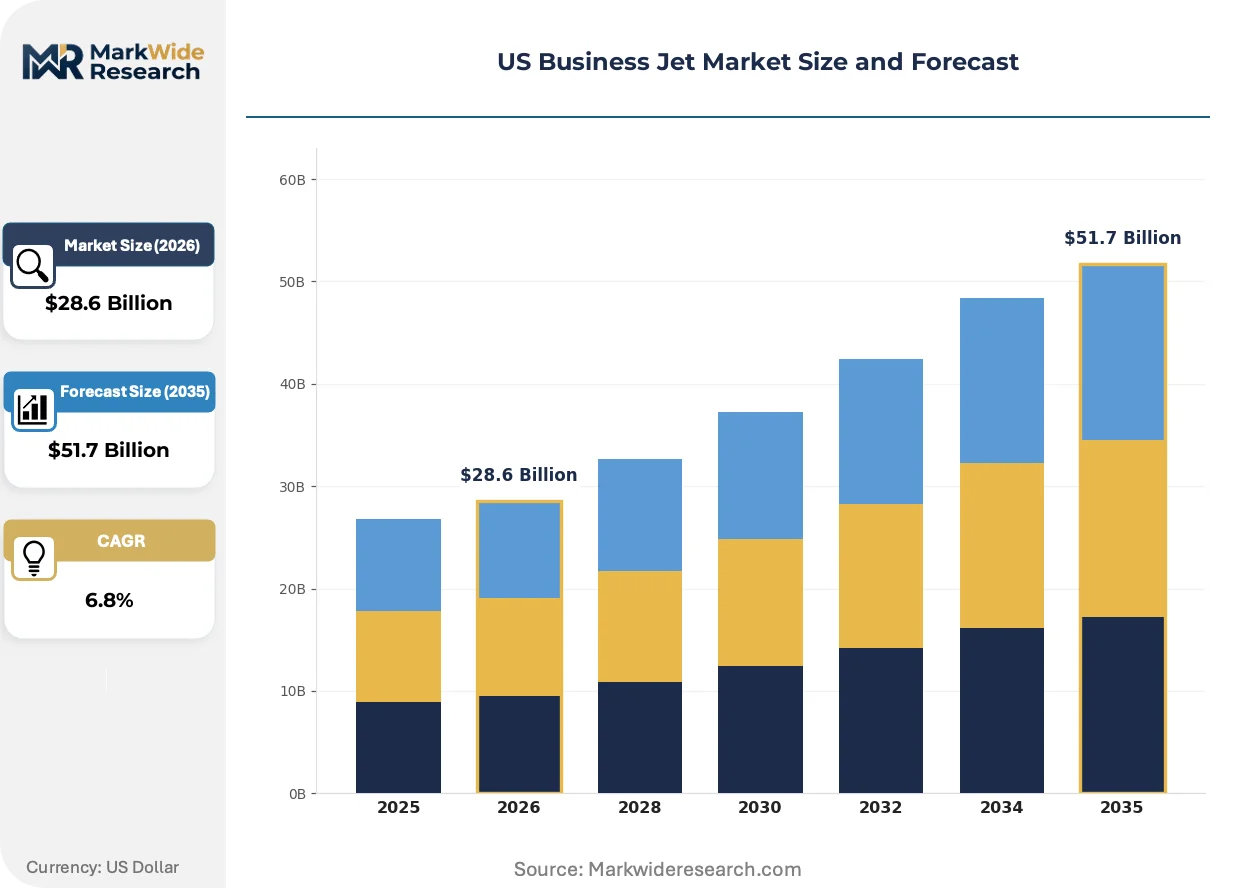
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Light Jets, Mid-Size Jets, Large Jets, Ultra-Long-Range Jets End User: Corporate Executives, Charter Operators, Private Individuals, Government Agencies Exterior Finish: Metallic, Non-Metallic, Composite, Custom Paint Technology: Avionics, Engine Types, Wing Designs, Cabin Features |
| Companies Covered | Gulfstream Aerospace Corporation, Textron Aviation, Bombardier Aviation, Dassault Aviation, Embraer Executive Jets, Honda Aircraft Company, Airbus Corporate Jets, Boeing Business Jets, NetJets, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Business Jet Market Strategic Shifts
Propulsion technology roadmaps and cabin experience engineering are diverging competitive strategies. OEMs place divergent bets on efficiency gains versus architectural disruption.
Hybrid-electric distributed propulsion is bifurcating development priorities across the OEM landscape. Established turbofan suppliers advance incremental thermal efficiency improvements for near-term certification. Startup airframers pursue all-electric architectures for sub-500-nautical-mile urban air mobility segments, compressing the addressable market for traditional light-jet incumbents.
FAA NextGen performance-based navigation mandates reshape avionics retrofit demand. Required navigation performance specifications force legacy fleet equipage upgrades or retirement. Part 135 charter operators in high-density Northeast corridors face the steepest compliance timelines and are accelerating replacement cycles.
Jet-card membership models displace whole-aircraft ownership among mid-market executives. Charter operators capture demand from corporate flight departments seeking capital efficiency. This shift concentrates in Texas and Florida, where fractional providers scale fleet utilization through density-optimized scheduling algorithms.
US Business Jet Market Segmentation
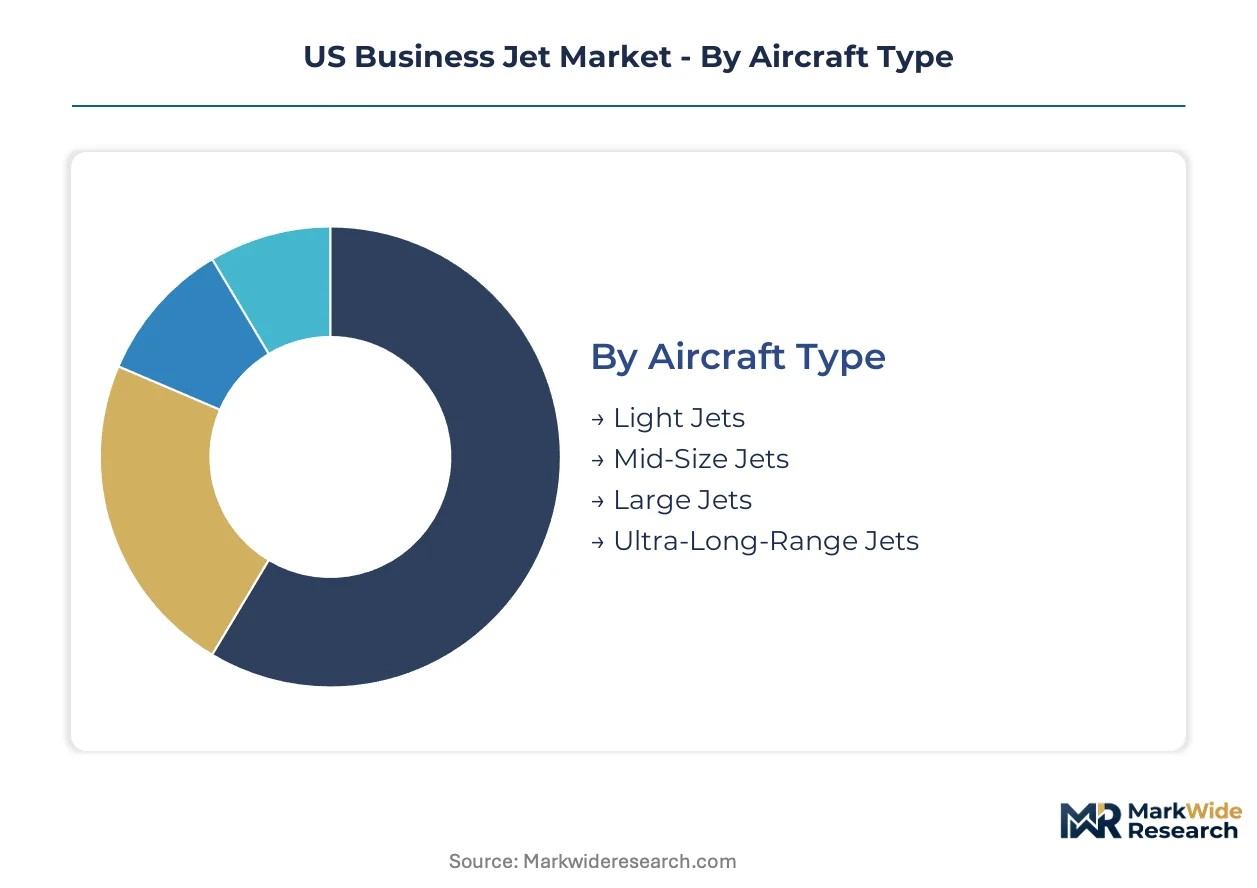
Segmentation in the US business jet market exposes where substitute pressure reshapes procurement. Turboprop alternatives and fractional ownership models compress addressable demand in certain categories while amplifying premium positioning in others.
Aircraft Type:
Substitution pressure from turboprops and emerging electric vertical takeoff platforms concentrates most intensely on shorter-range segments, forcing cabin efficiency and speed differentials to defend positioning.
- Ultra-Long-Range Jets:Pressurized cabins maintain sea-level equivalent altitudes below 5,000 feet at 51,000 feet cruise height, reducing passenger fatigue on transoceanic routes. Corporate flight departments in Texas and Florida concentrate demand here as nonstop Asia-Pacific and Middle East connectivity becomes a competitive necessity for energy and finance executives. IRA sustainable aviation fuel tax credits partially offset higher fuel burn per hour.
- Large Jets:Three-zone cabin configurations accommodate 12-16 passengers with full standing headroom and lie-flat berthing. Sun Belt charter operators scale fractional membership fleets around these airframes to capture coast-to-coast missions without fuel stops. FAA Part 25 certification requirements for system redundancy elevate development costs and protect incumbent margins.
- Mid-Size Jets:Transcontinental range envelopes of 3,000-3,500 nautical miles bridge continental missions with moderate acquisition costs.
- Light Jets:Sub-2,000-nautical-mile range profiles face intensifying turboprop competition on sub-1,500-nautical-mile sectors from Wichita-manufactured alternatives.
Light jets retain volume leadership; ultra-long-range jets hold the steepest expansion curve.
End User:
Capital efficiency pressures and utilization optimization drive divergent purchasing patterns across customer types, with asset-light models gaining traction among mid-market buyers.
- Charter Operators:Fleet purchasing prioritizes standardized configurations for rapid turnaround and maintenance commonality. Jet-card membership growth in Arizona, Texas, and Florida concentrates demand for 300-400 annual hour utilization rates. Revenue per available seat mile metrics dominate procurement criteria over cabin customization.
- Corporate Flight Departments:Dedicated aircraft ownership supports executive scheduling security and proprietary cabin configurations. Energy sector headquarters in Houston and Dallas maintain the largest per-company fleet concentrations. FAA NextGen avionics mandates accelerate replacement cycles for legacy airframes lacking required navigation performance capability.
- Private Individuals:Single-aircraft ownership concentrates in wealth corridors connecting New York, Palm Beach, and Aspen.
- Government Agencies:Federal and state procurement emphasizes US-manufactured content and crashworthiness certification for VIP transport missions.
Charter operators are expanding most quickly; corporate flight departments maintain the largest installed base.
Exterior Finish:
Material selection trade-offs between weight, durability, and aesthetic differentiation shape aftermarket revenue concentration and manufacturing complexity.
- Composite:Carbon fiber reinforced polymer skins reduce airframe weight 15-20% versus aluminum counterparts, extending range-payload performance. Gulfstream and Bombardier super-large programs in Georgia and Kansas leverage autoclave-cured structures for fatigue resistance. Repair station certification for composite damage assessment remains scarcer than metallic training pipelines.
- Custom Paint:Multi-layer pearlescent and metallic schemes command premium positioning for individual and corporate branding. Florida and Arizona completion centers specialize in climate-controlled spray booths for humidity-sensitive clearcoat application. Turnaround times of 4-6 weeks constrain fleet availability during peak refurbishment seasons.
- Metallic:Aluminum alloy skins dominate legacy fleet maintenance and aftermarket replacement demand.
- Non-Metallic:Fiberglass and hybrid substrates serve radome and control surface applications requiring electromagnetic transparency.
Metallic finishes retain volume leadership; composite applications gain share fastest.
Technology:
Regulatory mandates and passenger experience differentiation concentrate R&D allocation across competing engineering domains.
- Avionics:FAA NextGen performance-based navigation systems integrate GPS, inertial reference, and satellite-based augmentation for precision approaches. Required navigation performance 0.3 specifications for high-density Northeast corridors force equipage upgrades or airframe retirement. Texas and Florida avionics shops capture retrofit volumes as Part 135 operators accelerate compliance timelines.
- Engine Types:High-bypass turbofans with full-authority digital engine control optimize thermal efficiency across climb, cruise, and descent profiles. IRA sustainable aviation fuel tax credits steer operator purchasing toward certified blend compatibility. Hybrid-electric architectures face unresolved energy density limitations for range-equivalent payload.
- Wing Designs:Supercritical airfoils and winglets reduce transonic drag and improve fuel efficiency on long-range missions.
- Cabin Features:Lower-pressurization systems, active noise cancellation, and connectivity suites differentiate premium offerings.
Avionics captures the largest retrofit spend; cabin features command the steepest new-aircraft premium trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing scale clusters in Georgia, Kansas, and Quebec anchor North American supply, while Sun Belt demand corridors in Texas, Florida, and Arizona concentrate flight operations and MRO infrastructure.
Georgia
Savannah hosts the continent's largest super-large cabin assembly footprint. FAA Part 25 certification timelines protect incumbent margins on ultra-long-range deliveries. The Savannah metropolitan area sustains specialized composite technician training pipelines through technical college partnerships.
Kansas
Wichita retains light-jet volume leadership through century-old airframe manufacturing heritage. IRA sustainable aviation fuel tax credits steer operator purchasing toward certified blend compatibility. The Wichita industrial corridor supports vertically integrated supply chains from machining through final assembly.
Texas
Houston and Dallas energy sector headquarters maintain the largest per-company corporate fleet concentrations. FAA NextGen avionics mandates accelerate replacement cycles for legacy airframes lacking required navigation performance capability. Gulf Coast MRO clusters in Houston position for NextGen retrofit volumes through specialized technician training.
Florida
Palm Beach and Miami wealth corridors concentrate single-aircraft ownership among private individuals. NetJets and fractional operators scale fleet utilization through density-optimized scheduling algorithms. Florida completion centers specialize in climate-controlled spray booths for humidity-sensitive custom paint application.
Arizona
Scottsdale and Phoenix charter operators expand jet-card membership bases faster than traditional corporate flight departments. Revenue per available seat mile metrics dominate procurement criteria over cabin customization. Arizona's dry climate supports year-round flight training and maintenance operations.
US Business Jet Market Competitive Environment
Concentration sits with super-large cabin specialists commanding premium positioning on transoceanic routes. Three distinct strategic archetypes populate the competitive map: Savannah-based ultra-long-range manufacturers, Wichita-scaled light-jet volume leaders, and Montreal-engineered cabin altitude differentiation specialists. Dominant competitive moves include M&A consolidation of fractional ownership platforms and geographic expansion of Gulf Coast MRO service networks.
Within the super-large cabin tier, Gulfstream Aerospace Corporation and Bombardier Aviation exemplify engineering-led differentiation through cabin pressurization and noise suppression architectures. Textron Aviation anchors the light-jet volume position through Kansas-based manufacturing scale. These three manufacturers collectively represent the structural poles around which charter operators and corporate flight departments organize procurement decisions.
| Leading Market Players |
|---|
| Gulfstream Aerospace Corporation |
| Textron Aviation |
| Bombardier Aviation |
| Dassault Aviation |
| Embraer Executive Jets |
| Honda Aircraft Company |
| Airbus Corporate Jets |
| Boeing Business Jets |
| NetJets |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month order backlogs for super-large cabin airframes concentrate pricing power with Savannah and Wichita OEMs while compressing negotiation leverage for charter operators seeking fleet standardization. This inventory scarcity reinforces premium positioning on transoceanic-capable deliveries and elevates deposit requirements for new aircraft positions.
Pricing Analysis
FAA Part 25 certification dictates the pricing tier structure across the US business jet market. Three-tier pricing structure across premium, standard, and economy levels separates ultra-long-range Gulfstream and Bombardier deliveries from mid-size Textron offerings and light-jet alternatives. Price differentiation rests on cabin altitude engineering and NextGen avionics compliance rather than airframe scale alone. Pricing pressure stems from SAF supply scarcity and fuel cost volatility constraining operator budget certainty. Charter operators exhibit highest price sensitivity due to revenue-per-seat-mile procurement metrics, while corporate flight departments prioritize scheduling security over acquisition cost.
Supply Chain Analysis
Port congestion on Savannah River inbound lanes and container availability constraints on carbon fiber precursor imports from Japan and Germany elevate landed costs for composite-intensive super-large programs. Geographic supply concentration centers on Georgia, Kansas, and Quebec for final assembly, with Rolls-Royce and Pratt & Whitney turbofan sourcing from the United Kingdom and United States. Raw material dependencies span carbon fiber reinforced polymers from Japan, aluminum alloys from domestic smelters, and avionics subsystems from Israeli and Canadian suppliers. Single-source vulnerability on full-authority digital engine control modules creates bottleneck exposure. Distribution runs through factory-direct sales teams and fractional ownership platforms rather than traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US business jet market approaches a platform-economics inflection as fractional membership models and jet-card interoperability reshape asset utilization patterns. This ecosystem shift rewards operators who integrate scheduling algorithms with maintenance predictive analytics.
For Market Incumbents: Consolidate fractional ownership platforms and Gulf Coast MRO networks to defend against turboprop substitution pressure on sub-1,500-nautical-mile missions. Acquire specialized avionics repair stations in Texas and Florida to capture NextGen retrofit volumes. Deepen backward integration into carbon fiber autoclave capacity to secure composite airframe supply.
For New Entrants and Emerging Players: Differentiate on hybrid-electric propulsion architectures for sub-500-nautical-mile urban air mobility segments where energy density limitations matter less. Target Arizona charter operators seeking density-optimized scheduling algorithms for jet-card membership expansion. Pursue FAA Part 135 certification pathways rather than Part 25 to compress time-to-market.
For Investors and Strategic Acquirers: Carve-out targets emerge from aerospace conglomerates divesting non-core business jet divisions amid capital reallocation toward defense and commercial aviation. Long-term viability hinges on SAF infrastructure buildout and NextGen avionics retrofit demand sustainability. Monitor IRA sustainable aviation fuel tax credit renewal negotiations as the critical inflection signal for operator fleet modernization cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Fractional Platform Consolidation | NetJets and competitors capture recurring revenue through utilization-based service contracts in Sun Belt corridors. |
| NextGen Avionics Retrofit | FAA performance-based navigation mandates force Part 135 operator compliance or airframe retirement in Northeast corridors. |
| Gulf Coast MRO Expansion | Texas and Florida facilities position for specialized technician training pipelines supporting fleet modernization. |
| SAF Supply Agreement | Long-term offtake contracts with renewable fuel producers hedge against production capacity trailing fleet demand. |
| Cabin Altitude Engineering | Lower-pressurization systems differentiate ultra-long-range offerings commanding premium on transoceanic routes. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FAA certification databases, SEC aerospace filings, and IRA tax credit implementation guidance. Primary interviews encompassed OEM program managers, charter operator fleet directors, and Part 145 repair station executives. Secondary sources included FAA NextGen implementation timelines, EIA sustainable aviation fuel production data, and state-level aerospace manufacturing employment statistics. Bottom-up aircraft delivery forecasts triangulate against top-down corporate flight department budget surveys.
Segmentation dimensions modeled span aircraft type, end user category, exterior finish material, and technology subsystem across the projection horizon. CAGRs derive from fleet replacement cycle analysis, IRA incentive duration assumptions, and NextGen mandate compliance deadlines. Industry-specific inputs incorporated turbofan thermal efficiency roadmaps, composite technician training pipeline capacity, and fractional ownership membership growth trajectories.
Material uncertainties — SAF production scale shortfalls, hybrid-electric certification timeline extensions, and avionics technician shortage intensification — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory incentive continuity and macroeconomic conditions supporting executive travel demand. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Commercial Aircraft Lighting Market
Aircraft
America Freighter Aircraft Market
Aircraft
Helicopter Lighting Market
Aircraft
Air Starter Market
Aircraft
France Aviation Market
Aircraft
Fixed Wing Turbine Aircraft Market
Aircraft
Ultra-Light Aircraft Market
Aircraft
Aircraft Wheels Market
Aircraft
Aircraft Mounts Market
Aircraft
Aircraft Cargo Systems Market
Aircraft
Onboard Oxygen Generating System (OBOGS) Market
Aircraft
GCC Business Jet Market
Aircraft
Global LW Sport Aircraft Market
Aircraft
Aircraft Cables Market
Aircraft
Japan Aircraft Windshield Wiper and Washer System Market
Aircraft
Wireless in-Flight Entertainment Market