
 Global Aircraft Towbars Market | 2026-2036
Global Aircraft Towbars Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Towbars Market Analysis
Market Context with Strategic Players
Military base procurement is rotating toward heavy-duty and adjustable towbar systems as defense fleets modernize with larger transport aircraft. Douglas Equipment leverages its steel fabrication expertise to dominate North American military contracts, while Goldhofer AG anchors European demand through specialized heavy-lift ground support equipment. Tronair Inc. differentiates via composite material R&D, reducing towbar weight for commercial airline fuel-efficiency programs.
Technical Definition and Structural Segments
Aircraft towbars are rigid or adjustable linkage devices, typically fabricated from high-strength steel or aluminum alloys, that connect a tow vehicle to an aircraft nose gear for pushback and repositioning operations on airport aprons. Standard towbars retain the largest volume share across commercial aviation applications, though composite-material segments are gaining traction as airlines prioritize weight reduction for ground handling cost control. Heavy-duty towbars command premium positioning in military aviation, where load ratings exceed commercial thresholds and procurement cycles favor durability over unit economics. Aerospace maintenance end users represent a concentrated margin pool, as MRO facilities require adapter-compatible systems serving multiple aircraft platforms.
Regulatory Framework and Forward Outlook
The FAA mandates periodic load-testing and structural inspection protocols under 14 CFR Part 139 airport operating certificates, while EASA enforces CE-marked conformity under its ground support equipment directive. India's DGCA and China's CAAC are tightening import certification requirements, creating compliance barriers for non-domestic manufacturers. Stakeholders must monitor evolving carbon-footprint disclosure rules under the EU Green Deal, as material sourcing and manufacturing location decisions face emerging sustainability audit requirements.
Market Dynamics
Defense procurement cycles are compressing as NATO members accelerate airbase modernization, while commercial aviation MRO consolidation is concentrating buyer power among fewer ground-handling operators demanding multi-platform towbar compatibility.
Growth Catalysts
- 14 CFR Part 139 mandates:FAA airport operating certificates require periodic load-testing of ground support equipment, forcing fleet upgrades at certified US airports and expanding replacement demand for compliant towbar systems.
- Composite material substitution:Carbon-fiber-reinforced polymer towbars reduce ground handling equipment weight by 40-60% versus steel, cutting fuel burn during repositioning operations and aligning with airline sustainability targets.
- German military base clusters:Ramstein Air Base and NATO logistics hubs in Bavaria anchor concentrated procurement for heavy-lift adjustable towbars serving C-17 and A400M transport fleets.
Market Restraints
- High-strength steel price volatility:Aerospace-grade alloy steel input costs fluctuate with nickel and chromium spot markets, compressing fabrication margins for standard towbar manufacturers.
- Single-source forging dependencies:Critical towbar head castings rely on a concentrated supplier base in northern Italy, creating geographic supply risk for European OEMs.
- CE-marking friction:EASA ground support equipment directive conformity assessments require third-party notified body involvement, extending European market entry timelines for non-EU manufacturers.
Strategic Opportunities
- India DGCA import certification:Tightened GSE import rules under India's 2023 technical regulations create first-mover advantage for domestic assembly partnerships serving IndiGo and Air India ground operations.
- EU Green Deal material disclosure:Carbon-footprint audit requirements for public procurement favor towbar manufacturers with verified low-emission supply chains and recycled aluminum sourcing.
- Telematics-integrated towbars:IoT sensor convergence with structural health monitoring enables predictive maintenance contracts, shifting revenue models from equipment sales to subscription-based fleet management services.
Industry Challenges
- Welding certification scarcity:Aerospace-grade aluminum TIG welding expertise is concentrated among aging specialist workforces in Germany and the US, constraining production scaling for lightweight towbar programs.
- Multi-platform adapter complexity:MRO facilities require towbar systems compatible with 15+ aircraft nose gear configurations, forcing inventory duplication and training overhead that erodes operational efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Towbars Market |
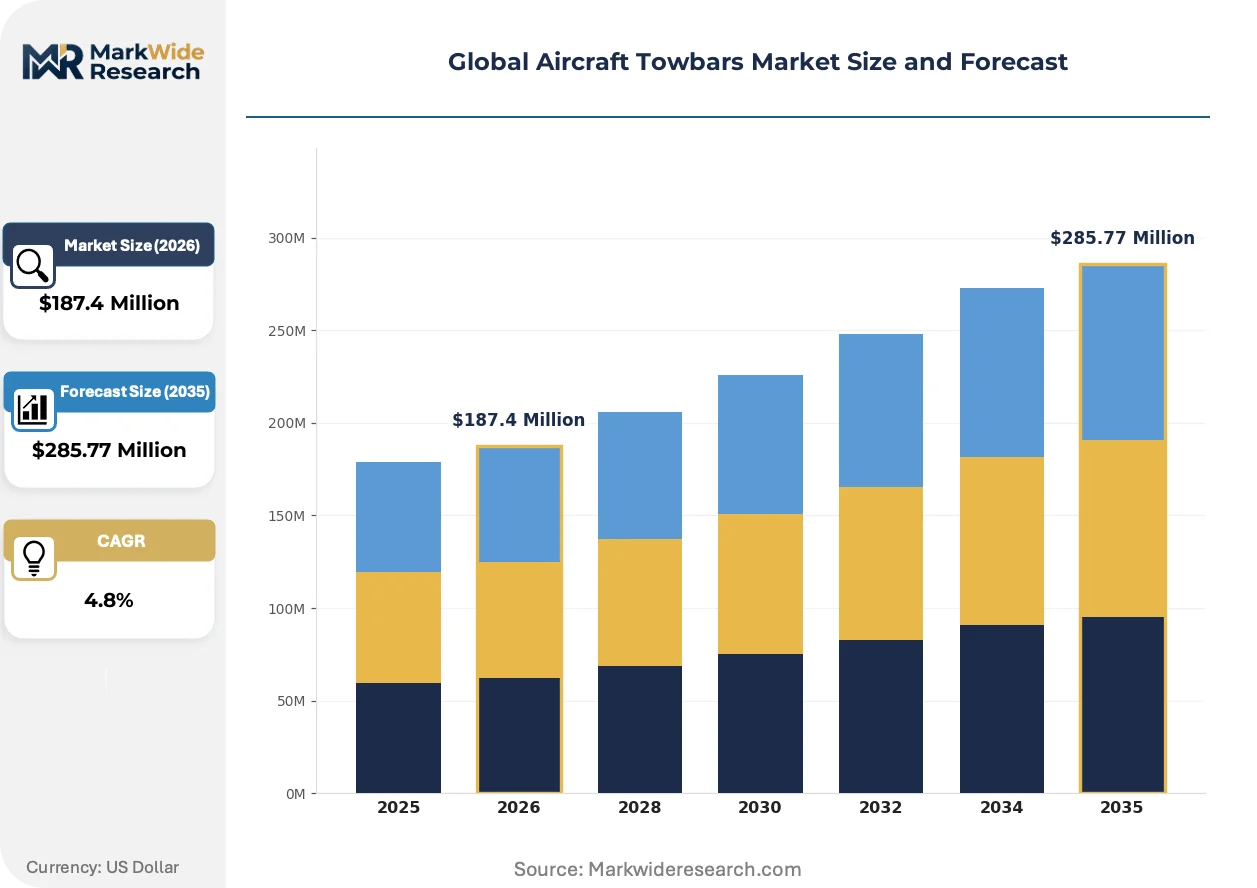
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Towbars, Heavy-Duty Towbars, Adjustable Towbars, Towbar Adapters Material: Aluminum, Steel, Composite, Plastic Application: Commercial Aviation, Military Aviation, General Aviation, Aerospace Maintenance End User: Airports, Airlines, Maintenance Repair Organizations, Military Bases |
| Companies Covered | Douglas Equipment, Aero-Pac, TLD Group, Collins Aerospace, Textron, Tronair Inc., JMS AG, Goldhofer AG, JBT AeroTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Towbars Market Emerging Trajectories
Material science breakthroughs and regulatory disclosure mandates are restructuring competitive advantage around verified supply chain transparency rather than unit cost alone, compressing legacy manufacturing models.
Carbon-fiber composite towbar construction is fragmenting traditional steel-dominated procurement patterns. Lufthansa Technik and Emirates Engineering have adopted hybrid composite-steel designs for narrow-body pushback operations, reducing ground crew fatigue and equipment transport costs. This material transition is fragmenting supplier hierarchies as specialized composites firms capture share from conventional metal fabricators.
EASA's CE-marked ground support equipment directive is tightening conformity assessment protocols for structural load testing. Manufacturers must now submit fatigue-test documentation to notified bodies before market placement, extending product development cycles by 4-6 months. Military aviation procurement offices in France and Spain are responding by pre-qualifying suppliers with established European technical files, favoring incumbent EU-based manufacturers.
Airline ground handling departments are consolidating vendor relationships around full-fleet service contracts rather than per-unit towbar purchases. Swissport and dnata are negotiating multi-year agreements bundling equipment, maintenance, and training, displacing spot-market transactions. This behavioral shift is most visible in the Middle East, where Dubai Airports and Abu Dhabi International have mandated single-source GSE providers for terminal operations.
Global Aircraft Towbars Market Segmentation
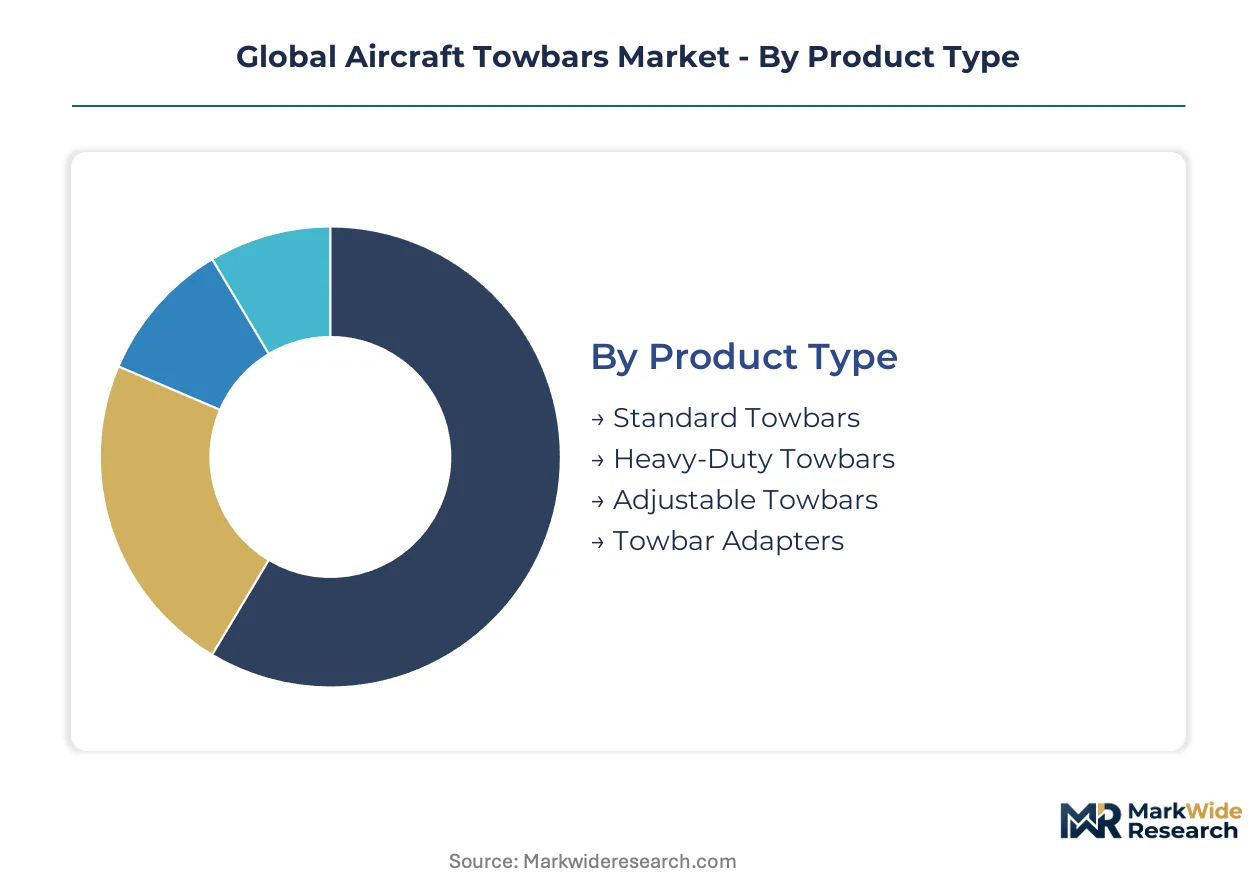
Aircraft towbar procurement patterns diverge sharply across operational contexts, with military and commercial aviation imposing incompatible load specifications and certification requirements. Understanding segment boundaries reveals where specialized manufacturers command pricing power versus where commodity fabrication dominates.
Product Type:
Margin pools concentrate in heavy-duty and adjustable configurations where NATO defense procurement and multi-platform MRO contracts sustain premium pricing.
- Standard Towbars:Fixed-length steel linkages designed for narrow-body commercial aircraft with consistent nose gear geometry. Demand clusters at major hub airports in Germany and the United States where high-frequency pushback operations prioritize equipment standardization and rapid crew training.
- Heavy-Duty Towbars:Reinforced structural members rated for transport aircraft exceeding 100-ton towing loads, typically fabricated from high-strength alloy steel with forged head castings. Procurement concentrates at Ramstein Air Base and other NATO logistics hubs in Bavaria serving C-17 and A400M fleets under compressed defense modernization cycles.
- Adjustable Towbars:Telescoping or modular designs accommodating variable aircraft configurations through interchangeable head attachments.
- Towbar Adapters:Interface components enabling cross-platform compatibility between towbar systems and diverse nose gear specifications.
The dominant share belongs to Standard Towbars, while Heavy-Duty Towbars is closing the gap fastest.
Material:
Cost tier stratification separates aerospace-grade alloys from emerging composites, with fuel-efficiency programs in commercial aviation driving material substitution at the premium end.
- Aluminum:Lightweight alloy construction reducing ground crew fatigue and equipment transport costs, prevalent in European commercial aviation where EASA weight-reduction advisories influence procurement specifications. Lufthansa Technik adoption of hybrid aluminum-composite designs signals technology transition.
- Steel:High-strength alloy and carbon steel dominating military applications where durability thresholds override unit weight considerations. Nickel and chromium price volatility compresses fabrication margins for standard product lines.
- Composite:Carbon-fiber-reinforced polymer systems achieving 40-60% weight reduction versus steel equivalents.
- Plastic:Limited-application polymer components for low-load general aviation and training equipment.
Steel retains volume leadership across defense contracts, though Composite is expanding most quickly in commercial airline sustainability programs.
Application:
Customer type fragmentation creates distinct sales cycles, with military procurement favoring durability certification and commercial aviation prioritizing total cost of ownership metrics.
- Commercial Aviation:Scheduled passenger and cargo airline operations requiring high-availability ground support equipment with standardized training protocols. Swissport and dnata consolidation around full-fleet service contracts displaces spot-market transactions in the Middle East.
- Military Aviation:Defense airbase operations with load ratings exceeding commercial thresholds and procurement cycles favoring multi-year durability guarantees over unit economics.
- General Aviation:Private and corporate aircraft operations with fragmented demand across regional airfields.
- Aerospace Maintenance:MRO facility requirements for adapter-compatible systems serving multiple aircraft platforms represent a concentrated margin pool.
Commercial Aviation commands the largest installed base, while Aerospace Maintenance is gaining share fastest through MRO consolidation.
End User:
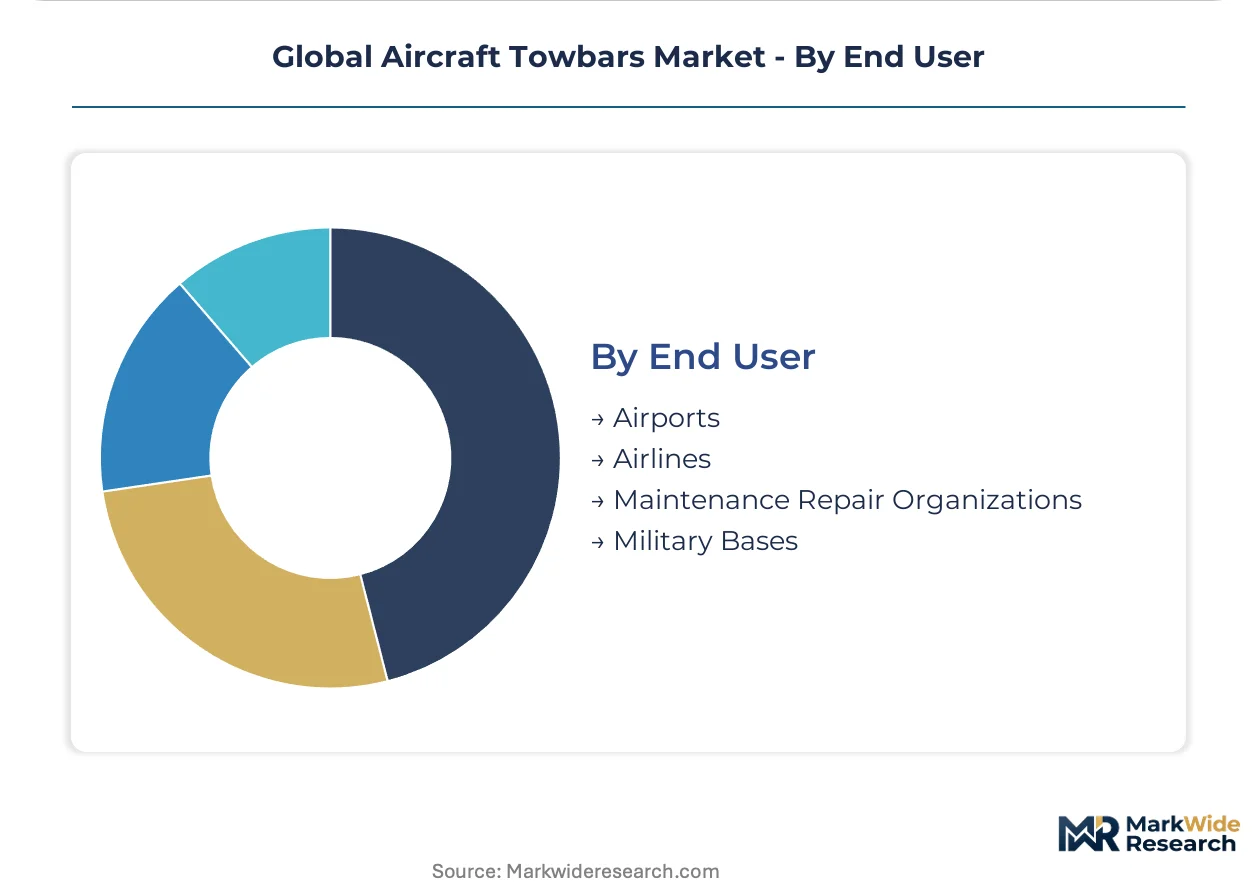
Procurement authority concentration varies by geography, with airport authorities in the United States and Germany wielding consolidated purchasing power versus fragmented airline decision-making elsewhere.
- Airports:Municipal and regional airport authorities managing ground handling equipment fleets under FAA 14 CFR Part 139 or EASA operating certificate requirements. Periodic load-testing mandates force replacement cycles at certified facilities.
- Airlines:Carrier-operated ground handling departments at hub locations, particularly concentrated in the Middle East where Dubai Airports and Abu Dhabi International mandate single-source GSE providers.
- Maintenance Repair Organizations:Third-party MRO facilities requiring multi-platform compatibility and rapid adapter interchangeability.
- Military Bases:Defense procurement offices with specialized heavy-lift requirements and extended technical qualification timelines.
Airports hold the dominant procurement volume, though Maintenance Repair Organizations is climbing the fastest as airline outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fabrication capacity clusters in Germany, the United States, and France, where defense procurement and commercial aviation MRO networks sustain specialized manufacturing ecosystems. Regulatory divergence across FAA, EASA, and national aviation authorities shapes regional compliance requirements and market entry barriers.
United States
Military base modernization at Ramstein Air Base and domestic defense installations drives heavy-duty towbar procurement cycles. FAA 14 CFR Part 139 mandates periodic load-testing and structural inspection, forcing certified airport operators into equipment replacement schedules. Douglas Equipment anchors North American production through steel fabrication expertise serving military contracts.
Germany
NATO logistics hubs in Bavaria concentrate demand for adjustable towbar systems compatible with C-17 and A400M transport fleets. EASA CE-marking requirements under the ground support equipment directive extend conformity assessment timelines for structural load testing. Goldhofer AG and TLD Group anchor production clusters serving European military and commercial fleets from southern German manufacturing bases.
France
Airbus manufacturing and maintenance networks in Toulouse and Paris-Charles de Gaulle generate concentrated demand for multi-platform compatible ground support equipment. EASA regulatory harmonization with French DGAC technical standards streamlines certification for domestic suppliers. Military aviation procurement offices in Paris pre-qualify suppliers with established European technical files, favoring incumbent EU-based manufacturers.
United Kingdom
Royal Air Force base modernization and commercial hub operations at Heathrow create dual-track demand for standard and heavy-duty configurations. CAA alignment with EASA post-Brexit transitional arrangements maintains CE-marking recognition for ground support equipment imports. Aerospace maintenance clusters in the Midlands require adapter-compatible systems serving narrow-body and wide-body platforms.
India
IndiGo and Air India fleet expansion at Delhi and Mumbai hubs intensifies ground handling equipment procurement from domestic assembly partnerships. DGCA tightened GSE import certification rules under 2023 technical regulations, creating compliance barriers for non-domestic manufacturers. Aviation infrastructure development in Maharashtra and Karnataka states concentrates demand for standardized pushback equipment at greenfield airport projects.
Global Aircraft Towbars Market Vendor Landscape
Concentration sits with diversified aerospace conglomerates and specialized ground support equipment fabricators competing across defense and commercial segments. Market structure shows moderate consolidation, with tiered positioning between scale-driven manufacturers and niche specialists serving military specifications. Strategic archetypes include steel-forging defense contractors, composite-material innovators, and full-fleet service integrators. Dominant competitive moves encompass vertical integration into critical forging capabilities and geographic expansion through domestic assembly partnerships in regulated import markets.
Among diversified aerospace conglomerates, Collins Aerospace and Textron occupy positions spanning avionics through ground support equipment portfolios. Specialized fabricators include Douglas Equipment representing North American steel-forging capabilities, Goldhofer AG exemplifying European heavy-lift ground support specialization, and Tronair Inc. anchoring composite-material development programs. These named entities illustrate archetype segmentation rather than exhaustive market coverage, with additional participants populating tiered positions across regional procurement networks.
| Leading Market Players |
|---|
| Douglas Equipment |
| Aero-Pac |
| TLD Group |
| Collins Aerospace |
| Textron |
| Tronair Inc. |
| JMS AG |
| Goldhofer AG |
| JBT AeroTech |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German and Italian forging facilities runs above 85%, compressing lead times for aerospace-grade towbar head castings and elevating price floors for standard steel configurations. This scale concentration grants incumbent metal fabricators pricing power over NATO defense contracts while forcing commercial buyers toward composite alternatives.
Pricing Analysis
Volume-discount tiering structures separate military procurement bundles from spot-market commercial transactions. Three-tier pricing stratifies across premium heavy-duty alloy systems, standard fixed-length steel units, and economy-grade aluminum configurations. Price differentiation hinges on EASA CE-marking certification status and load-test documentation completeness. Pricing pressure stems from nickel and chromium spot volatility eroding fabrication margins for carbon steel product lines. Commercial airlines exhibit highest price sensitivity, while defense procurement offices prioritize durability guarantees over unit economics.
Supply Chain Analysis
Strategic stockpiling of aerospace-grade alloy steel dominates military procurement patterns, while commercial ground handlers favor just-in-time composite component flows. Supply concentrates in Germany, Italy, and the United States, with critical towbar head castings drawing from northern Italian forging clusters. Raw material dependencies rest on nickel-chromium alloy feeds, carbon-fiber precursor chemicals, and high-strength aluminum billet. Single-source vulnerability concentrates in Italian forging capacity for military-grade head components. Distribution runs through OEM-direct channels for defense contracts and GSE service integrators for commercial aviation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite material substitution and EASA CE-marking tightening constitute dual inflection points disrupting legacy steel fabrication models. Stakeholders must reposition around verified supply chain transparency and predictive maintenance service architectures.
For Market Incumbents: Shield installed base relationships by securing captive forging capacity in Germany or Italy before alloy steel price volatility deepens. Accelerate CE-marking technical file completion for European defense pre-qualification cycles. Composite specialists like Tronair threaten premium positioning; counter with hybrid material R&D partnerships and backward integration into carbon-fiber precursor supply. For New Entrants and Emerging Players: Lead with telematics-integrated towbar platforms targeting MRO consolidation in the Middle East and India. India's DGCA import certification barriers create white-space for domestic assembly joint ventures serving IndiGo and Air India ground operations. Bundle predictive maintenance subscriptions with equipment sales to capture recurring revenue from Swissport and dnata fleet service contracts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telematics-enabled fleet management providers and full-fleet GSE service integrators. Over a five-to-ten year horizon, acquisition targets with established EASA technical files and NATO supplier pre-qualification status command defensive moats. Monitor EU Green Deal carbon-footprint audit implementation as the inflection signal for material sourcing compliance premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging Capacity | Captive supply of towbar head castings insulates margin from Italian supplier concentration risk. |
| Composite Material R&D Partnership | Carbon-fiber weight reduction aligns with Lufthansa Technik and Emirates Engineering sustainability procurement criteria. |
| CE-Marking Technical File Investment | EASA notified body pre-approval accelerates European defense procurement cycles in France and Spain. |
| Telematics Platform Development | IoT sensor integration enables predictive maintenance subscriptions shifting revenue from equipment sales to services. |
| Domestic Assembly Joint Venture | India DGCA compliance through local partnership captures IndiGo and Air India ground handling equipment demand. |
Methodological Framework
Cross-validation between primary interviews with ground handling equipment procurement managers and secondary validation through FAA 14 CFR Part 139 enforcement records anchors the qualitative findings. Stakeholder engagement encompassed GSE fleet directors at major hub airports, defense procurement officers at NATO airbases, MRO facility maintenance heads, and composite material R&D leads at European airlines. Secondary sources included EASA ground support equipment directive conformity databases, customs trade flows for aerospace-grade alloy steel, and airport operating certificate inspection records. Bottom-up unit economics triangulated against top-down defense budget allocation patterns.
Sensitivity analysis around nickel price volatility and defense procurement cycle compression informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product type configuration, material grade tier, application context, and end-user procurement authority. CAGRs derive from installed base replacement schedules, fleet expansion trajectories, and regulatory mandate compliance deadlines. Forecast inputs incorporate NATO airbase modernization timelines and commercial airline ground handling outsourcing rates.
The analysis sits within stated boundaries; outcomes outside sustained defense budget expansion or EASA regulatory enforcement intensity would require recalibration. Forecasts reflect assumptions regarding composite material adoption curves and CE-marking assessment timelines. Revision becomes warranted when alloy steel price volatility exceeds historical bands or when India DGCA import certification rules shift enforcement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Asia-Pacific Turboprop Aircraft Market
Aircraft
Helicopter Lighting Market
Aircraft
Light Sport Aircraft (LSA) Market
Aircraft
Hybrid Aircraft Market
Aircraft
Asia-Pacific Aircraft Manufacturing Market
Aircraft
Air Starter Market
Aircraft
Commercial Aerospace Market
Aircraft
Middle-East and Africa Turboprop Aircraft Market
Aircraft
America Freighter Aircraft Market
Aircraft
Europe Aircraft Engines Market
Aircraft
Global Aircraft De-Icing Market
Aircraft
Asia-Pacific Aviation Market
Aircraft
Asia-Pacific General Aviation Market
Aircraft
Aircraft Galley Systems Market
Aircraft
Aircraft Aerostructures Market
Aircraft
Aircraft Cargo Systems Market