
 Refrigerated Vans Market | 2026-2036
Refrigerated Vans Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigerated Vans Market Analytics
Consolidation among food distributors is restructuring procurement patterns for refrigerated van fleets. Carrier Transicold leverages its transport refrigeration heritage to sustain aftermarket parts revenue across European logistics corridors. Thermo King competes on electric compressor technology for last-mile delivery in urban zones with emission restrictions.
Refrigerated vans are insulated commercial vehicles equipped with active cooling systems, typically maintaining cargo temperatures between minus 25 degrees Celsius and plus 20 degrees Celsius for perishable goods transport. Small refrigerated vans lead urban last-mile delivery where maneuverability constraints dominate routing decisions, while dual-temperature systems represent the fastest-expanding technology segment as pharmaceutical and food-service operators seek single-vehicle flexibility for mixed cargo loads. Diesel fuel types still occupy the largest installed base, though electric variants are capturing disproportionate attention in municipal fleet tenders with zero-emission mandates.
The European Commission's F-Gas Regulation and the EPA's SNAP program in the United States are both tightening refrigerant phase-down schedules, forcing manufacturers to redesign thermal systems around lower-global-warming-potential alternatives. Germany's KBA enforces type-approval standards that delay entry for non-compliant imported chassis. Fleet operators and system integrators must monitor regulatory divergence between jurisdictions to avoid stranded assets in cross-border logistics networks.
Market Dynamics
The refrigerated vans market is restructuring around refrigerant phase-down mandates that force thermal system redesigns while pharmaceutical cold-chain requirements pull fleet specifications toward tighter temperature precision.
Growth Catalysts
- Biologics logistics expansion:Pharmaceutical distributors are scaling temperature-controlled last-mile capacity to protect mRNA vaccines and cell therapies from production facilities to point-of-care sites.
- F-Gas Regulation:Europe's hydrofluorocarbon phase-down timeline accelerates CO2-based transport refrigeration deployment across German, French, and Dutch logistics corridors.
- Urban emission zones:Municipal zero-emission mandates in London, Amsterdam, and Stockholm concentrate electric refrigerated van procurement in food-service and grocery delivery fleets.
Market Restraints
- Refrigerant supply concentration:CO2 compressor manufacturing capacity clusters with German and Japanese component suppliers, creating procurement bottlenecks during fleet conversion cycles.
- Battery thermal trade-offs:Electric van range degradation under refrigeration load limits payload-distance economics for rural distribution routes.
- Chassis type-approval friction:Germany's KBA certification delays strand non-compliant imported chassis in cross-border logistics networks.
Strategic Opportunities
- Dual-temperature system penetration:Pharmaceutical and food-service operators seek single-vehicle flexibility for mixed frozen-chilled cargo loads, expanding addressable unit economics.
- Service contract unbundling:Fleet operators separate refrigeration unit maintenance from vehicle leasing, creating standalone aftermarket revenue pools for thermal system specialists.
- IRA commercial vehicle credits:United States tax incentives for zero-emission medium-duty trucks accelerate electric refrigerated van adoption in California and New York metro distribution.
Industry Challenges
- Refrigeration technician scarcity:CO2 system servicing requires pressure-certification beyond conventional HVAC training, constraining aftermarket service network expansion.
- Cross-border compliance fragmentation:Divergent refrigerant handling permits between EU member states and Swiss border regimes complicate pan-European fleet standardization.
- Telematics integration complexity:Temperature monitoring systems must interface with legacy fleet management platforms without disrupting real-time cargo documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigerated Vans Market |
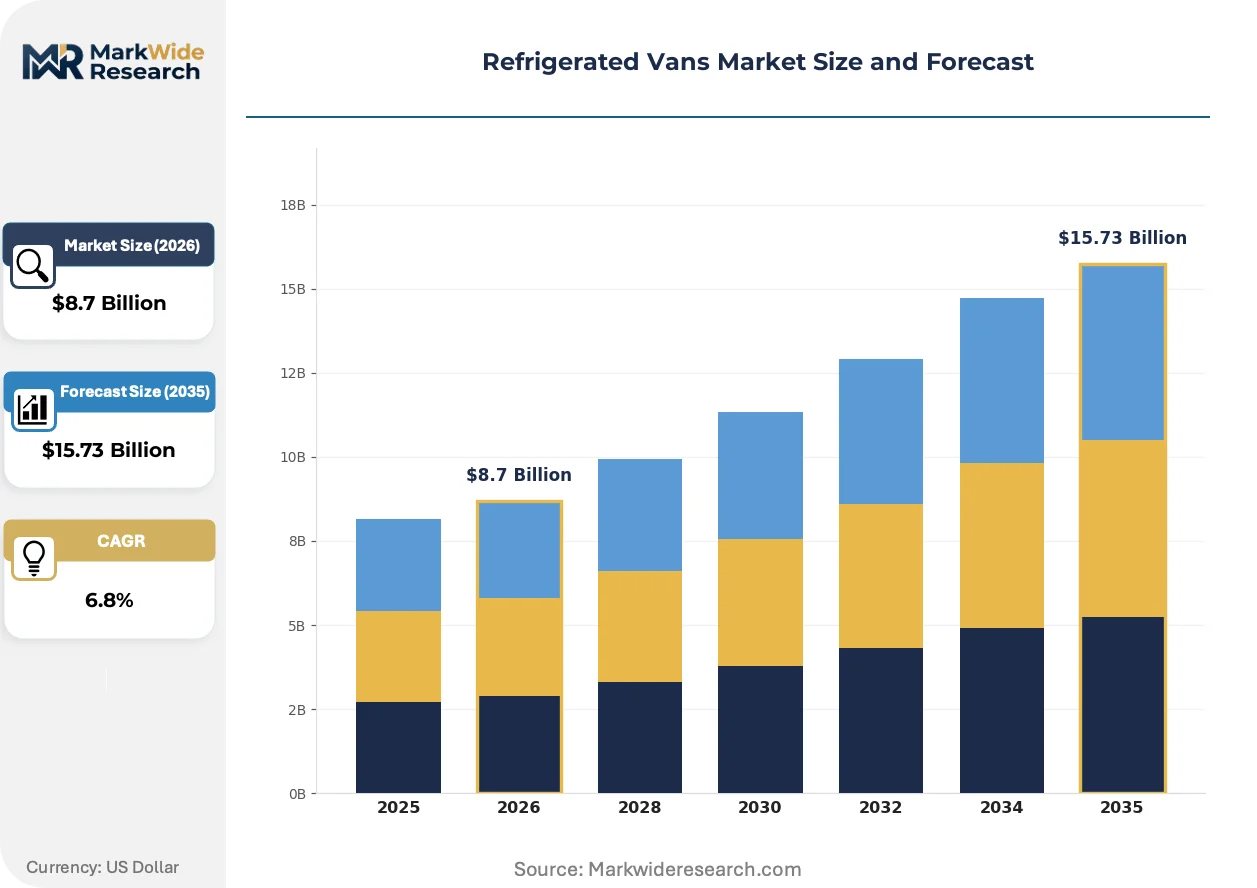
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Refrigerated Vans, Medium Refrigerated Vans, Large Refrigerated Vans, Custom Refrigerated Vans End User: Food Distributors, Pharmaceutical Companies, Catering Services, Logistics Providers Temperature Control Technology: Refrigeration Units, Freezer Units, Dual-Temperature Systems, Passive Cooling Fuel Type: Diesel, Petrol, Electric, Hybrid |
| Companies Covered | Webasto Group, Volvo Trucks, Carrier Transicold, Schmitz Cargobull, Iveco, Thermo King, Mercedes-Benz, Isuzu Motors, Daikin Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigerated Vans Market Evolving Landscape
Refrigerated van technology is converging on electrification and digital traceability, with regulatory pressure compressing development cycles and procurement specifications fragmenting across urban emission zones and pharmaceutical compliance tiers.
CO2 transcritical refrigeration is integrating into medium-duty van platforms as the dominant alternative to phased-down hydrofluorocarbon systems. Food distributors operating German urban routes are specifying these units in municipal tender responses. The technology is integrating thermal performance with regulatory compliance, compressing the viable product lifecycle for conventional refrigerant architectures.
Europe's F-Gas Regulation mandates specific hydrofluorocarbon quota reductions through 2030, forcing transport refrigeration manufacturers to redesign compressor architectures and service protocols. Fleet operators face asset stranding risk where refrigerant recharge availability constricts before vehicle replacement cycles complete. German logistics providers are responding with accelerated CO2 fleet conversion schedules ahead of regulatory deadlines.
Outcome-based temperature guarantees are displacing equipment-centric procurement in pharmaceutical logistics contracts. Cold-chain service providers now absorb cargo-loss liability in exchange for per-delivery fees, transferring capital risk from shippers to fleet operators. This shift concentrates most visibly in Netherlands-Belgium pharmaceutical distribution corridors where GDP compliance auditing costs have escalated.
Refrigerated Vans Market Segmentation
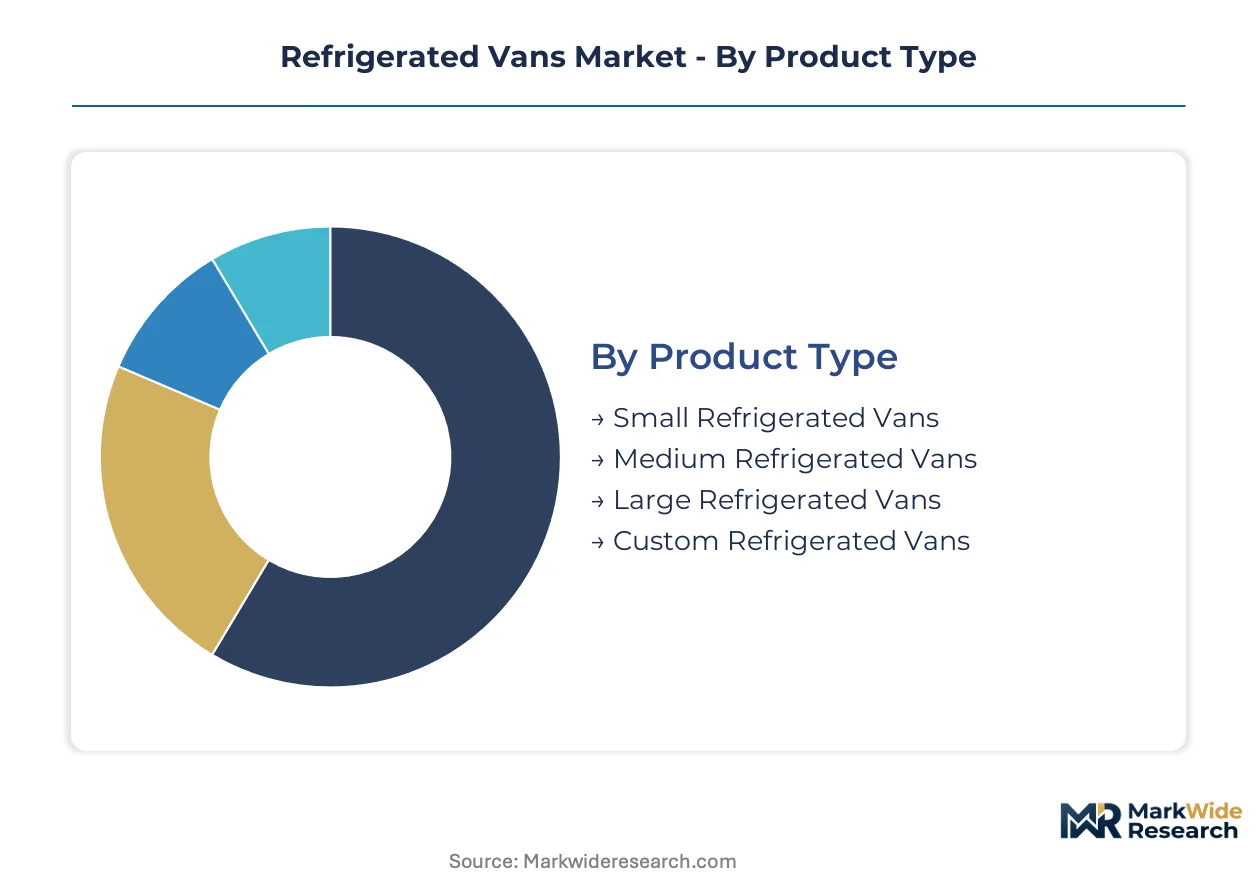
Fleet procurement decisions in the refrigerated vans market hinge on payload-distance economics, regulatory compliance tiers, and cargo temperature precision requirements. Segment boundaries shift as urban emission zones expand and pharmaceutical cold-chain specifications tighten.
Product Type:
Small vans dominate urban route density while large platforms capture intercity pharmaceutical volume; the split reflects maneuverability premiums against payload efficiency.
- Small Refrigerated Vans:Compact chassis with sub-3.5-tonne gross vehicle weight ratings optimize last-mile routing through Amsterdam, London, and Stockholm low-emission zones. Grocery delivery aggregators specify these units to comply with municipal zero-emission mandates while maintaining frozen and chilled cargo separation.
- Medium Refrigerated Vans:The 3.5-to-7.5-tonne gross vehicle weight class balances payload capacity with driver licensing accessibility across German and French logistics networks. Food-service distributors favor this segment for multi-drop catering routes requiring dual-zone temperature maintenance.
- Large Refrigerated Vans:Heavy-duty platforms exceeding 7.5 tonnes serve pharmaceutical trunk routes from production facilities to regional distribution hubs.
- Custom Refrigerated Vans:Bespoke bodywork and refrigeration configurations address specialized cargo profiles including floral transport and medical specimen collection.
Today's leader: Medium vans. Tomorrow's challenger: Small electric platforms.
End User:
Application-driven procurement separates commodity food logistics from compliance-intensive pharmaceutical distribution, with service contract structures diverging accordingly.
- Food Distributors:Supermarket chains and wholesale grocers operate the largest installed base, prioritizing total cost of ownership over temperature precision. Their fleet replacement cycles accelerate where F-Gas Regulation refrigerant phase-downs strand conventional thermal systems before depreciation completion.
- Pharmaceutical Companies:mRNA vaccine and cell therapy logistics demand continuous temperature documentation with GDP compliance auditing. These operators specify dual-temperature systems and telematics integration to absorb cargo-loss liability under outcome-based service contracts.
- Catering Services:Event and institutional food providers require rapid temperature pull-down capabilities for intermittent high-volume loads.
- Logistics Providers:Third-party cold-chain operators aggregate demand across fragmented shipper bases, standardizing fleet specifications to maximize asset utilization.
Food distribution commands current volume. Pharmaceutical compliance is climbing the fastest.
Temperature Control Technology:
Active versus passive thermal management separates regulated pharmaceutical cargo from short-haul food service, with hybrid systems gaining traction in mixed-load operations.
- Refrigeration Units:Compressor-driven systems maintaining 0°C to +4°C dominate fresh produce and dairy logistics. These units face refrigerant redesign pressure as hydrofluorocarbon quotas constrict under European F-Gas Regulation timelines.
- Dual-Temperature Systems:Independent evaporator circuits enable simultaneous frozen and chilled cargo carriage within a single vehicle envelope. Pharmaceutical and food-service operators specify these configurations to reduce fleet capital intensity while expanding serviceable contract scope.
- Freezer Units:Minus-25°C capability serves ice cream distribution and frozen protein supply chains.
- Passive Cooling:Insulated containers with phase-change materials support short-duration pharmaceutical transport where active systems prove economically unjustified.
Refrigeration units hold installed base dominance. Dual-temperature systems show steepest expansion trajectory.
Fuel Type:
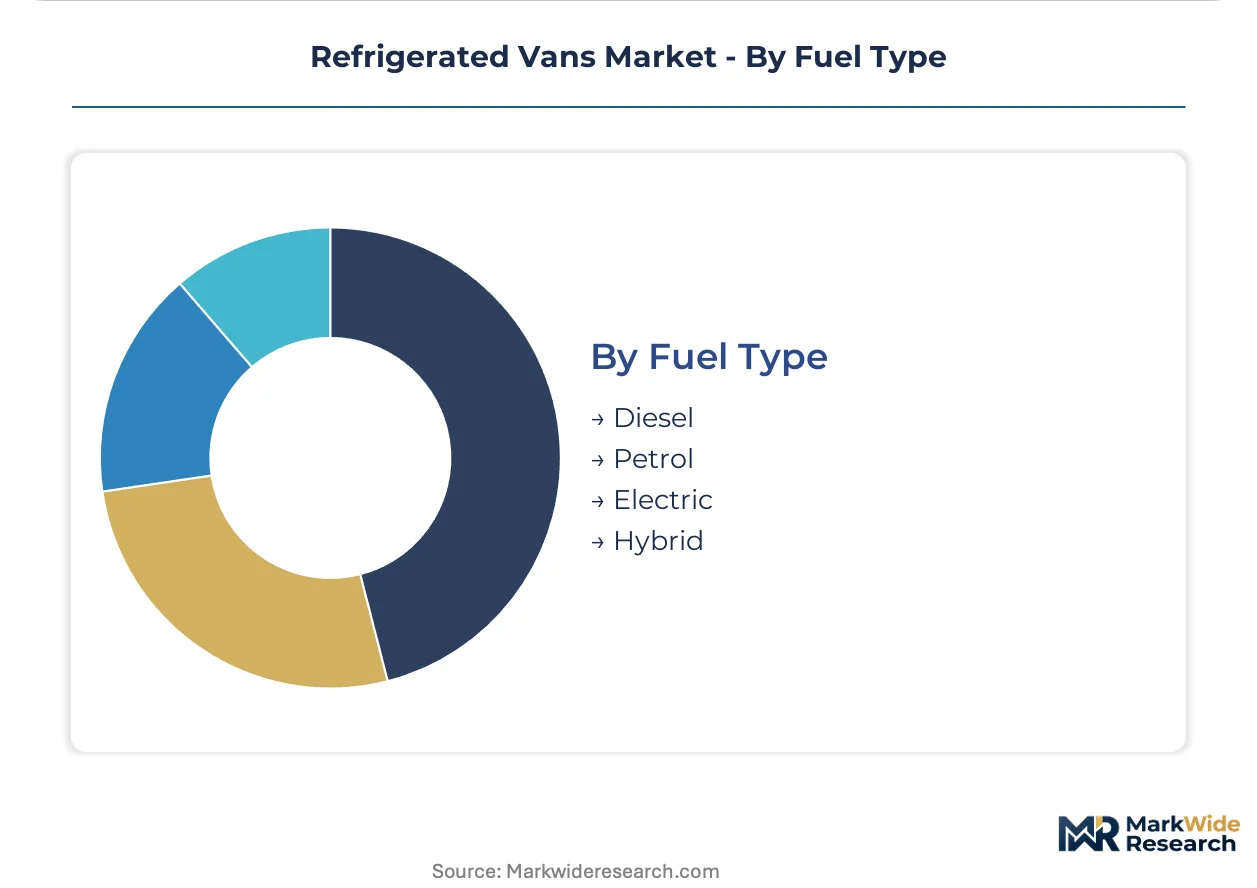
Powertrain selection tracks regulatory pressure gradients, with diesel retreating from urban cores while electric adoption concentrates in tender-driven municipal fleets.
- Diesel:Compression-ignition engines power the majority of long-haul and rural distribution routes where refueling infrastructure density and range requirements favor established technology. These platforms face escalating access restrictions in London's Ultra Low Emission Zone and comparable European urban regimes.
- Electric:Battery-electric drivetrains capture disproportionate procurement attention in California and New York metro distribution networks where IRA commercial vehicle credits improve total cost of ownership calculations. Range degradation under refrigeration load constrains deployment to sub-200-kilometer daily cycles.
- Petrol:Spark-ignition engines persist in light-duty applications and markets with limited diesel retail availability.
- Hybrid:Dual-powertrain configurations bridge electric zero-emission zone compliance with extended-range diesel operation.
Diesel retains route flexibility leadership. Electric platforms are displacing conventional powertrains in urban emission zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany enforces stricter F-Gas phase-down timelines than the United States, while China's electric van subsidies outpace European IRA-equivalent programs. Fleet procurement concentrates where urban emission zones intersect with pharmaceutical distribution corridors.
Germany
Pharmaceutical cold-chain expansion and grocery delivery aggregation drive fleet renewal in the Rhine-Ruhr and Bavarian logistics clusters. The KBA enforces chassis type-approval standards that delay non-compliant imports. Munich-based food distributors accelerate CO2 refrigeration adoption ahead of F-Gas Regulation deadlines.
United States
IRA commercial vehicle credits reshape electric refrigerated van economics for California and New York metro distribution networks. The EPA SNAP program tightens hydrofluorocarbon refrigerant phase-down schedules. Los Angeles cold-chain operators integrate telematics systems to meet FDA pharmaceutical documentation requirements.
Netherlands
Amsterdam's zero-emission zone mandates concentrate electric small-van procurement among grocery delivery fleets. GDP compliance auditing costs escalate along the Rotterdam-Antwerp pharmaceutical corridor. Dutch logistics providers unbundle refrigeration maintenance from vehicle leasing contracts.
United Kingdom
London's Ultra Low Emission Zone restricts diesel van access while supermarket chains expand temperature-controlled last-mile capacity. Post-Brexit refrigerant handling permits diverge from EU F-Gas Regulation alignment. Birmingham food-service distributors specify dual-temperature systems for multi-drop catering routes.
Japan
Metropolitan Tokyo emission regulations accelerate electric van trials for convenience store replenishment cycles. METI efficiency standards pressure thermal system redesigns. Osaka-based pharmaceutical distributors invest in passive cooling containers for short-duration medical specimen transport.
Refrigerated Vans Market Competitive Landscape
German and Japanese component suppliers anchor one tier; Swedish and American system integrators hold fleet-scale contract positions. The market structures around three tiers: chassis OEMs with captive refrigeration partnerships, independent thermal system specialists, and aftermarket service networks. Competitive moves concentrate on refrigerant architecture transitions and electric compressor manufacturing partnerships.
Among European-based fabricators, Carrier Transicold and Thermo King exemplify transport refrigeration heritage leveraged into aftermarket parts revenue. Webasto Group occupies a position bridging automotive thermal management expertise with commercial vehicle applications. These three represent distinct archetypes: legacy refrigeration equipment, electric compressor technology, and integrated thermal system design.
| Leading Market Players |
|---|
| Webasto Group |
| Volvo Trucks |
| Carrier Transicold |
| Schmitz Cargobull |
| Iveco |
| Thermo King |
| Mercedes-Benz |
| Isuzu Motors |
| Daikin Industries |
| Others |
Value Network & Pricing Analysis
CO2 refrigeration certification tiers split the refrigerated vans market into premium thermal system providers and commodity compressor assemblers, with that bifurcation manifesting in both unit pricing spreads and supplier qualification requirements across German and Japanese component networks.
Pricing Analysis
Capacity additions in Germany and Japan are reshaping price floors for transcritical CO2 compressors as component suppliers expand manufacturing lines ahead of F-Gas Regulation deadlines. Three-tier pricing structure across premium-certified, standard-compliant, and economy-grade thermal systems tracks GDP compliance certification levels and telematics integration depth. Cost compression in economy-grade diesel-powered segments is intensifying because fleet operators accelerate replacement cycles to avoid refrigerant stranding risk. Food distributors exhibit highest price sensitivity, while pharmaceutical logistics providers absorb premium pricing for outcome-based temperature guarantees.
Supply Chain Analysis
GDP compliance certification and KBA type-approval gating restrict supplier participation to established German and Japanese thermal system manufacturers with validated pressure-certification protocols. Compressor manufacturing draws from precision-machined aluminum castings, specialized refrigerant-grade sealing materials, and high-pressure CO2-compatible electronics. Single-source vulnerability concentrates in Japanese electric compressor motor suppliers serving European system integrators. Distribution runs through captive OEM service networks for chassis-integrated units and independent aftermarket channels for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in refrigerated vans rests on CO2 system conversion premiums and unbundled service contract economics, with fleet operators transferring cargo-loss liability to cold-chain specialists willing to absorb capital risk.
For Market Incumbents: To counter electric van range degradation under refrigeration load, Carrier Transicold and Thermo King should deepen backward integration into battery thermal management systems while accelerating CO2 compressor manufacturing partnerships in Germany. Certification investment in multi-jurisdictional refrigerant handling permits protects against cross-border compliance fragmentation stranding pan-European fleet contracts. For New Entrants and Emerging Players: The price-point gap between premium pharmaceutical-grade dual-temperature systems and economy food-service refrigeration units creates entry space for mid-tier hybrid-electric specialists targeting Dutch and Belgian urban emission zones. Focus white-space capture on grocery delivery aggregators in Amsterdam and London seeking zero-emission compliance without full pharmaceutical certification overhead. Go-to-market leverage rests on telematics-native platforms with API-first fleet management integration. For Investors and Strategic Acquirers: Asymmetric upside sits with thermal system specialists possessing CO2 pressure-certification capabilities and established aftermarket service networks. Five-to-ten-year viability favors acquisition targets with unbundled maintenance contract revenue streams and municipal tender track records in European zero-emission zones. Watch for inflection when IRA commercial vehicle credit extensions trigger accelerated electric van procurement in California distribution corridors.| Strategic Initiative | Industry Significance |
|---|---|
| CO2 Refrigeration Platform Standardization | Carrier Transicold and Thermo King compress development costs across German logistics corridors under F-Gas Regulation pressure. |
| Dual-Temperature System Manufacturing Scale-Up | Webasto Group expands addressable contract scope for pharmaceutical and food-service mixed-load operators. |
| Battery Thermal Management Integration | Electric van range degradation under refrigeration load constrains payload-distance economics without specialized thermal design. |
| Telematics-Native Fleet Partnership | API-first temperature monitoring platforms interface with legacy fleet management systems in Netherlands-Belgium pharmaceutical corridors. |
| Aftermarket Service Network Expansion | CO2 pressure-certification scarcity constrains technician supply for transcritical system maintenance across European logistics networks. |
Research Methodology
Direct dialogue with fleet procurement directors, refrigeration system engineers, pharmaceutical logistics compliance officers, and municipal tender administrators grounded qualitative findings, validated against customs trade data for insulated vehicle chassis, EPA SNAP program filings, KBA type-approval registries, and European F-Gas Regulation quota tracking databases. Bottom-up unit economics modeling triangulated with top-down market sizing across vehicle class, temperature control technology, and fuel type segmentation dimensions.
Installed base projections and replacement cycle forecasts across the modeling period incorporated refrigerant phase-down compliance deadlines, urban emission zone expansion schedules, and pharmaceutical cold-chain GDP certification tier adoption curves. CAGRs derived from logistic curve fitting to historical fleet penetration data, cross-referenced with municipal procurement volume disclosures and IRA commercial vehicle credit utilization rates in California and New York metro distribution networks.
Caveats apply where F-Gas Regulation acceleration or battery energy density breakthroughs could materially shift the outlook for electric refrigerated van economics. Forecasts reflect assumptions around CO2 compressor manufacturing capacity expansion and technician certification pipeline throughput. A model refresh is warranted upon material change in municipal zero-emission mandate enforcement timelines or pharmaceutical outcome-based contract penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Global Timber Trailer Market
Commercial Vehicles
Japan Commercial Vehicles Market
Commercial Vehicles
Iraq Trailer Market
Commercial Vehicles
Electric LCV Market
Commercial Vehicles
Heavy Haulage Trucks Market
Commercial Vehicles
Semi-Tractor Trailer Market
Commercial Vehicles
Europe Light Commercial Vehicle Trailer Market
Commercial Vehicles
Farm Trucks Market
Commercial Vehicles
Heavy-Duty Trucks Market
Commercial Vehicles
Truck-As-A-Service Market
Commercial Vehicles
Mini Truck Market
Commercial Vehicles
Commercial Vehicle Steering Column Market
Commercial Vehicles
Commercial Vehicle Calibration Market
Commercial Vehicles
Small Commercial Vehicle Market
Commercial Vehicles
Industrial Vehicles Market
Commercial Vehicles
Global Commercial Vehicle Fuel Tank Market