
 Mini Truck Market | 2026-2036
Mini Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Mini Truck Market Outlook
The split between premium connected-light-commercial vehicles and bare-bones utility haulers is realigning procurement patterns across emerging economies. Tata Motors leverages its captive chassis engineering to dominate sub-one-tonne rural logistics in South Asia. Suzuki Motor Corporation anchors the Japanese kei-truck segment through kei-class regulatory optimization and tight dealer-network control. Mahindra & Mahindra differentiates via diesel-hybrid development for unpaved-road durability in African and Latin American export markets.
A mini truck denotes a light commercial vehicle with gross vehicle weight typically below 3.5 tonnes, featuring cab-over-engine architecture and open or enclosed cargo beds optimized for tight urban turning radii and narrow rural roads. These vehicles serve micro-enterprises requiring payload capacity exceeding three-wheelers without the operating cost of full-size trucks. The pickup product type occupies the largest revenue pool due to versatility across construction and delivery applications, while electric fuel types represent the fastest-expanding segment as battery costs decline and urban access restrictions multiply. Diesel variants remain entrenched in agricultural and utility end uses where charging infrastructure is sparse and torque demands are high.
India's BIS crash-test mandates and CEA electrification directives are forcing platform redesigns for domestic-market compliance, while Japan's METI kei-vehicle dimension rules preserve a protected design envelope that shapes exportable architectures. China's MIIT new-energy-vehicle credits and GB standards for commercial EV safety are accelerating battery-platform homologation timelines for OEMs serving multiple Asian markets. Stakeholders must track how divergent national safety-economy trade-offs reshape commonality across regional product lines.
Market Dynamics
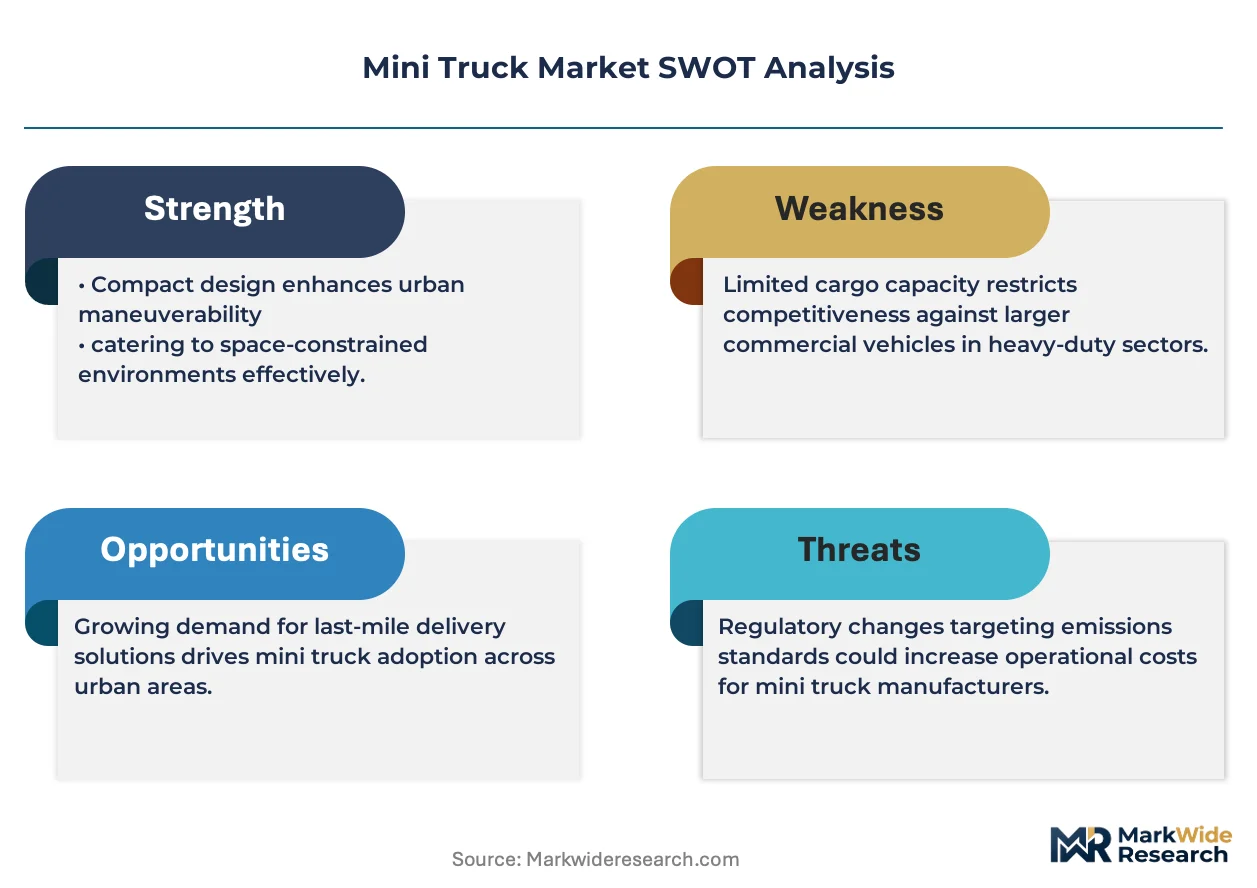
The electrification pivot is fragmenting platform architectures across the Mini Truck Market, as OEMs split development resources between ICE durability for rural corridors and battery-electric urban compliance.
Growth Catalysts
- CEA Electrification Directives:India's central electricity authority mandates are accelerating domestic battery-platform investments and expanding charging infrastructure along logistics corridors.
- Last-Mile E-Commerce Density:Urban fulfillment networks in Southeast Asian megacities are scaling compact electric fleets to navigate congestion zones and access-restricted central business districts.
- Kei-Class Regulatory Optimization:Japan's METI dimension rules preserve protected design envelopes that lower homologation costs for exportable compact architectures serving adjacent Asian markets.
Market Restraints
- Lithium-Ion Cell Supply Concentration:Battery raw material processing and cathode production clusters in specific East Asian geographies create input cost volatility and supply security exposure for non-integrated OEMs.
- Rural Charging Infrastructure Gaps:Agricultural and remote utility end-uses face range and downtime constraints where grid extension remains uneconomical, entrenching diesel dependence.
- Dual Homologation Burden:Divergent crash-test mandates between India's BIS standards and China's GB protocols force redundant engineering cycles for multi-market platforms.
Strategic Opportunities
- Vietnam Agricultural Mechanization:Mekong Delta farming cooperatives present unmet demand for sub-one-tonne haulers capable of navigating narrow delta levees and post-harvest transport.
- Swappable Battery Standardization:Convergence between modular pack architectures and automated swap station networks could eliminate charging downtime for high-utilization delivery fleets.
- Indonesian Logistics Corridor Electrification:Jakarta-Bandung-Surabaya freight lanes under the national net-zero roadmap offer regulatory tailwinds for electric mini truck deployment with preferential toll and parking access.
Industry Challenges
- Power Electronics Talent Scarcity:Battery management system firmware and motor control engineering expertise concentrates in automotive hubs, creating recruitment bottlenecks for emerging market OEMs.
- Platform Certification Timeline Compression:Simultaneous BIS crash-test validation and MIIT new-energy-vehicle credit qualification stretches regulatory affairs capacity and delays market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mini Truck Market |
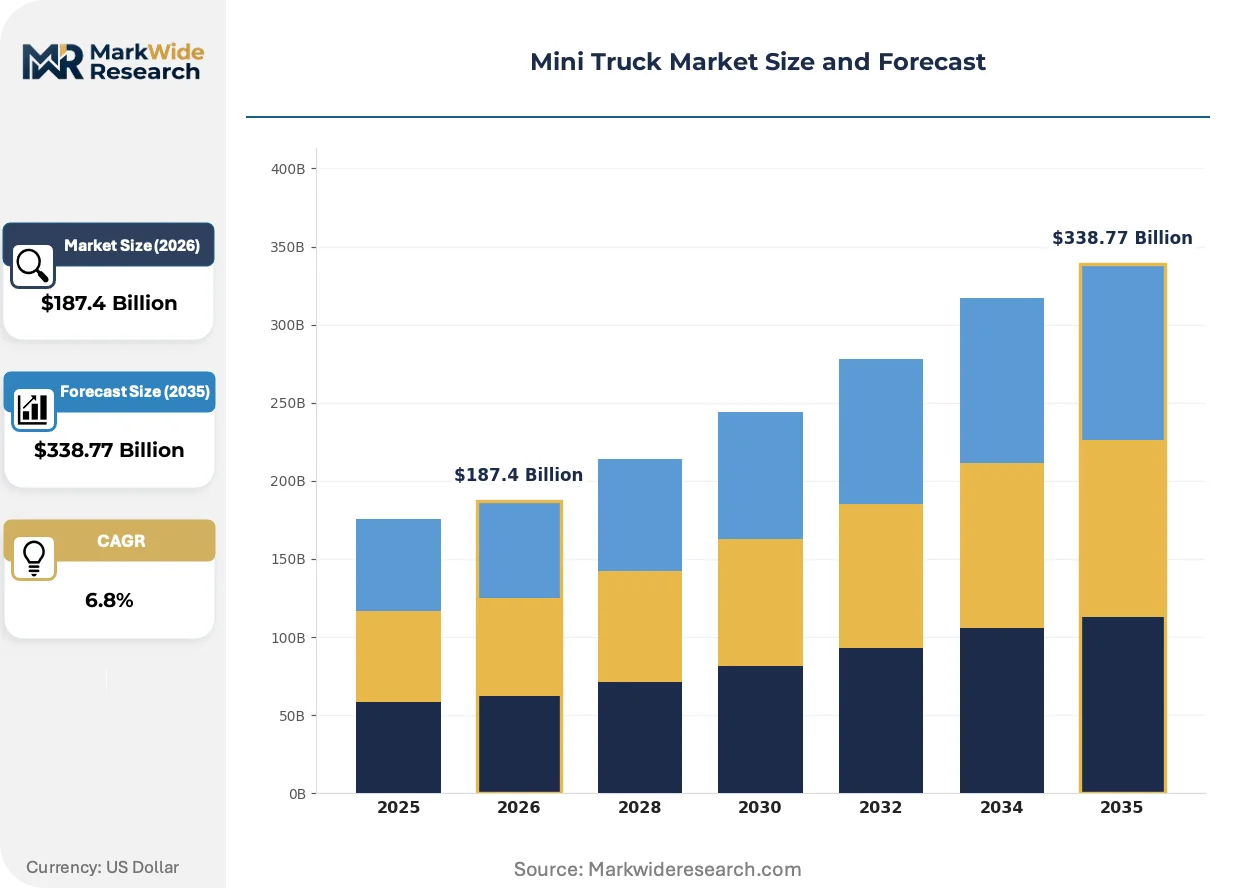
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pickup, Dump, Flatbed, Chassis Application: Construction, Delivery, Agriculture, Utilities End User: Small Businesses, Government, Contractors, Agricultural Firms Fuel Type: Diesel, Gasoline, Electric, Hybrid |
| Companies Covered | FAW Jiefang, Mahindra & Mahindra, Ford Motor Company, Mitsubishi Motors, Daihatsu Motor, Toyota Motor Corporation, Suzuki Motor Corporation, Tata Motors, Hyundai Motor Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mini Truck Market Strategic Shifts
Platform modularity is redefining how mini trucks bridge urban delivery and rural utility applications, compressing development cycles while expanding addressable use cases.
Cell-to-pack battery architecture is unifying thermal management and structural integrity into single-component designs. Fleet operators in Indonesian logistics corridors are adopting these integrated platforms for reduced maintenance intervals. The technology is unifying previously separate chassis engineering and energy storage supply chains, forcing tier-one suppliers to reconfigure manufacturing footprints.
China's MIIT dual carbon goals and GB standards for commercial EV safety are compressing homologation timelines for battery-platform variants. OEMs serving multiple Asian markets must now front-load crash-test validation and electromagnetic compatibility certification. The pickup segment faces the steepest compliance burden as payload versatility attracts the strictest safety scrutiny.
Micro-enterprise buyers are consolidating procurement through fleet management aggregators rather than traditional dealer networks. These platforms bundle financing, insurance, and predictive maintenance into per-kilometer contracts. The shift is most visible in India's tier-two cities where informal logistics operators lack capital for direct vehicle ownership.
Mini Truck Market Segmentation
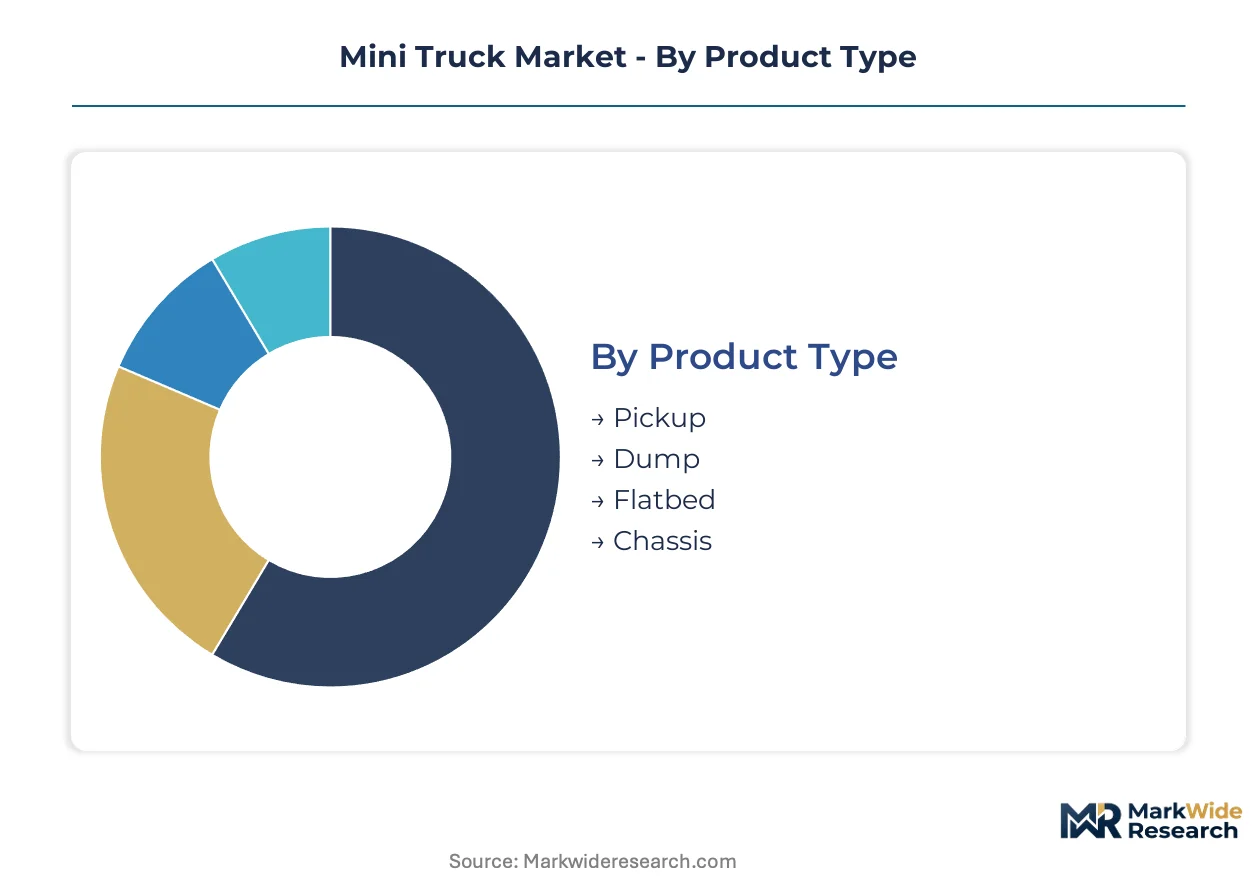
Mini truck segmentation reveals divergent engineering priorities across use cases. Product architecture, fuel system, and buyer economics each reshape competitive positioning in distinct ways.
Product Type:
Integration depth varies sharply—pickup and dump configurations serve standalone owner-operators, while chassis and flatbed variants embed into larger fleet systems requiring bodybuilder integration.
- Pickup:Enclosed or open cargo beds mounted on integrated ladder-frame architectures optimize for mixed-load versatility. Construction subcontractors in Indonesia's Greater Jakarta corridor favor these for equipment-and-material combined hauling under three-tonne GVW limits.
- Dump:Hydraulically actuated tipping mechanisms with reinforced bed floors handle abrasive aggregates. Vietnamese quarry operators around Hai Phong specify these for limestone transport where road width prohibits standard tipper trucks.
- Flatbed:Unrestricted load floors accommodate irregular dimensions via stake-side or drop-side configurations.
- Chassis:Cab-and-chassis units ship incomplete for third-party body installation—ambulance, refrigeration, or tanker upfitting.
Volume placements concentrate in Pickup; the faster expansion belongs to Chassis as fleet standardization spreads.
Application:
Cost tier stratification separates premium uptime-dependent operations from economy-grade seasonal deployment.
- Construction:Reinforced suspensions and high-torque diesel powertrains endure stop-start loading cycles. India's National Highways Authority contractor networks in Maharashtra deploy sub-one-tonne units for site-to-site material shuttles where full-size trucks face access restrictions.
- Delivery:Optimized turning radii and low-load-floor heights accelerate parcel handling. Last-mile e-commerce fleets in Bangkok's congestion-charged districts are electrifying these configurations for zero-emission zone compliance.
- Agriculture:Simple mechanical systems tolerate dust, moisture, and irregular maintenance intervals.
- Utilities:Upfit-ready electrical and hydraulic take-offs power aerial buckets or compressors.
Construction commands the largest installed base; Delivery is climbing the fastest as urban fulfillment density intensifies.
End User:
Customer type determines procurement channel and financing structure across the ownership spectrum.
- Small Businesses:Owner-operators purchasing one to three units through dealer floorplan financing or microfinance institutions. These buyers dominate India's tier-three city logistics networks where informal credit markets supplement formal banking.
- Government:Municipal corporations and public works departments tender for standardized fleet procurement with multi-year maintenance contracts. Indonesia's Ministry of Public Works specifies domestic-content-compliant vehicles for rural road maintenance crews.
- Contractors:Project-based rental and lease arrangements favor flexible term structures.
- Agricultural Firms:Cooperative purchasing pools aggregate demand for seasonal harvest logistics.
Small Businesses account for the highest unit placements; Government procurement is gaining share fastest as infrastructure stimulus expands.
Fuel Type:
Maturity gradients separate established propulsion from emerging platforms still scaling supply chains.
- Diesel:Compression-ignition engines with high-pressure common-rail injection deliver torque-rich performance for laden gradients. Agricultural heartlands in India's Punjab and Haryana retain diesel dominance due to refueling infrastructure maturity and cold-start reliability.
- Electric:Battery-electric platforms with lithium-iron-phosphate cell chemistry and liquid-cooled thermal management. China's MIIT new-energy-vehicle credit system accelerates OEM homologation for urban delivery variants serving Shenzhen and Chengdu low-emission zones.
- Gasoline:Port-fuel-injected or direct-injection spark-ignition engines serve price-sensitive markets.
- Hybrid:Parallel or series-parallel architectures combining downsized combustion with electric assist.
Diesel retains the deepest installed base; Electric represents the fastest-growing trajectory as battery cost curves flatten and urban access restrictions multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jakarta's logistics corridors anchor mini truck deployment density across Southeast Asia, with fleet operators navigating congestion-charged districts through compact electric configurations. Procurement concentrates in four national markets where regulatory frameworks and infrastructure constraints reshape vehicle specifications.
China
Shenzhen and Chengdu low-emission zones drive battery-electric homologation under MIIT new-energy-vehicle credit systems. GB standards for commercial EV safety compress certification timelines for multi-market platforms. Yangtze River Delta manufacturing clusters supply integrated cell-to-pack architectures to Indonesian and Vietnamese assemblers.
India
Punjab and Haryana agricultural heartlands retain diesel dominance for cold-start reliability and sparse charging infrastructure. BIS crash-test mandates and CEA electrification directives force platform redesigns for domestic compliance. Maharashtra contractor networks deploy sub-one-tonne units for National Highways Authority site shuttles.
Japan
METI kei-vehicle dimension rules preserve protected design envelopes lowering homologation costs for exportable compact architectures. Kanto and Kansai industrial corridors optimize kei-class regulatory frameworks for adjacent Asian market penetration. Domestic volume concentrates in last-mile delivery fleets serving Tokyo and Osaka congestion zones.
Indonesia
Jakarta-Bandung-Surabaya freight lanes under the national net-zero roadmap offer preferential toll access for electric mini truck deployment. Greater Jakarta construction subcontractors favor pickup configurations for equipment-and-material combined hauling under three-tonne GVW limits. Domestic-content compliance shapes Ministry of Public Works rural road maintenance tenders.
Vietnam
Mekong Delta farming cooperatives present unmet demand for sub-one-tonne haulers navigating narrow delta levees. Hai Phong quarry operators specify dump configurations for limestone transport where road width prohibits standard tipper trucks. Agricultural mechanization programs redirect procurement toward utility-grade durability specifications.
Mini Truck Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent platform strategies. The vendor base splits between integrated OEMs captive to chassis engineering and modular assemblers sourcing battery platforms from tier-one suppliers. Three archetypes dominate: kei-class regulatory optimizers, diesel-hybrid durability specialists, and battery-electric urban compliance leaders. Competitive moves center on strategic partnerships for charging infrastructure and geographic expansion through CKD assembly licensing.
Among kei-class specialists, Suzuki Motor Corporation and Daihatsu Motor occupy positions shaped by METI dimension rule optimization. Tata Motors exemplifies the integrated chassis engineering archetype dominating South Asian rural logistics. Mahindra & Mahindra anchors the diesel-hybrid development vector for unpaved-road export markets.
| Leading Market Players |
|---|
| FAW Jiefang |
| Mahindra & Mahindra |
| Ford Motor Company |
| Mitsubishi Motors |
| Daihatsu Motor |
| Toyota Motor Corporation |
| Suzuki Motor Corporation |
| Tata Motors |
| Hyundai Motor Company |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between BIS-compliant domestic platforms and GB-standard export variants splits both procurement economics and component sourcing footprints across the Mini Truck Market. Premium electrified architectures command value-based contracts tied to uptime guarantees, while bare-bones diesel haulers transact on spot-equivalent terms with minimal after-sales bundling.
Pricing Analysis
Per-kilometer outcome contracts now anchor premium fleet procurement in Indonesian logistics corridors and Vietnamese agricultural cooperatives. Price differentiation separates MIIT-certified electric platforms with preferential toll access from uncertified ICE alternatives facing congestion charges. Cost compression in the diesel tier intensifies as lithium-iron-phosphate cell costs decline and urban access restrictions multiply. Small-business owner-operators in India's tier-three cities exhibit acute price sensitivity, while government tenders with multi-year maintenance clauses absorb premium positioning.
Supply Chain Analysis
Freight cost volatility from Yangtze River Delta manufacturing clusters to Southeast Asian assembly plants compresses margin structures for non-integrated OEMs. Cell-to-pack architectures draw from China, South Korea, and Japan; high-torque diesel powertrains rest on Indian and Japanese engineering. Single-source vulnerability concentrates in cathode active material processing. Distribution runs through captive dealer networks for rural small-business segments and fleet management aggregators for urban delivery operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery cell capacity constraints prop pricing power for integrated cathode producers, sustaining margin structures despite downstream cost pressure.
For Market Incumbents: Deepen backward integration into lithium-iron-phosphate cell production to offset raw material volatility from East Asian processing clusters. Lock in long-term offtake agreements with Mekong Delta farming cooperatives before agricultural mechanization programs consolidate procurement. Prioritize BIS-GB dual certification investment to compress homologation timelines for multi-market platforms. For New Entrants and Emerging Players: Tier-two Indonesian construction subcontractors present unmet demand for sub-one-tonne pickup configurations with domestic-content compliance. Vietnamese quarry operators around Hai Phong require dump variants where road width excludes standard tippers. Pursue CKD assembly licensing with established chassis suppliers to bypass captive dealer network barriers. For Investors and Strategic Acquirers: Re-rating potential sits with modular battery-platform specialists given MIIT credit system acceleration and swap-station infrastructure rollout. Long-term viability favors tier-one suppliers with cell-to-pack thermal management capabilities and cross-OEM standardization traction. Monitor BIS electrification directive implementation pace as inflection indicator for domestic Indian platform investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-iron-phosphate cell allocation from Yangtze River Delta producers for Indonesian assembly. |
| Platform Standardization | Unifies cab-over-engine architectures across kei-class and sub-one-tonne GVW segments for export markets. |
| Charging Infrastructure Partnership | Deploys automated swap stations along Jakarta-Bandung-Surabaya freight lanes under net-zero roadmap. |
| Geographic Manufacturing Footprint | Establishes CKD assembly in Vietnam to satisfy domestic-content requirements for Ministry of Public Works tenders. |
| Software-Defined Vehicle Investment | Integrates battery management system firmware with fleet management aggregator platforms for per-kilometer contracts. |
Study Parameters
Independent corroboration across OEM platform engineers, Tier 1 supplier procurement leads, and fleet management aggregator operators underwrites the qualitative findings. Secondary validation draws from MIIT new-energy-vehicle credit disclosures, BIS crash-test homologation records, and ASEAN automotive trade customs data. Bottom-up production estimates triangulate against top-down logistics fleet deployment surveys across Indonesian and Vietnamese corridors.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon. Segmentation modeling incorporates product architecture, fuel type, end-user procurement channel, and regional regulatory cluster dimensions. CAGRs derive from fitted growth curves applied to electrification penetration rates and agricultural mechanization program budgets.
Revisions become necessary when BIS-GB regulatory divergence widens, lithium-ion cell supply concentrates further, or rural charging infrastructure deployment accelerates beyond baseline assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
France Light Commercial Vehicles Market
Commercial Vehicles
Europe Light Commercial Vehicle Trailer Market
Commercial Vehicles
Robotic Haul Trucks Market
Commercial Vehicles
Electric Garbage Van Market
Commercial Vehicles
Farm Trucks Market
Commercial Vehicles
Used Truck Market
Commercial Vehicles
Compact Utility Vehicles Market
Commercial Vehicles
Electric Drive Mining Truck Market
Commercial Vehicles
Asia-Pacific Commercial Vehicles Market
Commercial Vehicles
Canada Commercial Vehicles Market
Commercial Vehicles
Japan Commercial Vehicles Market
Commercial Vehicles
Electric Truck Market
Commercial Vehicles
Iran Vehicles Market
Commercial Vehicles
ASEAN Commercial Vehicles Market
Commercial Vehicles
Canada Refrigerated Vehicles Market
Commercial Vehicles
Flatbed Semi-Trailer Market