
 Asia Pacific Road Freight Transport Market | 2026-2036
Asia Pacific Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Road Freight Transport Market Outlook
Last-mile distribution networks across ASEAN are rewriting contract logistics economics. DHL Group leverages its multimodal hubs to anchor cross-border lane density between Thailand and Vietnam. CJ Logistics Corporation sustains refrigerated dominance across South Korea's grocery e-commerce sector. SF Express competes through proprietary sorting infrastructure that controls parcel velocity in China's tier-two cities.
Road freight transport encompasses the movement of goods via motorized vehicles over paved road infrastructure, typically operating at gross vehicle weights from 3.5 tonnes to 40-plus tonnes depending on axle configuration and national permit frameworks. Full Truck Load services dominate margin pools on volume corridors, while Less Than Truck Load segments attract fragmented SME demand across Indonesia's archipelago. Refrigerated Trucks within vehicle classifications command premium positioning as cold-chain compliance tightens around Australian perishable exports and Japanese pharmaceutical distribution.
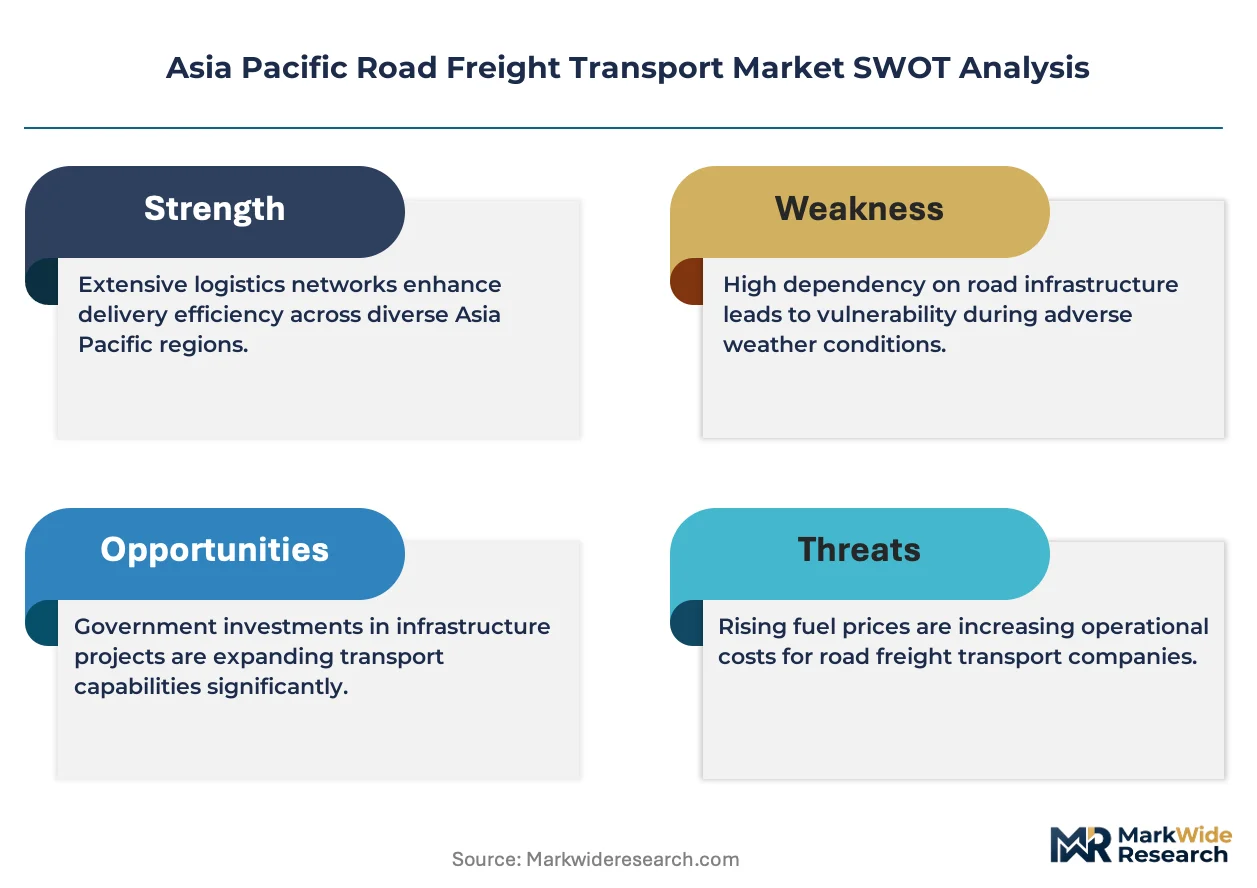
Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces driver hour limits that reshape fleet sizing, while Australia's National Heavy Vehicle Regulator mandates performance-based standards for high-productivity vehicles. China's MIIT pushes new energy truck quotas through subsidy taper mechanisms. Stakeholders must weigh electrification capex against regulatory compliance timelines and route-specific charging viability.
Market Dynamics
E-commerce fulfillment networks across Southeast Asia are pulling capacity into dedicated parcel lanes, while India's axle-load norms under the Ministry of Road Transport and Highways force fleet upgrades toward heavier configurations. This dual pressure is compressing contract structures and reshaping asset deployment across the region.
Growth Catalysts
- Axle-load norm revisions:India's Ministry of Road Transport and Highways mandates heavier configurations, accelerating fleet turnover and expanding per-vehicle payload economics on national highways.
- Cold-chain compliance tightening:Australian perishable exports and Japanese pharmaceutical distribution drive refrigerated truck premium positioning and specialized lane development.
- Manufacturing corridor density:Vietnam's Hanoi-to-Ho Chi Minh City axis concentrates demand, attracting dedicated fleet investment and cross-border consolidation services.
Market Restraints
- Driver hour enforcement:Japan's Ministry of Land, Infrastructure, Transport and Tourism imposes strict limits that inflate fleet sizing requirements and compress asset utilization rates.
- Electrification capex burden:China's MIIT new energy truck quotas, delivered through subsidy taper mechanisms, force premature battery-electric adoption before charging infrastructure matures on long-haul corridors.
- Archipelago fragmentation:Indonesia's island geography necessitates multimodal handoffs, inflating transit times and complicating full-truckload economics across the Nusantara chain.
Strategic Opportunities
- Tier-two city parcel velocity:China's inland urban clusters present underserved demand for proprietary sorting infrastructure and controlled last-mile networks.
- Cross-border lane density:Thailand-Vietnam corridors offer white space for multimodal hub anchoring and bonded warehousing integration.
- Refrigerated grocery e-commerce:South Korea's cold-chain standards create exportable compliance frameworks for ASEAN temperature-controlled distribution expansion.
Industry Challenges
- Charging infrastructure mismatch:Route-specific charging viability gaps strand battery-electric assets on corridors where China's MIIT mandates apply but grid capacity lags.
- Performance-based standard compliance:Australia's National Heavy Vehicle Regulator mandates complex vehicle approval pathways that extend procurement cycles for high-productivity configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Road Freight Transport Market |
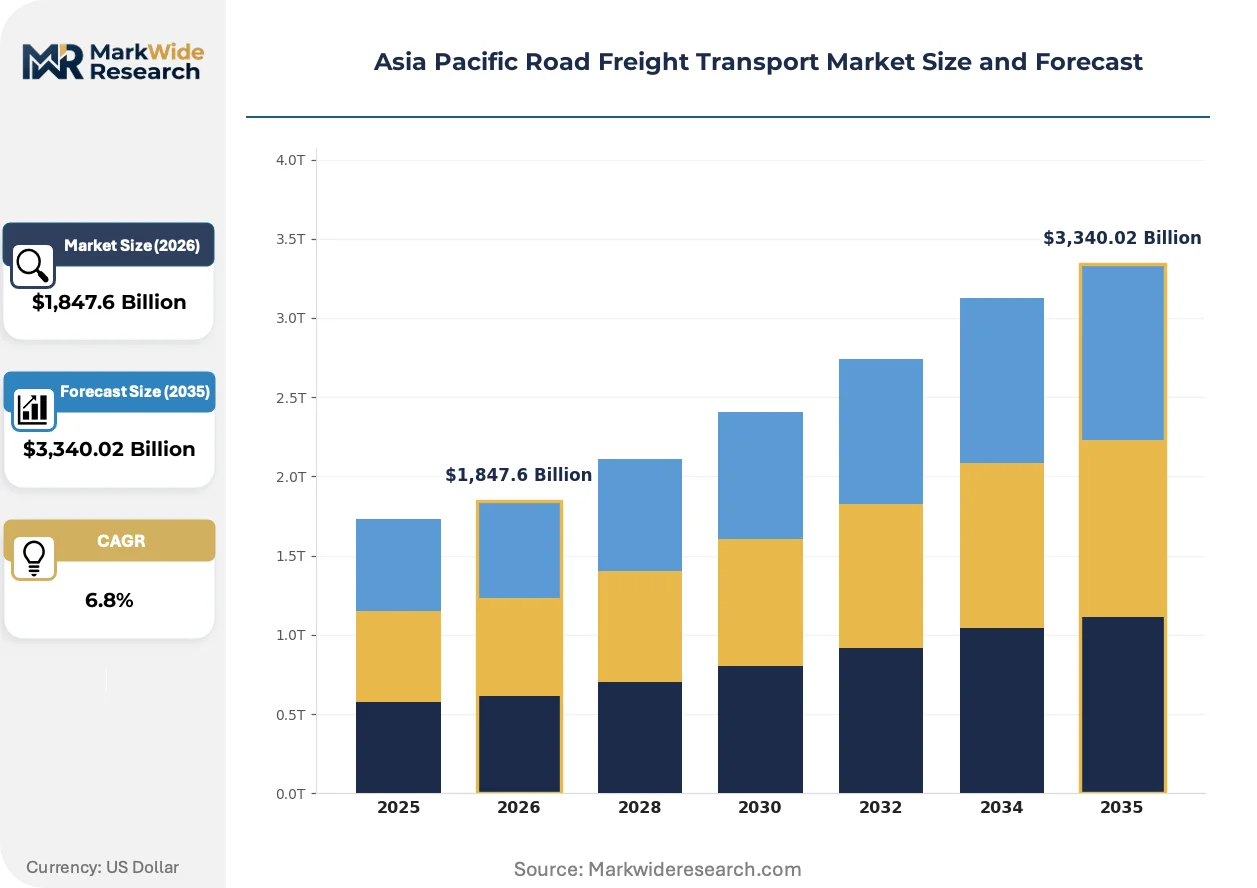
| Market Size in 2026 | $1,847.6 Billion |
| Market Size in 2035 | $3,340.02 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full Truck Load, Less Than Truck Load, Intermodal, Specialized Transport Vehicle Type: Heavy-Duty Trucks, Light-Duty Trucks, Refrigerated Trucks, Tanker Trucks End User: E-Commerce, Retail, Manufacturing, Pharmaceuticals Route Type: Urban Routes, Highway Routes, Regional Routes, Long-Distance Routes |
| Companies Covered | Kintetsu Group Holdings Co., Ltd., Sinotrans Limited, DHL Group, CJ Logistics Corporation, SF Express, Nippon Express Holdings, Toll Group, Kuehne + Nagel, CMA CGM Group (including CEVA Logistics), Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Road Freight Transport Market Strategic Shifts
Digital freight matching platforms and telematics integration are compressing traditional broker margins while enabling real-time capacity optimization across fragmented owner-operator networks.
Telematics-driven predictive maintenance is virtualizing traditional fleet management by embedding sensor networks in engine and brake systems. Large fleet operators in Australia's mining corridors and Japan's just-in-time automotive supply chains are adopting these systems at accelerating pace. This technology is virtualizing the role of dispatch centers, compressing headcount while raising vehicle availability through algorithmic intervention before mechanical failure.
China's MIIT subsidy taper mechanisms for new energy commercial vehicles are forcing premature technology transitions. The industrial consequence is stranded asset risk for fleets that adopted early-generation battery-electric trucks before charging density matured. Long-haul operators running Shanghai-Beijing corridors are responding by leasing rather than purchasing, transferring technology obsolescence risk to lessors.
Shipper procurement is consolidating around contracted lane density rather than spot-market flexibility. Large retailers in Vietnam's manufacturing corridor are displacing transactional broker relationships with multi-year dedicated fleet agreements. This pattern is most visible in electronics and automotive component verticals where inventory velocity penalties exceed freight cost differentials.
Asia Pacific Road Freight Transport Market Segmentation
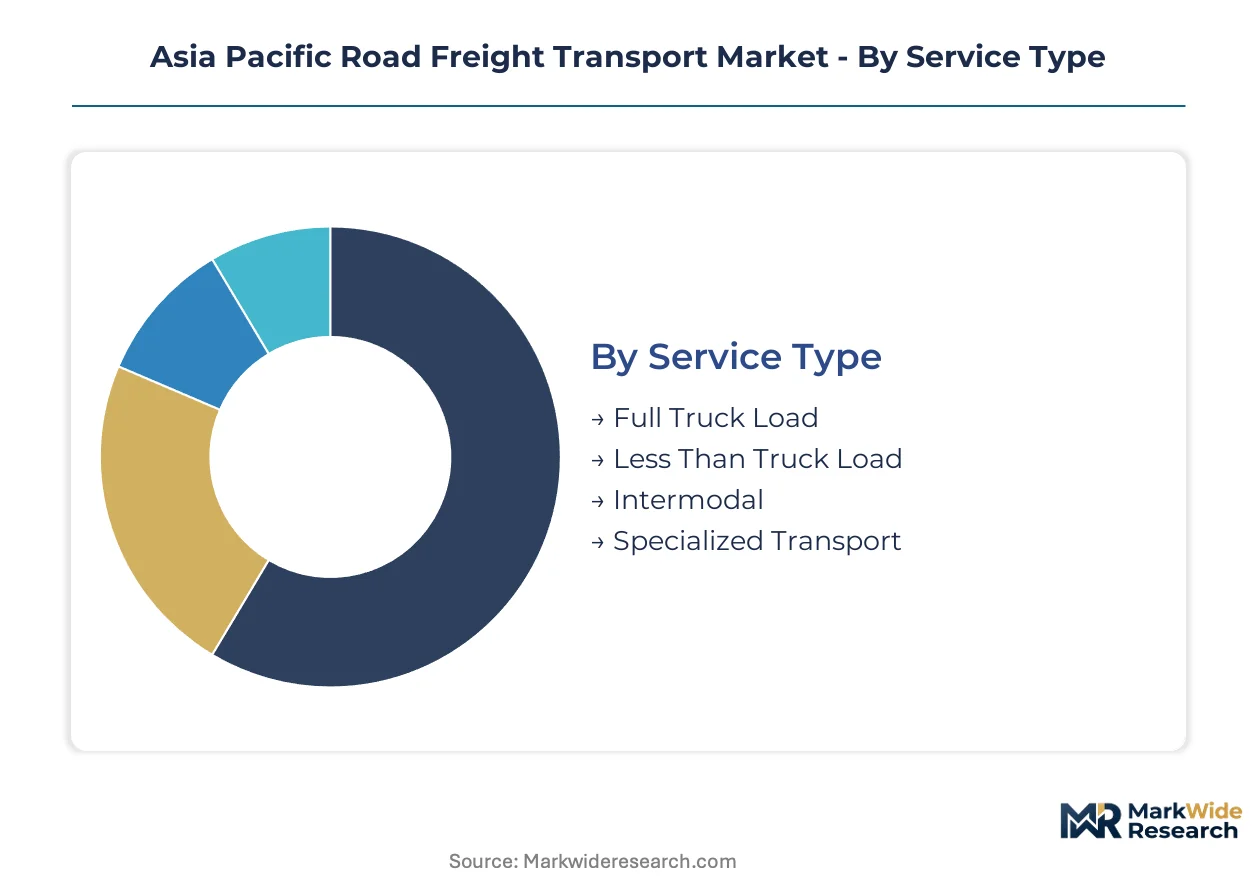
Road freight transport across Asia Pacific fragments along operational dimensions that determine asset deployment, margin capture, and regulatory exposure. Service configuration, vehicle specification, end-use concentration, and route economics each create distinct competitive arenas with diverging investment requirements.
Service Type:
Use-case spectrum spans dedicated capacity contracts through fragmented parcel aggregation to multimodal orchestration and niche compliance services.
- Full Truck Load:Dedicated vehicle capacity moving single-shipper cargo from origin to destination without intermediate handling. Electronics manufacturers along Vietnam's Hanoi-Ho Chi Minh City corridor anchor demand, with inventory velocity penalties exceeding freight cost differentials driving contract consolidation.
- Less Than Truck Load:Consolidated shipments from multiple shippers sharing trailer space through hub-and-spoke terminal networks. Indonesia's archipelago geography inflates transit times and complicates unit economics across the Nusantara chain, fragmenting provider landscapes.
- Intermodal:Sequenced road-rail or road-sea movements optimizing cost over pure trucking for non-urgent cargo. Thailand-Vietnam corridors leverage bonded warehousing integration to anchor cross-border lane density.
- Specialized Transport:Oversized, hazardous, or temperature-critical cargo requiring permit frameworks and equipment certification. Australian mining corridors and Japanese automotive supply chains concentrate demand for performance-based standard compliance.
The dominant share belongs to Full Truck Load, while Intermodal is closing the gap fastest on corridor-specific cost optimization.
Vehicle Type:
Cost tier stratification separates heavy payload configurations from light urban delivery through premium cold-chain and bulk liquid specializations.
- Heavy-Duty Trucks:Gross vehicle weights exceeding 16 tonnes configured for maximum payload on national highway networks. India's Ministry of Road Transport and Highways axle-load norm revisions accelerate fleet turnover toward heavier configurations.
- Light-Duty Trucks:Vehicles under 3.5 tonnes gross weight optimized for urban access restrictions and last-mile density. China's tier-two city parcel velocity demands strain proprietary sorting infrastructure capacity.
- Refrigerated Trucks:Insulated bodies with mechanical refrigeration units maintaining temperature-controlled environments. Australian perishable exports and Japanese pharmaceutical distribution drive premium positioning and specialized lane development.
- Tanker Trucks:Cylindrical vessels designed for liquid bulk transport including chemicals, fuels, and food-grade commodities. South Korea's industrial chemical corridors concentrate specialized fleet deployment.
Heavy-Duty Trucks retain volume leadership, though Refrigerated Trucks command the steepest expansion trajectory on cold-chain compliance tightening.
End User:
Customer type determines service level requirements, technology adoption timing, and contract structure preferences across vertical demand pools.
- E-Commerce:Parcel-centric fulfillment networks demanding velocity guarantees and real-time visibility. Southeast Asia's fulfillment networks pull capacity into dedicated lanes with multi-year dedicated fleet agreements displacing transactional brokers.
- Retail:Replenishment-driven distribution with seasonal volatility and store-door delivery requirements. South Korea's grocery e-commerce sector sustains refrigerated dominance through CJ Logistics Corporation's cold-chain infrastructure.
- Manufacturing:Just-in-time component flows with severe inventory velocity penalties for disruption. Japan's Ministry of Land, Infrastructure, Transport and Tourism driver hour limits reshape fleet sizing for automotive supply chains.
- Pharmaceuticals:GDP-compliant distribution with audit trails, temperature mapping, and serialization requirements. Japanese pharmaceutical distribution networks command specialized refrigerated truck premium positioning.
E-Commerce commands the dominant share, while Pharmaceuticals is expanding most quickly on regulatory compliance intensification.
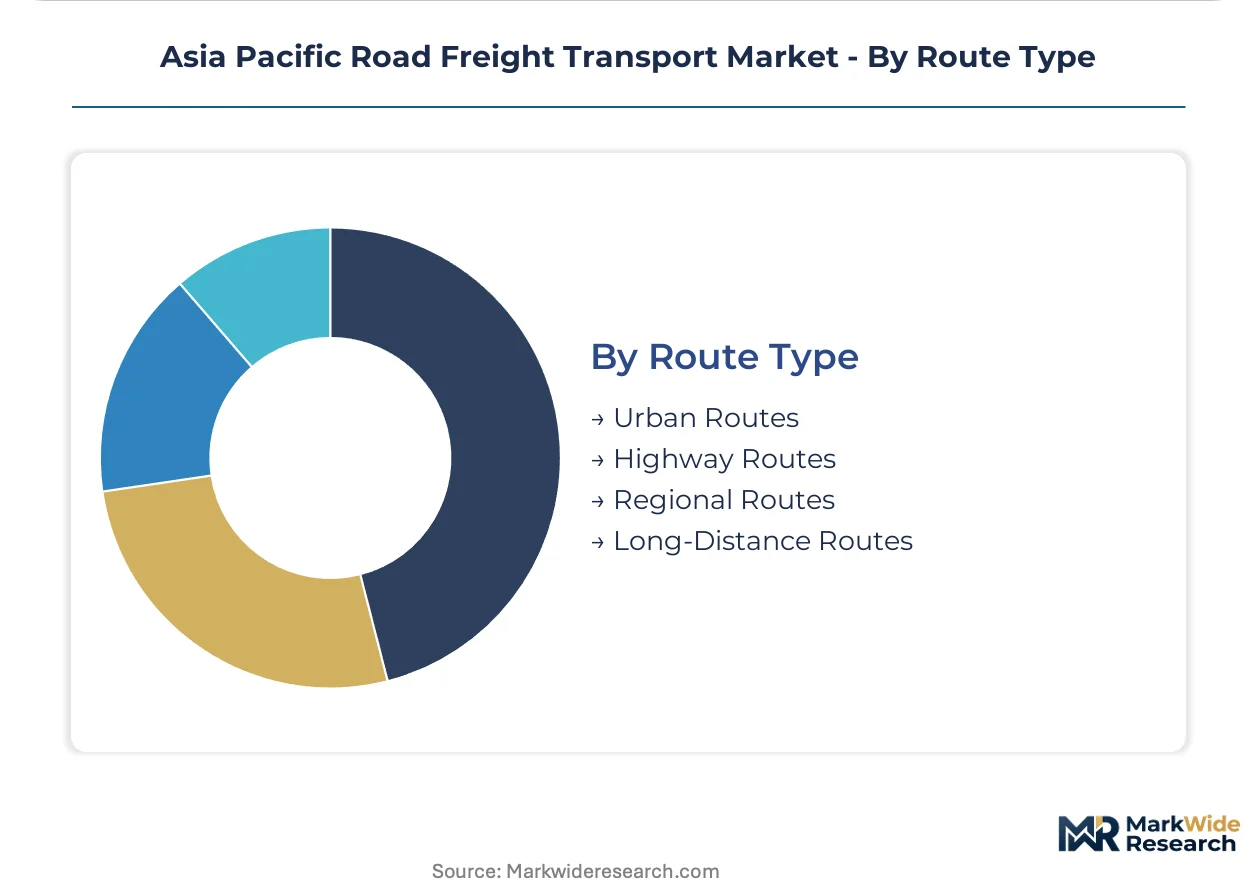
Route Type:
Geography and distance dictate vehicle specification, driver regime compliance, and infrastructure dependency across operational environments.
- Urban Routes:Last-mile delivery within metropolitan boundaries facing congestion, access restrictions, and parking scarcity. China's MIIT new energy truck quotas force premature battery-electric adoption before charging infrastructure matures.
- Highway Routes:Intercity movement on controlled-access roads optimizing speed and fuel efficiency. India's national highways accommodate heavier axle-load configurations under revised norms.
- Regional Routes:Multi-provincial or inter-state corridors connecting economic clusters without full national span. Vietnam's manufacturing corridor attracts dedicated fleet investment and cross-border consolidation services.
- Long-Distance Routes:Transcontinental spans exceeding 1,000 kilometers requiring driver rotation and fuel logistics. China's Shanghai-Beijing corridors see leasing preference over ownership to transfer technology obsolescence risk.
Highway Routes hold the dominant share, while Urban Routes are gaining share fastest on e-commerce last-mile density requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Laem Chabang Port corridor anchors Thailand's freight distribution into the Greater Mekong subregion, while Singapore's Tuas megaport integrates Malaysian and Indonesian hinterland traffic through dedicated road-rail feeders.
China
E-commerce fulfillment networks in tier-two cities strain proprietary sorting infrastructure capacity. MIIT's new energy truck quotas force premature battery-electric adoption before charging density matures on long-haul corridors. The Yangtze River Delta manufacturing cluster sees leasing preference over ownership to transfer technology obsolescence risk.
India
Electronics manufacturers anchor demand along the Delhi-Mumbai Industrial Corridor. The Ministry of Road Transport and Highways mandates heavier axle-load configurations, accelerating fleet turnover toward 40-tonne configurations. Gujarat's Mundra Port hinterland attracts dedicated fleet investment for containerized exports.
Japan
Automotive just-in-time supply chains concentrate demand in the Chubu-Nagoya manufacturing belt. The Ministry of Land, Infrastructure, Transport and Tourism enforces strict driver hour limits that reshape fleet sizing requirements. Kanto's Tokyo-Osaka highway corridor compresses asset utilization rates through mandatory rest protocols.
Vietnam
Electronics and textile exporters drive volume along the Hanoi-to-Ho Chi Minh City manufacturing axis. Cross-border bonded warehousing integration with Thailand enables multimodal hub anchoring. The northern Bac Ninh industrial zone attracts dedicated parcel lane capacity from regional logistics operators.
Australia
Mining corridor operators adopt telematics-driven predictive maintenance across Western Australia's Pilbara region. The National Heavy Vehicle Regulator mandates performance-based standards that extend procurement cycles for high-productivity configurations. Melbourne's Port of Hastings hinterland concentrates refrigerated demand for perishable exports.
Asia Pacific Road Freight Transport Market Competitive Environment
On the supply side, the industry is consolidating around integrated multimodal operators with proprietary infrastructure assets. Asset-heavy players with dedicated fleet networks command premium positioning on contracted lane density, while digital-native platforms compress traditional broker margins through real-time matching. Three archetypes dominate: integrated logistics conglomerates with cross-border hub networks, regional specialists with cold-chain certification depth, and technology-enabled parcel operators with sorting infrastructure control. Competitive moves center on multi-year dedicated fleet agreements displacing transactional relationships, and strategic leasing structures transferring electrification obsolescence risk.
Within the integrated logistics tier, DHL Group and Kuehne + Nagel represent the multinational hub-and-spoke archetype with bonded warehousing integration across ASEAN corridors. CJ Logistics Corporation occupies a specialist position exemplifying refrigerated dominance through compliance depth in temperature-controlled distribution. SF Express anchors the technology-enabled vector with proprietary sorting infrastructure controlling parcel velocity in China's inland urban clusters.
| Leading Market Players |
|---|
| Kintetsu Group Holdings Co., Ltd. |
| Sinotrans Limited |
| DHL Group |
| CJ Logistics Corporation |
| SF Express |
| Nippon Express Holdings |
| Toll Group |
| Kuehne + Nagel |
| CMA CGM Group (including CEVA Logistics) |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on Chinese battery-electric chassis suppliers determines both pricing tier spreads and supply chain shape across Asia Pacific road freight networks. MIIT subsidy taper mechanisms force premature fleet electrification before charging density matures, compressing margin structures and fragmenting procurement strategies between leasing and ownership models.
Pricing Analysis
Volume-discount tiering structures dominate contract negotiations between electronics manufacturers and dedicated fleet operators along Vietnam's manufacturing corridor. Three-tier pricing separates premium refrigerated compliance from standard dry freight and economy spot-market capacity, with cold-chain certification commanding substantial spreads. Cost compression in economy tiers intensifies as digital freight platforms aggregate fragmented owner-operator supply. SME shippers across Indonesia's archipelago exhibit highest price sensitivity, while pharmaceutical distributors in Japan prioritize compliance guarantees over rate minimization.
Supply Chain Analysis
Upstream feedstock concentration in Chinese steel and South Korean battery cell production anchors chassis manufacturing costs across the region. Vehicle assembly draws heavily from Japanese precision components, Thai axle fabrication, and domestic Indian bodywork. Single-source vulnerability around lithium-ion cell supply creates exposure to commodity volatility and tariff escalation. Distribution runs through bonded warehousing hubs at Laem Chabang and Singapore's Tuas megaport, with final-mile handoffs to national carrier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific road freight market sits in a cyclical recovery phase driven by inventory restocking across ASEAN manufacturing corridors. E-commerce fulfillment density and cross-border lane consolidation are accelerating contract renewal cycles.
For Market Incumbents: Insulate dedicated fleet agreements from digital platform erosion by embedding multi-year refrigerated compliance contracts with Japanese pharmaceutical distributors. Deepen backward integration into proprietary charging infrastructure along China's Shanghai-Beijing corridor to offset MIIT mandate risks. Anchor cross-border hub density through Thailand-Vietnam bonded warehousing integration.
For New Entrants and Emerging Players: Geographic underpenetration in Indonesia's tier-two island markets presents white-space opportunity for intermodal consolidation services. Target Australia's mining corridor predictive maintenance segment where telematics adoption lags fleet scale. Pursue asset-light leasing models that transfer technology obsolescence risk to balance sheets of established financial institutions.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors cold-chain specialists with GDP certification depth. Long-term viability over a five-to-ten-year window rests on regulatory compliance capabilities rather than pure scale. Target acquisition archetypes include refrigerated fleet operators with Japanese pharmaceutical network access. Watch driver hour enforcement tightening across Japan and Australia as the signal for fleet sizing inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerated Fleet Expansion | Cold-chain compliance tightening around Australian perishable exports commands premium positioning. |
| Cross-Border Hub Integration | Thailand-Vietnam bonded warehousing anchors multimodal lane density for electronics manufacturers. |
| Telematics Platform Deployment | Predictive maintenance virtualization compresses dispatch headcount across Australia's mining corridors. |
| Electrification Leasing Structures | Technology obsolescence risk transfer enables MIIT quota compliance without stranded asset exposure. |
| Last-Mile Sorting Infrastructure | Proprietary parcel velocity control captures tier-two city demand in China's inland urban clusters. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade databases, national transport ministry filings, and fleet operator registration records. Interviews with fleet procurement directors, logistics terminal managers, cold-chain compliance officers, and OEM chassis sales executives informed demand-side validation. Top-down market sizing from macroeconomic freight tonnage indicators was cross-checked against bottom-up aggregation of disclosed fleet capacities and contract values.
Forecast inputs incorporate service type segmentation, vehicle specification tiers, end-use vertical concentration, and route economics across the projection horizon. Modeled dimensions span Full Truck Load contract structures, refrigerated compliance requirements, and e-commerce parcel velocity demands. CAGRs were derived from trend extrapolation of corridor-specific lane density growth, adjusted for regulatory mandate acceleration and infrastructure deployment timelines.
The forecast holds incumbent behavior within observed patterns; aggressive electrification capex deployment by state-backed logistics conglomerates would shift outcomes substantially. Cross-checking against national highway freight tonnage statistics and bonded warehouse throughput data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Brazil Road Freight Transport Market
Transportation & Logistics
Australia Road Freight Transport Market
Transportation & Logistics
France Road Freight Transport Market
Transportation & Logistics
Middle-East and North Africa Taxi Market
Transportation & Logistics
US Reverse Logistics Market
Transportation & Logistics
Cold Chain Vehicles Market
Transportation & Logistics
Japan Cold Chain Logistics Market
Transportation & Logistics
Global Fourth Party Logistics Market
Transportation & Logistics
China Road Freight Transport Market
Transportation & Logistics
ASEAN Road Freight Transport Market
Transportation & Logistics
Colombia Road Freight Transport Market
Transportation & Logistics
United States Retail Reverse Logistics Market
Transportation & Logistics
Czech Republic Road Freight Transport Market
Transportation & Logistics
Mexico Cold Chain Logistics Market
Transportation & Logistics
Rail Asset Management Market
Transportation & Logistics
Thailand Road Freight Transport Market