
 Africa Cross Border Road Freight Transport Market | 2026-2036
Africa Cross Border Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Cross Border Road Freight Transport Market Outlook
Modular fleet configuration is hardening as the dominant procurement pattern, with buyers unbundling vehicle ownership from logistics management to access flexible capacity pools. DSV South Africa leverages integrated cross-border customs brokerage to sustain throughput across the Beitbridge corridor. Bidvest Freight anchors its position through specialized perishable cold-chain units serving retail distribution networks. Super Group competes via asset-light subcontractor networks that extend reach into secondary SADC routes without direct fleet investment.
Africa cross border road freight transport encompasses the movement of goods by road between sovereign African states, typically involving heavy-duty trucks with axle load limits ranging from 8 to 12 tonnes per axle depending on corridor infrastructure class, operating under bilateral or multilateral transit agreements. Its primary commercial purpose is to connect landlocked production zones to coastal port gateways, with cargo types spanning dry bulk commodities, temperature-sensitive agricultural products, and oversized mining equipment requiring specialized low-bed trailers. Full Truck Load services dominate revenue pools on major mineral export corridors where single-commodity volumes justify dedicated vehicle deployment, while Less Than Truck Load offerings capture margin in fragmented manufacturing supply chains linking South African industrial hubs to neighboring consumer markets. Intermodal segments incorporating rail-truck handoffs at Maputo and Dar es Salaam port terminals are expanding fastest as congestion at pure road border posts escalates transit delays.
The African Continental Free Trade Area Secretariat coordinates tariff-phase implementation that reshapes cargo routing decisions across member states, while national revenue authorities in Zambia, Zimbabwe, and Mozambique enforce axle-load compliance through weighbridge enforcement networks that directly filter fleet specification demand. SADC Protocol on Transport, Communications and Meteorology standards govern cross-border operator licensing, creating compliance cost differentials that influence carrier market entry decisions. Stakeholders must monitor AfCFTA dispute resolution mechanisms and emerging green freight corridor pilots to anticipate regulatory-driven fleet renewal cycles and corridor prioritization shifts.
Market Dynamics
Modular fleet unbundling is compressing asset ownership cycles across Southern African corridors, as logistics buyers separate vehicle capital from operational control to access flexible capacity pools during volatile commodity export windows.
Growth Catalysts
- AfCFTA Protocol:The African Continental Free Trade Area Secretariat coordinates tariff-phase implementation that streamlines customs harmonization across member states, reducing border dwell times on major mineral export corridors.
- Mining Equipment Procurement:Heavy machinery transport demand from copper and coal extraction operations is expanding across Zambian and Zimbabwean corridors, requiring specialized low-bed trailer deployment.
- Intermodal Rail-Truck Handoffs:Port terminals at Maputo and Dar es Salaam are expanding integrated transfer facilities, accelerating cargo velocity as pure road border congestion escalates.
Market Restraints
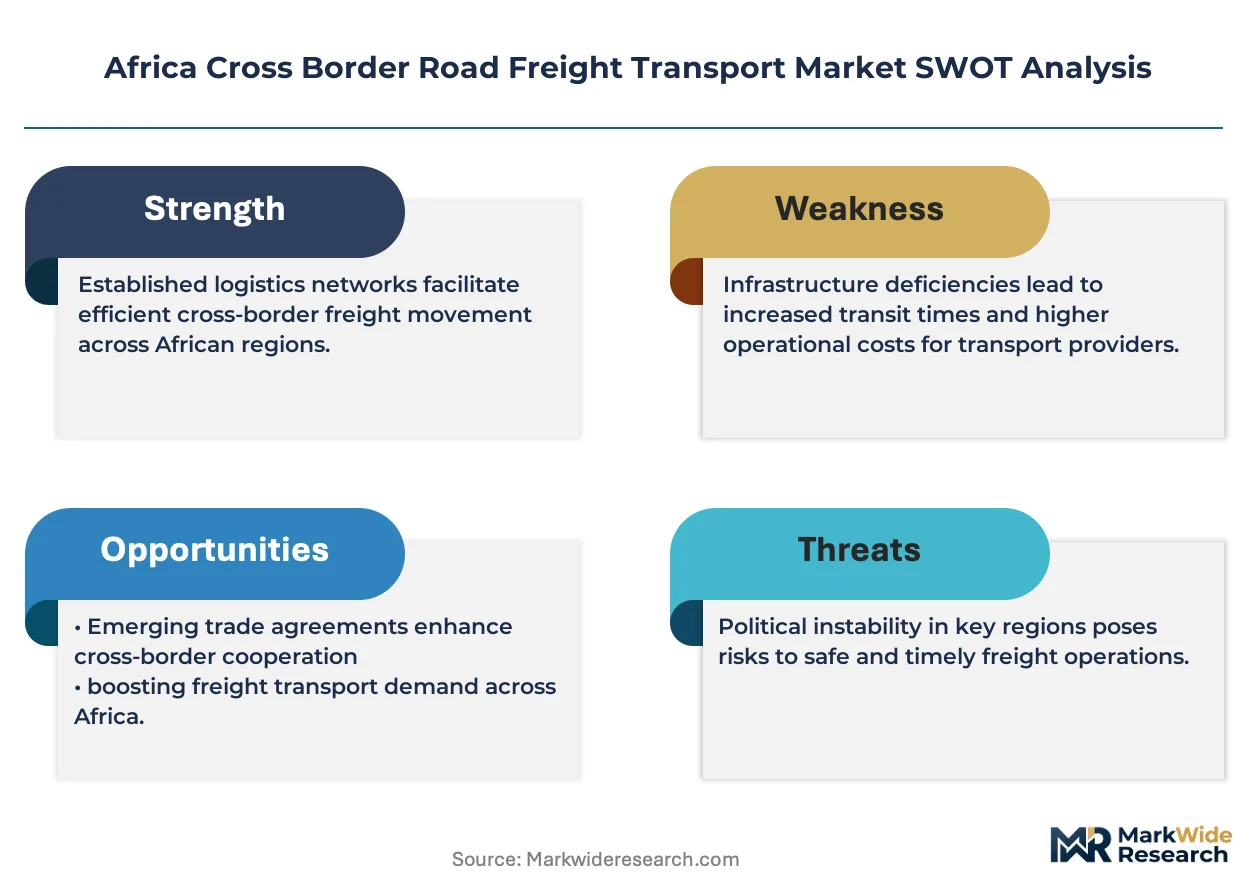
- Fuel Price Volatility:Diesel cost fluctuations constitute the largest variable in operating cost structures, squeezing margins on long-haul routes between Johannesburg and Lusaka.
- Weighbridge Enforcement Networks:National revenue authorities in Zambia, Zimbabwe, and Mozambique impose axle-load compliance costs that filter fleet specifications and raise barrier-to-entry for smaller carriers.
- Rail Freight Substitution:Rehabilitation of the Benguela railway corridor and Tazara line is capturing bulk commodity volumes that previously moved exclusively by road.
Strategic Opportunities
- Green Freight Corridor Pilots:Emerging low-emission route designations in South Africa and Botswana will mandate fleet renewal cycles favoring LNG and electric drivetrain adoption.
- Cold-Chain Perishables:Temperature-controlled units serving retail distribution networks remain underpenetrated in Malawi and Tanzania, where post-harvest losses exceed regional benchmarks.
- Digital Freight Matching:Platform-based load aggregation is converging with telematics penetration to enable real-time capacity optimization across fragmented subcontractor networks.
Industry Challenges
- Customs Brokerage Talent Scarcity:Cross-border documentation expertise is concentrating among a shrinking pool of accredited agents, creating bottlenecks at Beitbridge and Kazungula posts.
- Legacy Fleet Integration:Older vehicles lacking GPS and electronic logging device compatibility face exclusion from major shipper preferred-carrier programs, forcing premature retirement decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Cross Border Road Freight Transport Market |
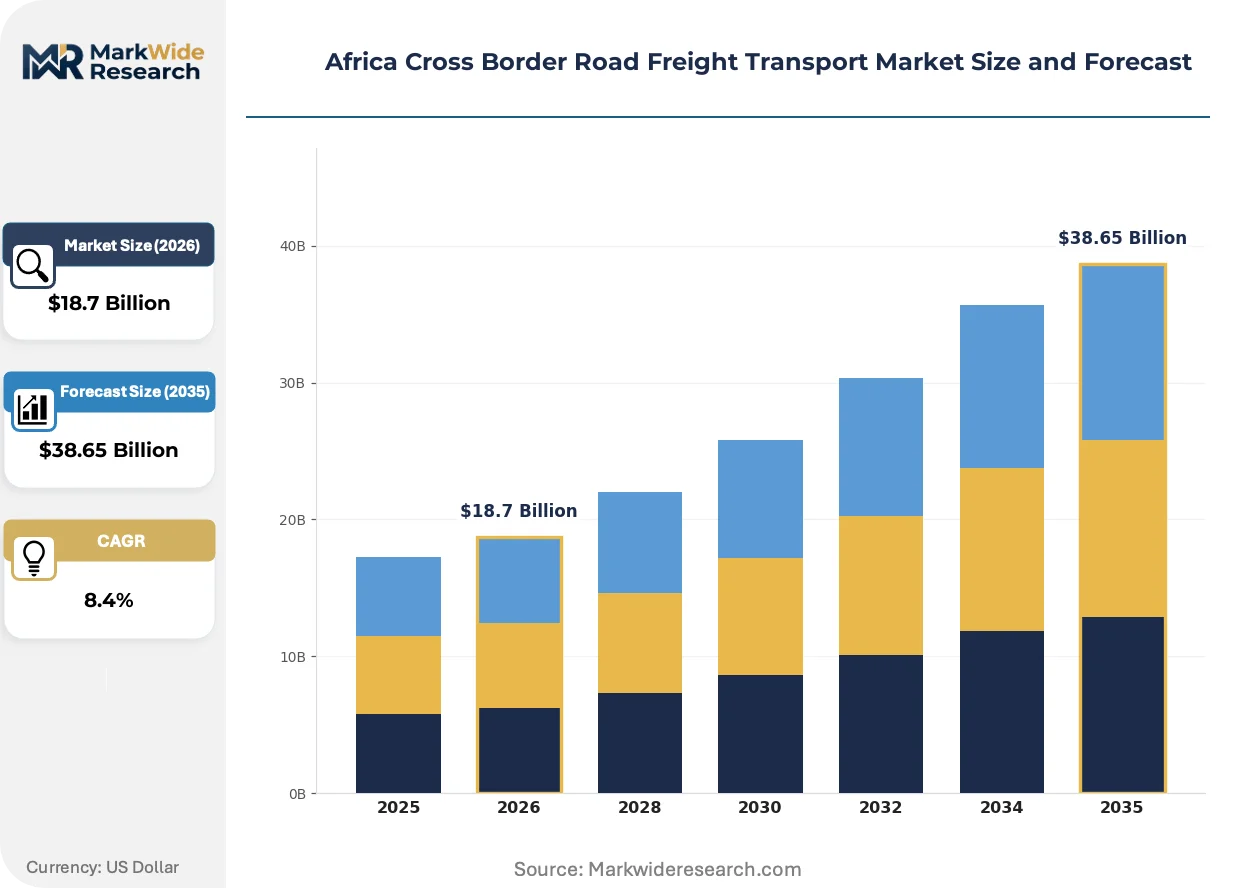
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Trucks, Trailers, Vans, Buses Service Type: Full Truck Load, Less Than Truck Load, Intermodal, Express Cargo Type: Dry Goods, Perishables, Hazardous Materials, Heavy Machinery Delivery Model: Scheduled, On-Demand, Contract, Ad Hoc |
| Companies Covered | CEVA Logistics, Bidvest Freight (Pty) Ltd, DSV South Africa (Pty) Ltd, Value Logistics Ltd, DPD Laser Express Logistics (Pty) Ltd, DHL Freight Forwarding, Cargo Carriers (Pty) Ltd, Super Group Ltd, Unitrans Supply Chain Solutions (Pty) Ltd, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Cross Border Road Freight Transport Market Strategic Shifts
Telematics penetration is reconfiguring how cargo visibility contracts are priced, as real-time tracking becomes a baseline procurement requirement rather than a premium service tier across SADC logistics procurement.
Blockchain-enabled documentation is converging with mobile customs platforms to create immutable cargo records that accelerate clearance at congested border posts. Large mining houses and agricultural exporters in South Africa and Zambia are piloting these systems to reduce demurrage exposure. The technology is converging with existing weighbridge data streams to enable pre-arrival risk scoring that diverts low-risk shipments to green lanes.
SADC Protocol on Transport, Communications and Meteorology standards are tightening cross-border operator licensing requirements, raising compliance cost differentials that influence carrier market entry decisions. The harmonization mandates are forcing fleet investments in standardized safety equipment and driver certification programs. Zimbabwean and Mozambican operators face the steepest adaptation curves due to legacy regulatory fragmentation.
Shippers are unbundling long-term dedicated fleet contracts in favor of spot-market capacity pools accessed through digital freight platforms. This pattern is most visible among fast-moving consumer goods distributors serving secondary cities in Botswana and Namibia. The shift is compressing carrier revenue predictability while expanding market access for asset-light subcontractors operating across the Durban-Johannesburg-Maputo triangle.
Africa Cross Border Road Freight Transport Market Segmentation
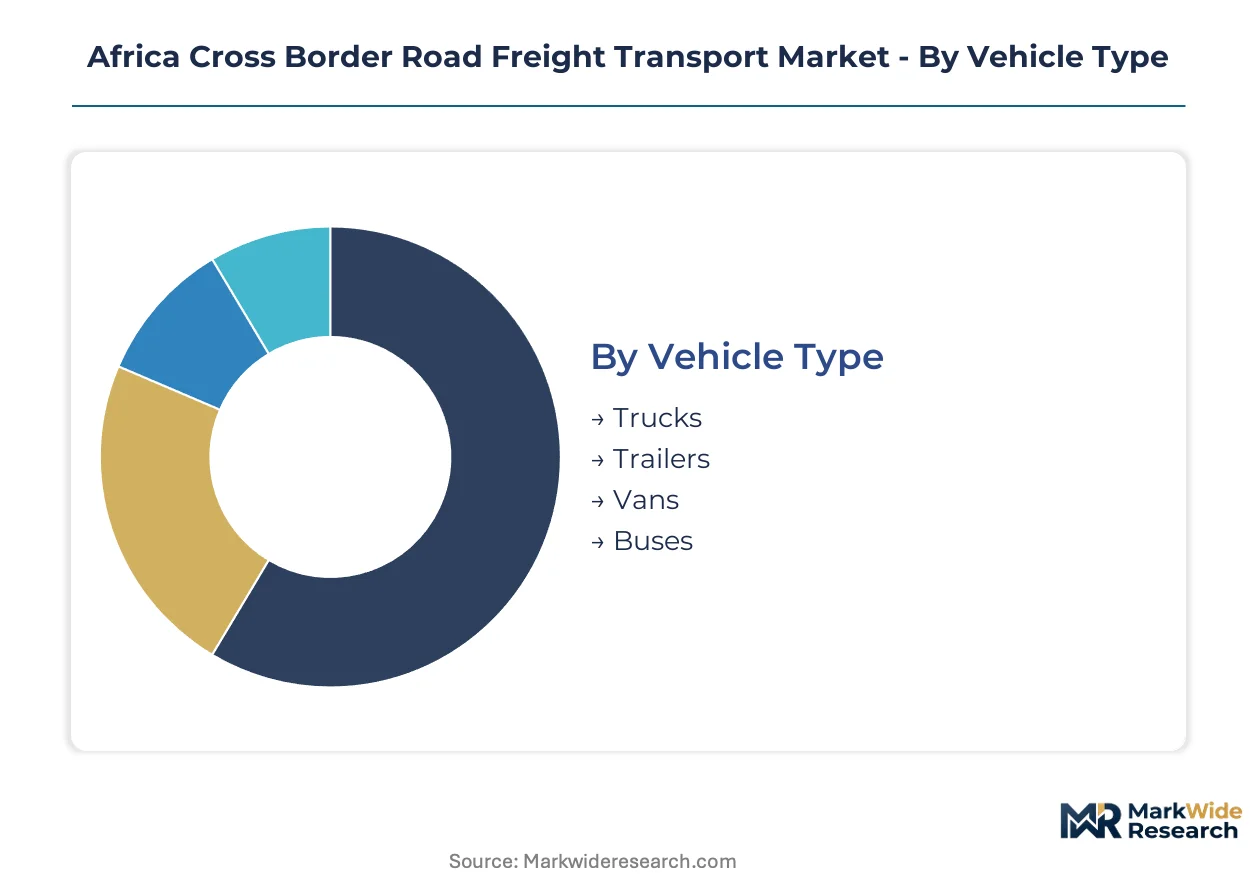
Segmentation in African cross-border road freight reveals how procurement patterns split between asset-heavy mineral corridors and fragmented consumer distribution networks. Vehicle specification, service configuration, and cargo handling requirements diverge sharply across the Durban-Johannesburg-Maputo triangle versus secondary SADC routes.
Vehicle Type:
Supply concentration in heavy-duty tractor-trailer combinations dominates fleet procurement across copper and coal export corridors, while lighter configurations capture margin in retail distribution networks.
- Trucks:Heavy-duty tractor units with 6x4 and 8x4 axle configurations haul bulk commodities across the Beitbridge and Kazungula corridors. Mining houses in Zambia and Zimbabwe specify these for dedicated mineral export lanes where single-commodity volumes justify direct vehicle deployment.
- Trailers:Flatbed, refrigerated, and low-bed trailer variants attach to tractor units based on cargo requirements. Low-bed configurations transport oversized mining equipment from South African manufacturing hubs to extraction sites in the Copperbelt region.
- Vans:Light commercial vehicles handle last-mile distribution across Botswana and Namibia retail networks.
- Buses:Passenger-cargo combi configurations serve informal cross-border trader routes.
Trucks absorb the bulk of installed capacity; trailers are expanding most quickly as mining procurement drives specialized equipment demand.
Service Type:
Cost tier differentiation separates dedicated mineral haulage from fragmented manufacturing supply chains, with intermodal handoffs capturing premium pricing for velocity-sensitive cargo.
- Full Truck Load:Single-shipper dedicated capacity dominates revenue pools on major corridors where commodity export volumes justify vehicle exclusivity. Copper concentrate movements from Zambian mine sites to Dar es Salaam port terminals operate almost exclusively under FTL contracts.
- Less Than Truck Load:Consolidated cargo services capture margin in fragmented manufacturing supply chains linking Johannesburg industrial hubs to neighboring consumer markets. Fast-moving consumer goods distributors serving secondary Botswana and Namibian cities rely on LTL for inventory replenishment frequency.
- Intermodal:Rail-truck handoffs at Maputo and Dar es Salaam port terminals accelerate cargo velocity as pure road border congestion escalates transit delays.
- Express:Time-definite services command premium pricing for automotive components and pharmaceutical shipments.
Full Truck Load commands the deepest capacity allocation; intermodal services are climbing the fastest as port terminal investments mature.
Cargo Type:
Application-specific handling requirements dictate fleet specification, with temperature-sensitive and hazardous classifications filtering carrier qualification tiers.
- Dry Goods:Non-temperature-sensitive commodities including packaged consumer products, construction materials, and agricultural inputs move via standard curtain-sided trailers. Retail distribution networks across Malawi and Tanzania generate consistent baseline demand.
- Perishables:Temperature-controlled units serving agricultural exports and retail cold chains remain underpenetrated in Malawi and Tanzania, where post-harvest losses exceed regional benchmarks. Specialized reefer trailers with multi-temperature zone capability capture premium rates.
- Hazardous Materials:Chemical and fuel transport requires certified tanker configurations and driver endorsements.
- Heavy Machinery:Mining equipment transport demands specialized low-bed trailers with hydraulic steering axles.
Dry goods absorb the bulk of installed capacity; perishables are gaining share fastest as retail cold-chain infrastructure expands.
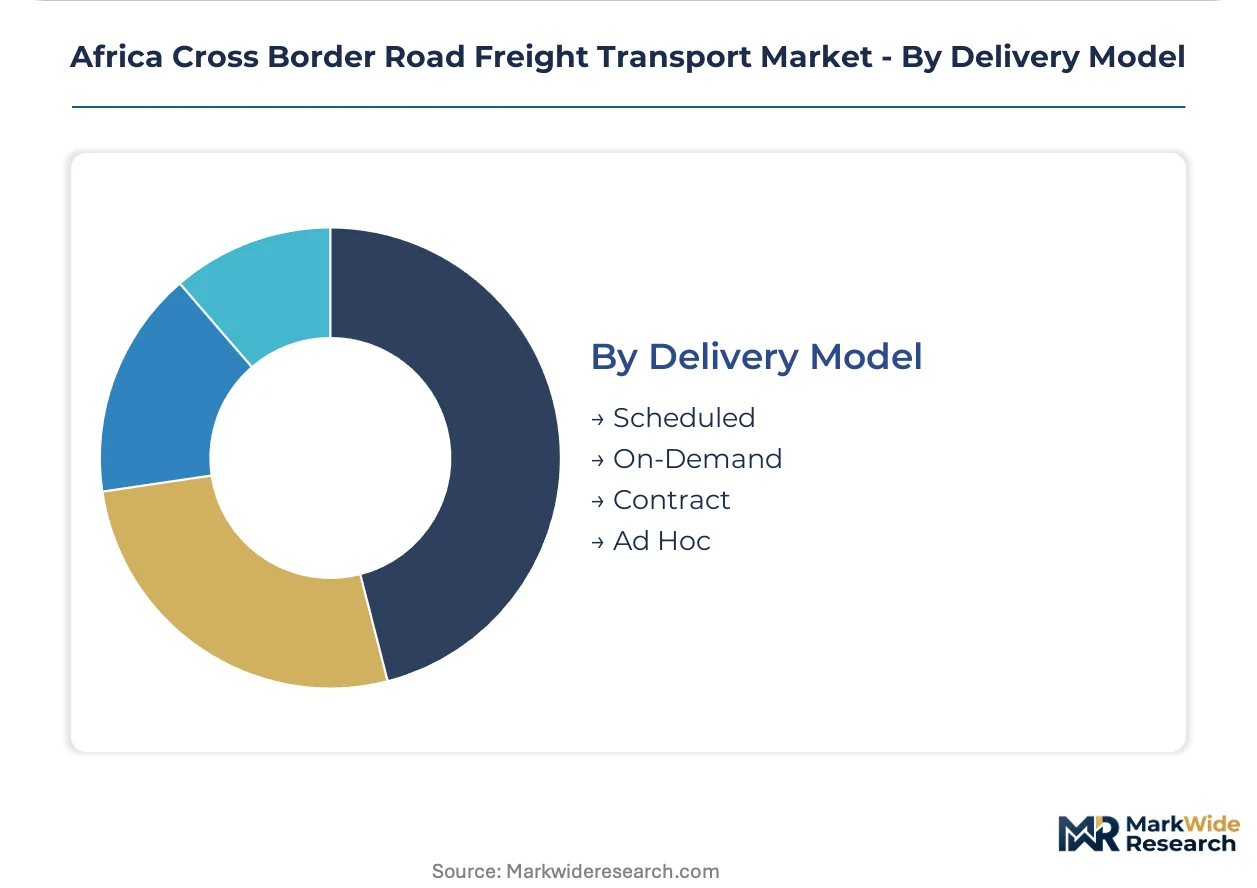
Delivery Model:
Customer type segmentation separates scheduled mining procurement from volatile spot-market access, with contract structures determining carrier revenue predictability.
- Scheduled:Fixed-route, fixed-frequency services anchor mining house procurement where extraction timelines dictate predictable haulage requirements. Copper and coal producers in Zambia and Zimbabwe contract scheduled capacity years in advance to secure equipment availability during export windows.
- On-Demand:Spot-market access enables shippers to access flexible capacity pools during demand spikes without asset ownership. Digital freight platforms now aggregate real-time subcontractor availability across the Durban-Johannesburg-Maputo triangle.
- Contract:Multi-year dedicated fleet agreements persist among agricultural exporters with seasonal volume concentration.
- Ad Hoc:Transactional shipments serve informal traders and emergency procurement scenarios.
Scheduled services absorb the bulk of installed capacity; on-demand access is expanding most quickly as digital freight matching platforms penetrate subcontractor networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in South Africa's industrial heartland while consumption demand radiates into landlocked neighbors. This asymmetry funnels cross-border tonnage through the Durban-Johannesburg-Maputo logistics triangle. Corridor investments now determine competitive positioning across Southern Africa.
South Africa
Mining machinery manufacturing and automotive component production anchor Gauteng's export volumes to SADC markets. The National Transport Master Plan prioritizes N3 corridor upgrades linking Durban port to Johannesburg industrial zones. Richards Bay coal terminal expansions are redirecting bulk flows from road to rail-truck intermodal handoffs.
Zambia
Copper concentrate extraction in the Copperbelt generates dedicated heavy-haul demand toward Dar es Salaam and Durban ports. The Zambia Revenue Authority enforces axle-load compliance through weighbridge networks that filter fleet specifications. Kitwe-Ndola manufacturing clusters are expanding cold-chain distribution capacity for agricultural exports.
Zimbabwe
Platinum and chrome mining operations in the Great Dyke corridor sustain full-truck-load contracts to South African smelters. The Zimbabwe Revenue Authority's pre-clearance customs systems are reducing Beitbridge border dwell times. Harare-Bulawayo distribution networks are consolidating around digital freight platforms for spot-market access.
Mozambique
Maputo port terminal expansions are accelerating rail-truck intermodal transfers for Zimbabwean and Zambian cargo. The Mozambique Tax Authority coordinates SADC customs harmonization protocols at Ressano Garcia border post. Nacala corridor investments are diverting northern hinterland traffic from Durban toward domestic port capacity.
Botswana
Diamond processing and beef exports generate temperature-controlled and high-security transport demand to Johannesburg and Cape Town. The Botswana Unified Revenue Service implements green freight corridor pilot standards for low-emission vehicle certification. Gaborone-Francistown logistics clusters are attracting asset-light subcontractor networks for retail distribution.
Africa Cross Border Road Freight Transport Market Competitive Environment
The competitive structure tilts toward integrated logistics providers with captive customs brokerage capabilities. Asset-heavy operators with owned fleets dominate mineral corridors, while asset-light platforms capture fragmented manufacturing demand. Three archetypes define the field: integrated end-to-end providers, specialized cold-chain operators, and digital freight aggregators. Capacity expansion and customs technology licensing represent the dominant competitive vectors.
Among integrated logistics providers, DSV South Africa and Bidvest Freight exemplify the customs-brokerage-anchored model. DSV South Africa occupies a position leveraging integrated cross-border documentation expertise, while Bidvest Freight anchors specialized perishable distribution networks. Super Group represents the asset-light archetype, extending reach through subcontractor aggregation without direct fleet ownership. Value Logistics and Cargo Carriers sit within the mid-tier specialized haulage segment.
| Leading Market Players |
|---|
| CEVA Logistics |
| Bidvest Freight (Pty) Ltd |
| DSV South Africa (Pty) Ltd |
| Value Logistics Ltd |
| DPD Laser Express Logistics (Pty) Ltd |
| DHL Freight Forwarding |
| Cargo Carriers (Pty) Ltd |
| Super Group Ltd |
| Unitrans Supply Chain Solutions (Pty) Ltd |
| Others |
Value Chain & Pricing Dynamics
Mining house procurement concentration in the Copperbelt and Great Dyke corridors anchors contract-based long-term offtake pricing, with annual volume commitments exchanged for dedicated fleet allocation and customs brokerage bundling. This buyer structure compresses spot-market premiums during commodity export windows while elevating intermodal service pricing where velocity-sensitive cargo bypasses congested road borders.
Pricing Analysis
Cost compression in standard FTL services reflects diesel price volatility and subcontractor oversupply across the Durban-Johannesburg-Maputo triangle. Three-tier pricing structure across premium, standard, and economy levels separates dedicated mining contracts with guaranteed capacity from spot-market access and ad hoc brokered loads. Certification tier differentiation—SADC operator licensing compliance versus non-compliant carriers—creates price spreads that filter fleet investment decisions. Smaller carriers serving retail distribution networks exhibit highest price sensitivity, while mining houses prioritize reliability over rate negotiation.
Supply Chain Analysis
Dual-sourcing mandates from copper and coal producers require carriers to maintain subcontractor networks across both South African and Mozambican registered fleets, mitigating single-jurisdiction regulatory disruption. Vehicle manufacturing concentrates in South Africa, while trailer specialized equipment sources from regional fabrication hubs in Botswana and Zimbabwe. Supply chain risk centers on axle-load compliance enforcement variance between Zambia Revenue Authority and Zimbabwe Revenue Authority weighbridge networks. Distribution runs through port-centric logistics clusters at Durban, Maputo, and Dar es Salaam with rail-truck handoff terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-border road freight is consolidating around captive customs brokerage capabilities as the decisive vertical-integration lever, with carriers racing to internalize documentation expertise that previously sat with third-party agents.
For Market Incumbents: Extend customs technology licensing to secondary SADC corridors before digital freight platforms aggregate subcontractor capacity. Consolidate weighbridge compliance data streams into pre-arrival risk scoring that secures green lane access at Beitbridge and Kazungula. Defensive positioning requires backward integration into trailer manufacturing to control specialized low-bed and reefer equipment availability during mining procurement cycles. For New Entrants and Emerging Players: Platform-based load aggregation offers the lowest barrier entry path into fragmented manufacturing supply chains linking Johannesburg to Botswana and Namibian retail networks. White-space concentration sits in cold-chain perishables for Malawian and Tanzanian agricultural exports, where post-harvest losses indicate unmet temperature-controlled capacity demand. Digital freight matching with telematics integration provides the essential go-to-market angle for asset-light market penetration. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier specialized haulage operators in Zimbabwe with SADC-compliant fleets and stranded mining contracts during commodity price corrections. Long-term viability hinges on AfCFTA customs harmonization execution and green freight corridor mandate timing. The signal to watch is LNG and electric drivetrain pilot adoption rates across Botswana and South Africa green corridor designations.| Strategic Initiative | Industry Significance |
|---|---|
| Customs Brokerage Technology Licensing | Captive documentation expertise accelerates clearance at Beitbridge and Kazungula border posts. |
| Green Freight Corridor Fleet Renewal | LNG and electric drivetrain adoption aligns with Botswana and South Africa low-emission mandates. |
| Intermodal Rail-Truck Terminal Investment | Maputo and Dar es Salaam port handoffs bypass pure road congestion for velocity-sensitive cargo. |
| Cold-Chain Perishable Capacity Expansion | Multi-temperature reefer deployment captures premium rates in underpenetrated Malawi and Tanzania markets. |
| Digital Freight Platform Integration | Real-time subcontractor aggregation compresses carrier revenue predictability while expanding market access. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across fleet operations managers, cross-border customs brokers, mining procurement officers, and SADC transport authority officials. Bottom-up triangulation validated vehicle registration databases, weighbridge enforcement reports, and port terminal throughput statistics against top-down revenue estimates from logistics provider financial disclosures and AfCFTA Secretariat implementation tracking.
Data-stream reconciliation across the analysis window applied segment-level modeling for vehicle type, service configuration, cargo classification, and delivery model dimensions. CAGRs derived from corridor-specific volume projections weighted by mining export schedules, retail distribution frequency requirements, and intermodal terminal capacity expansion timelines. Forecast inputs incorporated diesel price scenario modeling and axle-load compliance enforcement intensity variations across Zambia, Zimbabwe, and Mozambique.
The model holds under sustained AfCFTA customs harmonization and stable mining export demand; deviation in green freight corridor mandate acceleration or rail freight rehabilitation pace would shift fleet investment priorities and corridor competitiveness materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Europe Freight and Logistics Market
Transportation & Logistics
United States Road Freight Transport Market
Transportation & Logistics
Australia Road Freight Transport Market
Transportation & Logistics
United States Refrigerated Transport Market
Transportation & Logistics
Rail Asset Management Market
Transportation & Logistics
Railcar Unloader Market
Transportation & Logistics
Train Collision Avoidance System Market
Transportation & Logistics
Trade-In and Buy-Back Logistics Programs Management Market
Transportation & Logistics
Romania Road Freight Transport Market
Transportation & Logistics
Cold Chain Vehicles Market
Transportation & Logistics
Boxcar Scars Market
Transportation & Logistics
India Road Freight Transport Market
Transportation & Logistics
GCC Refrigerated Transport Market
Transportation & Logistics
Refrigerated Transport Market
Transportation & Logistics
Netherlands Road Freight Transport Market
Transportation & Logistics
Ski Conveyor Lift Market