
 North America Road Freight Transport Market | 2026-2036
North America Road Freight Transport Market Size, Share, and Industry Trends Forecast 2026-2036
North America Road Freight Transport Market Analytics
Last-mile platform revenue is rewriting profit expectations across North American trucking. J.B. Hunt Transport Services leverages intermodal infrastructure to capture margin from rail-road integration. Schneider National anchors dedicated contract carriage with proprietary fleet management systems. Old Dominion Freight Line dominates less-than-truckload density in the southeastern lanes.
Road freight transport encompasses the movement of goods via motor vehicles over public highway networks, utilizing power units ranging from light-duty vans to Class 8 tractors with gross vehicle weight ratings exceeding 33,000 pounds, operating through either asset-based or brokered capacity arrangements. Full truckload transport commands the largest revenue pool but faces margin compression from digital freight matching platforms, while temperature-controlled service commands premium pricing from pharmaceutical and fresh food shippers. Heavy-duty trucks remain the dominant capital deployment category, though light-duty van utilization is expanding fastest in urban e-commerce fulfillment.
The EPA Phase 3 standards and the US DOT hours-of-service regulations shape fleet investment cycles and driver availability across the United States, while Transport Canada's clean fuel regulations and provincial weight limits govern Canadian cross-border operations. Mexico's Secretariat of Infrastructure, Communications and Transportation enforces axle-load standards that affect harmonized freight flows under USMCA. Stakeholders must monitor the divergence between California's Advanced Clean Trucks mandate and federal baseline standards, as this regulatory fragmentation will force route-specific fleet composition decisions rather than continent-wide uniform procurement.
Market Dynamics
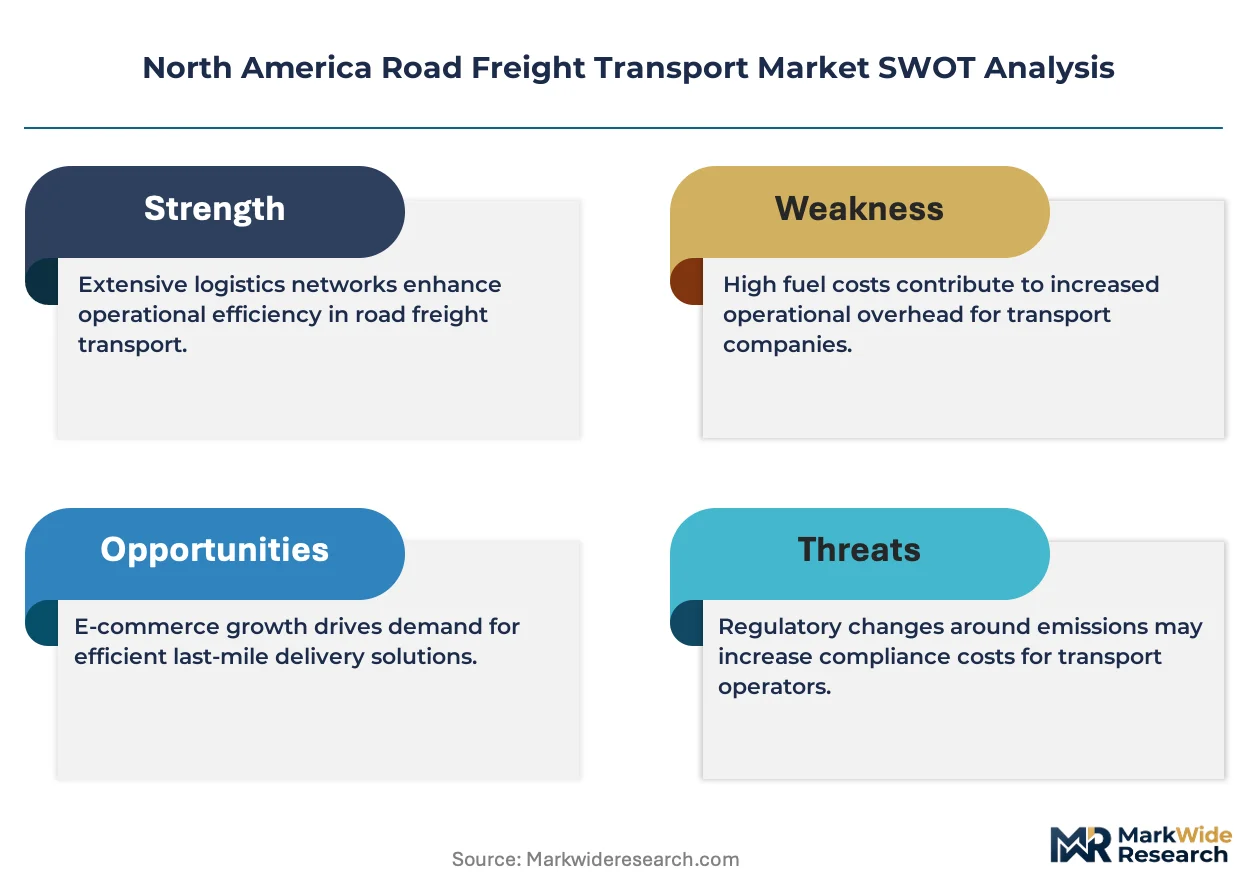
EPA Phase 3 greenhouse gas standards are forcing North American fleet operators to accelerate electrification investments while simultaneously managing diesel asset depreciation cycles. This regulatory compression is reshaping capital allocation across asset-heavy carriers and third-party logistics providers.
Growth Catalysts
- Cross-border manufacturing integration:Texas-Mexico corridor freight volumes are expanding as nearshoring accelerates electronics and automotive component flows under USMCA provisions.
- EPA Phase 3 standards:The regulation mandates progressive emissions reductions that compel fleet renewal and create aftermarket demand for aerodynamic retrofits and idle-reduction technologies.
- Pharmaceutical cold chain expansion:Temperature-controlled transport capacity is capturing premium rates from biologics distribution networks requiring validated thermal packaging and real-time monitoring.
Market Restraints
- Driver availability constraints:US DOT hours-of-service regulations limit fleet utilization rates while demographic shifts compress the qualified driver pool.
- California regulatory fragmentation:The state's Advanced Clean Trucks mandate diverges from federal EPA baselines, forcing bifurcated fleet procurement strategies.
- Battery energy density limitations:Current lithium-ion chemistries restrict Class 8 electric tractor range to sub-500-mile routes, constraining long-haul electrification.
Strategic Opportunities
- Intermodal rail-road integration:Highway-to-rail transloading infrastructure investments in Chicago and Memphis corridors offer margin expansion for domestic containerized freight.
- Autonomous middle-mile pilots:Texas and Arizona regulatory frameworks permit driver-out operations on designated freight-only highway segments.
- Mexico manufacturing cluster expansion:Nuevo León and Baja California production capacity is generating northbound dedicated contract carriage demand.
Industry Challenges
- Telematics integration complexity:Legacy fleet management systems require costly API bridging to connect with emerging electric vehicle monitoring platforms and charging network software.
- Technician skill gaps:High-voltage powertrain diagnostics and battery thermal management expertise remains scarce across maintenance networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Road Freight Transport Market |
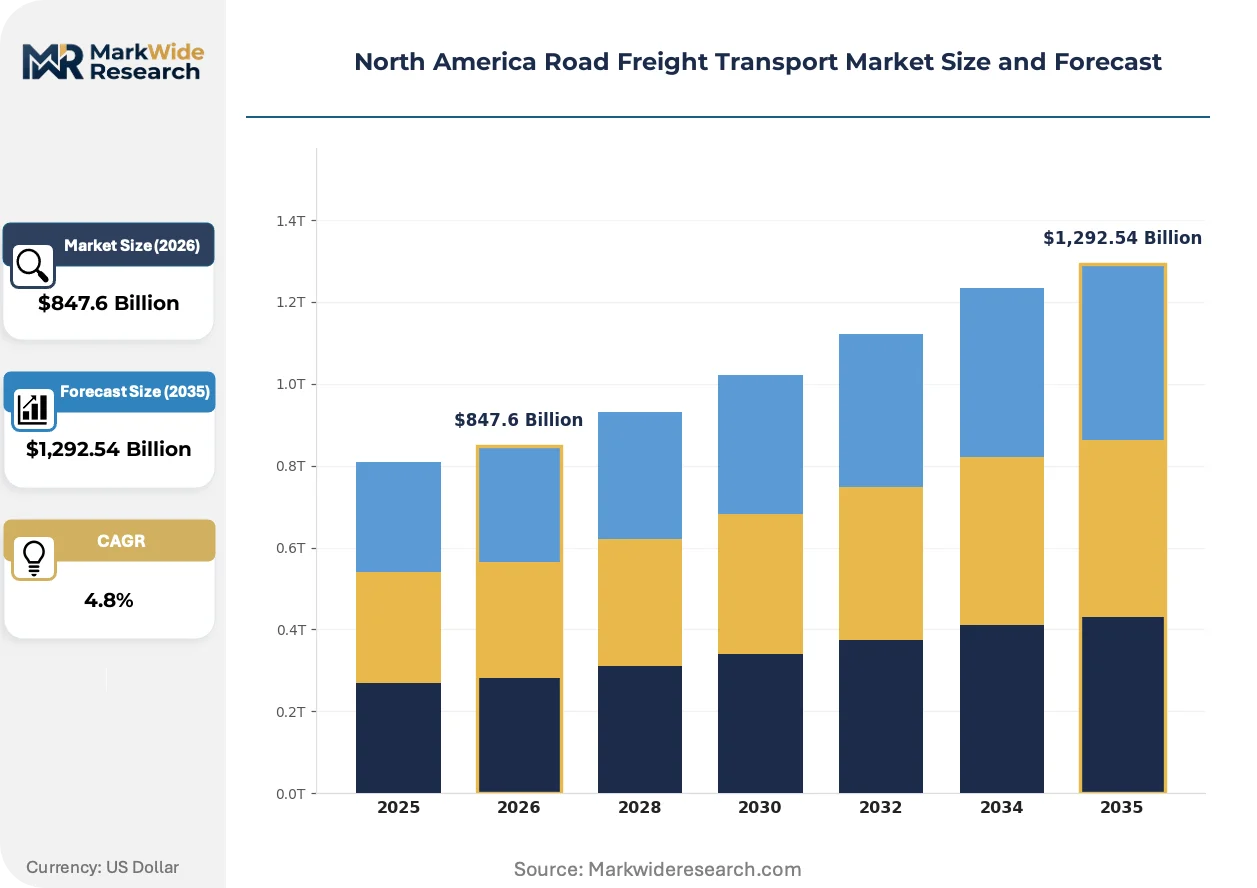
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $1,292.54 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Transport Type: Full Truckload, Less-than-Truckload, Intermodal, Dedicated Vehicle Type: Light-Duty Trucks, Heavy-Duty Trucks, Cargo Vans, Trailers End User: Retailers, Manufacturers, Wholesalers, Distributors Service Type: Standard Shipping, Expedited Shipping, Temperature-Controlled, Freight Brokerage |
| Companies Covered | FedEx Freight, Schneider National, Old Dominion Freight Line, Ryder System, Estes Express Lines, J.B. Hunt Transport Services, XPO, TFI International, Knight-Swift Transportation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Road Freight Transport Market Evolving Landscape
Digital freight matching platforms are compressing brokerage margins while real-time visibility tools are becoming table stakes for shipper retention. Fleet electrification timelines are diverging sharply between urban last-mile operators and long-haul asset-based carriers.
Telematics-enabled predictive maintenance is migrating from aftermarket add-on installations to factory-integrated OEM standard equipment. Large dedicated contract carriage fleets are mandating embedded diagnostic modules at procurement. This technology shift is compressing third-party maintenance provider margins while transferring data ownership toward vehicle manufacturers.
Transport Canada's clean fuel regulations are tightening carbon intensity benchmarks for diesel alternatives used in cross-border operations. The policy is accelerating renewable natural gas infrastructure investments at Ontario and British Columbia terminal facilities. Temperature-controlled carriers serving the Vancouver-Seattle corridor are prioritizing R-CNG retrofits to maintain shipper sustainability scorecard compliance.
Shippers are consolidating freight procurement through centralized transportation management systems that algorithmically optimize mode selection. Regional distributors are displacing traditional freight brokers through direct carrier API connections. This pattern is most pronounced in Midwest manufacturing networks where automotive tier-one suppliers operate captive routing optimization platforms.
North America Road Freight Transport Market Segmentation
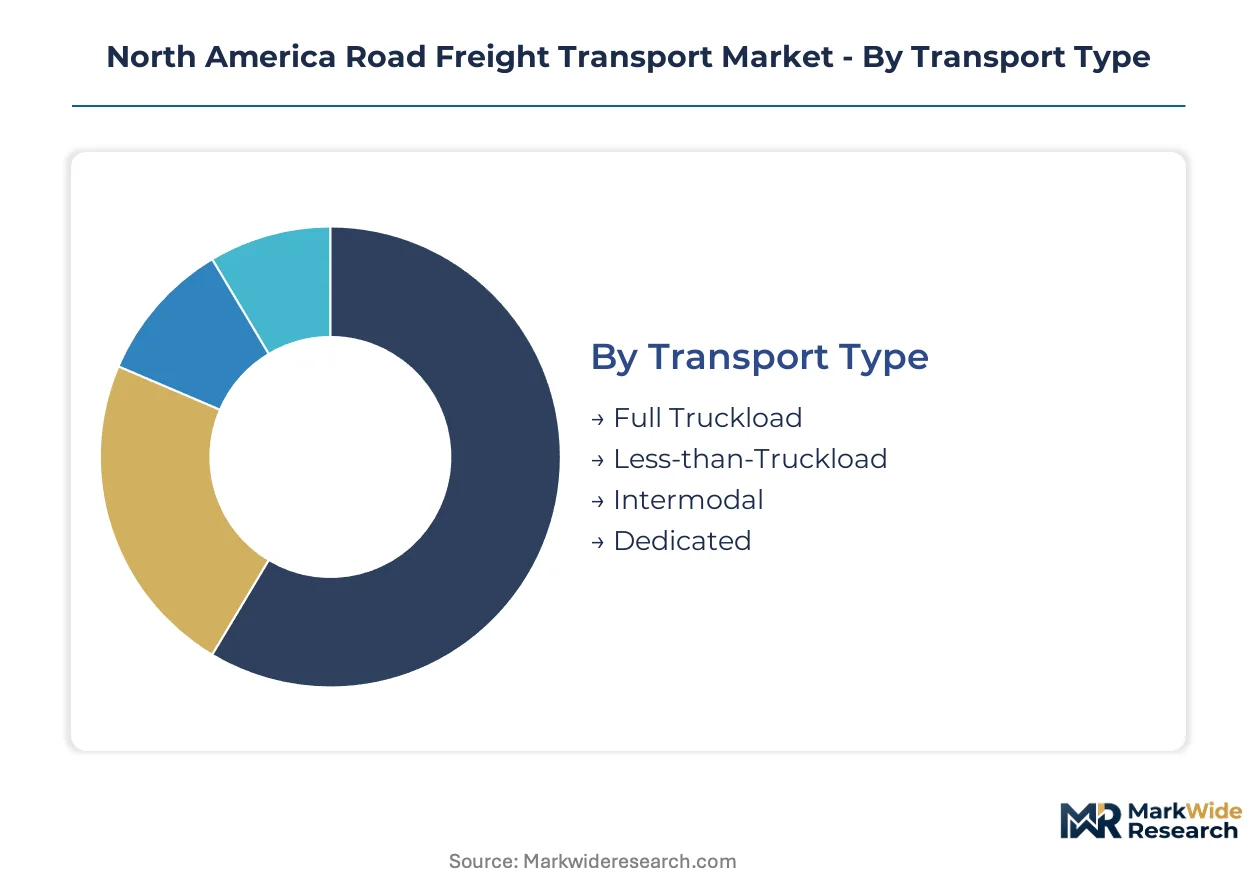
Road freight segmentation in North America reflects divergent capital intensity and regulatory exposure across service models. Fleet operators configure asset portfolios around route density, cargo specialization, and cross-border compliance requirements rather than pursuing uniform scale.
Transport Type:
Mature modes anchor revenue stability while emerging formats capture margin from supply chain restructuring.
- Full Truckload:Dedicated tractor-trailer units move single-shipper cargo from origin to destination without intermediate handling. Demand concentrates in Texas-Mexico automotive corridors where USMCA rules of origin require direct manufacturing plant-to-plant routing.
- Less-than-Truckload:Consolidated shipments from multiple shippers share trailer capacity through hub-and-spoke terminal networks. E-commerce fulfillment networks in southeastern United States are expanding LTL density as last-mile complexity fragments parcel volumes into palletized shipments.
- Intermodal:Containerized freight transfers between highway and rail modes at transloading facilities.
- Dedicated:Exclusive fleet assignment to single shipper under multi-year contract terms.
Full Truckload retains volume leadership; Less-than-Truckload holds the steepest expansion curve.
Vehicle Type:
Cost tier stratification separates premium electrification investments from legacy diesel depreciation management.
- Heavy-Duty Trucks:Class 8 tractors with gross vehicle weight ratings exceeding 33,000 pounds haul the majority of long-haul tonnage. EPA Phase 3 standards are accelerating fleet renewal cycles while battery energy density constraints limit electric range to sub-500-mile routes.
- Light-Duty Trucks:Commercial pickups and chassis-cab vehicles serve urban final-mile delivery routes. California's Advanced Clean Trucks mandate is forcing bifurcated procurement strategies distinct from federal baselines.
- Cargo Vans:Compact enclosed vehicles handle parcel and small-package distribution.
- Trailers:Non-powered units including dry vans, refrigerated containers, and flatbeds.
Heavy-Duty Trucks retain volume leadership; Light-Duty Trucks hold the steepest expansion curve.
End User:
Customer type determines contract structure, with captive fleets diverging from spot-market procurement patterns.
- Retailers:Big-box and e-commerce operators require synchronized inbound inventory and outbound fulfillment. Midwest automotive tier-one suppliers are displacing traditional freight brokers through direct carrier API connections.
- Manufacturers:Industrial production facilities demand scheduled replenishment of raw materials and component parts. Nuevo León and Baja California production clusters are generating northbound dedicated contract carriage demand under USMCA integration.
- Wholesalers:Intermediate distributors consolidate volumes from multiple suppliers for downstream resale.
- Distributors:Specialized logistics operators manage inventory and fulfillment for manufacturer clients.
Retailers retain volume leadership; Manufacturers hold the steepest expansion curve.
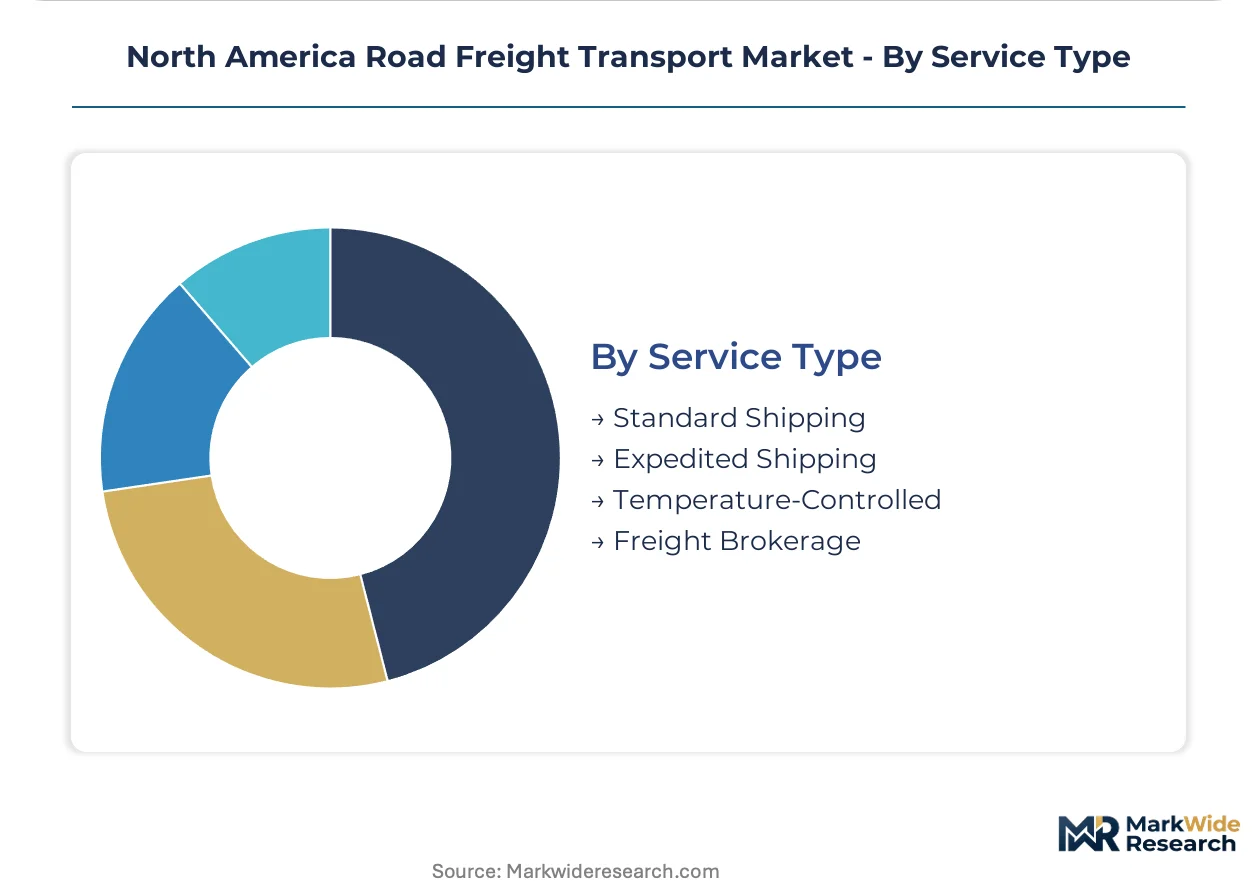
Service Type:
Margin structure separates commodity offerings from premium-validated service tiers.
- Temperature-Controlled:Refrigerated and frozen transport maintains specified thermal ranges through validated packaging and real-time monitoring. Biologics distribution networks are capturing premium rates as pharmaceutical cold chain requirements tighten.
- Freight Brokerage:Non-asset intermediaries match shipper demand with available carrier capacity through digital platforms. Digital freight matching is compressing brokerage margins while real-time visibility tools become mandatory for shipper retention.
- Standard Shipping:Regular-schedule, non-expedited transport without specialized handling requirements.
- Expedited Shipping:Time-definite delivery with guaranteed transit windows and dedicated equipment assignment.
Standard Shipping retains volume leadership; Temperature-Controlled holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freight corridors concentrate along the United States-Mexico border and the Great Lakes manufacturing belt. Carrier networks optimize around these density nodes while navigating divergent emissions regulations across federal and state jurisdictions.
United States
Texas-Mexico automotive corridors drive dedicated contract carriage demand under USMCA rules of origin. The EPA Phase 3 greenhouse gas standards mandate progressive emissions reductions that accelerate fleet renewal cycles. Chicago and Memphis anchor intermodal transloading infrastructure for rail-road integration.
Canada
Ontario-Quebec manufacturing clusters generate cross-border temperature-controlled freight to U.S. Midwest distribution centers. Transport Canada's clean fuel regulations tighten carbon intensity benchmarks for diesel alternatives. Vancouver-Seattle corridor carriers prioritize renewable natural gas retrofits for sustainability scorecard compliance.
Mexico
Nuevo León and Baja California production capacity generates northbound dedicated contract carriage demand. The Secretariat of Infrastructure, Communications and Transportation enforces axle-load standards affecting harmonized freight flows. Monterrey manufacturing clusters require direct plant-to-plant routing for electronics and automotive components.
California
The state's Advanced Clean Trucks mandate forces bifurcated fleet procurement strategies distinct from federal EPA baselines. Los Angeles and Long Beach port complexes drive drayage electrification investments. Urban last-mile operators face accelerated zero-emission vehicle deployment timelines.
Texas
Laredo and McAllen border crossings handle the highest volume of USMCA-compliant manufacturing freight. The state permits autonomous middle-mile pilots on designated freight-only highway segments. Dallas-Fort Worth distribution centers anchor southeastern less-than-truckload density networks.
North America Road Freight Transport Market Competitive Landscape
Asset-heavy carriers and non-asset intermediaries split the market along capital intensity lines. Consolidation concentrates among dedicated contract carriage providers with proprietary fleet management systems, while digital freight matching platforms fragment spot-market brokerage. Strategic archetypes include integrated intermodal operators, less-than-truckload density specialists, and temperature-controlled niche carriers. Dominant competitive moves encompass rail-road infrastructure partnerships and electric vehicle procurement alliances.
Within the integrated intermodal tier, J.B. Hunt Transport Services and Schneider National exemplify carriers leveraging hub infrastructure for margin expansion. Old Dominion Freight Line anchors the less-than-truckload density archetype in southeastern lanes. These three companies represent the strategic positioning spectrum from rail-road integration to terminal network optimization.
| Leading Market Players |
|---|
| FedEx Freight |
| Schneider National |
| Old Dominion Freight Line |
| Ryder System |
| Estes Express Lines |
| J.B. Hunt Transport Services |
| XPO |
| TFI International |
| Knight-Swift Transportation |
| Others |
Value Network & Pricing Analysis
The Texas-Mexico manufacturing corridor concentrates supply density and cost leverage, with Laredo border crossing volumes anchoring spot-rate volatility that cascades into contract pricing tiers for automotive and electronics shippers.
Pricing Analysis
After-sales revenue from maintenance contracts and parts programs drives lifetime value for asset-heavy carriers. Three-tier pricing structure across dedicated contract, spot market, and brokered capacity segments reflects service reliability guarantees and equipment exclusivity. Cost compression in long-haul full truckload stems from digital freight matching platforms disintermediating traditional brokerage. Small and mid-sized shippers exhibit highest price sensitivity, while pharmaceutical cold chain operators accept premium rates for validated thermal compliance.
Supply Chain Analysis
Diesel refining capacity and battery cell manufacturing feed into fleet procurement decisions across the United States, Mexico, and Canada. Lithium-ion cell supply draws from South Korean and Chinese producers, while Class 8 chassis assembly concentrates in Mexican and U.S. heartland plants. Single-source vulnerability in semiconductor-based telematics modules threatens production scheduling. Distribution runs through hub-and-spoke terminal networks anchored by Memphis and Chicago intermodal facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American road freight sits in early-cycle expansion, with EPA Phase 3 compliance deadlines accelerating fleet renewal investment across asset-based carriers.
For Market Incumbents: Harden terminal network density in southeastern LTL lanes to deflect digital freight platform encroachment. Deepen backward integration into trailer manufacturing to capture equipment margin and secure chassis allocation priority. Electrification procurement alliances with OEMs represent the critical capacity lever against California regulatory divergence. For New Entrants and Emerging Players: Temperature-controlled middle-mile routes between Nuevo León and Texas distribution centers represent the most penetrable entry point for dedicated contract carve-outs. Autonomous freight pilots on Arizona and Texas highway segments offer regulatory sandbox access unavailable to established liability-heavy fleets. Direct API integration with automotive tier-one supplier platforms bypasses brokered procurement layers. For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate logistics divisions lacking fleet telematics integration or electrification roadmaps. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than scale alone. Watch EPA enforcement variance across state jurisdictions as early inflection signal for route-specific asset stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| Rail-Road Intermodal Partnership | Chicago and Memphis transloading investments capture margin from domestic containerized freight conversion. |
| Electric Fleet Procurement Alliance | OEM volume commitments secure battery allocation priority ahead of Class 8 production constraints. |
| Autonomous Middle-Mile Pilot | Texas and Arizona regulatory frameworks permit driver-out operations on designated freight-only segments. |
| Temperature-Controlled Capacity Expansion | Biologics distribution networks require validated thermal packaging capturing premium pharmaceutical rates. |
| Cross-Border Terminal Network | Laredo and McAllen facilities anchor USMCA-compliant manufacturing flows under direct plant-to-plant routing. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations directors, shipper procurement managers, OEM platform engineers, and intermodal terminal operators and refined through secondary validation against DOT freight flow databases, EPA regulatory filings, USMCA trade statistics, and carrier SEC disclosures. Bottom-up volume estimates from route-density analysis were triangulated against top-down macroeconomic freight demand indicators.
Demand-supply balance modeling across transport type, vehicle class, end-user vertical, and service tier segmentation generated volume and value outputs over the projection horizon. CAGRs were derived from regression analysis against manufacturing output indices and cross-border trade velocity. Forecast inputs incorporated EPA Phase 3 compliance cost curves and battery energy density improvement trajectories.
Practitioners should monitor EPA enforcement variance, lithium supply contract renegotiations, and autonomous vehicle regulatory approvals for early signals of forecast revision. Cross-checking against DOT freight tonnage reports and ACT Research equipment order data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation & Logistics
Automatic Vehicle Location System (AVL) Market
Transportation & Logistics
Cross-Border Road Transport Market
Transportation & Logistics
Brazil Road Freight Transport Market
Transportation & Logistics
Europe Cross Border Road Freight Transport Market
Transportation & Logistics
Cold Chain Vehicles Market
Transportation & Logistics
GCC International Express Service Market
Transportation & Logistics
Transportation Aggregators Market
Transportation & Logistics
United States Road Freight Transport Market
Transportation & Logistics
Global Automotive 3PL Market
Transportation & Logistics
Asia Pacific Road Freight Transport Market
Transportation & Logistics
Indonesia Refrigerated Trailer Market
Transportation & Logistics
Europe Road Feeder Services Market
Transportation & Logistics
Europe Fleet Management Market
Transportation & Logistics
Vietnam Road Freight Transport Market
Transportation & Logistics
India Road Freight Transport Market
Transportation & Logistics
Refrigerated Trailer Market