
 Bonnet Lock Plate and Latch Market | 2026-2036
Bonnet Lock Plate and Latch Market Size, Share, and Industry Trends Forecast 2026-2036
Bonnet Lock Plate and Latch Market Analysis
Stamping capacity across East Asian tier-one suppliers is rebalancing toward higher-strength steel grades. Kiekert AG leverages captive die-casting operations in Europe to sustain margin control on premium latch modules. Magna International anchors North American supply through vertically integrated stamping and assembly lines. Brose Fahrzeugteile differentiates via mechatronic integration expertise across German and Chinese production bases.
Bonnet lock plates and latches are mechanical fastening devices engineered to secure engine compartment closures against aerodynamic and impact loads, typically fabricated from zinc-coated high-strength steel or die-cast aluminum with specified release forces between 300-600 N for pedestrian protection compliance. Their primary purpose is to maintain hood positional integrity during vehicle operation while enabling rapid emergency access. Steel lock plates still dominate installed volume across mass-market vehicle programs, though aluminum latches claim expanding share in electric vehicle architectures where mass reduction targets intensify. OEM channel concentration creates durable margin pools for suppliers with validated production part approval process (PPAP) status, while aftermarket providers compete on inventory velocity rather than engineering content.
NHTSA Federal Motor Vehicle Safety Standard No. 113 governs hood latch displacement requirements in the United States, while ECE R21 and the EU General Safety Regulation mandate pedestrian head-impact performance that directly shapes latch release kinematics. China's GB standards and MIIT homologation protocols enforce equivalent structural integrity thresholds for domestic vehicle sales. Stakeholders must monitor evolving UN R127 pedestrian protection amendments and assess dual-sourcing exposure as regional content rules tighten across major automotive production zones.
Market Dynamics
OEM procurement of lightweight aluminum latch assemblies is accelerating as manufacturers comply with NHTSA pedestrian safety standards, compressing traditional steel architectures while reshaping tier-one supplier capacity allocation across major automotive production zones.
Growth Catalysts
- NHTSA Federal Motor Vehicle Safety Standard No. 113:Mandates hood latch displacement thresholds that force redesign cycles, generating replacement demand for compliant pedestrian-protection architectures in US-bound vehicle programs.
- Die-cast aluminum substitution:Mass reduction targets in electric vehicle platforms are pulling aluminum latches into premium and mid-range EV architectures where every kilogram affects range certification.
- Stuttgart-Wolfsburg engineering corridor:Concentrated R&D investment from German OEMs is validating next-generation latch kinematics for EU General Safety Regulation compliance, creating specification pull-through effects.
Market Restraints
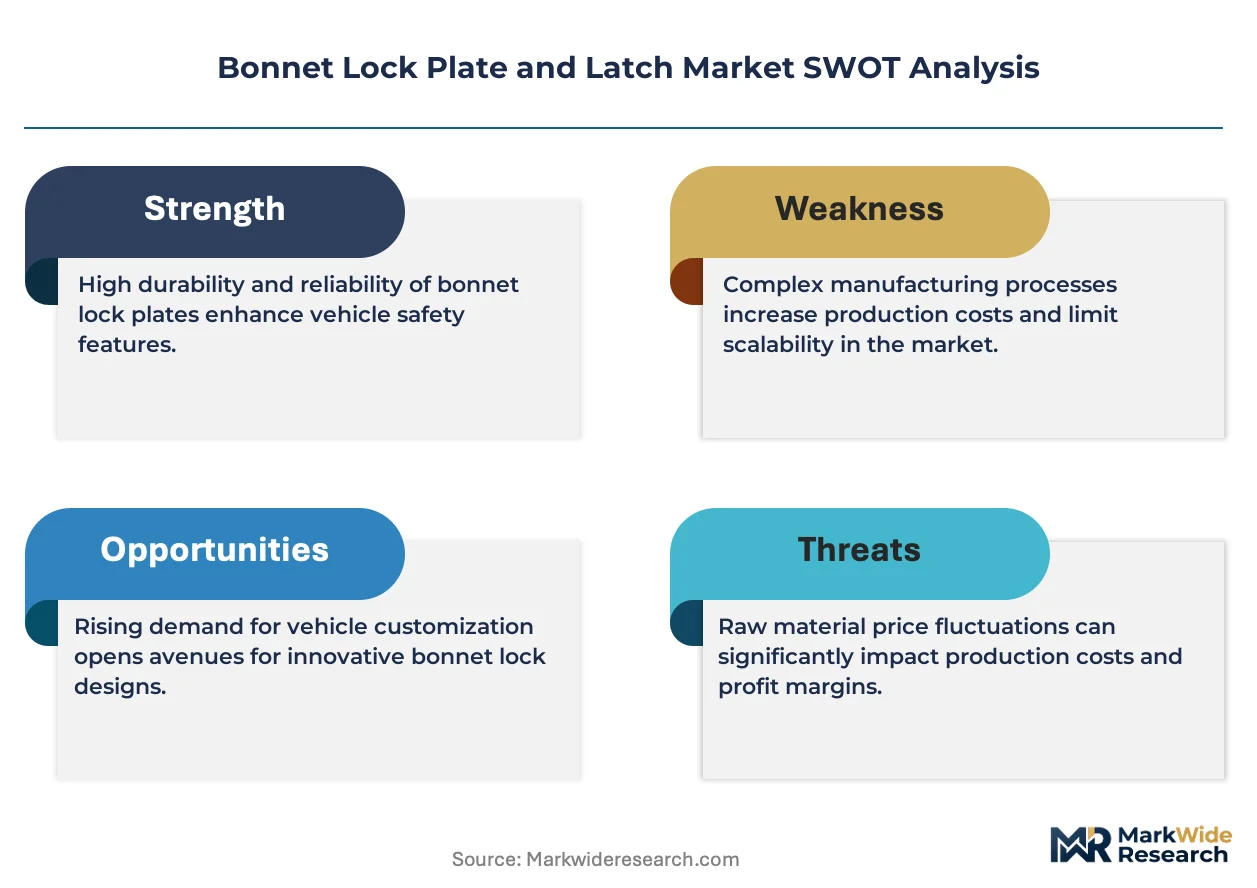
- Zinc-coated high-strength steel price volatility:Raw material input swings compress margin predictability for stampers locked into annual price agreements with mass-market OEMs.
- East Asian tier-one supply concentration:Stamping capacity rebalancing toward higher-strength grades creates geographic dependency risk for European and North American OEMs seeking dual-source security.
- ECE R21 head-impact performance thresholds:Technical limitation in achieving 300-600 N release force consistency across temperature ranges extends validation timelines and tooling amortization periods.
Strategic Opportunities
- GB standards alignment in China:MIIT homologation protocols for domestic vehicle sales create entry pathways for suppliers with validated PPAP status to capture volume in the world's largest automotive market.
- Mechatronic integration convergence:Combining electronic release actuation with mechanical backup systems opens specification opportunities in premium vehicle segments where convenience features command price premiums.
- Aftermarket inventory velocity models:Digital parts-matching platforms are compressing distribution layers, enabling specialized distributors to capture margin pools previously held by traditional wholesale networks.
Industry Challenges
- Production part approval process certification timelines:Extended PPAP validation cycles for new latch architectures strain working capital for mid-tier stampers competing against vertically integrated rivals.
- Die-casting talent scarcity:Specialized process engineering expertise for thin-wall aluminum casting remains concentrated in European and Japanese supplier bases, limiting geographic expansion options.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bonnet Lock Plate and Latch Market |
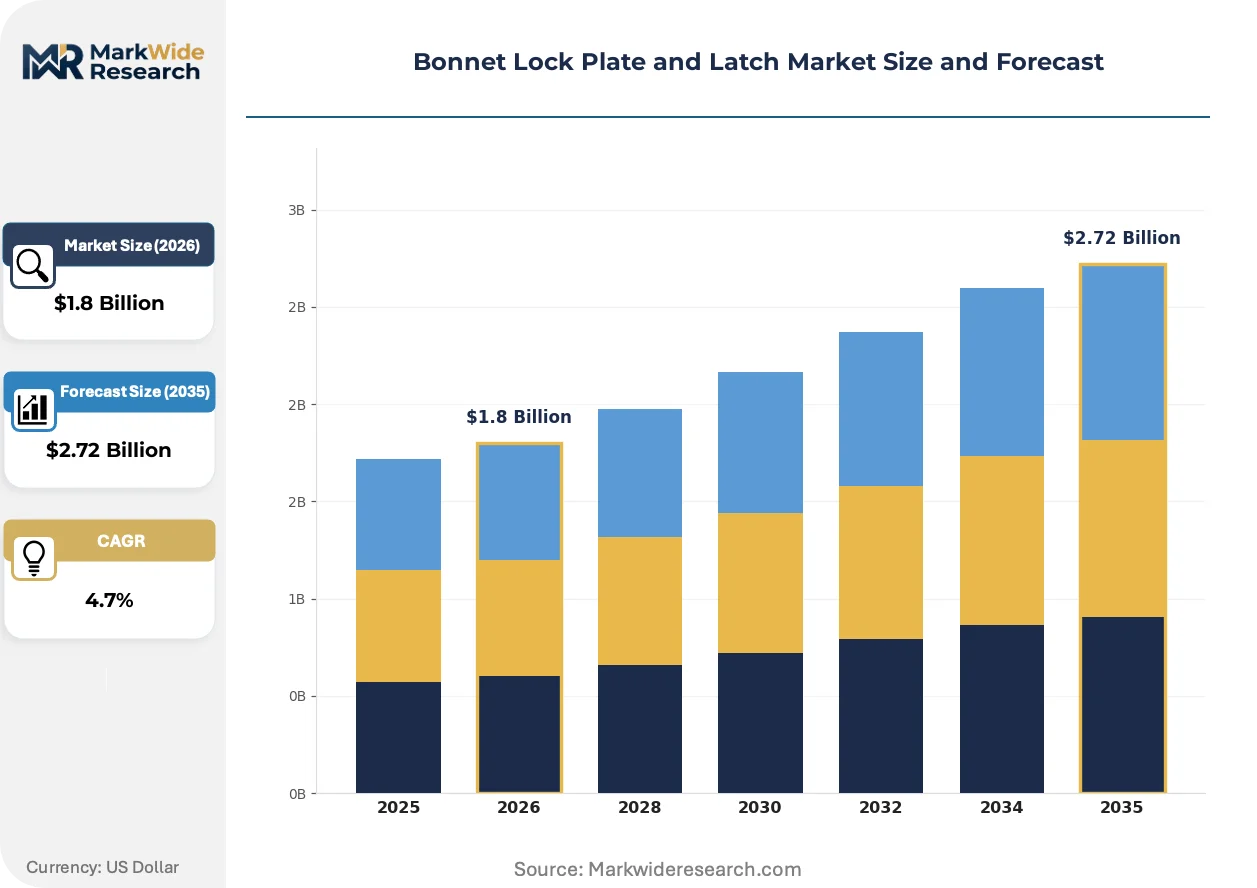
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Lock Plates, Latches, Bolts, Fasteners Material: Steel, Aluminum, Plastic, Composite End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops Installation Type: Standard Installation, Modular Installation, Custom Installation, Retrofit |
| Companies Covered | Kiekert AG, Shivani Locks, Inteva Products, U-Shin Ltd., IFB Automotive, Magna International, Strattec Security Corporation, Brose Fahrzeugteile, Aisin Seiki Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bonnet Lock Plate and Latch Market Emerging Trajectories
Active safety integration and material substitution are converging to redefine bonnet latch engineering specifications, with pedestrian protection compliance serving as the forcing function for architectural redesign across ICE and electric vehicle platforms.
Aluminum die-cast latch housings are absorbing structural loads previously managed by steel stampings, enabling 30-40% mass reduction in hood closure systems. Premium EV manufacturers are specifying these architectures for range optimization, and the shift is compressing steel supplier margins while rewarding foundries with automotive aluminum expertise.
UN R127 pedestrian protection amendments are tightening head-impact performance thresholds across European type-approval processes. The regulation is forcing latch release kinematics redesigns that extend engineering validation cycles, and German OEMs are responding by pre-qualifying suppliers against anticipated 2026 enforcement timelines.
Buyer concentration among platform-sharing OEM consortia is consolidating procurement decisions around fewer, larger supply agreements. Long-term framework contracts with annual volume commitments are displacing spot purchasing for latch modules, and this pattern is most visible in German and Japanese automotive engineering clusters where cross-brand platform architectures dominate.
Bonnet Lock Plate and Latch Market Segmentation
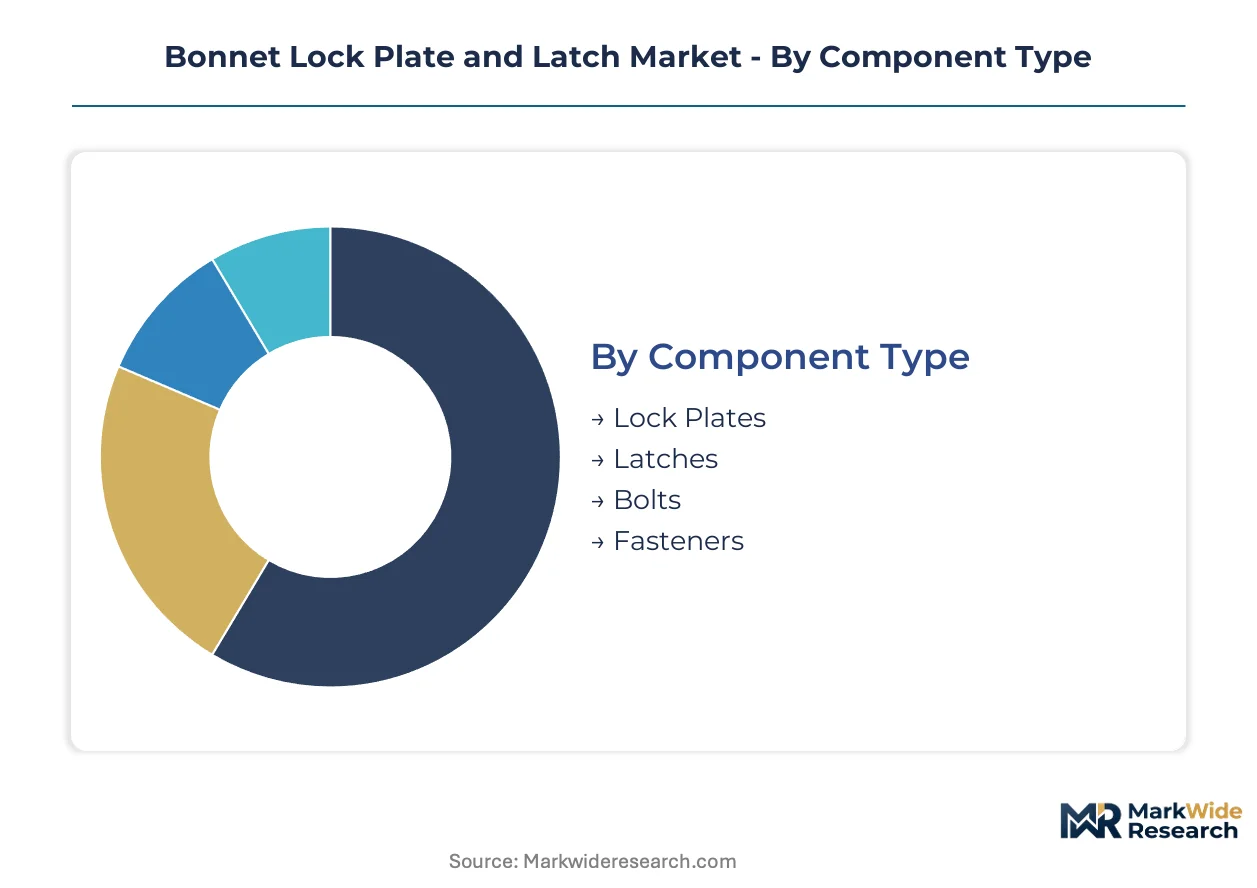
Segmentation in bonnet lock plate and latch procurement reveals how material substitution and installation complexity reshape supplier margins. OEM specification divergence between steel and aluminum architectures forces tier-one manufacturers to maintain dual production competencies.
Component Type:
Supply concentration for precision-engineered closure components clusters around German and Japanese tier-one suppliers with captive stamping and die-casting capabilities.
- Lock Plates:Stamped zinc-coated high-strength steel plates form the primary load-bearing interface between hood and body structure, with release force calibration between 300-600 N for NHTSA pedestrian compliance. Demand concentrates in Stuttgart-Wolfsburg engineering corridor programs where German OEMs validate next-generation kinematics for EU General Safety Regulation alignment.
- Latches:Die-cast aluminum housings are displacing steel in electric vehicle architectures where mass reduction targets intensify, with thin-wall casting expertise concentrated in European and Japanese supplier bases limiting geographic expansion options for competitors.
- Bolts:Precision-grade fasteners with specified torque retention characteristics secure latch-to-plate interfaces across temperature ranges.
- Fasteners:Secondary hardware components including spring retainers and adjustment shims complete assembly integration.
Today's leader: Lock Plates. Tomorrow's challenger: Latches.
Material:
Cost tier differentiation separates premium aluminum architectures from mass-market steel programs, with raw material volatility compressing margin predictability for stampers locked into annual OEM agreements.
- Steel:Zinc-coated high-strength grades dominate installed volume across mass-market vehicle programs, with price swings in coated steel inputs creating margin compression for suppliers without backward integration into raw material sourcing.
- Aluminum:Die-cast alloys enable 30-40% mass reduction in hood closure systems, with premium EV manufacturers specifying these architectures for range certification and foundries with automotive aluminum expertise capturing expanding share.
- Plastic:Glass-reinforced polymer components serve non-structural release handle and cable guide applications.
- Composite:Carbon fiber-reinforced materials occupy niche motorsport and ultra-premium segments where cost thresholds permit experimental architectures.
Steel commands current volume. Aluminum climbs the fastest.
End User:
Customer type concentration creates durable margin pools for suppliers with validated PPAP status, while aftermarket providers compete on inventory velocity rather than engineering content.
- OEMs:Original equipment manufacturers specify latch modules through long-term framework contracts with annual volume commitments, displacing spot purchasing and consolidating procurement decisions around fewer, larger supply agreements in German and Japanese engineering clusters.
- Aftermarket Providers:Digital parts-matching platforms compress distribution layers, enabling specialized distributors to capture margin pools previously held by traditional wholesale networks through inventory velocity models.
- Vehicle Assemblers:Contract manufacturing operations for emerging EV brands source validated latch architectures without internal engineering resources.
- Repair Shops:Independent service facilities drive replacement demand for collision-damaged closure systems through distributor channels.
OEMs anchor specification authority. Aftermarket providers gain digital leverage.
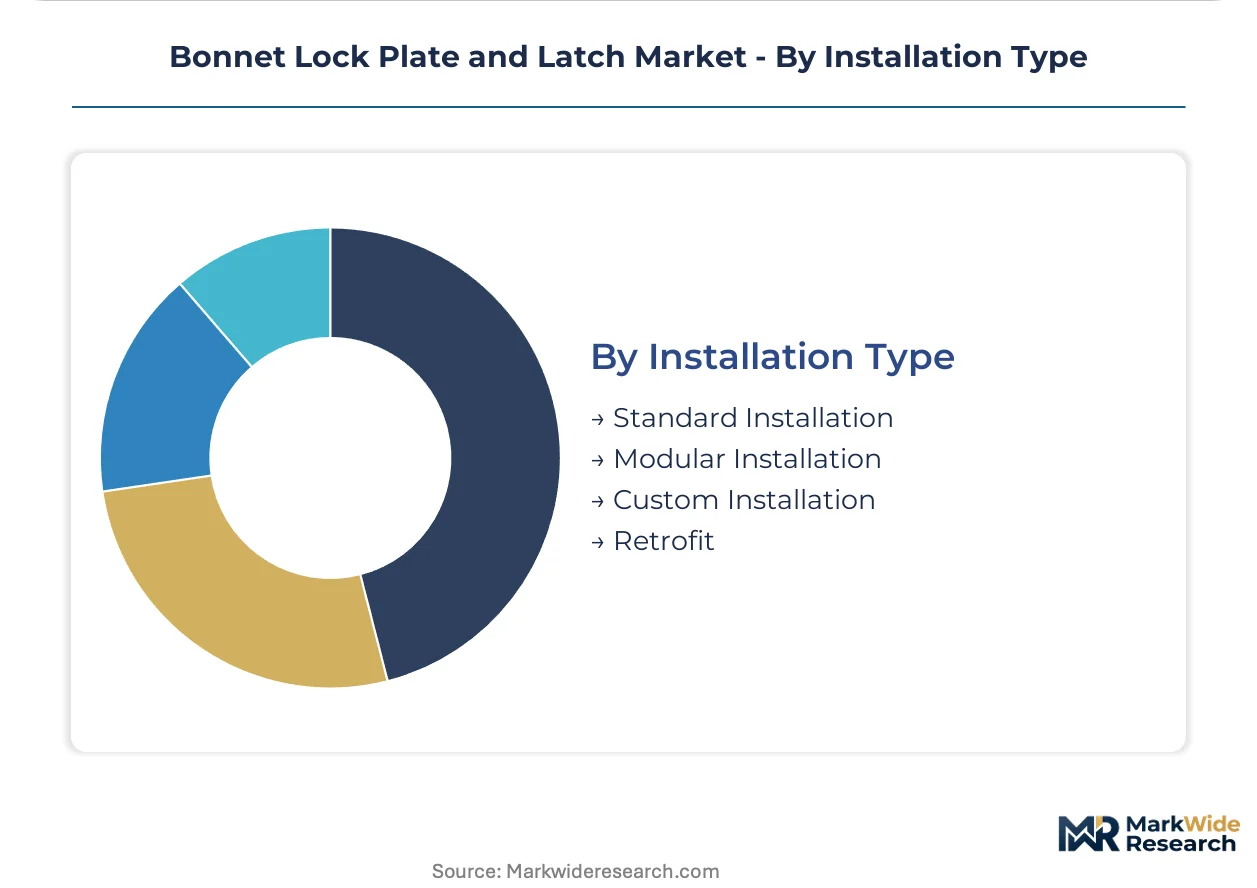
Installation Type:
Application complexity stratifies pricing across standard, modular, and custom architectures, with engineering validation timelines extending for non-standard configurations.
- Standard Installation:Fixed-position mounting interfaces designed for high-volume assembly line integration dominate mass-market production programs.
- Modular Installation:Pre-assembled latch-and-plate subsystems reduce line-side complexity for OEMs running mixed-model production.
- Custom Installation:Bespoke kinematics for low-volume specialty vehicles extend tooling amortization periods and strain working capital for mid-tier stampers.
- Retrofit:Post-production upgrade kits for regulatory compliance or performance modification occupy niche demand segments.
Modular Installation captures efficiency premiums. Custom Installation faces validation bottlenecks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are pulling aluminum latch production toward jurisdictions with lower energy costs for die-casting operations, while steel stamping capacity remains anchored near traditional automotive assembly corridors to minimize logistics exposure.
United States
NHTSA pedestrian safety mandates are accelerating aluminum latch procurement across Detroit Three vehicle programs. Federal Motor Vehicle Safety Standard No. 113 enforcement is tightening displacement thresholds for hood closure systems. Michigan's automotive engineering cluster around Detroit anchors validation testing for compliant architectures.
Germany
EU General Safety Regulation alignment is pre-qualifying next-generation latch kinematics for 2026 enforcement timelines. KBA type-approval processes are extending validation cycles for pedestrian head-impact compliance. Stuttgart-Wolfsburg engineering corridor concentrates R&D investment from premium OEMs.
China
MIIT homologation protocols are enforcing structural integrity thresholds equivalent to NHTSA and ECE standards for domestic vehicle sales. GB standards alignment is creating entry pathways for suppliers with validated PPAP status. Yangtze River Delta die-casting foundries are absorbing aluminum latch demand from European EV programs.
Japan
METI industrial policy is supporting lightweight closure system development for export-oriented vehicle platforms. JIS standards govern fastener torque retention specifications across temperature ranges. Nagoya-Toyota City manufacturing belt maintains captive stamping capacity for mass-market latch modules.
India
PLI scheme incentives for automotive component manufacturing are attracting tier-one suppliers to establish local die-casting operations. BIS certification requirements are harmonizing with UN R127 pedestrian protection benchmarks. Tamil Nadu's Chennai automotive cluster is emerging as a regional sourcing hub for Southeast Asian OEMs.
Bonnet Lock Plate and Latch Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue mechatronic integration and aluminum casting specialization to capture premium specification share. The supplier base stratifies across three maturity tiers: vertically integrated global module suppliers, regional stampers with captive tooling, and specialized foundries with thin-wall aluminum expertise. Competitive positioning hinges on PPAP validation status and long-term framework contract security. Primary competitive moves include backward integration into raw material sourcing and geographic expansion toward emerging EV production zones.
Among European-based suppliers, Kiekert AG and Brose Fahrzeugteile exemplify the premium-tier archetype through mechatronic integration capabilities. Magna International represents the scale-driven North American position with vertically integrated stamping and assembly operations. Shivani Locks occupies a specialist position within the India-based fabricator tier serving regional aftermarket and OEM replacement demand.
| Leading Market Players |
|---|
| Kiekert AG |
| Shivani Locks |
| Inteva Products |
| U-Shin Ltd. |
| IFB Automotive |
| Magna International |
| Strattec Security Corporation |
| Brose Fahrzeugteile |
| Aisin Seiki Co. Ltd. |
| Others |
Supply Flow & Price Mechanics
Zinc-coated high-strength steel sheet flows from European and East Asian mills through tier-one stampers to OEM assembly plants, with annual price agreements locking in material costs that fluctuate on London Metal Exchange indices and regional energy tariffs. Aluminum die-cast alloys command 30-40% mass-reduction premiums in electric vehicle programs, concentrating margin capture among foundries with thin-wall casting expertise in Germany and Japan.
Pricing Analysis
Direct-to-OEM contract pricing dominates procurement, with long-term framework agreements displacing spot purchasing for validated PPAP suppliers. Three-tier pricing structure across premium aluminum architectures, standard steel modules, and economy-grade aftermarket components separates specification tiers by certification grade and volume scale. Pricing pressure stems from raw material volatility in coated steel inputs, compressing margins for stampers without backward integration. Mass-market OEMs exhibit highest price sensitivity, while premium EV manufacturers prioritize mass reduction over unit cost.
Supply Chain Analysis
PPAP certification gating restricts qualified supplier pools to tier-one manufacturers with validated production part approval process status in Germany, China, and Japan. Supply chains draw from zinc-coated steel mills, aluminum foundries, and precision fastener specialists, with die-casting talent scarcity limiting geographic expansion options. Single-source vulnerability concentrates in thin-wall aluminum casting expertise held by European and Japanese supplier bases. Distribution runs through OEM direct procurement channels and digital aftermarket platforms compressing traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with UN R127 pedestrian protection amendments and NHTSA Federal Motor Vehicle Safety Standard No. 113 enforcement tightening head-impact thresholds and driving architectural redesign cycles across major automotive production zones.
For Market Incumbents: Cement long-term framework contract security with platform-sharing OEM consortia through pre-qualified supplier status against anticipated enforcement timelines. Deepen captive die-casting operations in Europe to sustain margin control against emerging foundry competition from China's Yangtze River Delta. Prioritize mechatronic integration R&D to defend specification share in premium vehicle segments where electronic release actuation commands price premiums. For New Entrants and Emerging Players: Digital parts-matching platforms offer the lowest barrier to aftermarket penetration, enabling specialized distributors to capture margin pools through inventory velocity models rather than engineering content. Target India's PLI scheme incentives for automotive component manufacturing to establish regional die-casting operations serving Southeast Asian OEMs. Pursue GB standards alignment for MIIT homologation protocols as the entry pathway into China's domestic vehicle sales volume. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier stampers with captive tooling because buyer concentration among platform-sharing OEMs is consolidating procurement decisions around fewer, larger supply agreements. Focus acquisition screening on European and Japanese suppliers with validated PPAP status and thin-wall aluminum expertise. Watch NHTSA displacement threshold enforcement timelines as the inflection indicator for replacement demand acceleration in US-bound vehicle programs.| Strategic Initiative | Industry Significance |
|---|---|
| Die-Casting Capacity Expansion | Captures aluminum latch demand from European and Chinese EV programs seeking mass reduction certification. |
| Mechatronic Integration Development | Opens specification opportunities in premium segments where Brose Fahrzeugteile and Kiekert AG currently dominate. |
| PPAP Certification Investment | Secures validated supplier status for NHTSA and EU General Safety Regulation compliance programs. |
| Aftermarket Digital Platform Launch | Compresses distribution layers to capture margin pools from traditional wholesale networks serving repair shops. |
| Regional Manufacturing Footprint | Establishes local die-casting in India's Tamil Nadu cluster to serve PLI scheme incentives and Southeast Asian OEMs. |
Methodological Framework
Coverage spans Germany, United States, China, Japan, and India, with primary inputs from each automotive production zone combining interviews with tier-one supplier procurement directors, OEM platform engineers, aftermarket distributors, and die-casting operations managers. Secondary validation draws from NHTSA Federal Motor Vehicle Safety Standard filings, KBA type-approval databases, MIIT homologation records, vehicle production data, and SEC filings from listed automotive suppliers. Bottom-up volume modeling triangulates against top-down market sizing across component type, material, and end-user segments.
Granularity-level modeling operates at the intersection of vehicle program, propulsion architecture, and regional regulatory cluster, with aluminum versus steel material substitution tracked separately for ICE and electric vehicle platforms. CAGRs derive from segment-level volume projections weighted by content-per-vehicle assumptions and regional production forecasts across the analysis window. Forecast inputs incorporate pedestrian safety regulation enforcement timelines, platform-sharing consortium procurement patterns, and die-casting capacity expansion announcements.
Raw material price volatility, regulatory delay risk, and EV platform volume shortfalls are the dominant revision risks warranting model adjustment. Forecasts reflect documented assumptions on material substitution rates and OEM dual-sourcing behavior. A model refresh is warranted upon material change in UN R127 amendment adoption schedules or NHTSA enforcement discretion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
North America Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Interior Materials Market
Automotive Interior & Exterior
Weatherstrip Market
Automotive Interior & Exterior
China Automotive Sunroof Market
Automotive Interior & Exterior
Car Canopies Market
Automotive Interior & Exterior
Automotive Woven Upholstery Market
Automotive Interior & Exterior
Automotive Glove Box Market
Automotive Interior & Exterior
Light Weight Automotive Body Panels Market
Automotive Interior & Exterior
Automotive Trim Market
Automotive Interior & Exterior
Automotive Overhead Console Market
Automotive Interior & Exterior
Automotive Decorative Exterior Trim Market
Automotive Interior & Exterior
Germany Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Seating Systems Market
Automotive Interior & Exterior
Automotive Electrically Adjustable Outside Rear View Mirror (ORVM) Market
Automotive Interior & Exterior
Global Smart Tailgate Market
Automotive Interior & Exterior
Automotive Leather Upholstery Market