
 Global Whole Grain and High Fiber Food Market | 2026-2036
Global Whole Grain and High Fiber Food Market Size, Share, and Industry Trends Forecast 2026-2036
Global Whole Grain and High Fiber Food Market Outlook
Refined wheat flour is recalibrating cost structures as whole grain formulations replace it across bakery and cereal applications. General Mills leverages its milling infrastructure to sustain North American supply consistency for oat and barley inputs. Nestlé S.A. anchors European distribution through specialized nutrition channels, while Cargill competes as a bulk ingredient supplier to private-label manufacturers.
Whole grain and high fiber food comprises minimally processed cereals, pseudocereals, and legumes retaining bran, germ, and endosperm, typically delivering three grams or more dietary fiber per serving under AOAC analytical standards. These products serve metabolic health applications, glycemic management, and digestive wellness in consumer diets. High fiber cereal dominates shelf space in conventional retail, while online retailers represent the fastest-growing distribution channel as direct-to-consumer subscription models expand. Granola bars concentrate margin pools through premium positioning and portable convenience formats.
The FDA's Nutrition Facts labeling rules and the USDA Dietary Guidelines for Americans shape fiber content claims and school nutrition procurement standards. EFSA health claim regulations in Europe enforce strict substantiation for beta-glucan and whole grain cardiovascular benefit statements. Stakeholders must monitor evolving Codex Alimentarius fiber definition harmonization efforts and calibrate formulation investments against divergent transatlantic compliance thresholds.
Market Dynamics
The FDA's updated dietary fiber definition under Nutrition Facts labeling rules is forcing reformulation across bakery and cereal categories as manufacturers recalibrate fiber content claims against AOAC analytical standards.
Growth Catalysts
- USDA Dietary Guidelines for Americans:Federal nutrition standards mandate whole grain servings in school meal programs, creating institutional procurement pull for certified products.
- India:Government nutrition programs and urbanization expand the addressable consumer base for fortified staples in tier-1 and tier-2 cities.
- Direct-to-consumer subscription models:Online retailers deploy recurring delivery platforms for granola bars and breakfast cereals, locking in predictable volume.
Market Restraints
- Oat and barley input costs:Weather volatility in North American growing regions creates margin compression for mill-dependent manufacturers.
- EFSA health claim substantiation:Strict cardiovascular benefit documentation requirements for beta-glucan statements limit European marketing flexibility.
- Refined wheat flour substitution:Lower-cost alternatives retain share in price-sensitive private-label bakery applications.
Strategic Opportunities
- Brazil:Underpenetrated whole grain consumption in urban centers offers white space for fortified bread and pasta introduction.
- Japan:METI-backed functional food frameworks create regulatory runway for glycemic management positioning of barley-based products.
- Plant protein convergence:Formulators combine high-fiber grains with legume isolates to capture dual-trend demand in meat alternatives.
Industry Challenges
- AOAC fiber analytical certification:Laboratory validation timelines delay new product launches by six to eighteen months.
- Legacy milling infrastructure:Retrofitting equipment for whole grain processing requires capital deployment that mid-tier bakeries struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Whole Grain and High Fiber Food Market |
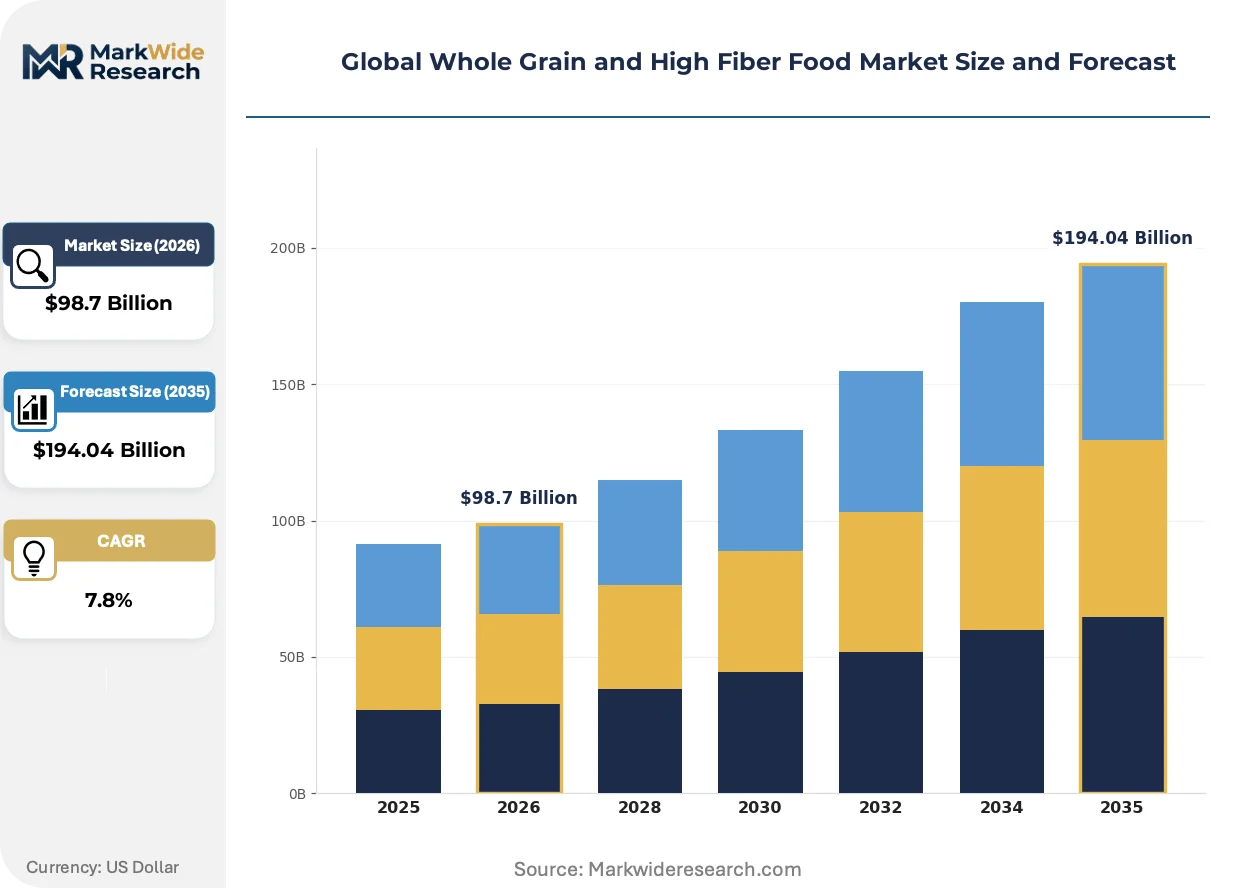
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $194.04 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Grain Bread, High Fiber Cereal, Granola Bars, Oatmeal End User: Health-Conscious Consumers, Fitness Enthusiasts, Diabetics, Families Distribution Channel: Supermarkets, Health Food Stores, Online Retailers, Specialty Shops Packaging Type: Bags, Boxes, Tetra Packs, Bulk Packaging |
| Companies Covered | Kellogg Company, Mondelez International, General Mills, Bob's Red Mill, Post Holdings, Nestlé S.A., Cargill, The Kraft Heinz Company, PepsiCo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Whole Grain and High Fiber Food Market Strategic Shifts
Formulation science and distribution infrastructure are converging to redefine how fiber claims reach consumers, with regulatory precision and supply chain proximity becoming competitive differentiators.
Sprouted grain processing is integrating enzymatic activation techniques that reduce phytic acid while preserving bran integrity. Artisanal bakeries and premium cereal manufacturers adopt these systems to support digestibility claims. The technology is integrating clean-label positioning into mainstream retail channels previously dominated by conventional milling.
REACH chemical safety protocols in Europe now govern processing aids and fortification compounds used in grain handling facilities. Manufacturers face expanded documentation requirements for novel fiber isolates. The regulation is compressing formulation timelines as R&D teams await ECHA hazard assessments before scaling production.
Subscription-based replenishment models for breakfast cereals and snack bars are displacing conventional supermarket stocking patterns. Urban professionals in Seoul and Singapore drive volume through mobile-first ordering platforms. This behavioral shift concentrates demand forecasting risk with direct-to-consumer brands holding inventory rather than traditional retailers.
Global Whole Grain and High Fiber Food Market Segmentation
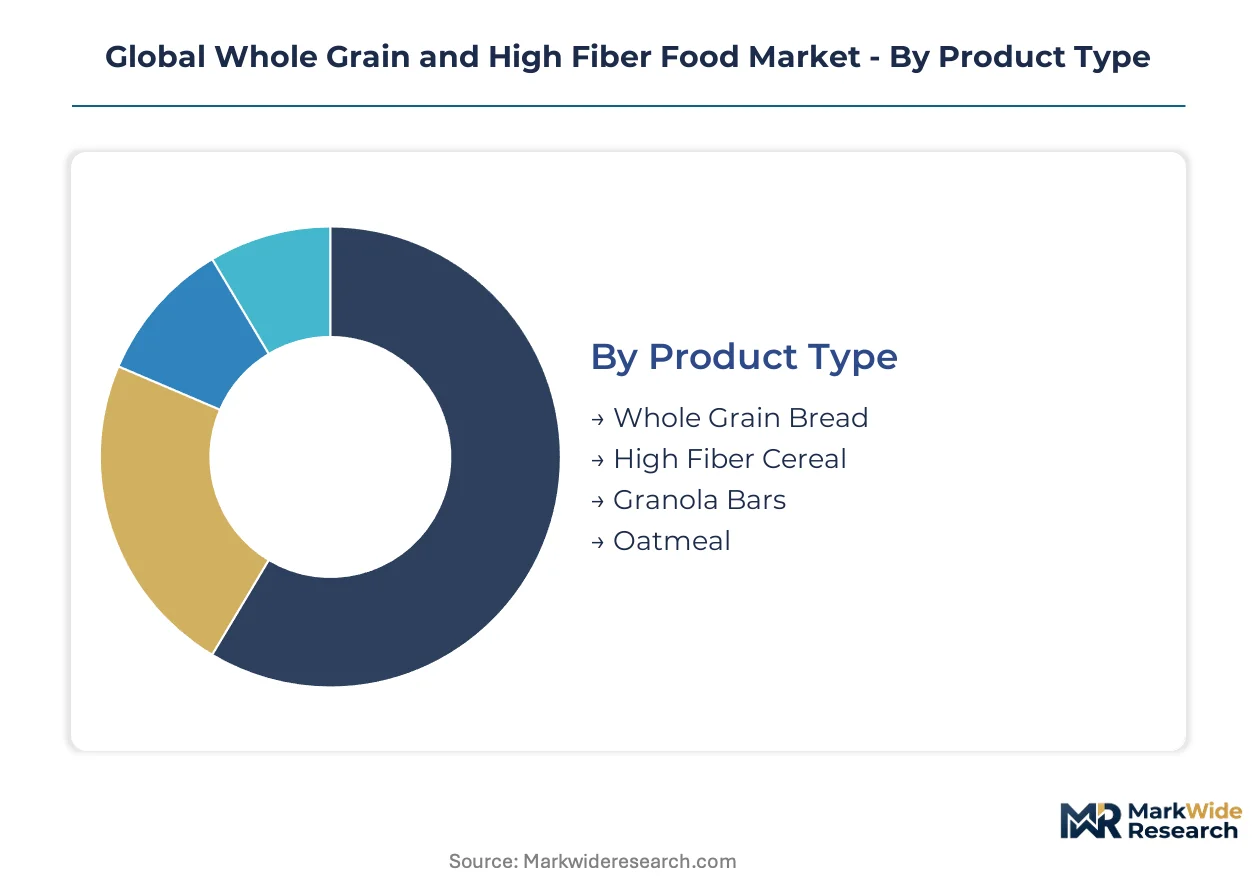
Product differentiation in whole grain and high fiber foods hinges on processing intensity and fiber retention rates. Segment-specific capital requirements determine which manufacturers can compete across bakery, cereal, and snack applications.
Product Type:
Capital intensity peaks with whole grain bread production, where legacy milling infrastructure requires substantial retrofitting for bran and germ retention.
- Whole Grain Bread:Formulations retaining all three kernel layers demand stone-milling or modified roller systems with higher maintenance schedules. Commercial bakeries in Germany and the United States are replacing refined flour lines to meet FDA whole grain labeling thresholds.
- High Fiber Cereal:Extrusion and flaking equipment represents moderate capital outlay compared to bread systems, with fiber fortification occurring at the coating or blending stage. Breakfast cereal manufacturers in the United Kingdom concentrate volume around oat-based clusters that qualify for EFSA beta-glucan cardiovascular claims.
- Granola Bars:Cold-press binding and enrobing lines require lower upfront investment than thermal processing equipment.
- Oatmeal:Steel-cut and rolled oat milling uses standardized equipment with established supply chains from Canadian and Australian growing regions.
Most installed capacity flows through high fiber cereal. Expansion is steepest in granola bars.
End User:
Customer acquisition costs vary sharply across health motivation levels, with clinical need segments commanding premium pricing power.
- Health-Conscious Consumers:This segment drives mainstream retail placement through scanner data velocity. Urban professionals in Seoul and Singapore subscribe to direct-to-cereal replenishment platforms that lock in predictable quarterly volume.
- Fitness Enthusiasts:Protein-fiber convergence products target this group's macronutrient tracking behavior. Sports nutrition brands in Australia formulate granola bars with isolated pea protein to capture dual-trend demand.
- Diabetics:Glycemic index certification requirements add regulatory compliance costs that filter out smaller formulators.
- Families:Multi-serve packaging and child-friendly palatability specifications dominate purchasing criteria in this price-sensitive segment.
Health-conscious consumers anchor current revenue. Diabetics are gaining share fastest.
Distribution Channel:
Channel selection determines working capital intensity, with inventory risk shifting from retailers to manufacturers in direct-to-consumer models.
- Supermarkets:Slotting fees and promotional calendars strain cash flow for emerging brands. Major chains in France and Italy reserve end-cap positioning for products with FSSAI or EFSA-approved fiber claims.
- Health Food Stores:Curated assortments and educated staff support premium pricing for sprouted grain and ancient wheat varieties.
- Online Retailers:Subscription algorithms reduce customer acquisition costs while concentrating demand forecasting risk with brand owners rather than distributors.
- Specialty Shops:Artisanal bakeries and regional mills serve localized preferences with limited distribution radius.
Supermarkets hold the deepest shelf space. Online retailers are climbing the fastest.
Packaging Type:
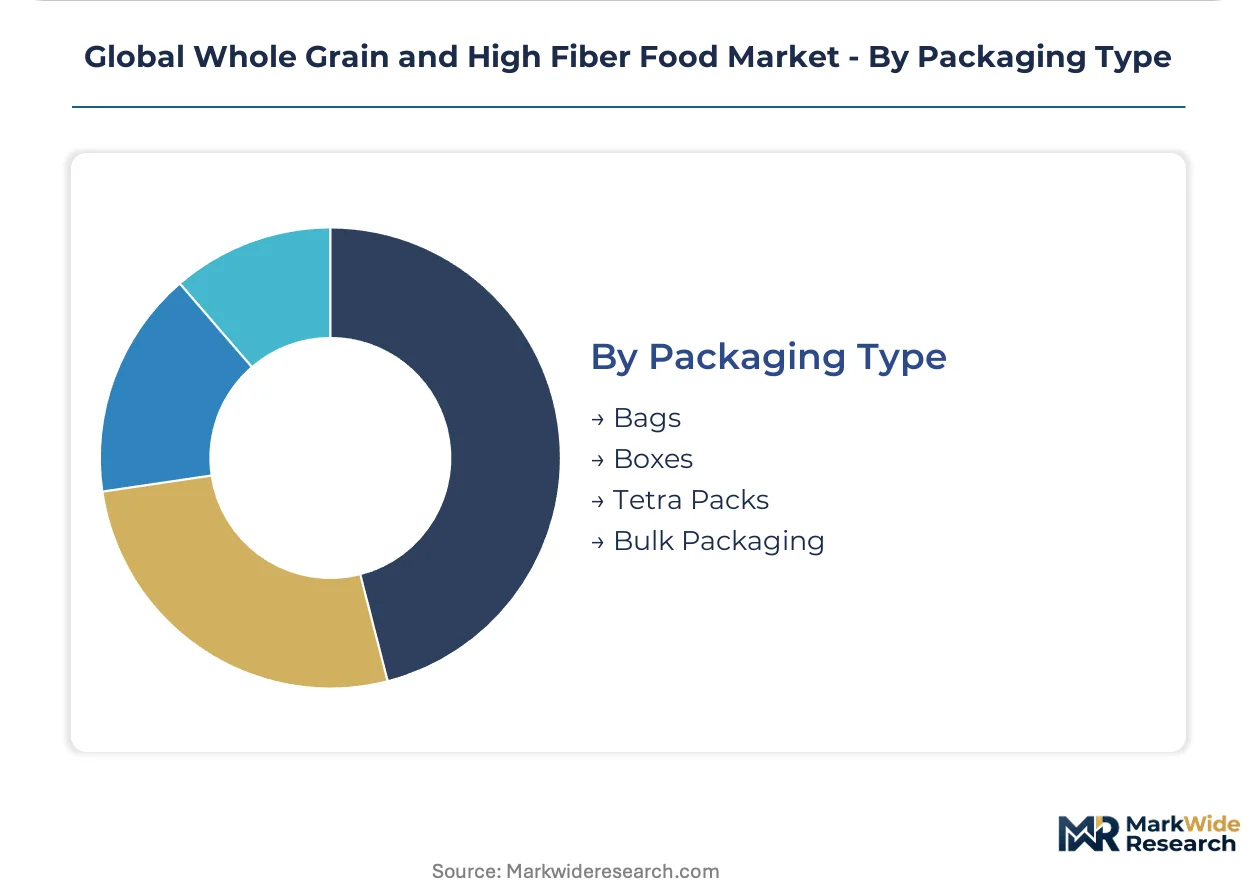
Material science investments separate shelf-stable formats from those requiring climate-controlled logistics.
- Bags:Flexible packaging with high-barrier films protects whole grain flours from oxidation in extended distribution.
- Boxes:Structural integrity for cereal and granola bars supports retail stacking height and shipping density optimization.
- Tetra Packs:Aseptic filling lines for ready-to-drink grain beverages represent the highest capital barrier in this category.
- Bulk Packaging:Foodservice and institutional channels in India and Brazil use sack formats for fortified flour distribution through government nutrition programs.
Boxes dominate current production lines. Tetra packs show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis-St. Paul anchors North American whole grain milling capacity with integrated oat processing facilities serving bakery and cereal manufacturers across the continent.
United States
FDA's updated Nutrition Facts labeling rules drive reformulation across Minneapolis and Chicago processing corridors. The USDA Dietary Guidelines for Americans mandate whole grain servings in school meal programs, creating institutional procurement pull. General Mills leverages its milling infrastructure to sustain supply consistency for oat and barley inputs across the Upper Midwest.
Germany
Commercial bakeries in Munich and Hamburg replace refined flour lines to meet EFSA whole grain labeling thresholds. REACH chemical safety protocols govern processing aids and fortification compounds used in grain handling facilities. Stone-milling clusters in Bavaria retrofit legacy equipment for bran and germ retention to serve premium retail channels.
India
Government nutrition programs and urbanization expand the addressable consumer base for fortified staples in Mumbai and Bangalore. FSSAI fiber content claims reshape formulation standards for packaged bread and breakfast cereals. Tier-1 and tier-2 cities concentrate demand forecasting for bulk institutional distribution through government procurement channels.
Japan
METI-backed functional food frameworks create regulatory runway for glycemic management positioning of barley-based products in Tokyo and Osaka. Urban professionals drive volume through mobile-first ordering platforms for direct-to-consumer cereal replenishment. Kansai region mills specialize in beta-glucan extraction for cardiovascular health claim substantiation.
Brazil
Underpenetrated whole grain consumption in São Paulo and Rio de Janeiro urban centers offers white space for fortified bread and pasta introduction. ANVISA governs novel fiber isolate approvals for bakery applications. Government nutrition programs in the Southeast region expand distribution infrastructure for sack-format institutional flour.
Global Whole Grain and High Fiber Food Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers retrofit legacy milling infrastructure for whole grain processing. The market structures around three tiers: multinational CPG conglomerates with captive milling assets, mid-tier regional bakeries with specialized nutrition positioning, and private-label suppliers competing on bulk ingredient cost. Strategic archetypes include integrated mill-to-retail operators, functional nutrition specialists, and commodity grain traders. M&A activity and backward integration into oat and barley sourcing represent the dominant competitive moves.
Within the integrated CPG tier, General Mills and Nestlé S.A. exemplify multinational operators with established milling infrastructure and specialized nutrition distribution channels. Cargill occupies a position among bulk ingredient suppliers serving private-label manufacturers with oat and barley inputs. These three entities represent distinct archetypes: captive supply chain control, European functional nutrition anchoring, and commodity-scale raw material provision.
| Leading Market Players |
|---|
| Kellogg Company |
| Mondelez International |
| General Mills |
| Bob's Red Mill |
| Post Holdings |
| Nestlé S.A. |
| Cargill |
| The Kraft Heinz Company |
| PepsiCo |
| Others |
Value Chain & Pricing Dynamics
Oat and barley input costs transmit volatility from North American growing regions through three distinct pricing tiers, with premium whole grain bread absorbing weather-driven premiums while private-label cereal manufacturers face margin compression at the economy tier.
Pricing Analysis
Input-cost pass-through operates asymmetrically across the value chain. Three-tier pricing structure across premium, standard, and economy levels separates stone-milled artisanal bread from extruded cereal clusters and bulk institutional flour. Certification under FDA whole grain labeling thresholds commands measurable premiums in retail channels. Pricing pressure stems from refined wheat flour substitution in price-sensitive bakery applications. Families exhibit highest price sensitivity, while health-conscious consumers in direct-to-subscription models show lowest elasticity.
Supply Chain Analysis
Workforce availability constraints in Minneapolis-St. Paul milling corridors and Bavarian stone-milling clusters limit capacity expansion timelines. Supply concentrates in the United States, Canada, and Australia for oat inputs, with India and Brazil emerging for fortified wheat derivatives. Raw material dependencies center on beta-glucan-rich barley, high-protein wheat varieties, and sprouted grain feedstocks. Single-source vulnerability runs through Upper Midwest oat processing infrastructure. Distribution runs through supermarket slotting agreements, though online subscription models concentrate inventory risk with brand owners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Whole Grain and High Fiber Food Market functions as a stable compounder, with regulatory mandates for school nutrition programs and FDA labeling standards generating predictable institutional procurement volume.
For Market Incumbents: To counter margin compression from weather-driven oat and barley volatility, deploy backward integration into Canadian and Australian growing regions to secure supply consistency. Lock in multi-year offtake agreements with tier-1 grain cooperatives. Invest in AOAC-certified laboratory infrastructure to compress fiber analytical validation timelines and accelerate new product launches. For New Entrants and Emerging Players: Sprouted grain processing technology offers a technology-first wedge into premium retail channels previously dominated by conventional milling. Target underpenetrated urban centers in Brazil for fortified bread and pasta introduction. Capture glycemic management positioning in Japan through METI functional food frameworks. Deploy mobile-first subscription platforms in Seoul and Singapore to bypass supermarket slotting barriers. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier regional bakeries with specialized nutrition positioning because legacy milling infrastructure retrofitting requirements create capital barriers that filter out smaller competitors. Five-to-ten year viability hinges on regulatory tailwinds from school nutrition procurement standards. Watch for AOAC fiber definition harmonization at Codex Alimentarius as the inflection signal for cross-border formulation scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oat Sourcing | Captive supply from Canadian prairies insulates margin from Upper Midwest weather volatility. |
| AOAC Laboratory Certification Investment | In-house fiber validation compresses product launch timelines from eighteen months to under six. |
| Direct-to-Consumer Subscription Launch | Mobile-first platforms in Seoul and Singapore bypass supermarket slotting fee structures. |
| Sprouted Grain Processing Adoption | Enzymatic activation reduces phytic acid while preserving bran integrity for clean-label positioning. |
| EFSA Beta-Glucan Health Claim Substantiation | Cardiovascular benefit documentation unlocks premium pricing in Munich and Hamburg retail channels. |
Study Parameters
Direct dialogue with brand managers, category buyers at major retailers, supply planners at milling operations, and regulatory affairs specialists at CPG conglomerates grounded qualitative insights. Secondary validation drew from FDA Nutrition Facts labeling guidance documents, USDA Dietary Guidelines procurement data, EFSA health claim registers, FSSAI fortification standards, and customs records for oat and barley trade flows. Bottom-up volume modeling triangulated against top-down expenditure analysis across the projection horizon.
Segment-level outputs across product type, end user motivation, distribution channel, and packaging format fed into analytical framework calibration. CAGRs derived from regression analysis against historical volume trajectories, adjusted for regulatory inflection points and infrastructure investment cycles. Forecast inputs incorporated school nutrition program procurement schedules, urbanization rates in tier-1 and tier-2 Indian cities, and subscription platform penetration in East Asian metropolitan markets.
The model holds under stable regulatory enforcement of fiber content claims; deviation in Codex Alimentarius harmonization timelines or ECHA hazard assessment delays would shift formulation investment patterns. Forecasts reflect assumptions about continued USDA school meal program mandates and FDA labeling rule adherence. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Vegan DHA Market
Functional Food & Ingredients
Lovage Extract Market
Functional Food & Ingredients
South America Omega-3 PUFA Market
Functional Food & Ingredients
Omega 3 PUFA Market
Functional Food & Ingredients
Asia-Pacific Omega3 PUFA Market
Functional Food & Ingredients
North America Pea Protein Ingredients Market
Functional Food & Ingredients
Refined Functional Carbohydrates Market
Functional Food & Ingredients
Prickly Pear Fruit Metabolic Health Ingredients Market
Functional Food & Ingredients
APAC Heart Health Functional Food Market
Functional Food & Ingredients
Europe Prebiotic Ingredient Market
Functional Food & Ingredients
Mediterranean Cognitive-First Ingredient Systems Market
Functional Food & Ingredients
Functional Food Ingredients Market
Functional Food & Ingredients
Poultry Probiotic Ingredients Market
Functional Food & Ingredients
Functional Ingredients Market
Functional Food & Ingredients
Essential Fatty Acids Market
Functional Food & Ingredients
Healthy Fats Low Carb Market