
 Africa Omega-3 PUFA Market | 2026-2036
Africa Omega-3 PUFA Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Omega-3 PUFA Market Outlook
Qualified marine biochemists and aquaculture technicians is reorganizing supply reliability across the Africa Omega-3 PUFA landscape. BASF SE leverages its global fatty acid distillation expertise to secure pharmaceutical-grade EPA and DHA supply lines into North African markets. DSM sustains competitive pressure through microalgae fermentation platforms that reduce dependence on wild-catch fish stocks. Croda International anchors its position via lipid purification technologies tailored to African humidity and temperature conditions during transport.
Omega-3 polyunsaturated fatty acids are long-chain lipids—principally eicosapentaenoic acid (EPA) and docosahexaenoic acid (DHA)—extracted through molecular distillation or cold-pressing of marine biomass, functioning as essential membrane components and anti-inflammatory precursors in human, animal, and pharmaceutical applications. Fish oil dominates volume throughput due to established coastal processing infrastructure in Morocco and Senegal, yet algal oil captures margin expansion as vegan certification requirements intensify among West African dietary supplement distributors. Pharmaceutical-grade formulations command premium positioning through cold-chain packaging and stability-tested bulk containers, while animal feed applications in Egyptian aquaculture and South African poultry operations absorb mid-tier fish oil volumes.
South Africa's Department of Health fortification mandates, Nigeria's National Agency for Food and Drug Administration and Control (NAFDAC) import certification protocols, and Ghana's Food and Drugs Authority (FDA) labeling requirements collectively elevate compliance costs for uncertified suppliers while creating preferential access for GMP-accredited manufacturers. The country's national pharmaceutical regulator in Kenya and Tanzania's Bureau of Standards are converging toward harmonized East African Community quality benchmarks for omega-3 potency claims. Stakeholders must monitor which regional bloc—ECOWAS, EAC, or SADC—first establishes mutual recognition for omega-3 analytical testing to preempt capital misallocation across redundant certification pathways.
Market Dynamics
Algal fermentation platforms are restructuring supply economics across the Africa Omega-3 PUFA landscape, compressing reliance on Moroccan and Senegalese fish oil processing infrastructure while opening new sourcing corridors for vegan-certified concentrates.
Growth Catalysts
- NAFDAC import certification protocols:Nigeria's pharmaceutical-grade import requirements are filtering uncertified suppliers and accelerating GMP-accredited manufacturer penetration in Lagos and Abuja distribution channels.
- Aquaculture feed intensification:Egyptian tilapia and South African poultry operations are absorbing mid-tier fish oil volumes as protein producers integrate omega-3 into finished feed formulations.
- Cold-chain packaging advances:Stability-tested bulk containers are enabling pharmaceutical-grade EPA and DHA to reach North African markets without potency degradation during Saharan transit routes.
Market Restraints
- Wild-catch stock dependency:Moroccan and Senegalese coastal processing infrastructure remains tethered to volatile sardine and anchovy harvest cycles, creating input cost instability for bulk fish oil concentrates.
- Harmonization friction:Divergent ECOWAS, EAC, and SADC analytical testing standards force manufacturers to maintain redundant certification pathways, elevating compliance overhead for cross-bloc shipments.
- Algal oil production scale:Microalgae fermentation capacity in Africa remains concentrated in pilot-scale facilities, constraining volume throughput for vegan-certified infant nutrition applications.
Strategic Opportunities
- Ghana aquaculture feed gap:The country's expanding tilapia farming sector lacks dedicated omega-3 premix suppliers, creating first-mover positioning for certified concentrate distributors.
- Kenya-Tanzania EAC convergence:Harmonized East African Community quality benchmarks for potency claims will streamline cross-border trade once mutual recognition protocols activate.
- Direct-to-clinic distribution:Nigerian maternal health programs and South African prenatal care networks are bypassing traditional pharmacy channels for bulk EPA/DHA procurement.
Industry Challenges
- Qualified marine biochemist scarcity:Lipid purification and molecular distillation expertise concentrates in South African and Moroccan technical institutes, creating recruitment bottlenecks for Ghanaian and Nigerian processing facilities.
- GMP accreditation timelines:Ghana's Food and Drugs Authority and Kenya's national pharmaceutical regulator maintain extended facility inspection queues, delaying market entry for new concentrate suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Omega-3 PUFA Market |
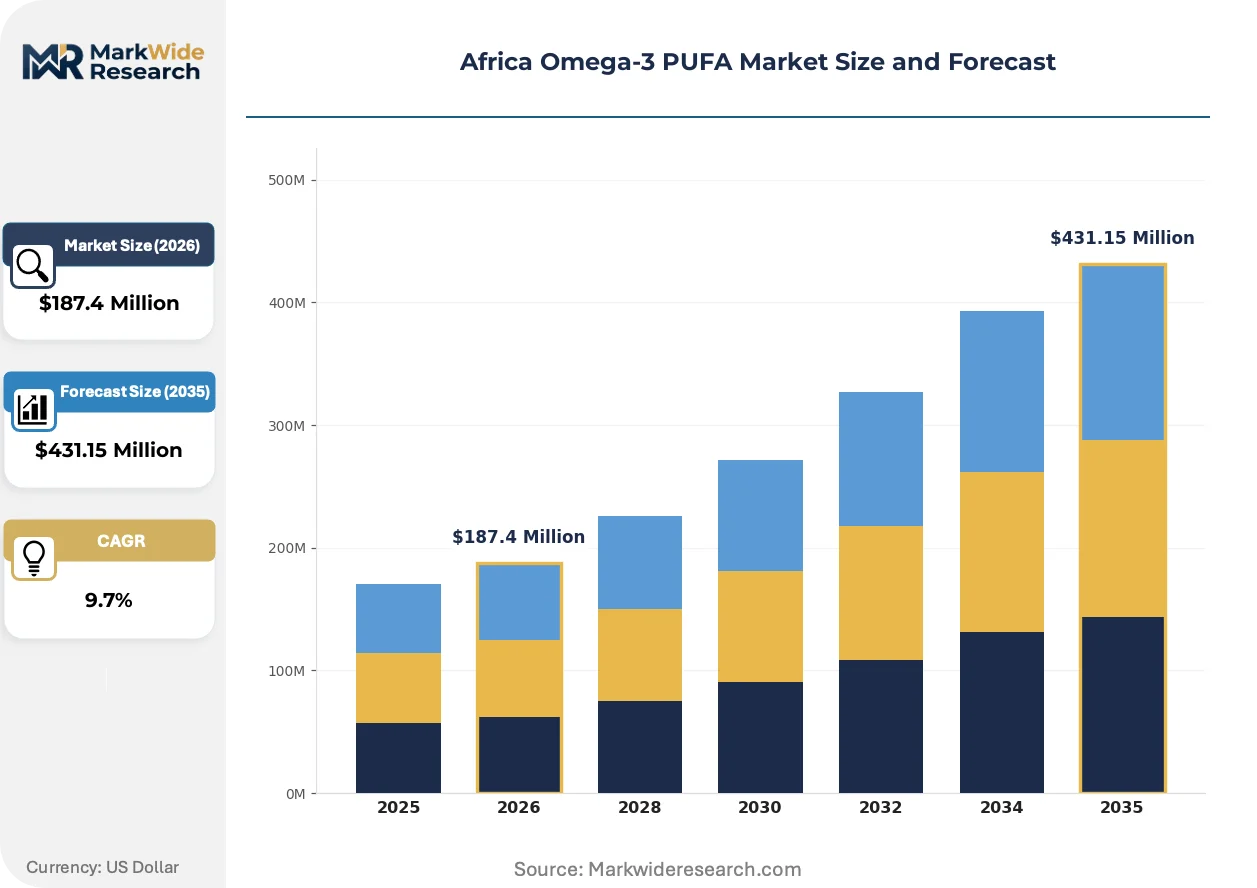
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Oil, Algal Oil, Krill Oil, Other Oils Application: Food & Beverages, Dietary Supplements, Animal Feed, Pharmaceuticals Packaging Type: Bottles, Capsules, Bulk Containers, Sachets Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | BASF SE, DSM, Croda International, Arista Industries, Omega Protein Corporation, A&Z Food Additives, Cargill, ADM, Corbion, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Omega-3 PUFA Market Strategic Shifts
Technology convergence across fermentation engineering and lipid purification is compressing traditional fish oil dominance while regulatory harmonization efforts reshape competitive access across African economic blocs.
Microalgae fermentation systems optimized for EPA and DHA output are displacing conventional marine extraction for vegan-certified dietary supplements. West African distributors in Lagos and Accra are prioritizing algal concentrates for infant nutrition portfolios. This shift is compressing margin structures for traditional fish oil traders dependent on Moroccan processing infrastructure.
South Africa's Department of Health has tightened food fortification standards for omega-3 potency claims in dietary supplements. Manufacturers must now demonstrate stability-tested certification through cold-chain documentation. Premium pharmaceutical-grade suppliers with GMP-accredited facilities are capturing preferential shelf placement in Johannesburg and Cape Town retail channels.
Certification-driven procurement is restructuring buyer-supplier relationships across the continent. Nigerian infant nutrition formulators and Ghanaian aquaculture feed producers are consolidating vendor lists around GMP-accredited, stability-certified concentrate suppliers. This concentration is most visible in Lagos procurement offices, where technical teams now mandate third-party potency verification before contract execution.
Africa Omega-3 PUFA Market Segmentation
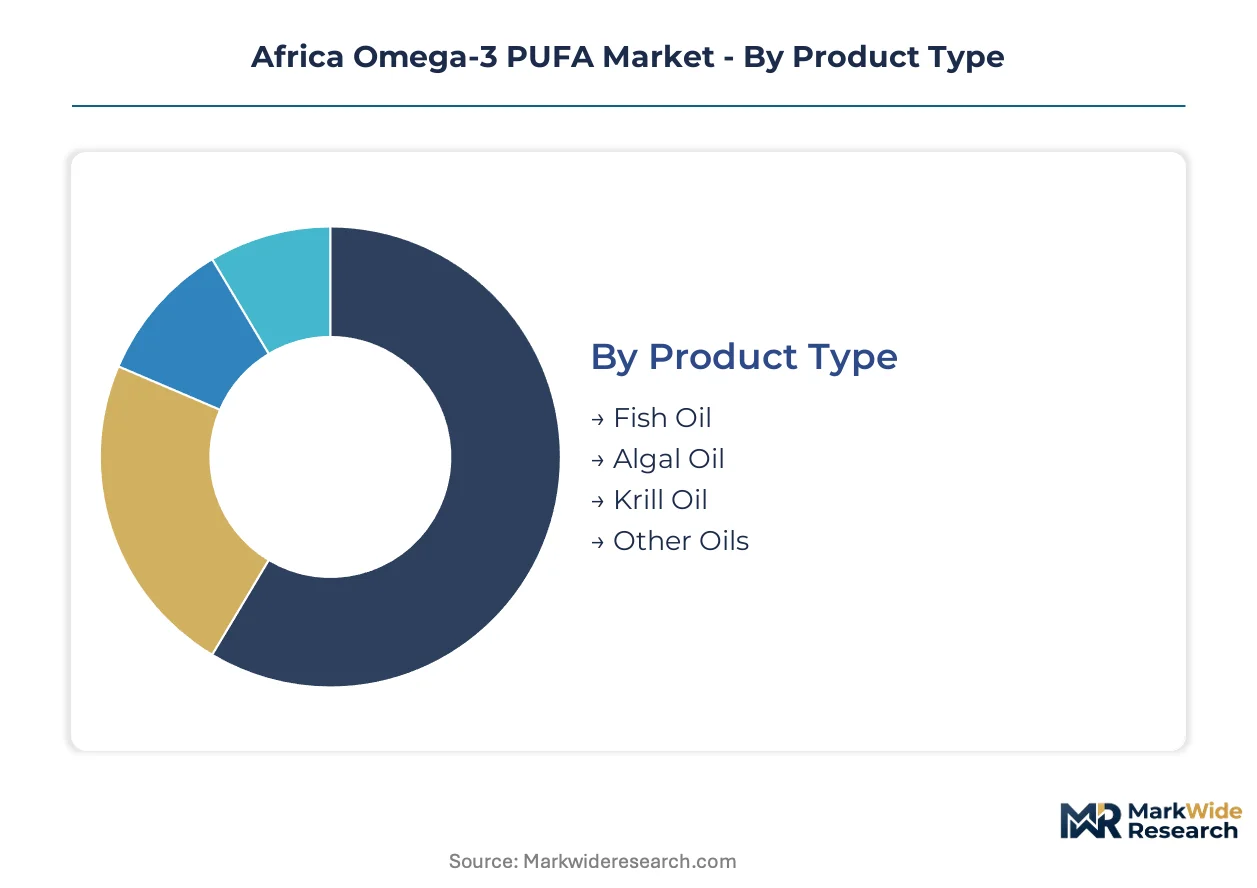
Segmentation in the Africa Omega-3 PUFA market reveals how certification requirements, cold-chain capabilities, and end-use specifications fragment procurement patterns across dietary supplements, aquaculture feed, and pharmaceutical applications. Margin pools concentrate in pharmaceutical-grade concentrates and algal oil for infant nutrition, while bulk fish oil serves price-sensitive animal feed operations.
Product Type:
Premium extraction technologies and vegan certification protocols concentrate margin pools in algal and krill oil segments, leaving fish oil as a volume-driven commodity play dependent on Moroccan and Senegalese coastal processing infrastructure.
- Fish Oil:Long-chain EPA and DHA concentrates extracted through molecular distillation of sardine and anchovy biomass dominate volume throughput. Egyptian aquaculture feed mills and South African poultry integrators absorb bulk quantities, though volatile wild-catch cycles in Moroccan waters create input cost instability for concentrate suppliers.
- Algal Oil:Fermentation-derived EPA and DHA from microalgae platforms enables vegan certification for West African infant nutrition distributors. Lagos and Accra procurement offices now mandate algal concentrates for premium maternal health portfolios, compressing margins for traditional fish oil traders.
- Krill Oil:Phospholipid-bound omega-3 from Antarctic biomass commands niche positioning in South African high-end supplement retail.
- Other Oils:Flaxseed and chia-derived ALA sources serve vegetarian positioning in Kenya and Tanzania health food channels.
Fish oil holds installed capacity across North African coastal infrastructure. Algal oil is rotating up the share rankings as Nigerian NAFDAC protocols filter uncertified marine suppliers.
Application:
Regulatory stringency and end-use performance requirements create tiered margin structures, with pharmaceutical and infant nutrition applications capturing premium positioning while animal feed absorbs commoditized bulk volumes.
- Dietary Supplements:Encapsulated EPA/DHA concentrates for adult wellness and prenatal care drive GMP-accredited procurement in Johannesburg and Cape Town retail channels. South Africa's Department of Health fortification mandates now require stability-tested certification through cold-chain documentation, elevating compliance barriers for uncertified importers.
- Animal Feed:Mid-tier fish oil integration into Egyptian tilapia farming and South African poultry operations emphasizes cost-per-unit protein enhancement over potency verification. Ghana's expanding aquaculture sector lacks dedicated omega-3 premix infrastructure, creating supply gaps for certified concentrate distributors.
- Pharmaceuticals:Clinical-grade EPA/DHA for cardiovascular and neurological therapeutics demands pharmaceutical-grade cold-chain packaging through Saharan transit routes.
- Food & Beverages:Functional fortification of dairy and bakery products remains underdeveloped outside South African urban retail clusters.
Dietary supplements command pricing premiums through certification layering. Animal feed is climbing the fastest as Egyptian protein producers scale omega-3 integration.
Packaging Type:
Temperature stability requirements and distribution economics concentrate investment in bulk containers for B2B feed and pharmaceutical channels, while unit-dose formats serve fragmented retail access.
- Bulk Containers:Stability-tested pharmaceutical-grade totes enable potency-preserving shipment of EPA/DHA concentrates across North African markets. BASF SE and DSM leverage this format for GMP-accredited supply into Egyptian and Moroccan manufacturing facilities.
- Capsules:Soft-gel and hard-shell encapsulation dominates Nigerian infant nutrition and South African prenatal care procurement, with Lagos distributors consolidating vendor lists around third-party potency verification.
- Bottles:Liquid oil retail formats concentrate in South African supermarket and health store channels.
- Sachets:Single-serve powder sachets for pediatric fortification are gaining traction in Ghanaian and Kenyan direct-to-clinic distribution models.
Bulk containers anchor pharmaceutical and feed supply contracts. Capsules are gaining share fastest as Nigerian maternal health programs bypass traditional pharmacy channels.
Distribution Channel:
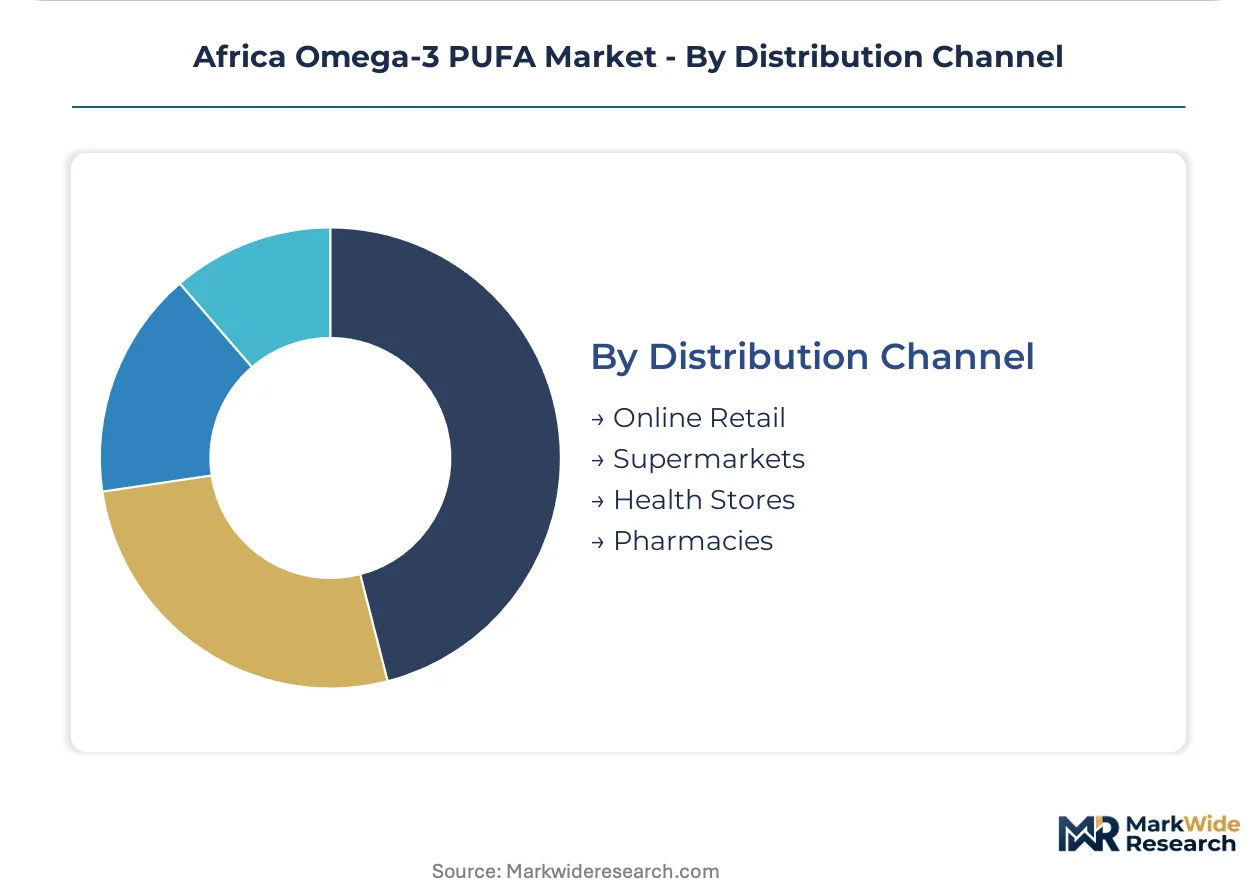
Channel selection reflects end-use certification requirements and cold-chain reliability, with pharmacies and health stores capturing premium positioning while online retail fragments price discovery.
- Pharmacies:GMP-accredited EPA/DHA concentrates for prenatal and therapeutic applications command preferential shelf placement in Johannesburg, Cape Town, and Lagos pharmacy chains. South Africa's tightened fortification standards filter uncertified products from this channel.
- Health Stores:Specialty retailers in Accra and Nairobi curate vegan-certified algal oil portfolios for affluent urban consumers seeking infant nutrition alternatives.
- Supermarkets:Mass-market fish oil capsules and liquid formats serve price-sensitive South African and Egyptian household purchasing.
- Online Retail:E-commerce platforms fragment price transparency across West African markets, with Lagos-based distributors leveraging direct-to-consumer models for bulk concentrate procurement.
Pharmacies maintain certification-gated positioning for clinical-grade products. Online retail is expanding most quickly as Nigerian procurement teams consolidate vendor relationships through digital platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across the continent. North African markets prioritize pharmaceutical-grade cold-chain shipments through Saharan corridors, while West African procurement concentrates on infant nutrition algal concentrates and East African demand centers on harmonized cross-border feed formulations.
South Africa
Johannesburg and Cape Town retail channels absorb GMP-accredited EPA/DHA concentrates for prenatal and adult wellness applications. The Department of Health fortification mandates now require stability-tested certification through cold-chain documentation, elevating compliance barriers for uncertified importers. Premium pharmaceutical-grade suppliers capture preferential shelf placement in pharmacy chains.
Nigeria
Lagos and Abuja distribution channels drive pharmaceutical-grade import requirements that filter uncertified suppliers. NAFDAC certification protocols accelerate GMP-accredited manufacturer penetration, particularly for infant nutrition formulators consolidating vendor lists around third-party potency verification. Direct-to-clinic distribution models bypass traditional pharmacy channels for bulk maternal health procurement.
Egypt
Tilapia farming operations along the Nile Delta absorb mid-tier fish oil volumes as protein producers integrate omega-3 into finished feed formulations. The country's national pharmaceutical regulator maintains extended facility inspection queues, delaying market entry for new concentrate suppliers. Cold-chain packaging advances enable pharmaceutical-grade shipments to reach manufacturing facilities without potency degradation.
Ghana
The expanding tilapia farming sector lacks dedicated omega-3 premix suppliers, creating first-mover positioning for certified concentrate distributors. Accra procurement offices now mandate algal concentrates for premium maternal health portfolios, compressing margins for traditional fish oil traders. The Food and Drugs Authority labeling requirements elevate compliance costs while creating preferential access for accredited manufacturers.
Kenya
Nairobi health food channels serve vegetarian ALA positioning for affluent urban consumers. The national pharmaceutical regulator and Tanzania's Bureau of Standards are converging toward harmonized East African Community quality benchmarks for omega-3 potency claims. Mutual recognition protocols will streamline cross-border trade once activated.
Africa Omega-3 PUFA Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with multinational chemical conglomerates controlling pharmaceutical-grade supply lines while regional distributors capture niche vegan-certified segments. The structure rewards cold-chain capabilities and GMP accreditation over pure scale. Three archetypes dominate: fermentation-platform specialists, coastal fish oil processors, and lipid purification technology providers. Competitive moves concentrate on strategic partnerships for distribution access and portfolio diversification into algal-derived alternatives.
Within the integrated chemical tier, BASF SE and DSM exemplify divergent sourcing strategies—BASF leveraging global fatty acid distillation expertise while DSM sustains pressure through microalgae fermentation platforms. Croda International occupies a position among lipid purification specialists, with technologies tailored to African humidity and temperature conditions during transport. These three anchors represent the spectrum from marine extraction dependence to vegan-certified fermentation scale.
| Leading Market Players |
|---|
| BASF SE |
| DSM |
| Croda International |
| Arista Industries |
| Omega Protein Corporation |
| A&Z Food Additives |
| Cargill |
| ADM |
| Corbion |
| Others |
Value Chain & Pricing Dynamics
Algal fermentation concentrates displacing Moroccan fish oil volumes simultaneously redraw sourcing geography toward Nigerian infant nutrition distributors and compress margin structures for coastal processors tethered to volatile sardine harvest cycles. This substitution dynamic concentrates pricing power among GMP-accredited suppliers capable of vegan certification while fragmenting negotiation leverage for traditional bulk traders.
Pricing Analysis
Long-term offtake contracts anchor pharmaceutical-grade EPA and DHA procurement between BASF SE and North African manufacturing facilities, while spot transactions dominate Egyptian aquaculture feed channels. Price differentiation separates cold-chain-certified concentrates from uncertified bulk shipments, with Lagos procurement offices now mandating third-party potency verification before contract execution. Cost compression in mid-tier fish oil is intensifying because Ghanaian tilapia farmers prioritize cost-per-unit protein enhancement over stability documentation. Animal feed operations exhibit highest price sensitivity, whereas Nigerian maternal health programs demonstrate lowest sensitivity due to NAFDAC-mandated quality floors.
Supply Chain Analysis
Inventory lead times for pharmaceutical-grade concentrates extend across Saharan transit corridors, necessitating stability-tested bulk containers that preserve EPA and DHA potency through temperature excursions. Supply concentrates in Morocco, Senegal, and South Africa, with Moroccan coastal infrastructure processing sardine and anchovy biomass while South African facilities handle lipid purification for humidity-stressed distribution. Raw material flows draw from wild-catch marine stocks, fermentation-derived microalgae platforms, and Antarctic krill biomass. Single-source vulnerability concentrates in Moroccan sardine harvest cycles, which fluctuate with Atlantic ocean temperature patterns. Distribution runs through GMP-accredited pharmaceutical distributors in Lagos, Johannesburg, and Cairo, bypassing traditional wholesale channels for direct-to-clinic maternal health procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algal fermentation platforms and tightening NAFDAC certification protocols constitute a dual inflection reshaping competitive access across West African procurement channels. This technological-regulatory convergence compresses traditional fish oil dominance while elevating GMP-accredited, vegan-certified suppliers.
For Market Incumbents: Shield market position by deepening backward integration into microalgae fermentation capacity and securing exclusive cold-chain distribution partnerships with Lagos maternal health programs. Algal oil substitution threatens Moroccan-dependent processors lacking vegan certification pathways. Certification investment represents the critical defensive lever for preferential shelf placement in Johannesburg pharmacy chains. For New Entrants and Emerging Players: Anchor in Ghana's tilapia farming sector, where dedicated omega-3 premix infrastructure remains absent and first-mover positioning awaits certified concentrate distributors. The aquaculture feed application offers lowest competitive density relative to saturated Nigerian infant nutrition channels. Direct-to-clinic distribution models bypass entrenched pharmacy networks while capturing bulk procurement from maternal health programs. For Investors and Strategic Acquirers: Capital is best deployed toward fermentation-platform specialists with demonstrated EPA and DHA output scalability and existing GMP accreditation for African humidity conditions. Long-term viability hinges on regulatory convergence across ECOWAS, EAC, and SADC blocs enabling cross-border shipment without redundant certification. The signal to watch is which regional economic community first establishes mutual recognition for omega-3 analytical testing protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Microalgae Fermentation Scale-Up | DSM's platform reduces wild-catch dependency while capturing vegan-certified infant nutrition demand in Lagos. |
| GMP Accreditation Investment | Certification unlocks preferential access to NAFDAC-regulated Nigerian pharmaceutical distribution channels. |
| Cold-Chain Distribution Partnership | BASF SE's stability-tested bulk containers enable potency-preserving Saharan transit to Egyptian manufacturers. |
| Backward Integration into Algal Cultivation | In-house fermentation capacity insulates margin structures from Moroccan sardine harvest volatility. |
| Direct-to-Clinic Channel Development | Bypassing traditional pharmacy networks captures bulk procurement from South African prenatal care programs. |
Study Parameters
Desk research of trade flow databases, regulatory filings with NAFDAC and South Africa's Department of Health, and coastal processing capacity reports preceded structured interviews with marine biochemists, aquaculture feed formulators, and maternal health procurement officers. Primary fieldwork with Lagos distribution channel managers and Cairo pharmaceutical manufacturing executives combined with secondary validation against East African Community harmonization documents and Ghana FDA labeling guidelines. Bottom-up volume estimates from individual facility throughput triangulated against top-down market size assessments derived from import certification records.
Variance decomposition across product type, application, and regional regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include extraction technology, certification tier, end-use performance requirements, and distribution channel access patterns. CAGRs were synthesized from trajectory analysis of historical procurement volumes and regulatory implementation timelines. Forecast inputs incorporated NAFDAC inspection queue durations, East African Community mutual recognition protocol activation probability, and algal fermentation capacity expansion announcements.
Material uncertainties — wild-catch harvest volatility, regional bloc harmonization friction, and fermentation scale-up delays — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory enforcement consistency and cold-chain infrastructure investment continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Japan Soy Protein Market
Functional Food & Ingredients
Functional Food Ingredients Market
Functional Food & Ingredients
Asia-Pacific Omega3 PUFA Market
Functional Food & Ingredients
Poultry Probiotic Ingredients Market
Functional Food & Ingredients
APAC Heart Health Functional Food Market
Functional Food & Ingredients
Banana Leaf Extract Market
Functional Food & Ingredients
Europe Omega-3 PUFA Market
Functional Food & Ingredients
Refined Functional Carbohydrates Market
Functional Food & Ingredients
Italy Protein Market
Functional Food & Ingredients
North America Pea Protein Ingredients Market
Functional Food & Ingredients
Africa Algae Omega-3 Ingredients Market
Functional Food & Ingredients
Omega 3 PUFA Market
Functional Food & Ingredients
Prebiotic Ingredients Market
Functional Food & Ingredients
North America and Europe Medical Foods Market
Functional Food & Ingredients
Beta Glucan and Fucoidan Market
Functional Food & Ingredients
Global Whole Grain and High Fiber Food Market