
 Multifunctional Food Ingredients Market | 2026-2036
Multifunctional Food Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Multifunctional Food Ingredients Market Outlook
Multi-source procurement of hydrocolloid and protein systems is recalibrating how food manufacturers secure functional ingredient supply. Cargill Incorporated leverages its oilseed processing network to backward-integrate into lecithin and emulsifier production. Kerry Group PLC anchors its position through captive flavor-enhancer and texture-system R&D facilities across Europe and North America. BASF SE competes by specializing in microbial-sourced stabilizers with precise rheological specifications for beverage applications.
Multifunctional food ingredients are formulated compounds that deliver two or more simultaneous technical effects—such as emulsification combined with shelf-life extension or texture modification paired with nutritional fortification—typically at usage levels between 0.1% and 5% by weight in finished food matrices. Their primary commercial purpose is to reduce ingredient inventory complexity while maintaining or improving product performance under accelerated distribution conditions. Emulsifiers and stabilizers together constitute the largest functional value pool, reflecting entrenched demand in dairy and bakery systems where phase stability determines manufacturing yield. Plant-based sourcing is expanding fastest among source categories, though synthetic thickeners still dominate margin capture in cost-sensitive snack applications. The end-use split tilts toward beverages and dairy products, where clean-label reformulation has intensified demand for single-ingredient solutions that replace multiple additives.
The FDA maintains stringent GRAS notification requirements for novel multifunctional ingredients, while the EU's EFSA evaluates emulsifier and stabilizer petitions under evolving food-additive frameworks that now incorporate extended toxicity screening. In parallel, the FSSAI in India has tightened contaminant limits for microbial-sourced thickeners, reshaping export compliance burdens for multinational suppliers. Stakeholders must monitor how divergent purity benchmarks across FDA, EFSA, and Asian regulators will fragment formulation strategies and determine which ingredient platforms achieve cross-border scale without reformulation.
Market Dynamics
Clean-label reformulation mandates are compressing ingredient lists while demanding equivalent functional performance, forcing manufacturers to consolidate multiple technical effects into single-component solutions that satisfy both regulatory purity benchmarks and consumer transparency expectations.
Growth Catalysts
- EU Enzyme Regulation Evolution:EFSA's streamlined safety assessments for microbial-sourced emulsifiers accelerate approval timelines for novel plant-based stabilizers entering dairy and bakery applications.
- Reduced-Sodium Dairy Mandates:Germany's reformulation requirements for sodium reduction in processed cheese systems drive demand for multifunctional salts that maintain texture while lowering sodium content.
- Plant Protein Functionality Gaps:Rapid expansion of oat and pea protein beverages creates urgent need for hydrocolloid-protein complexes that prevent phase separation without synthetic additives.
Market Restraints
- Hydrocolloid Raw Material Volatility:Seaweed harvest fluctuations and guar gum price swings in India disrupt cost predictability for texture-system suppliers serving cost-sensitive snack manufacturers.
- Synthetic Thickener Lock-In:Marginal cost advantages of cellulose derivatives and modified starches delay substitution timelines in emerging-market beverage applications where clean-label premiums remain unproven.
- FSSAI Contaminant Limits:India's tightened microbial thresholds for xanthan and gellan gum production impose compliance burdens that disqualify smaller fermentation-based suppliers from export qualification.
Strategic Opportunities
- Precision Fermentation Scale-Up:Microbial-derived emulsifiers with tailored HLB values offer pathway to replace lecithin in chocolate and confectionery systems facing allergen labeling pressures.
- Direct-to-Manufacturer Platforms:Digital ingredient marketplaces bypass traditional distributor markups for mid-size bakery and beverage producers seeking technical formulation support alongside supply.
- EU Green Deal Alignment:Carbon footprint disclosure requirements for food ingredients create first-mover advantage for suppliers with verified lifecycle data on plant-sourced hydrocolloids versus petroleum-based alternatives.
Industry Challenges
- Cross-Functional Formulation Expertise:Shortage of food scientists capable of integrating rheology, shelf-life modeling, and sensory mapping slows clean-label prototype development cycles for ingredient houses.
- Dual Certification Timelines:Simultaneous pursuit of FDA GRAS self-determination and EFSA food-additive petitions stretches regulatory affairs resources and delays commercial launch windows by 18-24 months.
- Legacy Equipment Compatibility:Existing dairy and bakery processing lines optimized for synthetic emulsifiers require retrofit investment to handle temperature-sensitive plant-based alternatives without yield loss.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multifunctional Food Ingredients Market |
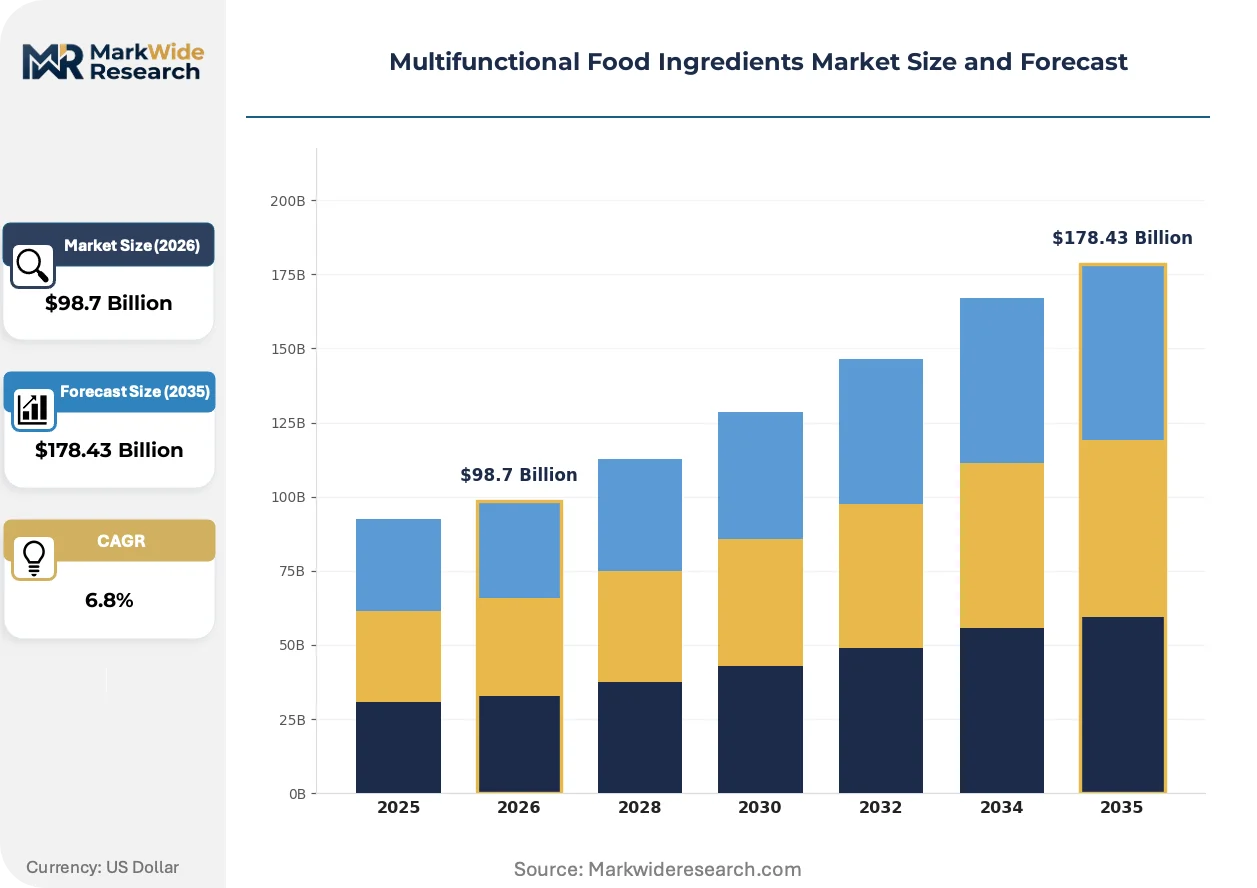
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
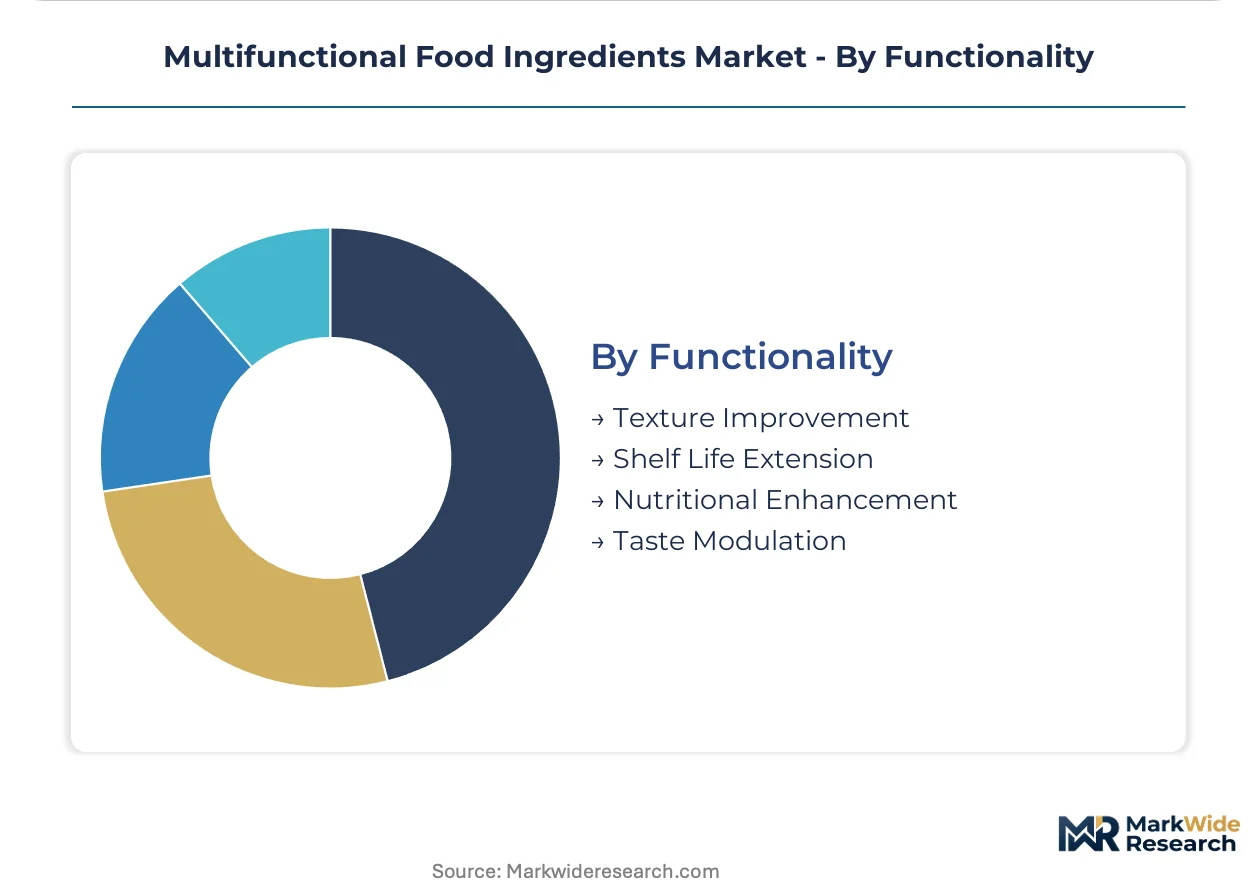
| Segmentation | Ingredient Type: Emulsifiers, Stabilizers, Thickeners, Flavor Enhancers Source: Plant-Based, Animal-Based, Synthetic, Microbial End Use: Bakery, Dairy Products, Snacks, Beverages Functionality: Texture Improvement, Shelf Life Extension, Nutritional Enhancement, Taste Modulation |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, BASF SE, Kerry Group PLC, Ingredion Incorporated, Ajinomoto Co. Inc., GELITA, DuPont Nutrition & Biosciences, Arla Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multifunctional Food Ingredients Market Strategic Shifts
Ingredient functionality is converging with nutritional enhancement as bioactive delivery systems merge with traditional texture modification, while regulatory transparency requirements reshape how technical performance claims are validated and communicated to downstream buyers.
Precision-fermented phospholipids are overtaking soy and sunflower lecithin in premium chocolate applications where allergen-free positioning commands formulation priority. European confectionery manufacturers are adopting these microbial-derived emulsifiers at accelerated trial-to-commercial rates. This transition is compressing conventional lecithin price premiums and redirecting supplier R&D investment toward strain optimization for customized melting profiles.
EFSA's extended toxicity screening protocols for food additives now incorporate cumulative exposure assessments and endocrine disruption potential, tightening evidentiary standards for emulsifier and stabilizer petitions. Manufacturers reformulating for EU market access face expanded safety study requirements that extend approval timelines. Dairy alternative producers are responding by prioritizing ingredients with existing food-additive approvals over novel self-determined GRAS positions.
Buyer concentration among multinational beverage and dairy conglomerates is consolidating procurement leverage and demanding ingredient suppliers provide integrated technical service including application labs and accelerated shelf-life testing. Regional mid-size manufacturers are losing direct supplier access as tier-one ingredient houses prioritize volume accounts with dedicated formulation support. This bifurcation is most pronounced in Western Europe where clean-label mandates have intensified technical complexity beyond commodity supply relationships.
Multifunctional Food Ingredients Market Segmentation

Ingredient segmentation determines which regulatory pathways manufacturers must navigate and which technical service levels suppliers must maintain. Category boundaries increasingly blur as single ingredients deliver multiple functional effects simultaneously.
Ingredient Type:
Emulsifiers and stabilizers face the heaviest EFSA and FDA scrutiny, requiring food-additive petitions or GRAS self-determination before commercial use.
- Emulsifiers:Phospholipid and mono-diglyceride compounds stabilize oil-water interfaces in dairy and confectionery matrices. Demand concentrates in Germany's reduced-sodium cheese reformulation sector, where emulsifiers compensate for salt removal without texture degradation.
- Stabilizers:Hydrocolloid and protein-based systems prevent phase separation in extended shelf-life beverages. Clean-label mandates in Western Europe accelerate substitution of synthetic variants with plant-sourced alternatives in oat and pea protein drinks.
- Thickeners:Cellulose derivatives and modified starches dominate cost-sensitive snack applications where clean-label premiums remain unproven.
- Flavor Enhancers:Yeast extracts and nucleotide compounds reduce sodium content while maintaining taste intensity in processed foods.
Emulsifiers sit at the top of the volume ranking, with stabilizers climbing the fastest.
Source:
Source selection dictates supply chain resilience and carbon footprint disclosure obligations under EU Green Deal frameworks.
- Plant-Based:Seaweed-derived hydrocolloids and legume proteins face harvest volatility but satisfy clean-label positioning. Western European bakery applications show accelerating uptake as reformulation mandates tighten.
- Microbial:Precision-fermented phospholipids and xanthan gum deliver consistent specifications with lower land-use intensity. Strain optimization programs target customized HLB values for chocolate applications.
- Synthetic:Petroleum-derived emulsifiers retain cost advantages in emerging-market beverages where regulatory pressure lags.
- Animal-Based:Gelatin and dairy-derived proteins maintain niche positions in premium confectionery despite allergen labeling burdens.
Plant-based sourcing commands the highest R&D investment intensity, with microbial platforms expanding most quickly.
End Use:
End-use concentration determines technical service requirements and formulation support depth from ingredient suppliers.
- Dairy Products:Processed cheese and yogurt systems demand emulsifier-stabilizer complexes that maintain texture through thermal processing and distribution. Germany's sodium reduction mandates drive multifunctional salt substitution.
- Beverages:Plant-protein drinks require hydrocolloid-protein complexes to prevent sedimentation without synthetic additives. Oat and pea protein expansion creates urgent functionality gaps.
- Bakery:Clean-label reformulation in Western Europe replaces DATEM and SSL with plant-based alternatives in bread and pastry applications.
- Snacks:Cost-sensitive extruded and coated products retain synthetic thickeners where margin pressure outweighs label transparency demands.
Dairy products anchor procurement volumes, with beverages gaining share fastest.
Functionality:
Functional convergence reduces ingredient inventory complexity while demanding cross-disciplinary formulation expertise.
- Texture Improvement:Rheology modification spans viscosity control, gelation, and mouthfeel engineering across liquid and semi-solid matrices. Bakery and dairy applications dominate specification development.
- Shelf Life Extension:Antimicrobial and antioxidant effects combined with moisture retention address distribution challenges in emerging markets. EFSA's extended toxicity screening tightens evidentiary requirements.
- Nutritional Enhancement:Bioactive delivery systems merge mineral fortification with texture modification in functional beverages.
- Taste Modulation:Bitter blocking and salt enhancement enable sodium and sugar reduction without sensory compromise.
Texture improvement generates the highest absolute demand, with taste modulation showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's ingredient processing corridor along the Rhine-Main industrial belt concentrates Europe's most sophisticated emulsifier and stabilizer manufacturing infrastructure, serving reformulation mandates that now span dairy, bakery, and beverage systems.
Germany
Reduced-sodium dairy mandates in processed cheese systems drive demand for multifunctional salt substitutes that maintain texture without sodium. EFSA's evolving enzyme regulations accelerate approval timelines for microbial-sourced emulsifiers entering commercial use. The Frankfurt-Rhine-Main cluster hosts captive R&D facilities where ingredient houses develop texture-system solutions for clean-label reformulation.
United States
Plant-protein beverage expansion in California and the Pacific Northwest creates urgent demand for hydrocolloid-protein complexes preventing phase separation. FDA's updated GRAS notification requirements impose stringent purity benchmarks for novel multifunctional ingredients. Chicago's food ingredient corridor anchors North American procurement volumes, with suppliers prioritizing technical service integration for multinational dairy conglomerates.
India
Export-oriented fermentation facilities in Maharashtra and Gujarat face tightened FSSAI contaminant limits for xanthan and gellan gum production. The central food regulator's microbial thresholds disqualify smaller suppliers from qualifying for international shipments. Mumbai-Pune industrial belt concentrates backward-integrated hydrocolloid processing serving both domestic snack manufacturers and Middle East export channels.
China
Synthetic thickener demand in cost-sensitive beverage applications retains market share despite clean-label pressures building in coastal provinces. SAMR's national food safety standards incorporate extended toxicity screening protocols aligned with evolving international benchmarks. Yangtze River Delta manufacturing clusters optimize cellulose derivative production for domestic distribution and Southeast Asian export markets.
Brazil
Snack and confectionery applications in São Paulo state retain petroleum-based emulsifiers where margin pressure outweighs label transparency investments. ANVISA's food additive frameworks lag European purity benchmarks, delaying substitution timelines for plant-based alternatives. Campinas-São Paulo corridor concentrates South American ingredient formulation expertise serving Andean and Southern Cone export destinations.
Multifunctional Food Ingredients Market Competitive Environment
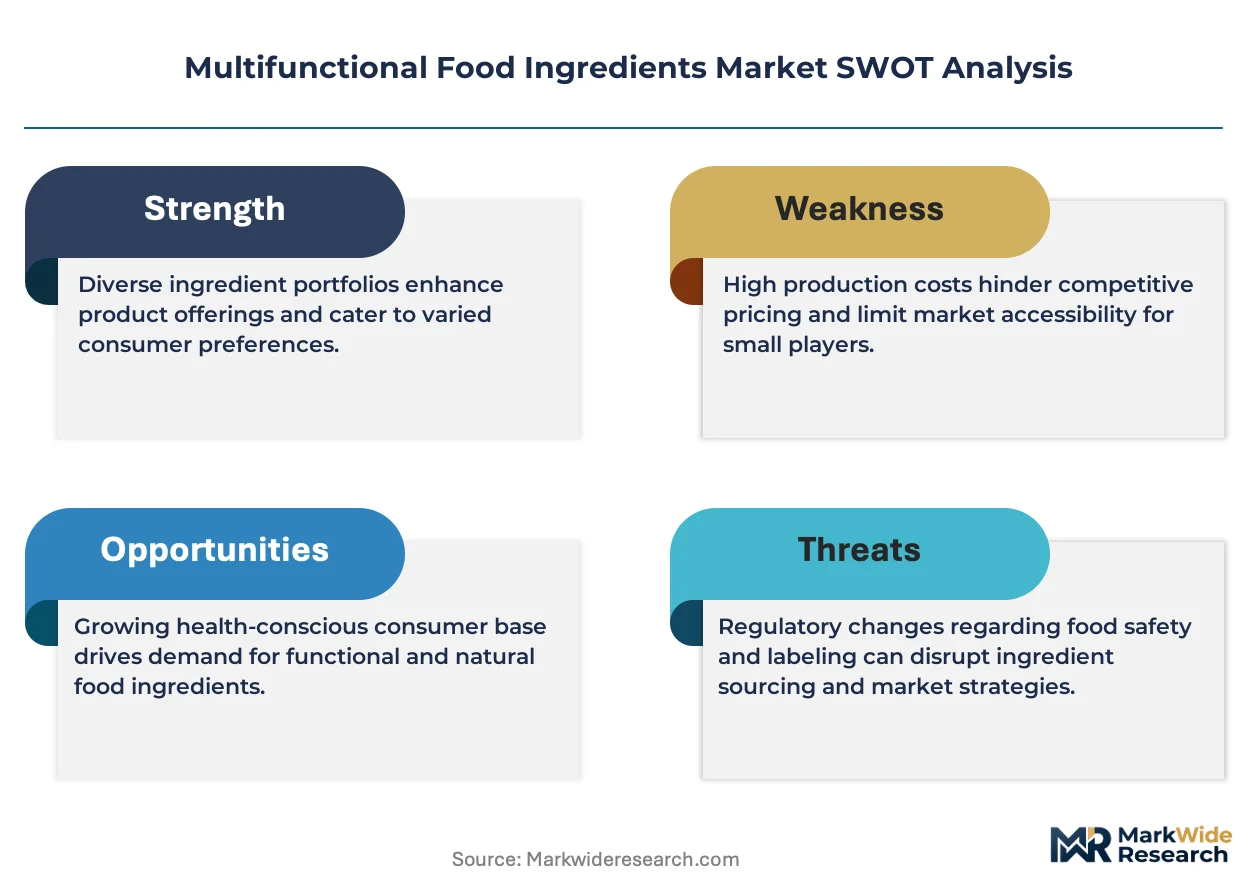
Global majors compete with regional champions across technical service depth and regulatory compliance capabilities. Market structure tilts toward consolidated procurement leverage among multinational beverage and dairy conglomerates, compressing margins for mid-tier suppliers lacking integrated application laboratories. Three archetypes dominate: oilseed processors with backward integration into lecithin production, specialty chemical houses with microbial fermentation platforms, and integrated ingredient houses combining flavor, texture, and nutritional systems. Competitive intensity centers on M&A activity consolidating regional formulation expertise and strategic partnerships locking in precision fermentation capacity.
Within the integrated ingredient house tier, Cargill Incorporated and Kerry Group PLC exemplify divergent geographic anchoring strategies, with the former leveraging North American oilseed infrastructure and the latter concentrating European flavor-system capabilities. BASF SE occupies a position representing specialty chemical fermentation expertise, particularly for microbial-sourced stabilizers with precise rheological specifications. Archer Daniels Midland Company sits within the agricultural processor archetype, linking grain origination networks to downstream emulsifier production without full integration into finished ingredient systems.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| BASF SE |
| Kerry Group PLC |
| Ingredion Incorporated |
| Ajinomoto Co. Inc. |
| GELITA |
| DuPont Nutrition & Biosciences |
| Arla Foods |
| Others |
Value Chain & Pricing Dynamics
Guar gum price volatility in India cascades through hydrocolloid supply chains into three-tier pricing structures across premium, standard, and economy levels for texture-system suppliers. EFSA's evolving purity benchmarks and FSSAI's tightened microbial thresholds for xanthan production compress margins at the fermentation tier while concentrating procurement leverage among multinational dairy and beverage conglomerates.
Pricing Analysis
Input-cost pass-through from seaweed harvest fluctuations and petroleum-derived cellulose feedstocks stratifies pricing across premium, standard, and economy tiers. Certification grade under EU food-additive frameworks and volume scale with multinational buyers drive price differentiation between specialty emulsifier houses and commodity hydrocolloid traders. Cost compression in economy-tier snack applications intensifies as Indian guar gum price swings disrupt cost predictability. Mid-size bakery manufacturers in Western Europe exhibit highest price sensitivity, while premium chocolate confectioners prioritize allergen-free positioning over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Indian guar gum processing and Indonesian seaweed harvesting for carrageenan and agar extraction. Raw material dependencies draw from South Asian legume proteins, European oilseed lecithin, and Chinese cellulose derivatives. Tariff exposure on fermentation-based thickeners crossing into EU regulatory jurisdictions compounds supply chain fragility. Distribution runs through regional ingredient houses with captive application laboratories serving dairy and beverage reformulation mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The multifunctional food ingredients market reads as a late-cycle quality story where clean-label reformulation mandates concentrate demand for premium-grade microbial-sourced emulsifiers with verified lifecycle carbon footprints. Precision-fermented phospholipids displacing conventional lecithin in allergen-sensitive applications exemplifies this specification shift toward higher-purity, lower-land-intensity alternatives.
For Market Incumbents: Anticipate margin compression from precision-fermentation scale-up by locking in long-term offtake agreements with strain-optimization platforms before HLB-customization capabilities commoditize. Defend position by deepening backward integration into oilseed processing networks that captive-supply lecithin and emulsifier precursors, while accelerating EFSA food-additive petition pipelines to preempt regulatory delays from extended toxicity screening protocols. For New Entrants and Emerging Players: The price-point gap between premium microbial-derived emulsifiers and economy-tier synthetic cellulose derivatives opens white-space in mid-market bakery and beverage applications where clean-label premiums are proven but technical service integration remains shallow. Target Western European oat and pea protein beverage manufacturers seeking hydrocolloid-protein complexes without synthetic additives. Establish direct-to-manufacturer digital platforms bundling formulation support with supply to bypass traditional distributor markups. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-fermentation specialists possessing validated strain libraries and EFSA-approved food-additive positions for phospholipid emulsifiers. Long-term viability hinges on carbon footprint disclosure capabilities aligning with EU Green Deal procurement criteria. Monitor EFSA approval timelines for novel microbial-sourced stabilizers as the inflection signal determining which ingredient platforms achieve cross-border scale without reformulation.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbial-derived phospholipids with tailored HLB values displace soy lecithin in chocolate applications facing allergen labeling pressures. |
| Backward Integration into Oilseed Processing | Cargill's captive lecithin production from North American oilseed networks secures emulsifier supply against raw material volatility. |
| Direct-to-Manufacturer Platform Launch | Digital ingredient marketplaces bypass distributor markups for mid-size bakery producers seeking technical formulation support. |
| EU Green Deal Certification Investment | Verified lifecycle carbon data on plant-sourced hydrocolloids creates first-mover advantage in procurement from sustainability-mandated buyers. |
| Regulatory Affairs Capacity Expansion | Dual-track FDA GRAS self-determination and EFSA food-additive petition capabilities compress commercial launch windows by 12-18 months. |
Study Parameters
Bottom-up beverage and dairy modeling reconciled against top-down hydrocolloid and emulsifier production tracking forms the analytical core of this study. Primary interviews with ingredient house R&D directors, dairy reformulation technologists, EFSA regulatory affairs consultants, and procurement managers at multinational beverage conglomerates combined with secondary validation from FDA GRAS notifications, EFSA food-additive petitions, FSSAI contaminant limit circulars, and customs trade data on guar gum and seaweed-derived hydrocolloids.
Input-output matrices mapping emulsifier functionality requirements to end-use application specifications across ingredient type, source category, and regional regulatory cluster drove segmentation-level forecasts. CAGRs derived from elasticity-adjusted demand curves incorporating clean-label reformulation intensity, sodium-reduction mandate compliance deadlines, and plant-protein beverage expansion rates. Industry-specific forecast inputs included EFSA approval timeline probabilities for microbial-sourced stabilizers and precision-fermentation capacity buildout schedules.
The model assumes a particular technology adoption path; alternative pathways for precision-fermented phospholipids displacing conventional lecithin would alter the outlook if strain optimization costs fail to achieve parity with oilseed processing economics. Forecasts reflect assumptions on regulatory harmonization between FDA, EFSA, and FSSAI purity benchmarks, with divergence risk compressing cross-border formulation standardization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
APAC Heart Health Functional Food Market
Functional Food & Ingredients
Europe Botanical Extract Market
Functional Food & Ingredients
Brazil Flavored and Functional Water Market
Functional Food & Ingredients
Italy Protein Market
Functional Food & Ingredients
Prickly Pear Fruit Metabolic Health Ingredients Market
Functional Food & Ingredients
Functional Food Ingredients Market
Functional Food & Ingredients
Europe Prebiotic Ingredient Market
Functional Food & Ingredients
Healthy Fats Low Carb Market
Functional Food & Ingredients
Africa Omega-3 PUFA Market
Functional Food & Ingredients
Essential Fatty Acids Market
Functional Food & Ingredients
Functional Non-Meat Ingredients Market
Functional Food & Ingredients
South America Prebiotic Ingredients Market
Functional Food & Ingredients
Africa Algae Omega-3 Ingredients Market
Functional Food & Ingredients
Refined Functional Carbohydrates Market
Functional Food & Ingredients
Mediterranean Cognitive-First Ingredient Systems Market
Functional Food & Ingredients
Lovage Extract Market