
 Mediterranean Pre-Diabetes Ingredient Concepts Market | 2026-2036
Mediterranean Pre-Diabetes Ingredient Concepts Market Size, Share, and Industry Trends Forecast 2026-2036
Mediterranean Pre-Diabetes Ingredient Concepts Market Insights
Multi-source botanical extraction is repositioning supply security for Mediterranean pre-diabetes ingredient suppliers. Indena leverages Italian cultivation networks to secure olive and artichoke extract volumes. Euromed anchors Spanish-grown standardized polyphenol output for nutraceutical clients. Kerry competes through applied health science platforms that bridge ingredient supply and finished formulation.
Mediterranean pre-diabetes ingredient concepts comprise bioactive compounds—principally hydroxytyrosol, oleuropein, and berberine-class alkaloids—extracted from region-specific flora and formulated for glycemic modulation at doses between 200–500 mg active equivalents. These ingredients serve pharmaceutical manufacturers and nutraceutical brands seeking clinically substantiated alternatives to synthetic glucose-control agents. Polyphenol extracts occupy the dominant value share given EFSA-backed health claim potential and established supply from Spanish and Italian cooperatives. Functional beverage delivery forms sustain the fastest growth trajectory as beverage makers seek to differentiate sugar-reduced portfolios with clinically positioned botanical inclusions.
EFSA novel food assessments and EU Health Claims Regulation (EC) 1924/2006 govern market access by demanding human intervention data for glycemic-related claims. Spain's AESAN and Italy's Ministry of Health enforce national transpositions that add labeling and substantiation layers. France's ANSES contributes additional safety opinions on concentrated botanical extracts. Stakeholders must monitor evolving EFSA guidance on polyphenol-specific beneficial physiological effect definitions to calibrate R&D investment against claim probability.
Market Dynamics
EFSA's evolving guidance on polyphenol-specific beneficial physiological effects is forcing ingredient suppliers to recalibrate clinical trial investment against claim probability, compressing R&D timelines while elevating substantiation costs for market access.
Growth Catalysts
- EU Health Claims Regulation (EC) 1924/2006:EFSA-backed approval pathways for glycemic-related claims create differentiated positioning for clinically substantiated botanical extracts versus synthetic alternatives.
- Functional beverage makers:Sugar-reduced portfolio differentiation strategies accelerate incorporation of clinically positioned polyphenol inclusions at 200–500 mg active equivalent doses.
- Spanish and Italian cooperative networks:Established olive cultivation clusters secure standardized hydroxytyrosol and oleuropein supply volumes for nutraceutical formulation pipelines.
Market Restraints
- Olive-derived raw material concentration:Single-source botanical dependency across Southern European cooperatives creates harvest volatility exposure for extract standardization.
- EFSA novel food assessment timelines:Extended safety evaluation periods delay commercialization of innovative berberine-class alkaloid formulations.
- Synthetic glucose-control agents:Established pharmaceutical alternatives compete on price and reimbursement familiarity in clinician prescribing patterns.
Strategic Opportunities
- Greece:Underdeveloped artichoke extract commercialization relative to olive polyphenols offers white space for cynarin-standardized ingredient positioning.
- France's ANSES safety opinion framework:Concentrated botanical extract approvals create regulatory tailwind for premium polyphenol concentration products.
- Direct-to-practitioner digital platforms:Functional medicine networks bypass traditional distribution markups for clinically validated glycemic modulation ingredients.
Industry Challenges
- Clinical trial design expertise:Shortage of human intervention specialists familiar with EFSA glycemic endpoint requirements slows claim substantiation execution.
- Multi-source extraction capex:Artichoke and olive parallel processing lines demand capital deployment for supply security diversification.
- Cross-border batch consistency:Harmonization gaps between Spain's AESAN and Italy's Ministry of Health labeling enforcement complicate multi-market launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mediterranean Pre-Diabetes Ingredient Concepts Market |
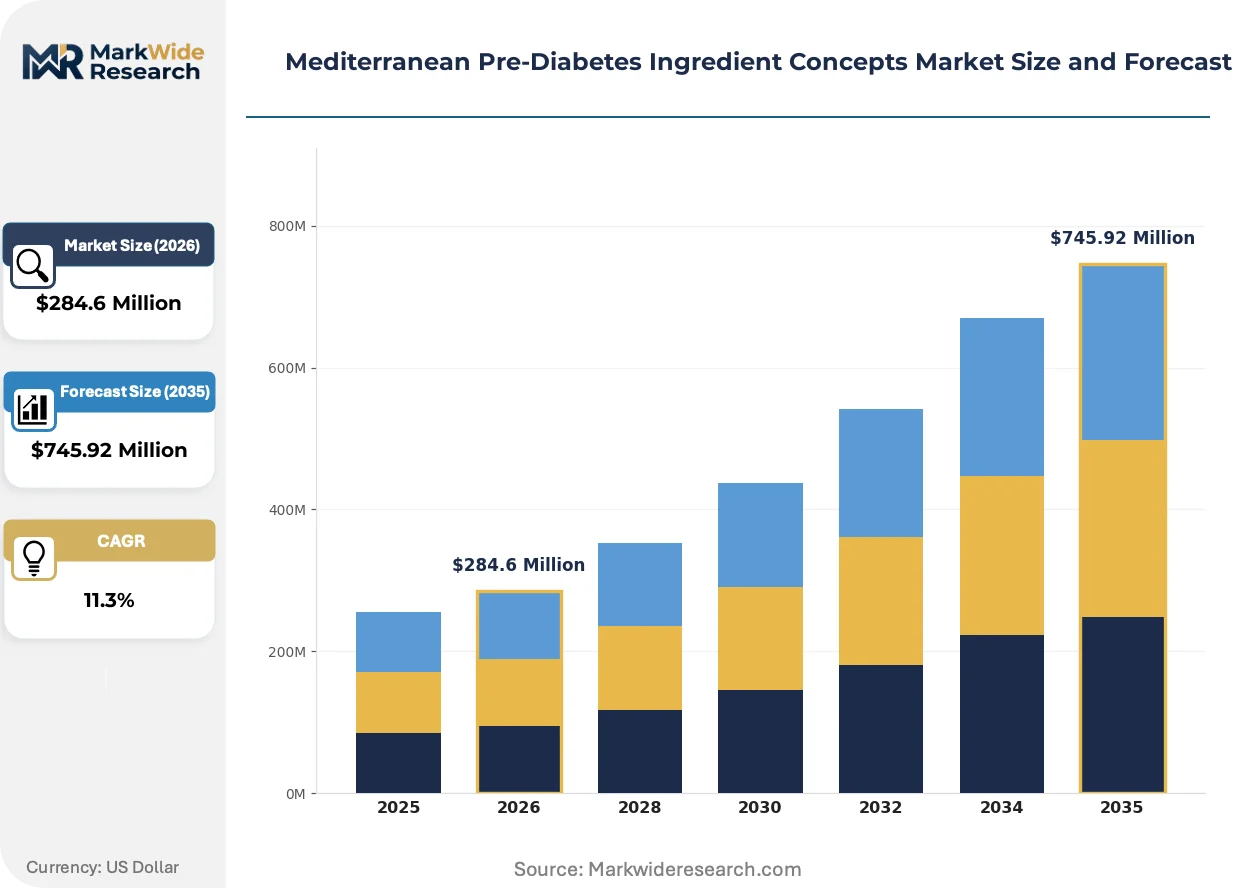
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $745.92 Million |
| CAGR (2026 – 2036) | 11.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Polyphenols, Fiber Complexes, Omega-3 Fatty Acids, Plant Extracts, Probiotics Delivery Form: Capsules, Powders, Functional Beverages, Nutritional Bars, Liquid Concentrates Target Application: Blood Sugar Regulation, Insulin Sensitivity, Weight Management, Cardiovascular Support, Digestive Health End User Group: Pharmaceutical Manufacturers, Nutraceutical Brands, Health Clinics, Wellness Centers, Research Institutions |
| Companies Covered | Indena, Euromed, ADM, Kerry, dsm-firmenich, Givaudan, Ingredion, Tate & Lyle, Archer Daniels Midland Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mediterranean Pre-Diabetes Ingredient Concepts Market Trends and Innovations
Formulation science and delivery mechanism innovation are repositioning how Mediterranean bioactives reach end-consumers, with beverage and personalized nutrition formats displacing traditional capsule dominance.
Microencapsulation technology for polyphenol stability is expanding into functional beverage applications, protecting hydroxytyrosol from oxidation during pasteurization. Major beverage manufacturers in Spain and Italy are adopting these stabilized extracts for shelf-stable sugar-reduced launches. This protection capability is expanding into ambient distribution channels previously inaccessible to oxidation-sensitive botanical actives.
EFSA's draft guidance on polyphenol-specific beneficial physiological effect definitions is tightening evidentiary standards for glycemic-related health claims. Ingredient suppliers must now demonstrate mechanistic biomarker links beyond simple glucose endpoints. Mediterranean extract producers with existing human trial portfolios are accelerating dossier submissions ahead of anticipated guidance finalization.
Practitioner-channel purchasing for personalized glycemic protocols is fragmenting traditional retail concentration. Functional medicine clinicians in Italy and Greece are specifying compound formulations blending olive polyphenols with berberine-class alkaloids. This specification behavior is most visible in urban wellness clinic clusters across Barcelona, Milan, and Athens.
Mediterranean Pre-Diabetes Ingredient Concepts Market Segmentation
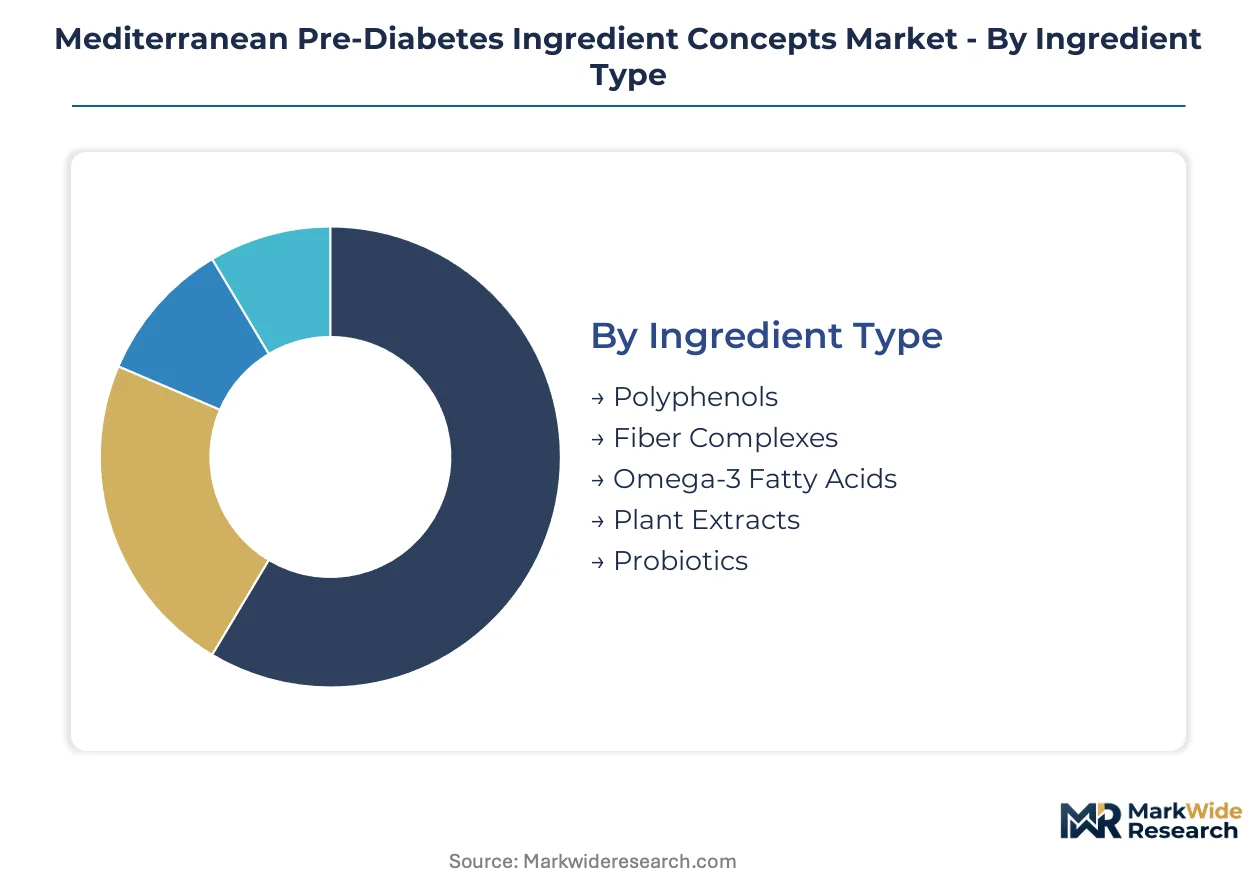
Ingredient classification determines formulation complexity and regulatory pathway requirements for Mediterranean pre-diabetes concepts. Delivery mechanisms and target applications further stratify commercial opportunity across pharmaceutical and nutraceutical value chains.
Ingredient Type:
Standalone bioactive concentrates command premium positioning versus embedded multi-ingredient systems in finished formulations.
- Polyphenols:Hydroxytyrosol and oleuropein concentrates extracted from Spanish and Italian olive cultivars dominate clinical substantiation investment. EFSA health claim eligibility drives pharmaceutical manufacturer procurement concentration in Southern European cooperative supply zones.
- Plant Extracts:Artichoke-derived cynarin and berberine-class alkaloids from regional botanical sources anchor emerging glycemic modulation portfolios. Greek cultivation networks remain underdeveloped relative to olive polyphenol infrastructure.
- Fiber Complexes:Soluble and insoluble matrices from Mediterranean grain and legume sources support digestive-metabolic dual claims.
- Omega-3 Fatty Acids:Algae and marine-derived EPA/DHA concentrates target cardiovascular-glycemic crossover positioning.
- Probiotics:Strain-specific formulations from fermented Mediterranean dairy traditions occupy nascent microbiome-glycemia research corridors.
Polyphenols lead volumes today; plant extracts are gaining share fastest.
Delivery Form:
Cost tier stratification separates premium stabilized formats from commodity bulk inputs.
- Functional Beverages:Microencapsulated polyphenol systems enable ambient-stable, sugar-reduced launches in Spanish and Italian beverage pipelines. Pasteurization protection technology unlocks distribution previously inaccessible to oxidation-sensitive actives.
- Capsules:Hard-shell and soft-gel formats retain dominance in practitioner-channel personalized protocols across Milan and Athens wellness clinic clusters. Standardized dosing precision supports clinical specification behavior.
- Powders:Bulk active equivalents serve nutraceutical brand in-house formulation and compound blending operations.
- Nutritional Bars:Matrix-embedded bioactives target convenience-positioned glycemic management in retail wellness segments.
- Liquid Concentrates:High-potency extracts for pharmaceutical-scale tableting and encapsulation outsourcing.
Capsules dominate current revenue; functional beverages show steepest expansion trajectory.
Target Application:
Application maturity correlates directly with evidentiary burden and health claim authorization status under EU regulatory frameworks.
- Blood Sugar Regulation:Primary glycemic endpoint positioning demands EFSA-compliant human intervention data. Spanish and Italian extract suppliers concentrate clinical trial investment on fasting glucose and HbA1c biomarker linkages.
- Insulin Sensitivity:Mechanistic claims requiring HOMA-IR and clamp study substantiation attract pharmaceutical manufacturer partnership interest.
- Weight Management:Adjacent metabolic positioning leverages satiety and adiposity biomarkers with lower regulatory barriers.
- Cardiovascular Support:Polyphenol antioxidant claims with established EFSA opinions enable faster market access.
- Digestive Health:Gut microbiome modulation represents emerging research frontier with limited current claim authorization.
Blood sugar regulation commands the largest addressable base; insulin sensitivity applications are climbing the fastest.
End User Group:
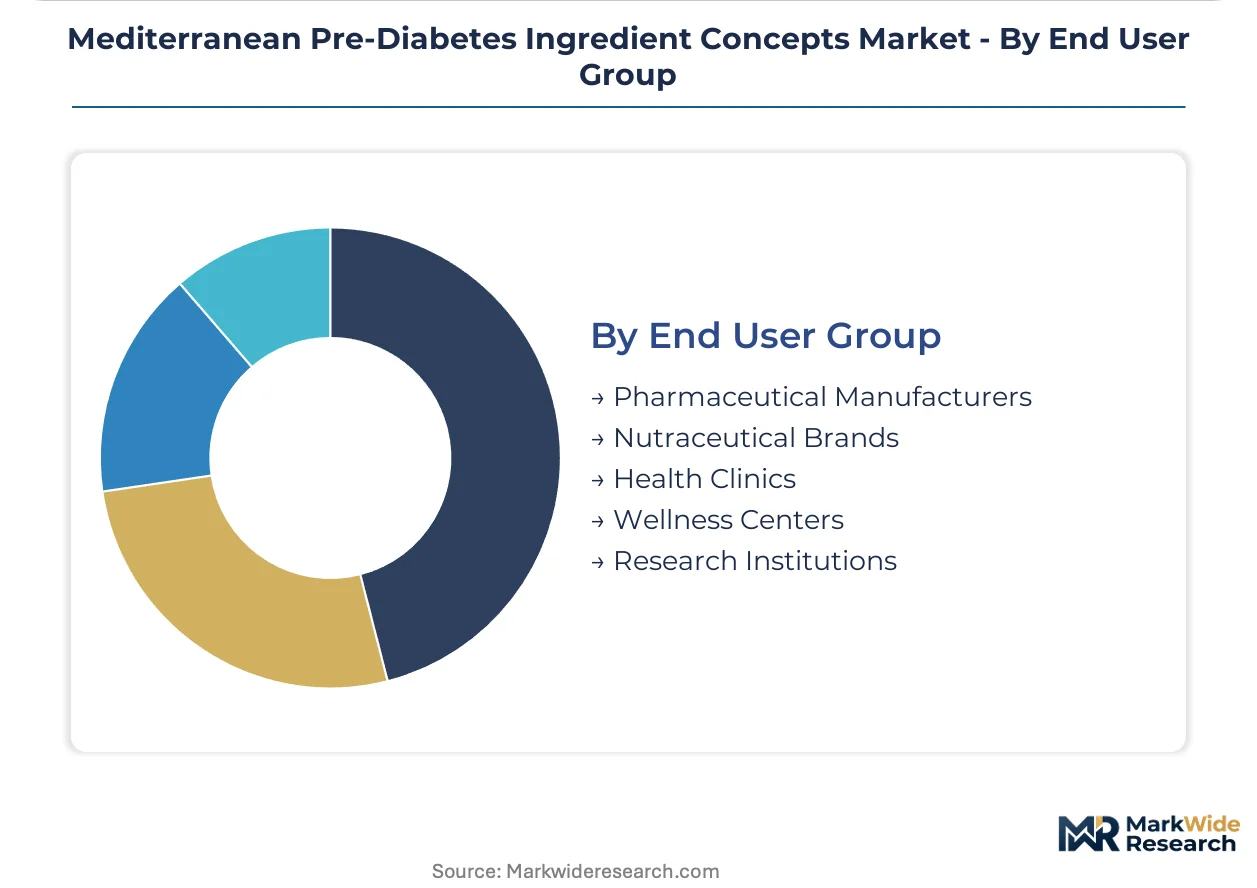
Customer type determines specification authority, batch scale requirements, and margin capture potential across value chain tiers.
- Nutraceutical Brands:Southern European formulation houses drive standardized extract procurement for finished product pipelines. Direct sourcing relationships with Spanish and Italian cooperatives secure volume commitments.
- Pharmaceutical Manufacturers:GMP-grade bioactive requirements and drug-master-file documentation elevate supplier qualification barriers.
- Health Clinics:Functional medicine practitioners in Barcelona, Milan, and Athens specify compound formulations blending multiple bioactive classes.
- Wellness Centers:Lifestyle protocol integration creates demand for co-branded and white-label finished products.
- Research Institutions:Academic clinical trial material supply supports mechanistic and efficacy study pipelines.
Nutraceutical brands anchor current procurement volumes; health clinics are expanding specification influence most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish olive cultivation networks anchor Mediterranean pre-diabetes ingredient supply. EFSA novel food assessments and national health claim enforcement create differentiated market access conditions across Southern European extraction zones.
Spain
Andalusian cooperative networks supply standardized hydroxytyrosol volumes for nutraceutical formulation. AESAN enforces EU Health Claims Regulation transpositions with additional labeling requirements. Seville extraction clusters process olive-derived polyphenols for pharmaceutical-grade specifications.
Italy
Artichoke and olive dual-crop cultivation secures multi-source botanical feedstock for extract producers. Ministry of Health novel food opinions add substantiation layers beyond EFSA baseline. Milan wellness clinic clusters drive practitioner-channel specification behavior for compound formulations.
Greece
Underdeveloped artichoke extract commercialization creates white space for cynarin-standardized positioning. National pharmaceutical regulator assessments align with EFSA timelines for novel botanical approvals. Athens functional medicine networks specify blended polyphenol-alkaloid protocols for glycemic management.
France
ANSES safety opinions on concentrated botanical extracts enable premium polyphenol concentration products. National regulator frameworks complement EU-level health claim substantiation requirements. Provence-Alpes-Côte d'Azur research institutions anchor mechanistic biomarker study corridors.
Mediterranean Pre-Diabetes Ingredient Concepts Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue microencapsulation technology partnerships. The supplier base concentrates around Southern European extraction specialists with cooperative cultivation ties. Three archetypes dominate: vertically integrated botanical extractors, applied health science platform operators, and pharmaceutical-grade bioactive specialists. Capacity expansion into parallel processing lines and strategic partnerships with functional beverage manufacturers represent the dominant competitive vectors.
Within the vertically integrated extraction tier, Indena and Euromed exemplify archetype positioning through Italian and Spanish cultivation network control respectively. Kerry occupies a position bridging ingredient supply and finished formulation capabilities. These three entities represent distinct strategic postures: cooperative-anchored raw material security, multi-source botanical diversification, and health science platform integration.
| Leading Market Players |
|---|
| Indena |
| Euromed |
| ADM |
| Kerry |
| dsm-firmenich |
| Givaudan |
| Ingredion |
| Tate & Lyle |
| Archer Daniels Midland Company |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal sustainability mandates gate qualified supply access and premium-tier pricing eligibility for Mediterranean pre-diabetes ingredient suppliers. EFSA novel food dossier requirements and cooperative cultivation certification standards filter which extract producers command pharmaceutical-grade price premiums versus commodity bulk positioning.
Pricing Analysis
Input-cost pass-through from olive harvest volatility and artichoke cultivation cycles shapes contract structures across Southern European cooperative networks. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-standard, and commodity-economy levels separates GMP-certified hydroxytyrosol concentrates from bulk oleuropein powders. Pricing pressure stems from synthetic glucose-control agent competition in clinician prescribing patterns, compressing margins at the standard tier. Nutraceutical brands exhibit highest price sensitivity due to finished formulation cost targets, while pharmaceutical manufacturers accept premium positioning for drug-master-file documentation.
Supply Chain Analysis
Single-source vulnerability sits with Andalusian olive cooperative concentration for hydroxytyrosol feedstock. Spain, Italy, and Greece anchor geographic supply concentration for polyphenol and cynarin extraction infrastructure. Raw material dependencies rest on olive cultivar harvest yields, artichoke thistle availability, and berberine-class botanical sourcing. Tariff exposure on cross-border extract shipments between Southern European jurisdictions creates supply chain risk. Distribution runs through Seville and Milan extraction clusters into pharmaceutical manufacturer GMP facilities and nutraceutical brand formulation houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in microencapsulation technology adoption and practitioner-channel direct distribution, both enabling premium-tier capture away from retail markups.
For Market Incumbents: Lock in cooperative cultivation contracts across Spanish and Italian olive networks before harvest volatility intensifies. Extend backward integration into Greek artichoke cultivation zones to diversify single-source botanical risk. Deepen EFSA health claim dossier investment ahead of anticipated polyphenol-specific guidance finalization to defend positioning against emerging entrants lacking clinical trial portfolios. For New Entrants and Emerging Players: Enter via underdeveloped Greek artichoke extract commercialization, where cynarin-standardized supply gaps create white space absent from saturated olive polyphenol competition. Target functional beverage manufacturer partnerships in Spain and Italy seeking pasteurization-stable microencapsulated formats. Pursue direct-to-practitioner digital platform routes through Barcelona, Milan, and Athens wellness clinic clusters to bypass entrenched distribution markups. For Investors and Strategic Acquirers: Roll-up economics work for applied health science platform operators because EFSA substantiation cost barriers concentrate viable acquisition targets among dossier-holding extract specialists. Five-to-ten year viability hinges on health claim authorization velocity outpacing synthetic pharmaceutical innovation cycles. Monitor EFSA draft guidance finalization timelines as inflection indicator for premium-tier pricing power reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Health Claim Dossier Advancement | Secures differentiated positioning for hydroxytyrosol extracts against synthetic alternatives in pharmaceutical procurement. |
| Microencapsulation Technology Partnership | Unlocks ambient-stable functional beverage applications for oxidation-sensitive polyphenol actives. |
| Greek Artichoke Cultivation Expansion | Diversifies feedstock sources beyond olive-dependent Andalusian cooperative networks. |
| Direct-to-Practitioner Channel Development | Bypasses retail distribution markups through functional medicine clinic specification networks. |
| Multi-Source Botanical Processing Scale-Up | Reduces harvest volatility exposure via parallel olive and artichoke extraction line deployment. |
Research Methodology
Bottom-up nutraceutical brand procurement modeling reconciled against top-down extraction capacity tracking forms the analytical core. Primary interviews with extraction plant managers, EFSA regulatory consultants, functional beverage R&D directors, and wellness clinic procurement officers combined with secondary validation from EFSA novel food opinions, AESAN labeling enforcement records, EU Health Claims Regulation submissions, and Southern European cooperative harvest reports. Triangulation between supply-side capacity announcements and demand-side formulation pipeline commitments calibrated volume estimates.
Historical trendline analysis of polyphenol extract shipments and health claim authorization velocity informed projection frameworks across the analysis window. Segmentation dimensions modeled include ingredient type, delivery form complexity, target application evidentiary burden, and end-user specification authority. CAGRs derived from curve-fitting approaches against EFSA approval timeline scenarios and functional beverage launch pipeline densities. Forecast inputs incorporated cooperative harvest yield variability and practitioner-channel purchasing growth trajectories.
Inputs from EFSA guidance drafts and national regulator transposition documents were available through the study window; gaps in real-time harvest yield data introduce uncertainty bands around short-term volume estimates. Forecasts reflect documented assumptions regarding health claim authorization probabilities and synthetic pharmaceutical competitive response. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Functional Food & Ingredients
Brazil Flavored and Functional Water Market
Functional Food & Ingredients
Global Probiotic Ingredients Market
Functional Food & Ingredients
Low-Carb Low-Fat Meal Market
Functional Food & Ingredients
Europe Sterol Market
Functional Food & Ingredients
South America Prebiotic Ingredients Market
Functional Food & Ingredients
Global Medical Foods Market
Functional Food & Ingredients
Banana Leaf Extract Market
Functional Food & Ingredients
South America Omega-3 PUFA Market
Functional Food & Ingredients
Europe Prebiotic Ingredient Market
Functional Food & Ingredients
Sacha Inchi Protein Market
Functional Food & Ingredients
North America Omega-3 PUFA Market
Functional Food & Ingredients
Prickly Pear Fruit Metabolic Health Ingredients Market
Functional Food & Ingredients
Omega 3 PUFA Market
Functional Food & Ingredients
Lovage Extract Market
Functional Food & Ingredients
Global Whole Grain and High Fiber Food Market
Functional Food & Ingredients
Europe Botanical Extract Market