
 Carbohydrates Testing Services Market | 2026-2036
Carbohydrates Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Carbohydrates Testing Services Market Insights
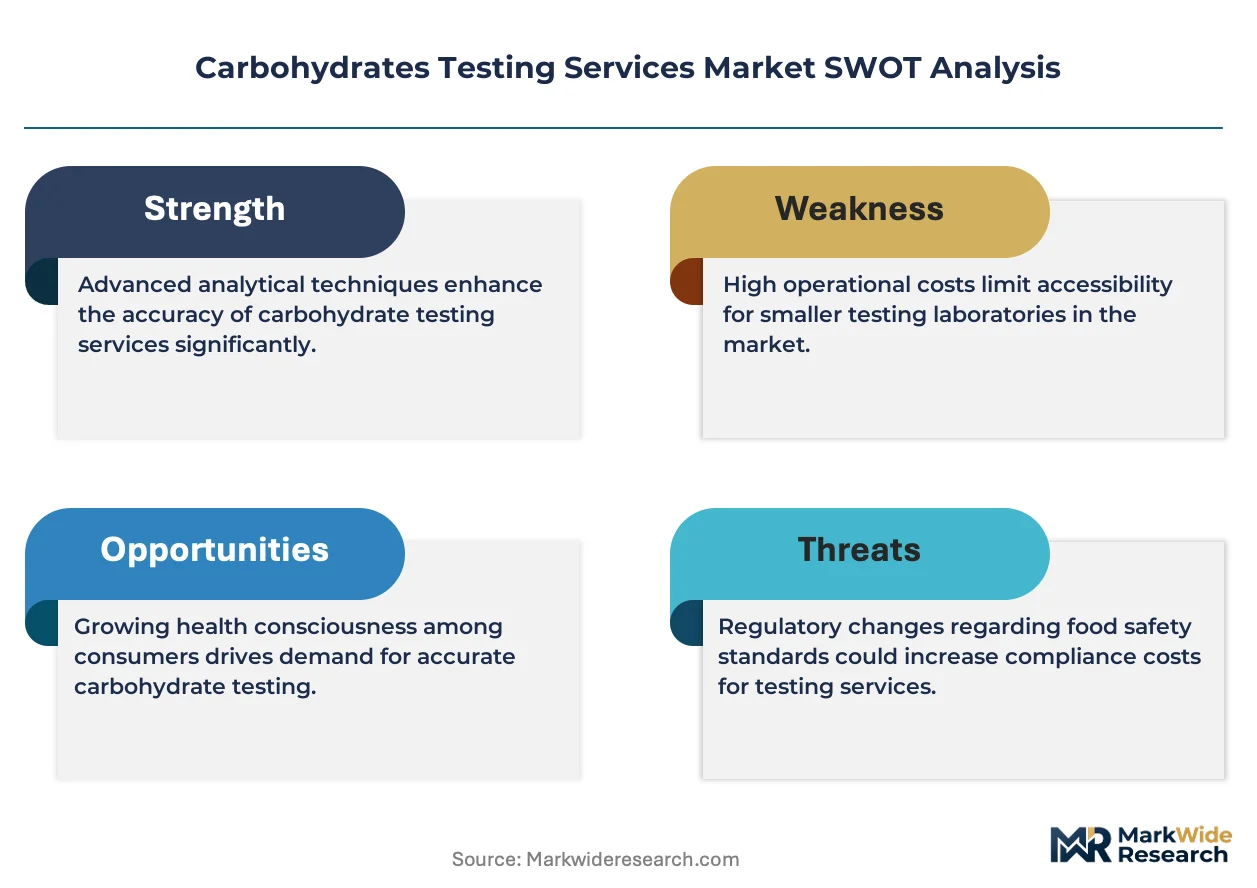
Mass spectrometry-based glycan analysis is fragmenting traditional chromatography workflows across carbohydrate testing laboratories. Eurofins Scientific leverages its pan-European laboratory network to anchor high-volume food carbohydrate profiling for major manufacturers. SGS competes through specialized pharmaceutical glycan sequencing services aligned with FDA biologics guidance. Bureau Veritas sustains market presence by integrating ISO 17025-accredited carbohydrate purity assessment into broader food safety audit programs.
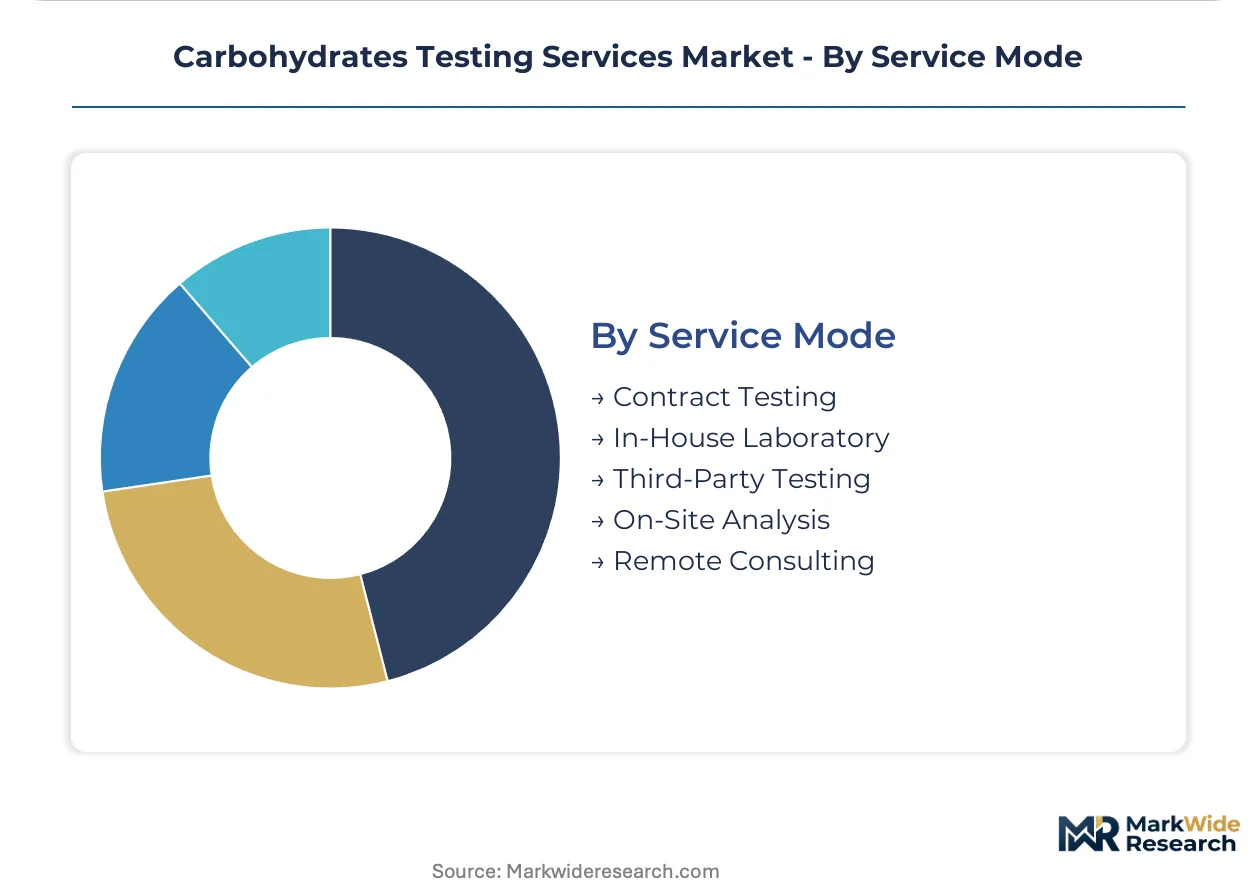
Carbohydrates testing services encompass analytical protocols that quantify, characterize, and verify saccharide composition in raw materials and finished products using techniques such as high-performance anion-exchange chromatography with pulsed amperometric detection, capillary electrophoresis, and tandem mass spectrometry. These services primarily ensure regulatory compliance, nutritional label accuracy, and therapeutic glycoprotein quality in biopharmaceutical manufacturing. Polysaccharide profiling dominates current service revenue due to sustained demand from food manufacturers verifying soluble fiber content and prebiotic claims. Glycan sequencing represents the fastest-expanding test type as pharmaceutical companies advance biosimilar development requiring N-linked glycan mapping for comparability studies. Contract testing occupies the largest share of service mode activity, though third-party testing is gaining traction among mid-sized dietary supplement firms seeking independent verification without capital investment in analytical infrastructure.
FDA nutrition labeling rules for added sugars and dietary fiber, EFSA health claim substantiation requirements, and ISO 17025 laboratory accreditation standards collectively shape service demand and methodological rigor in this market. Regulatory divergence between FDA and EFSA definitions of dietary fiber creates complexity for multinational food manufacturers seeking harmonized testing protocols across jurisdictions. Stakeholders must monitor evolving pharmacopeial monographs for carbohydrate excipients and glycoprotein quality attributes to anticipate shifts in analytical service specifications and laboratory capability investments.
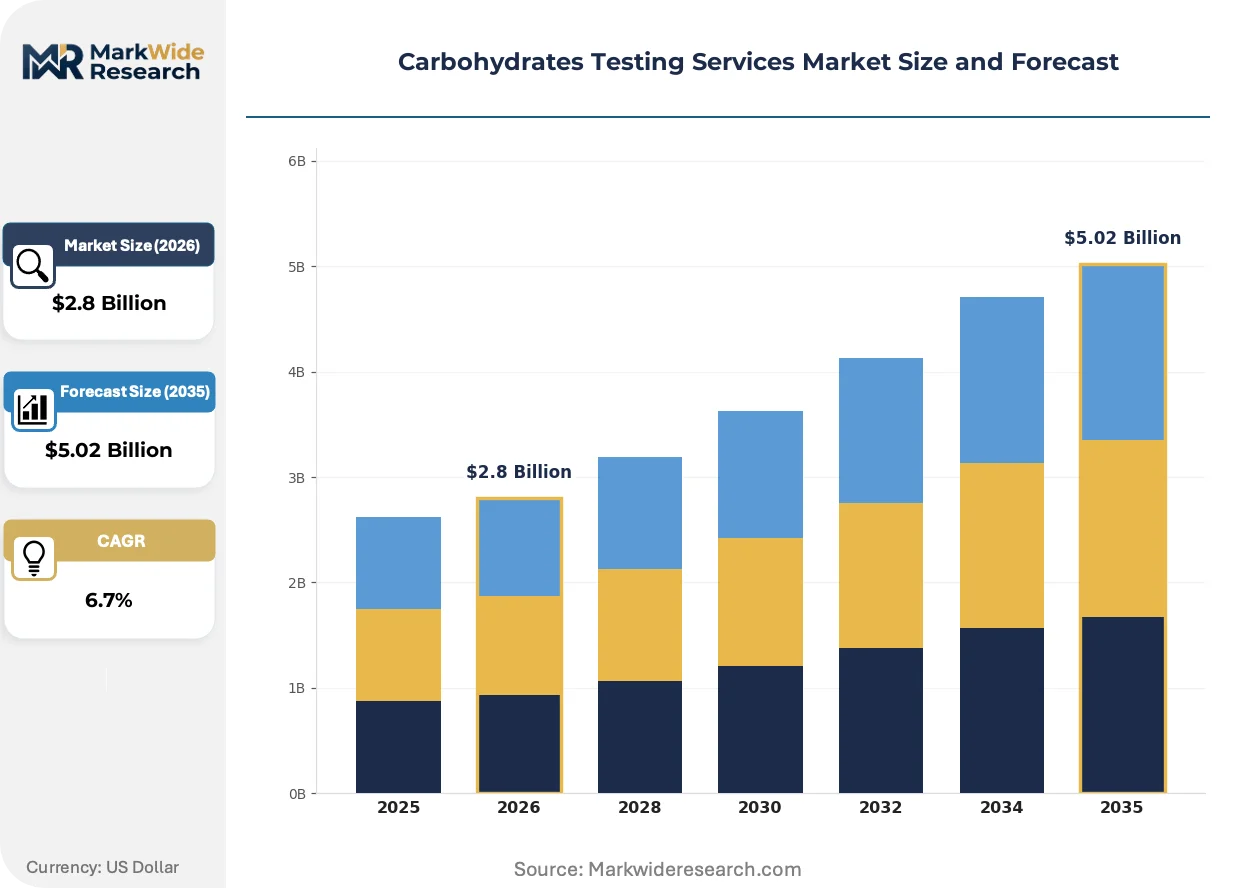
Market Dynamics
Mass spectrometry is hybridizing with chromatography platforms across carbohydrate testing laboratories, compressing analytical timelines while elevating method sensitivity thresholds for glycan characterization workflows.
Growth Catalysts
- FDA added sugars labeling mandates:Food manufacturers in the United States must verify nutritional panel accuracy through third-party carbohydrate quantification, expanding contract laboratory volumes.
- Pharmaceutical glycobiology:Biosimilar developers require N-linked glycan mapping for FDA biologics comparability studies, accelerating demand for specialized sequencing services.
- Germany:EFSA health claim substantiation requirements for prebiotic fiber products drive soluble fiber verification protocols among major European food processors.
Market Restraints
- High-purity solvent supply:Acetonitrile price volatility constrains HPLC method economics for high-throughput quality control operations.
- Mass spectrometer vendor concentration:Instrument supply chains concentrate among three dominant manufacturers, creating procurement bottlenecks for laboratory expansion programs.
- Regulatory divergence:EFSA and FDA maintain incompatible dietary fiber definitions, forcing multinational food companies to duplicate testing protocols across jurisdictions.
Strategic Opportunities
- Japan:METI-funded precision nutrition initiatives create demand for personalized carbohydrate metabolism profiling among dietary supplement manufacturers.
- Capillary electrophoresis-laser induced fluorescence convergence:Combined platforms enable rapid glycan fingerprinting for biopharmaceutical release testing at reduced sample volumes.
- ISO 17025 remote audit protocols:Digital accreditation pathways reduce certification timelines for emerging market laboratories seeking international recognition.
Industry Challenges
- Glycobiology analytical talent:Specialized mass spectrometry operators command premium compensation, constraining laboratory scaling for mid-tier service providers.
- Legacy LIMS integration:Newer mass spectrometry data formats require costly middleware development to connect with established laboratory information management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbohydrates Testing Services Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Monosaccharide Analysis, Disaccharide Quantification, Polysaccharide Profiling, Glycan Sequencing, Carbohydrate Purity Assessment Application: Food Quality Control, Pharmaceutical Research, Biotechnology Development, Nutritional Analysis, Cosmetic Formulation End User Industry: Food Manufacturers, Pharma Companies, Bio-Research Institutes, Dietary Supplement Firms, Personal Care Producers Service Mode: Contract Testing, In-House Laboratory, Third-Party Testing, On-Site Analysis, Remote Consulting |
| Companies Covered | Eurofins Scientific, SGS, Intertek Group, Bureau Veritas, ALS Limited, Mérieux NutriSciences, TÜV SÜD, Reading Scientific Services Ltd, Dextra Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbohydrates Testing Services Market Trends and Innovations
Carbohydrate testing methodologies are converging around multi-modal analytical platforms that compress characterization timelines while expanding molecular coverage across complex glycan structures.
High-resolution mass spectrometry is hybridizing with ion mobility separation for intact glycoprotein analysis. Biopharmaceutical quality control laboratories in the United States and Germany are adopting these platforms for lot release testing. The technology is compressing traditional multi-day chromatography workflows into same-day characterization protocols.
EFSA's evolving guidance on prebiotic health claims is mandating more rigorous polysaccharide structural verification for functional food submissions. European manufacturers must now demonstrate specific molecular weight distributions and linkage patterns beyond simple monosaccharide composition. Dietary fiber testing services are responding by investing in methylation analysis and NMR spectroscopy capabilities.
Subscription-based analytical service contracts are displacing transactional per-sample pricing among mid-sized dietary supplement firms. These arrangements bundle routine carbohydrate profiling with regulatory documentation support, reducing capital burden for manufacturers lacking in-house ISO 17025 infrastructure. The model is gaining traction most visibly among United States-based nutraceutical brands seeking predictable compliance costs.
Carbohydrates Testing Services Market Segmentation
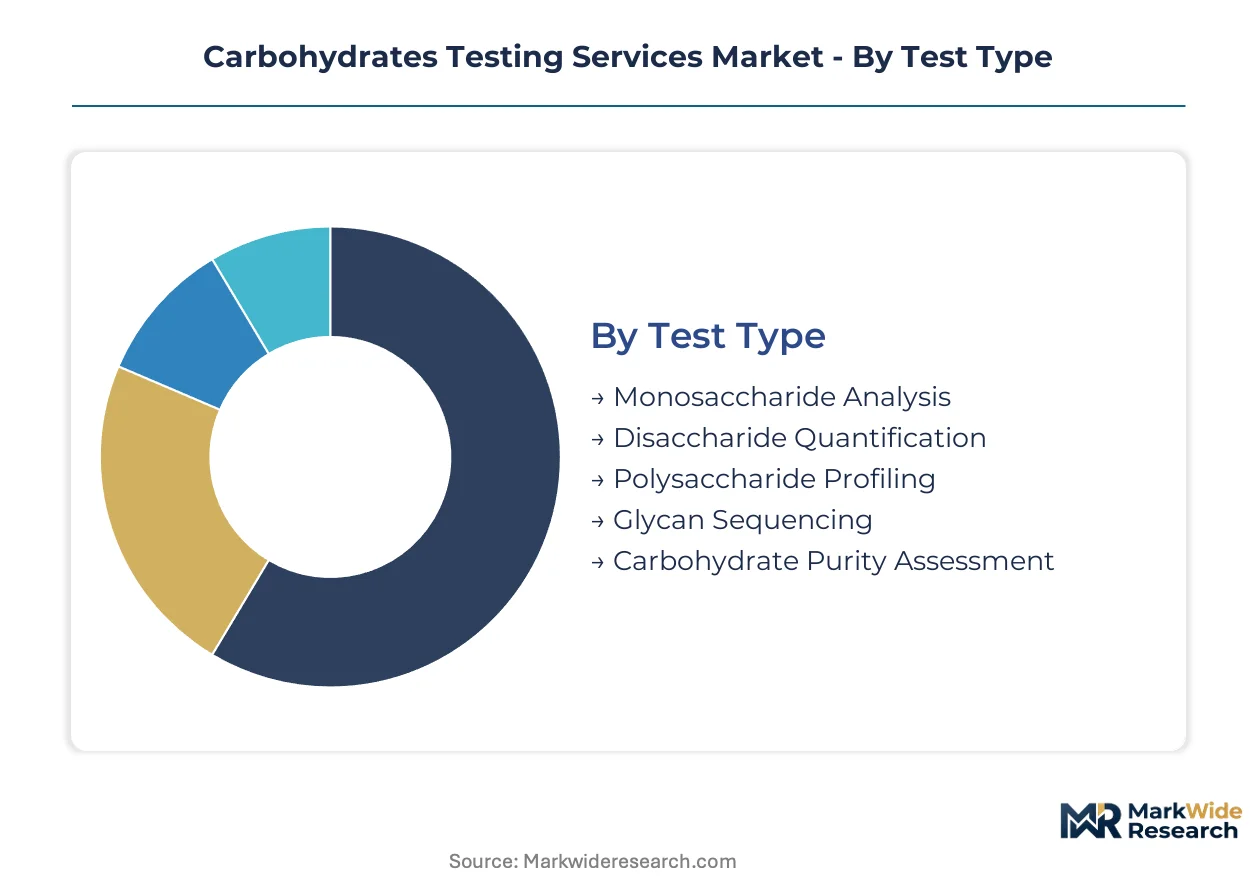
Carbohydrate testing services fragment across multiple technical and commercial dimensions, with test complexity and regulatory urgency driving divergent margin profiles. Contract laboratories calibrate capacity investments against the velocity of each segment's analytical cycle.
Test Type:
Polysaccharide profiling and glycan sequencing operate at opposite ends of the analytical timeline, with routine fiber verification compressing turnaround to hours while biopharmaceutical glycan mapping extends across multiple days.
- Polysaccharide Profiling:Quantifies complex carbohydrate structures including molecular weight distributions and linkage patterns in dietary fibers and prebiotics. Food manufacturers across Germany and the United States commission these services to substantiate EFSA health claims and FDA-compliant fiber declarations on nutritional panels.
- Glycan Sequencing:Maps N-linked and O-linked glycan structures on therapeutic glycoproteins using tandem mass spectrometry workflows. Biosimilar developers in Japan and the United States require these analyses for FDA comparability studies, with each characterization cycle spanning three to five business days.
- Monosaccharide Analysis:Identifies individual sugar units through chromatographic separation for raw material verification.
- Disaccharide Quantification:Measures sucrose, lactose, and maltose concentrations in processed foods and infant nutrition products.
- Carbohydrate Purity Assessment:Validates excipient grade specifications for pharmaceutical formulations against pharmacopeial monographs.
Polysaccharide profiling anchors the volume base while glycan sequencing gains share at the steepest rate.
Application:
Pharmaceutical research commands premium pricing per sample, whereas food quality control generates scale through repetitive batch testing of standardized matrices.
- Food Quality Control:Verifies carbohydrate content, fiber claims, and added sugars declarations in finished products. Major manufacturers in the United States rely on third-party laboratories to satisfy FDA nutrition labeling mandates for soluble and insoluble fiber quantification.
- Pharmaceutical Research:Supports glycoprotein characterization, biosimilar development, and carbohydrate-based drug delivery systems. German biopharmaceutical clusters drive demand for high-resolution glycan mapping to meet EMA quality guidelines.
- Biotechnology Development:Enables cell culture medium optimization and glycoengineering of recombinant proteins.
- Nutritional Analysis:Supports precision nutrition programs and metabolic research initiatives.
- Cosmetic Formulation:Validates polysaccharide functionality in skin hydration and texture modification claims.
Food quality control sustains the highest absolute revenue while pharmaceutical research delivers the strongest margin expansion.
End User Industry:
Capital intensity and regulatory exposure separate large-scale manufacturers from research organizations with project-based procurement patterns.
- Food Manufacturers:Multinational processors in the United States and Germany outsource routine carbohydrate verification to ISO 17025-accredited laboratories. FDA added sugars labeling rules and EFSA prebiotic claim requirements compel sustained contract testing volumes across breakfast cereal, beverage, and bakery categories.
- Pharma Companies:Biologics developers require glycan characterization for lot release and comparability documentation. Japanese pharmaceutical manufacturers leverage METI-funded precision glycobiology initiatives to advance biosimilar portfolios.
- Bio-Research Institutes:Academic and government laboratories conduct fundamental carbohydrate metabolism studies.
- Dietary Supplement Firms:Mid-sized nutraceutical brands seek independent fiber verification without capital investment in analytical infrastructure.
- Personal Care Producers:Cosmetic manufacturers validate hyaluronic acid and plant polysaccharide specifications.
Food manufacturers generate the deepest order backlogs while pharma companies drive adoption of advanced mass spectrometry platforms.
Service Mode:
Asset ownership models diverge sharply, with capital-constrained end users gravitating toward variable-cost arrangements while large manufacturers balance control against scale.
- Contract Testing:Dominates revenue as external laboratories absorb instrument depreciation and specialist labor costs. Eurofins Scientific and SGS capture major food and pharmaceutical accounts through pan-regional laboratory networks with harmonized methods.
- Third-Party Testing:Expanding among mid-sized dietary supplement firms seeking independent verification without long-term contractual commitments. United States-based nutraceutical brands particularly favor per-sample pricing for seasonal product launches.
- In-House Laboratory:Reserved for large manufacturers with sufficient throughput to justify HPLC and mass spectrometry capital expenditure.
- On-Site Analysis:Deployed for supply chain audits and raw material intake verification at manufacturing facilities.
- Remote Consulting:Delivers regulatory documentation support and method development guidance without physical sample handling.
Contract testing captures the majority of current activity while third-party testing expands most quickly among emerging market entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German contract laboratories export carbohydrate testing services to food manufacturers across the European Union, while Japanese analytical firms supply glycan characterization to biosimilar developers in the United States and Southeast Asia.
United States
FDA added sugars labeling mandates and biologics comparability guidelines drive sustained demand for third-party carbohydrate quantification and glycan mapping. The FDA's 2020 fiber definition updates compel manufacturers to verify soluble and insoluble content through accredited laboratories. Boston and San Diego biopharmaceutical clusters anchor specialized glycobiology service capacity for therapeutic protein developers.
Germany
EFSA health claim substantiation requirements for prebiotic fibers and pharmaceutical glycoprotein quality standards create dual demand streams. Germany's national food safety authority enforces strict analytical documentation for functional food submissions. The Rhine-Main and Upper Bavaria regions concentrate ISO 17025-accredited laboratories serving both European food processors and EMA-regulated biopharmaceutical manufacturers.
Japan
METI-funded precision nutrition initiatives and biosimilar development programs accelerate demand for advanced carbohydrate metabolism profiling. Japan's national pharmaceutical regulator mandates rigorous glycan characterization for biologics lot release. The Kanto region around Tokyo hosts specialized analytical service providers supporting both domestic pharmaceutical firms and export-oriented nutraceutical brands.
United Kingdom
Post-Brexit regulatory divergence from EU food labeling standards forces manufacturers to maintain parallel testing protocols for domestic and continental markets. The UK Food Standards Agency enforces distinct fiber measurement methodologies compared to EFSA guidelines. The Southeast England corridor retains significant contract testing infrastructure serving multinational food and pharmaceutical companies navigating dual compliance requirements.
Switzerland
Swissmedic's stringent biologics quality guidelines and the country's pharmaceutical manufacturing concentration sustain premium demand for glycan sequencing services. Swiss precision nutrition research programs require specialized carbohydrate characterization for personalized health applications. The Basel biotech cluster and Zurich analytical service corridor anchor high-margin pharmaceutical testing operations serving global drug developers.
Carbohydrates Testing Services Market Competitive Landscape
On the supply side, the industry is consolidating around pan-regional laboratory networks capable of harmonizing methods across multiple regulatory jurisdictions. Three strategic archetypes dominate: diversified testing conglomerates with food-pharma cross-capability, specialized glycobiology boutiques serving biopharmaceutical developers, and mid-tier regional players competing on turnaround speed. M&A activity concentrates on acquiring ISO 17025-accredited facilities in high-growth markets, while technology licensing agreements accelerate mass spectrometry platform standardization.
Within the diversified conglomerate tier, Eurofins Scientific and SGS exemplify scale-driven positioning through extensive laboratory networks spanning multiple continents. Bureau Veritas occupies a distinct archetype as an integrated certification and testing provider, bundling carbohydrate analysis with broader food safety audit programs. These three entities collectively represent the dominant competitive configuration, with each anchoring a different value proposition: Eurofins Scientific through geographic coverage density, SGS through pharmaceutical specialization depth, and Bureau Veritas through compliance integration breadth.
| Leading Market Players |
|---|
| Eurofins Scientific |
| SGS |
| Intertek Group |
| Bureau Veritas |
| ALS Limited |
| Mérieux NutriSciences |
| TÜV SÜD |
| Reading Scientific Services Ltd |
| Dextra Laboratories |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Main laboratory cluster anchors European carbohydrate testing capacity, with ISO 17025-accredited facilities in Frankfurt and Darmstadt translating instrument depreciation burdens into tiered service pricing for pharmaceutical glycan mapping. Food manufacturers in Germany and the United States absorb these cost structures through subscription contracts that bundle routine polysaccharide profiling with regulatory documentation support.
Pricing Analysis
Next-generation mass spectrometry platforms command 40-60% premiums over legacy HPLC workflows for glycan sequencing services, while prior-generation enzymatic assays retreat to commodity pricing for routine fiber verification. Contract testing dominates through project-based pricing for pharmaceutical clients and subscription models for food manufacturers. Price differentiation centers on ISO 17025 accreditation tier and sample turnaround velocity. Pricing pressure stems from acetonitrile solvent cost volatility constraining HPLC margin economics. Mid-sized dietary supplement firms exhibit highest price sensitivity, while biologics developers prioritize analytical rigor over per-sample cost.
Supply Chain Analysis
Upstream feedstock concentration in acetonitrile manufacturing centers on Germany, the United States, and China, with pharmaceutical-grade solvent purity specifications limiting qualified supplier pools. Laboratory instrumentation draws from mass spectrometer production in the United States, Germany, and Japan, while chromatography columns source from specialized polymer manufacturers in the United States and Switzerland. Single-source vulnerability concentrates in high-resolution mass spectrometer procurement, where three dominant vendors control component supply. Distribution runs through pan-regional laboratory networks with harmonized methods across jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbohydrate testing services fragment across regulatory jurisdictions and analytical complexity tiers, with FDA-EFSA fiber definition divergence creating service niches for laboratories capable of dual-protocol execution.
For Market Incumbents: Pre-empt emerging specialized glycobiology boutiques by acquiring ISO 17025-accredited facilities in Japan and Switzerland, where METI-funded precision nutrition initiatives and Swissmedic biologics guidelines concentrate premium demand. Defend against mass spectrometry platform commoditization through backward integration into proprietary glycan database development, locking in biosimilar developer relationships via comparability study archives. For New Entrants and Emerging Players: Southeast Asian pharmaceutical manufacturing corridors present underpenetrated demand for glycan release testing, with Singapore and South Korea biologics facilities lacking local sequencing capacity. Target mid-tier dietary supplement firms in the United States with third-party per-sample pricing for seasonal fiber verification, avoiding capital-intensive subscription model competition with established contract laboratories. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because FDA and EFSA divergence deepens analytical service moats for laboratories with multi-jurisdictional accreditation. Acquisition candidates include specialized glycobiology boutiques with N-linked glycan mapping expertise and established biopharmaceutical client relationships. Watch EFSA prebiotic health claim guidance revisions as inflection indicators for polysaccharide structural verification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Mass Spectrometry Platform Acquisition | High-resolution glycan mapping capability secures biosimilar developer contracts under FDA comparability guidelines. |
| ISO 17025 Accreditation Expansion | Multi-jurisdictional certification enables single-source testing for multinational food manufacturers navigating EFSA-FDA divergence. |
| Glycan Database Development | Proprietary comparability study archives create switching costs for biologics developers seeking lot release documentation. |
| Capillary Electrophoresis Integration | Laser-induced fluorescence platforms reduce sample volumes for biopharmaceutical release testing at premium pricing. |
| Remote Audit Protocol Investment | Digital ISO 17025 certification pathways accelerate emerging market laboratory recognition and capacity scaling. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with laboratory directors at Eurofins Scientific, SGS, and Bureau Veritas, regulatory affairs managers at multinational food manufacturers, and glycobiology specialists at Japanese and German pharmaceutical firms. Secondary validation drew from FDA guidance documents, EFSA scientific opinions, ISO 17025 accreditation registries, and pharmacopeial monographs. Bottom-up testing volume estimates triangulated against top-down market sizing from instrument vendor shipment data and laboratory capacity utilization surveys.
Calibration against historical contract testing revenue disclosures and mass spectrometer installation bases anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include test type complexity tier, end-user industry capital intensity, service mode asset ownership structure, and regional regulatory cluster. CAGRs derived from instrument replacement cycles and regulatory mandate implementation timelines, with pharmaceutical glycobiology R&D expenditure trajectories and food manufacturer outsourcing propensity indices serving as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by diversified testing conglomerates or rapid EFSA-FDA harmonization would shift outcomes beyond modeled ranges. Cross-checking against mass spectrometer vendor order backlogs and ISO 17025 accreditation application volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Safety Testing
Food Safety Testing Services Market
Food Safety Testing
Rapid Microbiology Testing Market
Food Safety Testing
US Food Safety Testing Market
Food Safety Testing
Ireland Food Testing Market
Food Safety Testing
Meat Species Identification Kits Market
Food Safety Testing
Water Activity Meter Market
Food Safety Testing
Food Tester Market
Food Safety Testing
Italy Food Safety Testing Market
Food Safety Testing
Food and Beverages Disinfection Market
Food Safety Testing
Food Testing Services Market
Food Safety Testing
Water Quality Testing Market
Food Safety Testing
South Africa Food Safety Testing Market
Food Safety Testing
Food Traceability Solutions Market
Food Safety Testing
Chromatography Food Testing Market
Food Safety Testing
Dairy Testing Services Market
Food Safety Testing
Food Allergen Testing Market