
 Mexico Meat Products Market | 2026-2036
Mexico Meat Products Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Meat Products Market Insights
NOM-243-SSA1-2010 sanitary standards for meat processing is expanding quality compliance requirements across Mexican slaughterhouses and cold-chain facilities. Sigma Alimentos leverages its vertically integrated distribution network to maintain shelf-stable product penetration in urban centers. Industrias Bachoco sustains poultry supply dominance through captive feed-milling operations across Guanajuato and Querétaro. SuKarne anchors beef exports to Asian markets via its Sinaloa-based processing complex.
Mexico meat products encompass fresh, chilled, frozen, and processed animal proteins derived from cattle, swine, and poultry, typically processed under HACCP protocols with controlled temperature maintenance from slaughter through retail. These products serve household consumption, restaurant procurement, and industrial food manufacturing across formal and informal channels. Beef and poultry categories command the largest volume positions, with processed meat registering the fastest value growth as time-constrained urban consumers shift toward marinated cuts and ready-to-cook formats. Supermarkets and wholesalers capture the dominant share of distribution value, though online retail is gaining traction among middle-income households in Mexico City and Monterrey metropolitan zones.
COFEPRIS enforces microbiological and labeling standards that determine market access for domestic processors and imported alternatives. SENASICA operates federal inspection protocols at TIF-certified plants that govern export eligibility to the United States and Japan. Mexico's Secretariat of Economy coordinates PLI-aligned incentives for cold-chain infrastructure modernization in priority agricultural states. Stakeholders must monitor pending updates to NOM standards and bilateral SPS negotiations to anticipate compliance cost trajectories and export corridor viability.
Market Dynamics
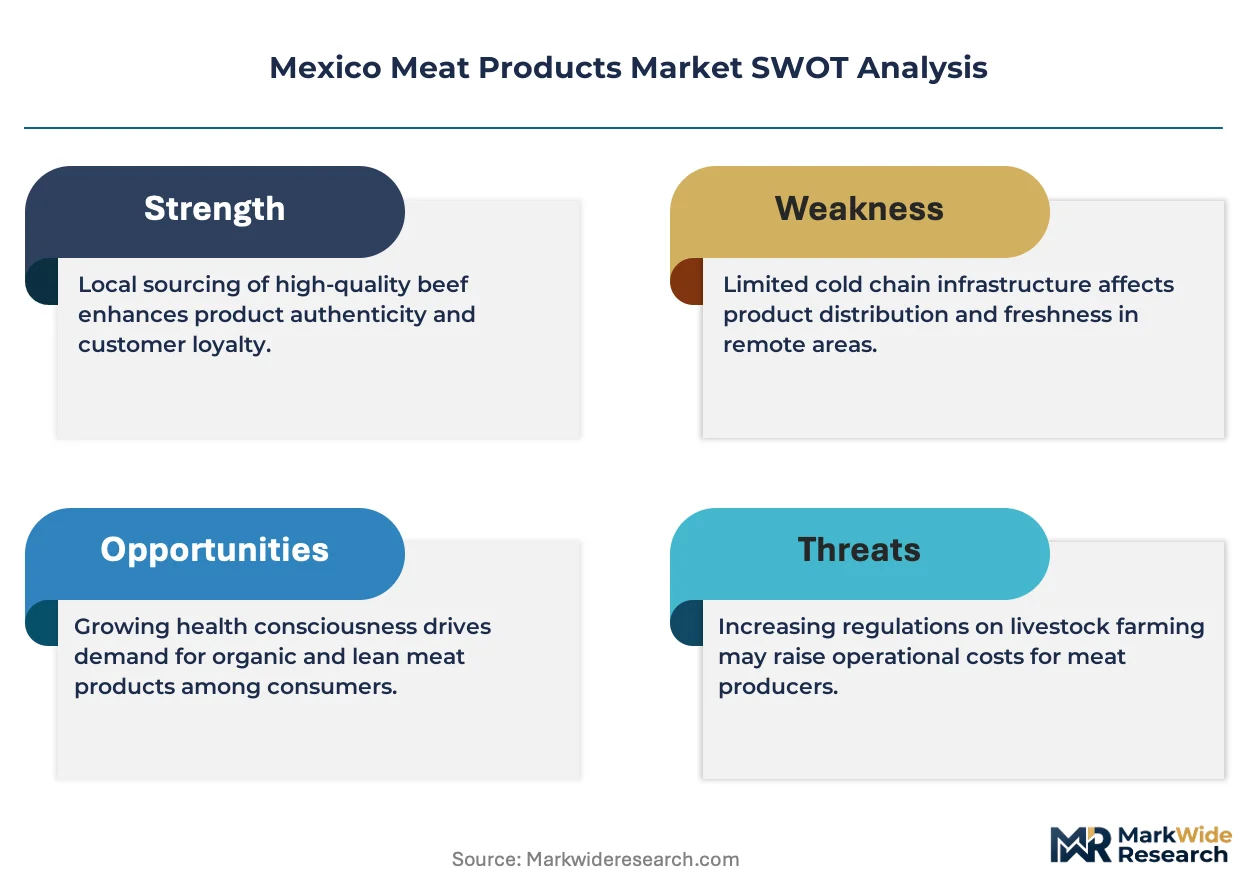
NOM-243-SSA1-2010 sanitary standards are compressing compliance timelines for Mexican slaughterhouses while concentrating processing capacity among TIF-certified facilities that can absorb certification costs.
Growth Catalysts
- Food service channel expansion:Quick-service restaurants and hotel chains in Mexico City, Guadalajara, and Monterrey are expanding protein procurement volumes as tourism and urban dining recover post-pandemic.
- COFEPRIS labeling modernization:Updated nutritional disclosure requirements are pushing processors toward cleaner-label formulations that command shelf-space premiums in supermarket channels.
- Bajío industrial corridor concentration:Guanajuato and Querétaro host expanding cold-chain infrastructure that reduces logistics costs for processors serving central Mexico demand.
Market Restraints
- Feed grain input volatility:Yellow corn and soybean meal prices fluctuate with US Midwest harvest conditions, compressing margins for poultry and pork integrators who lack captive grain sourcing.
- TIF plant concentration risk:Export-eligible beef and poultry processing clusters in Sinaloa and Sonora face single-point-of-failure exposure during climate disruptions or labor disputes.
- SENASICA inspection bottlenecks:Federal veterinarian staffing gaps at border inspection posts delay cross-border shipments to US markets during peak seasonal demand windows.
Strategic Opportunities
- Ready-to-cook format penetration:Marinated and pre-portioned meat products remain underdeveloped in Mexico's informal retail sector, creating white space for branded processors.
- SENASICA-negotiated Japan access:Expanded beef export quotas to Japanese markets reward processors who invest in traceability systems and aged-cattle finishing programs.
- Online grocery channel emergence:Mexico City and Monterrey metropolitan households are adopting e-commerce meat subscriptions, opening direct-to-consumer routes bypassing traditional wholesale layers.
Industry Challenges
- HACCP auditor scarcity:COFEPRIS-certified food safety professionals concentrate in major urban centers, forcing rural processors to absorb travel costs or delay certification timelines.
- Cold-chain capex intensity:Blast freezing and controlled-atmosphere storage equipment requires substantial upfront investment that informal sector slaughterhouses cannot access through traditional credit channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Meat Products Market |
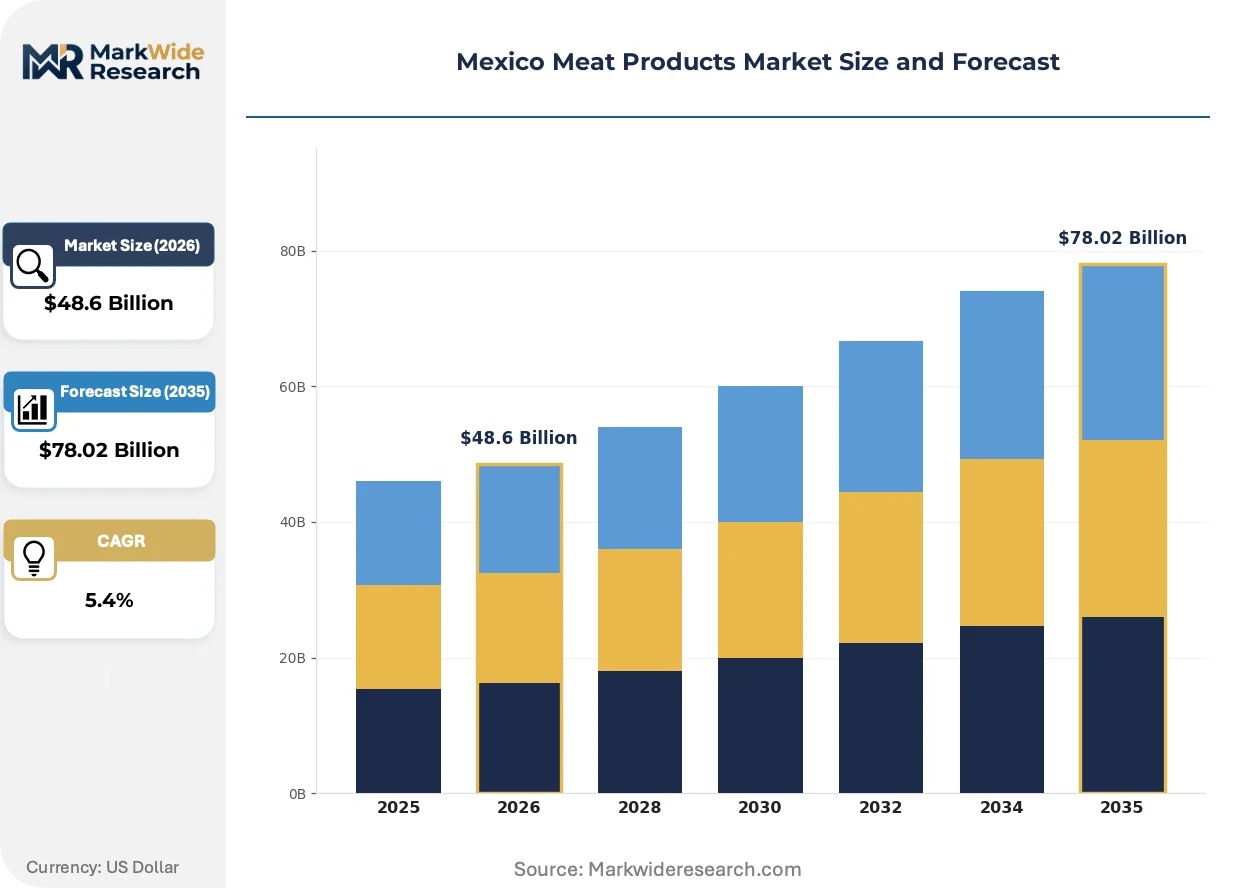
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $78.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Poultry, Processed Meat Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesalers End User: Households, Restaurants, Food Service, Retailers Packaging Type: Vacuum Packs, Cans, Trays, Wrappers |
| Companies Covered | SuKarne, Sigma Alimentos, Industrias Bachoco, Grupo Kuo, Grupo Arias, Frigorifica Contreras, Procarne, Carnes ViBa, Grupo BaFar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Meat Products Market Trends and Innovations
Digital traceability systems and automated processing equipment are compressing quality-control cycles while NOM standard updates force rapid facility upgrades across Mexican meat operations.
Blockchain-enabled livestock tracking is unifying herd-origin data with slaughterhouse processing records and retail packaging labels. Large supermarket chains in Mexico City are piloting these systems to satisfy COFEPRIS audit requirements. The technology is unifying previously siloed supply chain data into single-source verification platforms that reduce recall response times.
SENASICA's updated TIF certification protocols are mandating video monitoring and automated temperature logging at federal inspection points. Medium-sized processors in Jalisco and Michoacán are retrofitting facilities to meet these standards ahead of enforcement deadlines. Poultry slaughterhouses with existing automation infrastructure are adapting fastest, while smaller beef operations face extended compliance timelines.
Urban households in Monterrey and Guadalajara are consolidating weekly meat purchases into fewer, larger transactions through membership-based warehouse clubs. Traditional neighborhood butcher shops are losing share to these formats as consumers prioritize price transparency and standardized portion sizes. This pattern is most visible among dual-income professional households with limited weekday shopping windows.
Mexico Meat Products Market Segmentation
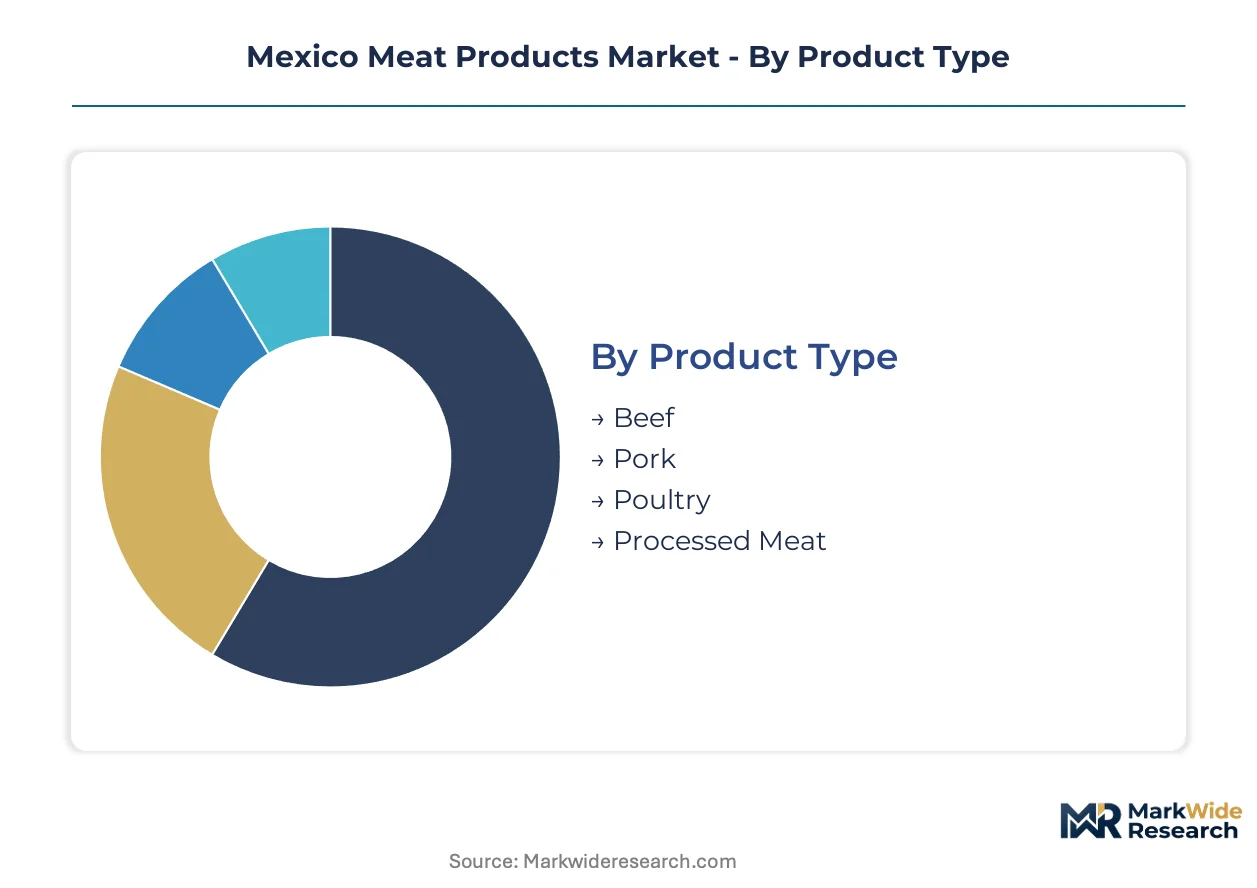
Segmentation in the Mexico meat products market reveals how protein flows diverge across channels and end-uses. COFEPRIS labeling requirements and SENASICA certification tiers create natural partitions that processors must navigate to reach distinct buyer groups.
Product Type:
Fresh proteins operate as standalone commodities requiring minimal processing infrastructure, while processed formats demand embedded cold-chain and formulation capabilities that concentrate among TIF-certified operators.
- Beef:Carcass and primal cuts dominate formal retail and restaurant procurement in Mexico City and Monterrey. Demand concentrates in premium steakhouses and upscale supermarket channels where SENASICA traceability commands price premiums over informal sector alternatives.
- Poultry:Whole birds and cut portions serve as the protein foundation for quick-service restaurants and household bulk purchasing. Industrias Bachoco's captive feed operations in Guanajuato anchor supply stability that pork and beef segments cannot replicate.
- Pork:Fresh cuts and processed varieties fill intermediate price positioning between beef and poultry. Bajío corridor processors leverage proximity to Guadalajara's wholesale markets to compress logistics costs.
- Processed Meat:Marinated, cured, and ready-to-cook formats embed seasoning and portion-control functions that urban dual-income households prioritize for weekday meal preparation.
Volume placements concentrate in poultry; the faster expansion belongs to processed meat.
Distribution Channel:
Channel selection in Mexico tracks household income stratification and refrigeration access, with cost tiers separating formal retail from informal procurement patterns.
- Supermarkets:Organized retail chains in metropolitan zones capture middle-income households seeking standardized portioning and COFEPRIS-compliant labeling. These outlets require suppliers to maintain HACCP documentation and cold-chain integrity from distribution center to display case.
- Wholesalers:Restaurant and hotel procurement flows through centralized meat markets in Mexico City, Guadalajara, and Monterrey. Volume discounts and direct relationships with TIF-certified processors dominate transaction logic.
- Convenience Stores:Small-format retail in dense urban neighborhoods stocks limited fresh meat SKUs alongside processed and frozen alternatives.
- Online Retail:E-commerce platforms serving Mexico City and Monterrey metropolitan areas are gaining traction among time-constrained professionals seeking subscription-based protein delivery.
Transaction value clusters with supermarkets; channel expansion is climbing the fastest among online retail formats.
End User:
End-use segmentation separates household consumption patterns from institutional procurement volumes, with customer type determining specification rigor and delivery frequency requirements.
- Restaurants:Full-service and quick-service operators in tourism-dependent zones demand consistent portion weights and delivery scheduling that informal slaughterhouses cannot satisfy. SENASICA certification opens access to hotel chains with corporate procurement standards.
- Households:Weekly bulk purchasing at membership clubs is displacing traditional neighborhood butcher relationships in Monterrey and Guadalajara professional districts.
- Food Service:Institutional caterers and centralized kitchens for corporate campuses require frozen and pre-portioned formats that reduce on-site labor.
- Retailers:Independent meat shops and small grocery operators in secondary cities source through regional wholesalers rather than direct processor relationships.
Procurement volume concentrates with restaurants; the steepest expansion trajectory belongs to food service channels.
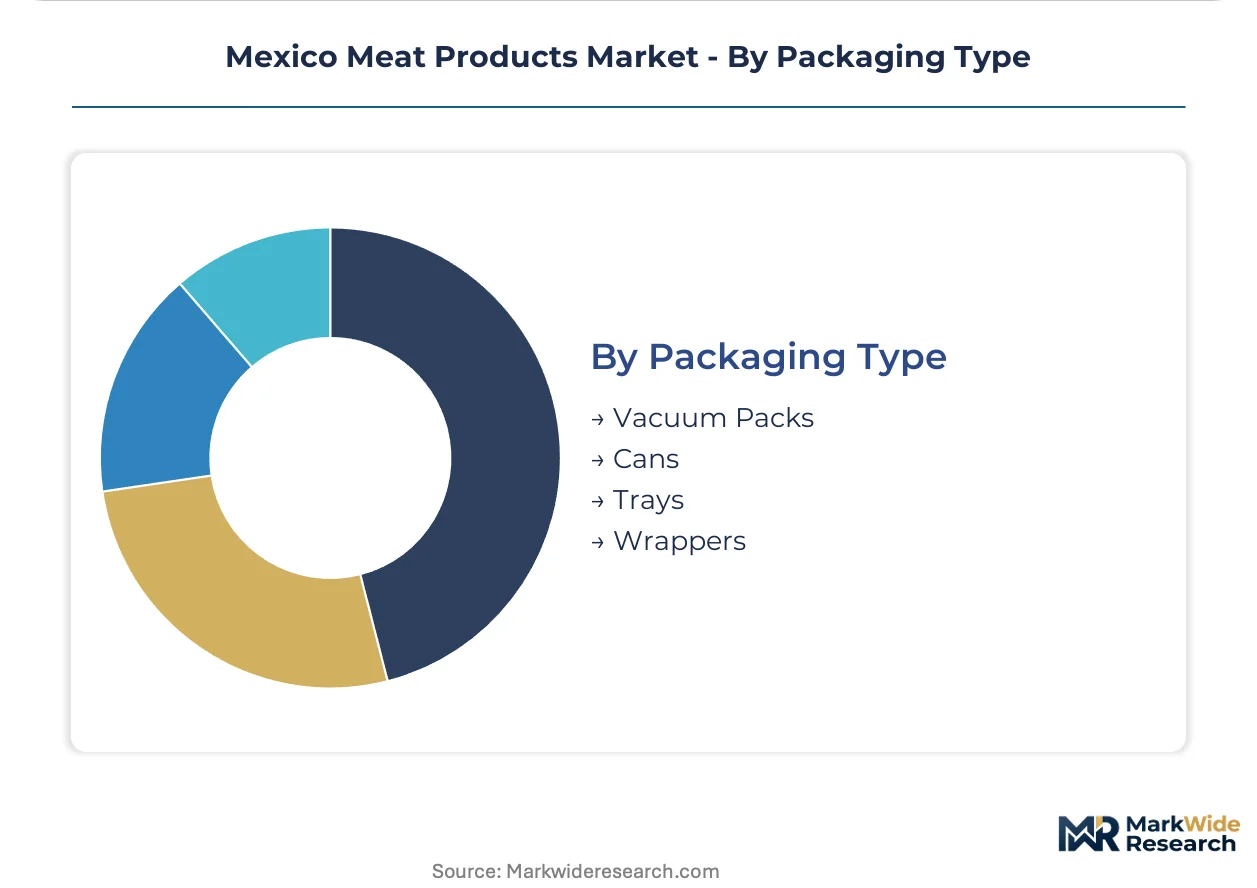
Packaging Type:
Packaging selection maps to shelf-life requirements and retail format constraints, with technology maturity separating vacuum and modified-atmosphere systems from basic wrapping methods.
- Vacuum Packs:Barrier films removing oxygen extend retail case life for fresh beef and pork cuts in supermarket self-service cases. COFEPRIS labeling mandates are pushing adoption of standardized vacuum formats with integrated nutritional panels.
- Trays:Foam or rigid plastic bases with overwrap film dominate poultry display presentation across Mexican retail formats.
- Cans:Shelf-stable processed meats including ham and luncheon meats serve rural markets with limited cold-chain infrastructure.
- Wrappers:Basic polyethylene film covers remain prevalent in traditional butcher shops and informal sector transactions.
Packaging volume concentrates in vacuum packs; the fastest technology adoption is occurring with tray formats incorporating modified atmosphere capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico City anchors national meat consumption through its dense concentration of hotel chains, restaurant groups, and organized retail headquarters that coordinate procurement across central Mexico.
Mexico City Metropolitan Zone
Quick-service restaurant expansion and tourism recovery drive protein demand in the capital's hospitality corridor. COFEPRIS labeling modernization pushes processors toward cleaner-label formulations for supermarket shelf placement. Santa Fe and Polanco districts host corporate procurement offices that aggregate volumes for national retail chains.
Nuevo León
Monterrey's industrial base sustains above-average beef consumption among professional households with limited weekday shopping windows. SENASICA inspection protocols at border posts govern cross-border shipment timing to Texas markets. Apodaca and Guadalupe municipalities concentrate cold-storage facilities serving northeastern Mexico.
Jalisco
Guadalajara's wholesale markets channel pork and poultry volumes to restaurant operators across western states. State-level agricultural incentives support cold-chain infrastructure upgrades in priority zones. Tlajomulco de Zúñiga hosts expanding distribution centers that compress logistics costs for Bajío-serving processors.
Bajío Region
Guanajuato and Querétaro combine captive feed-milling with poultry processing density unmatched elsewhere in Mexico. PLI-aligned federal incentives reward cold-chain modernization investments in these priority agricultural states. Celaya and Irapuato industrial corridors attract processors seeking proximity to central Mexico demand.
Northern Border States
Sinaloa and Sonora anchor beef export eligibility through TIF-certified plant concentration serving Asian markets. Climate disruption and labor dispute risks create single-point-of-failure exposure for export volumes. Culiacán and Hermosillo processing complexes invest in traceability systems to maintain Japan market access.
Mexico Meat Products Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers, with TIF-certified operators capturing export premiums while informal slaughterhouses serve price-sensitive local markets. The vendor base concentrates among vertically integrated poultry specialists and diversified protein conglomerates with captive distribution networks. Two strategic archetypes dominate: scale-driven integrators controlling feed-to-retail value chains, and regionally focused beef processors leveraging geographic proximity to export corridors. Competitive moves center on cold-chain capacity expansion and SENASICA certification acquisition to unlock export quotas.
Among Mexico-based operators, SuKarne and Sigma Alimentos occupy positions at opposite ends of the protein spectrum, with the former exemplifying export-oriented beef specialization and the latter representing diversified processed-food penetration through urban retail channels. Industrias Bachoco anchors the poultry-integrated archetype through Guanajuato-based feed-milling density. These three entities collectively illustrate how certification access, geographic positioning, and channel control separate margin tiers in Mexican meat processing.
| Leading Market Players |
|---|
| SuKarne |
| Sigma Alimentos |
| Industrias Bachoco |
| Grupo Kuo |
| Grupo Arias |
| Frigorifica Contreras |
| Procarne |
| Carnes ViBa |
| Grupo BaFar |
| Others |
Pricing and Supply Chain Analysis
Chicago Board of Trade yellow corn futures cascade through Mexican poultry and pork integrators, compressing margins for operators lacking captive feed-milling capacity while concentrating pricing power among Guanajuato-based operators with backward-integrated grain sourcing.
Pricing Analysis
Yield-per-bird throughput metrics anchor value-based pricing for Industrias Bachoco's contract poultry sales to quick-service restaurant chains. Three-tier pricing structure across SENASICA-certified premium, TIF-compliant standard, and informal-economy economy levels separates export-eligible beef from domestic-channel pork and uninspected local slaughterhouse output. Cost compression in the standard tier is intensifying because COFEPRIS labeling modernization forces reformulation investments. Quick-service restaurants exhibit lowest price sensitivity due to menu-price pass-through capability; traditional neighborhood butcher shops face highest sensitivity with thin working-capital buffers.
Supply Chain Analysis
Federal veterinarian staffing gaps at Sinaloa and Sonora TIF plants constrain workforce availability in Mexico's primary beef-export manufacturing geographies. Feed grain draws from US Midwest harvests, soybean meal from Argentine crushing operations, and breeding stock from Canadian genetics suppliers. Single-source vulnerability concentrates in Sinaloa's Culiacán processing complex, which anchors Japan-bound beef export eligibility. Distribution runs through Bajío corridor cold-storage hubs serving central Mexico supermarket and wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NOM-243-SSA1-2010 sanitary standards erect a cost-of-compliance barrier that rewards TIF-certified incumbents while excluding informal slaughterhouses from formal retail and export channels.
For Market Incumbents: Anchor market position through SENASICA certification acquisition at secondary Jalisco and Michoacán facilities before enforcement deadlines tighten. Expand captive feed-milling capacity in Guanajuato to offset Chicago Board of Trade grain volatility threatening poultry margin structures. Defend against emerging ready-to-cook format specialists by controlling supermarket shelf-space allocation through direct distribution relationships. For New Entrants and Emerging Players: Launch via online subscription models targeting Monterrey and Mexico City metropolitan professionals seeking portion-controlled protein delivery. White space concentrates in marinated beef formats for informal retail sectors where traditional butchers lack formulation capability. Penetrate through direct-to-consumer routes bypassing wholesale margin layers that incumbent conglomerates dominate. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale beef processors in Jalisco with incomplete TIF certification but established Sinaloa logistics relationships. Five-to-ten-year viability hinges on Japan quota expansion rewarding traceability infrastructure investments. Monitor SENASICA veterinarian staffing appropriations as inflection indicator for cross-border shipment velocity and working-capital efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| TIF Certification Acquisition | Unlocks Japan beef export quotas requiring SENASICA traceability protocols. |
| Cold-Chain Infrastructure Expansion | Reduces spoilage losses in Bajío corridor serving central Mexico demand clusters. |
| Ready-to-Cook Format Development | Captures time-constrained urban households shifting from traditional butcher relationships. |
| Backward Integration into Feed Milling | Insulates poultry margins from Chicago Board of Trade yellow corn volatility. |
| Blockchain Traceability Implementation | Satisfies COFEPRIS audit requirements for supermarket chain supply contracts. |
Research Methodology
Multi-period observation of SENASICA certification timelines, COFEPRIS enforcement patterns, and TIF plant capacity utilization anchored the trend analysis, supplemented by interviews with plant operations managers at Bajío corridor processors, procurement directors at Mexico City quick-service restaurant chains, SENASICA federal veterinarians, cold-storage facility engineers, and supermarket category buyers. Secondary validation drew from Mexican Secretariat of Economy PLI incentive disclosures, USGS feed grain trade statistics, COFEPRIS labeling regulation updates, and Japan MAFF beef import quota announcements. Bottom-up channel volume estimates triangulated against top-down protein consumption per-capita benchmarks.
Input-output matrices mapped feed grain costs, labor availability, and certification status against output pricing tiers across product type, distribution channel, and end-use segmentation dimensions. CAGRs were derived from trajectory fitting to historical volume series with adjustment for regulatory enforcement phase-ins. Industry-specific forecast inputs included SENASICA staffing budget appropriations and Chicago Board of Trade futures curve assumptions.
Climate disruption in northern Mexico, bilateral SPS negotiation outcomes, and feed grain price spikes are the dominant revision risks warranting forecast reassessment. Material deviation in named triggers warrants pause and re-evaluation of capacity expansion timing and export corridor viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Europe Animal Protein Market
Meat Products
Organic Meat Products Market
Meat Products
United States Processed Pork Meat Market
Meat Products
Saudi Arabia Edible Meat Market
Meat Products
Bacon Market
Meat Products
3D Printed Meat Market
Meat Products
Edible Offal Market
Meat Products
Grassfed Jerky Market
Meat Products
Chicken Buckets Market
Meat Products
Organic Beef Meat Market
Meat Products
Global Processed Pork Meat Market
Meat Products
Canned Pork Market
Meat Products
Asia-Pacific Red Meat Market
Meat Products
Europe Canned Meat Market
Meat Products
Organic Eggs Market
Meat Products
Europe Processed Meat Market