
 Non-Veg Rte and Rtc Market | 2026-2036
Non-Veg Rte and Rtc Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Veg Rte and Rtc Market Analysis
The capital-intensity divergence between integrated processors and contract-dependent packers is rotating competitive advantage toward firms with captive cold-chain assets. Tyson Foods leverages vertical integration from feedstock through retail-ready packaging to sustain margin capture across volatile protein cycles. JBS S.A. anchors its position through global slaughterhouse and distribution scale that competitors struggle to replicate.
Non-Veg Rte and Rtc products comprise pre-processed animal proteins preserved through chilling, freezing, thermal treatment, or modified-atmosphere packaging for direct consumption or minimal-preparation cooking, with shelf-life parameters typically ranging from days for chilled formats to months for frozen retort pouches. Ready-to-Eat poultry segments dominate volume flows in mature retail channels where convenience premiums command consistent basket placement. Frozen red meat formats occupy expanding freezer space in online retail distribution as last-mile cold logistics mature across Asian markets. Chilled seafood pouches differentiate through shorter ingredient decks and cleaner-label positioning that attracts health-focused urban buyers.
FDA hazard analysis requirements and USDA FSIS inspection protocols shape product safety standards and plant certification thresholds for US-market access, while EU Regulation 853/2004 and EFSA guidance on Listeria monocytogenes in ready-to-eat foods enforce stringent microbiological limits that reshape formulation and shelf-life claims. India's FSSAI licensing mandates and cold-chain infrastructure directives under the PLI scheme for food processing are accelerating formalization of previously informal meat processing capacity. Stakeholders must monitor how divergent pathogen-testing regimes and emerging packaging sustainability mandates reshape cross-border product qualification costs and regional sourcing strategies.
Market Dynamics
Cold-chain infrastructure gaps between established and emerging markets are fragmenting competitive advantage, rewarding processors with captive logistics assets while squeezing contract-dependent packers dependent on third-party chilling networks.
Growth Catalysts
- India's PLI scheme for food processing:Directives under this incentive framework are accelerating formalization of previously informal meat processing capacity and channeling investment into compliant cold-chain assets.
- Modified-atmosphere packaging:This preservation technology is extending shelf-life parameters for chilled poultry formats and enabling branded proteins to displace wet-market alternatives in Southeast Asian urban centers.
- Quick-service restaurant chains:These institutional buyers are scaling procurement of chilled poultry formats and demanding consistent quality specifications that favor integrated processors over fragmented suppliers.
Market Restraints
- Feedstock cost volatility:Grain and soybean meal price swings compress margin predictability for processors lacking backward integration into feed production.
- Cold-chain concentration risk:Third-party chilling networks in Indonesia and Vietnam remain underdeveloped, creating spoilage exposure for packers without captive logistics infrastructure.
- EU Regulation 853/2004 microbiological limits:These stringent pathogen thresholds create qualification barriers for emerging-market exporters seeking European market access.
Strategic Opportunities
- Vietnam's urban retail modernization:Convenience store expansion and e-grocery platforms are creating channel space for branded frozen red meat formats previously excluded from traditional wet-market distribution.
- Cleaner-label chilled seafood:Shorter ingredient decks are attracting health-focused urban buyers in Thai and Malaysian metropolitan markets.
- FSSAI licensing mandates:India's formalization push is consolidating previously fragmented processing capacity and creating acquisition targets for scaled operators.
Industry Challenges
- HACCP certification timelines:Plant-level hazard analysis and critical control point validation creates extended qualification periods that delay market entry for new processing facilities.
- Legacy ERP integration:Temperature-monitoring IoT systems require reconfiguration of existing inventory management platforms, complicating traceability compliance.
- Specialized cold-chain engineering talent:Scarcity of technicians capable of maintaining modified-atmosphere equipment constrains operational scaling in secondary Indian cities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Veg Rte and Rtc Market |
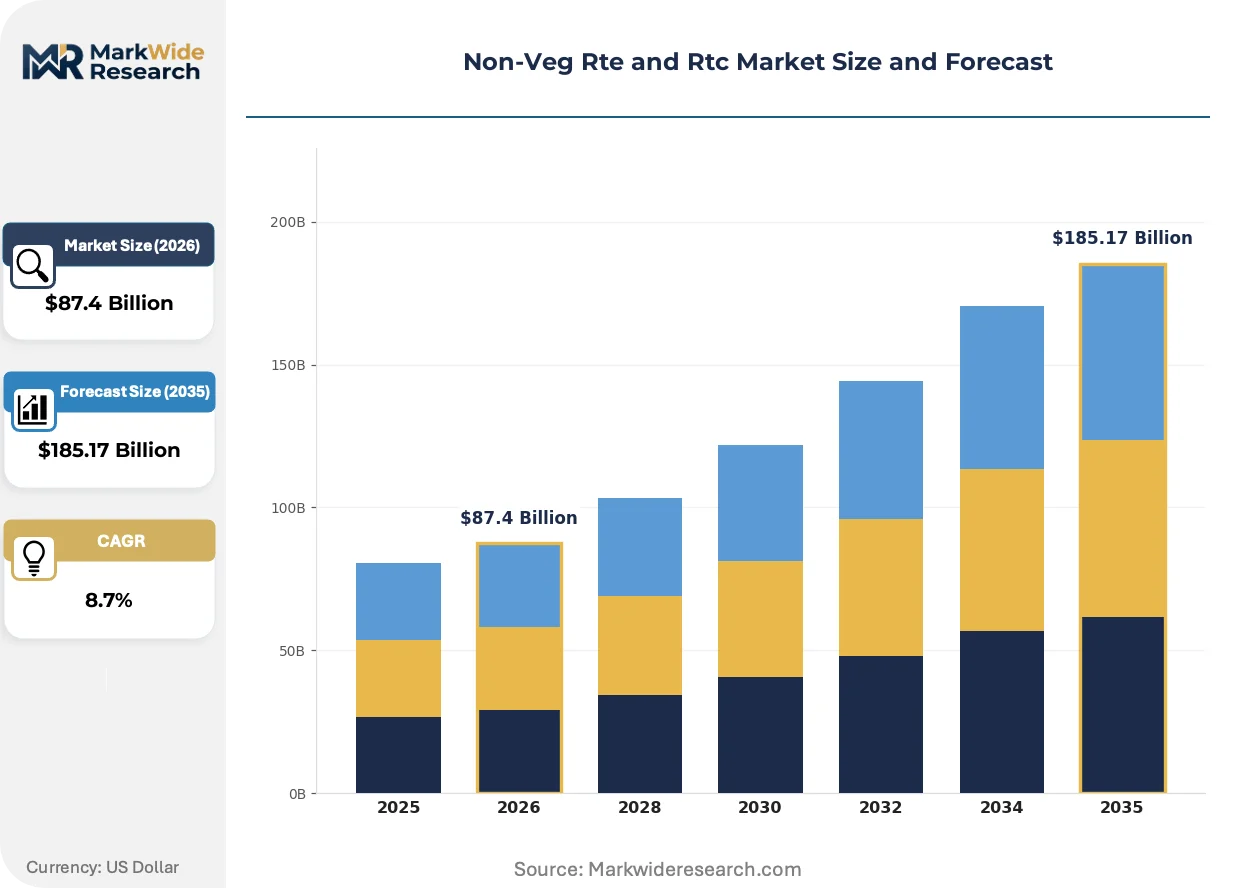
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $185.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Eat, Ready-to-Cook, Frozen, Chilled Source: Poultry, Seafood, Red Meat, Game Packaging Type: Tray, Pouch, Can, Vacuum Pack Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Food Service |
| Companies Covered | Nestlé S.A., Tyson Foods, Inc., Hormel Foods Corporation, JBS S.A., Conagra Brands, Inc., BRF S.A., Marfrig Global Foods S.A., Godrej Agrovet Limited, Venkys India, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Veg Rte and Rtc Market Emerging Trajectories
Preservation technologies and regulatory compliance architectures are converging to reshape product qualification costs and shelf-life claims across emerging-market supply chains.
Modified-atmosphere packaging systems are decomposing the traditional trade-off between shelf-life extension and ingredient simplicity. Thai and Vietnamese retail chains are adopting these formats at accelerating pace for chilled poultry and seafood SKUs. This technology is decomposing the competitive advantage of frozen-only processors by enabling chilled products to reach secondary cities previously outside viable distribution radii.
EU EFSA guidance on Listeria monocytogenes in ready-to-eat foods is tightening microbiological surveillance protocols and compressing permissible shelf-life windows for chilled formats. Processors serving European export channels are reformulating preservation chemistries and accelerating pathogen-testing frequencies. Indian and Brazilian exporters are most affected, responding by segregating production lines between domestic and export-qualified output.
Urban consumer migration from wet markets to branded retail channels is restructuring protein procurement patterns across Southeast Asian metropolitan areas. E-grocery platforms and convenience store chains are displacing traditional butcher counters as primary purchase points for younger demographics. This behavioral shift is most visible in Jakarta, Manila, and Ho Chi Minh City, where refrigerated last-mile logistics are maturing fastest.
Non-Veg Rte and Rtc Market Segmentation
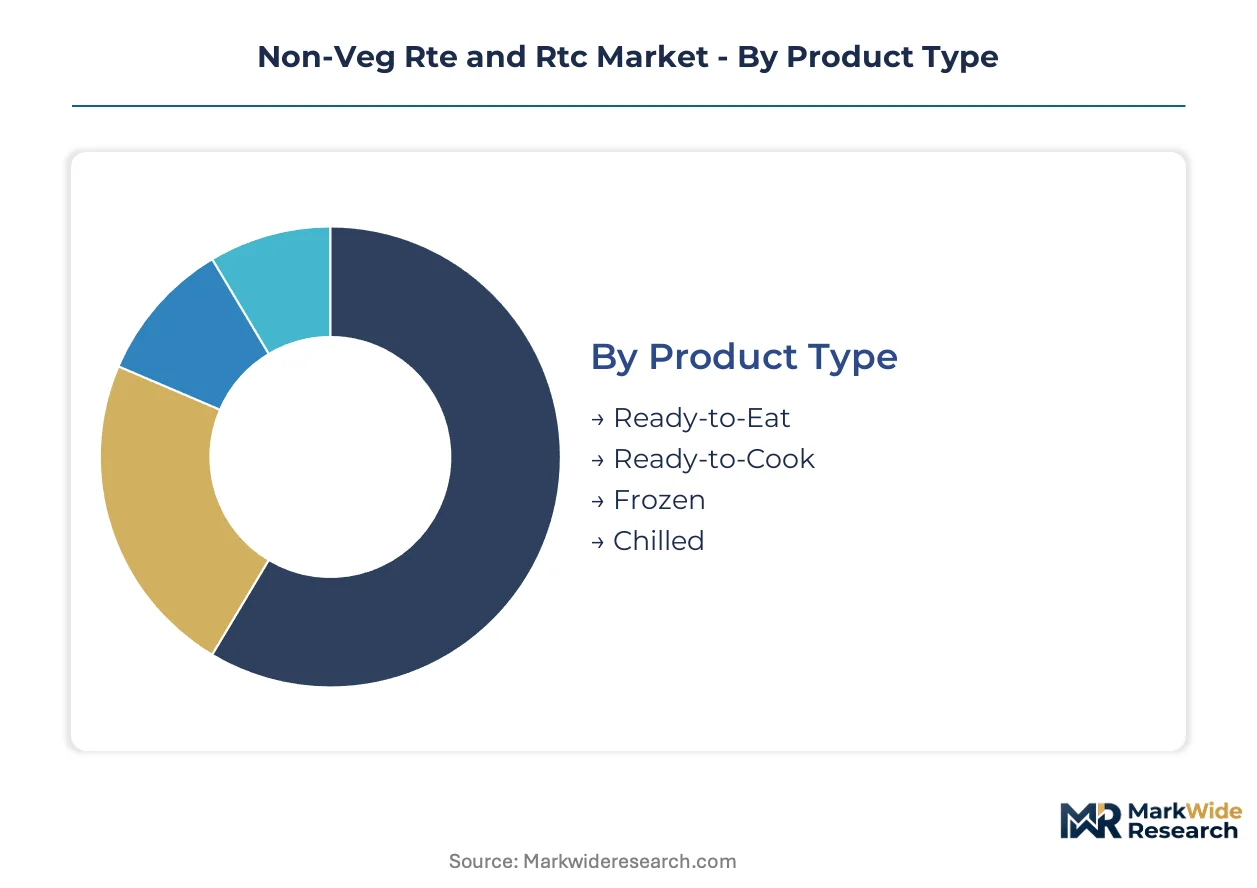
Segmentation in the Non-Veg Rte and Rtc Market reveals how preservation formats and protein sources align with divergent cold-chain capabilities and regulatory thresholds across retail and foodservice channels. Understanding these divisions exposes where integrated processors capture margin versus where contract packers face substitution risk from wet-market alternatives.
Product Type:
Substitution pressure from traditional butcher counters and live-animal markets weighs most heavily on chilled formats with shortest shelf-life windows, while frozen and thermally stabilized products resist displacement through extended distribution reach.
- Ready-to-Eat:Thermally processed or cured animal proteins in retort pouches or sealed trays requiring no further preparation before consumption. Quick-service restaurant chains in India and Southeast Asia are scaling procurement of RTE poultry formats as labor costs rise and consistency specifications tighten.
- Ready-to-Cook:Marinated, portioned, or seasoned proteins demanding minimal preparation time. Urban consumers in Jakarta and Ho Chi Minh City are trading up from wet markets to branded RTC packs as e-grocery platforms expand refrigerated last-mile coverage.
- Frozen:Blast-frozen proteins preserved at sub-zero temperatures for extended storage. Cold-chain infrastructure gaps in Indonesian and Vietnamese secondary cities constrain penetration.
- Chilled:Refrigerated formats with shelf-life parameters typically ranging from days to weeks. Modified-atmosphere packaging is extending viability radii for this highest-substitution-risk category.
Ready-to-Eat retains volume leadership; Ready-to-Cook holds the steepest expansion curve.
Source:
Cost tier stratification separates poultry as the accessible protein backbone from red meat and seafood segments commanding premium positioning through supply scarcity and processing complexity.
- Poultry:Chicken and turkey derivatives dominating procurement volumes across institutional and retail channels. India's PLI scheme for food processing is channeling investment into compliant poultry processing capacity.
- Seafood:Finfish and shellfish products differentiated through shorter ingredient decks and cleaner-label positioning. Thai and Malaysian metropolitan markets are attracting health-focused urban buyers to chilled seafood pouches.
- Red Meat:Beef, pork, and lamb formats occupying expanding freezer space in online retail distribution. Vietnam's urban retail modernization is creating channel space for branded frozen red meat previously excluded from wet-market distribution.
- Game:Venison, wild boar, and specialty proteins serving niche gastronomic and ethnic demand segments. Regulatory complexity limits formal channel penetration.
Poultry commands absolute volume; seafood is climbing the fastest.
Packaging Type:
Application-driven format selection maps directly to shelf-life requirements and retail channel slotting constraints, with modified-atmosphere systems disrupting traditional material hierarchies.
- Tray:Rigid plastic or foam containers with permeable film lidding for chilled retail display. Supermarket chains in Manila and Jakarta favor tray formats for visual merchandising of fresh-appearing poultry cuts.
- Pouch:Flexible laminated films enabling retort sterilization or modified-atmosphere preservation. This format is displacing cans in RTE segments through reduced weight and improved microwave compatibility.
- Can:Metal containers for ambient-stable thermally processed proteins. Legacy format facing displacement by pouch alternatives in all but institutional food service procurement.
- Vacuum Pack:Barrier films with oxygen evacuation extending chilled shelf-life without chemical preservatives. EU EFSA guidance on Listeria monocytogenes is accelerating vacuum pack adoption for export-qualified European channels.
Tray formats retain volume leadership; vacuum packs hold the steepest expansion curve.
Distribution Channel:
Customer-type concentration separates high-volume institutional buyers demanding specification consistency from fragmented retail channels where brand building determines price realization.
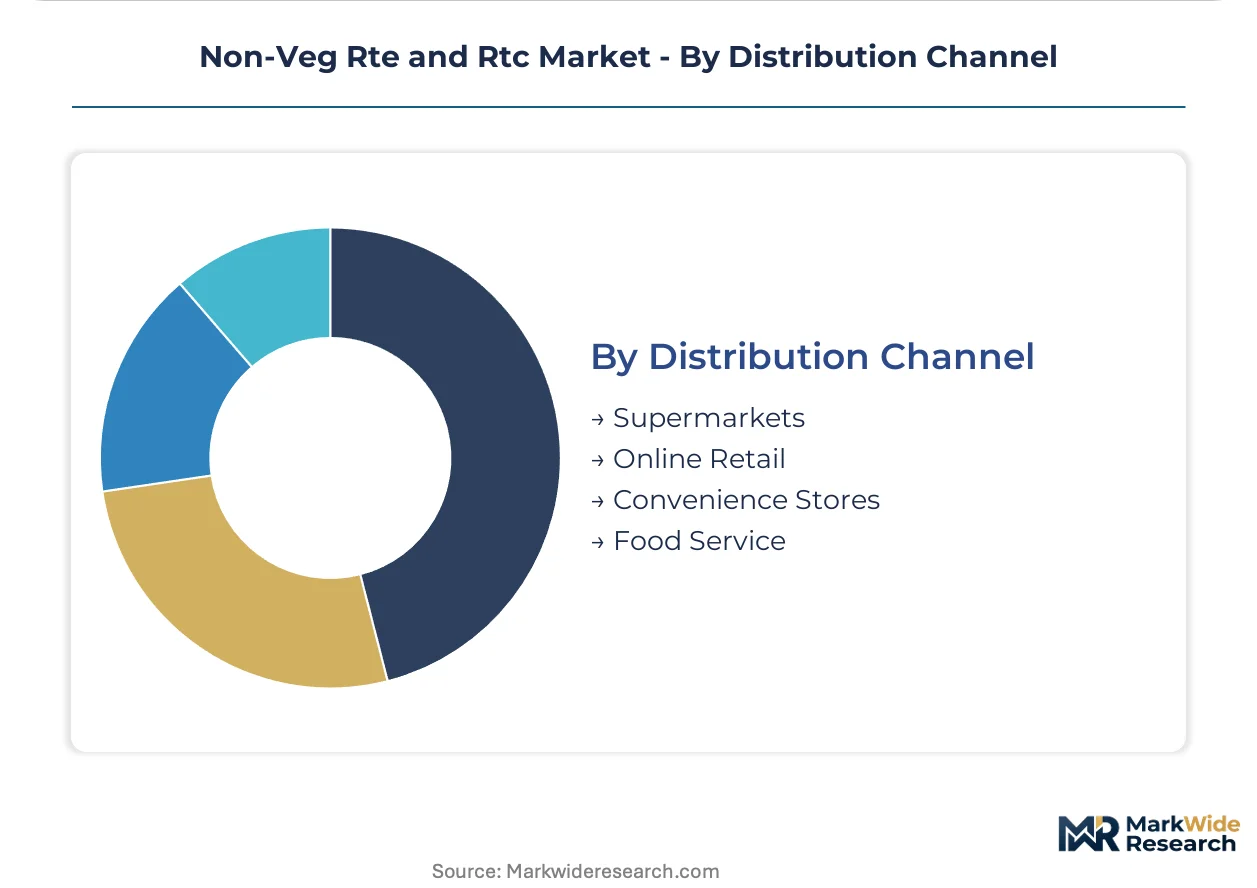
- Supermarkets:Organized retail chains with dedicated refrigerated display infrastructure. Urban consumer migration from wet markets is restructuring protein procurement patterns across Southeast Asian metropolitan areas.
- Online Retail:E-grocery platforms and direct-to-consumer delivery services. Last-mile cold logistics maturation across Asian markets is enabling frozen red meat expansion.
- Convenience Stores:Small-format urban retail with limited refrigeration capacity. Chilled poultry SKUs with abbreviated shelf-life are gaining placement as store networks expand.
- Food Service:Restaurants, institutional caterers, and hospitality operators. Quick-service chains are demanding consistent quality specifications that favor integrated processors.
Supermarkets retain volume leadership; online retail holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States outstrips India by a factor reflecting cold-chain density and brand concentration, while Southeast Asian markets occupy an intermediate tier where infrastructure investments are compressing historical premiums.
United States
Quick-service restaurant chains and institutional food buyers drive procurement volumes for chilled poultry formats. USDA FSIS inspection protocols and FDA hazard analysis requirements shape plant certification thresholds for domestic and export-qualified output. Tyson Foods anchors integrated processing capacity across Arkansas and Iowa, leveraging captive cold-chain assets to sustain margin capture across volatile protein cycles.
India
Urban consumers in Mumbai and Delhi-NCR are trading up from wet markets to branded packaged proteins as e-grocery platforms expand refrigerated last-mile coverage. FSSAI licensing mandates and PLI scheme directives for food processing are accelerating formalization of previously informal meat processing capacity. Godrej Agrovet and Venkys India dominate poultry processing clusters in Maharashtra and Telangana, channeling investment into compliant cold-chain infrastructure.
Brazil
Export-qualified beef and poultry processors serve European and Middle Eastern channels through specialized production line segregation. EU Regulation 853/2004 microbiological limits and EFSA guidance on Listeria monocytogenes enforce stringent pathogen thresholds that reshape formulation and shelf-life claims. JBS S.A. and BRF S.A. anchor slaughterhouse and distribution scale in São Paulo and Paraná that competitors struggle to replicate.
Vietnam
Convenience store expansion and e-grocery platforms in Ho Chi Minh City and Hanoi are creating channel space for branded frozen red meat formats previously excluded from traditional wet-market distribution. Cold-chain concentration risk in third-party chilling networks creates spoilage exposure for packers without captive logistics infrastructure. Modified-atmosphere packaging adoption is accelerating for chilled poultry SKUs as urban retail modernizes.
Thailand
Health-focused urban buyers in Bangkok metropolitan markets are gravitating toward cleaner-label chilled seafood pouches with shorter ingredient decks. National food safety regulators enforce HACCP certification timelines that create extended qualification periods for new processing facilities. Seafood processing clusters along the Eastern Seaboard are integrating temperature-monitoring IoT systems to comply with traceability mandates for European export channels.
Non-Veg Rte and Rtc Market Vendor Landscape
Concentration sits with vertically integrated protein conglomerates that control feedstock through retail-ready packaging, while contract-dependent packers face margin compression from cold-chain infrastructure gaps. The vendor base stratifies across three tiers: global scale operators with multi-protein portfolios, regional specialists dominating single-geography procurement relationships, and emerging-market consolidators capturing formalization-driven acquisition targets. Dominant competitive moves include backward integration into feed production and captive cold-chain asset deployment.
Within the global scale tier, Nestlé S.A. exemplifies packaged food conglomerate positioning across ambient and chilled formats, while Tyson Foods and JBS S.A. anchor integrated protein processing archetypes with slaughterhouse-to-distribution control. Hormel Foods Corporation and Conagra Brands, Inc. occupy positions within the North American branded prepared foods segment. Among emerging-market consolidators, Godrej Agrovet Limited and Venkys India represent Indian poultry processing formalization, while BRF S.A. and Marfrig Global Foods S.A. exemplify Brazilian export-oriented protein scale.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Tyson Foods, Inc. |
| Hormel Foods Corporation |
| JBS S.A. |
| Conagra Brands, Inc. |
| BRF S.A. |
| Marfrig Global Foods S.A. |
| Godrej Agrovet Limited |
| Venkys India |
| Others |
Supply Flow & Price Mechanics
EU Regulation 853/2004 microbiological limits gate both supply qualification and price differentiation simultaneously, forcing exporters to segregate production lines between domestic and export-qualified output while commanding certification premiums for compliant chilled formats. USDA FSIS inspection protocols and India's FSSAI licensing mandates create parallel tiering systems where cold-chain asset ownership separates margin-capturing integrated processors from contract-dependent packers facing spoilage exposure.
Pricing Analysis
The customization-premium spread separates configured-to-order RTC marinated portions from standard frozen bulk packs, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade and captive cold-chain ownership. Price differentiation stems from HACCP validation status and modified-atmosphere packaging capability, while cost compression in economy chilled tiers intensifies because wet-market alternatives retain residual share. Quick-service restaurant chains exhibit lowest price sensitivity due to specification consistency requirements, whereas convenience store buyers in Vietnamese secondary cities face acute budget constraints.
Supply Chain Analysis
Inventory-strategy preferences favor just-in-time chilled poultry flows for QSR procurement in Indian metropolitan markets, contrasting with strategic stockpiling of frozen red meat formats by Brazilian exporters navigating EU qualification timelines. Geographic supply concentration centers on Brazil, India, and the United States for poultry processing; Thailand and Vietnam for seafood; and Australia for premium beef. Raw material dependencies include grain and soybean meal for feedstock, modified-atmosphere packaging films, and blast-freezing equipment. Single-source vulnerability in Indonesian third-party chilling networks creates spoilage risk. Distribution runs through integrated processor-controlled logistics for institutional channels and fragmented cold-chain partnerships for retail penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against wet-market protein sources that retain cost advantages through regulatory arbitrage and zero cold-chain overhead. Incumbents must navigate informal channel persistence while formalizing capacity.
For Market Incumbents: Secure captive cold-chain assets in Indian secondary cities where PLI scheme incentives accelerate formalization, and lock in multi-year offtake agreements with quick-service restaurant chains before regional specialists consolidate procurement relationships. Wet-market price competition and feedstock cost volatility threaten margin stability without backward integration into feed production.
For New Entrants and Emerging Players: Lead with cleaner-label chilled seafood pouches in Thai metropolitan markets where health-focused urban buyers trade up from traditional wet-market sources, targeting convenience store expansion in Ho Chi Minh City as e-grocery platforms mature refrigerated last-mile coverage. Direct-to-retail partnerships with modern trade chains bypass entrenched distributor networks.
For Investors and Strategic Acquirers: India's FSSAI licensing mandates reshape the acquisition landscape by consolidating fragmented processing capacity into formalized targets with compliant cold-chain infrastructure. Long-term viability hinges on 5-10 year formalization trajectories in Southeast Asian markets. Target mid-scale Indian poultry processors with PLI scheme qualification. Monitor modified-atmosphere packaging adoption rates as inflection indicator for chilled format viability expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Production | Tyson Foods and JBS S.A. anchor margin capture across volatile grain and soybean meal price cycles. |
| Modified-Atmosphere Packaging Deployment | Thai and Vietnamese retail chains extend chilled poultry shelf-life to reach secondary cities outside traditional distribution radii. |
| Cold-Chain Asset Captive Buildout | Godrej Agrovet and Venkys India channel PLI scheme investment into FSSAI-compliant infrastructure. |
| Export-Qualified Production Line Segregation | Brazilian processors separate EU Regulation 853/2004 compliant output from domestic-grade production. |
| Quick-Service Restaurant Direct Contracting | Institutional procurement consistency specifications favor integrated processors over fragmented wet-market suppliers. |
Methodological Framework
Cross-validation between processor procurement executives and retail category managers anchors the qualitative findings, combining primary interviews with cold-chain logistics directors, FSSAI compliance officers, and QSR supply chain leads against secondary validation through customs trade data, SEC 10-K protein segment disclosures, and PLI scheme beneficiary registries. Bottom-up facility capacity assessments and top-down retail channel audits triangulate volume estimates.
Sensitivity analysis across feedstock cost scenarios and cold-chain penetration rates shapes the analytical framework over the projection horizon, modeling segmentation dimensions across preservation format, protein source, packaging technology, and distribution channel. CAGRs derive from installed cold-chain capacity expansion trajectories and urban retail modernization indices, incorporating modified-atmosphere packaging adoption curves and regulatory compliance cost escalators as industry-specific inputs.
Underlying assumptions cover sustained PLI scheme disbursement continuity and EU microbiological limit stability, with deviation risk concentrated in Indonesian logistics infrastructure delays and grain price volatility. Forecasts reflect documented conditions with explicit scenario boundaries. Revision becomes warranted when wet-market substitution rates in Indian metropolitan areas cross formalization acceleration thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Beef Fat Market
Meat Products
North America Bacon Market
Meat Products
United States Processed Pork Meat Market
Meat Products
Meat Tenderizer Market
Meat Products
Saudi Arabia Red Meat Market
Meat Products
Meat Emulsions Market
Meat Products
Middle-East and Africa Animal-Based Meat and Dairy Products Market
Meat Products
Edible Offal Market
Meat Products
Low-Fat Chorizo Market
Meat Products
Meat Ingredients Market
Meat Products
Grass-Fed Meat Market
Meat Products
Fresh Organic Chicken Market
Meat Products
Global Edible Meat Market
Meat Products
North America Processed Pork Meat Market
Meat Products
GCC Edible Meat Market
Meat Products
GCC Red Meat Market