
 Canned Beef Market | 2026-2036
Canned Beef Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Beef Market Insights
A capital-intensity divergence between large-scale canneries and regional processors is bifurcating competitive dynamics in the Canned Beef Market. Hormel Foods Corporation leverages vertical integration from cattle procurement through retail distribution to sustain margin control across volatile feedstock cycles. JBS S.A. anchors its position through global protein sourcing networks that compete on cost efficiency with North American-centric rivals. Keystone Meats specializes in premium grass-fed formulations that differentiate its portfolio within conventional commodity segments.
Canned beef comprises cooked, preserved bovine muscle tissue processed through retort sterilization at temperatures exceeding 121 degrees Celsius, sealed in hermetic containers to achieve shelf stability exceeding two years without refrigeration. The product serves commercial and institutional buyers requiring protein security independent of cold-chain infrastructure. Chunk product formats lead volume throughput due to manufacturing efficiency and recipe versatility across household and food service applications. Easy Open Can packaging commands preference in convenience-oriented channels where tool-free access drives repeat purchase behavior. Online Retail as a sales channel exhibits the fastest structural expansion as direct-to-consumer fulfillment infrastructure matures.
USDA Food Safety and Inspection Service oversight mandates pathogen elimination standards and labeling accuracy that shape production economics and facility certification requirements. FDA regulations governing low-acid canned foods establish thermal processing parameters and container integrity testing that determine market access eligibility. Stakeholders must monitor evolving sodium reduction mandates and clean-label expectations that threaten conventional brine-based preservation formulations.
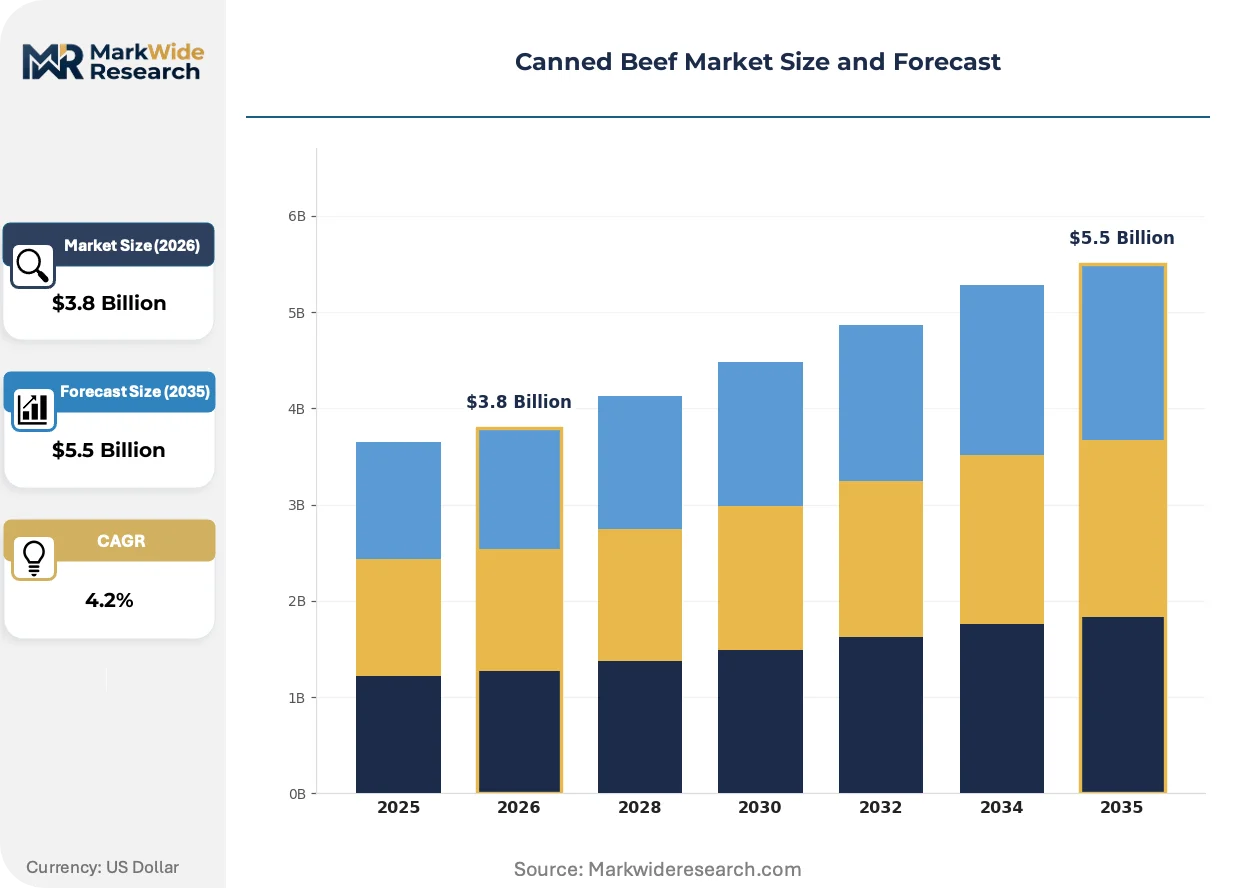
Market Dynamics
Military procurement programs sustain baseline demand for shelf-stable protein formats, while USDA retort processing mandates reshape capital allocation across domestic canneries. The divergence between large-scale automated facilities and regional processors is fragmenting competitive economics.
Growth Catalysts
- Emergency Food Reserve Expansion:Institutional buyers in the United States are stockpiling long-shelf-life protein to meet FEMA continuity requirements. This procurement pattern insulates volume demand from consumer cyclicality.
- Online Retail Infrastructure:Direct-to-consumer fulfillment networks are maturing for ambient protein products. Cold-chain independence allows nationwide distribution without refrigerated last-mile complexity.
- Retort Technology Advances:Next-generation sterilization systems reduce thermal degradation of amino acid profiles. Premium nutrition claims now align with extended shelf stability.
Market Restraints
- Feedstock Cost Volatility:Live cattle price swings transmit directly into input cost structures. Processors without captive supply face margin compression during commodity spikes.
- Sodium Reduction Mandates:FDA pressure on preserved food sodium content threatens conventional brine formulations. Reformulation R&D costs burden mid-tier producers disproportionately.
- Plant Protein Substitution:Textured vegetable protein alternatives capture institutional contract share. Price-sensitive food service buyers rotate toward lower-cost analogues.
Strategic Opportunities
- Grass-Fed Premium Positioning:Differentiated supply chains command price premiums in natural retail channels. USDA organic certification unlocks shelf placement in specialty grocers.
- Easy Open Packaging Innovation:Tool-free can access expands repeat purchase in convenience-oriented demographics. Elderly and outdoor recreation segments show particular responsiveness.
- Disaster Preparedness Retail:Big-box retailers are expanding ambient protein facings in emergency preparedness aisles. This channel placement captures incremental household penetration.
Industry Challenges
- FSIS Compliance Timeline:Pathogen elimination validation extends new product introduction cycles. Laboratory certification bottlenecks delay seasonal formulation launches.
- Retort Equipment Capex:Continuous-flow sterilization systems require seven-figure capital commitments. Regional processors face barriers to scaling automated throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Beef Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chunk, Shredded, Sliced, Whole Packaging Type: Easy Open Can, Traditional Can, Pouch, Jar Sales Channel: Supermarkets, Online Retail, Convenience Stores, Wholesalers End User: Households, Restaurants, Military, Food Services |
| Companies Covered | Hormel Foods Corporation, Tyson Foods, Inc., JBS S.A., Conagra Brands, Inc., Campbell Soup Company, Smithfield Foods, Inc., Bolton Group, Keystone Meats, Valleyfresh Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Beef Market Trends and Innovations
Retort processing advances and packaging format evolution are reconfiguring production economics and consumer access patterns across the canned beef category.
High-pressure processing as an auxiliary pasteurization step is fragmenting traditional thermal treatment protocols. Premium private-label brands are adopting hybrid sterilization to preserve texture and micronutrient density. This dual-technology approach enables clean-label positioning without sacrificing shelf stability.
USDA FSIS is tightening labeling accuracy enforcement for protein content declarations. Canneries must now maintain batch-level analytical records subject to inspection. Smaller regional processors face disproportionate documentation burden relative to integrated majors.
Subscription-based pantry stocking is displacing episodic emergency purchasing among preparedness-oriented households. Direct-to-consumer brands capture recurring revenue through auto-ship programs. This behavioral shift concentrates most visibly in the Mountain West and Pacific Northwest states.
Canned Beef Market Segmentation
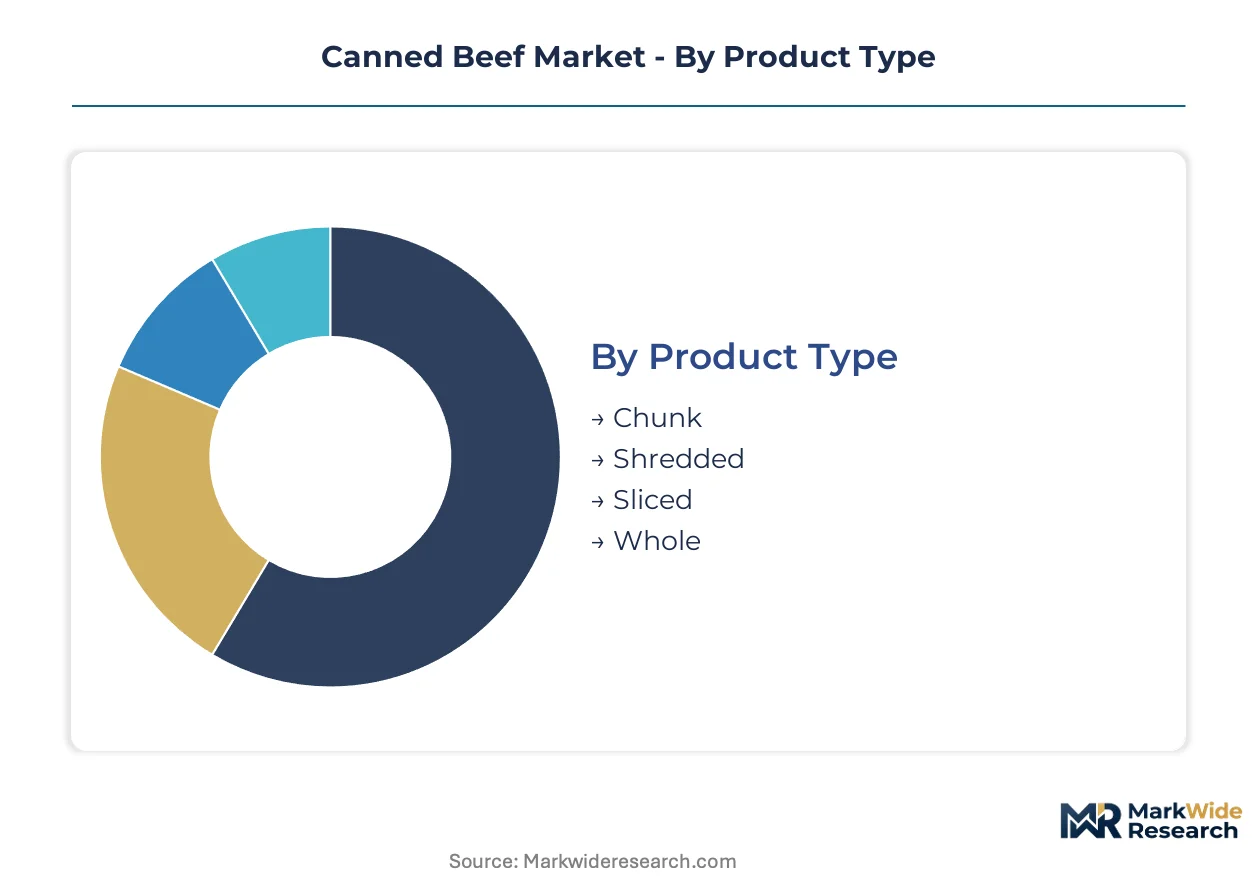
Segmentation in the Canned Beef Market reveals how regulatory requirements, packaging specifications, and distribution economics fragment production and procurement strategies. Each dimension carries distinct compliance burdens and margin structures that shape competitive positioning.
Product Type:
USDA FSIS inspection protocols vary by physical form, with surface-area-to-volume ratios determining pathogen elimination validation requirements.
- Chunk:Cubed muscle tissue in variable sizes dominates manufacturing throughput due to retort efficiency and recipe versatility across institutional meal planning. Households in the United States stock chunk formats for stew and casserole applications where texture retention matters.
- Shredded:Pulled beef strands offer rapid rehydration and uniform distribution in sauced preparations. Food service buyers in Texas and California specify shredded formats for sandwich and taco fillings where portion consistency controls food cost.
- Sliced:Uniform cross-sections suit plated presentations in restaurant settings.
- Whole:Intact muscle cuts command premium positioning in specialty retail.
Chunk handles the majority of throughput; Shredded is expanding most quickly on share.
Packaging Type:
Container selection drives distribution economics through shelf-space efficiency and last-mile handling requirements.
- Easy Open Can:Tool-free lid mechanisms command preference in convenience-oriented channels where repeat purchase correlates with accessibility. Elderly demographics and outdoor recreation segments in Colorado and Utah show particular responsiveness to pull-tab designs.
- Traditional Can:Standard seamed metal containers sustain cost leadership in commodity procurement.
- Pouch:Flexible retort packaging reduces shipping cube and disposal mass.
- Jar:Glass containers enable premium visual merchandising in natural retail.
Traditional Can retains volume leadership; Pouch is climbing the fastest on share.
Sales Channel:
Channel mix determines working capital intensity and promotional investment patterns across the category.
- Supermarkets:Grocery retail anchors household penetration through ambient protein aisle placement and seasonal promotional cycles. Chains in the Midwest and Southeast maintain dedicated emergency preparedness facings that stabilize baseline volume.
- Online Retail:Direct-to-consumer fulfillment networks bypass cold-chain complexity for ambient protein distribution. Mountain West and Pacific Northwest states concentrate subscription-based pantry stocking behavior.
- Convenience Stores:Limited SKU counts favor single-serve and grab-and-go formats.
- Wholesalers:Institutional procurement aggregates volume for food service and government buyers.
Supermarkets manage the majority of throughput; Online Retail is gaining share fastest.
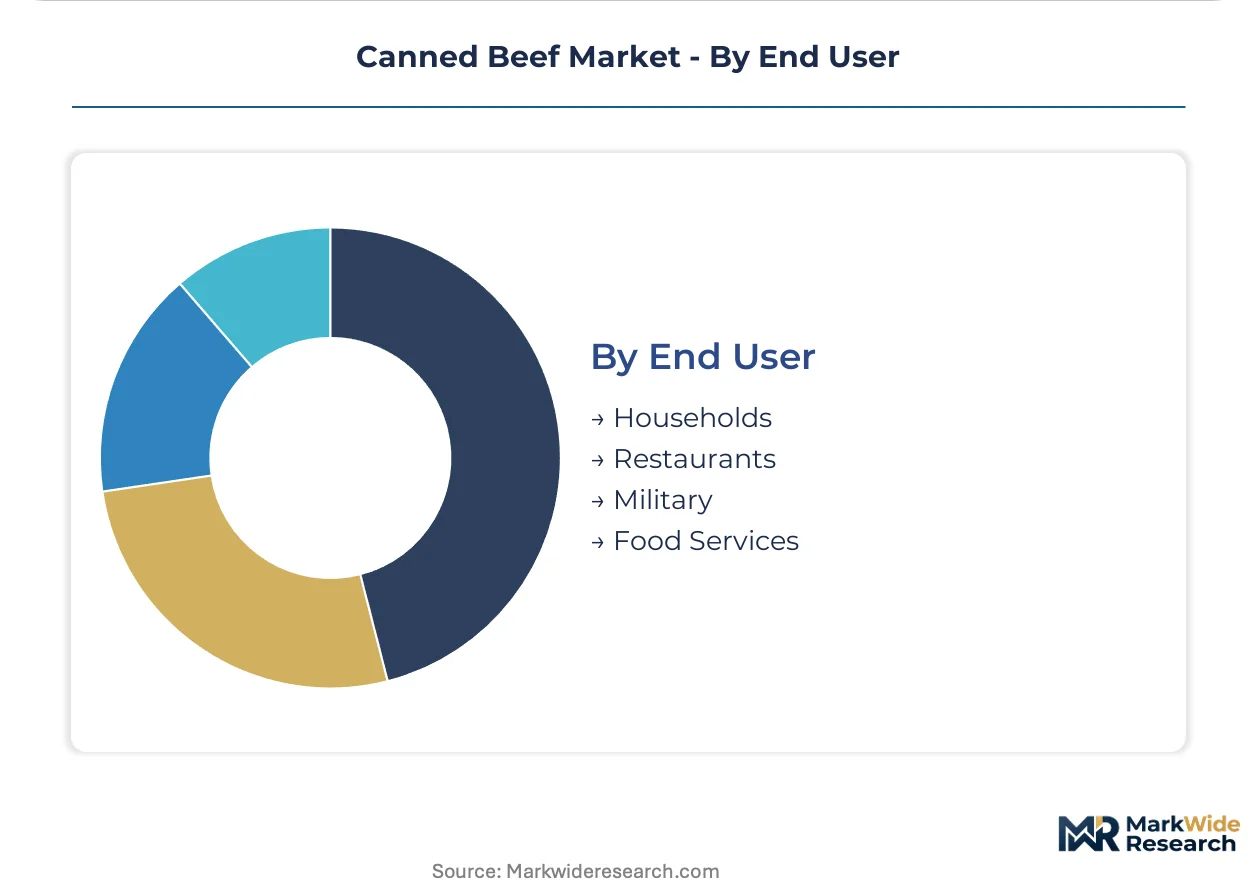
End User:
Customer type dictates specification stringency and contract duration in procurement relationships.
- Households:Consumer pantry stocking responds to emergency preparedness messaging and promotional pricing. FEMA continuity requirements indirectly shape household purchase patterns through public awareness campaigns.
- Military:Defense procurement programs sustain baseline demand with multi-year contracts and specification stability. Shelf-life requirements exceeding two years without refrigeration define technical parameters.
- Restaurants:Food service operations prioritize labor reduction and holding stability.
- Food Services:Institutional feeding programs balance nutrition compliance with cost controls.
Households absorb the majority of volume; Military contracts provide the steadiest demand foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Household buyers in the United States absorb price premiums for convenience formats, while institutional procurement in Brazil and Southeast Asia rotates aggressively toward cost-minimized alternatives. Military and emergency reserve buyers worldwide show the least price sensitivity.
United States
Household pantry stocking and FEMA continuity requirements drive baseline volume. USDA FSIS inspection mandates shape facility certification economics across domestic canneries. Nebraska and Kansas host concentrated cattle feeding operations that supply regional processing plants.
Brazil
Export-oriented beef processing leverages grass-fed herds for premium positioning in North American and European markets. Ministry of Agriculture (MAPA) oversight of canned meat exports establishes sanitary certification requirements. São Paulo state anchors industrial canning capacity with integrated slaughter-to-retail facilities.
China
Strategic pork reserve protocols are expanding to include shelf-stable beef formats for protein security. SAMR regulations on low-acid canned foods establish thermal processing standards for import eligibility. Shandong Province concentrates retort packaging manufacturing that supplies domestic canneries.
Australia
Grass-fed beef exports command premium positioning in Asian retail channels. Department of Agriculture, Water and the Environment biosecurity protocols govern canned meat export certification. Queensland and New South Wales host integrated processing corridors linking cattle production to port infrastructure.
Germany
Discount retail channels absorb volume through private-label canned meat programs. EFSA guidance on processed meat consumption influences reformulation trends toward reduced sodium. North Rhine-Westphalia maintains specialized canning equipment manufacturing that supplies European processors.
Canned Beef Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-layer competitive architecture. Hormel Foods Corporation and JBS S.A. anchor the upper tier through captive supply chains and global sourcing networks. Mid-scale regional processors occupy the specialist tier with differentiated formulations. Competitive moves concentrate on backward integration into cattle procurement and automated retort capacity expansion.
Within the integrated protein conglomerate tier, Hormel Foods Corporation and JBS S.A. exemplify scale-driven positioning through vertical control from livestock to retail shelf. Keystone Meats occupies a specialist position representing premium grass-fed differentiation. Tyson Foods, Inc. anchors a diversified protein portfolio that spans conventional and value-added formats.
| Leading Market Players |
|---|
| Hormel Foods Corporation |
| Tyson Foods, Inc. |
| JBS S.A. |
| Conagra Brands, Inc. |
| Campbell Soup Company |
| Smithfield Foods, Inc. |
| Bolton Group |
| Keystone Meats |
| Valleyfresh Global |
| Others |
Pricing and Supply Chain Analysis
Grass-fed beef substitution for conventional grain-fed inputs is reshaping procurement geography toward Australia and Brazil while compressing margin structures for North American processors tethered to higher-cost feedlot systems. This feedstock divergence simultaneously fragments supplier power and intensifies price competition across premium and commodity tiers.
Pricing Analysis
After-sales revenue from institutional replenishment contracts and emergency reserve rotations drives lifetime value more than initial cannery sales. Three-tier pricing structure across premium grass-fed, standard commodity, and economy private-label levels segments buyer wallets. Pricing pressure stems from plant protein substitution in food service procurement. Military buyers show least price sensitivity while budget-conscious households absorb most margin compression.
Supply Chain Analysis
Live cattle supply concentrates in Nebraska, Kansas, and São Paulo state, creating geographic chokepoints for processor procurement. Retort packaging materials and hermetic sealing equipment draw from China and Germany. Single-source vulnerability in continuous-flow sterilization machinery elevates capital risk for regional canners. Distribution runs through supermarket ambient protein aisles, online direct-to-consumer fulfillment, and institutional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase anchored to military procurement cycles and FEMA reserve replenishment schedules. Live cattle price volatility and sodium reduction mandates compress margins during procurement troughs.
For Market Incumbents: Compound defensive positioning through backward integration into cattle procurement and automated retort capacity expansion. Capture margin control against feedstock volatility by securing captive supply in Nebraska and Kansas feeding corridors. Neutralize plant protein substitution threats by embedding in military multi-year contracts with specification stability. For New Entrants and Emerging Players: Differentiate on grass-fed premium positioning and USDA organic certification to unlock specialty grocer shelf placement. Target underpenetrated online retail channels in Mountain West and Pacific Northwest subscription pantry markets. Launch direct-to-consumer auto-ship programs with emergency preparedness messaging as the go-to-market angle. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated protein conglomerates with captive supply chains. Long-term viability over the next decade hinges on retort automation scale and regulatory compliance infrastructure. Target acquisition archetypes include regional canneries with FSIS certification and grass-fed supply relationships. Watch live cattle futures and sodium mandate enforcement timelines as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cattle Procurement | Hormel and JBS anchor margin control through captive livestock supply across volatile commodity cycles. |
| Retort Automation Capacity Expansion | Continuous-flow sterilization investments separate integrated majors from regional processors facing seven-figure capital barriers. |
| Grass-Fed Premium Certification | Keystone Meats demonstrates how USDA organic unlocks shelf placement in natural retail channels. |
| Direct-to-Consumer Channel Launch | Online retail infrastructure in Mountain West states captures subscription-based pantry stocking behavior. |
| Sodium Reduction Reformulation R&D | Clean-label positioning aligns with FDA pressure on preserved food sodium content without sacrificing shelf stability. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of USDA FSIS inspection records, FDA low-acid canned food filings, and trade customs data for beef and meat product flows. Interviews with cannery operations directors, military procurement officers, supermarket category buyers, and food service distribution managers inform demand-side validation. Top-down market sizing triangulates against bottom-up production capacity assessments across domestic and export-oriented facilities.
Segmentation dimensions modeled span product type, packaging format, sales channel, and end-user category across the projection horizon. CAGRs derive from trend extrapolation of military procurement cycles, household pantry stocking patterns, and online retail infrastructure maturation. Forecast inputs incorporate live cattle price trajectory assumptions and sodium reduction mandate implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained military budget allocations and FEMA continuity funding levels would require recalibration. Forecasts reflect documented assumptions about feedstock cost trajectories and regulatory enforcement intensity. Practitioners should keep alternative scenarios live as plant protein substitution rates and clean-label reformulation costs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Beef Liver Market
Meat Products
Animal Protein Market
Meat Products
Beef Extract Market
Meat Products
North America Processed Pork Meat Market
Meat Products
Global Duck Meats Market
Meat Products
United States Bacon Market
Meat Products
Canned Pork Market
Meat Products
Grassfed Jerky Market
Meat Products
Ham Slicers Market
Meat Products
Middle-East and Africa Animal-Based Meat and Dairy Products Market
Meat Products
Saudi Arabia Goat Meat and Cheese Market
Meat Products
Organic Meat Products Market
Meat Products
Kosher Beef Market
Meat Products
United Arab Emirates Red Meat Market
Meat Products
Europe Animal Protein Market
Meat Products
Pork Belly Meat Market