
 Fresh Organic Chicken Market | 2026-2036
Fresh Organic Chicken Market Size, Share, and Industry Trends Forecast 2026-2036
Fresh Organic Chicken Market Foresight
Contract grower networks across the southeastern United States is realigning toward certified organic capacity as conventional margins compress. Tyson Foods, Inc. leverages its vertically integrated feed-to-retail infrastructure to secure organic grain supply chains. Perdue Farms, Inc. anchors its premium positioning through Animal Welfare Approved certification across company-owned hatcheries. Bell & Evans differentiates with air-chilled processing technology that extends shelf life without chemical intervention.
Fresh organic chicken denotes broiler poultry raised without antibiotics, synthetic hormones, or genetically modified feed, meeting third-party organic certification standards requiring outdoor access and non-therapeutic health management; the product serves retail consumers and foodservice operators seeking verified clean-label protein. Whole chicken and chicken breasts occupy the dominant volume positions due to household familiarity and versatile preparation across cuisines. Specialty stores and online retailers represent the fastest-expanding distribution channels as direct-to-consumer subscription models bypass traditional supermarket markups.
USDA Organic standards govern feed sourcing and livestock living conditions in the United States, while EU Organic regulations enforce comparable restrictions across member states with additional emphasis on stocking density limits; both frameworks elevate compliance costs that filter through to shelf price and restrict market access for uncertified imports. The Food Safety and Inspection Service collaborates with certifiers to maintain chain-of-custody documentation from hatchery to retail case. Stakeholders must monitor evolving antibiotic residue testing protocols and state-level cage-free mandates that could further fragment supply qualification requirements.
Market Dynamics
USDA Organic and EU Organic certification requirements are compressing conventional capacity while forcing feed-to-retail traceability investments across contract grower networks.
Growth Catalysts
- EU Organic stocking density limits:German and Dutch retailers now require compliance documentation from hatchery through processing, locking in premium shelf placement for verified supply chains.
- Precision livestock monitoring:Sensor networks tracking bird health metrics are reducing mortality rates and antibiotic dependency in certified operations.
- Foodservice procurement mandates:Restaurant chains across the United States are embedding organic poultry requirements into supplier scorecards, pulling volume from conventional channels.
Market Restraints
- Organic grain supply concentration:Corn and soybean sourcing for certified feed concentrates in the Midwestern United States and Black Sea regions, exposing processors to weather-driven price spikes.
- EU Organic conversion timelines:The 24-month land transition period blocks rapid capacity expansion when demand surges, creating supply rigidities.
- Air-chilled processing capex barriers:The technology requires facility upgrades that smaller processors cannot finance, consolidating processing share among capital-rich operators.
Strategic Opportunities
- Direct-to-consumer subscription channels:Online retailers are bypassing supermarket markups with farm-branded organic chicken boxes, capturing margin typically lost to retail intermediaries.
- Animal Welfare Approved certification:This third-party standard exceeds USDA Organic requirements and commands additional price premiums in specialty retail.
- State-level cage-free mandates:California and Massachusetts regulations are accelerating conventional-to-organic flock transitions as producers seek to avoid stranded conventional capacity.
Industry Challenges
- Veterinary workforce scarcity:Certified organic operations require specialists trained in non-therapeutic health management, a skill set concentrated among aging practitioners.
- Chain-of-custody documentation:FSIS collaboration with certifiers demands real-time tracking systems that legacy hatcheries struggle to implement without IT infrastructure overhauls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fresh Organic Chicken Market |
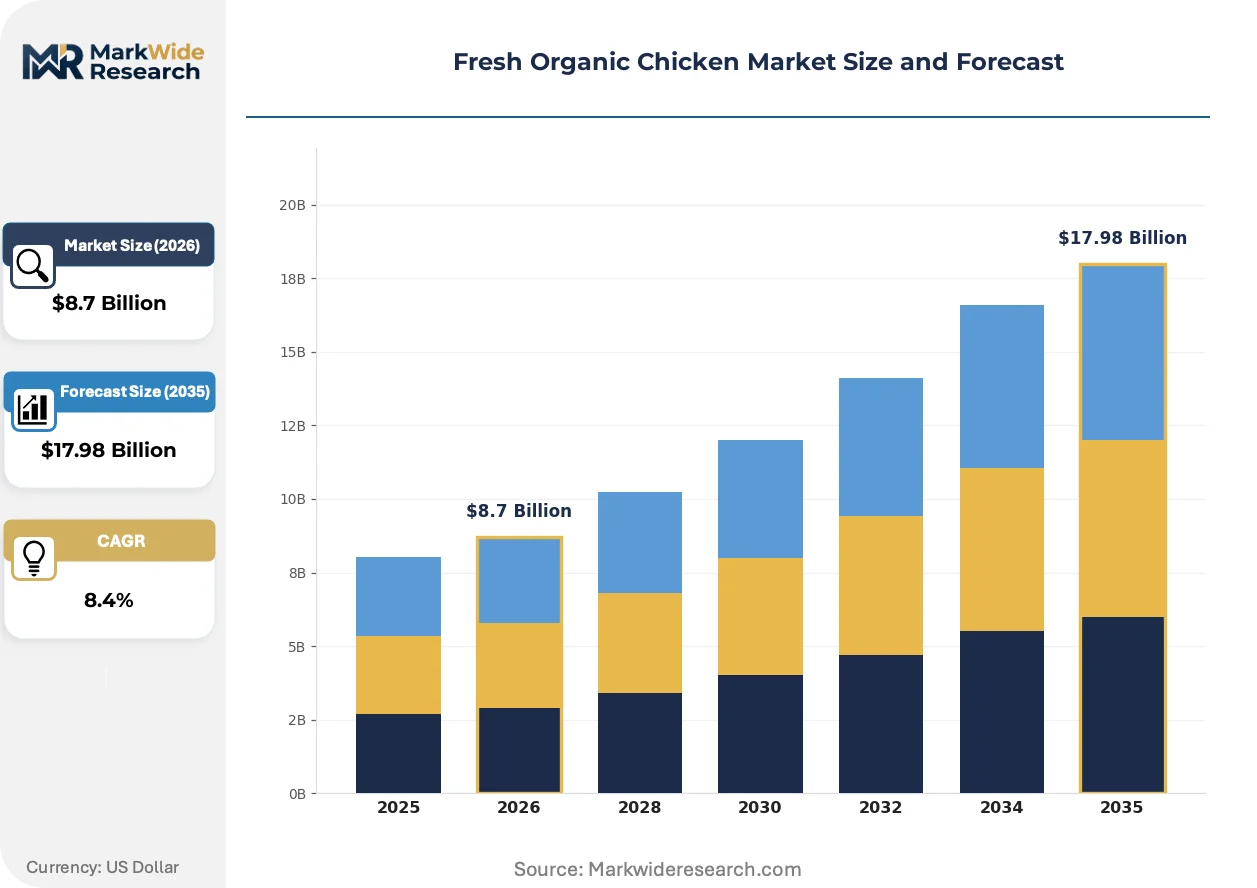
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Chicken, Chicken Breasts, Chicken Thighs, Chicken Wings, Chicken Drumsticks Distribution Channel: Supermarkets, Specialty Stores, Online Retailers, Farmers Markets, Direct Sales End User: Foodservice Providers, Catering Companies, Hotels, Restaurants, Institutional Kitchens Certification: USDA Organic, EU Organic, Non-GMO, Certified Humane, Animal Welfare Approved |
| Companies Covered | Tyson Foods, Inc., Perdue Farms, Inc., Sanderson Farms, Foster Farms, Bell & Evans, Plainville Farms LLC, Mary's Organic Chicken, Pilgrim's Pride Corporation, Maple Leaf Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fresh Organic Chicken Market Shifts & Advancements
Automation and regulatory tightening are converging to reshape farm-to-table verification, with technology investments clustering around traceability and processing efficiency rather than volume expansion.
Computer vision systems deployed in poultry houses are automating welfare monitoring by tracking bird movement patterns, feed intake, and environmental stress indicators. Mid-sized organic operations in the southeastern United States are adopting these systems fastest, driven by audit preparation burdens. The technology is automating compliance documentation that previously required manual record-keeping, compressing labor costs while tightening certification adherence.
EU Green Deal agricultural targets are mandating 25% organic land use by 2030, forcing member states to expand poultry conversion incentives. France and Germany have introduced tax credits for organic feed infrastructure, redirecting capital from conventional expansion. The policy shift is concentrating organic processing investments in Poland and Romania where land conversion costs remain lower than in Western European markets.
Retail buyers are consolidating procurement through verified supplier pools, displacing spot-market purchasing for organic chicken. Supermarket chains in the United Kingdom now require pre-approved supplier status with third-party welfare audits, locking out uncertified processors. This pattern is most visible in London and Southeast England, where discounters and premium grocers alike have adopted parallel sourcing restrictions.
Fresh Organic Chicken Market Segmentation
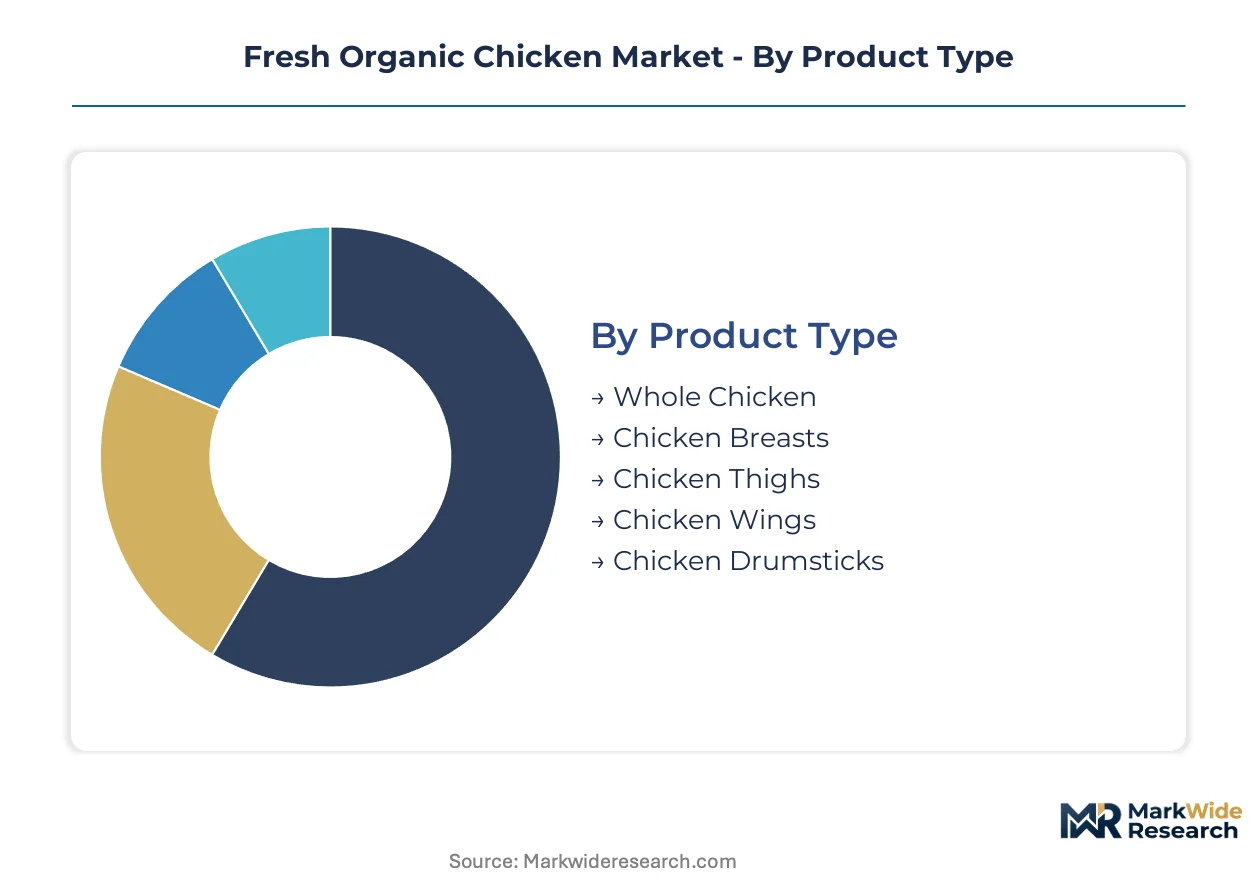
Segmentation in fresh organic chicken reveals how capital deployment, certification tiers, and channel economics fragment purchasing power across distinct buyer clusters. Each dimension carries unique compliance burdens and margin structures that reshape competitive positioning.
Product Type:
Capital intensity varies sharply across processing configurations, with air-chilled whole birds requiring facility investments that portioned cuts bypass through secondary processing.
- Whole Chicken:Air-chilled processing lines demand facility upgrades exceeding conventional water-chilled infrastructure by substantial margins. United States households in the Southeast and Midwest anchor volume, driven by roast-centric meal preparation traditions and price-per-pound value perception.
- Chicken Breasts:Portion-controlled fabrication concentrates in large-scale plants with automated deboning systems. Foodservice operators across Germany and the United Kingdom specify this cut for menu consistency, though labor-intensive trimming compresses processor margins.
- Chicken Thighs:Dark meat recovery from whole-bird breakdown supports processor economics.
- Chicken Wings:Sports-bar demand in the United States creates seasonal price volatility.
- Chicken Drumsticks:Ethnic retail channels in urban United States markets drive niche volume.
Whole chicken absorbs the bulk of installed capacity; chicken breasts are expanding most quickly.
Distribution Channel:
Channel selection determines working capital cycles, with direct sales compressing receivables periods while retail intermediaries extend payment terms.
- Supermarkets:Slotting fees and promotional allowances consume 12-18% of wholesale value for shelf placement in top United States chains. Kroger and Albertsons demand quarterly volume commitments that lock suppliers into forward grain contracts.
- Specialty Stores:Smaller format operators in London, Berlin, and New York City accept delivery minimums one-tenth of supermarket requirements. These channels prioritize Animal Welfare Approved certification over USDA Organic alone, filtering supplier pools.
- Online Retailers:Subscription box models bypass retail markups entirely.
- Farmers Markets:Direct producer sales dominate in France and Italy.
- Direct Sales:Restaurant procurement teams source hatchery-to-kitchen contracts.
Supermarkets retain the deepest volume footprint; online retailers are climbing the fastest.
End User:
End-use concentration shapes batch size requirements, with institutional kitchens demanding truckload consistency that small-batch organic operations struggle to deliver.
- Foodservice Providers:Broadline distributors like Sysco and US Foods now require organic poultry SKUs in core catalogs, pulling volume from conventional channels. United States K-12 school districts in California and New York embed organic protein mandates into nutrition procurement.
- Restaurants:Fast-casual chains including Chipotle and Sweetgreen specify organic chicken for menu transparency claims. These operators accept 15-20% protein cost premiums to support price positioning.
- Catering Companies:Event-driven demand creates volume spikes around holidays.
- Hotels:Full-service properties in London and Paris lead conversion.
- Institutional Kitchens:Hospital and university contracts emphasize cost control.
Foodservice providers command the largest procurement volumes; restaurants are gaining share fastest.
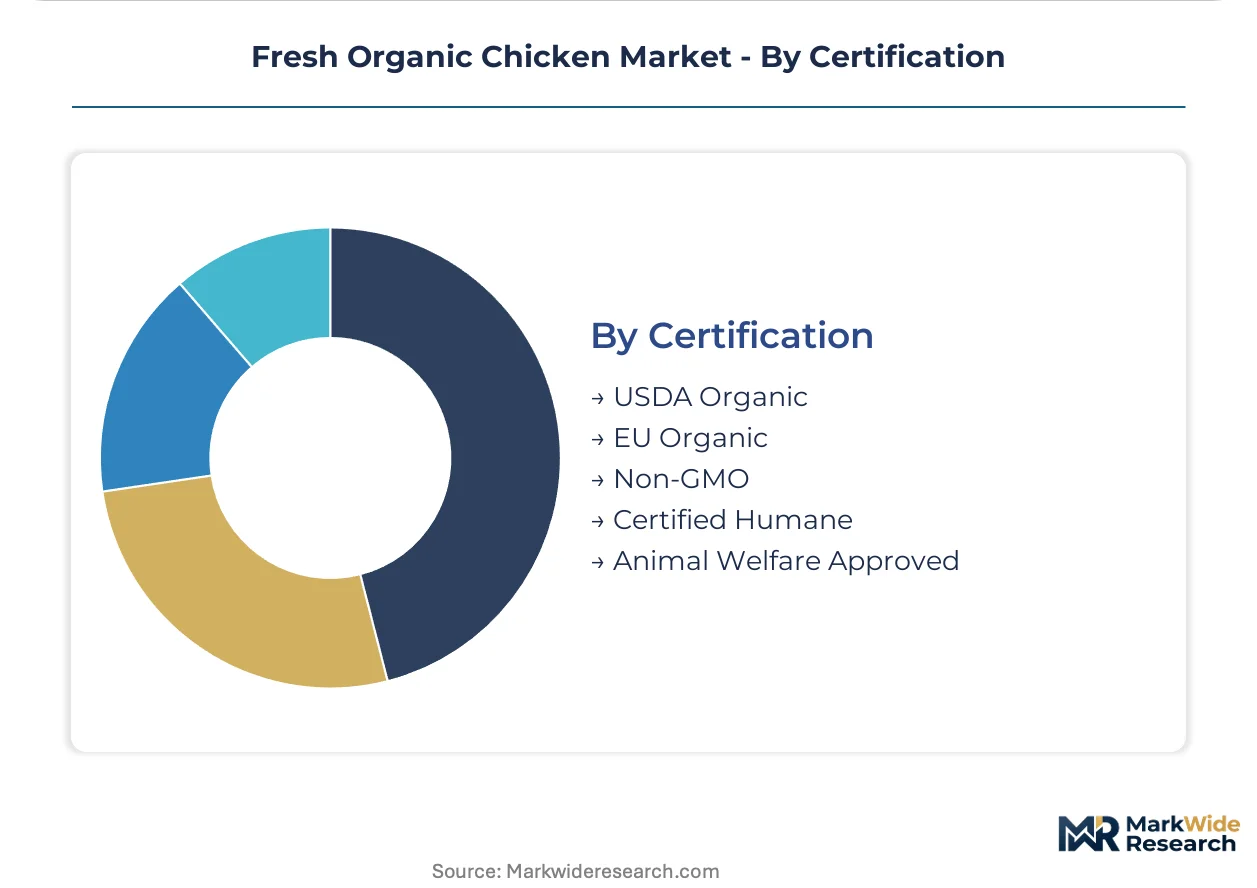
Certification:
Certification tier determines feed sourcing costs and outdoor access infrastructure, with multi-standard operations requiring parallel audit trails.
- USDA Organic:Corn and soybean sourcing from certified Midwestern United States farms adds 30-40% to feed costs versus conventional grain. FSIS chain-of-custody documentation demands real-time tracking systems from hatchery through retail.
- Animal Welfare Approved:Pasture-based requirements exceed USDA outdoor access minimums, limiting eligible producers to operations with 5+ acres per thousand birds. United Kingdom retailers Waitrose and Marks & Spencer reserve premium shelf placement for this standard.
- EU Organic:Stocking density limits and beak-trimming restrictions apply across member states.
- Non-GMO:Feed verification without full organic compliance captures price-sensitive segments.
- Certified Humane:Indoor housing allowances attract producers in northern climates.
USDA Organic carries the broadest producer base; Animal Welfare Approved is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwestern organic grain belts in the United States anchor feedstock supply for certified poultry operations, while conversion timelines and processing infrastructure fragment capacity expansion across North America and Western Europe.
United States
Restaurant chains and K-12 school districts in California and New York embed organic protein mandates into procurement contracts. USDA Organic standards govern feed sourcing and livestock living conditions through FSIS chain-of-custody documentation. The southeastern contract grower networks are realigning toward certified organic capacity as conventional margins compress.
Germany
Retailers now require compliance documentation from hatchery through processing, locking in premium shelf placement for verified supply chains. EU Organic stocking density limits and the EU Green Deal agricultural targets mandate expanded conversion incentives. Processing investments concentrate in Lower Saxony where land conversion costs remain manageable.
United Kingdom
Supermarket chains in London and Southeast England require pre-approved supplier status with third-party welfare audits. Animal Welfare Approved certification exceeds USDA Organic requirements and commands additional price premiums. Specialty stores in London prioritize this standard over USDA Organic alone, filtering supplier pools.
France
Tax credits for organic feed infrastructure redirect capital from conventional expansion under EU Green Deal targets. Farmers markets dominate direct producer sales in regional agricultural zones. The policy shift is accelerating organic land use conversion ahead of the 2030 mandate.
Poland
Lower land conversion costs relative to Western Europe are concentrating organic processing investments. EU Organic regulations enforce stocking density limits and beak-trimming restrictions across member states. Emerging processing clusters serve export demand into Germany and the Netherlands.
Fresh Organic Chicken Market Competitive Landscape
Global majors compete with regional champions across feed-to-retail infrastructure and certification tiers. The market structure tilts toward capital-rich operators capable of financing air-chilled processing upgrades and organic grain supply chain security. Three archetypes dominate: vertically integrated agribusiness conglomerates with captive feed operations; mid-sized regional specialists leveraging Animal Welfare Approved positioning; and farm-branded direct-to-consumer subscription players bypassing retail intermediaries. Consolidation pressures favor M&A activity around organic grain sourcing assets and strategic partnerships with precision livestock monitoring technology providers.
Among United States-based agribusiness operators, Tyson Foods, Inc. and Perdue Farms, Inc. represent the vertically integrated archetype, occupying positions secured through feed-to-retail infrastructure and hatchery certification programs. Bell & Evans exemplifies the technology-differentiated specialist tier, with air-chilled processing capabilities that extend shelf life parameters without chemical intervention.
| Leading Market Players |
|---|
| Tyson Foods, Inc. |
| Perdue Farms, Inc. |
| Sanderson Farms |
| Foster Farms |
| Bell & Evans |
| Plainville Farms LLC |
| Mary's Organic Chicken |
| Pilgrim's Pride Corporation |
| Maple Leaf Foods |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap producers across the southeastern United States anchor supply discipline through multi-generational land holdings that buffer organic grain cost spikes. Their patient capital deployment contrasts with private-equity-rolled-up specialists who compress procurement cycles to meet IRR targets, amplifying price volatility when feed markets tighten.
Pricing Analysis
Certification-bundled pricing separates Animal Welfare Approved premiums from base USDA Organic tiers, with welfare documentation unbundled as a surcharge in conventional retail channels. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, outdoor access infrastructure, and hatchery traceability investment. Cost compression in the standard tier is intensifying because organic grain supply concentrates in drought-exposed Midwestern regions. Foodservice providers exhibit highest price sensitivity due to volume procurement mandates, while specialty retail buyers absorb premiums for welfare-verified SKUs.
Supply Chain Analysis
Dual-sourcing requirements mandated by Kroger and Albertsons procurement teams force processors to qualify secondary organic grain suppliers in the Black Sea region and Argentina. Feedstock supply draws from the United States, Ukraine, and Brazil, with corn and soybean meal anchoring input costs. Single-source vulnerability concentrates in Midwestern organic grain elevators, where weather-driven harvest failures cascade through contract grower networks. Distribution runs through broadline distributors including Sysco and US Foods, with direct-to-consumer subscription channels bypassing retail markups entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fresh organic chicken functions as a cost-of-compliance market where USDA Organic and EU Organic standards erect barrier-to-entry moats that protect certified incumbents from conventional margin erosion.
For Market Incumbents: Anchor feed supply security through backward integration into certified organic grain elevators across Iowa and Illinois. Expand air-chilled processing capacity in Pennsylvania and Georgia to capture shelf-life premiums that water-chilled competitors cannot match. Defensive consolidation should target Animal Welfare Approved-certified hatcheries before EU Green Deal conversion incentives accelerate land competition. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest customer acquisition cost route for farm-branded organic chicken bypassing supermarket slotting fees. White-space concentration sits in K-12 school district procurement in Texas and Florida, where organic protein mandates lag California and New York adoption curves. Go-to-market positioning should emphasize hatchery-to-kitchen traceability documentation that institutional buyers now embed in supplier scorecards. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-sized regional processors with existing USDA Organic certification in Poland and Romania, where land conversion costs remain below Western European levels. Long-term viability hinges on securing organic grain supply contracts that outlast the current commodity price cycle. The inflection signal to watch is state-level cage-free mandate expansion beyond California and Massachusetts, which would strand conventional capacity and accelerate acquisition premiums for certified operations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Grain Supply | Tyson Foods' captive corn and soybean sourcing insulates feed costs from Black Sea volatility. |
| Animal Welfare Approved Certification Investment | Perdue Farms' hatchery accreditation commands Waitrose shelf placement premiums in London. |
| Air-Chilled Processing Capacity Expansion | Bell & Evans' facility upgrades extend retail shelf life without chemical preservatives. |
| Direct-to-Consumer Subscription Launch | Farm-branded box models capture margin typically lost to Kroger and Albertsons slotting fees. |
| Precision Livestock Monitoring Deployment | Computer vision systems automate FSIS chain-of-custody documentation for organic audit compliance. |
Research Methodology
Independent corroboration across USDA AMS price reports, EU Commission organic sector data, and FSIS inspection records underwrites the qualitative findings in this study. Primary interviews with organic certification specialists, contract grower network managers, and broadline distributor procurement directors combined with secondary validation from customs trade databases, SEC 10-K filings of publicly traded processors, and EU Green Deal agricultural transition reports. Bottom-up volume modeling triangulated against top-down market sizing from retail scanner data and foodservice procurement disclosures.
Rate-of-change decomposition across the analysis window isolates volume drivers from price effects in the 8.40% CAGR projection. Segmentation dimensions modeled include product type, distribution channel, end user, and certification tier, with additional granularity on regional regulatory cluster adoption curves. CAGRs derive from regression analysis of historical organic land conversion rates against protein demand elasticities, incorporating feed cost indices and welfare certification penetration as industry-specific forecast inputs.
The model holds under stable organic grain supply conditions and continued EU Green Deal subsidy enforcement; deviation in Midwestern drought frequency or suspension of conversion tax credits would shift the outlook materially. Deviation in state-level cage-free mandate rollouts would accelerate conventional-to-organic flock transitions beyond baseline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Rendered Poultry Products Market
Meat Products
Meat Tenderizer Market
Meat Products
Binders and Scaffolders for Meat and Meat Substitutes Market
Meat Products
North America Canned Meat Market
Meat Products
Blended Meat Market
Meat Products
China Processed Meat Market
Meat Products
Beef Fat Market
Meat Products
Brazil Meat Products Market
Meat Products
Organic Chicken Market
Meat Products
Europe Edible Meat Market
Meat Products
United Arab Emirates Edible Meat Market
Meat Products
Ham Slicers Market
Meat Products
Pork Flavors Market
Meat Products
Meat Products Market
Meat Products
Pork Meat Market
Meat Products
Middle East Red Meat Market