
 Germany Plastics Market | 2026-2036
Germany Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Plastics Market Intelligence
The distinction between high-performance engineering plastics and commodity polymers is hardening within the German market, driven by specialized end-use requirements. BASF SE leverages its extensive R&D to lead in engineered materials for demanding automotive applications. LANXESS AG competes through its focus on high-performance polymers and additives. In contrast, suppliers like INEOS operate at scale in the commoditized polyethylene and polypropylene segments.
Plastics are synthetic or semi-synthetic polymers characterized by their high molecular weight and plasticity. These materials, derived primarily from petrochemicals or bio-based sources, are processed into final forms using methods like injection molding, extrusion, and blow molding. Packaging applications continue to drive volume for polyethylene and polypropylene, though with lower margins. Conversely, automotive components and construction materials represent higher-value segments where polyamides and polycarbonates offer superior performance characteristics.
The EU Green Deal and its Circular Economy Action Plan are compelling German manufacturers to increase recycled content and design for end-of-life recyclability. Stringent substance regulations under REACH and specific material standards enforced by Germany's KBA for automotive parts govern market access. Navigating the interplay between these circularity mandates and the performance requirements for advanced applications is the central strategic challenge for market participants.
Market Dynamics
The central dynamic in the Germany plastics market is the tension between the automotive industry's demand for advanced, lightweight polymers for electric vehicles and the simultaneous regulatory pressure from the EU Green Deal to adopt circular, recyclable materials.
Growth Catalysts
- Electric Vehicle Production:The automotive sector's demand for lightweight polyamides and polycarbonates to reduce EV weight and extend battery range is a primary catalyst.
- EU Green Deal Mandates:Regulations requiring higher percentages of post-consumer recycled content in new products, particularly in packaging, are stimulating investment in Germany's recycling infrastructure and creating demand for high-quality recyclates.
- Industrial Concentration:The dense network of automotive and machinery manufacturers in southern German states like Bavaria and Baden-Württemberg creates localized, high-volume demand for specialized engineering plastics.
Market Restraints
- Feedstock Price Volatility:The market's dependence on petrochemical feedstocks exposes German plastic producers to significant price fluctuations and supply chain disruptions tied to global energy markets.
- Regulatory Friction:High costs and administrative burdens under the EU's REACH regulation for substance registration impede new material development and market entry for smaller innovators.
- Substitution Threats:In certain high-stress structural applications within the automotive and aerospace sectors, advanced aluminum alloys and carbon fiber composites present a persistent substitution threat to engineering plastics.
Strategic Opportunities
- Bio-Based Polymers:Expanding production of bio-based and biodegradable plastics for single-use applications like food packaging and consumer goods offers a pathway to meet sustainability targets.
- Chemical Recycling Advancement:Developing chemical recycling to process mixed plastic waste aligns with EU circularity goals and opens new feedstock sources currently lost to incineration.
- Circular Economy Infrastructure:German federal and state-level incentives for circular economy projects create opportunities for investment in advanced sorting technologies and specialized recycling facilities.
Industry Challenges
- Automotive Certification Hurdles:Navigating Germany's stringent KBA material approval process for new automotive components is a time-consuming and costly challenge that can delay the introduction of innovative polymers.
- Capital Investment Needs:Transitioning to a circular model requires significant capital for new sorting and reprocessing facilities to handle post-consumer recyclate volumes at scale.
- Specialized Skills Gap:A shortage of polymer scientists and chemical engineers with expertise in bioplastics, circular material design, and advanced recycling processes hinders R&D and operational efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Plastics Market |
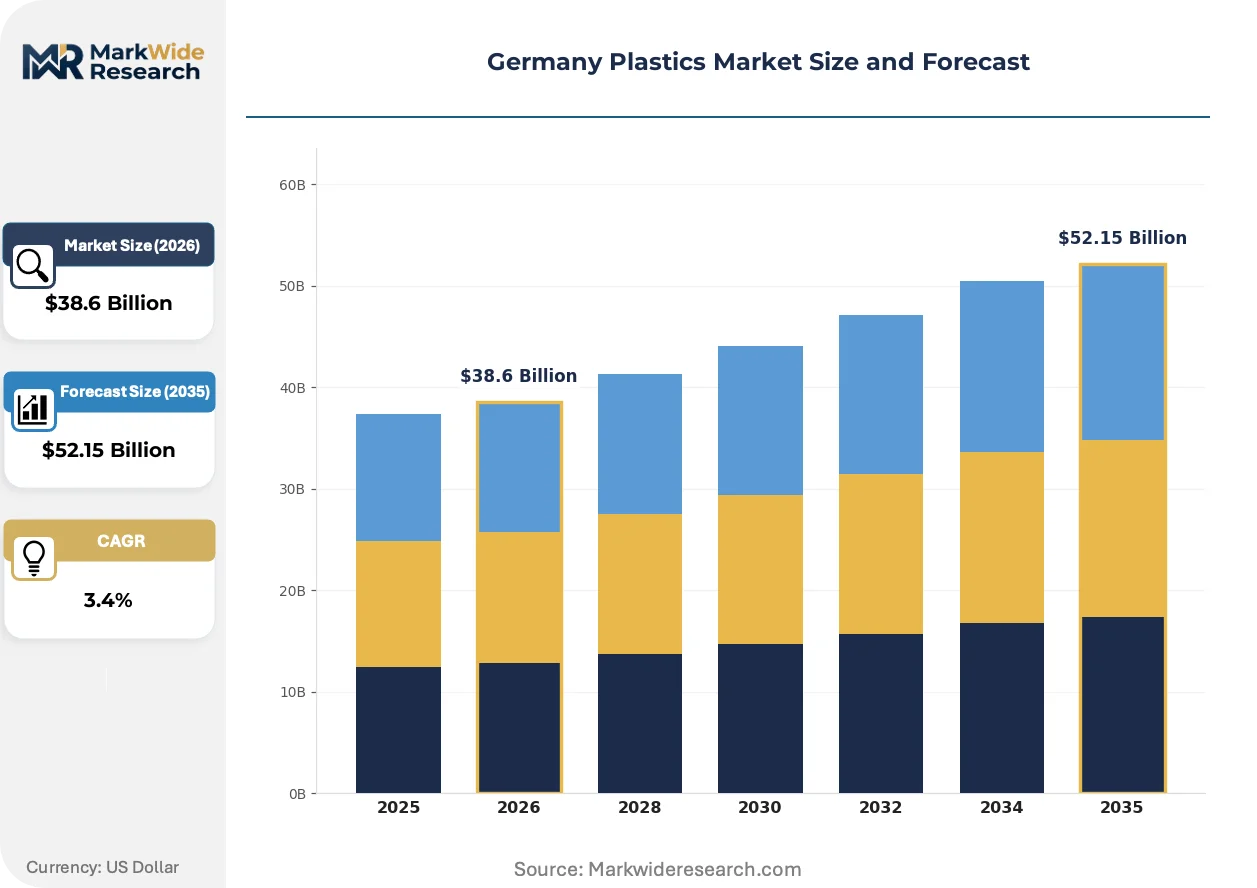
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $52.15 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene, Polycarbonate, Polyamide Form: Film, Sheet, Granules, Pellets, Foam, Fibers Application: Packaging, Automotive Components, Construction Materials, Consumer Goods, Electrical Devices, Agriculture Supplies End User Industry: Automotive OEMs, Building Contractors, Electrical Manufacturers, Food & Beverage Producers |
| Companies Covered | Braskem SA, LANXESS AG, BASF SE, Celanese Corp., Saudi Basic Industries Corp. (SABIC), Evonik Industries AG, Koninklijke DSM N.V., Röchling SE & Co. KG, INEOS AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Plastics Market Strategic Shifts & Innovations
Material innovation and regulatory compliance are the defining forces in the German plastics market. The industry navigates the dual demands of high-performance applications and sustainability mandates, compelling a reevaluation of material portfolios and production processes.
High-performance thermoplastic composites, such as carbon-fiber-reinforced polyamides, provide a superior strength-to-weight ratio. Germany's automotive and aerospace sectors are the primary adopters, using these materials to replace heavier metal parts. This technology is absorbing design focus from monolithic plastics, enabling more complex, integrated structural parts.
The EU's Circular Economy Action Plan is a key policy driver. It compels German manufacturers to increase recycled content and design products for end-of-life recyclability. The packaging sector is most affected, responding by simplifying polymer choices in multilayer films and adopting mono-material designs.
A significant behavioral shift is underway as automotive OEMs demand full material traceability and life-cycle assessment data. This disrupts traditional supplier relationships based on price alone, favoring vendors who provide digital product passports to verify sustainability claims. This requirement is most visible in southern Germany, where premium automotive brands manage complex, globally sourced supply chains.
Germany Plastics Market Segmentation
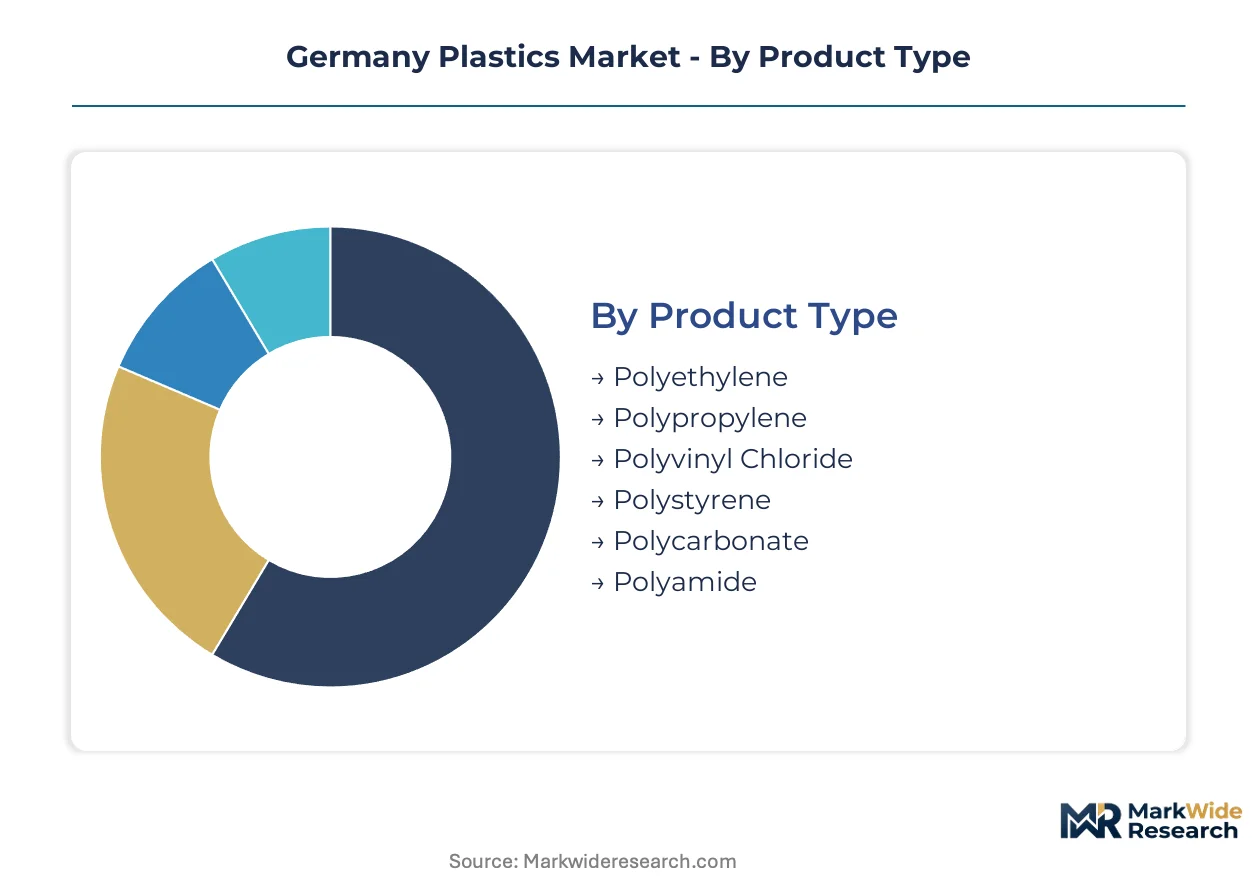
Segmentation of the Germany plastics market clarifies the diverse material demands and application landscapes driving industry evolution. Understanding these distinct segments allows participants to identify high-value niches and navigate the complex interplay between commodity volumes and specialized engineering requirements. This granular view informs strategic decisions for product development and market penetration across the German industrial base.
Product Type:
The product type segmentation highlights the volume-driven commodity polymers versus the premium, performance-oriented engineering plastics in the German market.
- Polyethylene:This thermoplastic polymer, available in various densities (HDPE, LDPE, LLDPE), offers excellent chemical resistance and flexibility. Demand concentrates in the German packaging sector for films and bottles, driven by cost-effectiveness and processability for high-volume consumer goods.
- Polycarbonate:A high-performance thermoplastic known for its transparency, impact resistance, and heat deflection properties, polycarbonate is critical for optical and structural applications. German automotive OEMs in Bavaria and Baden-Württemberg increasingly specify it for lightweighting initiatives in electric vehicle battery housings and interior components.
- Polypropylene:A versatile, semi-crystalline thermoplastic polymer valued for its high strength-to-weight ratio and chemical resistance. It finds extensive use in German automotive interiors, packaging, and consumer goods.
- Polyvinyl Chloride:PVC is a durable and cost-effective polymer widely used in construction for pipes, window profiles, and flooring due to its weather resistance. German infrastructure projects maintain steady demand for this material.
- Polystyrene:This rigid, transparent thermoplastic is common in German packaging for disposable containers and insulation applications as expanded polystyrene (EPS). Its ease of processing supports high-volume manufacturing.
- Polyamide:Known for its strength, stiffness, and high-temperature resistance, polyamide (Nylon) is a key engineering plastic. German machinery manufacturers and the automotive industry deploy it for structural parts and engine components requiring robust mechanical properties.
Today's leader: Polyethylene. Tomorrow's challenger: Polyamide.
Form:
The market for plastics in Germany is segmented by the physical form in which materials are supplied, directly impacting their processing and end-use applications.
- Film:Thin, flexible plastic sheets are produced through extrusion and are essential for protective and barrier applications. German food and beverage producers rely on plastic films for packaging, where they provide extended shelf life and tamper evidence for consumer products.
- Foam:Cellular plastic structures, such as expanded polystyrene (EPS) or polyurethane foam, offer excellent insulation and cushioning properties. German construction companies utilize foam for thermal insulation in buildings, supporting energy efficiency mandates and reducing heating costs.
- Sheet:Thicker, rigid plastic panels used for thermoforming, signage, and construction. German manufacturers incorporate plastic sheets into various industrial and architectural designs.
- Granules:Small, uniform plastic pellets or beads are the primary raw material form for most plastic processing techniques like injection molding and extrusion. German plastics converters consume vast quantities of granules for diverse product manufacturing.
- Pellets:Similar to granules, these small, solid pieces of plastic resin are standard feedstock for molding and extrusion processes. German polymer producers supply pellets to a wide array of industrial clients.
- Fibers:Long, thin strands of plastic, often spun into textiles or used for reinforcement in composite materials. German textile manufacturers and technical applications utilize plastic fibers for specialized products.
Film materials currently drive the highest volume, while foam products demonstrate the steepest expansion trajectory.
Application:
This segment categorizes plastics based on their primary end-use, illustrating where the largest volumes and highest-value propositions are realized within the German market.
- Packaging:Plastics in packaging provide protection, preservation, and presentation for goods across numerous industries. The German food sector and retail industry represent the largest consumers, where plastics enable efficient distribution and consumer convenience, despite increasing regulatory scrutiny.
- Automotive Components:Plastics are indispensable for manufacturing vehicle parts, contributing to weight reduction, fuel efficiency, and design flexibility. German automotive OEMs, particularly those focused on electric vehicles, integrate advanced polymers for interior trim, exterior body panels, and under-the-hood components to enhance performance.
- Construction Materials:This application includes plastics used in pipes, insulation, flooring, and window frames. German building codes and sustainability targets drive demand for durable and energy-efficient plastic solutions in residential and commercial construction.
- Consumer Goods:Plastics form a wide array of everyday products from appliances to toys and sporting equipment. German consumers value the durability, versatility, and aesthetic appeal that plastics bring to these diverse articles.
- Electrical Devices:Plastics provide essential insulation, housing, and structural elements for electronic and electrical products. German electronics manufacturers use specialized polymers for components requiring high heat resistance and electrical non-conductivity.
- Agriculture Supplies:This segment encompasses plastics used in greenhouses, irrigation systems, mulching films, and protective covers. German agricultural practices utilize these materials to improve crop yield and resource efficiency.
Automotive components command a significant value share, while packaging maintains the largest volume contribution.
End User Industry:
The end-user industry segmentation delineates the primary sectors consuming plastics, reflecting distinct purchasing patterns and margin structures across the German economy.
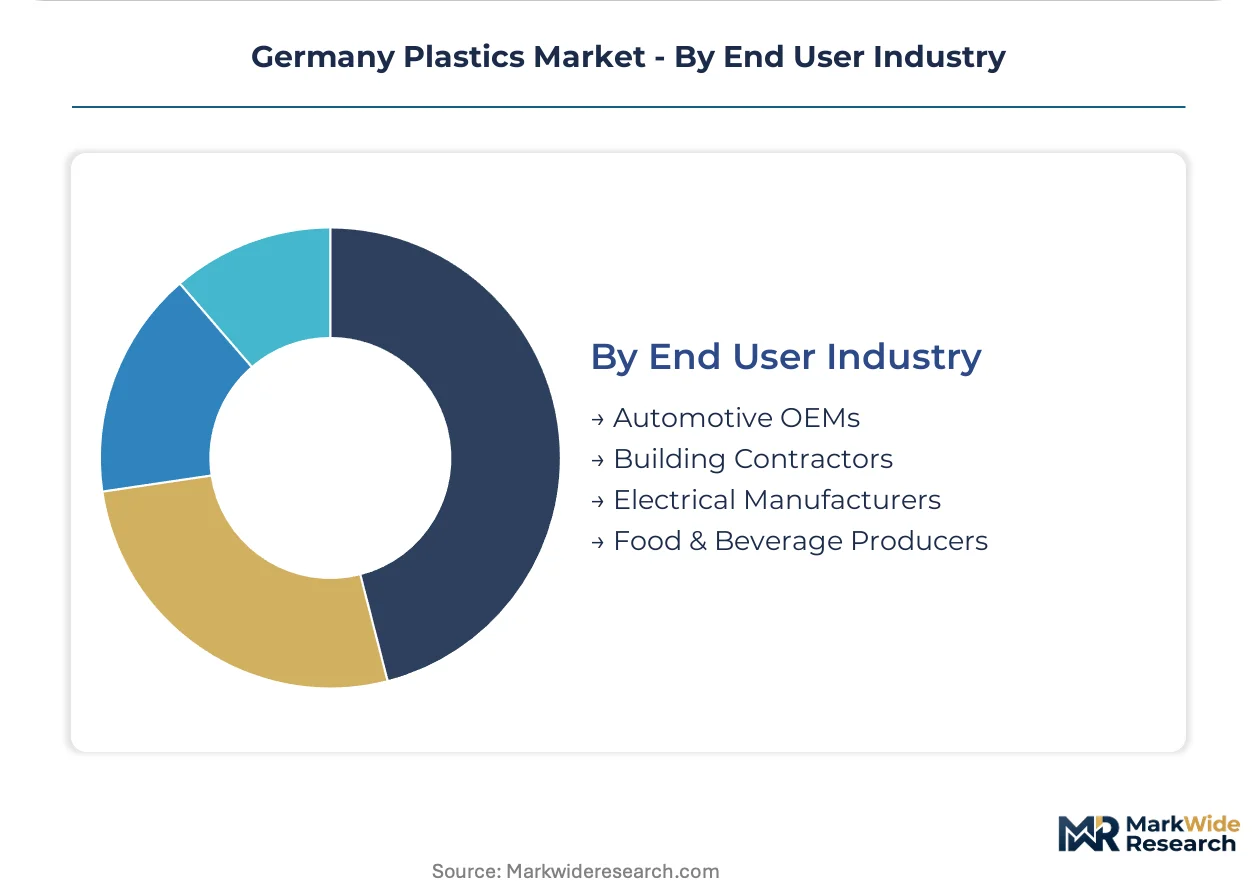
- Automotive OEMs:Original Equipment Manufacturers in the automotive sector require high-performance, lightweight plastics for vehicle production. German car manufacturers, especially in the premium and electric vehicle segments, demand materials that meet stringent safety and performance standards for both interior and exterior applications.
- Food & Beverage Producers:This industry relies heavily on plastics for packaging, storage, and processing of food and drink products. German food companies prioritize materials that ensure hygiene, extend shelf life, and comply with strict food contact regulations, often seeking sustainable packaging solutions.
- Building Contractors:Construction companies utilize plastics for various building applications, including piping, insulation, and architectural elements. German contractors seek durable, cost-effective, and energy-efficient plastic materials for residential and commercial projects.
- Electrical Manufacturers:Producers of electrical and electronic devices incorporate plastics for insulation, casings, and internal components. German electrical manufacturers require materials with specific dielectric properties and flame retardancy to ensure product safety and performance.
Automotive OEMs represent a high-margin segment for specialized plastics, contrasting with the volume-driven requirements of Food & Beverage Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's robust automotive sector drives demand for high-performance polymers, contrasting with North Rhine-Westphalia's emphasis on packaging and industrial films. German federal incentives for circular economy projects support material innovation across these diverse regions. This regional specialization shapes plastic market dynamics within Germany.
Bavaria
Demand for lightweight polyamides and polycarbonates for electric vehicle production remains strong in Bavaria. The KBA's stringent material approval processes influence polymer selection for automotive components. Munich and Augsburg concentrate advanced manufacturing, requiring specialized engineering plastics for complex assemblies.
Baden-Württemberg
This state's machinery and automotive industries require advanced thermoplastic composites for structural applications. EU Green Deal mandates push manufacturers towards increased recycled content in product designs. Stuttgart's automotive cluster leads innovation in high-strength, low-weight plastic solutions.
North Rhine-Westphalia
Packaging applications, particularly for polyethylene and polypropylene, generate substantial volume in this industrial heartland. German regulations on single-use plastics encourage innovation in bio-based and recyclable materials. The Rhine-Ruhr region's chemical parks are centers for polymer production and processing.
Hesse
The chemical and pharmaceutical industries in Hesse drive demand for specialized plastics in medical devices and laboratory equipment. REACH regulations govern the development and use of new polymers, ensuring product safety. Frankfurt's strategic location supports distribution networks for plastic raw materials and finished goods.
Lower Saxony
Automotive manufacturing and agricultural plastics contribute significantly to demand in Lower Saxony. German energy efficiency mandates promote the use of foam insulation products in construction. Wolfsburg's automotive production facilities require high-performance plastics for vehicle interiors and exteriors.
Germany Plastics Market Key Industry Players
Top-tier vendors anchor the high-performance engineering plastics segment, while commodity polymer producers compete on scale and efficiency. The market structure exhibits a tiered consolidation, with large chemical conglomerates dominating primary production. Strategic archetypes include diversified chemical giants, specialized polymer manufacturers, and regional converters. Portfolio diversification and capacity expansion represent dominant competitive moves among market participants. Technology licensing also facilitates market entry for niche players.
Within the diversified chemical conglomerates, Germany-based BASF SE and LANXESS AG exemplify extensive R&D capabilities for advanced materials. These entities anchor the high-value engineering plastics segment, serving demanding applications like automotive and electronics. UK-headquartered INEOS AG, in contrast, represents a scale-driven archetype, focusing on large-volume commodity polymers such as polyethylene and polypropylene for packaging. These companies collectively shape the supply dynamics for various plastic types and performance tiers in the German market.
| Leading Market Players |
|---|
| Braskem SA |
| LANXESS AG |
| BASF SE |
| Celanese Corp. |
| Saudi Basic Industries Corp. (SABIC) |
| Evonik Industries AG |
| Koninklijke DSM N.V. |
| Röchling SE & Co. KG |
| INEOS AG |
| Others |
Cost & Logistics Intelligence
Diversified chemical conglomerates, with their integrated production capabilities, significantly influence both supply behavior and pricing discipline across the German plastics market. Their scale allows for cost efficiencies in commodity segments, while specialized R&D supports premium pricing for advanced materials.
Pricing Analysis
Bundled solutions, integrating material supply with technical support for complex applications, command higher margins than unbundled commodity transactions. The pricing model often shifts from commodity spot rates for polyethylene to long-term contract-based offtake agreements for specialized polyamides. Price differentiation stems from material quality grade, KBA certification for automotive use, and the volume scale of procurement. Pricing pressure stems from feedstock price volatility and substitution threats from alternative materials. Packaging end-users exhibit the highest price sensitivity, whereas automotive OEMs prioritize performance over cost for critical components.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks facilitate efficient material flow from major European chemical production sites into Germany's industrial heartlands. The German plastics market primarily sources from global petrochemical suppliers for feedstocks like naphtha and ethylene. A key supply chain risk is commodity price volatility, particularly for petrochemical inputs tied to global energy markets. Distribution for high-performance polymers often runs through direct sales channels to large industrial customers, while commodity plastics rely on a network of specialized distributors and converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
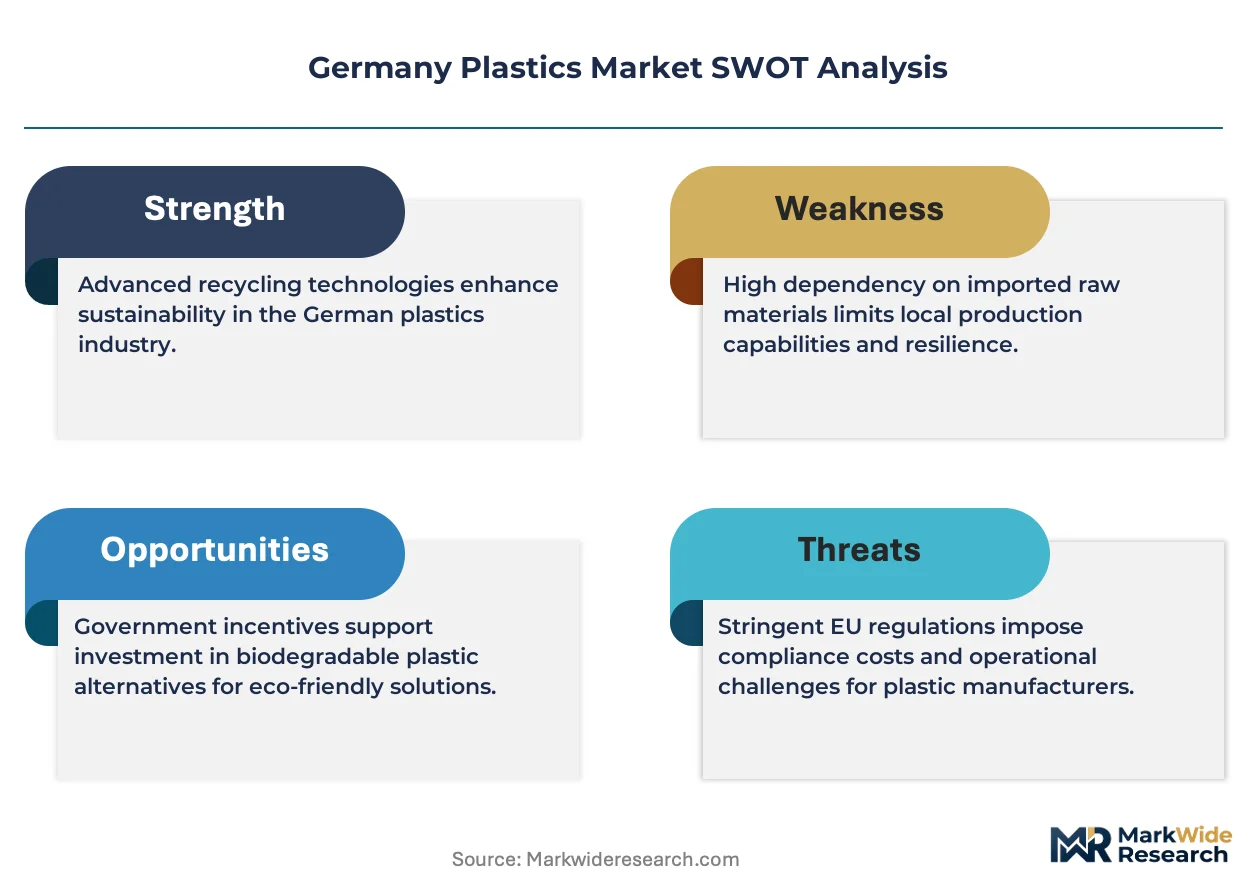
The German plastics market offers a geographic-arbitrage play due to stringent EU Green Deal mandates and higher operational costs compared to less regulated manufacturing regions. This creates opportunities for specialized material solutions.
For Market Incumbents:
Cement leadership in high-performance engineering plastics by expanding R&D into next-generation thermoplastic composites. Invest significantly in chemical recycling infrastructure within Germany to meet EU circularity mandates and mitigate future petrochemical supply risks. Secure long-term supply agreements for high-quality recyclates to address increasing demand from automotive OEMs. This defensive posture counters substitution threats from advanced metal alloys and addresses regulatory pressure on virgin plastic consumption.
For New Entrants and Emerging Players:
A price-point gap exists for bio-based and high-quality recycled polymers that meet stringent performance criteria. Target the packaging sector with innovative mono-material designs that simplify end-of-life recycling. Focus on developing specialized chemical recycling technologies that can process mixed plastic waste streams, currently a significant challenge. A direct-to-OEM partnership model for co-developing circular materials for electric vehicle components offers a strong go-to-market angle.
For Investors and Strategic Acquirers:
Valuations sit cheapest among traditional commodity polymer producers facing significant regulatory headwinds and feedstock volatility. The long-term viability favors entities focused on circular economy solutions and high-performance materials for demanding applications. Target specialized chemical recycling technology providers or bio-polymer startups with proven scalability. The signal to watch is an increase in KBA approvals for automotive components containing high percentages of post-consumer recycled content, indicating market acceptance.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Aligns German production processes with EU sustainability targets and reduces carbon footprint. |
| Capacity Expansion for Recyclates | Addresses the growing demand for recycled content, particularly in packaging and automotive sectors. |
| Joint Venture in Bio-polymers | Accelerates innovation and market penetration for sustainable plastic alternatives. |
| Long-term Supply Agreements for Recyclates | Secures stable feedstock sources for manufacturers transitioning to circular models. |
| Technology Licensing for Chemical Recycling | Provides access to advanced processes for challenging plastic waste streams, enhancing circularity. |
Research Approach
Bottom-up automotive component modeling reconciled against top-down petrochemical supply tracking forms the analytical core for the Germany plastics market. The approach integrates extensive primary interviews with polymer scientists, automotive OEM procurement leads, packaging R&D managers, and chemical plant managers. Secondary validation draws from EU Commission reports, KBA material approval databases, German federal statistics, and industry association reports.
The input-output matrix frames the forecast across the analysis window, segmenting by product type, form, application, end-user industry, and regional production/consumption clusters within Germany. Compound annual growth rates (CAGRs) derive from historical trends, projected market dynamics, and anticipated regulatory impacts. Key industry-specific forecast inputs include petrochemical feedstock prices and electric vehicle production targets for German automotive manufacturers.
The model assumes a particular technology adoption path; alternative pathways for advanced recycling or bio-based material penetration would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and sustained investment in circular economy initiatives. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Green Polyvinyl Chloride Market
Recycled Plastics
Aluminum Recycling Market
Recycled Plastics
Asia-Pacific Plastic Waste Management Market
Recycled Plastics
Indonesia Plastics Market
Recycled Plastics
Vietnam Recycled Plastics Market
Recycled Plastics
Myanmar Plastics Market
Recycled Plastics
Japan Recycled Plastics Market
Recycled Plastics
Iron Recycling Market
Recycled Plastics
Recyclability-Optimized Impact Modifiers for Polyolefins Market
Recycled Plastics
Saudi Arabia Plastic Components Market
Recycled Plastics
Global Construction Plastics Market
Recycled Plastics
Global Recycled Asphalt Market
Recycled Plastics
South Korea Recycled Plastics Market
Recycled Plastics
Recycled Carbon Fiber Market
Recycled Plastics
Recycled PET Market
Recycled Plastics
Plastic Color Sorter Market