
 Electric Vehicle (EV) Battery Housing Market | 2026-2036
Electric Vehicle (EV) Battery Housing Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle (EV) Battery Housing Market Analytics
Tier-1 supplier networks is reconfiguring around aluminum-intensive housing platforms as OEMs consolidate vendor bases for electric architectures. Novelis Inc. leverages its rolled aluminum capabilities to anchor North American supply contracts for prismatic cell enclosures. ThyssenKrupp AG competes through integrated stamping and coating operations that sustain cost positions across European passenger EV programs.
An EV battery housing constitutes the structural enclosure that protects lithium-ion cells from mechanical intrusion, thermal runaway propagation, and environmental ingress, typically fabricated from 5000 or 6000 series aluminum extrusions with wall thicknesses between 1.5 mm and 3.0 mm depending on crash-load requirements. Aluminum material type dominates current procurement volumes due to its strength-to-weight ratio and established recycling infrastructure, while composite configurations represent the fastest-growing segment as carbon-fiber-reinforced thermoplastics penetrate premium platform designs. Module-level battery configuration retains the largest addressable base, though prismatic housings capture disproportionate margin pools from integrated cell-to-pack architectures.
China's SAMR enforces GB/T standards for battery mechanical abuse testing that directly dictate housing wall thickness and joint specifications. ECE R100 in Europe mandates thermal event containment timelines that shape material selection and venting geometry. EPA tailpipe regulations in the United States indirectly accelerate housing lightweighting investments by extending vehicle range thresholds. Stakeholders must monitor how cell-to-chassis integration trends alter the boundary between housing and vehicle structure.
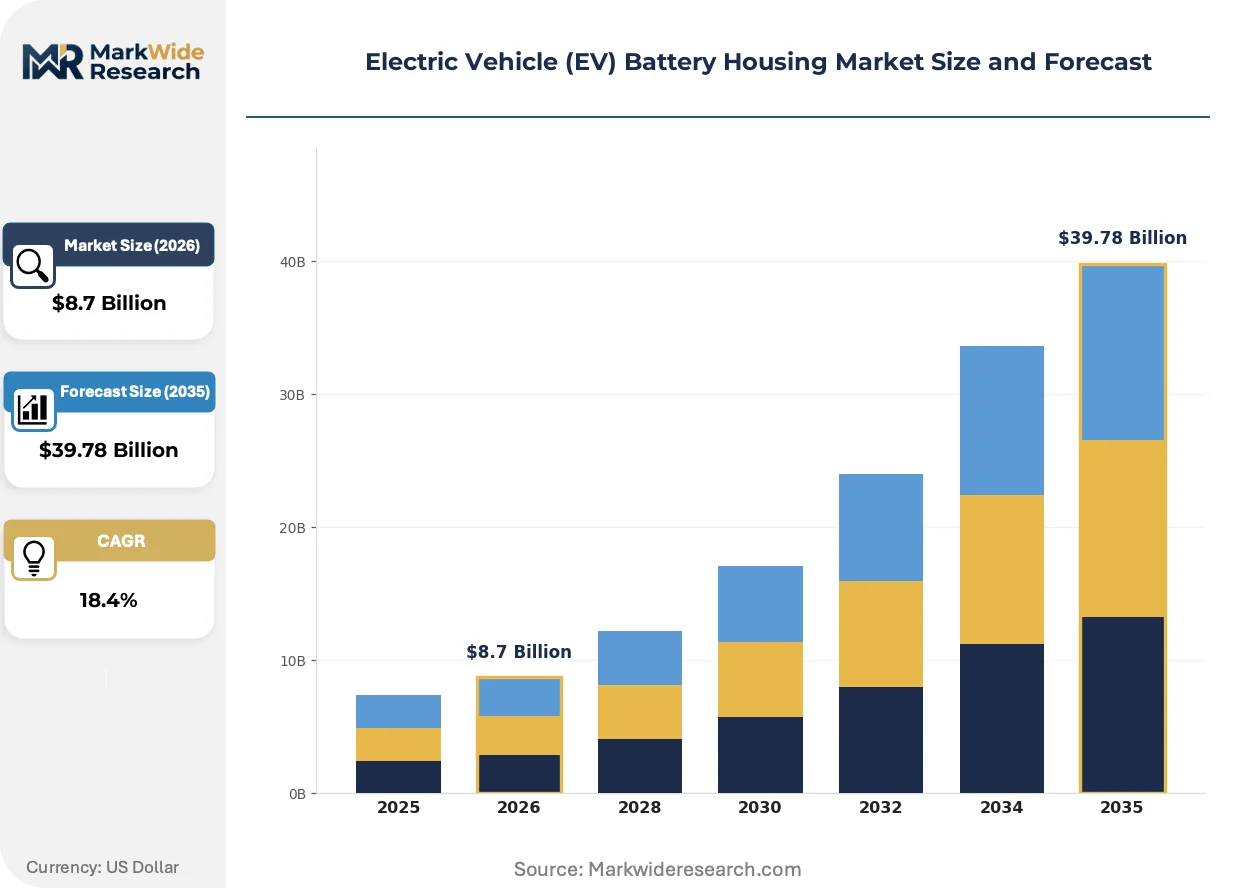
Market Dynamics
Cell-to-pack integration architectures are compressing the traditional housing supply chain by eliminating module-level enclosures and transferring structural loads directly to the vehicle chassis, forcing housing manufacturers to requalify as tier-1 chassis suppliers or retreat to niche aftermarket applications.
Growth Catalysts
- GB/T 31485 mechanical abuse testing:China's SAMR mandates stricter penetration and crush resistance standards that expand addressable content per vehicle as OEMs thicken aluminum extrusion profiles and add multi-layer shielding configurations.
- 800V electrical architectures:High-voltage platform proliferation in premium passenger segments demands enhanced electromagnetic shielding integration within housing designs, creating specification tiers that housing suppliers can monetize through value-added coating and assembly services.
- Cell-to-chassis manufacturing:Tesla's structural battery pack approach at Gigafactory Berlin and Austin is compelling European and North American OEMs to redesign housing-to-body-in-white interfaces, opening engineering services contracts for housing specialists with vehicle-level crash simulation capabilities.
Market Restraints
- Primary aluminum price volatility:LME aluminum contract swings above $2,400 per tonne compress housing fabricator margins when OEMs lock annual purchase agreements at fixed conversion premiums that do not float with ingot costs.
- Extrusion capacity concentration:Large-format press availability for 6000-series profiles above 300mm width clusters in China's Henan and Shandong provinces, exposing non-Chinese battery programs to logistics disruption and tariff exposure.
- Thermoplastic composite substitution:Carbon-fiber-reinforced PEEK and PA6 compounds from SGL Carbon and Teijin achieve comparable specific stiffness at 40% lower mass for low-volume premium applications, threatening aluminum's position in halo EV architectures.
Strategic Opportunities
- Second-life housing refurbishment:End-of-life battery pack disassembly regulations in Germany's Batteriegesetz create aftermarket demand for housing inspection, reconditioning, and recertification services that extend supplier revenue streams beyond initial OEM fitment.
- Solid-state cell compatibility:Next-generation lithium-metal and sulfide electrolyte chemistries from QuantumScape and Solid Power operate at elevated pressures requiring rigid housing architectures with precision-machined sealing surfaces, favoring suppliers with high-tolerance CNC and friction-stir welding capabilities.
- IRA domestic content credits:The Inflation Reduction Act's $7,500 EV tax credit assembly and sourcing rules incentivize North American housing production co-located with cell manufacturing, rewarding early movers with qualified domestic content status.
Industry Challenges
- Multi-physics simulation talent scarcity:Housing design now requires coupled thermal-electrical-mechanical modeling expertise that combines LS-DYNA crash, Ansys Fluent thermal, and CST Studio electromagnetic competencies, a skill stack concentrated at tier-1 automotive engineering consultancies rather than traditional metals suppliers.
- Cell-to-pack qualification timelines:OEM validation cycles for structural battery enclosures extend 18-24 months due to extended abuse testing protocols and thermal runaway propagation studies, compressing supplier cash conversion cycles and demanding patient capital structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle (EV) Battery Housing Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Aluminum, Steel, Composite, Plastic Battery Configuration: Prismatic, Cylindrical, Pouch, Module End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Commercial Fleets Manufacturing Process: Injection Molding, Stamping, Machining, Assembling |
| Companies Covered | Constellium SE, Gestamp Automocion, Novelis Inc., SGL Carbon, ThyssenKrupp AG, Nemak, UACJ Corporation, LANXESS, Magna International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle (EV) Battery Housing Market Evolving Landscape
Active materials research and manufacturing process intensification are converging to redefine housing performance benchmarks, with thermal management integration and structural multifunctionality displacing pure mechanical protection as the primary design objective.
Multi-layer aluminum-steel hybrid laminates are migrating from aerospace containment applications into EV battery housings as OEMs seek to optimize electromagnetic shielding effectiveness against cost and mass trade-offs. BMW's Neue Klasse platform and Hyundai's E-GMP derivatives specify these configurations for 800V architectures where inverter switching noise threatens vehicle electronics. The technology is compressing the addressable market for monolithic aluminum extrusions in the 150-200 kWh pack segment.
ECE R100 Revision 2 thermal propagation containment requirements are mandating venting geometry and fire barrier integration that housing suppliers must co-develop with cell manufacturers rather than specify independently. The regulation's 5-minute no-fire-exit protocol forces redesign of housing lid structures and pressure relief valve placement. European passenger EV programs face the most acute compliance pressure as type approval deadlines approach.
Fleet operators and energy storage integrators are consolidating vendor relationships around housing suppliers offering integrated battery management system mounting, cooling plate pre-assembly, and module-level fire suppression routing. This specification bundling displaces component sourcing from multiple tier-2 suppliers. The pattern is most visible in North American commercial vehicle electrification programs where uptime guarantees and total cost of ownership calculations dominate procurement criteria.
Electric Vehicle (EV) Battery Housing Market Segmentation
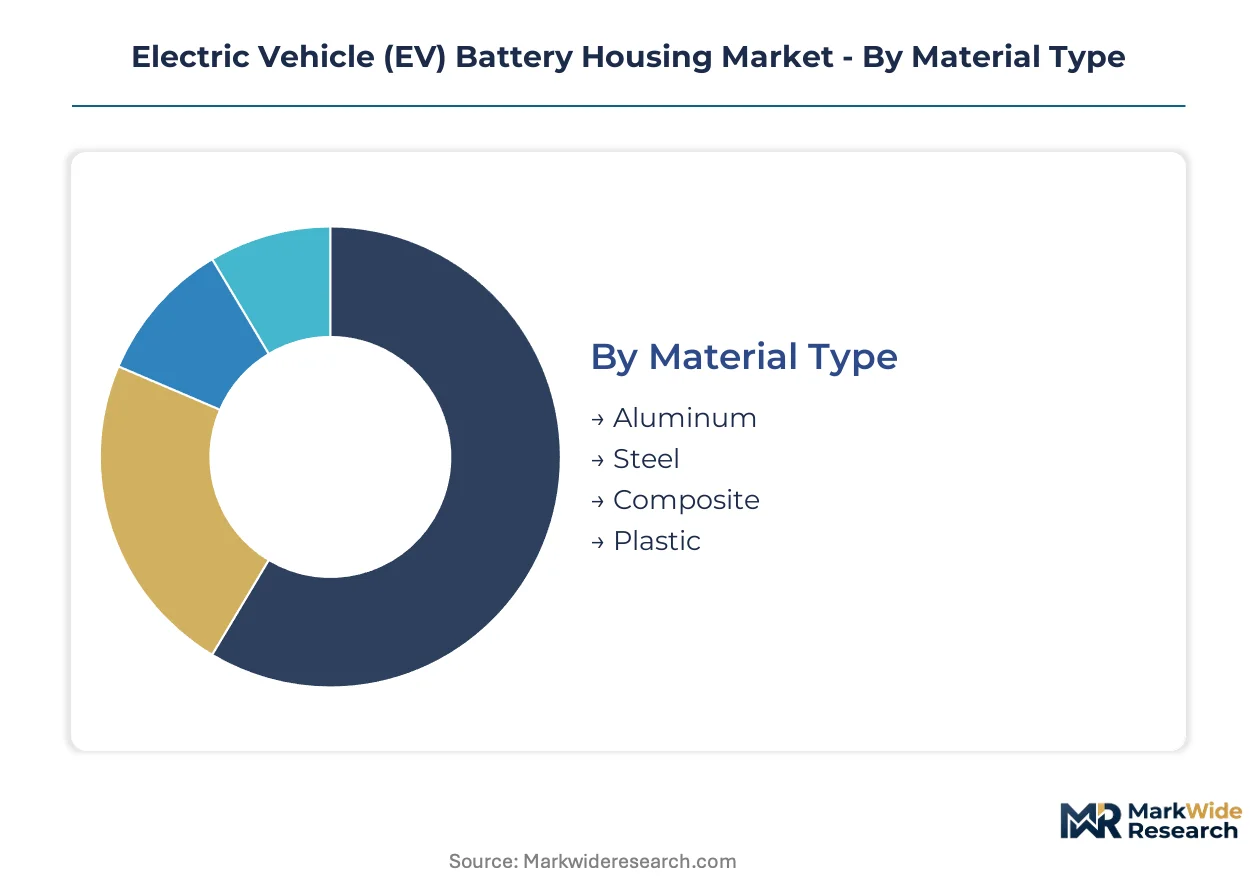
Segmentation in the EV battery housing market reveals how material selection, cell geometry, and manufacturing method combine to determine supplier positioning and margin capture. Procurement patterns diver sharply between mass-market passenger programs and premium architectures with distinct thermal management requirements.
Material Type:
After-sales service intensity varies dramatically by material—aluminum housings demand collision repair network certification, while composite configurations require specialized technician training for damage assessment and bonded joint restoration.
- Aluminum:Fabricated from 5000 or 6000 series extrusions with wall thicknesses between 1.5 mm and 3.0 mm depending on crash-load requirements. Demand concentrates in Germany's automotive manufacturing corridor where Volkswagen, BMW, and Mercedes-Benz operate dedicated battery assembly facilities, driven by strength-to-weight optimization and established recycling infrastructure.
- Steel:Cold-rolled high-strength grades dominate commercial vehicle applications where cost minimization outweighs mass reduction targets. Procurement volumes cluster in heavy-duty truck electrification programs across the US Great Lakes manufacturing belt, constrained by density penalties that limit range extension in passenger segments.
- Composite:Carbon-fiber-reinforced thermoplastics penetrate premium platform designs through SGL Carbon and Teijin supply relationships.
- Plastic:Injection-molded polymer housings serve secondary containment and non-structural applications in low-voltage auxiliary battery systems.
Aluminum holds the largest share; momentum sits with composite configurations.
Battery Configuration:
Cost tier stratification separates prismatic housings commanding premium engineering margins from cylindrical formats optimized for high-volume automation.
- Prismatic:Rectangular cell enclosures capture disproportionate margin pools from integrated cell-to-pack architectures where housing walls become primary structural members. Specification intensity peaks in 800V electrical architectures requiring enhanced electromagnetic shielding integration.
- Module:Retains the largest addressable base as legacy platform designs persist through model year transitions, though content per vehicle compresses as cell-to-pack integration eliminates intermediate enclosures.
- Cylindrical:2170 and 4680 formats drive housing standardization at Tesla's Gigafactory Berlin and Austin facilities.
- Pouch:Soft-cell configurations require rigid frame structures that hybridize aluminum extrusion with composite lid assemblies.
Module-level configuration retains volume leadership; prismatic housings gain share fastest.
End User:
Customer type determines qualification burden—OEM direct contracts demand 18-24 month validation cycles, while aftermarket channels prioritize inventory velocity and cross-platform interchangeability.
- OEMs:Direct procurement from Volkswagen, BMW, and Mercedes-Benz concentrates engineering resources on platform-specific crash simulation and thermal runaway containment protocols, with contract structures locking conversion premiums independent of aluminum ingot price volatility.
- Tier-1 Suppliers:Novelis Inc. and ThyssenKrupp AG anchor supply contracts through integrated stamping, coating, and assembly operations that sustain cost positions across European and North American passenger EV programs.
- Aftermarket Providers:Germany's Batteriegesetz creates demand for housing inspection, reconditioning, and recertification services.
- Commercial Fleets:Uptime guarantees dominate procurement criteria with bundled specifications for battery management system mounting and cooling plate pre-assembly.
OEMs command the largest share; commercial fleets represent the steepest expansion trajectory.
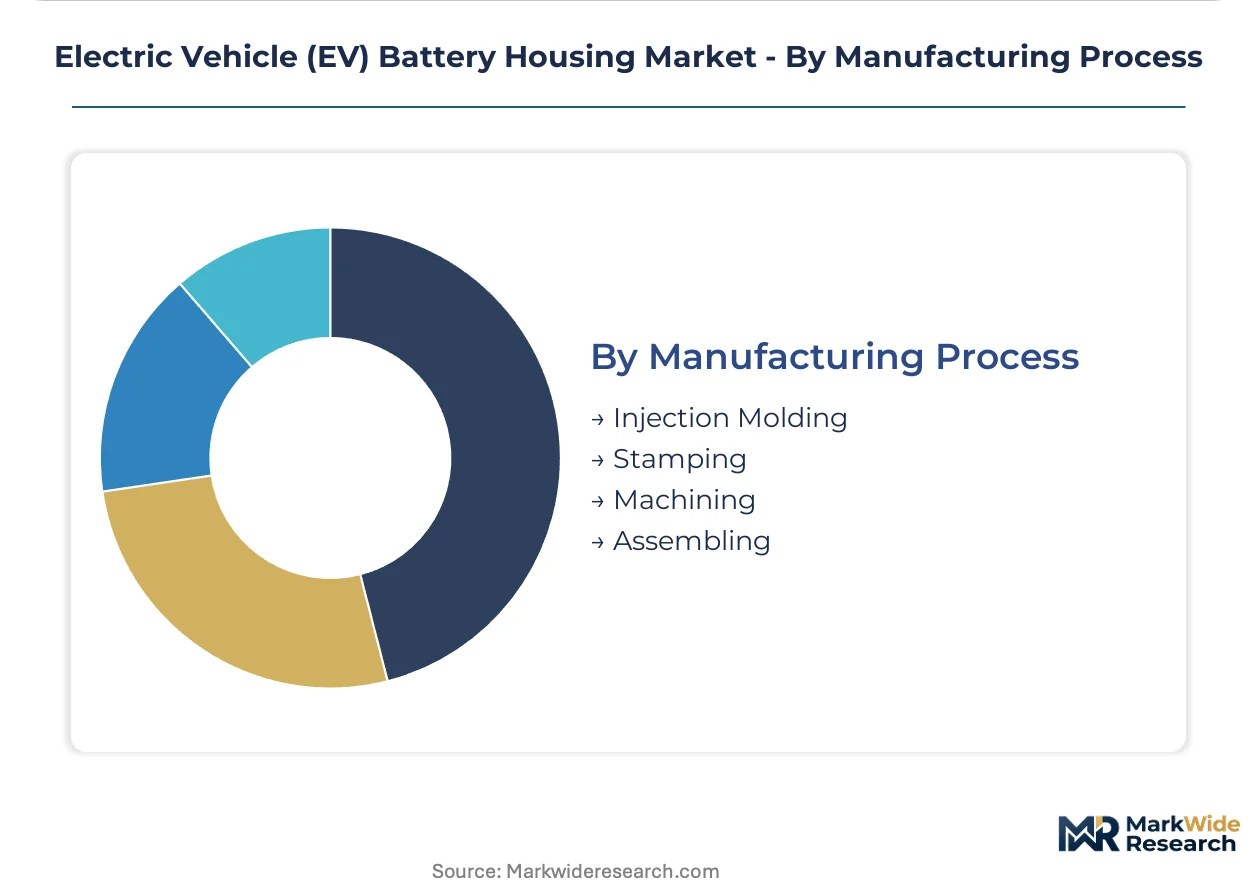
Manufacturing Process:
Supply concentration in large-format extrusion press capacity clusters manufacturing process selection, with 6000-series profiles above 300mm width bottlenecked in China's Henan and Shandong provinces.
- Stamping:High-speed press operations achieve cost efficiency in aluminum lid and tray production for high-volume passenger programs, with ThyssenKrupp AG competing through integrated coating operations that add electromagnetic shielding layers in-line.
- Machining:Precision CNC and friction-stir welding capabilities become critical for solid-state cell compatibility, where next-generation lithium-metal chemistries require rigid housing architectures with precision-machined sealing surfaces.
- Injection Molding:Thermoplastic composite substitution threatens aluminum in low-volume premium applications through carbon-fiber-reinforced PEEK compounds.
- Assembling:Module-level integration of cooling plates, fire suppression routing, and pressure relief valve placement occurs at housing suppliers offering bundled component sourcing.
Stamping holds the largest share; machining gains priority with solid-state cell development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Inflation Reduction Act's domestic content credits are redirecting battery housing investment toward North American manufacturing co-location with cell production. Germany's Batteriegesetz end-of-life regulations create aftermarket service demand that extends supplier revenue models. China's GB/T standards enforcement tightens material specifications across Asian supply chains.
United States
Tesla's structural battery pack production at Gigafactory Austin and Berlin-competitor programs from Detroit automakers drive housing demand toward cell-to-chassis integration. The IRA's assembly and sourcing rules reward qualified domestic content status for housing producers co-located with cell manufacturing. Michigan and Ohio automotive corridors concentrate stamping and coating operations serving 800V premium passenger platforms.
Germany
Volkswagen, BMW, and Mercedes-Benz battery assembly facilities in Bavaria and Lower Saxony anchor European demand for aluminum-intensive housing platforms. ECE R100 Revision 2 thermal propagation containment mandates reshape housing lid structures and pressure relief valve placement across passenger EV programs. Stuttgart and Munich engineering clusters specialize in coupled thermal-electrical-mechanical simulation for structural enclosure qualification.
China
SAMR enforcement of GB/T 31485 mechanical abuse testing expands aluminum extrusion content per vehicle as OEMs thicken wall profiles and add multi-layer shielding. Large-format 6000-series press capacity clusters in Henan and Shandong provinces expose non-Chinese battery programs to logistics concentration risk. BYD and CATL vertical integration into housing production compresses independent supplier margins in the Yangtze River Delta.
South Korea
Hyundai's E-GMP derivatives and Kia EV platforms specify multi-layer aluminum-steel hybrid laminates for electromagnetic shielding in 800V architectures. The country's national industrial regulator aligns battery safety certification with UN ECE harmonized standards to maintain export competitiveness. Gwangju and Ulsan manufacturing belts host integrated stamping and coating operations for prismatic cell enclosures.
Japan
Toyota and Honda solid-state cell development programs demand rigid housing architectures with precision-machined sealing surfaces for elevated-pressure lithium-metal chemistries. METI technology roadmaps prioritize friction-stir welding and high-tolerance CNC capabilities in supplier qualification criteria. Aichi and Kanagawa prefectures concentrate machining specialists serving next-generation battery platform engineering services.
Electric Vehicle (EV) Battery Housing Market Competitive Landscape
On the supply side, the industry is consolidating around aluminum-intensive platforms as OEMs reduce vendor counts for electric architectures. Rolled aluminum specialists and integrated stamping-coating operators anchor tier-1 supply positions across regional passenger EV programs. Three archetypes dominate: metals fabricators with extrusion capabilities, composite material specialists penetrating premium segments, and diversified automotive suppliers bundling housing with thermal management integration. Capacity expansion and strategic partnerships constitute the dominant competitive moves as suppliers secure qualification for 18-24 month OEM validation cycles.
Within the rolled aluminum tier, Novelis Inc. and UACJ Corporation represent North American and Japanese supply anchors respectively. ThyssenKrupp AG exemplifies the European integrated stamping-coating model. Constellium SE occupies a position bridging aerospace containment heritage with automotive electromagnetic shielding applications. These three fabricators anchor regional supply contracts through established recycling infrastructure and strength-to-weight optimization capabilities.
| Leading Market Players |
|---|
| Constellium SE |
| Gestamp Automocion |
| Novelis Inc. |
| SGL Carbon |
| ThyssenKrupp AG |
| Nemak |
| UACJ Corporation |
| LANXESS |
| Magna International Inc. |
| Others |
Value Network & Pricing Analysis
Henan and Shandong provinces' large-format 6000-series extrusion press concentration hands Chinese fabricators outsized leverage in annual contract negotiations with European and North American OEMs. LME aluminum volatility above $2,400 per tonne compresses margins for housing suppliers locked into fixed conversion premiums, forcing tier-1s to absorb ingot cost swings or renegotiate with cell manufacturers.
Pricing Analysis
Certification level (ECE R100/GB/T compliance grade) creates the primary spread between premium and standard tiers, with thermal propagation containment validation adding engineering margin capture. Contract-based long-term offtake dominates procurement, though spot aluminum exposure persists at conversion-stage fabricators. Price differentiation hinges on electromagnetic shielding integration and crash simulation certification depth. Cost compression in module-level configurations is intensifying because cell-to-pack integration eliminates intermediate enclosure content. Commercial fleet buyers exhibit highest price sensitivity due to total cost of ownership calculations, while premium passenger OEMs prioritize qualification speed over unit cost.
Supply Chain Analysis
Export-control regimes on large-format extrusion press technology limit capacity expansion outside China's Henan and Shandong clusters, constraining non-Chinese battery program supply security. Geographic supply concentration centers on China, Germany, and South Korea for aluminum-intensive platforms, with Japan anchoring machining capabilities for solid-state compatibility. Raw material dependencies draw from primary aluminum ingot, 6000-series billet, and electromagnetic shielding coatings. Single-source vulnerability runs through the 300mm-plus profile extrusion bottleneck. Distribution runs through tier-1 integrated stamping-coating operators serving OEM direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as cell-to-chassis integration and 800V platform proliferation extend addressable content per vehicle beyond traditional enclosure boundaries.
For Market Incumbents: Pre-empt composite substitution threats in premium architectures by securing carbon-fiber thermoplastic joint development contracts with SGL Carbon and Teijin. Anchor capacity addition in Michigan and Ohio corridors to capture IRA domestic content qualification. Deepen backward integration into aluminum recycling infrastructure to offset LME price volatility exposure. For New Entrants and Emerging Players: Solid-state cell compatibility engineering services in Japan and Germany represent the most penetrable entry point, as QuantumScape and Solid Power qualification timelines outstrip incumbent machining capacity. North American commercial fleet bundling opportunities—integrating cooling plate pre-assembly with housing supply—offer faster path to volume than OEM direct contracts. Go-to-market angle: position as cell-to-pack thermal management integration specialist rather than commodity fabricator. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors machining-capable tier-1s with friction-stir welding and high-tolerance CNC assets over pure extrusion players. Long-term viability rests on qualification for structural battery architectures where housing becomes primary vehicle structure. Acquisition target archetype: European stamping-coating operators with ECE R100 Revision 2 certification track record. Signal to watch: OEM announcements of cell-to-chassis platform engineering services outsourcing.| Strategic Initiative | Industry Significance |
|---|---|
| Cell-to-Chassis Platform Qualification | Secures 18-24 month OEM validation cycles with Volkswagen, BMW, and Mercedes-Benz. |
| Large-Format Extrusion Capacity Expansion | Reduces logistics concentration risk from China's Henan and Shandong provinces. |
| Electromagnetic Shielding Integration | Captures value-added coating margins from 800V architecture proliferation. |
| Solid-State Cell Compatibility Investment | Positions for QuantumScape and Solid Power elevated-pressure sealing requirements. |
| Second-Life Refurbishment Service Launch | Extends revenue streams beyond initial fitment under Germany's Batteriegesetz. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, vehicle production databases, customs/trade data, and IHS Markit registration data. Primary interviews engaged OEM platform engineers, tier-1 supplier procurement leads, aluminum extrusion plant managers, and aftermarket service operators. Bottom-up segment sizing triangulates against top-down market value reconciliation.
Forecast inputs include vehicle production volumes by propulsion architecture, content per vehicle trajectories for module versus cell-to-pack configurations, and regional regulatory enforcement timelines. Segmentation dimensions span material type, battery configuration, manufacturing process, and end-user category across the projection horizon. CAGRs derive from penetration curve modeling of 800V platform adoption and solid-state cell commercialization milestones.
Practitioners should monitor cell-to-chassis integration announcements, LME aluminum contract volatility, and ECE R100 Revision 2 type approval deadlines for early signals of forecast deviation. Material shifts in OEM structural battery pack sourcing strategies or GB/T standard enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Plug-In Hybrid Electric Vehicle Battery Market
Electric Vehicles
E-Bike Lithium-Ion Battery Market
Electric Vehicles
APAC E-Bikes Market
Electric Vehicles
Global Electric Vehicle (EV) Management Solution Market
Electric Vehicles
Electric Vehicle Regenerative Braking System Market
Electric Vehicles
France Solar E-Bike Market
Electric Vehicles
E-Axle Market
Electric Vehicles
Africa Electric Vehicle Market
Electric Vehicles
Electric Three Wheeler Market
Electric Vehicles
Battery Electric Vehicle (BEV) Market
Electric Vehicles
E-Bike Battery Pack Market
Electric Vehicles
North America Electric Vehicle Thermal Management System Market
Electric Vehicles
Asia-Pacific Lithium-Ion Battery for Electric Vehicle Market
Electric Vehicles
Vietnam Solar E-Bike Market
Electric Vehicles
Bus Pantograph Charger Market
Electric Vehicles
Europe Electric Light Commercial Vehicles Market