
 Commercial Electric Vehicle Dynamic Braking Resistors Market | 2026-2036
Commercial Electric Vehicle Dynamic Braking Resistors Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Electric Vehicle Dynamic Braking Resistors Market Outlook
Chinese resistor manufacturers is recalibrating capacity toward automotive-grade wirewound and thick-film designs. ABB Ltd. leverages its traction power heritage to anchor European bus and rail electrification programs. Siemens AG competes through integrated drive-train packages that bundle braking resistors with inverter systems. Vishay Intertechnology, Inc. specializes in precision power resistors for high-temperature commercial vehicle environments.
A commercial electric vehicle dynamic braking resistor dissipates excess kinetic energy as heat during regenerative braking, typically constructed from stainless steel or ceramic-composite elements rated for continuous duty cycles exceeding 600°C. These components protect battery systems from overvoltage conditions while enabling energy recovery in stop-and-go commercial duty profiles. Passive resistors dominate current installations due to cost simplicity and proven reliability in heavy-duty trucks, though smart resistors with integrated thermal monitoring are gaining traction among fleet operators seeking predictive maintenance capabilities. Water-cooled technology leads in high-power bus applications where air-cooled units face space constraints, while liquid-cooled variants are emerging for delivery vehicles requiring compact packaging.
NHTSA Federal Motor Vehicle Safety Standards govern brake system performance thresholds for commercial EVs sold in the United States, directly influencing resistor thermal capacity specifications. EPA greenhouse gas regulations for heavy-duty vehicles create compliance pathways that reward regenerative braking efficiency, embedding resistor performance into OEM platform decisions. EMA and REACH frameworks in Europe impose material restrictions on resistor coatings and substrates, reshaping supplier qualification requirements. Stakeholders must monitor how emerging battery-electric truck platforms integrate silicon carbide inverters, as higher switching frequencies alter resistor duty profiles and thermal management architectures.
Market Dynamics
The transition from silicon to silicon carbide traction inverters is compressing resistor duty cycles and forcing thermal management redesigns across commercial EV platforms. OEMs now specify dynamic braking resistors capable of handling higher switching frequencies and shorter pulse widths than legacy designs permitted.
Growth Catalysts
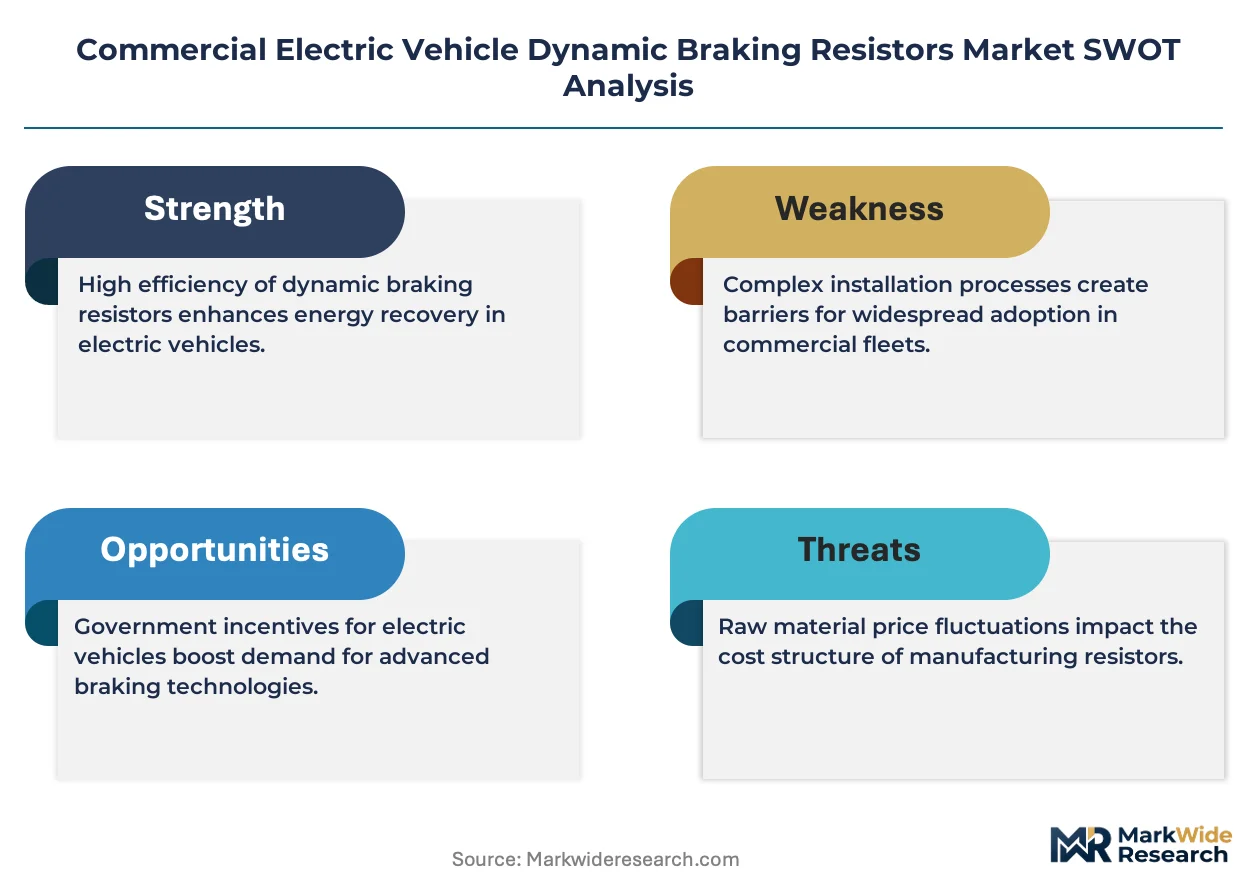
- EPA Greenhouse Gas Standards:Heavy-duty vehicle emissions rules reward regenerative braking efficiency, embedding resistor performance into OEM platform architectures.
- California Advanced Clean Trucks:Fleet procurement mandates in this state accelerate deployment of dynamic braking-equipped electric trucks and buses.
- Wirewound ceramic-composite elements:These materials now dominate high-temperature applications above 600°C continuous duty.
Market Restraints
- Nickel-chromium alloy costs:Raw material price volatility for resistor winding wires squeezes margins on stainless steel alternatives.
- Chinese supplier concentration:Automotive-grade thick-film capacity clusters in East Asian manufacturing zones, creating single-source exposure.
- Air-cooled thermal limits:Space-constrained delivery vehicles cannot dissipate sufficient heat through passive convection above 150kW braking loads.
Strategic Opportunities
- Water-cooled compact packaging:Liquid thermal management enables resistor integration into low-floor bus architectures previously blocked by space constraints.
- Integrated thermal monitoring:Smart resistors with embedded sensors create predictive maintenance revenue streams for fleet operators.
- German bus electrification:Federal and state transit procurement programs favor suppliers offering complete drive-train resistor-inverter bundles.
Industry Challenges
- High-voltage safety certification:IEC 60664 insulation coordination standards for 800V commercial platforms extend validation timelines by 8-14 months.
- Silicon carbide inverter integration:Faster switching frequencies alter harmonic profiles, requiring resistor redesigns without standardized test protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Electric Vehicle Dynamic Braking Resistors Market |
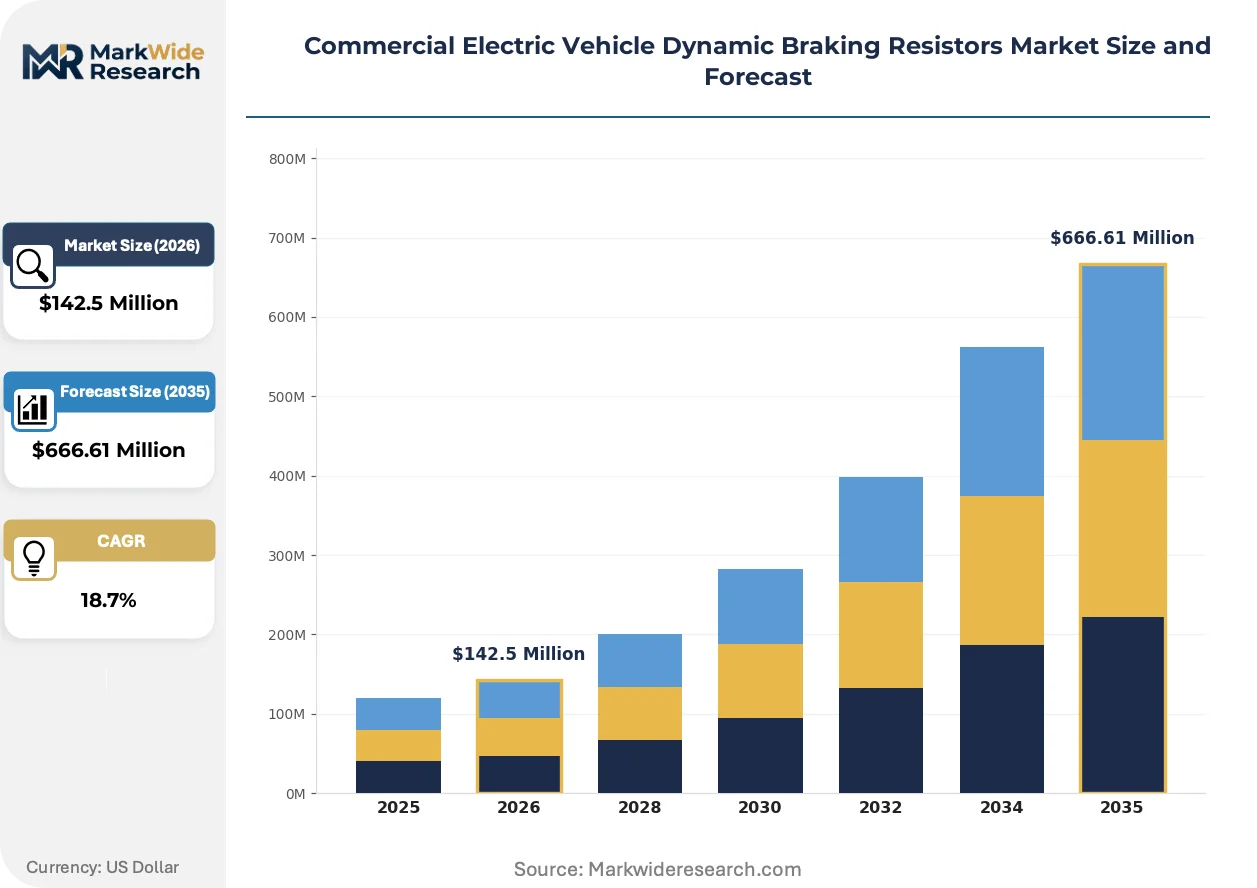
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $666.61 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Resistors, Active Resistors, Hybrid Resistors, Smart Resistors Technology: Air Cooled, Water Cooled, Liquid Cooled, Oil Cooled End User: Fleet Operators, OEMs, Aftermarket Providers, Public Transport Application: Heavy-Duty Trucks, Light Commercial Vehicles, Buses, Delivery Vehicles |
| Companies Covered | ABB Ltd., Siemens AG, Vishay Intertechnology, Inc., Murata Manufacturing Co., Ltd., Panasonic Corporation, TE Connectivity Ltd., Schneider Electric SE, TT Electronics, Ohmite Manufacturing Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Electric Vehicle Dynamic Braking Resistors Market Strategic Shifts
Component architectures are fragmenting between legacy passive designs and sensor-enabled intelligent systems. Three distinct trajectories now define competitive positioning in thermal management hardware.
Water-cooled resistor assemblies is overtaking air-cooled units in high-power bus applications where underfloor packaging constraints prevent adequate convection. European transit authorities specify liquid thermal management for continuous-duty routes exceeding 200kW regenerative loads. This shift compresses supplier margins on legacy air-cooled product lines while rewarding integrated cooling system expertise.
REACH substance restrictions on hexavalent chromium coatings are forcing substrate material substitutions across European supply chains. ECHA authorization requirements now cover resistor termination platings previously exempt under industrial equipment exemptions. German and French OEMs accelerate qualification of trivalent chromium and nickel-palladium alternatives ahead of 2026 sunset dates.
Fleet operators now unbundle resistor procurement from complete drive-train packages, sourcing direct from specialized thermal component vendors. Large North American logistics companies issue standalone technical specifications for braking resistors, bypassing traditional tier-one system integrators. This disintermediation concentrates in California and Texas markets where in-house engineering teams possess high-voltage integration capabilities.
Commercial Electric Vehicle Dynamic Braking Resistors Market Segmentation
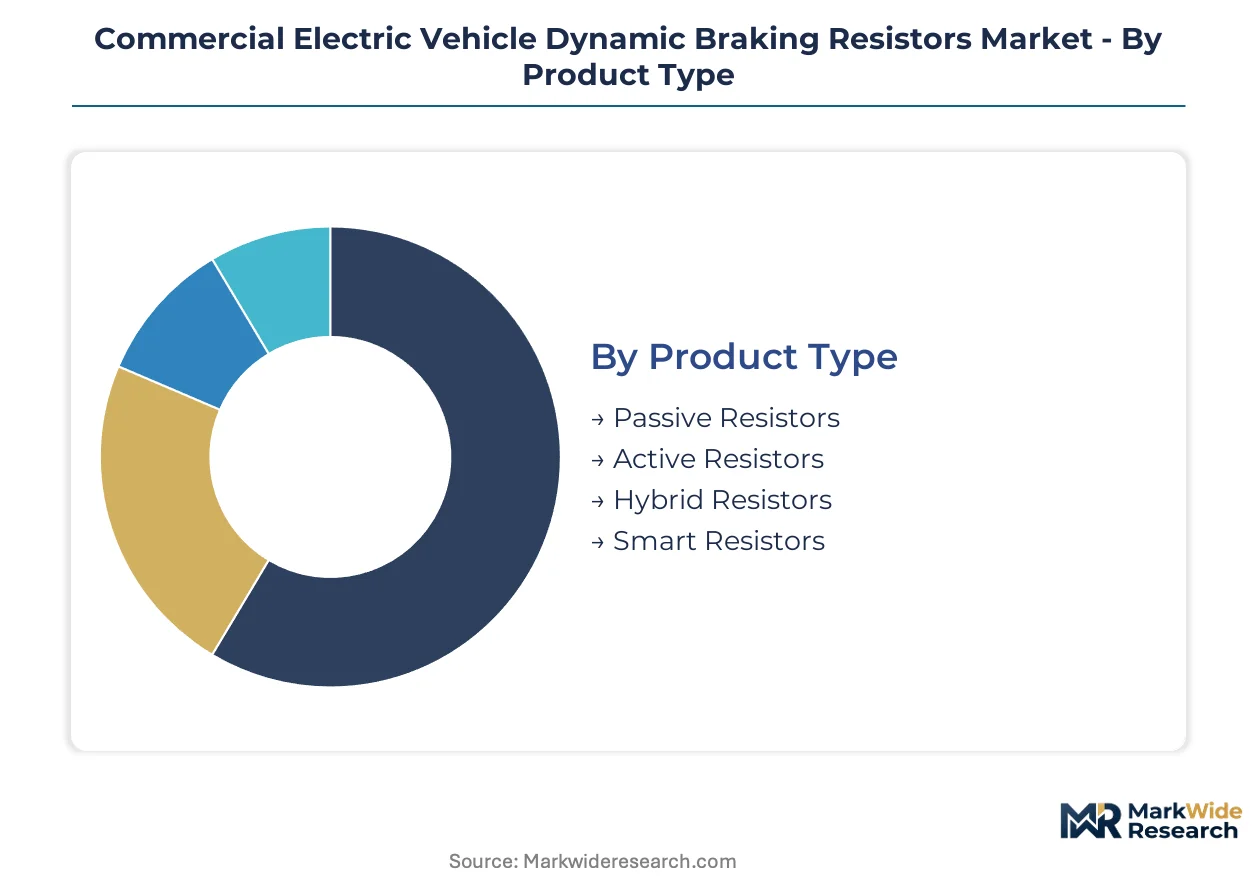
Segmentation in this market tracks how thermal management requirements diverge across vehicle electrification platforms. Certification burdens, cooling architectures, and procurement patterns create distinct commercial pockets with incompatible technical specifications.
Product Type:
NHTSA brake performance standards and IEC 60664 insulation coordination impose divergent validation timelines across resistor intelligence tiers, with passive designs clearing certification faster than sensor-enabled variants.
- Passive Resistors:Stainless steel or ceramic-composite elements without active monitoring circuitry. Fleet operators in Texas and California specify these for heavy-duty truck retrofits where cost simplicity outweighs predictive maintenance needs.
- Smart Resistors:Embedded thermal sensors enable real-time resistance monitoring and predictive failure alerts. Large North American logistics companies with in-house high-voltage engineering teams now unbundle these from complete drive-train packages.
- Active Resistors:Microcontroller-managed switching optimizes heat dissipation profiles dynamically.
- Hybrid Resistors:Combine passive thermal mass with limited active control for mid-tier commercial applications.
Passive Resistors sits at the top of the volume ranking, with Smart Resistors climbing the fastest.
Technology:
Cooling method selection tracks power density requirements and underfloor packaging constraints across commercial vehicle architectures.
- Water Cooled:Liquid thermal management enables continuous-duty operation above 200kW regenerative loads. European transit authorities specify these for low-floor bus architectures where air-cooled units face space constraints.
- Air Cooled:Passive convection through finned aluminum housings dominates heavy-duty truck installations. Space-constrained delivery vehicles cannot deploy these above 150kW braking loads without thermal derating.
- Liquid Cooled:Dielectric fluid circulation suits compact delivery vehicle packaging with moderate duty cycles.
- Oil Cooled:Mineral oil immersion provides electrical isolation in high-voltage rail and mining applications.
Air Cooled maintains the largest installed base, though Water Cooled is expanding most quickly in municipal bus procurement.
End User:
Procurement authority is shifting from tier-one system integrators toward specialized thermal component vendors as fleet engineering capabilities mature.
- Fleet Operators:Large logistics companies in California and Texas now issue standalone technical specifications for braking resistors, bypassing traditional OEM channels. These buyers prioritize predictive maintenance capabilities and total cost of ownership over upfront hardware pricing.
- OEMs:Commercial vehicle manufacturers integrate resistors into complete drive-train packages during platform development. EPA greenhouse gas regulations embed resistor performance into their architecture decisions.
- Aftermarket Providers:Service networks supply replacement units for out-of-warranty commercial EVs.
- Public Transport:Municipal transit agencies specify resistor-inverter bundles through centralized procurement programs.
OEMs retain the highest procurement volume, with Fleet Operators gaining share fastest through direct sourcing mandates.
Application:
Duty cycle intensity and stop-go frequency determine resistor thermal capacity requirements across commercial vehicle categories.
- Buses:Continuous regenerative braking on urban routes demands water-cooled resistors rated for 600°C-plus duty cycles. German federal and state transit programs favor suppliers offering complete drive-train resistor-inverter bundles.
- Heavy-Duty Trucks:Long-haul and regional delivery profiles require resistors handling intermittent high-load braking events. California's Advanced Clean Trucks regulation accelerates deployment of dynamic braking-equipped platforms in this category.
- Light Commercial Vehicles:Lower mass and regenerative energy volumes permit air-cooled resistor solutions.
- Delivery Vehicles:Compact packaging constraints favor liquid-cooled variants with space-efficient thermal management.
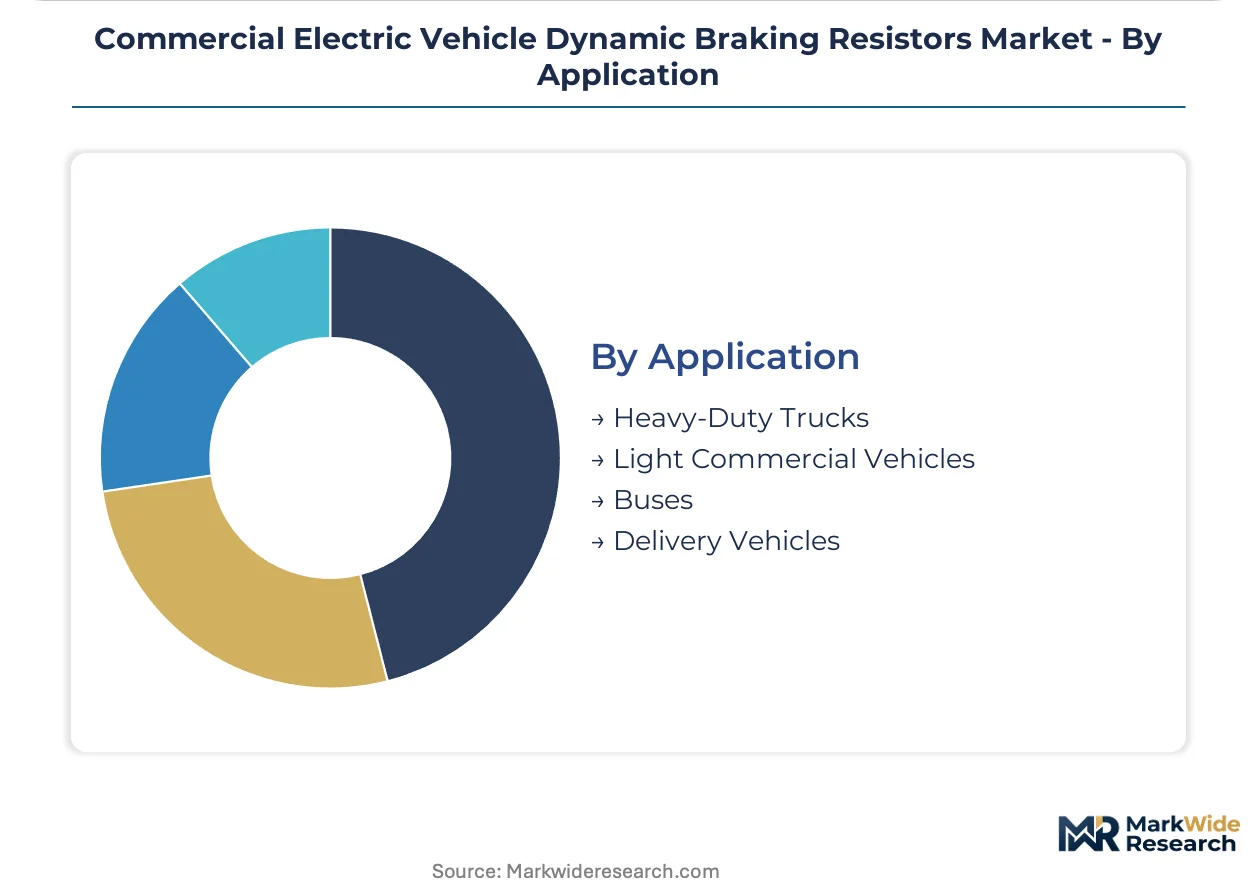
Heavy-Duty Trucks represents the largest addressable market, while Buses follows the steepest expansion trajectory driven by European electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between compliance-heavy European markets and cost-optimized Asian manufacturing zones is reshaping supplier location decisions. Chinese resistor fabricators capture volume through streamlined environmental clearances, while German and US producers defend premium positioning via NHTSA and KBA certification depth.
United States
California's Advanced Clean Trucks regulation and Texas fleet procurement mandates drive heavy-duty electric truck deployment. NHTSA Federal Motor Vehicle Safety Standards govern brake system performance thresholds, directly influencing resistor thermal capacity specifications. The Detroit-Warren automotive corridor anchors OEM integration facilities where ABB and Siemens maintain traction power engineering centers.
Germany
Federal and state transit procurement programs favor complete drive-train resistor-inverter bundles for municipal bus electrification. KBA type-approval requirements and REACH substance restrictions on hexavalent chromium coatings force substrate material substitutions. The Stuttgart engineering cluster concentrates smart resistor development for predictive maintenance integration.
China
Automotive-grade thick-film capacity concentrates in East Asian manufacturing zones serving domestic commercial EV production. MIIT new energy vehicle mandates and GB standards for braking performance create compliance pathways for local suppliers. The Yangtze River Delta hosts wirewound resistor fabricators recalibrating toward 600°C continuous-duty ceramic-composite designs.
Japan
METI carbon neutrality roadmaps accelerate commercial vehicle electrification timelines through 2030. JIS standards for high-voltage insulation coordination extend validation timelines for 800V platform components. The Nagoya-Chubu industrial belt maintains precision power resistor manufacturing for export-oriented tier-one suppliers.
India
FAME II subsidies and state-level electric bus procurement programs create demand for cost-optimized air-cooled resistor solutions. BIS certification requirements for automotive electrical components filter supplier qualification. The Tamil Nadu automotive cluster attracts wirewound resistor assembly operations targeting Southeast Asian export markets.
Commercial Electric Vehicle Dynamic Braking Resistors Market Competitive Environment
Chinese producers anchor the volume tier through thick-film and wirewound capacity concentration; European specialists hold premium positioning via integrated drive-train bundling. The vendor base splits between consolidated multinational electrical conglomerates and fragmented regional thermal component specialists. Three archetypes dominate: traction heritage players with rail-to-road technology transfer, precision resistor specialists with high-temperature material science, and diversified industrial electrical suppliers with inverter integration capabilities. Competitive moves concentrate on strategic partnerships for silicon carbide inverter co-development and geographic expansion through localized certification acquisition.
Within the traction heritage tier, ABB Ltd. and Siemens AG exemplify European producers leveraging rail electrification experience for commercial EV braking systems. Vishay Intertechnology, Inc. occupies a specialist position among precision power resistor fabricators targeting high-temperature commercial vehicle environments. These three companies represent distinct competitive vectors: integrated system bundling, component specialization, and material science depth.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| Vishay Intertechnology, Inc. |
| Murata Manufacturing Co., Ltd. |
| Panasonic Corporation |
| TE Connectivity Ltd. |
| Schneider Electric SE |
| TT Electronics |
| Ohmite Manufacturing Company |
| Others |
Value Chain & Pricing Dynamics
Captive integration into ceramic-composite substrate production anchors both supply security and pricing power for resistor manufacturers serving 600°C continuous-duty applications. German and Japanese producers defend premium positioning through in-house wirewound winding capabilities while Chinese competitors source nickel-chromium alloys through spot-market exposure.
Pricing Analysis
Distributor markups of 15-25% separate fleet-direct procurement from tier-one system integrator channels. Three-tier pricing structure across predictive-maintenance-enabled, standard passive, and retrofit economy levels tracks certification grade and thermal monitoring sophistication. Cost compression in economy-tier air-cooled units is intensifying because nickel-chromium alloy spot markets feed raw material volatility. Fleet operators with in-house high-voltage engineering teams exhibit lowest price sensitivity; aftermarket retrofit buyers face highest budget constraints.
Supply Chain Analysis
Skilled technician availability in Yangtze River Delta manufacturing zones underpins Chinese thick-film capacity expansion. Automotive-grade resistor supply concentrates in China, Germany, and Japan. Raw material flows draw from Indonesian nickel mining, South Korean precision alloy processing, and domestic Chinese ceramic substrate fabrication. Single-source vulnerability concentrates in East Asian thick-film winding equipment. Distribution runs through tier-one drive-train integrators, though direct fleet procurement is displacing traditional channels in California and Texas markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Fleet procurement mandates from California's Advanced Clean Trucks regulation are shifting demand toward predictive-maintenance-enabled smart resistors with embedded thermal monitoring.
For Market Incumbents: Anchor silicon carbide inverter co-development partnerships before switching-frequency standards crystallize. Invest in captive ceramic-composite substrate production to insulate against nickel-chromium alloy volatility. Defend against fleet disintermediation by embedding predictive maintenance software into resistor hardware bundles. For New Entrants and Emerging Players: Digital fleet-management platform partnerships offer channel access bypassing tier-one integrator lock-in. White-space concentrates in liquid-cooled compact packaging for delivery vehicles where space constraints block incumbent air-cooled solutions. Target Texas and Southeast Asian logistics operators with standalone technical specifications and rapid certification turnaround. For Investors and Strategic Acquirers: Roll-up economics work for precision power resistor specialists because OEM platform decisions embed multi-year resistor specifications with limited substitution risk. Five-to-ten year viability hinges on silicon carbide inverter penetration rates. Monitor NHTSA brake performance standard revisions as inflection signal for thermal capacity requirement shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Co-Development | Partnerships with ABB and Siemens anchor switching-frequency compatibility ahead of standardization. |
| Ceramic-Composite Substrate Backward Integration | In-house 600°C-rated material production insulates against nickel-chromium supply volatility. |
| Predictive Maintenance Software Embedding | Fleet operator retention depends on thermal monitoring data streams bundled with hardware. |
| California Direct Fleet Procurement | Advanced Clean Trucks mandates create channel access independent of tier-one integrators. |
| Water-Cooled Compact Packaging R&D | European low-floor bus specifications reward liquid thermal management expertise. |
Study Parameters
Direct dialogue with OEM platform engineers, tier-one procurement managers, fleet operations directors, and thermal component R&D heads grounded qualitative findings. Secondary validation drew from NHTSA Federal Motor Vehicle Safety Standards filings, EPA heavy-duty vehicle greenhouse gas rulemaking dockets, IHS Markit commercial vehicle production databases, and ECHA REACH substance restriction updates. Bottom-up resistor unit demand estimates triangulated against top-down commercial EV deployment projections.
Bottom-up modeling segmented demand across passive, smart, active, and hybrid resistor intelligence tiers; water, air, liquid, and oil cooling technologies; and bus, heavy-duty truck, light commercial, and delivery vehicle applications. CAGRs derived from installation rate assumptions tied to silicon carbide inverter penetration and fleet electrification mandate compliance timelines. Forecast inputs included California Advanced Clean Trucks phase-in schedules and German federal transit procurement program specifications.
The model assumes a particular technology adoption path; alternative pathways for silicon carbide inverter switching frequencies would alter resistor duty cycle and thermal management architecture requirements. Forecasts reflect assumptions regarding NHTSA brake performance standard stability, nickel-chromium alloy price bands, and REACH substance restriction enforcement timelines. Material deviation in EPA regulatory stringency or Chinese thick-film capacity expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Global Industrial Electric Vehicle Market
Electric Vehicles
EV Platform Market
Electric Vehicles
Global Electric Scooters Market
Electric Vehicles
North America Automotive High Performance Electric Vehicle Market
Electric Vehicles
Electric Commercial Vehicle Market
Electric Vehicles
Electromagnetic and Radio Frequency Interference Coating for Electric Vehicles Market
Electric Vehicles
Electric Vehicle E-Axle Market
Electric Vehicles
Mexico Automotive Electric Bus Market
Electric Vehicles
Denmark Solar E-Bike Market
Electric Vehicles
Electric Unicycle Market
Electric Vehicles
Commercial Vehicle Traction Battery Systems Market
Electric Vehicles
Canada Solar E-Bike Market
Electric Vehicles
Global Electric Classic Car Market
Electric Vehicles
Germany Electric Bus Battery Pack Market
Electric Vehicles
Vehicle-To-Grid (V2G) Market
Electric Vehicles
Norway E-Bike Market