
 Norway Electric Cars Market | 2026-2036
Norway Electric Cars Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Electric Cars Market Analytics
The price-performance gap between premium long-range electric vehicles and entry-level commuter models is hardening as battery cost curves diverge by chemistry and scale. Tesla sustains technology leadership through proprietary charging networks and over-the-air software architecture. Volkswagen anchors mass-market volume with its ID platform and localized Scandinavian distribution. BYD competes aggressively on lithium iron phosphate cost structures and vertical battery production.
Norway electric cars are road vehicles propelled by electric motors drawing energy from rechargeable battery packs or fuel cells, with battery electric variants typically achieving 300-600 kilometers per charge depending on cell chemistry and thermal management architecture. Their primary purpose is to displace internal combustion transport while aligning with national decarbonization commitments. Battery Electric Vehicle configurations command the dominant share of new registrations as Norwegian policy tilts subsidy structures away from plug-in hybrid alternatives. Fast Chargers within the charging infrastructure segment attract disproportionate capital deployment as highway corridor completion becomes a competitive differentiator for automakers.
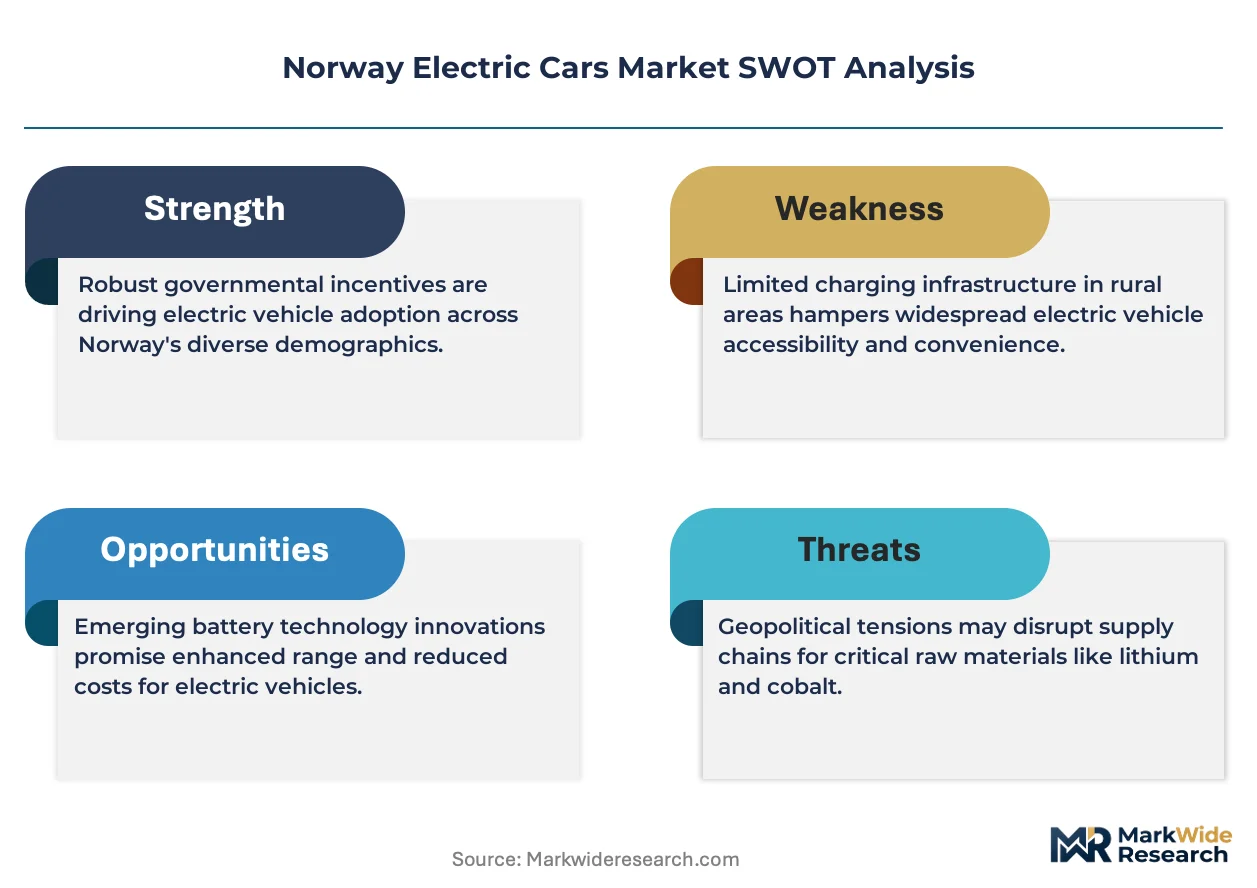
The Norwegian government, through its zero-emission vehicle mandate and ongoing tax exemption framework, shapes demand by maintaining purchase-price parity between electric and conventional vehicles. The country's national transport regulator enforces safety and homologation standards that exceed baseline UN ECE requirements for battery thermal runaway protection. Stakeholders must monitor whether Oslo adjusts its CO2-based vehicle taxation ladder to accelerate phase-out thresholds for remaining combustion sales.
Market Dynamics
Norway's zero-emission vehicle mandate and the removal of VAT exemptions for heavier plug-in hybrids are redirecting buyer preference toward pure battery electric platforms. Commercial fleets in Oslo and Bergen are accelerating procurement of battery electric vehicles as fleet operators target total cost of ownership reductions.
Growth Catalysts
- Zero-Emission Vehicle Mandate:The Norwegian government's zero-emission vehicle mandate maintains purchase-price parity between electric and conventional vehicles, eliminating upfront cost barriers for consumers and fleet operators.
- Fast Charging Infrastructure:Highway corridor completion along the E6 and E39 routes is attracting disproportionate capital deployment, reducing range anxiety and enabling inter-city electric mobility.
- Lithium Iron Phosphate Chemistry:Cost structures for lithium iron phosphate battery packs are compressing entry-level price points, expanding addressable demand beyond premium segments.
Market Restraints
- Grid Capacity Constraints:Rural electrification infrastructure in northern Norway lacks the transformer capacity to support simultaneous fast charging at scale, limiting deployment outside Oslo-Bergen corridors.
- Battery Mineral Concentration:Cathode active material supply concentrates among a limited set of Asian chemical processors, exposing Norwegian importers to input cost volatility and supply disruption risk.
- Thermal Runaway Standards:The national transport regulator enforces battery thermal runaway protection standards that exceed baseline UN ECE requirements, extending homologation timelines for new vehicle introductions.
Strategic Opportunities
- Commercial Fleet Electrification:Municipal procurement frameworks in Trondheim and Stavanger are opening dedicated tender channels for electric light commercial vehicles and refuse collection trucks.
- Vehicle-to-Grid Integration:Bidirectional charging protocols are converging with home energy management systems, creating new revenue streams for residential battery electric vehicle owners through grid services.
- CO2 Taxation Ladder Adjustment:Potential Oslo policy revisions to accelerate phase-out thresholds for remaining combustion sales would compress the residual internal combustion vehicle market.
Industry Challenges
- High-Voltage Technician Scarcity:Certified repair capacity for battery pack diagnostics and thermal management system maintenance lags behind vehicle stock growth, extending service wait times.
- Legacy Parking Infrastructure:Multi-unit residential buildings constructed before 2010 lack electrical capacity for resident charging, requiring expensive retrofitting of distribution panels and cabling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Electric Cars Market |
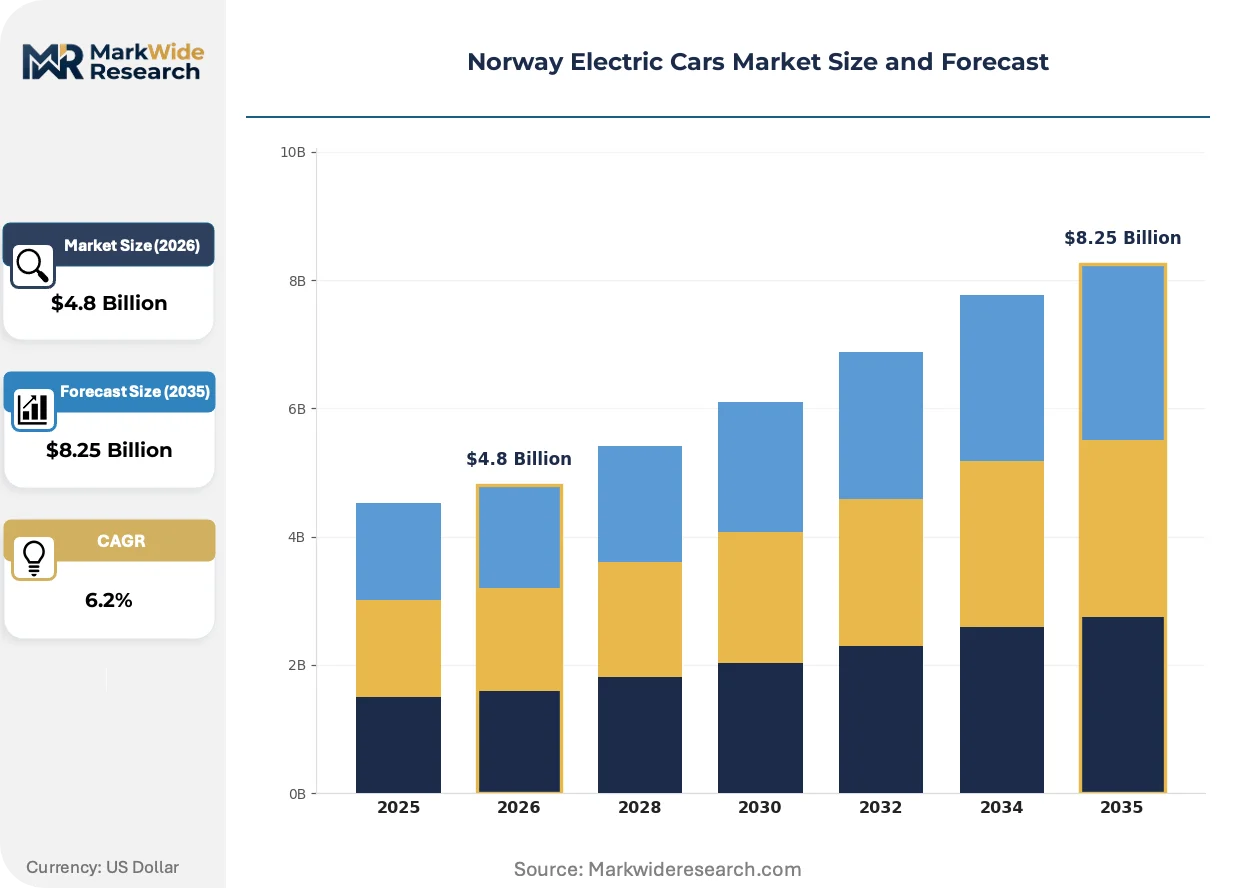
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Battery Electric Vehicle, Plug-in Hybrid Electric Vehicle, Fuel Cell Electric Vehicle, Others Charging Infrastructure: Home Charging Stations, Public Charging Stations, Fast Chargers, Superchargers Market Segment: Residential Users, Commercial Fleets, Government Agencies, Ride-Sharing Services Battery Technology: Lithium-ion, Solid State, Nickel-Metal Hydride, Lead Acid |
| Companies Covered | Volvo, Nissan, Tesla, BYD, Hyundai, Volkswagen, Škoda, Olavs Cars, Toyota, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Electric Cars Market Evolving Landscape
Battery chemistry diversification and charging infrastructure densification are actively reshaping competitive positioning in the Norwegian electric vehicle market. Technology trajectories are diverging by use case and price tier.
Silicon-anode battery formulations are expanding into long-range premium vehicle segments. These chemistries increase volumetric energy density by 20-40 percent over conventional graphite anodes. Premium buyers in the Oslo metropolitan corridor are adopting silicon-anode equipped vehicles at accelerated rates. The technology is expanding into fleet procurement specifications as operators prioritize maximum range per charging event.
The removal of VAT exemptions for heavier plug-in hybrids is compressing demand for dual-powertrain vehicles. This regulatory revision redirects subsidy flows toward pure battery electric platforms exclusively. Light commercial vehicle segments are most affected, with delivery van operators abandoning plug-in hybrid configurations for full battery electric alternatives.
Fleet procurement departments are consolidating vehicle sourcing through centralized tender platforms rather than decentralized dealer negotiations. This buying-pattern change is disintermediating traditional retail channels and compressing transaction margins. The shift is most visible among municipal and logistics operators in Bergen and Trondheim, where total cost of ownership calculations dominate selection criteria.
Norway Electric Cars Market Segmentation
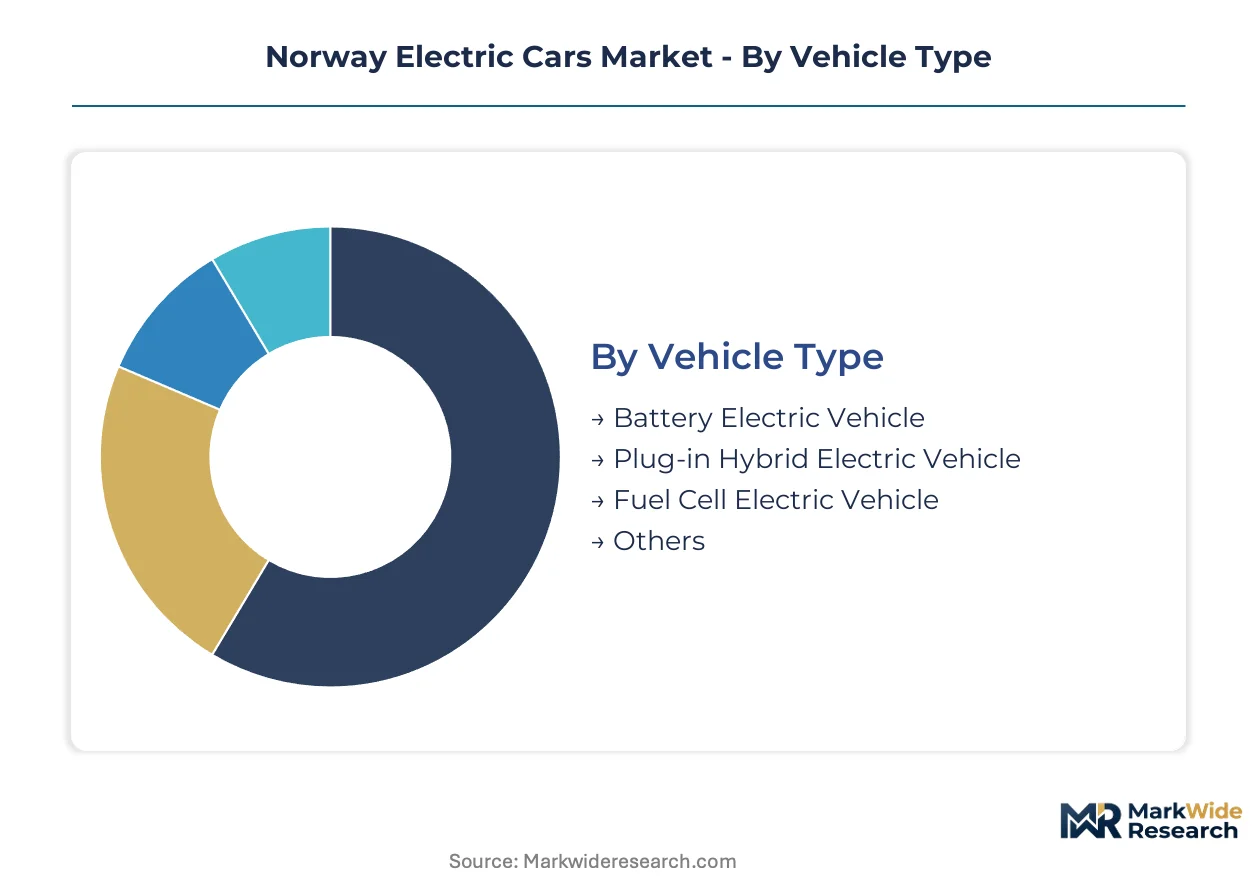
Norway's electric vehicle market segments reflect distinct procurement patterns shaped by Oslo's zero-emission mandate and the country's charging infrastructure geography. Fleet operators, residential buyers, and government agencies each prioritize different performance thresholds and ownership cost structures when selecting electrified platforms.
Vehicle Type:
Purchase subsidies and tax treatment differentiate buyer preference across electrified powertrain architectures in Norwegian cities.
- Battery Electric Vehicle:Pure-electric platforms utilizing lithium-ion or emerging solid-state chemistries achieve 300-600 kilometer ranges per charge. Demand concentrates among Oslo metropolitan commuters and Bergen logistics fleets seeking total cost of ownership advantages under Norway's VAT exemption framework. The Norwegian government's removal of plug-in hybrid incentives for heavier vehicle classes accelerates fleet migration toward this segment.
- Plug-in Hybrid Electric Vehicle:Dual-powertrain configurations combining internal combustion engines with electric motors are losing subsidy eligibility for commercial applications above weight thresholds. Operators in Trondheim and Stavanger are retiring plug-in hybrid vans from delivery specifications ahead of regulatory phase-out timelines.
- Fuel Cell Electric Vehicle:Hydrogen fuel cell platforms serve specialized heavy-duty applications in northern corridor logistics where battery weight penalties limit payload capacity.
- Others:Emerging electrified architectures including range-extended electric vehicles and solar-assisted prototypes occupy experimental niches in research procurement channels.
Battery Electric Vehicle leads volumes today; Fuel Cell Electric Vehicle is gaining share fastest in heavy-duty corridors.
Charging Infrastructure:
Deployment density and capital intensity separate charging modalities across Norway's urban-rural geography.
- Home Charging Stations:Residential wallbox installations at single-family dwellings and townhouses provide overnight charging at 3.7-22 kilowatt rates. Deployment concentrates in Oslo's detached housing stock and Bergen suburbs where electrical panel capacity supports dedicated circuits. Retrofitting costs in pre-2010 multi-unit buildings constrain penetration in dense urban districts.
- Fast Chargers:Direct current rapid charging stations delivering 50-350 kilowatts enable highway corridor completion along the E6 and E39 routes. Automakers and infrastructure consortia prioritize these installations to reduce inter-city range anxiety and differentiate brand ecosystems.
- Public Charging Stations:Alternating current destination chargers at retail and workplace locations serve dwell-time charging needs in municipal parking structures.
- Superchargers:Proprietary high-speed networks operated by individual manufacturers lock in brand loyalty through exclusive access protocols.
Home Charging Stations lead volumes today; Fast Chargers are expanding most quickly along highway corridors.
Market Segment:
Procurement centralization and subsidy eligibility distinguish customer categories in Norwegian electrification policy.
- Commercial Fleets:Centralized tender platforms in Oslo and Bergen aggregate demand from logistics operators, municipal services, and delivery networks. Total cost of ownership calculations dominate selection criteria as fleet managers target maintenance and fuel savings against higher upfront capital requirements.
- Residential Users:Individual households in the greater Oslo metropolitan corridor purchase battery electric vehicles through dealer networks and direct manufacturer channels. Charging density and parking infrastructure availability determine purchase feasibility in apartment-dominant districts.
- Government Agencies:Municipal and national procurement frameworks mandate zero-emission vehicle shares in public fleets, with Trondheim and Stavanger opening dedicated tender channels for electric light commercial vehicles.
- Ride-Sharing Services:Mobility platform operators deploy battery electric vehicles to align with Oslo's congestion charging exemptions and brand positioning requirements.
Commercial Fleets lead volumes today; Government Agencies are climbing the fastest on mandated procurement quotas.
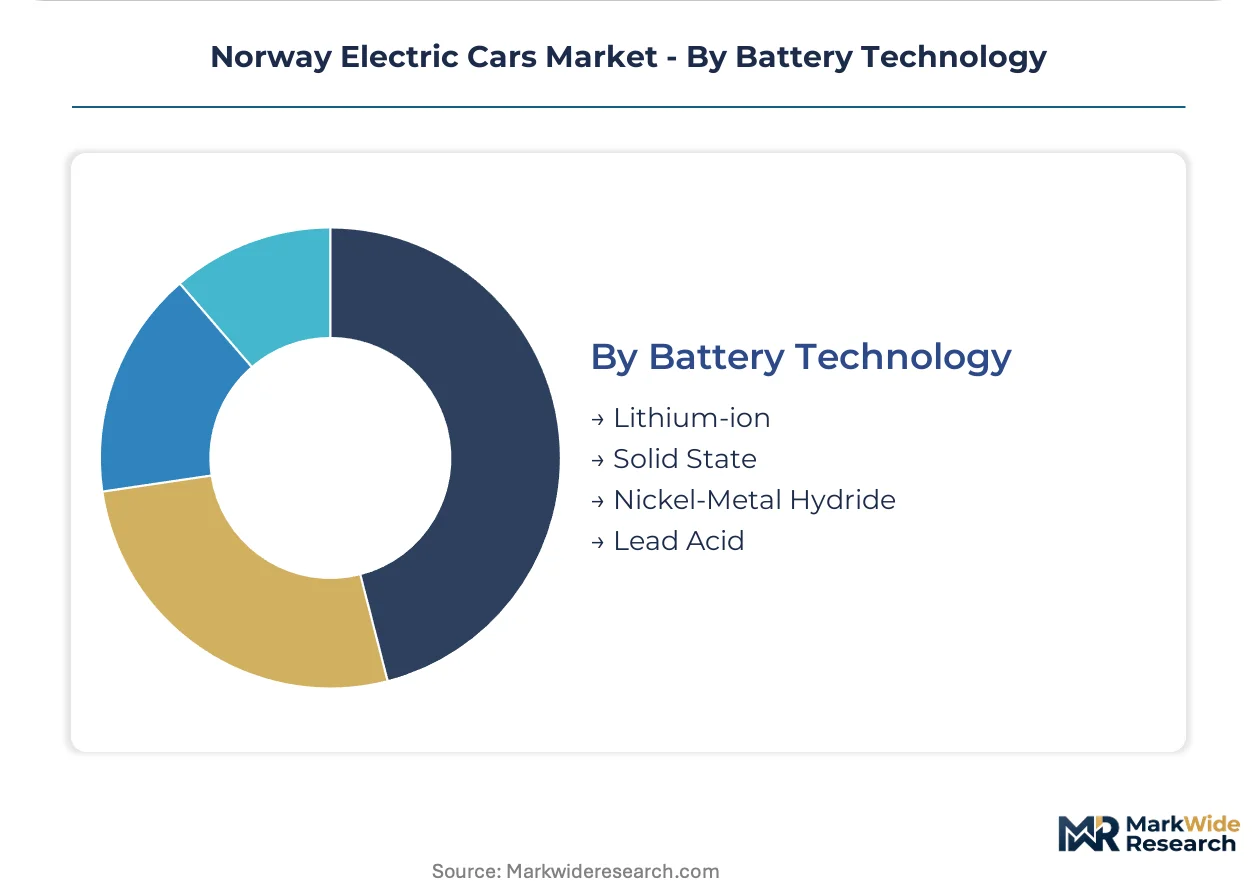
Battery Technology:
Cost structures and energy density specifications segment cell chemistry selection across price tiers and range requirements.
- Lithium-ion:NMC and LFP cathode formulations dominate current production with established supply chains from Asian chemical processors. Norwegian importers face input cost volatility from concentrated cathode active material sourcing.
- Solid State:Emerging ceramic or polymer electrolyte architectures promise 20-40 percent volumetric energy density improvements over liquid-electrolyte alternatives. Premium buyers in Oslo are adopting early silicon-anode equipped vehicles as the technology transitions toward fleet specifications.
- Nickel-Metal Hydride:Legacy chemistry persists in hybrid auxiliary applications with limited relevance to Norwegian pure-electric mandates.
- Lead Acid:Conventional chemistry serves low-voltage auxiliary systems and starter functions in specialized vehicle categories.
Lithium-ion leads volumes today; Solid State is advancing most rapidly in premium segment procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Oslo's dense concentration of electrical engineers and charging infrastructure specialists anchors Norway's electric vehicle workforce. Bergen and Trondheim clusters support secondary demand centers with technical talent pools in battery diagnostics and fleet management systems.
Oslo Metropolitan Corridor
Corporate fleet procurement and residential commuter demand concentrate in Greater Oslo, where charging density exceeds 150 fast chargers per 100,000 residents. The national transport regulator enforces battery thermal runaway protection standards that exceed baseline UN ECE requirements, extending homologation timelines for new vehicle introductions. Tesla and Volkswagen maintain flagship retail presence in Oslo's Fornebu district, competing for premium buyer segments.
Bergen
Logistics operators and maritime-adjacent industries drive commercial fleet electrification in Norway's second city. Municipal procurement frameworks mandate zero-emission vehicle shares in public fleets, with dedicated tender channels opening for electric light commercial vehicles. BYD and Hyundai anchor distribution partnerships through regional dealer networks serving western Norway's island and fjord logistics corridors.
Trondheim
Academic research institutions and public sector agencies generate institutional demand for battery electric vehicles in central Norway. The Norwegian government's zero-emission vehicle mandate maintains purchase-price parity between electric and conventional vehicles, eliminating upfront cost barriers for university and hospital procurement departments. Škoda and Volkswagen compete for municipal fleet contracts through centralized tender platforms.
Stavanger
Energy sector professionals and offshore industry suppliers create distinctive demand profiles in Norway's oil capital. Removal of VAT exemptions for heavier plug-in hybrids redirects subsidy flows toward pure battery electric platforms exclusively for commercial applications. Nissan and Toyota maintain service infrastructure supporting the region's transition from petroleum-sector fleet vehicles.
Tromsø and Northern Norway
Arctic climate conditions and sparse population density constrain electric vehicle penetration in Norway's northernmost regions. Rural electrification infrastructure lacks transformer capacity to support simultaneous fast charging at scale, limiting deployment outside Oslo-Bergen corridors. Volvo and Hyundai prioritize cold-weather battery thermal management systems for limited fleet trials in polar logistics applications.
Norway Electric Cars Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Norway's electric vehicle market structure. Integrated automakers with captive battery supply chains and proprietary charging networks battle specialized importers relying on third-party infrastructure partnerships. Three archetypes dominate: vertically integrated global OEMs, Asia-based cost leaders, and regional distribution specialists. Competitive moves center on highway corridor charging exclusivity deals and fleet procurement platform consolidation.
Among vertically integrated global OEMs, Tesla and Volkswagen occupy positions exemplifying contrasting ecosystem strategies. Tesla anchors premium segments through proprietary Supercharger access and over-the-air software architecture. Volkswagen represents mass-market volume deployment through scalable platform engineering and localized Scandinavian distribution networks. BYD sits within the Asia-based cost leader archetype, competing on lithium iron phosphate battery economics and upstream cell production control.
| Leading Market Players |
|---|
| Volvo |
| Nissan |
| Tesla |
| BYD |
| Hyundai |
| Volkswagen |
| Škoda |
| Olavs Cars |
| Toyota |
| Others |
Value Network & Pricing Analysis
Silicon-anode premium tiers diverge sharply from lithium iron phosphate entry segments across Norway's electric vehicle market, with battery chemistry cost curves dictating both sticker price spreads and upstream procurement configurations. Oslo fleet operators absorb silicon-anode premiums for maximum range density, while Bergen municipal buyers prioritize LFP cost structures in centralized tenders, compressing supplier margins at the chemistry source.
Pricing Analysis
Vehicle-to-service bundling splits the Norwegian market between hardware-only transactions and subscription-inclusive packages. Three-tier pricing structure across premium long-range, standard commuter, and economy urban segments reflects battery energy density and charging speed capabilities. Cost compression in economy tiers intensifies as BYD's LFP vertical control feeds aggressive fleet pricing. Government agencies exhibit lowest price sensitivity through mandated procurement quotas, while residential apartment buyers face highest sensitivity due to retrofitting cost burdens.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale fleet demand from Oslo and Bergen municipal aggregators, bypassing traditional dealer markups. Cathode active material production concentrates in China, South Korea, and Japan, with Norwegian importers drawing from concentrated Asian chemical processors. Lithium carbonate, nickel sulfate, and cobalt hydroxide constitute critical input dependencies. Single-source vulnerability in cathode precursor supply exposes distributors to disruption risk. Distribution runs through manufacturer-owned retail in premium segments and centralized tender platforms in commercial procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Norway's electric vehicle market compounds steadily through policy-backed demand visibility, with Oslo's zero-emission mandate creating predictable procurement pipelines across fleet and residential segments.
For Market Incumbents: To counter BYD's lithium iron phosphate cost aggression, Volkswagen and Tesla should deepen captive battery supply through Nordic logistics hub investments. Securing exclusive fast charger corridor rights along E39 routes locks in fleet customer retention against emerging Asia-based cost leaders. For New Entrants: Launch via centralized municipal tender platforms in Trondheim and Stavanger where procurement centralization has disintermediated traditional retail channels. Northern Norway's grid-constrained corridors present white-space opportunity for cold-weather thermal management specialists. Bidirectional charging integration with residential energy management systems offers differentiated entry angle against hardware-only competitors. For Investors and Strategic Acquirers: Consolidation pressure builds where certified high-voltage technician capacity lags vehicle stock growth, extending service wait times and eroding brand equity. Long-term viability favors asset-light software-defined vehicle platforms with over-the-air update architectures over capital-heavy manufacturing footprints. Monitor Oslo's CO2 taxation ladder adjustments as policy inflection signal for residual combustion market compression.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | LFP cell offtake from Chinese producers secures cost position for Bergen fleet tenders. |
| Charging Infrastructure Partnership | E39 highway corridor exclusivity reduces range anxiety for inter-city logistics operators. |
| Software-Defined Vehicle Investment | Over-the-air thermal management updates extend battery life in Tromsø Arctic conditions. |
| Platform Standardization | Modular skateboard architectures reduce homologation timelines under Norway's UN ECE-plus standards. |
| Geographic Manufacturing Footprint | Nordic battery assembly presence mitigates cathode material supply concentration risk. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with OEM platform engineers, Tier 1 supplier procurement leads, municipal fleet managers, and charging infrastructure operators with secondary validation. Vehicle registration databases, national transport regulator homologation filings, and customs import records provided triangulation anchors. Bottom-up fleet procurement aggregation and top-down macro demand modeling converged on segment-level outputs.
Comparable historical periods anchored the projection horizon to observed adoption curve inflections across the analysis window. Segmentation modeling spanned vehicle class, propulsion architecture, battery chemistry tier, and regional charging density. CAGRs derived from logistic diffusion curves fitted to policy mandate timelines and infrastructure deployment schedules. Battery cost curve assumptions and grid capacity expansion trajectories fed scenario-specific forecast pathways.
Forecast precision tightens around the base case; tail outcomes carry wider variance under grid infrastructure delay scenarios or cathode material supply disruption. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Car Battery Chargers Market
Electric Vehicles
Electric Bus Market
Electric Vehicles
Vehicle Electrification Market
Electric Vehicles
United States Electric Car Market
Electric Vehicles
Electric Vehicle Ambient Lighting Market
Electric Vehicles
Asia-Pacific Train Battery Market
Electric Vehicles
BEV Electric Drive Unit Market
Electric Vehicles
North America Electric Vehicle Thermal Management System Market
Electric Vehicles
Hybrid EV Conversion Kit Market
Electric Vehicles
China Automotive High Performance Electric Vehicle Market
Electric Vehicles
Japan Solar E-Bike Market
Electric Vehicles
Electric Loader Rickshaw Market
Electric Vehicles
Battery-Only Electric Bus Market
Electric Vehicles
Right Hand Drive Electric Vehicle Market
Electric Vehicles
E-SUV Market
Electric Vehicles
Automotive Intelligent Battery Sensor Market