
 Indian E-Bike Rental Market | 2026-2036
Indian E-Bike Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Indian E-Bike Rental Market Foresight
FAME-II is decoupling capital expenditure from fleet viability for new entrants. Yulu Bikes Pvt Ltd leverages its battery-swapping infrastructure to sustain density in Bengaluru and Delhi. Zypp Electric anchors B2B logistics rentals, competing with eBikeGo Pvt Ltd for corporate employee commute contracts. ONN Bikes differentiates through franchise-operated neighborhood depots, controlling last-mile availability.
An Indian e-bike rental denotes a short-term electric two-wheeler access service, typically deploying lithium-ion powered scooters with 25-45 kmph regulated top speeds and swappable battery architectures for continuous urban circulation. Personal Rentals dominate transaction volume, while Corporate Rentals command longer contract tenures and higher per-unit utilization. Subscription Services represent the fastest-growing payment-adjacent segment, as wallet-integrated recurring billing reduces friction for daily commuters.
The Ministry of Road Transport and Highways, state-level EV policies under the BIS framework, and city-specific RTO registration waivers collectively shape fleet compliance costs and parking access privileges. The central bank's green lending guidelines and SEBI-aligned ESG disclosure requirements for fleet investors are redirecting institutional capital toward asset-light rental operators. Stakeholders must monitor how state electricity regulators treat commercial swapping-station tariffs versus residential rates, as this spread determines network profitability.
Market Dynamics
FAME-II subsidy extensions are decoupling capital expenditure from fleet viability for new entrants, while state-level EV policies under BIS framework reshape procurement economics across metropolitan corridors.
Growth Catalysts
- Metro Rail Integration:Daily commuters in Bengaluru and Delhi are adopting fleet-based electric two-wheelers for last-mile connectivity, creating multimodal rental uptake in tier-one metropolitan corridors.
- Battery Swapping Infrastructure:Swappable battery architectures enable continuous urban circulation by eliminating charging downtime, allowing operators to sustain fleet density through rapid energy replenishment.
- State-Level RTO Waivers:City-specific registration exemptions reduce compliance costs and accelerate fleet deployment timelines for rental operators in Maharashtra, Karnataka, and Delhi.
Market Restraints
- Lithium-Ion Cell Import Concentration:Domestic battery pack assembly relies on imported cells, exposing operators to currency volatility and supply disruption risks from East Asian suppliers.
- Commercial Tariff Disparity:State electricity regulators treat swapping-station tariffs at commercial rates rather than residential, compressing network profitability margins for battery infrastructure operators.
- 25-45 Kmph Speed Regulation:BIS-mandated top-speed caps limit service differentiation and extend trip durations, reducing per-vehicle revenue generation potential during peak hours.
Strategic Opportunities
- Tier-Two City Expansion:Underpenetrated markets in Pune, Hyderabad, and Chennai offer density advantages with lower station deployment costs and reduced competitive congestion.
- Corporate Subscription Contracts:B2B logistics rentals and employee commute packages command longer tenures and higher per-unit utilization than consumer walk-in transactions.
- Wallet-Integrated Recurring Billing:Subscription Services represent emerging payment-adjacent growth as UPI-linked auto-debit reduces friction for daily commuters.
Industry Challenges
- Station Siting and Permitting:Municipal parking access privileges vary by city corporation, creating uneven deployment timelines and localized operational bottlenecks.
- Skilled Technician Scarcity:Battery diagnostics and thermal management expertise remains concentrated among OEM-trained personnel, inflating maintenance labor costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indian E-Bike Rental Market |
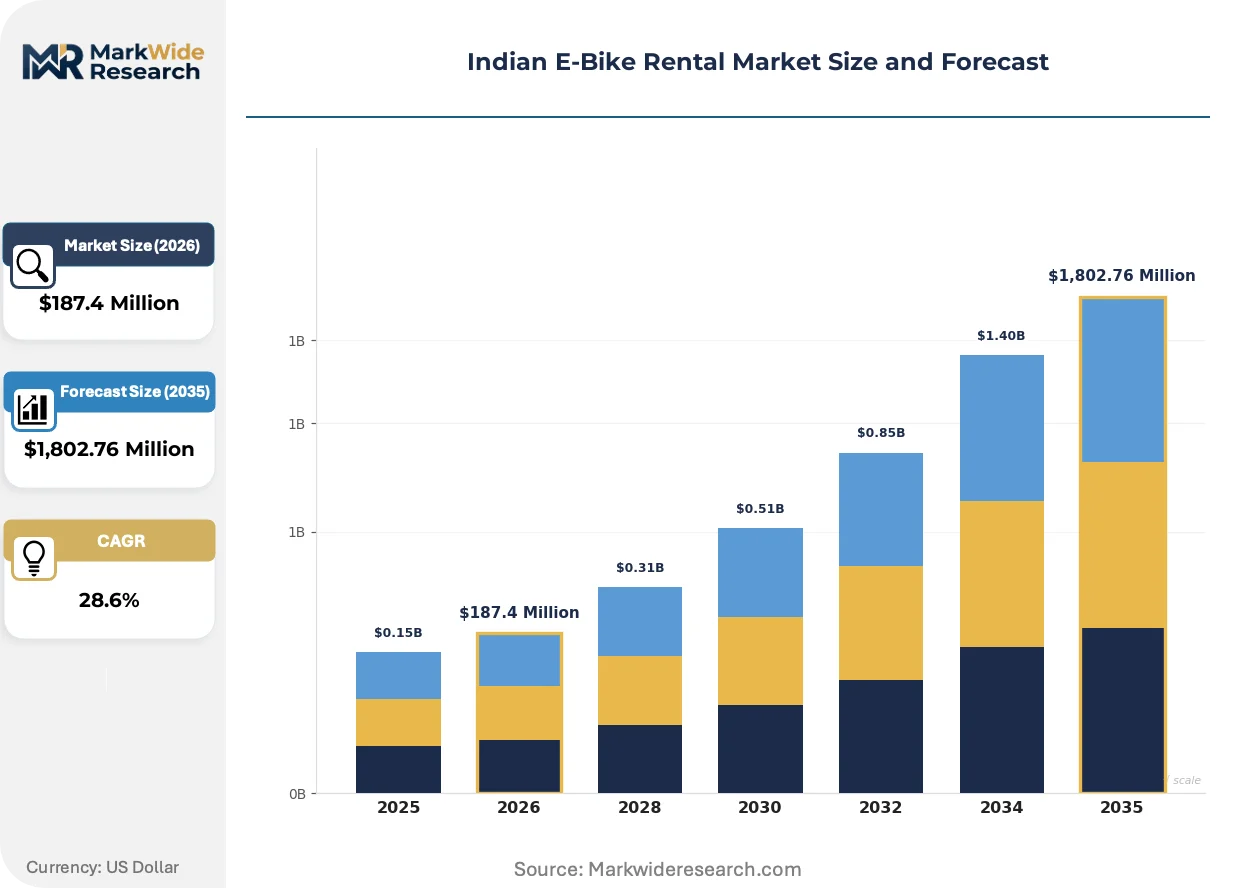
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Personal Rentals, Corporate Rentals, Subscription Services, Tour Packages Customer Type: Tourists, Daily Commuters, Students, Corporate Employees Charging Infrastructure: Public Charging Stations, Home Charging Solutions, Partnership Networks, Mobile Charging Payment Model: Pay-Per-Ride, Subscription Plans, Corporate Pricing, Wallet Integration |
| Companies Covered | Vogo Rental, Rentrip Services Pvt Ltd, Yulu Bikes Pvt Ltd, EXA Mobility EXA RIDE, ONN Bikes, Bounce Infinity, eBikeGo Pvt Ltd, Voltium, Zypp Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indian E-Bike Rental Market Shifts & Advancements
Technology convergence and policy calibration are compressing deployment cycles while reshaping how operators monetize vehicle access and energy infrastructure.
Internet-of-Things telematics is integrating real-time vehicle health monitoring with predictive maintenance scheduling. Fleet managers in corporate rental segments are adopting these systems to minimize downtime and optimize asset rotation. This convergence is integrating operational data streams with subscription billing platforms, enabling usage-based pricing models.
SEBI-aligned ESG disclosure requirements for fleet investors are redirecting institutional capital toward asset-light rental operators. The central bank's green lending guidelines amplify this shift by preferentially pricing debt for operators with documented carbon displacement metrics. Asset-heavy ownership models face higher cost-of-capital pressures, accelerating franchise and lease-based expansion strategies.
Last-mile connectivity preferences are rotating from ownership toward access-based models among urban professionals. Metro-adjacent residential clusters in Delhi NCR and Bengaluru are displacing private two-wheeler purchases with daily rental subscriptions. This behavioral pivot concentrates demand around transit interchanges, intensifying station location competition among operators.
Indian E-Bike Rental Market Segmentation
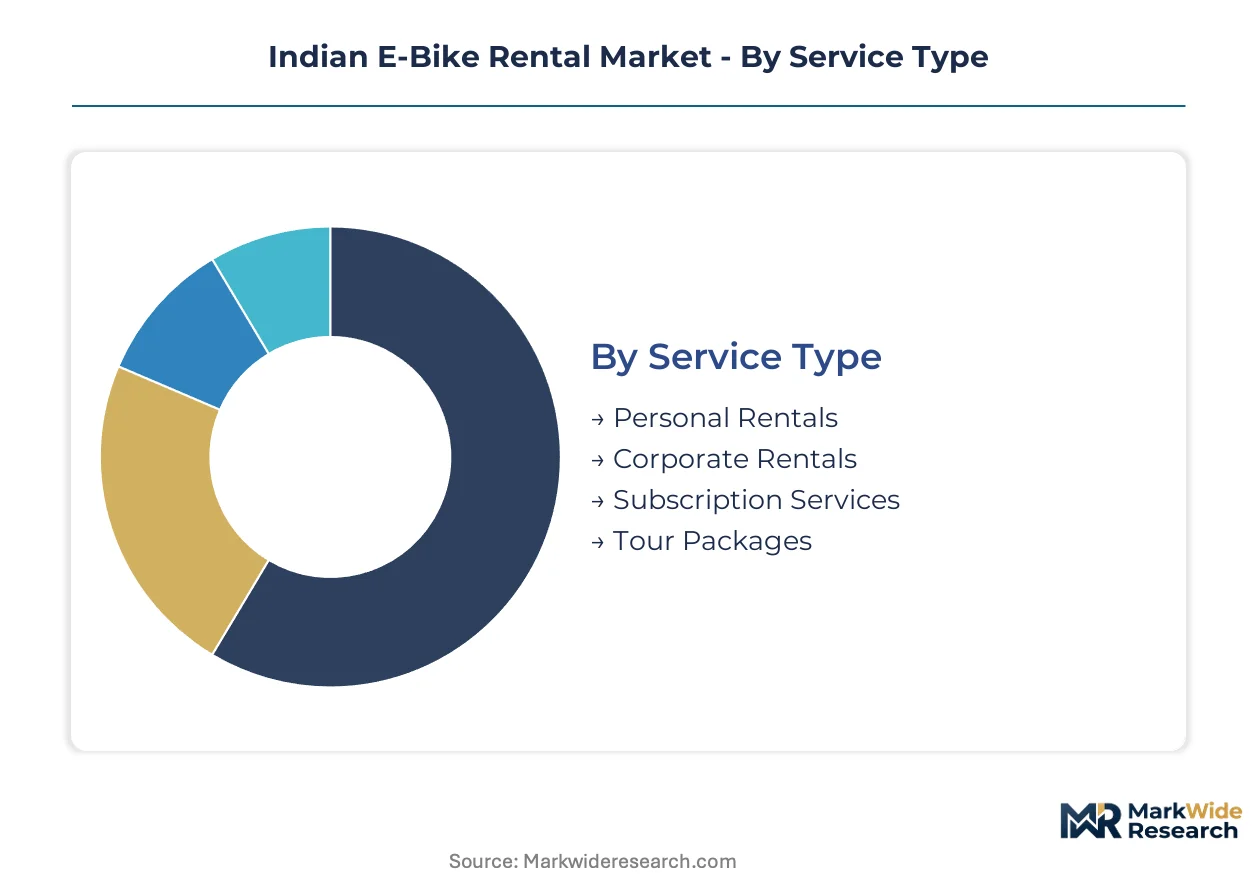
Segmentation in the Indian e-bike rental market reveals how distinct user behaviors, infrastructure access patterns, and payment preferences create divergent operational economics for fleet operators. Understanding these divides allows providers to calibrate vehicle specifications, station density, and pricing mechanics to specific demand pockets.
Service Type:
Usage duration and contract structure separate these segments, with implications for fleet rotation schedules and revenue predictability.
- Personal Rentals:Short-term, walk-in transactions for individual mobility needs, typically utilizing 25-45 kmph scooters with swappable batteries for immediate turnaround. Demand clusters around metro interchanges in Bengaluru and Delhi where last-mile gaps persist.
- Corporate Rentals:B2B contracts covering employee commute fleets or logistics operations, commanding longer tenures and higher per-vehicle utilization rates than consumer segments. These arrangements anchor revenue stability for operators like Zypp Electric.
- Subscription Services:Wallet-integrated recurring billing models reducing payment friction for daily commuters through UPI-linked auto-debit structures.
- Tour Packages:Curated rental experiences targeting leisure travelers with bundled route guidance and extended battery range allocations.
Volume sits with Personal Rentals; growth tilts toward Subscription Services.
Customer Type:
Mobility frequency and price sensitivity create four distinct profiles with varying tolerance for asset availability and service reliability.
- Daily Commuters:Recurrent users prioritizing station proximity and predictable availability over unit aesthetics, driving demand concentration along metro rail corridors in tier-one cities.
- Tourists:Episodic demand with higher per-ride willingness to pay, concentrated in heritage districts and leisure clusters where conventional transit coverage remains thin.
- Corporate Employees:Contract-embedded users with employer-subsidized access, generating steadier weekday utilization than discretionary renters.
- Students:Price-elastic segment gravitating toward campus-adjacent depots and discounted semester passes.
Corporate Employees deliver utilization density; Daily Commuters are expanding most quickly as metro networks extend.
Charging Infrastructure:
Capital deployment intensity and operational control levels distinguish how operators solve the energy replenishment challenge.
- Public Charging Stations:Grid-tied fixed infrastructure requiring municipal permits and commercial electricity tariffs, creating margin pressure where regulators classify swapping stations under commercial rather than residential rate schedules.
- Battery Swapping Networks:Modular exchange systems enabling continuous fleet circulation without vehicle downtime, the architecture Yulu Bikes deploys across Bengaluru and Delhi.
- Home Charging Solutions:Distributed residential replenishment reducing central infrastructure burden but complicating asset tracking and maintenance scheduling.
- Partnership Networks:Third-party host arrangements leveraging retail or fuel station real estate for station siting without direct capital ownership.
- Mobile Charging:Van-mounted or portable replenishment units addressing coverage gaps in emerging deployment zones.
Public Charging Stations absorb current capital deployment; Battery Swapping Networks are gaining share fastest as FAME-II subsidies decouple infrastructure costs from viability.
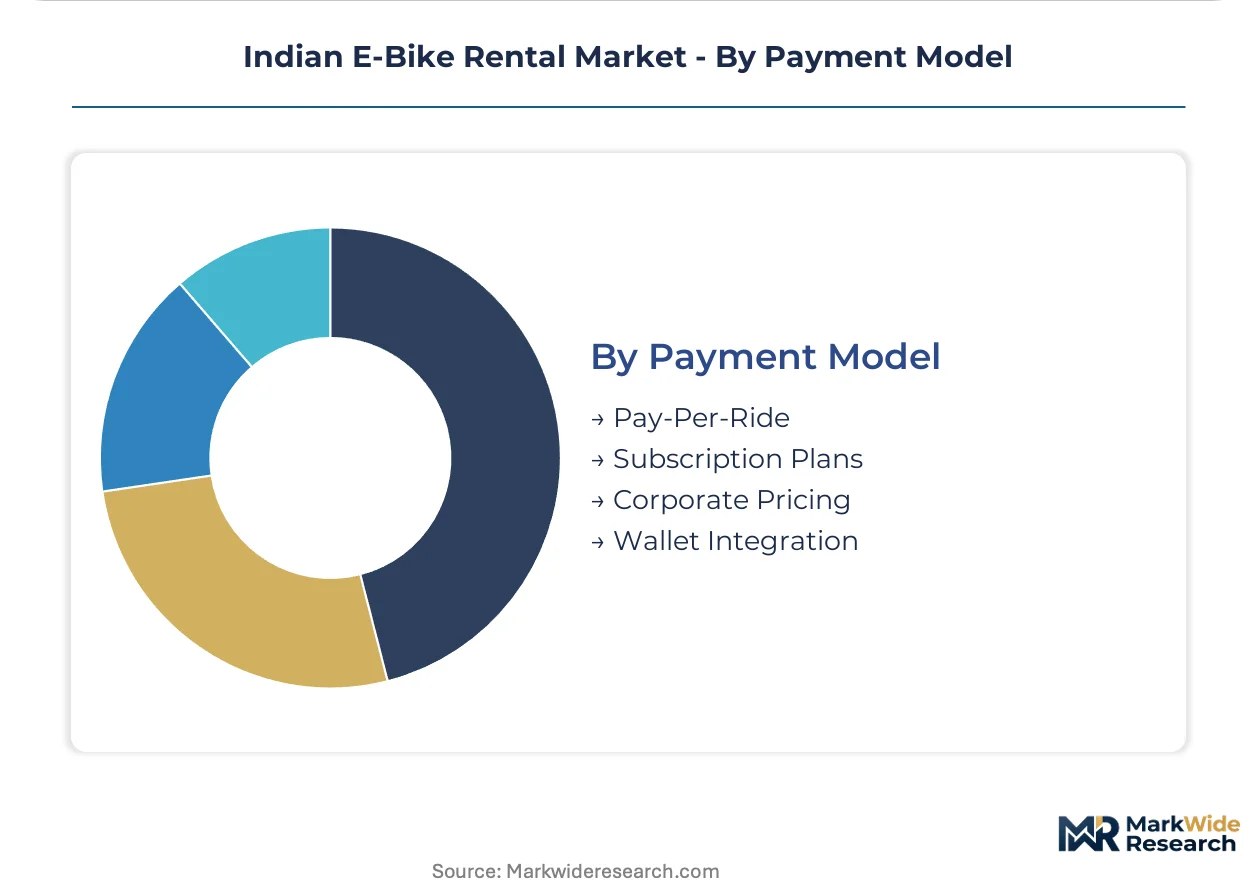
Payment Model:
Transaction friction and revenue recognition timing vary dramatically across these mechanisms, shaping working capital requirements.
- Pay-Per-Ride:Immediate settlement through UPI or wallet, capturing impulse demand but exposing operators to utilization volatility.
- Subscription Plans:Prepaid recurring commitments improving cash flow predictability and reducing customer acquisition costs for retained users.
- Corporate Pricing:Batched invoicing with extended payment terms, trading liquidity for contract scale and utilization guarantees.
- Wallet Integration:Pre-funded stored value reducing per-transaction processing costs and enabling dynamic pricing experimentation.
Pay-Per-Ride dominates transaction count; Subscription Plans show the steepest expansion trajectory as auto-debit penetration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metropolitan corridors in Karnataka, Maharashtra, and Delhi-NCR concentrate fleet deployment density, with metro rail interchanges generating multimodal rental uptake among daily commuters seeking last-mile connectivity solutions.
Karnataka
Bengaluru's metro expansion drives personal rental demand along the Purple and Green Lines, with BIS-certified swappable battery architectures dominating fleet specifications. The state EV policy extends registration waivers and parking privileges to commercial rental operators. Yulu Bikes anchors battery-swapping infrastructure across Koramangala, Indiranagar, and Whitefield tech corridors.
Maharashtra
Mumbai's suburban rail network creates last-mile gaps between stations and commercial districts, sustaining corporate rental contracts for employee commute fleets. The state electricity regulator classifies swapping stations under commercial tariffs, compressing network profitability margins. Pune emerges as a tier-two expansion target with lower station deployment costs and reduced competitive congestion.
Delhi-NCR
Delhi Metro's Phase IV expansion intensifies rental demand around interchange stations in Dwarka, Noida, and Gurugram. The Delhi government's EV policy mandates dedicated parking bays for rental fleets at metro premises. Gurugram's corporate office clusters anchor B2B logistics rental contracts with longer tenure structures than consumer segments.
Tamil Nadu
Chennai's underpenetrated rental market offers density advantages as metro rail construction advances along the Blue Line corridor. State-level EV incentives under the Tamil Nadu Electric Vehicle Policy reduce procurement costs for fleet entrants. The OMR-ECR tech corridor concentrates early deployment trials targeting IT park employee commutes.
Telangana
Hyderabad's HITEC City and Gachibowli financial district generate corporate rental demand from technology sector employers subsidizing employee mobility. The Telangana State Electric Vehicle and Energy Storage Policy provides capital subsidies for commercial fleet operators. The Miyapur-LB Nagar metro corridor shapes station siting priorities for rental network planners.
Indian E-Bike Rental Market Competitive Landscape
Bengaluru-based operators anchor one tier; Delhi-NCR specialists hold contract density in corporate segments. The market structures around three archetypes: battery-swapping infrastructure owners, franchise-depot network operators, and B2B logistics rental providers. Consolidation pressures favor asset-light franchise models over captive fleet ownership. Strategic moves concentrate on metro-adjacent station siting and corporate subscription contract acquisition.
Within the infrastructure-integrated tier, Yulu Bikes Pvt Ltd and Zypp Electric occupy positions exemplifying divergent specialization paths. ONN Bikes represents the franchise-operated depot model controlling neighborhood availability. These three entities illustrate how capital deployment choices—swapping networks versus fixed depots versus corporate contracts—segment competitive positioning across metropolitan corridors.
| Leading Market Players |
|---|
| Vogo Rental |
| Rentrip Services Pvt Ltd |
| Yulu Bikes Pvt Ltd |
| EXA Mobility EXA RIDE |
| ONN Bikes |
| Bounce Infinity |
| eBikeGo Pvt Ltd |
| Voltium |
| Zypp Electric |
| Others |
Supply & Pricing Matrix
FAME-II subsidy extensions in India gate qualified supply access and premium-tier pricing power for fleet operators meeting domestic value-addition thresholds. Battery-swapping station tariffs and lithium-ion cell import costs feed directly into subscription pricing structures across metropolitan corridors.
Pricing Analysis
Short lead-time procurement of FAME-II-certified vehicles commands premium subscription rates from corporate clients, while spot inventory of older-generation scooters trades at discounted walk-in tariffs. Three-tier pricing structure across premium swappable-battery fleets, standard fixed-battery models, and economy-grade campus rentals separates contract tenures and utilization guarantees. Pricing pressure stems from commercial electricity tariffs for swapping stations compressing network margins. Students and price-elastic daily commuters exhibit highest price sensitivity; corporate logistics clients demonstrate lowest sensitivity due to employer subsidy structures.
Supply Chain Analysis
Skilled technician availability for battery diagnostics in Bengaluru, Chennai, and Pune manufacturing corridors constrains fleet maintenance capacity expansion. Domestic battery pack assembly draws from imported lithium-ion cells originating in China, South Korea, and Japan, creating currency exposure for operators. Single-source vulnerability concentrates in East Asian cell suppliers subject to export licensing shifts. Distribution runs through franchise-operated neighborhood depots and corporate direct-contract channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market structures as a consolidation play where FAME-II subsidy qualification thresholds force undercapitalized operators toward acquisition or exit.
For Market Incumbents: To counter margin compression from commercial swapping-station tariffs, prioritize backward integration into captive battery assembly facilities in Karnataka and Maharashtra. Secure exclusive station-siting agreements at metro interchange premises before Phase IV expansion completes. Certification investment under BIS swappable-battery standards locks out non-compliant entrants from premium corporate contract pools. For New Entrants and Emerging Players: State-level EV policies in Tamil Nadu and Telangana open a window for tier-two city beachheads with lower competitive density and reduced station deployment costs. Target underpenetrated corporate employee commute segments in Hyderabad's HITEC City and Chennai's OMR corridor. Go-to-market leverage rests on wallet-integrated UPI auto-debit subscription structures minimizing customer acquisition friction. For Investors and Strategic Acquirers: RBI green lending guideline expansion is the leading indicator that institutional capital rotation toward asset-light rental operators will accelerate. Long-term viability favors franchise-depot network operators with documented carbon displacement metrics over captive fleet ownership models. Acquisition target archetype: mid-scale operators holding exclusive municipal parking privileges at metro premises. Signal to monitor: state electricity regulator reclassification of swapping-station tariffs toward residential rate schedules.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Swapping Network Expansion | FAME-II subsidies decouple infrastructure capital from network viability in Bengaluru and Delhi corridors. |
| Corporate Subscription Contract Acquisition | B2B logistics rentals anchor revenue stability through longer tenures than consumer walk-in transactions. |
| Franchise Depot Network Scaling | Asset-light expansion controls last-mile availability without balance-sheet fleet concentration. |
| Metro Rail Interchange Siting | Delhi Metro Phase IV and Bengaluru Purple Line extensions concentrate multimodal rental demand. |
| State EV Policy Alignment | Maharashtra and Karnataka registration waivers reduce compliance costs and accelerate deployment timelines. |
Research Methodology
Ministry of Road Transport and Highways circulars, state EV policy documents, and SEBI ESG disclosure filings formed the secondary backbone for regulatory and subsidy trajectory mapping. Primary interviews with fleet operations directors, battery-swapping infrastructure managers, and corporate mobility procurement leads at technology sector employers combined with secondary validation. BIS certification records, CEA electricity tariff orders, and RBI green lending guidelines provided triangulation anchors for bottom-up fleet deployment estimates and top-down market sizing across the analysis window.
Historical trendline analysis of metro rail ridership growth and FAME-II disbursement patterns informed the projection framework. Segmentation modeling incorporated service type, customer archetype, charging infrastructure, and payment model dimensions alongside state-level policy adoption trajectories. CAGRs derived from vehicle deployment density correlations with transit interchange proximity and subsidy eligibility windows. Forecast inputs included lithium-ion cell import volume trends and commercial electricity tariff spread assumptions for swapping station profitability.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for swappable-architecture operators. Forecasts reflect documented assumptions regarding FAME-II extension continuity and state electricity regulator tariff classifications. Material deviation in central subsidy disbursement rates or commercial-residential tariff spread compression warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Middle-East and Africa E-Bike Market
Electric Vehicles
Asia-Pacific Electric Vehicle Thermal Management System Market
Electric Vehicles
South America Electric Vehicle (EV) Fluids Market
Electric Vehicles
Global Golf Cart and Neighborhood Electric Vehicle (NEV) Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
India Electric Vehicle Financing Market
Electric Vehicles
Cargo-to-Passenger Convertible eVTOL Cabin Systems Market
Electric Vehicles
Electric Vehicle Electronic Expansion Valve (EXV) Market
Electric Vehicles
Electric Vehicle on Board Charger Market
Electric Vehicles
Recreational Vehicle (RV) Batteries Market
Electric Vehicles
Electric Vehicle Testing, Inspection, and Certification Market
Electric Vehicles
E-Bike Battery Market
Electric Vehicles
Embedded System for Electric Vehicle Market
Electric Vehicles
Busbar for EV Market
Electric Vehicles
Mexico Solar E-Bike Market
Electric Vehicles
US Electric Vehicle Market