
 Pickleball Paddle Market | 2026-2036
Pickleball Paddle Market Size, Share, and Industry Trends Forecast 2026-2036
Pickleball Paddle Market Insights
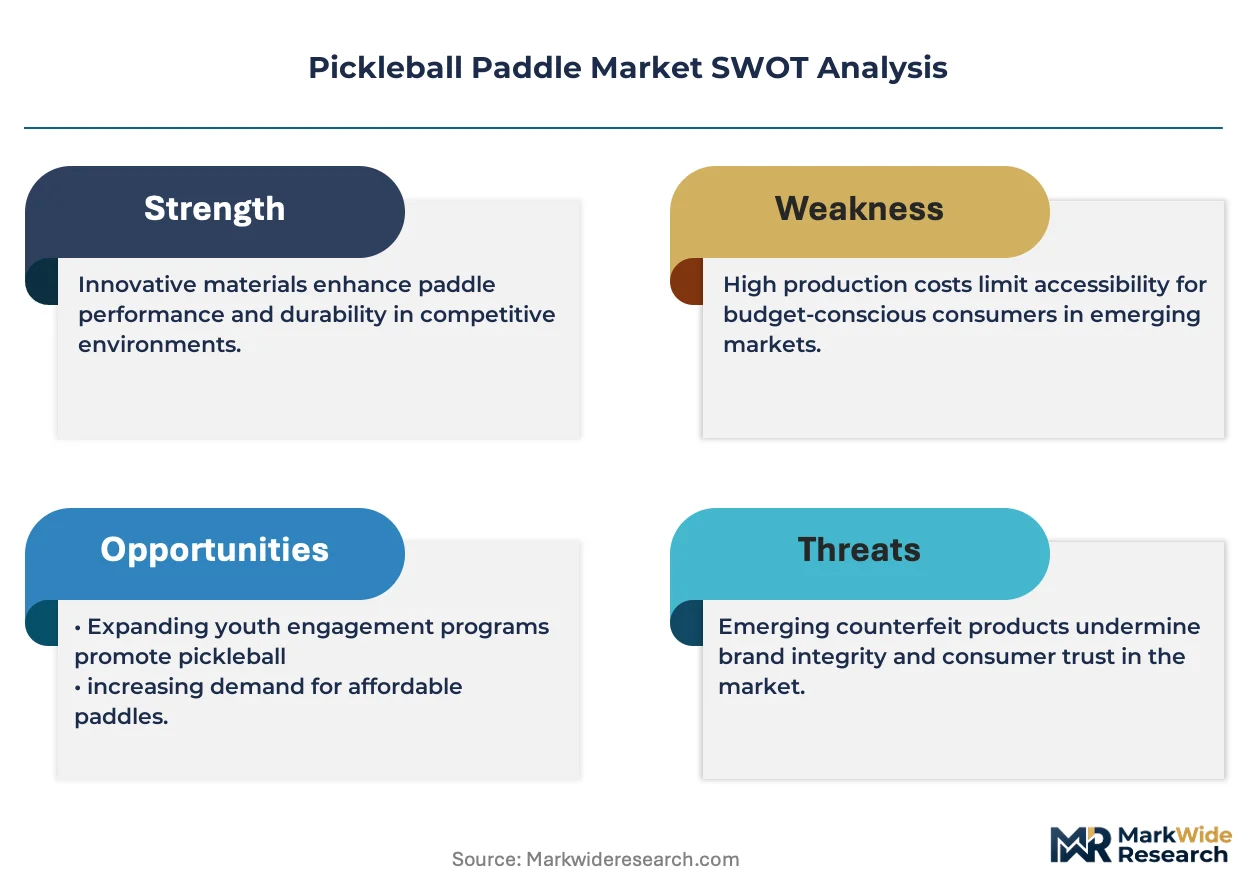
Aftermarket stringing and grip customization is rewriting margin capture in paddle sports accessories. Selkirk leverages vertical integration to control carbon fiber sourcing for premium graphite models. Gearbox sustains technology leadership through patented edgeless frame designs that reduce ball mis-hits. Paddletek anchors its position in the amateur segment through direct-to-consumer channel control and community tournament sponsorships.
A pickleball paddle is a solid-faced racket, typically measuring 15.5 to 17 inches in length and constructed from layered composites of polymer honeycomb cores with fiberglass, carbon fiber, or graphite face sheets, designed to strike a perforated plastic ball with controlled power and spin during court play. Composite and graphite product types command the strongest margin pools as players upgrade from entry-level wood equipment, while aluminum variants retain niche demand among institutional buyers prioritizing durability over performance. Customer type dynamics reveal amateurs as the volume foundation, though professionals and competitive seniors generate disproportionate premium-tier pull through equipment sponsorship visibility and skill-level stratification in league play.
The US Consumer Product Safety Commission governs surface coating safety and lead-content thresholds for recreational equipment, while ISO 9001 quality management standards shape manufacturing consistency among offshore suppliers. The EU REACH regulation constrains chemical treatments in composite resin systems, adding compliance cost layers for brands sourcing European-bound inventory. Stakeholders must monitor evolving state-level recreational facility mandates and material disclosure requirements as municipal investment in dedicated pickleball infrastructure accelerates participation rates and equipment replacement cycles.
Market Dynamics
The pickleball paddle market is experiencing structural compression from raw material sourcing constraints, as carbon fiber supply concentration in Asian manufacturing clusters forces brands to secure captive resin systems or absorb volatile input costs.
Growth Catalysts
- Retirement Community Infrastructure:Municipal investment in dedicated pickleball courts across Florida and Arizona retirement developments is accelerating equipment replacement cycles among senior recreational leagues.
- REACH Compliance Differentiation:EU REACH regulation constraints on chemical treatments in composite resin systems create competitive moats for brands with certified European-bound inventory.
- Polymer Honeycomb Core Advances:Enhanced polymer honeycomb core density specifications are extending paddle durability and justifying premium pricing in competitive amateur segments.
Market Restraints
- Graphite Supply Concentration:Carbon fiber precursor production concentrates in Japanese and Chinese chemical complexes, exposing paddle manufacturers to cross-border tariff volatility and shipping disruptions.
- Wood Paddle Substitution:Entry-level wood paddles retain institutional procurement preference in school and community center bulk purchasing, capping composite upgrade velocity.
- US Consumer Product Safety Commission Testing:Surface coating safety and lead-content threshold enforcement adds compliance timeline friction and third-party certification costs for new market entrants.
Strategic Opportunities
- Aftermarket Customization Services:Grip customization and professional stringing services represent unbundled revenue streams with margin profiles exceeding base equipment sales.
- Direct-to-Consumer Channel Expansion:Community tournament sponsorships combined with digital-native distribution bypass traditional sporting goods retail markups and capture customer data.
- State-Level Facility Mandates:Evolving municipal recreational facility standards requiring dedicated pickleball infrastructure are creating localized demand spikes for equipment procurement.
Industry Challenges
- Composite Technician Scarcity:Layered composite manufacturing requires specialized layup technicians, and training pipelines lag demand expansion in offshore production facilities.
- ISO 9001 Certification Timelines:Quality management standard compliance for offshore suppliers extends supplier qualification periods and delays new product launches.
- Edgeless Frame IP Complexity:Patented frame designs create licensing friction and litigation risk for manufacturers developing competing vibration-dampening geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pickleball Paddle Market |
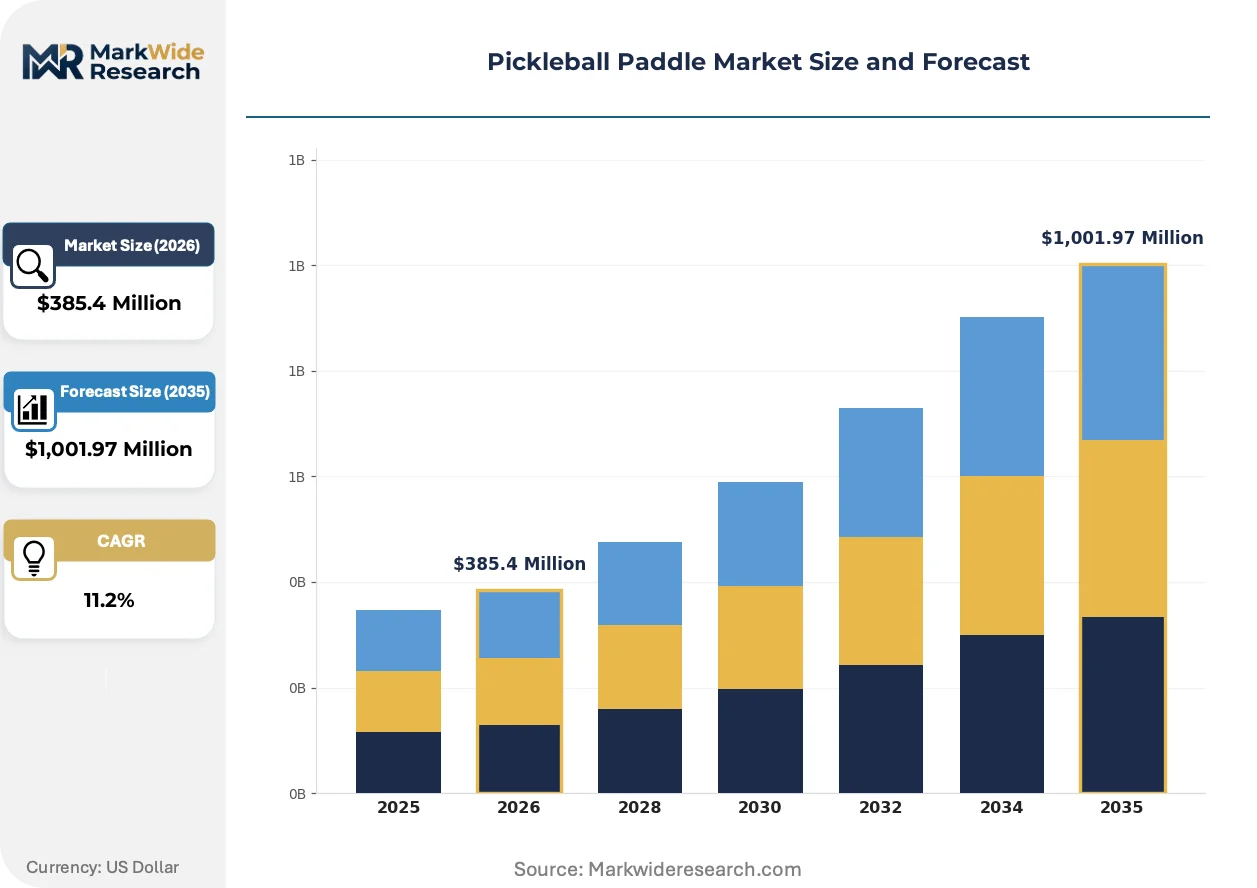
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,001.97 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood, Composite, Graphite, Aluminum Customer Type: Amateurs, Professionals, Youth, Seniors Price Tier: Budget, Mid-range, Premium, Luxury Distribution Channel: Online Retail, Specialty Stores, Sporting Goods, Others |
| Companies Covered | Onix, Gearbox, Selkirk, Gamma, ProLite, JOOLA, Paddletek, Proton, CRBN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pickleball Paddle Market Trends and Innovations
Sensor-embedded paddle technology is digitizing player performance data and compressing the feedback loop between equipment specification and skill development. This convergence of hardware and analytics is reshaping how manufacturers design product tiers and how retailers justify premium positioning.
Carbon fiber surface texture engineering is digitizing spin control calibration through precision-machined face patterns that interact with ball perforation geometry. Competitive seniors and league players are adopting these textured surfaces fastest, compressing the performance gap between amateur and professional equipment tiers.
REACH regulation chemical disclosure requirements are forcing composite resin reformulation across European-bound supply chains. Manufacturers with pre-certified material libraries are capturing shelf space faster, while laggards face extended requalification timelines that freeze product refresh cycles.
Subscription-based equipment refresh programs are displacing traditional ownership models among high-frequency recreational players. These programs concentrate demand visibility for manufacturers and shift inventory risk from retailers to brand-direct operations, with strongest uptake visible in Arizona and Florida retirement community clusters.
Pickleball Paddle Market Segmentation
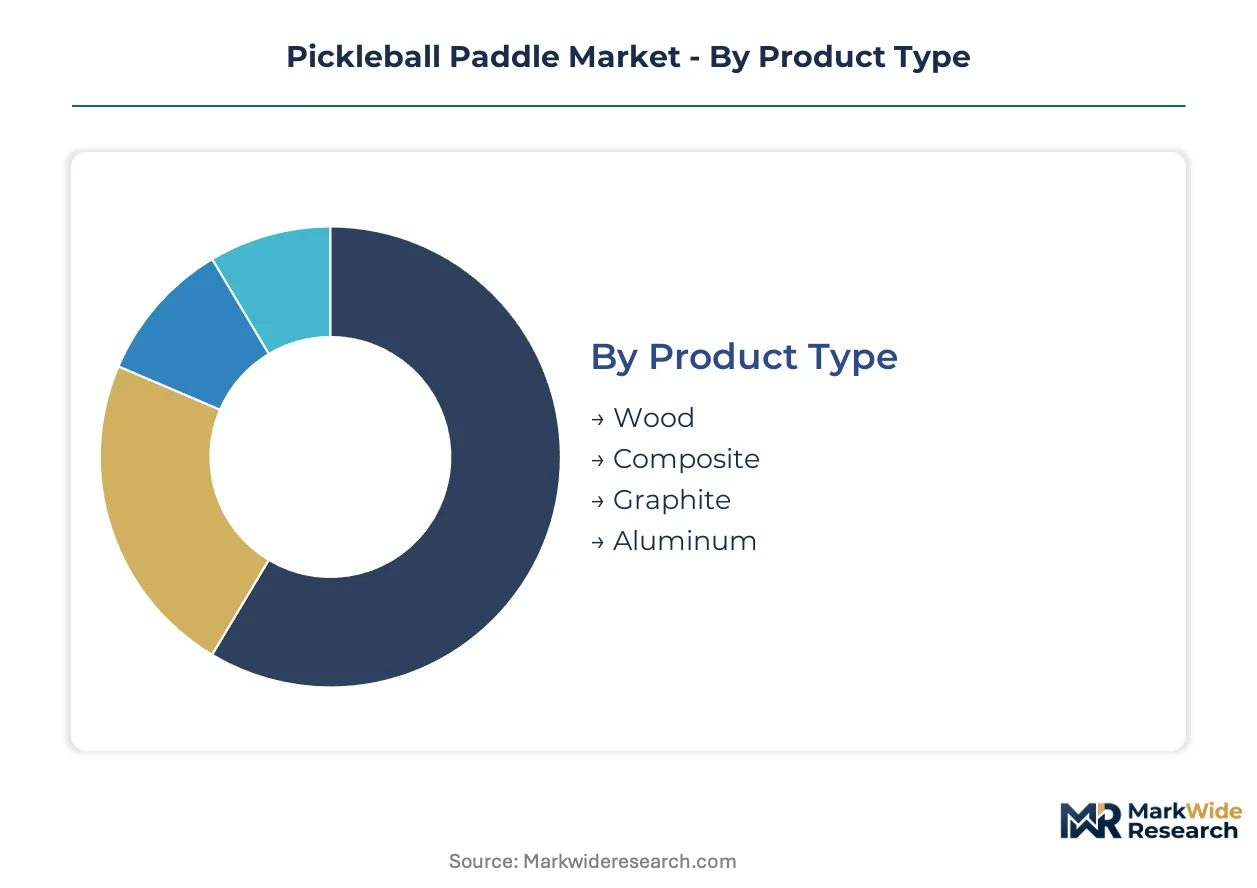
Segmentation in pickleball paddles determines aftermarket service intensity, with premium tiers demanding grip replacement and surface resurfacing that wood equipment never requires. Material composition and player sophistication stratify replacement cycles, warranty claims, and accessory attachment rates across the installed base.
Product Type:
After-sales-service intensity escalates dramatically from wood to graphite, with composite and graphite paddles requiring grip customization, edge guard replacement, and surface conditioning that wood equipment simply does not support.
- Composite:Layered polymer honeycomb cores with fiberglass face sheets deliver balanced power and control for intermediate players. Demand concentrates in Arizona and Florida retirement communities where municipal court investment accelerates replacement cycles among competitive amateur leagues.
- Graphite:Carbon fiber face sheets over polymer cores maximize lightweight responsiveness and spin generation. Competitive seniors and league players in US retirement developments drive disproportionate premium-tier pull through equipment sponsorship visibility.
- Wood:Solid hardwood construction serves institutional procurement in school and community center bulk purchasing with minimal service requirements.
- Aluminum:Metal face sheets over aluminum honeycomb cores prioritize durability over performance for institutional buyers prioritizing equipment longevity.
Composite holds the largest share; momentum sits with graphite.
Customer Type:
Cost tier alignment separates recreational volume from premium extraction, with professionals and competitive seniors justifying equipment investment levels that youth and casual amateurs cannot sustain.
- Amateurs:Recreational players form the volume foundation through community league participation and retirement community court access. Florida and Arizona municipal infrastructure investment compresses replacement cycles in this segment.
- Seniors:Competitive retirees generate disproportionate premium-tier demand through skill-level stratification in organized league play and equipment sponsorship visibility.
- Professionals:Elite tournament players drive technology adoption and specification refinement through performance feedback loops with manufacturers.
- Youth:School programs and junior leagues represent emerging volume with institutional procurement preferences for durability over performance.
Amateurs dominate unit volume; seniors are climbing the fastest in value contribution.
Price Tier:
Volume concentration at budget and mid-range levels funds premium innovation pipelines, with luxury tiers serving brand halo and professional endorsement functions rather than mass market penetration.
- Mid-range:Composite construction at accessible price points captures upgrade momentum from wood equipment in community league expansion zones.
- Premium:Graphite and advanced composite specifications serve competitive amateurs and seniors seeking performance differentiation in tournament play.
- Budget:Entry-level wood and basic composite paddles satisfy institutional procurement and casual recreational trial.
- Luxury:Limited editions and professional signature models command price premiums through scarcity and endorsement value rather than functional differentiation.
Mid-range holds the largest share; premium is gaining share fastest.
Distribution Channel:
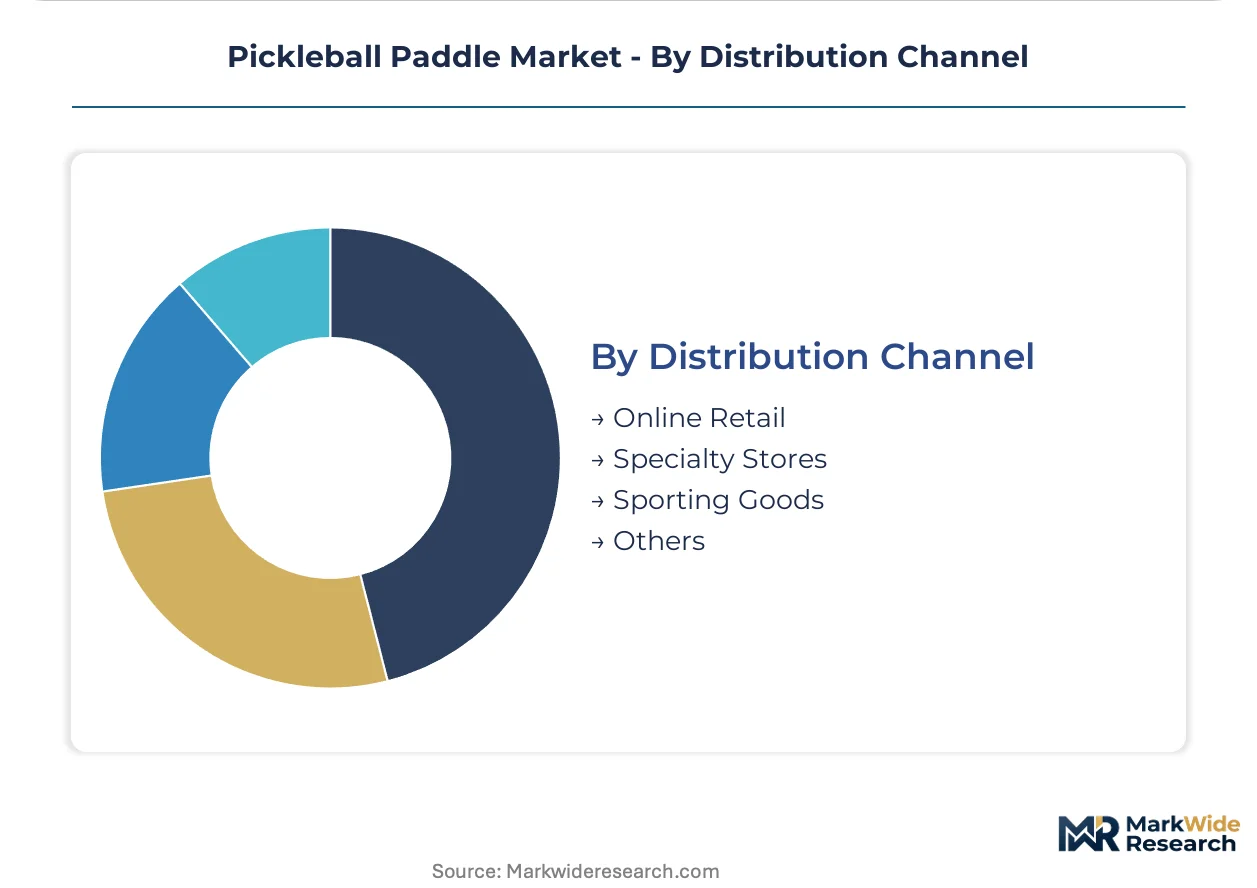
Channel selection determines margin capture and customer data access, with direct-to-consumer expansion threatening traditional sporting goods retail markups while specialty stores retain premium consultation value.
- Online Retail:Digital-native distribution bypasses retail markups and enables subscription-based equipment refresh programs with strongest uptake in Arizona and Florida retirement clusters.
- Specialty Stores:Pro shops and dedicated pickleball retailers provide grip customization and professional stringing services with margin profiles exceeding base equipment sales.
- Sporting Goods:Mass sporting goods chains retain institutional procurement relationships and entry-level equipment volume.
- Others:Direct club sales and tournament merchandise capture impulse replacement demand at point of play.
Online retail holds the largest share; specialty stores show the steepest expansion trajectory in service attach rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Florida and Arizona retirement communities show low price elasticity, absorbing premium graphite pricing, while institutional purchasers in school districts and community centers remain highly price-sensitive, favoring wood and aluminum alternatives.
United States
Municipal court construction in Florida and Arizona retirement developments drives equipment replacement cycles among competitive senior leagues. The US Consumer Product Safety Commission enforces surface coating safety and lead-content thresholds for recreational equipment. Phoenix and Naples anchor the densest concentrations of dedicated pickleball facilities, with equipment procurement accelerating alongside infrastructure investment.
Canada
Snowbird migration patterns and cross-border leisure travel sustain demand in British Columbia and Ontario retirement clusters. Health Canada regulates recreational equipment safety standards for consumer protection. Vancouver and Toronto metropolitan areas concentrate specialty retail expansion and community league formation.
Germany
Racket sports culture translation and aging demographic fitness priorities generate emerging pickleball adoption in municipal recreation programs. The KBA does not regulate pickleball equipment; general product safety law applies under EU harmonized standards. Munich and Hamburg lead facility pilot programs and club formation initiatives.
United Kingdom
Tennis club conversion and leisure center diversification create installation demand for multi-use court surfaces. The UK's Office for Product Safety and Standards oversees recreational equipment compliance. London and Southeast England concentrate early-adopter clubs and tournament organization activity.
Australia
Outdoor recreation culture and retirement migration from colder climates support paddle sports expansion in Queensland and New South Wales. The TGA does not regulate sporting equipment; consumer protection frameworks apply at state level. Gold Coast and Sydney metropolitan areas host the most developed competitive league structures.
Pickleball Paddle Market Competitive Landscape
Capability concentration sits with specialized composite fabricators; scale advantage sits with diversified sporting goods conglomerates. The market structure tiers between premium graphite specialists and mass-market wood suppliers, with mid-range composite occupying the contested middle. Three archetypes dominate: vertically integrated carbon fiber controllers, direct-to-consumer digital natives, and institutional procurement specialists. Competitive moves concentrate on backward integration into resin systems and community tournament sponsorship for channel bypass.
Among US-based specialists, Selkirk, Gearbox, and Paddletek exemplify divergent strategic positioning. Selkirk occupies the upstream control archetype through captive carbon fiber sourcing. Gearbox represents technology differentiation via patented frame geometries. Paddletek anchors the community-embedded direct-to-consumer model. These three illustrate how capability depth, design IP, and channel architecture separate winners in a market where material science and distribution economics determine margin capture.
| Leading Market Players |
|---|
| Onix |
| Gearbox |
| Selkirk |
| Gamma |
| ProLite |
| JOOLA |
| Paddletek |
| Proton |
| CRBN |
| Others |
Pricing and Supply Chain Analysis
Carbon fiber precursor concentration in Japanese and Chinese chemical complexes feeds directly into margin capture at the premium graphite tier, where brands with captive resin systems or long-term offtake contracts extract pricing power unavailable to wood and aluminum competitors.
Pricing Analysis
Aftermarket grip customization and surface resurfacing services drive lifetime value far beyond initial equipment transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies by material grade and certification tier, with ISO 9001 compliance adding cost layers that brands pass through or absorb. Pricing pressure stems from wood paddle substitution in institutional procurement, compressing composite upgrade velocity. Amateurs in community leagues show highest price sensitivity; competitive seniors in Florida and Arizona retirement developments absorb premium graphite pricing with minimal elasticity.
Supply Chain Analysis
Taiwanese and Chinese contract manufacturers hold dominant composite layup capacity for polymer honeycomb core assembly. Raw material flows draw from Japanese carbon fiber precursors, Chinese fiberglass weaving operations, and South Korean polymer resin systems. Single-source vulnerability concentrates in carbon fiber supply, exposing brands to cross-border tariff volatility and shipping disruptions. Distribution runs through direct-to-consumer digital channels bypassing traditional sporting goods retail markups, with specialty pro shops retaining premium service attach rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pickleball paddle demand sits in early-cycle expansion, with municipal court construction across retirement communities creating durable equipment replacement tailwinds that outpace typical sporting goods penetration curves.
For Market Incumbents: Pre-empt wood paddle substitution in institutional procurement by embedding durability guarantees and bulk pricing frameworks that neutralize entry-level cost advantages. Secure backward integration into carbon fiber resin systems to buffer Japanese and Chinese supply concentration. Defensive patent filings around edgeless frame geometries reduce litigation exposure from Gearbox's existing IP moat.
For New Entrants and Emerging Players: European market underpenetration offers white-space expansion, as REACH compliance differentiation creates competitive moats for brands with pre-certified material libraries. Target Germany and United Kingdom municipal recreation programs where tennis club conversion accelerates court availability. Launch through community tournament sponsorships to bypass established retail relationships and capture player data directly.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated carbon fiber controllers with captive sourcing and certified European inventory. Long-term viability hinges on brands that combine material science depth with direct-to-consumer channel architecture. Monitor sensor-embedded paddle adoption rates as the inflection signal separating hardware commodity plays from analytics-integrated platform investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Resin | Selkirk's captive sourcing model insulates margin from Asian supply volatility and tariff exposure. |
| REACH Certification Pre-Positioning | Pre-certified European inventory captures shelf space faster than laggards facing extended requalification timelines. |
| Direct-to-Consumer Channel Expansion | Paddletek's community tournament sponsorships bypass retail markups and concentrate customer data ownership. |
| Sensor-Embedded Technology Development | Digitized performance data compresses feedback loops between equipment specification and player skill advancement. |
| Subscription Equipment Refresh Programs | Arizona and Florida retirement clusters show strongest uptake, shifting inventory risk from retailers to brand-direct operations. |
Research Methodology
A standing panel of composite manufacturing technicians, specialty retail buyers, municipal recreation directors, and competitive league organizers provided ongoing calibration across primary fieldwork. Secondary validation drew from US Consumer Product Safety Commission filings, ISO certification registries, EU REACH chemical disclosure databases, and municipal infrastructure budget disclosures. Bottom-up equipment shipment data triangulated against top-down court installation permits and league registration counts.
Scenario bracketing anchored the analytical framework across the analysis window, with segmentation dimensions spanning material composition, player sophistication tier, distribution channel architecture, and regional regulatory cluster. CAGRs derived from equipment replacement cycle compression in retirement community developments and polymer honeycomb core durability advances. Forecast inputs incorporated sensor-embedded adoption curves and subscription program uptake rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified sporting goods conglomerates or private-equity-backed rollups would shift outcomes beyond modeled ranges. Quarterly review of municipal court construction permits, carbon fiber spot pricing, and REACH compliance certification timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Asia-Pacific Kickboxing Equipment Market
Sports Equipment
Squash Equipment Market
Sports Equipment
Triathlon Bikes Market
Sports Equipment
Juggling Clubs Market
Sports Equipment
Carbon-Fiber Badminton Racquet Market
Sports Equipment
Bicycle Crankset Market
Sports Equipment
Wave Windsurf Boards Market
Sports Equipment
Recreational Rowing Boats Market
Sports Equipment
Global Mountain Bicycles Market
Sports Equipment
Baseball Sliding Mitts Market
Sports Equipment
Soccer Cleats Market
Sports Equipment
Cricket Equipment Market
Sports Equipment
Riding Gear Market
Sports Equipment
Asia-Pacific Stand-Up Paddleboard Market
Sports Equipment
Boxing Gear Market
Sports Equipment
Figure Skating Equipment Market