
 Recombinant Protein Therapeutics CDMO Market | 2026-2036
Recombinant Protein Therapeutics CDMO Market Size, Share, and Industry Trends Forecast 2026-2036
Recombinant Protein Therapeutics CDMO Market Analytics
Capital-intensity divergence between single-use and stainless-steel bioreactor platforms is bifurcating the competitive landscape. Lonza leverages its large-scale mammalian cell culture infrastructure across Switzerland and the United States to anchor high-volume monoclonal antibody production. WuXi Biologics sustains cost-competitive microbial and mammalian expression systems through integrated campuses in China. FUJIFILM Diosynth Biotechnologies differentiates via specialized viral vector and protein manufacturing capabilities in Europe and North America.
Recombinant Protein Therapeutics CDMO denotes contract development and manufacturing organizations that engineer, produce, and purify therapeutic proteins using bacterial, yeast, insect, or mammalian expression systems, typically yielding batch sizes from hundreds to twenty thousand liters with purity thresholds exceeding ninety-five percent for clinical and commercial supply. The primary industrial purpose centers on enabling pharmaceutical and biotechnology firms to access specialized biomanufacturing capacity without building captive facilities. Monoclonal antibodies occupy the largest product-type revenue pool given their established oncology and immunology indications, while enzyme and hormone segments attract niche CDMO specialists with microbial expression expertise. Process development services command premium pricing due to lengthy cell-line optimization timelines, whereas manufacturing services generate volume-driven recurring revenue across multi-year supply agreements.
FDA guidelines on current Good Manufacturing Practice for biological products, EMA's biosimilar comparability protocols, and China's NMPA drug registration requirements collectively elevate compliance costs and extend facility qualification timelines for CDMO operators. These frameworks directly shape client vendor selection criteria, favoring organizations with proven regulatory submission track records across multiple jurisdictions. Stakeholders must monitor emerging gene therapy and multispecific protein formats that could redirect capacity investments away from traditional monoclonal antibody platforms.
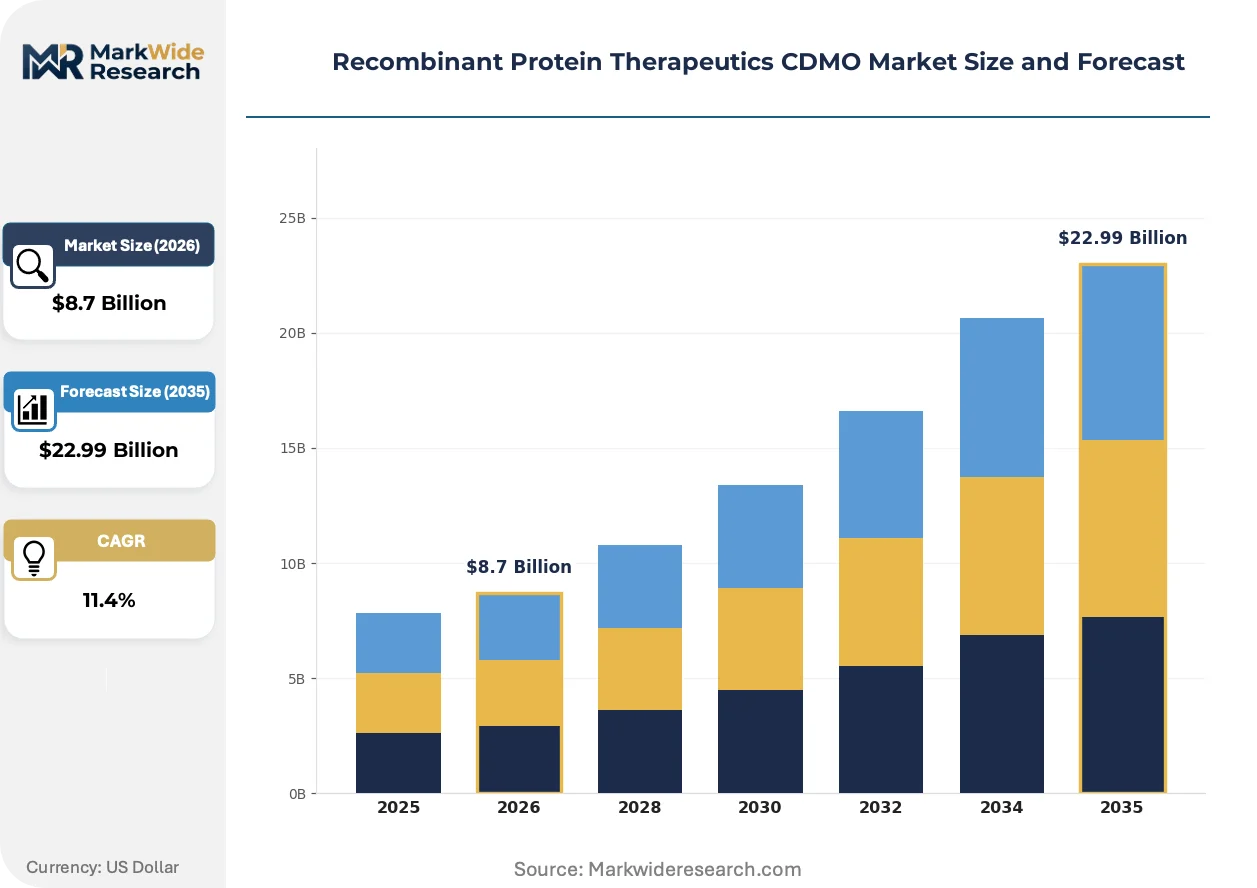
Market Dynamics
Bioreactor platform economics now dictates vendor selection, as stainless-steel scale-up costs diverge sharply from single-use flexibility premiums, forcing CDMOs to commit to irreversible capital paths before securing long-term supply agreements.
Growth Catalysts
- EMA Biosimilar Comparability Protocols:These frameworks mandate rigorous analytical characterization, driving originator and biosimilar developers toward CDMOs with established multi-jurisdiction regulatory dossier experience.
- Continuous Bioprocessing:Perfusion-based mammalian cell culture technologies reduce facility footprint requirements while increasing volumetric productivity, attracting capital-constrained biotech clients.
- Shanghai-Basel-Boston Capacity Clusters:Geographic concentration of multi-thousand-liter bioreactor infrastructure enables just-in-time logistics for clinical-to-commercial scale transitions.
Market Restraints
- Plasma-Derived Protein Competition:Fractionation facilities in the United States and Europe retain cost advantages for certain coagulation factors and immunoglobulins, limiting recombinant substitution in price-sensitive indications.
- Chinese Stainless-Steel Equipment Dependence:Domestic CDMOs rely on imported bioreactor hardware and automation systems, exposing capacity expansion timelines to semiconductor and precision manufacturing supply constraints.
- FDA Process Validation Burden:Extended facility qualification timelines for biological products compress effective contract durations and delay revenue recognition for new manufacturing suites.
Strategic Opportunities
- India's Emerging CDMO Infrastructure:CDSCO manufacturing license reforms and PLI scheme incentives for biopharmaceuticals are attracting investment in mammalian cell culture capabilities previously concentrated in Western markets.
- Multispecific Antibody Formats:Bispecific and trispecific constructs require novel purification workflows, creating service differentiation opportunities for CDMOs with advanced chromatography platform development expertise.
- Digital Twin Process Modeling:Convergence of computational fluid dynamics with real-time analytics enables predictive scale-up, reducing failed batch risk and accelerating client tech transfer timelines.
Industry Challenges
- Cell Line Development Talent Scarcity:Mammalian expression system optimization requires hybrid skill sets spanning molecular biology and bioprocess engineering, with limited training pipeline capacity relative to facility expansion rates.
- Legacy ERP Integration Friction:CDMOs acquiring smaller facilities face data architecture incompatibility between client-facing quality management systems and inherited enterprise resource planning platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recombinant Protein Therapeutics CDMO Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Process Development, Manufacturing, Quality Control, Regulatory Submission Product Type: Monoclonal Antibodies, Vaccines, Enzymes, Hormones End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Research Organizations Technology: Expression Systems, Purification Techniques, Formulation Processes, Analytical Methods |
| Companies Covered | Lonza, Catalent, WuXi Biologics, FUJIFILM Diosynth Biotechnologies, Curia Global, Batavia Biosciences, HALIX, Richter-Helm BioLogics, BIOVIAN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recombinant Protein Therapeutics CDMO Market Evolving Landscape
Process intensification technologies are compressing batch timelines while regulatory frameworks accelerate comparability requirements, together forcing CDMOs to differentiate through analytical capability depth rather than capacity scale alone.
Single-use perfusion bioreactor systems are miniaturizing upstream manufacturing footprints while maintaining equivalent titers to traditional fed-batch stainless-steel configurations. Mid-cap biotech sponsors now specify these platforms for Phase III material supply, avoiding capital-intensive facility dedication. This shift is compressing the minimum efficient scale for commercial viability, enabling distributed manufacturing networks closer to patient populations.
EMA's revised Good Manufacturing Practice Annex 1 for sterile medicinal products mandates enhanced contamination control strategies for biological manufacturing. Facility redesign costs for existing European CDMO infrastructure are diverting capital from capacity expansion toward environmental monitoring and isolator technology deployment. High-risk aseptic processing segments, including fill-finish for parenteral proteins, face the steepest compliance timeline compression.
Biopharmaceutical procurement departments now unbundle process development from commercial manufacturing contracts, awarding early-phase optimization to specialized boutiques while reserving high-volume supply agreements for established players with regulatory inspection histories. This bifurcation is fragmenting vendor relationships and extending qualification overhead for CDMOs seeking full-lifecycle client retention. The United States exhibits the most pronounced contract segmentation, reflecting consolidated buyer power among large-cap sponsors.
Recombinant Protein Therapeutics CDMO Market Segmentation
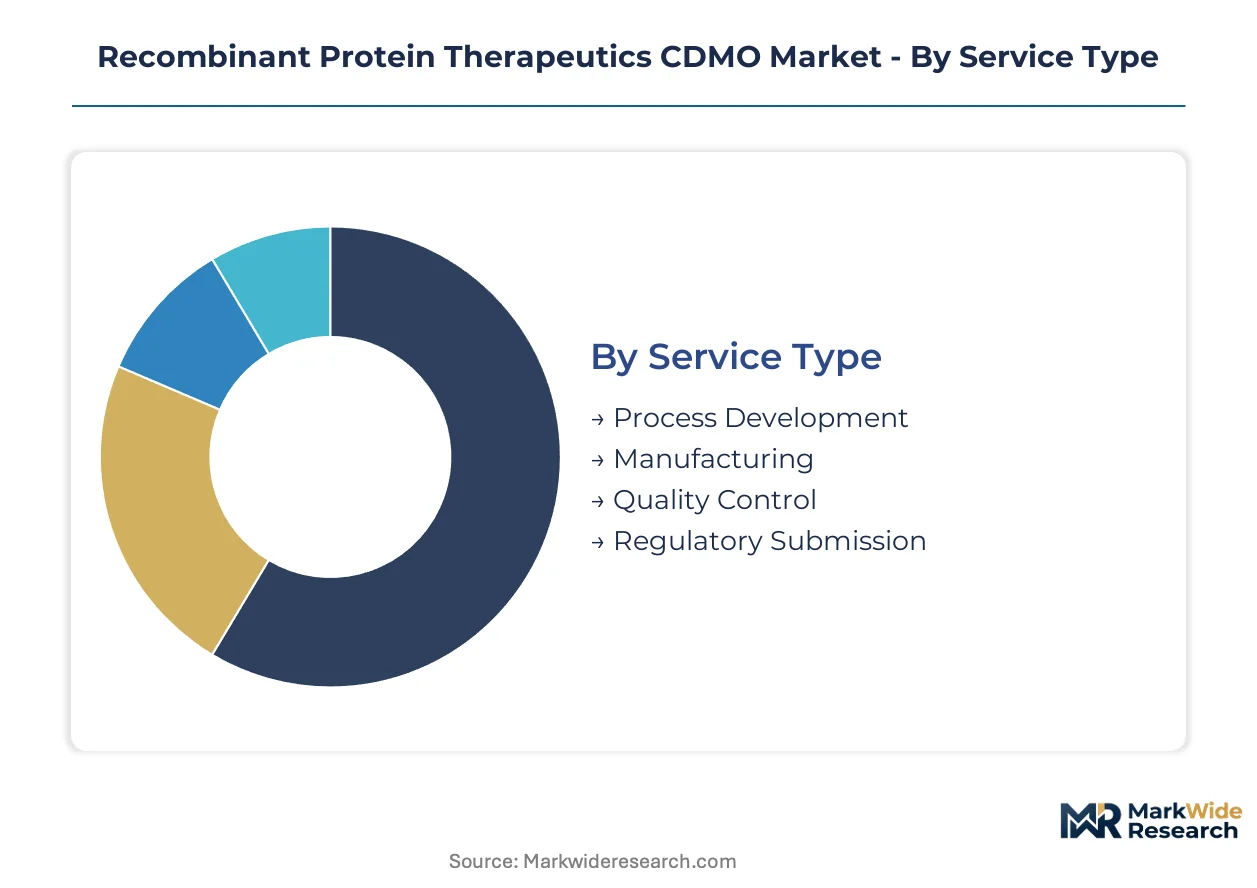
CDMO procurement decisions hinge on segment-specific regulatory requirements and capacity economics. Service type and product format dictate facility qualification timelines, while end-user scale determines contract structure and pricing models.
Service Type:
FDA process validation protocols and EMA Good Manufacturing Practice Annex 1 requirements create divergent compliance burdens across service categories, elevating vendor selection criteria for manufacturing-intensive segments.
- Process Development:Cell-line optimization and upstream scale-up design require hybrid molecular biology and bioprocess engineering expertise. Pharmaceutical sponsors in the United States increasingly unbundle this phase from commercial manufacturing contracts, awarding early-phase work to specialized boutiques with advanced perfusion platform capabilities.
- Manufacturing:Multi-thousand-liter bioreactor operations generate volume-driven recurring revenue across multi-year supply agreements. Stainless-steel fed-batch and single-use perfusion configurations now compete directly, with Boston and Basel clusters anchoring high-volume monoclonal antibody production for oncology indications.
- Quality Control:Analytical characterization services support biosimilar comparability studies mandated by EMA frameworks.
- Regulatory Submission:Dossier preparation and multi-jurisdiction filing assistance commands premium pricing from CDMOs with proven FDA, EMA, and NMPA track records.
Manufacturing handles the majority of throughput; process development is expanding most quickly on share as sponsors externalize early-phase optimization.
Product Type:
Cost tier differentiation separates high-volume monoclonal antibody platforms from niche microbial expression systems, with capital intensity determining competitive positioning.
- Monoclonal Antibodies:Established oncology and immunology indications anchor the largest revenue pool. Mammalian cell culture infrastructure in Switzerland and the United States concentrates capacity for these complex glycoproteins, with FDA biosimilar approval pathways accelerating demand for analytical characterization services.
- Vaccines:Recombinant subunit and virus-like particle formats require specialized containment and adjuvant formulation capabilities. Demand clusters around pandemic preparedness programs and seasonal influenza manufacturing, with fill-finish bottlenecks constraining effective supply.
- Enzymes:Microbial expression systems in China deliver cost-competitive production for lysosomal storage disorder therapies.
- Hormones:Insulin and growth factor manufacturing retains dedicated facility requirements due to peptide complexity and immunogenicity risks.
Monoclonal antibodies dominate current capacity allocation; vaccines are climbing the fastest on contract volume as sponsors diversify platform exposure.
End User:
Customer scale determines contract structure, with large-cap pharmaceutical procurement departments fragmenting vendor relationships across specialized boutiques and established manufacturing players.
- Pharmaceutical Companies:Consolidated buyer power in the United States drives aggressive unbundling of process development from commercial supply agreements. Multi-year manufacturing contracts with regulatory inspection history requirements favor CDMOs with established FDA and EMA dossier track records.
- Biotechnology Firms:Capital-constrained sponsors specify single-use perfusion platforms for Phase III material supply, avoiding facility dedication costs. These clients prioritize speed-to-IND and accelerated tech transfer timelines over unit cost optimization.
- Academic Institutions:Small-batch GMP material for investigator-initiated trials represents fragmented, price-sensitive demand.
- Research Organizations:Non-clinical grade protein supply for target validation and assay development operates outside formal regulatory submission pathways.
Pharmaceutical companies commit the largest contract values; biotechnology firms are gaining share fastest as venture-funded pipelines expand.
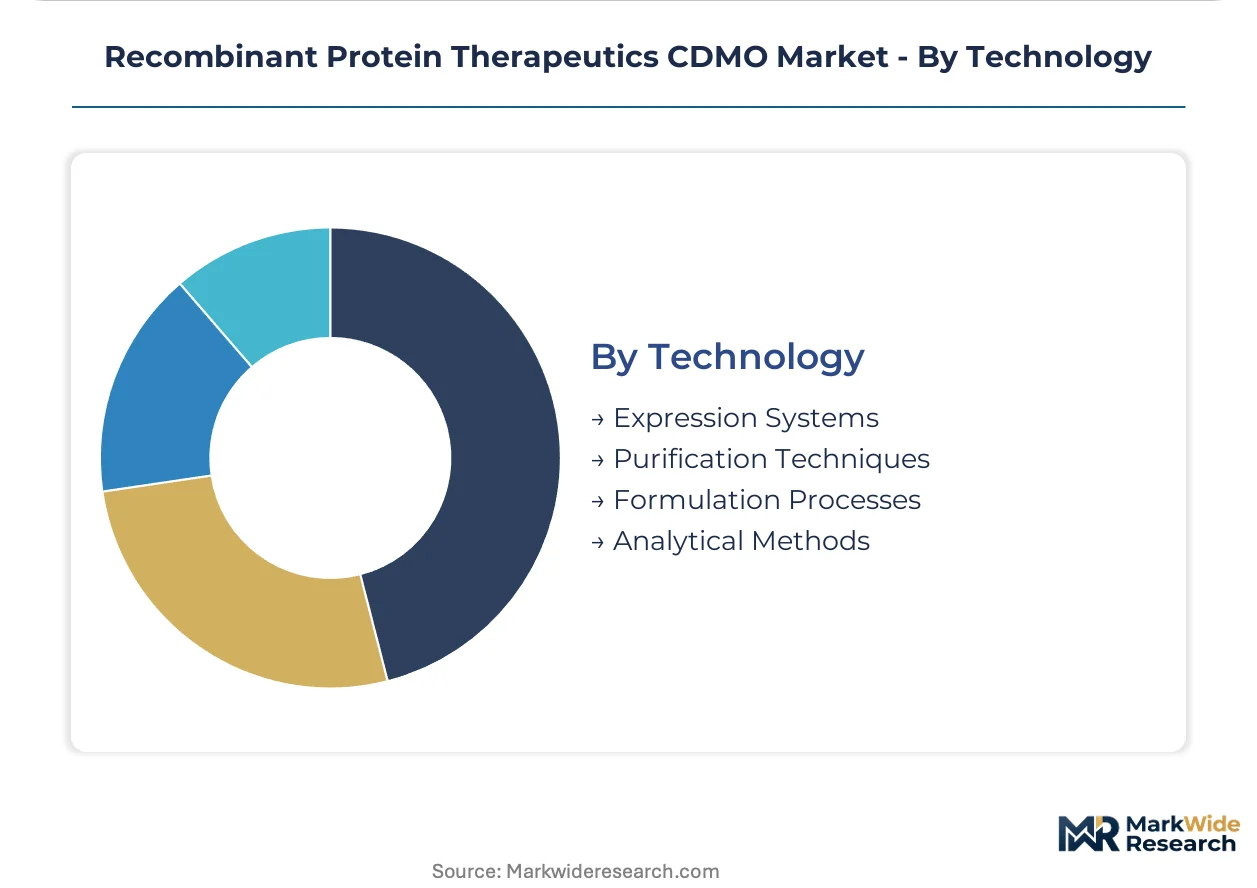
Technology:
Platform maturity separates validated mammalian expression systems from emerging continuous processing formats, with supply concentration in Boston, Basel, and Shanghai clusters determining access economics.
- Expression Systems:Mammalian cell culture dominates complex glycoprotein production, while microbial platforms in China sustain cost advantages for simpler proteins. Baculovirus-insect and yeast systems occupy niche positions for virus-like particle and peptide manufacturing.
- Purification Techniques:Protein A affinity chromatography anchors monoclonal antibody workflows, with multimodal and mixed-mode resins gaining traction for multispecific antibody formats requiring novel separation selectivity.
- Formulation Processes:Lyophilization and high-concentration liquid fill-finish capabilities determine parenteral protein stability and shelf-life performance.
- Analytical Methods:Mass spectrometry and capillary electrophoresis support biosimilar comparability protocols mandated by EMA and FDA guidelines.
Expression systems absorb the greatest capital investment; purification techniques are the steepest expansion trajectory as novel formats complicate downstream processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Switzerland and the United States demonstrate low price elasticity for complex glycoprotein manufacturing, while Chinese procurement teams aggressively negotiate unit costs for microbial-derived proteins. India represents an emerging middle ground where CDSCO reforms are attracting capacity investments without Western labor cost structures.
United States
FDA process validation requirements and biosimilar approval pathways sustain demand for CDMOs with established regulatory inspection histories. The Inflation Reduction Act's drug pricing provisions are compressing margins for originator sponsors, accelerating outsourcing decisions. Greater Boston anchors the highest concentration of multi-thousand-liter mammalian cell culture capacity serving oncology monoclonal antibody programs.
Switzerland
Swissmedic's stringent GMP enforcement and proximity to European pharmaceutical headquarters sustain premium pricing for high-complexity manufacturing. Basel's industrial cluster integrates chemical synthesis with biological production, enabling end-to-end therapeutic protein supply chains. Lonza leverages this infrastructure for large-scale fed-batch operations serving global oncology markets.
China
NMPA drug registration reforms and dual carbon goals are reshaping facility qualification timelines for domestic CDMOs. Shanghai's Pudong district concentrates single-use perfusion capacity targeting Phase III material supply for venture-funded biotechs. WuXi Biologics operates integrated campuses combining microbial and mammalian expression systems at cost positions below Western competitors.
Germany
EMA Annex 1 sterile manufacturing requirements are diverting capital toward environmental monitoring upgrades rather than net capacity expansion. Bavaria and Baden-Württemberg host specialized viral vector and protein manufacturing facilities serving European clinical trial supply. Richter-Helm BioLogics occupies a position within this regulatory-intensive environment.
India
CDSCO manufacturing license reforms and PLI scheme incentives for biopharmaceuticals are attracting mammalian cell culture investments previously concentrated in Western markets. Maharashtra and Gujarat are emerging as preferred locations for GMP facilities targeting export markets. Cost advantages in microbial expression systems are drawing enzyme and hormone manufacturing contracts from price-sensitive sponsors.
Recombinant Protein Therapeutics CDMO Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale-driven mammalian platforms commanding multi-year supply agreements while boutiques capture early-phase process development work. The competitive landscape bifurcates between stainless-steel fed-batch operators and single-use perfusion specialists, each pursuing irreversible capital commitments before securing long-term contracts. Three archetypes dominate: full-service integrators with regulatory dossier depth, geography-focused cost leaders, and modality-specific boutiques. M&A activity concentrates on acquiring analytical characterization capabilities, while capacity expansion focuses on continuous bioprocessing technologies.
Among Switzerland-based integrated operators, Lonza exemplifies the full-service archetype with large-scale mammalian infrastructure spanning multiple continents. WuXi Biologics represents the geography-focused cost leader, leveraging Chinese integrated campuses for competitive positioning in microbial and mammalian systems. FUJIFILM Diosynth Biotechnologies occupies a specialization position, differentiating through viral vector and protein manufacturing capabilities across European and North American facilities. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Lonza |
| Catalent |
| WuXi Biologics |
| FUJIFILM Diosynth Biotechnologies |
| Curia Global |
| Batavia Biosciences |
| HALIX |
| Richter-Helm BioLogics |
| BIOVIAN |
| Others |
Value Network & Pricing Analysis
Ninety-day cell-line development lead times concentrate pricing power among CDMOs with validated mammalian platforms in Switzerland and the United States, while Chinese microbial specialists compete on unit cost for simpler proteins. Stainless-steel bioreactor depreciation schedules and single-use consumables sourcing costs create divergent margin structures across geographic clusters.
Pricing Analysis
Multi-year commercial supply agreements anchor lifetime value, with process development services commanding premium rates due to lengthy cell-line optimization timelines. Three-tier pricing structure across premium, standard, and economy levels separates FDA-inspected mammalian facilities from pre-qualified microbial sites and non-GMP research-grade suppliers. Cost compression in standard-tier microbial manufacturing is intensifying because Chinese CDMOs leverage integrated campus economics. Biotechnology firms exhibit highest price sensitivity for early-phase work, while large-cap pharmaceutical sponsors prioritize regulatory inspection history over unit cost.
Supply Chain Analysis
Port congestion on transpacific lanes and semiconductor shortages for bioreactor automation systems are extending equipment delivery timelines for Chinese capacity expansions. Stainless-steel bioreactor hardware draws from German and Swiss precision engineering clusters, while single-use consumables feed from United States polymer suppliers and Chinese membrane manufacturers. Single-source vulnerability concentrates in bioreactor control systems and chromatography resins. Distribution runs through just-in-time logistics networks anchored by Boston, Basel, and Shanghai cold-chain hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell line development talent scarcity constrains facility expansion timelines, with hybrid molecular biology and bioprocess engineering skill gaps widening faster than training pipeline capacity across all major production clusters.
For Market Incumbents: Compound regulatory dossier depth across FDA, EMA, and NMPA jurisdictions to defend against emerging Indian CDMOs with CDSCO fast-track advantages. Prioritize analytical characterization capability acquisitions over stainless-steel capacity additions. Anchor multi-year supply agreements with large-cap pharmaceutical sponsors before single-use perfusion platforms commoditize Phase III manufacturing.
For New Entrants and Emerging Players: CDSCO manufacturing license reforms offer the fastest certification pathway for mammalian cell culture capabilities targeting export markets. White-space opportunities concentrate in multispecific antibody purification workflows and continuous bioprocessing platform development. Pursue boutique process development contracts from venture-funded biotechs seeking speed-to-IND over established regulatory track records.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because analytical characterization capabilities and multi-jurisdiction inspection histories are accumulating in fewer integrated operators. Target CDMOs with proven viral vector or protein manufacturing specialization and existing FDA warning letter clearance. Watch EMA Annex 1 compliance timeline compression as the inflection signal for facility upgrade capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Expansion | Multi-jurisdiction FDA, EMA, and NMPA filings accelerate sponsor vendor qualification timelines. |
| Continuous Bioprocessing Adoption | Perfusion-based mammalian platforms reduce facility footprint while maintaining volumetric productivity. |
| Analytical Capability Acquisition | Mass spectrometry and capillary electrophoresis assets support biosimilar comparability mandates. |
| Single-Use Platform Deployment | Flexible bioreactor configurations attract capital-constrained biotechnology sponsors for Phase III supply. |
| Geographic Capacity Diversification | India CDSCO reforms enable cost-competitive mammalian production without Western labor structures. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA filings, EMA submissions, ClinicalTrials.gov records, and CDSCO manufacturing license databases. Interviews with drug development executives, regulatory affairs leads, bioprocess engineering directors, and hospital procurement managers informed capacity utilization and vendor selection criteria. Bottom-up facility capacity modeling triangulated against top-down sponsor outsourcing expenditure patterns.
Segmentation dimensions modeled include service type, product format, expression system technology, and end-user scale across the analysis window. CAGRs derive from facility expansion announcements, sponsor pipeline progression rates, and regulatory approval velocity. Forecast inputs incorporate stainless-steel versus single-use platform adoption curves and EMA Annex 1 compliance capital diversion effects.
Underlying assumptions cover sustained biopharmaceutical outsourcing trends and stable regulatory framework enforcement, with deviation risk concentrated in Chinese equipment import constraints and cell line development talent pipeline capacity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
A - Estradiol Market
Biopharmaceuticals
Human Combinatorial Antibody Libraries (Hucal) Market
Biopharmaceuticals
North America Diabetes Drugs Market
Biopharmaceuticals
Tuberculosis Drugs Market
Biopharmaceuticals
Europe Monoclonal Antibodies Market
Biopharmaceuticals
Global Oncology/Cancer Drugs Market
Biopharmaceuticals
Global Swine Fever Vaccine Market
Biopharmaceuticals
North America Generic Oncology Drug Market
Biopharmaceuticals
China Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Human Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Anti-Infective Drugs Market
Biopharmaceuticals
Global Biopharma Buffer Market
Biopharmaceuticals
Brazil Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Pegylated Proteins Market
Biopharmaceuticals
Oncology Drugs Market
Biopharmaceuticals
Insulin Market