
 Human Insulin Drugs and Delivery Devices Market | 2026-2036
Human Insulin Drugs and Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Human Insulin Drugs and Delivery Devices Market Analysis
Recombinant human insulin is shifting toward biosimilar analogs with modified amino acid sequences that extend pharmacokinetic profiles and reduce hypoglycemic risk. Novo Nordisk A/S leverages its integrated fermentation-to-fill manufacturing footprint across Denmark and the United States to sustain supply security. Eli Lilly and Company anchors its position through concentrated R&D spending on glucose-responsive insulin formulations. Sanofi competes via established channel relationships with European hospital systems and pharmacy benefit managers.
Human insulin drugs and delivery devices comprise biologically active peptide hormones produced through recombinant DNA technology in microbial or mammalian cell cultures, formulated for parenteral administration to regulate blood glucose in diabetic patients, with delivery systems engineered for dose precision, patient adherence, and reduced injection burden. Insulin pens occupy the largest product category due to portability and dose accuracy, while insulin pumps represent the fastest-expanding segment as closed-loop artificial pancreas systems mature. Subcutaneous delivery dominates by mode, though transdermal microneedle patches are gaining investigational traction for needle-averse populations.
FDA bioequivalence pathways and EMA biosimilar guidelines shape product approval timelines, manufacturing quality standards, and interchangeability designations that determine pharmacy-level substitution. The EU MDR and FDA 21 CFR Part 820 impose escalating post-market surveillance and device software validation requirements on connected pumps and continuous glucose monitor integrations. Stakeholders must monitor regulatory divergence between FDA and EMA on biosimilar interchangeability and software-as-medical-device classifications to anticipate compliance costs and market access barriers.
Market Dynamics
Closed-loop artificial pancreas systems are compressing the distinction between insulin delivery and continuous glucose monitoring, forcing device manufacturers to integrate sensor algorithms with pump hardware or cede market position to platform specialists.
Growth Catalysts
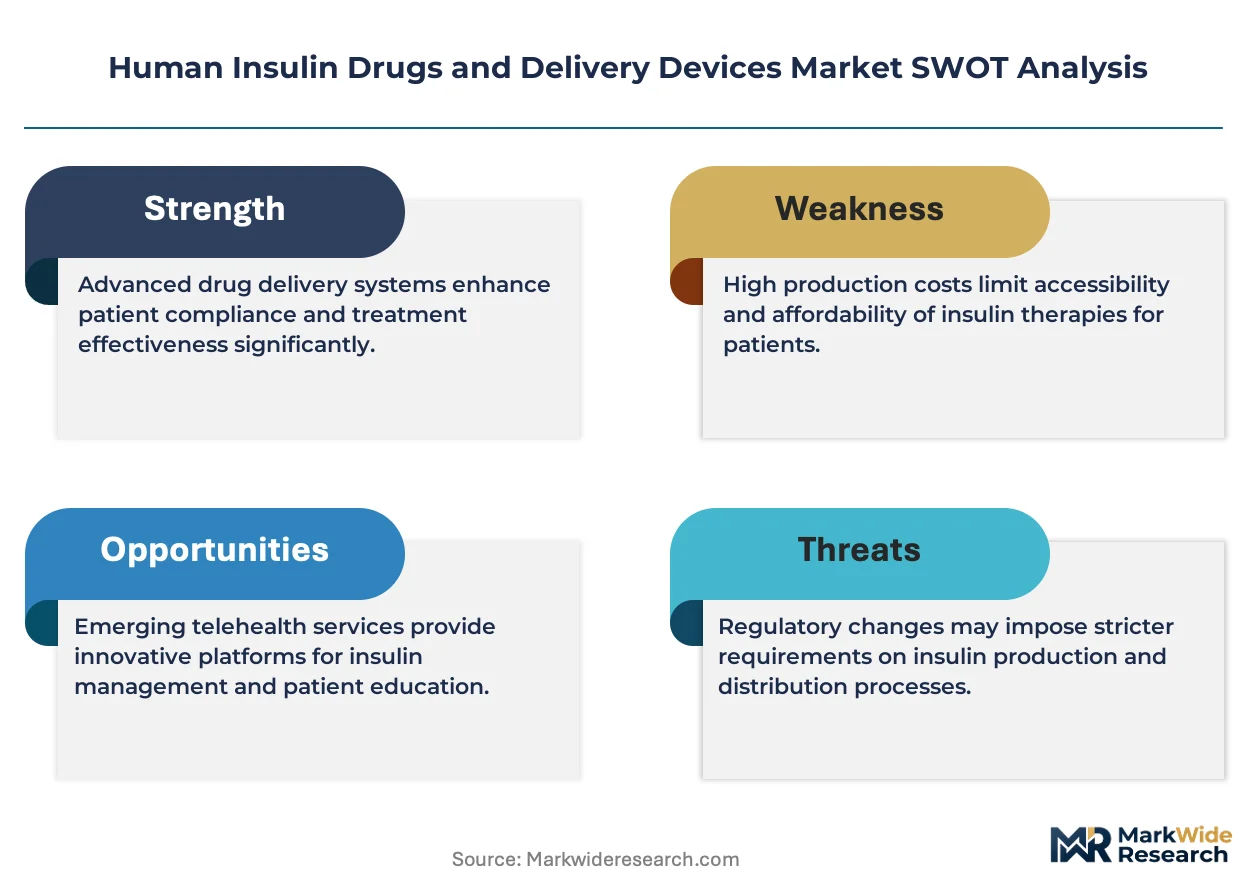
- Medicare Part D insulin price caps:The United States federal policy eliminates cost-sharing for covered insulin products, expanding patient access volumes and stabilizing demand predictability for manufacturers.
- Glucose-responsive insulin formulations:Smart insulin analogs that activate in hyperglycemic conditions reduce hypoglycemic episodes, improving therapeutic safety profiles and expanding addressable patient populations.
- Hospital glycemic management protocol upgrades:Inpatient insulin delivery system procurement is accelerating as acute care facilities implement standardized protocols to reduce hyperglycemia-associated complications.
Market Restraints
- Recombinant protein manufacturing concentration:Fermentation capacity for insulin active pharmaceutical ingredients concentrates in Denmark and the United States, creating supply vulnerability from single-site disruptions.
- FDA-EMA biosimilar interchangeability divergence:Divergent regulatory standards for pharmacy-level substitution create market access friction and compliance cost duplication for multi-territory launches.
- Transdermal microneedle patch technical limitations:Insulin bioavailability through microneedle arrays remains below subcutaneous injection thresholds, constraining adoption among needle-averse populations.
Strategic Opportunities
- Underpenetrated connected pump adoption in India:Type 1 diabetes populations in urban centers present expansion potential for smartphone-integrated delivery systems as private insurance coverage expands.
- EU MDR software-as-medical-device pathway:The European regulatory framework creates first-mover advantage for manufacturers validating algorithm-driven dose adjustment applications.
- Subscription-based insulin delivery service models:Direct-to-consumer channels combining device, consumables, and remote monitoring are displacing traditional pharmacy distribution in employer-sponsored health plans.
Industry Challenges
- Bioprocess engineering talent scarcity:Specialized expertise in microbial fermentation scale-up and downstream purification is concentrated among legacy manufacturers, constraining new entrant production ramp.
- Continuous glucose monitor-pump integration certification timelines:FDA 21 CFR Part 820 software validation requirements extend development cycles for closed-loop systems, compressing competitive windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Insulin Drugs and Delivery Devices Market |
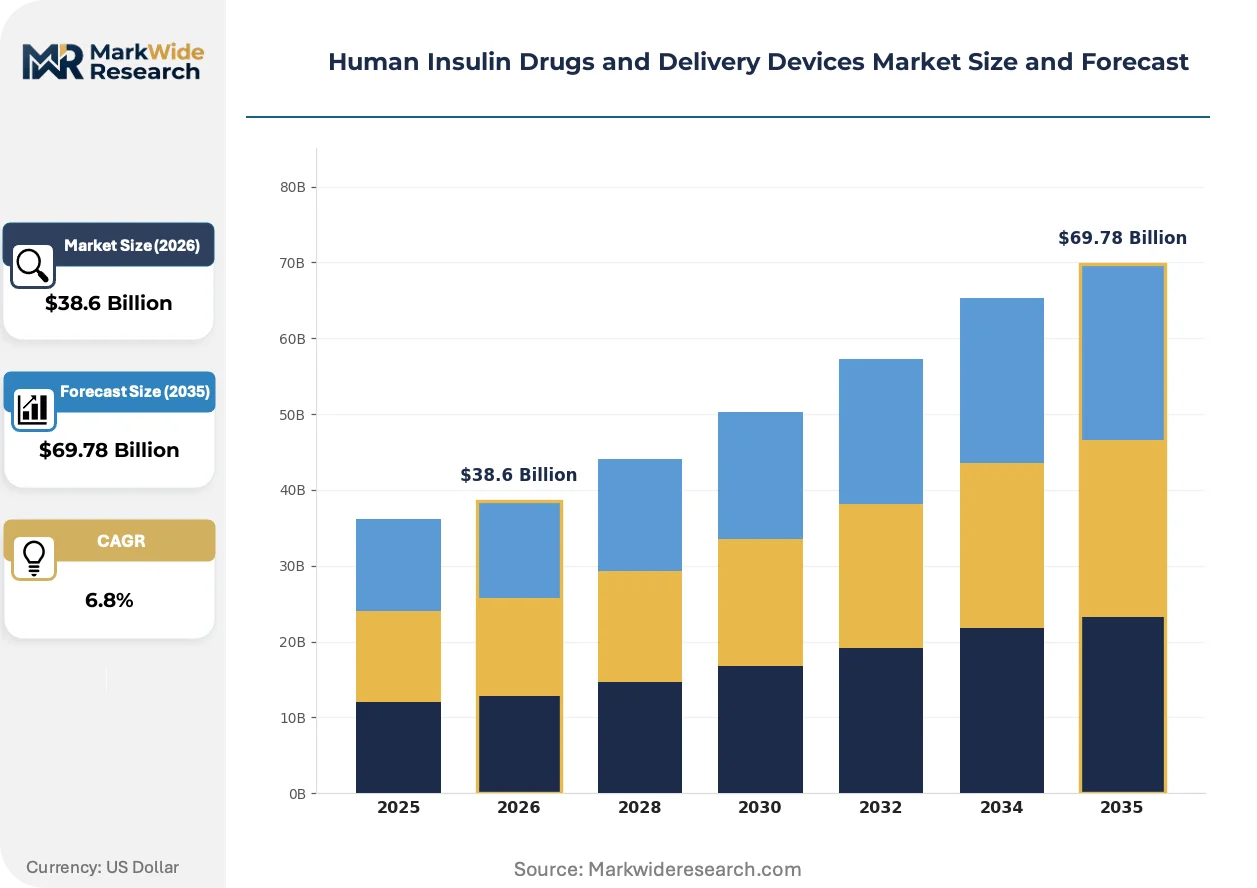
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pens, Insulin Pumps, Inhalable Insulin, Vials Delivery Mode: Subcutaneous, Intravenous, Intramuscular, Transdermal End User: Hospitals, Clinics, Home Care, Pharmacies Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes |
| Companies Covered | Novo Nordisk A/S, Sanofi, Eli Lilly and Company, Medtronic plc, Embecta Corp., Insulet Corporation, Ypsomed AG, Tandem Diabetes Care, Inc., Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Insulin Drugs and Delivery Devices Market Emerging Trajectories
Algorithm-driven dose optimization is displacing static basal-bolus protocols across both pump and pen delivery modalities, embedding machine learning into everyday diabetes management workflows.
Closed-loop control systems is automating insulin delivery adjustments through real-time sensor feedback, eliminating manual carbohydrate counting for many users. Pediatric endocrinology practices in the United States are adopting these platforms fastest, driven by caregiver demand for overnight hypoglycemia protection. The technology is compressing differentiation among pump manufacturers toward software reliability and sensor integration depth rather than hardware mechanics.
The FDA's updated bioequivalence standards for biosimilar insulin analogs are reshaping competitive dynamics by establishing clearer interchangeability pathways. Manufacturers must now generate switching study data to support pharmacy-level substitution, raising development costs but accelerating post-patent market entry. The United States retail pharmacy channel is responding with preferred formulary tiers that favor interchangeable products.
Remote patient monitoring integration is altering how endocrinologists prescribe and adjust insulin therapy. Telehealth platforms now incorporate pump data downloads and continuous glucose monitor trend reports, replacing quarterly in-person visits with algorithm-flagged intervention triggers. This pattern is most visible in United States Medicare Advantage plans, where capitated reimbursement incentivizes proactive glycemic management.
Human Insulin Drugs and Delivery Devices Market Segmentation
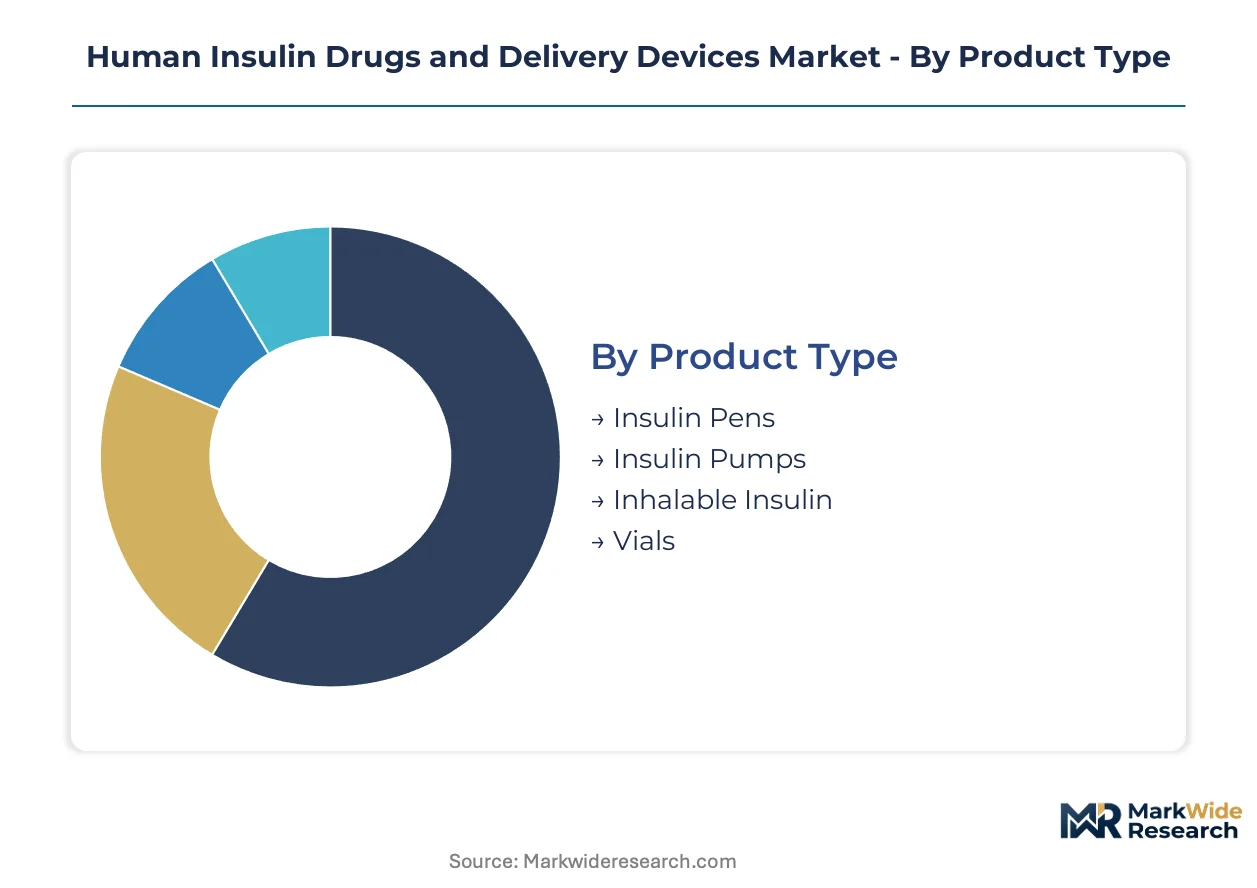
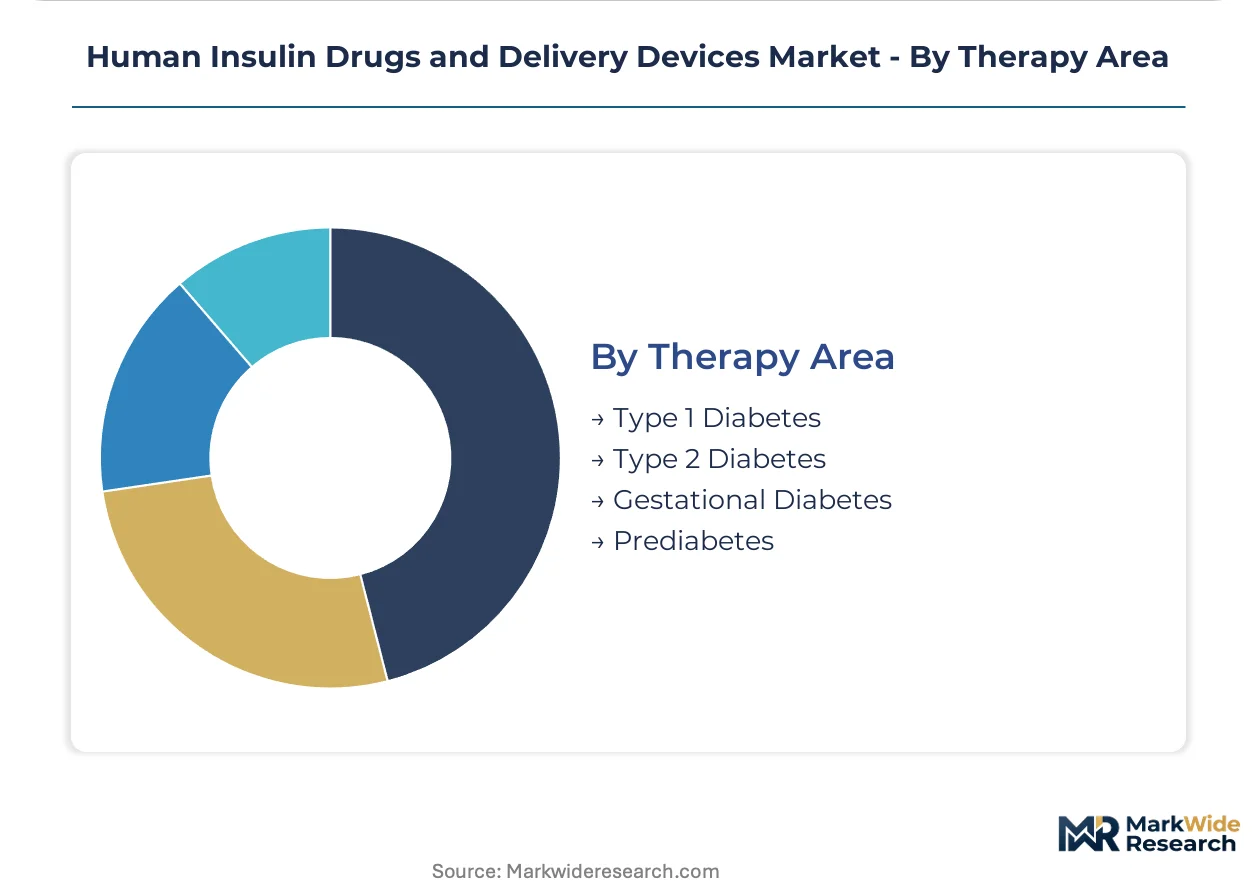
Segmentation in the human insulin market reveals how therapeutic requirements, patient lifestyle constraints, and care settings shape procurement decisions across devices and formulations. Manufacturers align R&D investments and distribution strategies to these distinct demand profiles.
Product Type:
Patient mobility needs and dosing complexity separate buyers into convenience-driven versus precision-controlled segments.
- Insulin Pens:Portable, multi-dose injection devices with dial-a-dose functionality dominate outpatient self-administration. United States Medicare Part D price caps sustain volume leadership in retail pharmacy channels where refill adherence matters most.
- Insulin Pumps:Continuous subcutaneous infusion systems with programmable basal rates address intensive insulin regimens. Closed-loop artificial pancreas integration is accelerating adoption among pediatric endocrinology practices seeking overnight hypoglycemia protection.
- Inhalable Insulin:Pulmonary delivery formulations eliminate injection burden for needle-averse Type 2 populations.
- Vials:Multi-dose glass containers with syringe compatibility serve cost-sensitive hospital inpatient protocols.
Insulin pens lead volumes today; insulin pumps are climbing the fastest as sensor integration matures.
Delivery Mode:
Absorption kinetics and patient technique tolerance determine route selection across acute and chronic care contexts.
- Subcutaneous:Adipose tissue injection via pen, pump, or syringe delivers controlled absorption for basal and bolus coverage. Home care settings in the United States favor this mode for its established reimbursement pathways and patient training infrastructure.
- Intravenous:Direct bloodstream administration achieves immediate glucose correction in critical care. Hospital ICU departments rely on IV insulin protocols for diabetic ketoacidosis management where minute-to-minute titration is essential.
- Intramuscular:Faster absorption than subcutaneous for emergency hypoglycemia reversal.
- Transdermal:Microneedle arrays and permeation enhancers investigate non-invasive alternatives.
Subcutaneous delivery commands current volume; transdermal approaches show steepest expansion trajectory in development pipelines.
End User:
Reimbursement structure and clinical oversight intensity segment procurement between institutional and direct-to-patient channels.
- Hospitals:Acute care facilities with glycemic management protocols procure infusion pumps and concentrated insulin for inpatient hyperglycemia control. CMS quality metrics for surgical complication rates are driving standardized protocol upgrades across United States health systems.
- Clinics:Outpatient endocrinology practices manage pump starts and dose titrations. United States telehealth expansion is shifting follow-up volumes toward remote monitoring platforms integrated with continuous glucose data.
- Home Care:Self-managed patients with private insurance or Medicare coverage drive pen and disposable pump consumable demand.
- Pharmacies:Retail and specialty dispensers handle interchangeable biosimilar substitution under FDA interchangeability designations.
Hospitals anchor institutional procurement today; home care is gaining share fastest as remote patient monitoring reduces clinic dependency.
Therapy Area:
Disease progression stage and residual beta-cell function dictate insulin dependence severity and device sophistication requirements.
- Type 1 Diabetes:Absolute insulin deficiency mandates lifelong exogenous replacement with intensive regimens. Pediatric populations in the United States and Europe drive premium pump adoption where caregiver oversight and overnight safety concerns justify technology investment.
- Type 2 Diabetes:Progressive beta-cell failure creates expanding insulin initiation need among oral agent failures. United States Medicare cost-sharing elimination is removing access barriers for older adults transitioning to basal insulin.
- Gestational Diabetes:Pregnancy-specific glycemic targets require rapid-acting mealtime coverage when diet modification fails.
- Prediabetes:Early pharmacologic intervention investigates insulin sensitization and beta-cell preservation strategies.
Type 2 Diabetes generates largest patient volumes today; Type 1 Diabetes is expanding most quickly on a percentage basis as closed-loop technology penetrates pediatric segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark's Kalundborg insulin fermentation cluster anchors global active pharmaceutical ingredient capacity, with secondary manufacturing nodes in the United States and Switzerland shaping regional supply security. National reimbursement frameworks and regulatory divergence now determine market access velocity across major economies.
United States
Medicare Part D insulin price caps eliminated patient cost-sharing, expanding volumes through retail pharmacy channels. FDA's updated bioequivalence standards for biosimilar interchangeability are reshaping formulary tier placement. Indianapolis and the Research Triangle Park concentration anchor domestic formulation and device engineering.
Germany
Hospital glycemic management protocol standardization drives infusion pump procurement across acute care networks. EMA biosimilar guidelines and EU MDR software-as-medical-device pathways create compliance complexity for connected delivery systems. Baden-Württemberg's medical technology corridor concentrates device manufacturing and algorithm development.
China
Type 2 diabetes prevalence expansion and private insurance penetration create demand for pen-based delivery systems in urban centers. NMPA streamlined biosimilar approval pathways are accelerating domestic insulin analog entry. Shanghai and Suzhou biotech clusters host fermentation capacity investments from multinational and local manufacturers.
India
Type 1 diabetes populations in Mumbai, Delhi, and Bangalore present underpenetrated connected pump adoption potential as employer-sponsored coverage expands. CDSCO regulatory harmonization with ICH guidelines is reducing approval lag for imported sensor-integrated devices. Gujarat's pharmaceutical manufacturing belt concentrates fill-finish operations for regional supply.
Switzerland
Swissmedic's stringent device software validation requirements create competitive barriers for algorithm-driven dose adjustment platforms. Basel's pharmaceutical and precision engineering convergence supports hybrid drug-device combination product development. Geneva-based health technology assessment bodies influence European reimbursement precedent for closed-loop systems.
Human Insulin Drugs and Delivery Devices Market Vendor Landscape
Strategic partnerships dominate the current landscape as device manufacturers integrate continuous glucose monitoring algorithms with pump hardware. The market structure concentrates around three legacy fermentation-to-fill integrators and a tier of specialized pump and pen fabricators. Two strategic archetypes define positioning: vertically integrated biologics manufacturers controlling active pharmaceutical ingredient supply, and platform specialists assembling sensor-pump-data ecosystems. Competitive moves center on algorithm licensing arrangements and hospital system procurement consolidation.
Within the integrated biologics tier, Novo Nordisk A/S and Sanofi exemplify archetypes of fermentation capacity control and European channel depth respectively. Eli Lilly and Company occupies a position representing concentrated R&D allocation toward glucose-responsive formulations. Among device-focused specialists, Medtronic plc and Insulet Corporation sit within the sensor-pump integration vector, while Tandem Diabetes Care, Inc. and Ypsomed AG represent algorithm-first and European pharmacy channel archetypes respectively.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Sanofi |
| Eli Lilly and Company |
| Medtronic plc |
| Embecta Corp. |
| Insulet Corporation |
| Ypsomed AG |
| Tandem Diabetes Care, Inc. |
| Becton, Dickinson and Company |
| Others |
Supply Flow & Price Mechanics
Closed-loop system premiumization versus commodity pen pricing creates a bifurcation that manifests in divergent margin structures and supply security investments across the insulin delivery landscape. FDA interchangeability designations for biosimilar analogs compress pricing power in retail pharmacy channels while sensor-integrated pump ecosystems command sustained premiums through software subscription bundling.
Pricing Analysis
Recombinant protein fermentation costs pass through to finished product pricing with limited elasticity, as Novo Nordisk A/S and Eli Lilly and Company anchor contract-based long-term offtake agreements with United States pharmacy benefit managers. Price differentiation separates premium closed-loop systems with algorithm-driven dose adjustment from standard pen-and-vial configurations, with certification level serving as the primary tiering mechanism. Cost compression in interchangeable biosimilar tiers is intensifying because Medicare Part D price caps eliminate patient cost-sharing buffers. Employer-sponsored health plans demonstrate highest price sensitivity, while pediatric endocrinology practices show lowest sensitivity due to overnight hypoglycemia protection requirements.
Supply Chain Analysis
Direct-to-hospital channels handle acute care procurement of infusion pumps and concentrated insulin, while retail pharmacy distribution runs through three-step wholesale networks for outpatient pen and vial fulfillment. Geographic supply concentration centers on Denmark's Kalundborg fermentation cluster, with secondary nodes in the United States and Switzerland providing formulation and device engineering capacity. Raw material dependencies include recombinant yeast cell lines, chromatography resins for downstream purification, and precision-machined pump components. Single-source vulnerability from Denmark's concentrated active pharmaceutical ingredient production creates structural exposure to site-specific disruptions from regulatory enforcement or biosecurity events.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Human Insulin Drugs and Delivery Devices Market represents a late-cycle quality story where demand migrates toward closed-loop artificial pancreas systems with algorithm-driven safety profiles. This shift rewards manufacturers with validated software-as-medical-device pathways and punishes commodity pen producers facing biosimilar price compression.
For Market Incumbents: To counter emerging platform specialists assembling sensor-pump-data ecosystems, legacy fermentation-to-fill integrators should deepen backward integration into continuous glucose monitor algorithm licensing and secure hospital system procurement consolidation through glycemic management protocol partnerships. Capacity addition in United States formulation sites reduces tariff exposure and shortens distribution lead times for Medicare-covered populations. For New Entrants and Emerging Players: Needle-averse Type 2 diabetes populations in employer-sponsored health plans present an underserved buyer archetype for transdermal microneedle patch development, with private insurance expansion in Indian urban centers offering secondary penetration potential. A direct-to-consumer subscription model combining device, consumables, and remote monitoring bypasses traditional pharmacy distribution chokepoints. For Investors and Strategic Acquirers: Consolidation pressure builds where algorithm development talent concentrates among legacy pump manufacturers lacking glucose-responsive insulin formulation pipelines. Long-term viability favors vertically integrated biologics manufacturers with captive fermentation capacity and validated EU MDR software pathways. The signal to watch is FDA interchangeability designation velocity for biosimilar analogs, which accelerates formulary tier displacement and compresses margin pools for non-integrated competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Licensing Agreement | Partnerships with continuous glucose monitor specialists accelerate closed-loop system certification timelines under FDA 21 CFR Part 820. |
| Hospital System Partnership | Glycemic management protocol standardization across United States acute care networks locks in infusion pump procurement volumes. |
| EU MDR Software-as-Medical-Device Pathway | First-mover validation of dose adjustment applications creates reimbursement precedent for algorithm-driven delivery platforms. |
| Manufacturing Scale-Up | Fermentation capacity expansion in Denmark and United States addresses supply vulnerability from single-site concentration. |
| Reimbursement Strategy | Medicare Advantage capitated contracts incentivize proactive glycemic management through remote patient monitoring integration. |
Methodological Framework
Direct dialogue with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists grounded qualitative insights in operational reality. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and CMS Medicare data. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates across the analysis window.
Segmentation outputs reflect discrete modeling of delivery mode, end-user setting, therapy area, and regional regulatory cluster throughout the projection horizon. CAGRs were derived from insulin initiation rates, pump penetration curves, and biosimilar substitution velocity. Forecast inputs incorporated Medicare Part D enrollment trajectories, EU MDR implementation timelines, and NMPA biosimilar pathway maturation.
Underlying measurement precision varies by segment; closed-loop system forecasts carry tighter precision than transdermic patch development pipelines due to commercial availability differentials. Forecasts reflect documented assumptions regarding regulatory harmonization progress and reimbursement policy continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Large Macrolide Drugs Market
Biopharmaceuticals
Global Bispecific Antibody Market
Biopharmaceuticals
Global Kinase Inhibitors Market
Biopharmaceuticals
Rapid Acting Insulin Market
Biopharmaceuticals
North America Monoclonal Antibody Market
Biopharmaceuticals
Norethisterone Enanthate API Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
Clindamycin Phosphate Market
Biopharmaceuticals
Coagulation Factor IX Market
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
Global Lenalidomide Market
Biopharmaceuticals
Canada Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Biopharmaceutical CMO and CRO Market
Biopharmaceuticals
Plasmid DNA Manufacturing Market
Biopharmaceuticals
Global Cytokine Market
Biopharmaceuticals
Global Topical Antibiotics Market