
 Global Pegylated Proteins Market | 2026-2036
Global Pegylated Proteins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pegylated Proteins Market Foresight
Modular contract manufacturing arrangements for pegylated biologics is recalibrating how biopharmaceutical buyers source conjugation services. Thermo Fisher Scientific leverages its integrated CDMO footprint to capture multi-site production contracts across North America and Europe. NOF Corporation anchors supply of activated polyethylene glycol reagents through proprietary polymer synthesis capabilities in Japan. JenKem Technology specializes in custom PEGylation architectures for niche therapeutic proteins with complex glycosylation patterns.
Pegylated proteins are therapeutic macromolecules covalently modified with polyethylene glycol chains to extend circulating half-life, reduce immunogenicity, and improve solubility through steric stabilization of the protein core. The PEGylation process typically employs N-hydroxysuccinimide ester chemistry or maleimide-thiol coupling to attach 20–40 kDa polymer branches at lysine residues or engineered cysteine sites. Mono pegylated proteins dominate current revenue pools due to established manufacturing reproducibility and regulatory familiarity in oncology applications. Multi pegylated proteins represent the fastest-expanding configuration as developers pursue enhanced pharmacokinetic profiles for subcutaneous administration in autoimmune disorders.
FDA's Center for Drug Evaluation and Research maintains rigorous comparability protocols for PEGylated biologics while EMA's Committee for Medicinal Products for Human Use enforces batch-to-batch polymer consistency standards under the MDR framework. Japan's PMDA applies supplementary JIS quality benchmarks for imported PEG reagents used in domestic protein conjugation. Stakeholders must monitor evolving polymer impurity thresholds and regional divergence in biosimilar interchangeability rules to protect development timelines and commercial access.
Market Dynamics
Specialized conjugation infrastructure is consolidating around multi-site CDMO networks as biopharmaceutical developers outsource complex PEGylation to capture regulatory expertise and polymer supply security. This structural concentration is reshaping competitive positioning across the value chain.
Growth Catalysts
- FDA biosimilar pathway streamlining:The abbreviated approval framework for follow-on biologics accelerates development timelines for pegylated protein candidates targeting oncology and autoimmune indications.
- Subcutaneous administration demand:Autoimmune therapy developers prioritize multi-pegylated architectures to enable patient self-injection and reduce clinic visit burden.
- Japan polymer synthesis concentration:Domestic activated PEG reagent manufacturing anchors regional supply security and reduces import dependency for Asia-Pacific bioconjugation facilities.
Market Restraints
- Activated PEG reagent cost volatility:Proprietary polymer synthesis requires pharmaceutical-grade raw materials subject to supply tightness and purification complexity.
- Single-source supplier risk:Niche activated PEG derivatives concentrate with limited qualified manufacturers, creating vulnerability in multi-site production planning.
- Batch-to-batch polymer consistency requirements:EMA MDR framework enforces stringent impurity thresholds that complicate scale-up and technology transfer between facilities.
Strategic Opportunities
- India biopharma manufacturing expansion:CDSCO regulatory alignment with ICH guidelines creates openings for pegylated biosimilar production targeting export markets.
- Site-specific PEGylation convergence:Engineered cysteine insertion combined with maleimide-thiol coupling enables homogeneous product profiles previously unattainable with lysine chemistry.
- Germany specialized manufacturing clusters:Rhine-Main and Munich biotech corridors offer integrated conjugation-analytical capabilities for complex glycoprotein modification.
Industry Challenges
- Analytical method transfer complexity:PEGylated protein characterization requires specialized size-exclusion chromatography and mass spectrometry expertise scarce across contract manufacturing networks.
- Comparability protocol execution:Post-approval manufacturing changes demand extensive immunogenicity and pharmacokinetic bridging studies that extend regulatory review timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pegylated Proteins Market |
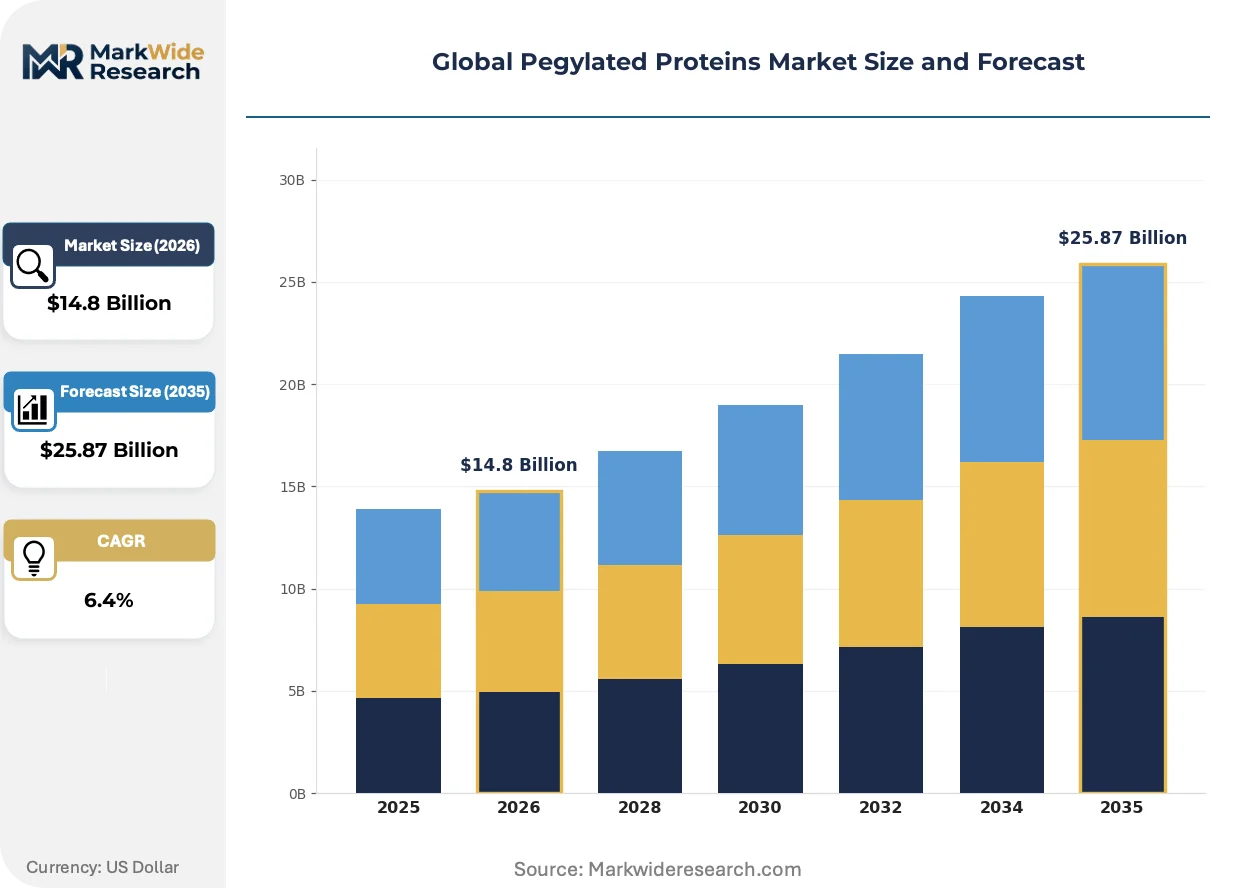
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mono Pegylated Proteins, Multi Pegylated Proteins, Conjugated Proteins, Polymer Conjugates Therapy Area: Oncology, Infectious Diseases, Autoimmune Disorders, Hematology Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral End User: Hospitals, Research Laboratories, Biopharmaceutical Companies, Clinics |
| Companies Covered | Merck KGaA, Thermo Fisher Scientific, NOF Corporation, JenKem Technology, Creative PEGworks, Celares GmbH, Laysan Bio, Amgen Inc., Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pegylated Proteins Market Shifts & Advancements
Process intensification and regulatory science advances are compressing development cycles while expanding the therapeutic scope of protein PEGylation beyond established oncology applications.
Branched PEG architectures with 40 kDa molecular weight are absorbing share from linear 20 kDa configurations as developers pursue extended half-life for subcutaneous autoimmune therapies. Rheumatology and dermatology biologics units at mid-cap biopharmaceutical firms are adopting these structures at accelerated pace. This absorption is compressing differentiation timelines for first-generation mono-pegylated products in competitive therapeutic categories.
EMA MDR batch-to-batch consistency requirements are tightening polymer impurity specifications for imported PEG reagents used in European protein conjugation. Manufacturers must implement enhanced analytical release testing and supplier qualification protocols. Oncology-focused CDMOs with established EMA rapporteur relationships are capturing disproportionate share of new molecule contracts as compliance costs rise.
Integrated service contracts bundling polymer supply, conjugation manufacturing, and regulatory filing support are displacing fragmented procurement of discrete PEGylation services. Biopharmaceutical development teams prioritize single-accountability partnerships over multi-vendor coordination. This consolidation is most visible in United States and Germany, where specialized CDMOs with captive PEG reagent supply are securing exclusive multi-year agreements.
Global Pegylated Proteins Market Segmentation
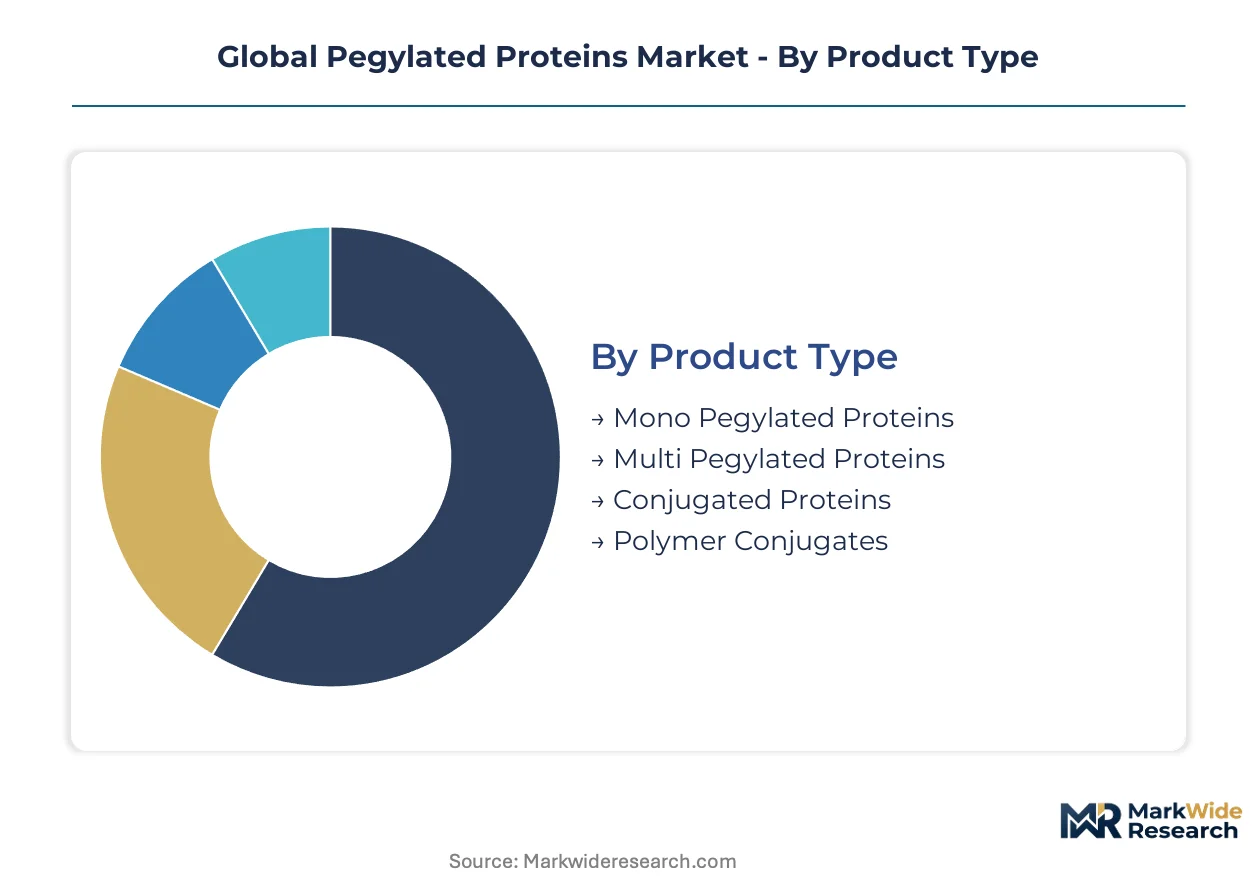
Pegylated protein architectures diverge sharply in manufacturing complexity and regulatory pathway, with conjugation chemistry and therapeutic application determining supply chain configuration and commercial access. Understanding these segment boundaries clarifies where capacity investments concentrate and which configurations face steepest technical barriers.
Product Type:
Activated PEG reagent supply concentrates with specialized polymer manufacturers in Japan and the United States, with conjugation service providers calibrating infrastructure investments to specific protein architectures.
- Mono Pegylated Proteins:Single polymer attachment at lysine residues or engineered cysteine sites yields homogeneous product profiles with established analytical release protocols. Oncology biologics developers in the United States and Germany anchor demand for these structures due to regulatory familiarity and reproducible pharmacokinetic bridging studies.
- Multi Pegylated Proteins:Branched 40 kDa architectures attach multiple polymer chains to extend half-life for subcutaneous administration. Autoimmune therapy units at mid-cap biopharmaceutical firms in Germany and Japan are expanding procurement of these configurations to enable patient self-injection and reduce clinic visit burden.
- Conjugated Proteins:Covalent linkage of therapeutic proteins to synthetic carriers beyond standard PEGylation, requiring specialized coupling chemistries and extended impurity profiling.
- Polymer Conjugates:Complex macromolecular assemblies incorporating multiple therapeutic or diagnostic moieties, demanding integrated analytical capabilities scarce across contract manufacturing networks.
Mono pegylated proteins absorb the bulk of installed capacity; multi pegylated proteins are expanding most quickly.
Therapy Area:
Clinical trial design and reimbursement frameworks vary substantially across therapeutic categories, with regulatory precedent and payer dynamics shaping developer prioritization of PEGylation investments.
- Oncology:Extended circulating half-life for cytotoxic protein conjugates supports reduced dosing frequency and improved patient compliance. FDA's streamlined biosimilar pathway accelerates development timelines for follow-on pegylated oncology biologics, with CDMOs in the United States capturing multi-site production contracts.
- Autoimmune Disorders:Subcutaneous administration enabled by branched PEG architectures reduces healthcare system burden and supports patient self-management. EMA MDR batch-to-batch consistency requirements tighten polymer impurity specifications for European protein conjugation facilities serving this category.
- Infectious Diseases:PEGylated interferon and antiviral proteins target chronic viral infections, with manufacturing scale-up constrained by comparability protocol complexity.
- Hematology:Coagulation factor modification requires precise glycosylation preservation alongside PEG attachment, limiting qualified manufacturing sites.
Oncology commands the deepest manufacturing experience; autoimmune disorders are climbing the fastest as subcutaneous delivery reshapes competitive positioning.
Delivery Mode:
Route of administration determines polymer molecular weight selection, formulation stability requirements, and patient access logistics, with subcutaneous delivery driving the steepest architectural innovation.
- Intravenous:Established administration route for oncology pegylated proteins, with hospital-based infusion infrastructure supporting higher molecular weight polymer tolerability.
- Subcutaneous:Branched 40 kDa PEG configurations enable patient self-injection for autoimmune therapies, with volume demand concentrating in Germany and Japan where specialized manufacturing clusters support complex glycoprotein modification.
- Intramuscular:Limited application for depot-formulation pegylated proteins, with injection site reaction profiles constraining therapeutic scope.
- Oral:Experimental delivery route facing enzymatic degradation barriers, with current development confined to preclinical and early-phase programs.
Intravenous delivery retains the largest procedure volume; subcutaneous administration is gaining share fastest as patient convenience drives formulary positioning.
End User:
Procurement authority and technical sophistication vary across customer types, with integrated service contracts displacing fragmented sourcing as biopharmaceutical developers prioritize single-accountability partnerships.
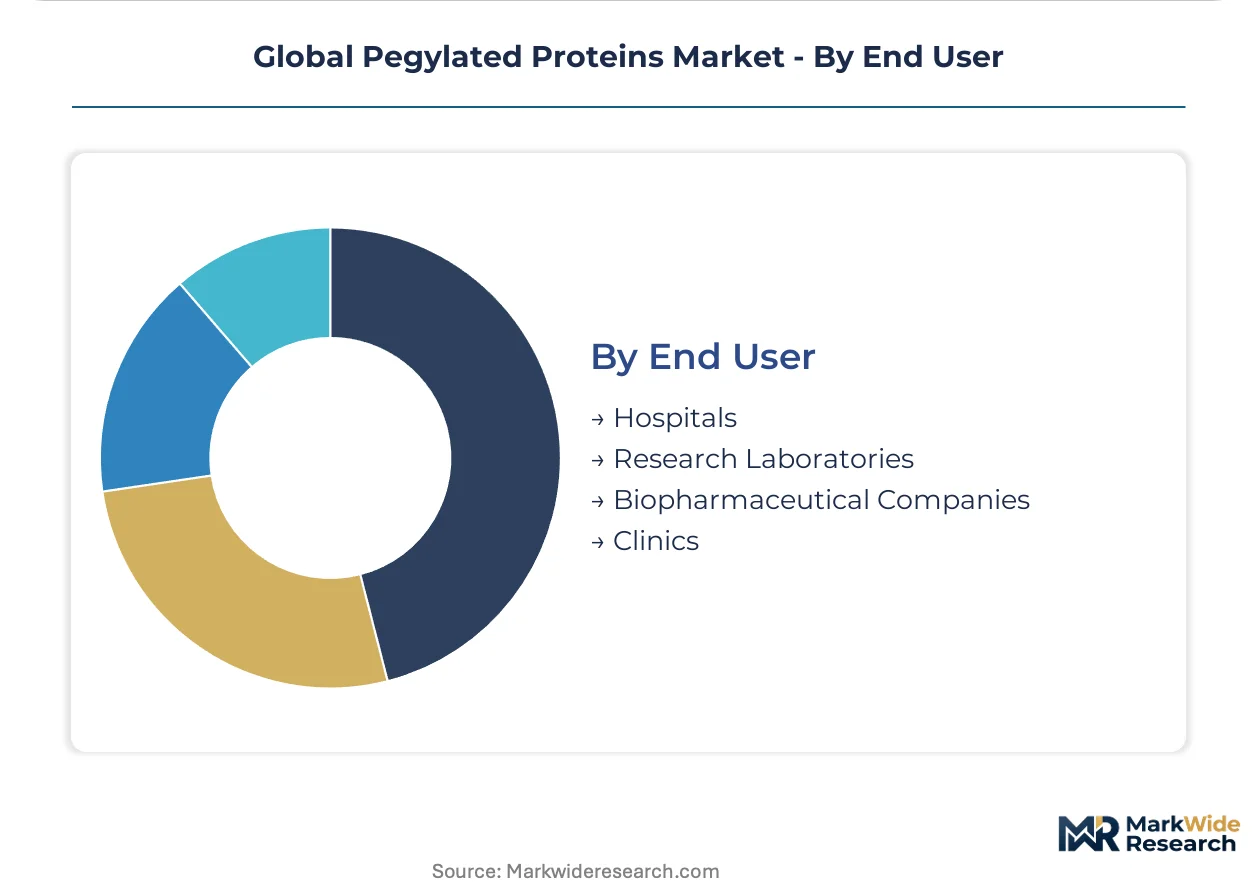
- Biopharmaceutical Companies:Originators and biosimilar developers source conjugation services through multi-year exclusive agreements with CDMOs offering captive PEG reagent supply. Thermo Fisher Scientific leverages its integrated footprint to capture contracts across North America and Europe.
- Hospitals:Institutional purchasers of infused oncology pegylated proteins, with procurement decisions influenced by payer reimbursement frameworks and therapeutic interchangeability protocols.
- Research Laboratories:Academic and government facilities utilize custom PEGylation architectures for investigative protein modification, with demand fragmented across small-batch specialty suppliers.
- Clinics:Outpatient settings for subcutaneous autoimmune therapy administration, with patient self-injection training programs reducing direct clinical involvement.
Biopharmaceutical companies direct the largest procurement value; research laboratories are expanding most quickly as site-specific conjugation technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized economic zones in Massachusetts, Bavaria, and Kansai concentrate PEGylation infrastructure through tax-advantaged research parks and accelerated regulatory review corridors. These jurisdictions attract biopharmaceutical developers seeking proximity to qualified CDMO networks and polymer synthesis capabilities.
United States
FDA's Center for Drug Evaluation and Research streamlines biosimilar pathways for oncology pegylated proteins, cutting approval timelines for follow-on biologics. The IRA Medicare price negotiation framework pressures developers to optimize manufacturing costs through multi-site production contracts. Greater Boston's Kendall Square corridor anchors conjugation-analytical capabilities for complex glycoprotein modification.
Germany
EMA MDR batch-to-batch consistency requirements tighten polymer impurity specifications for protein conjugation facilities serving autoimmune therapy developers. The country's national pharmaceutical regulator enforces stringent comparability protocols that extend technology transfer timelines between manufacturing sites. Rhine-Main and Munich biotech corridors integrate captive PEG reagent supply with regulatory filing support under single-accountability partnerships.
Japan
PMDA supplementary JIS quality benchmarks for imported PEG reagents protect domestic protein conjugation supply security. METI industrial clustering programs concentrate activated polymer synthesis in Kansai and Kanto regions, reducing import dependency for Asia-Pacific bioconjugation facilities. Osaka-based manufacturers anchor regional supply of pharmaceutical-grade polyethylene glycol derivatives.
India
CDSCO regulatory alignment with ICH guidelines creates openings for pegylated biosimilar production targeting export markets to Europe and the United States. The PLI scheme for pharmaceuticals incentivizes domestic conjugation infrastructure investment. Maharashtra and Gujarat pharmaceutical corridors attract multi-year exclusive agreements with integrated CDMOs offering captive PEG reagent supply.
United Kingdom
MHRA post-Brexit divergence from EMA MDR frameworks creates dual-track compliance requirements for PEGylated protein developers accessing both UK and European markets. The country's national pharmaceutical regulator maintains comparability protocols that demand extensive immunogenicity bridging studies. London-Southeast biotech clusters specialize in site-specific PEGylation technologies for engineered cysteine insertion programs.
Global Pegylated Proteins Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the pegylated proteins value chain, creating a tiered structure where scale-driven service providers capture multi-site production contracts while niche polymer architects secure premium pricing for custom activated reagents. The vendor base organizes around three strategic archetypes: integrated CDMOs with captive PEG supply, specialized polymer manufacturers with proprietary synthesis capabilities, and originator biopharmaceutical companies with in-house conjugation infrastructure. Dominant competitive moves include backward integration into activated PEG reagent production and exclusive multi-year service contracts bundling polymer supply with regulatory filing support.
Among diversified life science conglomerates, Thermo Fisher Scientific occupies a position exemplifying integrated CDMO scale across North America and Europe. NOF Corporation represents the specialized polymer synthesis archetype, anchoring Japanese supply of activated polyethylene glycol reagents through proprietary manufacturing capabilities. JenKem Technology sits within the custom architecture tier, serving niche therapeutic proteins with complex glycosylation patterns through specialized PEGylation chemistries.
| Leading Market Players |
|---|
| Merck KGaA |
| Thermo Fisher Scientific |
| NOF Corporation |
| JenKem Technology |
| Creative PEGworks |
| Celares GmbH |
| Laysan Bio |
| Amgen Inc. |
| Pfizer Inc. |
| Others |
Supply & Pricing Matrix
Specialized polymer chemists in Osaka and Kansai anchor global activated PEG synthesis capacity, with labor-cost differentials between Japanese specialist facilities and emerging Indian conjugation sites driving 40-60% pricing-tier spreads across equivalent polymer grades.
Pricing Analysis
Short-lead-time premiums of 15-25% apply to spot purchases of pharmaceutical-grade activated PEG reagents, while contract-based long-term offtake agreements secure volume discounts for multi-site biopharmaceutical manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-audited CDMO supply from GMP-compliant regional sources and research-grade material. Pricing pressure stems from EMA MDR batch-to-batch consistency requirements that escalate analytical release testing costs. Biosimilar developers in India exhibit highest price sensitivity; originator oncology biologics units in Germany and the United States demonstrate lowest sensitivity due to reimbursement protection.
Supply Chain Analysis
Activated PEG reagent supply rests on Japanese specialty chemical producers, with secondary concentration in United States and German polymer synthesis facilities. Pharmaceutical-grade ethylene oxide feedstock, succinimidyl ester activation reagents, and branched 40 kDa polymer scaffolds constitute critical input dependencies. Single-source vulnerability concentrates in niche maleimide-activated derivatives qualified for site-specific cysteine conjugation. Distribution runs through integrated CDMO networks bundling polymer supply with conjugation manufacturing, displacing fragmented multi-vendor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EMA MDR batch-to-batch consistency requirements erect barrier-to-entry moats favoring CDMOs with established rapporteur relationships and captive analytical infrastructure.
For Market Incumbents: Lock in exclusive multi-year service contracts with mid-cap biopharmaceutical developers before site-specific PEGylation technologies mature and displace conventional lysine chemistry demand. Backward integration into activated PEG reagent production protects margin compression from NOF Corporation and JenKem Technology supply concentration. Prioritize capacity expansion in Germany's Rhine-Main corridor to capture autoimmune therapy subcutaneous administration contracts requiring branched 40 kDa architectures. For New Entrants and Emerging Players: Begin with CDSCO-aligned pegylated biosimilar production in Maharashtra and Gujarat pharmaceutical corridors, targeting export markets to Europe and the United States where regulatory familiarity accelerates approval timelines. Site-specific PEGylation services for engineered cysteine insertion programs represent the most penetrable white-space segment, with London-Southeast biotech clusters underserved for homogeneous product profile development. Pursue licensing partnerships with Japanese polymer manufacturers to secure activated reagent supply without proprietary synthesis investment. For Investors and Strategic Acquirers: Re-rating potential sits with integrated CDMOs offering captive PEG reagent supply given FDA biosimilar pathway streamlining and IRA Medicare price negotiation framework compressing manufacturing cost tolerance. Long-term viability favors players with multi-site production footprints spanning United States and European regulatory jurisdictions. Watch EMA MDR impurity threshold tightening as the signal indicating which CDMOs can absorb compliance cost escalation versus forced exit.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA streamlined biosimilar framework accelerates pegylated protein development timelines for oncology indications. |
| Backward Integration | CDMOs acquiring proprietary polymer synthesis capabilities reduce dependency on NOF Corporation and JenKem Technology. |
| Manufacturing Scale-Up | Multi-site production contracts across North America and Europe capture biopharmaceutical outsourcing demand. |
| Site-Specific PEGylation Development | Maleimide-thiol coupling expertise enables homogeneous product profiles for subcutaneous autoimmune therapies. |
| Geographic Expansion | India's PLI scheme and CDSCO alignment create export-oriented pegylated biosimilar production capacity. |
Research Methodology
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov records, and CDSCO regulatory circulars, complemented by interviews with drug development executives, regulatory affairs leads, and CDMO procurement managers. Secondary validation drew from SEC 10-K disclosures, customs trade data, and formulary databases. Bottom-up and top-down triangulation cross-referenced polymer supply volumes against conjugation service contract values.
Historical volume trajectories were cross-referenced against expert panel input across therapy area, product architecture, and regional regulatory cluster dimensions. CAGRs were derived from segment-level growth rate reconciliation throughout the forecast period. Forecast inputs incorporated PMDA JIS quality benchmark evolution and METI industrial clustering program allocations.
Underlying measurement precision varies by segment; mono pegylated proteins carry tighter precision than multi pegylated proteins given established manufacturing reproducibility. Forecasts reflect assumptions about regulatory pathway stability and polymer impurity threshold convergence. EMA MDR enforcement intensity, IRA Medicare negotiation expansion, and site-specific PEGylation technology maturation warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Mammalian Polyclonal Igg Antibody Market
Biopharmaceuticals
Proteinuria Therapeutics Market
Biopharmaceuticals
Bio-Active Peptides Market
Biopharmaceuticals
Europe Insulin Pens Market
Biopharmaceuticals
North America Generic Oncology Drug Market
Biopharmaceuticals
Plasmid DNA Manufacturing Market
Biopharmaceuticals
Anti-Neoplastic Pharmaceutical Agents Market
Biopharmaceuticals
Global Drug Discovery Market
Biopharmaceuticals
Insulin Delivery Pens Market
Biopharmaceuticals
Bromodomain and Extraterminal Domain (BET) Inhibitors Market
Biopharmaceuticals
Global Antibody Market
Biopharmaceuticals
H1N1 Vaccines Market
Biopharmaceuticals
Germany Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Antibody Drug Conjugates Market
Biopharmaceuticals
Clindamycin Phosphate Market
Biopharmaceuticals
Mefentrifluconazole Market