
 Pates Market | 2026-2036
Pates Market Size, Share, and Industry Trends Forecast 2026-2036
Pates Market Intelligence
The shift towards asset-light production models, utilizing co-packers and third-party logistics, is reconfiguring the competitive landscape for artisanal producers. This approach lowers capital barriers, challenging established firms. For example, Henaff leverages its strong brand heritage and production control in France. Meanwhile, Rougie specializes in premium pates for the global food service channel, and Alexian Pates develops a diverse portfolio for the US retail market.
Pates are savory spreads or pies containing a forcemeat of finely minced meat, poultry, fish, or vegetables. The mixture, often enriched with fat and spices, is typically baked in a terrine to create a firm texture. While traditional meat-based pates command the largest market share, veggie pates show significant expansion driven by dietary shifts. In packaging, glass jars and tins are prevalent for premium and shelf-stable offerings, signaling quality to consumers.
Food safety standards from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) dictate processing, handling, and import requirements. Additionally, rules on geographical indications and animal welfare, like France's 'Label Rouge' certification, shape sourcing and consumer trust. The primary challenge for producers involves adapting formulations to meet clean-label demands without compromising traditional flavor profiles.
Market Dynamics
The central dynamic shaping the pates market is the tension between preserving traditional, rich flavor profiles and meeting modern consumer demands for clean-label products with transparent sourcing. This pressure, amplified by stringent food safety regulations from bodies like the US FDA, forces formulation and supply chain adjustments.
Growth Catalysts
- Premium Food Service Demand:Expansion within the global hospitality sector, particularly in fine dining restaurants and luxury hotels, drives consumption of high-end pates as gourmet appetizers and ingredients, signaling culinary sophistication.
- Plant-Based Diet Adoption:The increasing consumer shift towards vegetarian and flexitarian diets stimulates innovation and sales in the veggie pate category, which leverages ingredients like mushrooms, lentils, and nuts to mimic traditional textures.
- Geographical Indication Laws:Regulations such as the EU's Protected Geographical Indication (PGI) system allow producers in regions like France to certify authenticity, command premium pricing, and protect heritage products from imitation.
Market Restraints
- Input Cost Volatility:Producer margins are sensitive to price fluctuations for key raw materials, especially specialty meats like duck liver, pork, and game, which are subject to supply disruptions from animal diseases or feed costs.
- Strict Import Regulations:Complex sanitary and phytosanitary (SPS) measures enforced by authorities like the European Food Safety Authority (EFSA) create significant compliance hurdles and costs for exporting and importing meat-based pates.
- Competition from Alternatives:Pates compete for consumer spending and retail shelf space with a broad category of savory spreads, including hummus, cheese-based dips, and other plant-based alternatives that appeal to different dietary preferences.
Strategic Opportunities
- Expansion in Asia-Pacific Markets:Untapped demand exists in developed Asian economies like Japan and South Korea, where a growing middle class and interest in Western cuisine create openings for both premium imported and locally produced pates.
- Functional Ingredient Integration:Incorporating functional ingredients such as probiotics, omega-3 fatty acids, or plant-based proteins presents an opportunity to develop value-added pates that appeal to health-conscious consumers.
- Animal Welfare Certifications:Pursuing and marketing certifications related to humane animal treatment, beyond established standards like France's 'Label Rouge', can attract ethically-minded consumers and justify premium positioning in North American and European markets.
Industry Challenges
- Clean-Label Reformulation:A primary operational challenge is removing artificial preservatives and sodium from recipes to meet clean-label standards without compromising the product's shelf stability, safety, or traditional flavor profile.
- Supply Chain Traceability:Verifying the provenance of ingredients to substantiate claims of origin or adherence to animal welfare standards is complex and costly, particularly for producers sourcing from a fragmented network of farms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pates Market |
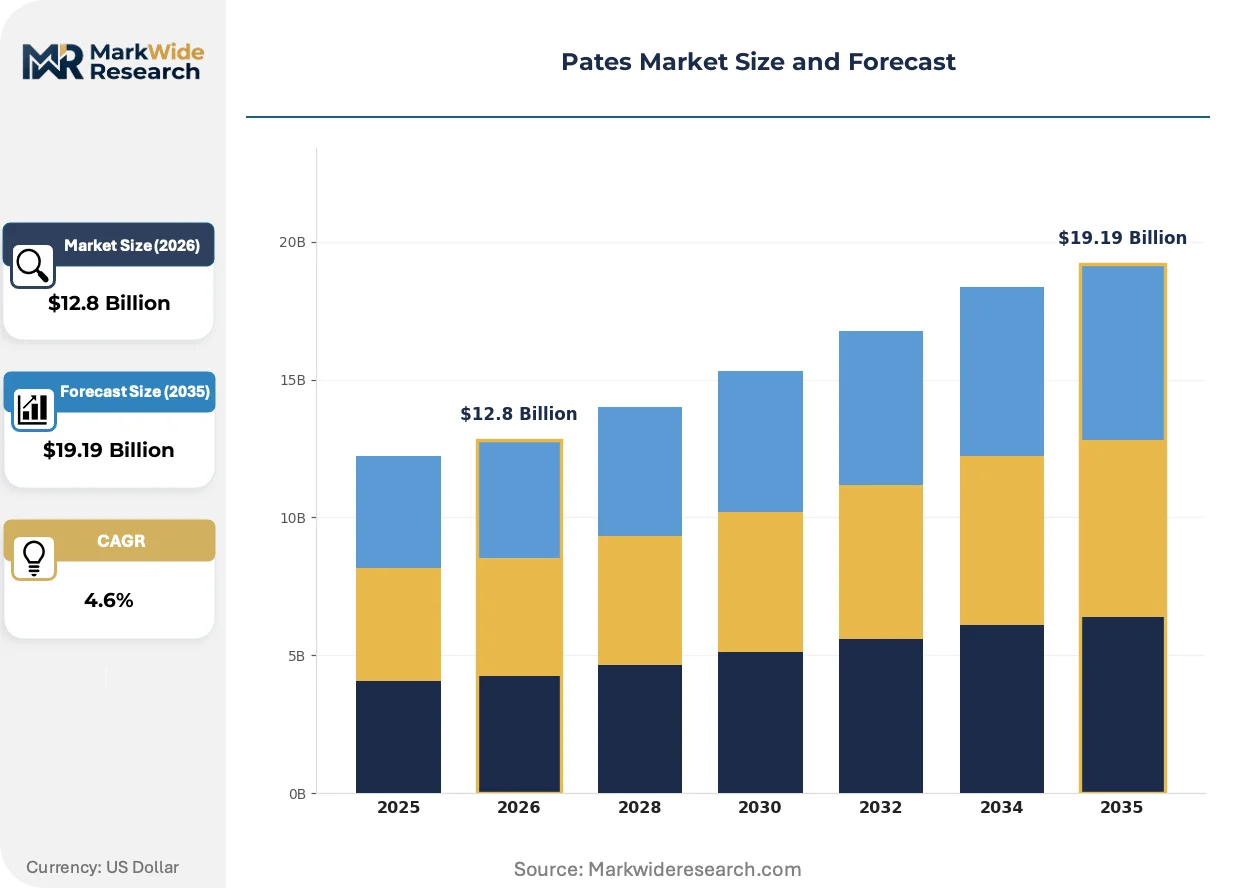
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Pates, Veggie Pates, Game Pates, Seafood Pates Packaging Type: Glass Jars, Tins, Plastic Containers, Vacuum Sealed Packs Flavor Profile: Herb-Infused, Spicy, Classic, Sweet Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Farmers Markets |
| Companies Covered | Alexian Pates, Henaff, Tesco Plc, Waitrose & Partners, Kinsale Bay Foods, Patchwork Traditional Foods, Rougie, Braehead Foods, Argeta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pates Market Strategic Shifts & Innovations
Product innovation is increasingly centered on reconciling artisanal quality with industrial-scale food safety and shelf-life requirements. This involves adopting new preservation technologies and adapting formulations to align with evolving regulatory and consumer expectations for ingredient transparency.
High-Pressure Processing (HPP) is a non-thermal pasteurization technique used to ensure food safety. Premium and artisanal producers are adopting HPP to create clean-label products without chemical preservatives. The market's preservation strategy is migrating from a heavy reliance on thermal treatment and additives toward HPP, which better preserves the delicate flavors and textures of high-end pates.
European Union regulations governing animal welfare and geographical indications continue to shape production standards. Frameworks like Protected Designation of Origin (PDO) enforce strict sourcing and processing rules for traditional products such as foie gras. This regulatory structure allows certified producers to protect brand equity and command higher prices, particularly affecting legacy manufacturers in France and Belgium.
A significant behavioral shift is the rise of direct-to-consumer (DTC) sales channels, enabled by e-commerce platforms. This trend allows small-batch and artisanal producers to bypass traditional retail distribution and connect directly with niche consumer segments. This movement is most visible in the US and UK, where food enthusiasts actively seek unique, story-driven products unavailable in mass-market grocery stores.
Pates Market Segmentation
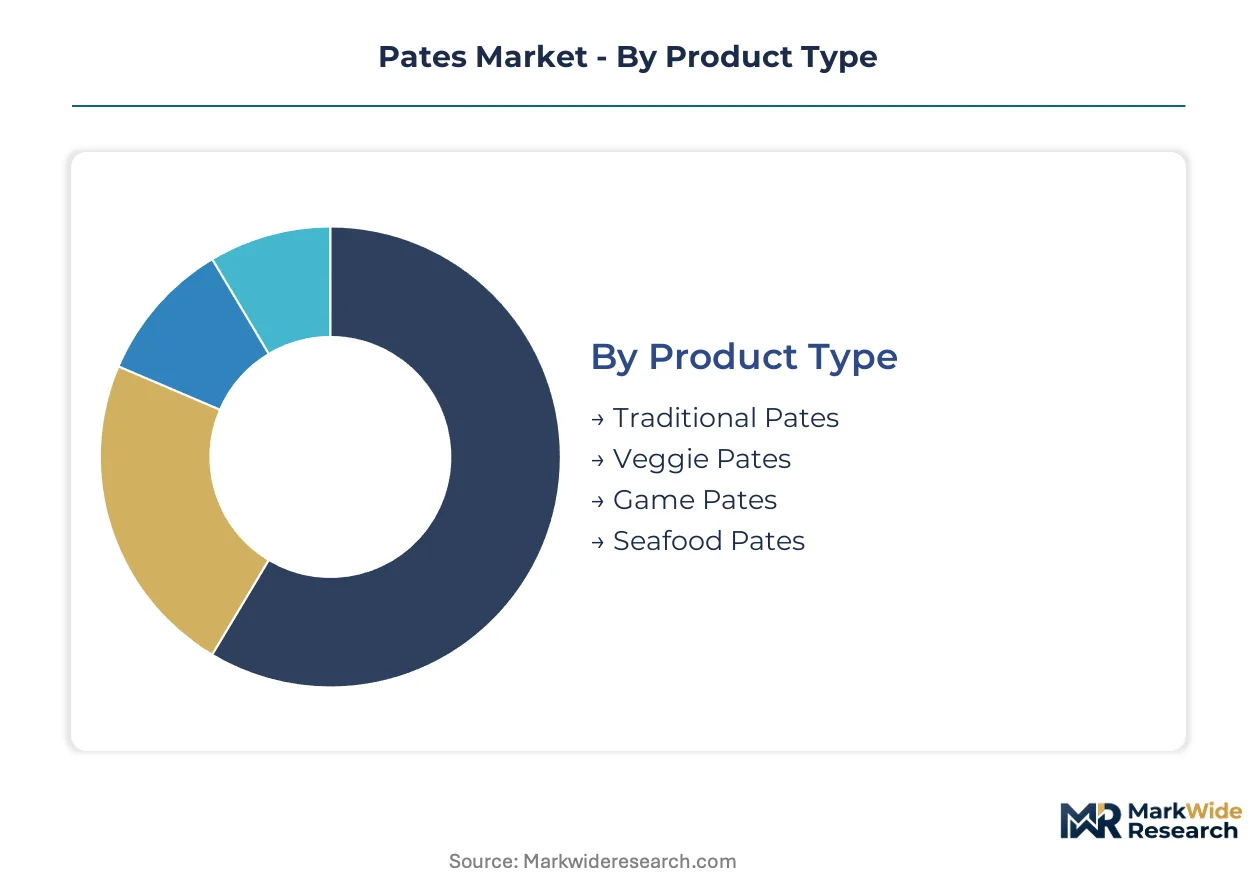
The pates market segmentation highlights diverse product offerings and consumer preferences shaping purchasing decisions. Understanding these distinct segments allows producers to tailor formulations, packaging, and distribution strategies effectively. This granular view clarifies market opportunities and competitive dynamics across various consumer touchpoints.
Product Type:
The use-case spectrum for pates ranges from daily consumption to gourmet applications, defining the varied product types available.
- Traditional Pates:These typically feature finely minced meat or liver, often pork or chicken, blended with fat and spices, baked in a terrine. Demand for these classic formulations concentrates within established European markets, particularly in France, driven by long-standing culinary heritage.
- Veggie Pates:Composed of plant-based ingredients such as mushrooms, lentils, or nuts, these pates mimic the texture and richness of meat-based alternatives. Their demand is expanding significantly in North American and European markets, stimulated by the global shift towards plant-based and flexitarian diets.
- Game Pates:These specialty products incorporate meats like duck, venison, or wild boar, offering richer and more distinctive flavor profiles.
- Seafood Pates:Featuring ingredients such as salmon, trout, or crab, these pates provide lighter and often briny taste experiences.
Established volume favors Traditional Pates; emerging adoption favors Veggie Pates.
Packaging Type:
Packaging choices reflect both preservation requirements and consumer perception of product quality and convenience in the market.
- Glass Jars:These containers offer excellent product visibility and convey a premium image, often used for artisanal and gourmet pate offerings. Demand for glass-jarred pates is strong in European specialty stores, where visual appeal and reusability resonate with discerning consumers.
- Tins:Providing superior shelf stability and protection from light and air, metal tins are ideal for long-term preservation of pates. Global food service channels frequently procure tinned pates for their extended shelf life and robust transport capabilities.
- Plastic Containers:These lightweight and often resealable options offer convenience and cost-effectiveness for everyday pate consumption.
- Vacuum Sealed Packs:Employed for fresh or refrigerated pates, these packs extend freshness by removing oxygen and preventing spoilage.
Premium offerings gravitate towards glass jars and tins, while everyday consumption leans into plastic containers for convenience.
Flavor Profile:
Flavor profiles dictate consumer appeal and product versatility, catering to diverse culinary preferences across geographies.
- Classic:These profiles typically feature balanced, savory notes derived from traditional meat bases like pork or chicken liver, often with subtle herbs and spices. Demand for classic pates remains foundational in French and Belgian markets, anchoring the traditional culinary landscape.
- Herb-Infused:Incorporating fresh or dried herbs such as thyme, rosemary, or parsley, these pates offer aromatic and often lighter taste experiences. These profiles are gaining traction in North American retail, appealing to consumers seeking sophisticated yet accessible flavors.
- Spicy:Pates with added chili, paprika, or other heat-inducing ingredients provide a bold and piquant taste sensation.
- Sweet:Less common, these pates might include fruits, honey, or port wine, offering a contrast to traditional savory options.
The largest segment volume resides with classic flavor profiles, while herb-infused varieties are gaining share fastest among new consumers.
Distribution Channel:
The distribution channel landscape reflects varying consumer access points and strategic market penetration for pate producers.
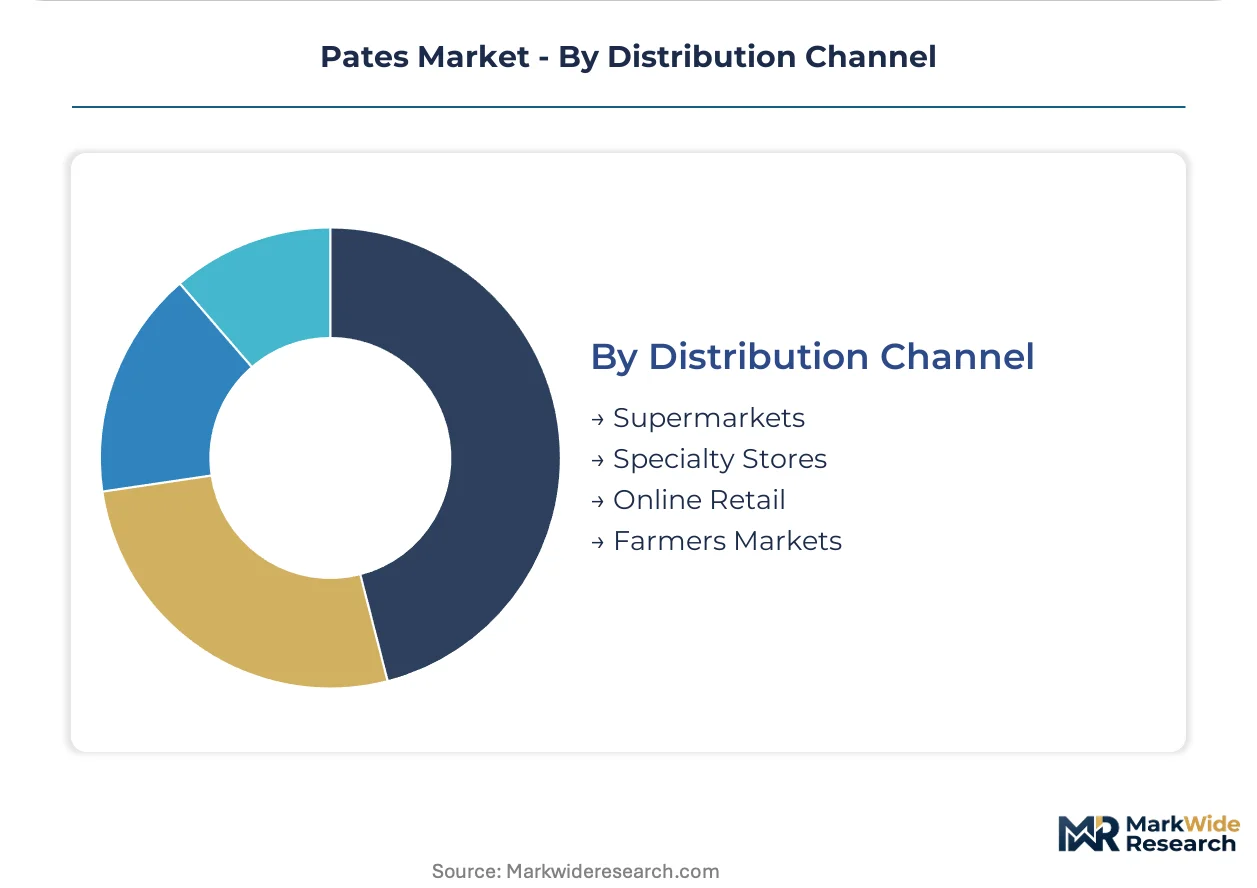
- Supermarkets:These large retail chains provide widespread availability and convenience, making pates accessible to a broad consumer base through mass-market placement. Supermarket sales drive volume in both European and North American markets, benefiting from high foot traffic and extensive product ranges.
- Online Retail:E-commerce platforms enable direct-to-consumer sales and provide access to niche or artisanal pates, bypassing traditional brick-and-mortar limitations. This channel exhibits the steepest expansion trajectory in the US and UK, as food enthusiasts seek unique, story-driven products.
- Specialty Stores:These outlets, including delis and gourmet food shops, cater to discerning consumers seeking premium, often locally sourced, pate selections.
- Farmers Markets:Offering direct interaction with producers, these markets are crucial for small-batch and artisanal pate makers to connect with local communities.
Supermarkets account for the largest sales volume, with online retail demonstrating significant growth potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global pates market exhibits a complex interplay of import and export dynamics, driven by localized culinary traditions and evolving consumer preferences. European nations traditionally lead in both production and consumption, while emerging markets increasingly focus on import growth. Export strategies often target regions with a growing appetite for Western gourmet foods.
France
French consumers maintain a foundational demand for traditional pates, particularly within fine dining and everyday consumption. The EU's Protected Geographical Indication (PGI) system helps producers certify authenticity and command premium pricing for heritage products. Manufacturers in Périgord focus on traditional foie gras production, protecting its cultural and economic value.
United States
United States retail demand for pates is expanding, driven by a diverse portfolio and plant-based alternatives. The US Food and Drug Administration (FDA) mandates strict food safety and labeling regulations for all pates. Specialty food manufacturers in California develop innovative veggie pates, targeting health-conscious consumers in urban centers.
Germany
German consumers show consistent demand for pates as part of convenience food and gourmet selections. European Food Safety Authority (EFSA) regulations govern processing and import requirements for meat-based pates. Major food manufacturers in Bavaria concentrate on producing shelf-stable tinned pates for widespread supermarket availability.
Japan
Japanese demand for pates is emerging, fueled by a growing middle class and interest in Western culinary traditions. Japan's Ministry of Health, Labour and Welfare (MHLW) establishes stringent food safety and import regulations. Food service distributors in Osaka focus on sourcing premium pates for high-end restaurants and specialty gourmet shops.
United Kingdom
United Kingdom consumers increasingly seek unique, story-driven pates through direct-to-consumer online channels. The UK Food Standards Agency (FSA) enforces food safety and hygiene standards for domestic production and imports. Artisanal food businesses in the Cotswolds region specialize in traditional game pates, selling through farmers' markets and online stores.
Pates Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, providing key ingredients. The pates market exhibits a tiered structure, with established firms coexisting with numerous artisanal producers. This structure differentiates between large-scale manufacturers focused on volume and smaller, specialized entities catering to premium niches. Competitive moves include portfolio diversification into plant-based options and strategic partnerships for distribution.
Within the premium and traditional pates segment, French-based Henaff exemplifies a brand leveraging strong heritage and integrated production control in France. Rougie, another French entity, occupies a position specializing in high-end pates for the global food service channel, catering to a sophisticated clientele. Meanwhile, Alexian Pates represents a player developing a diverse portfolio specifically for the United States retail market, reflecting adaptation to regional consumer preferences and dietary shifts.
| Leading Market Players |
|---|
| Alexian Pates |
| Henaff |
| Tesco Plc |
| Waitrose & Partners |
| Kinsale Bay Foods |
| Patchwork Traditional Foods |
| Rougie |
| Braehead Foods |
| Argeta |
Cost & Logistics Intelligence
Commodity volatility in specialty meats like duck liver significantly determines both pricing tier spreads and the overall supply chain shape for pates. This pressure forces producers to adjust formulations and sourcing strategies to maintain profitability across diverse market segments.
Pricing Analysis
Supermarket procurement teams anchor transactional pricing for mass-market pates, which are typically sold on a per-unit basis. Price differentiation stems from ingredient quality grade, such as certified organic components, and established brand premium, notably for heritage European labels. Pricing pressure stems from intense competition with alternative savory spreads, particularly in cost-sensitive retail channels. Mass-market consumers in large retail chains exhibit the highest price sensitivity, while fine dining establishments prioritize quality and origin over cost.
Supply Chain Analysis
Co-packers and third-party logistics providers concentrate manufacturing capacity for many artisanal pate brands, reducing capital expenditure for smaller producers. Geographic supply concentration for key ingredients remains strong in France for traditional forcemeats and Germany for shelf-stable tinned varieties. Raw material dependencies include specialty pork products and duck liver, which are susceptible to supply disruptions. Regulatory restrictions, such as strict sanitary and phytosanitary (SPS) measures enforced by the European Food Safety Authority (EFSA), represent a significant supply chain risk. Distribution runs through a dual model, with supermarkets handling volume and specialized food service channels serving premium markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pates market represents a culinary experience-attach opportunity, with curated gourmet food subscriptions expanding faster than individual product sales.
For Market Incumbents:
Entrench core market share by investing in clean-label reformulation, particularly for traditional meat-based pates, to meet evolving consumer expectations without compromising flavor profiles. Diversify product portfolios by expanding into innovative plant-based pate lines, leveraging existing distribution networks to counter competition from alternative spreads. Secure strategic sourcing agreements for specialty ingredients to mitigate input cost volatility and strengthen supply chain resilience against animal disease outbreaks.
For New Entrants and Emerging Players:
Pursue niche market opportunities by leveraging direct-to-consumer channels, especially in underserved Asia-Pacific markets like Japan and South Korea, where interest in Western gourmet foods is growing. Focus on developing unique, story-driven products with clear provenance, such as ethically sourced game pates or allergen-free veggie options. Emphasize animal welfare certifications or functional ingredient integration as key go-to-market angles to appeal to health-conscious consumers in North America and Europe.
For Investors and Strategic Acquirers:
The market sits at a mature phase with dynamic growth pockets that favors specialized innovators. Long-term viability is strong for brands that can adapt traditional offerings to modern dietary preferences and regulatory demands. Target acquisition profiles include artisanal producers with strong regional brand equity or companies pioneering plant-based pate formulations with scalable production capabilities. Quarterly review of plant-based segment growth rates and clean-label ingredient innovation is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop plant-based pate line with functional ingredients | Expands market reach to health-conscious consumers seeking nutritious, meat-free alternatives. |
| Expand direct-to-consumer sales in North America and UK | Bypasses traditional retail barriers and connects directly with niche, story-driven product enthusiasts. |
| Obtain animal welfare certifications beyond Label Rouge | Attracts ethically-minded consumers and justifies premium pricing in competitive European markets. |
| Form strategic partnerships with fine dining distributors in Asia-Pacific | Captures emerging demand for premium Western gourmet foods in high-growth hospitality sectors. |
| Introduce premium, HPP-preserved pate line for clean-label appeal | Ensures food safety and extends shelf life without artificial preservatives, addressing modern consumer demands. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and secondary validation from public sources. Primary research involved conversations with fine dining chefs, supermarket category managers, food safety regulators like the US FDA, and artisanal pate producers. Secondary data was gathered from EFSA reports, European retail audit data, and national culinary association publications, allowing for bottom-up and top-down triangulation.
Forecast inputs considered shifting consumer dietary preferences, evolving food safety regulations, and raw material supply dynamics. The analytical framework modeled market evolution across the analysis window, segmenting by product type (traditional, veggie), packaging type (glass, tin), flavor profile (classic, herb-infused), distribution channel (supermarkets, online), and regional consumption patterns. Compound annual growth rates were derived from historical trends and projected impacts of identified market drivers, incorporating plant-based ingredient availability and premium food service sector growth.
Sensitivities concentrate around geopolitical events impacting trade, animal disease outbreaks, and significant shifts in dietary guidelines. Forecasts reflect assumptions regarding regulatory stability and consumer behavior throughout the projection horizon. Quarterly review of commodity prices, new product launches in the plant-based category, and import/export volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Processed Foods
Middle East and Africa Processed Meat Market
Processed Foods
Low Moisture Food Market
Processed Foods
Casual Marinated Products Market
Processed Foods
Apple Butter Market
Processed Foods
Fast-Food Reusable Market
Processed Foods
Accompanying Marinated Product Market
Processed Foods
Porridge Market
Processed Foods
Processed Vegetable Market
Processed Foods
North America Soup Market
Processed Foods
United States Ice Cream Market
Processed Foods
Soup & Broth Market
Processed Foods
Ready to Cook Market
Processed Foods
Asia-Pacific Ice Cream Market
Processed Foods
Global Pasta Market
Processed Foods
Europe Processed Egg Market
Processed Foods
Fresh Pasta Market