
 Reamer Market | 2026-2036
Reamer Market Size, Share, and Industry Trends Forecast 2026-2036
Reamer Market Analytics
Tool-as-a-service subscription models for precision cutting tools is recalibrating how reamer vendors monetize capacity and uptime rather than unit sales. Kennametal Inc. leverages its North American service infrastructure to anchor recurring revenue streams from fleet management contracts. Sandvik Coromant dominates digital tool monitoring platforms that bundle reamer wear analytics with replacement logistics. MAPAL specializes in application-engineered reamer systems that command premium positioning through direct customer integration.
A reamer is a rotary cutting tool with multiple flutes designed to enlarge or finish pre-drilled holes to precise diameters and surface finishes, typically achieving tolerances of H7 or tighter through controlled material removal rates. Its primary industrial purpose centers on achieving geometric accuracy in critical bores for engine blocks, hydraulic manifolds, and aircraft structural joints where drilling alone leaves inadequate precision. Machine reamers lead product type demand due to automated production line integration, while carbide material selection captures expanding share in hardened steel aerospace applications. Metal working applications sustain the largest end-use volume, though maintenance segments in power generation are gaining traction as aging infrastructure drives rebuild activity.
ISO standards for cutting tool geometry and performance testing establish baseline specifications that determine supplier eligibility for tier-one manufacturing contracts. Germany's KBA and the EU Machinery Directive impose safety and precision requirements that filter reamer vendors serving automotive and aerospace OEMs. Stakeholders must monitor how digital thread standards and in-process measurement protocols reshape qualification criteria for precision hole-finishing suppliers.
Market Dynamics
Digital tool monitoring platforms and subscription-based fleet management contracts are restructuring how precision cutting tool suppliers capture value, displacing transactional unit sales with recurring revenue anchored to uptime guarantees and predictive maintenance integration.
Growth Catalysts
- Aerospace engine component finishing:Tighter bore tolerances for turbine housings and compressor discs are expanding procurement of H7-grade precision reamers from specialized tooling vendors.
- EU Machinery Directive compliance:Safety and precision mandates are filtering supplier qualification criteria, elevating certified manufacturers in tier-one automotive and aerospace supply chains.
- Carbide material substitution:Hardened steel aerospace applications are accelerating demand for solid carbide reamers over high-speed steel variants due to extended tool life in interrupted cuts.
Market Restraints
- Tungsten supply concentration:Carbide reamer production depends on tungsten sourced from concentrated mining jurisdictions, exposing tooling costs to raw material volatility and export restriction risk.
- ISO 9001 certification barriers:Small-scale reamer manufacturers face structural exclusion from OEM contracts due to quality management system audit costs and documentation requirements.
- Electrical discharge machining substitution:EDM hole-finishing in hardened aerospace alloys eliminates reamer applications in certain superalloy component geometries.
Strategic Opportunities
- Power generation maintenance rebuilds:Aging gas turbine and nuclear infrastructure in North America and Europe is creating aftermarket demand for precision hole restoration during component overhaul cycles.
- Digital thread standards adoption:In-process measurement protocol integration offers white space for reamer vendors to bundle metrology-enabled tooling with real-time bore quality feedback.
- India automotive tooling localization:PLI scheme incentives for domestic manufacturing are attracting precision cutting tool investments to serve expanding powertrain production capacity.
Industry Challenges
- Grinding specialist scarcity:Precision flute profile grinding requires skilled operators that tooling manufacturers struggle to recruit and retain against semiconductor equipment and aerospace machining sectors.
- Multi-axis machine integration complexity:Through-coolant reamer interfaces and tool length compensation protocols demand extended validation cycles with machine tool builders before production deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reamer Market |
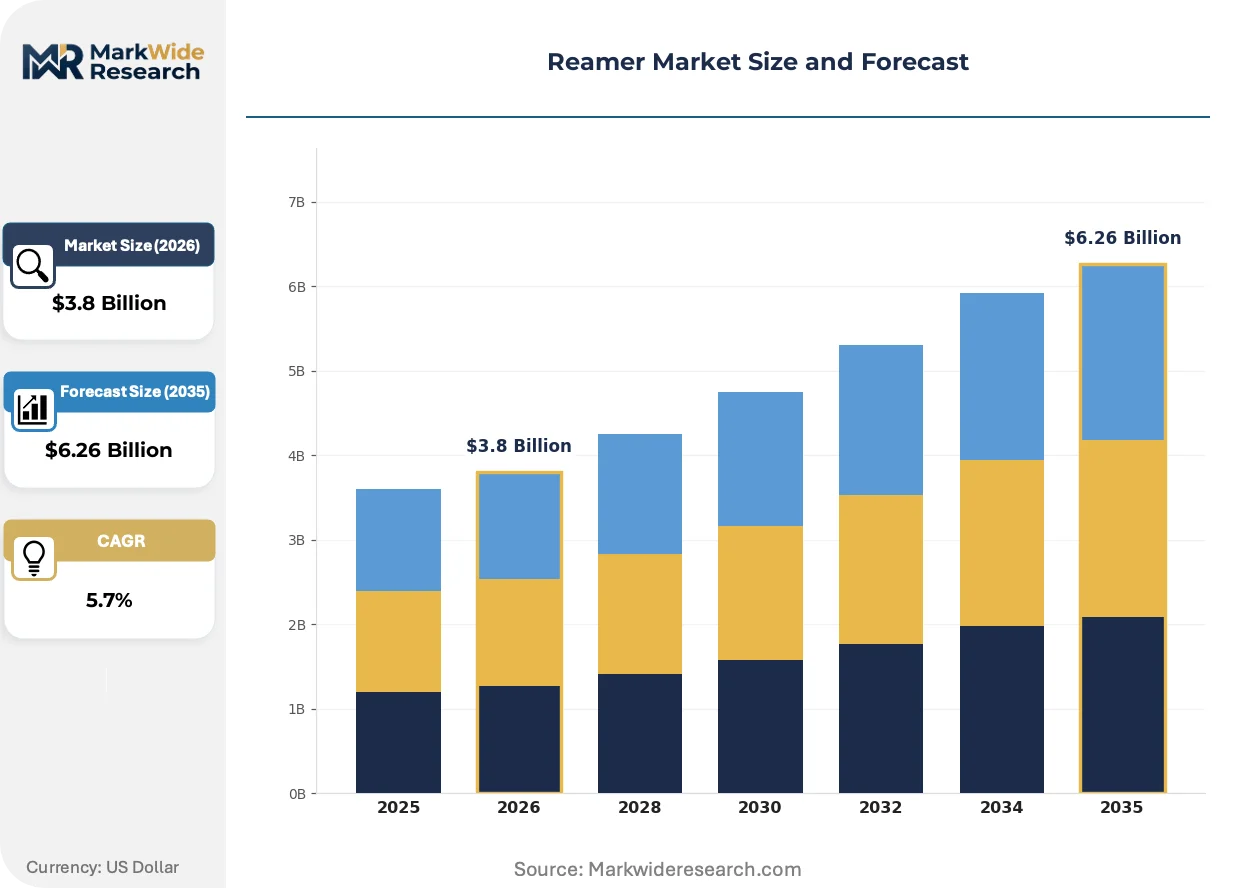
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand Reamers, Machine Reamers, Adjustable Reamers, Expansion Reamers Material: High-Speed Steel, Carbide, Cobalt, Titanium End User: Aerospace, Automotive, Construction, Manufacturing Application: Metal Working, Wood Working, Plastic Machining, Maintenance |
| Companies Covered | Kennametal Inc., Sandvik Coromant, WIDIA, HORN Cutting Tools, MAPAL, Guhring Inc., ISCAR Ltd., Walter AG, Yankee Reamers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reamer Market Evolving Landscape
Sensor-embedded cutting tools and cloud-connected wear analytics are converging to transform reamer lifecycle management from calendar-based replacement to condition-triggered logistics, compressing unplanned downtime in automated production environments.
Polycrystalline diamond (PCD) tipped reamers for carbon fiber reinforced polymer (CFRP) aerospace structures are rewriting material removal economics in composite wing and fuselage assembly. Boeing and Airbus tier suppliers are adopting PCD reamers at accelerated pace to eliminate delamination and fiber pull-out in automated drilling and reaming cells. This material shift is compressing the addressable market for conventional carbide geometries in emerging airframe programs while opening premium positioning for diamond tool specialists.
REACH substance restrictions on cobalt-containing carbide grades are forcing reformulation of conventional reamer substrates across European aerospace and automotive supply chains. The industrial consequence is elevated qualification timelines for alternative binder systems and increased testing documentation burden for tooling exporters serving EU manufacturers. Germany's KBA and France's ANSM are coordinating enforcement priority, with Stuttgart-area automotive tooling corridors experiencing the most acute supplier transition pressure.
Fleet management contracts with guaranteed availability clauses are displacing spot purchasing in high-volume automotive powertrain machining. Tier-one suppliers are consolidating vendor relationships around Sandvik Coromant and Kennametal service infrastructure, unbundling traditional distributor networks in Germany and the US Midwest. This concentration is most visible in Stuttgart and Detroit automotive clusters, where OEM-directed supplier rationalization programs favor integrated tool lifecycle partners over discrete product vendors.
Reamer Market Segmentation
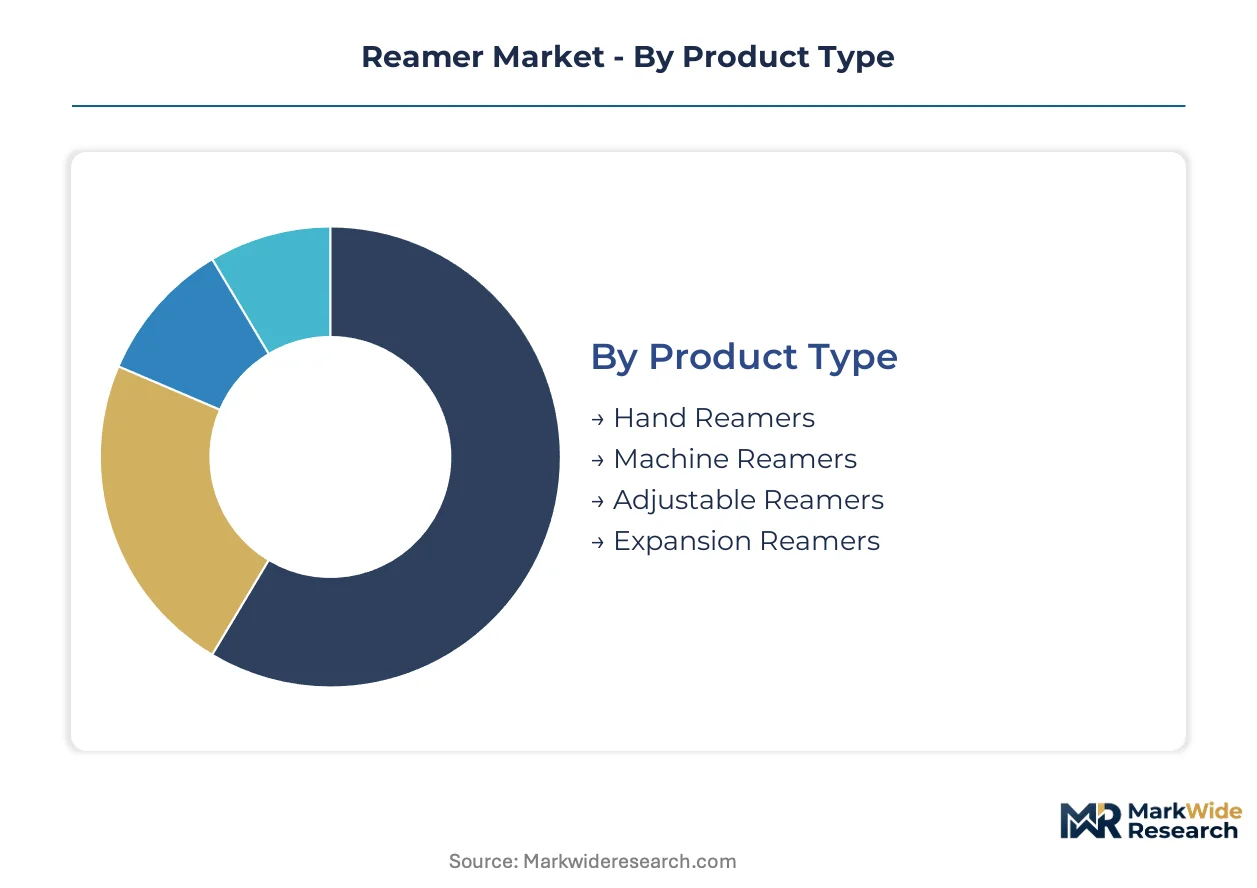
Reamer segmentation reveals how tooling economics split between standalone manual operations and embedded automated systems. Understanding these divides exposes where suppliers can capture premium positioning versus commodity exposure.
Product Type:
Hand reamers operate as standalone tools requiring operator skill, while machine reamers embed directly into automated production cells with through-coolant interfaces and tool length compensation protocols.
- Machine Reamers:Engineered for CNC integration with standardized shank geometries and internal coolant channels. Demand concentrates in Stuttgart-area automotive powertrain machining where OEM-directed supplier rationalization favors integrated tool lifecycle partners.
- Hand Reamers:Manual operation tools for field maintenance and low-volume repair work. Procurement clusters in construction equipment rebuild facilities across Germany and North American maintenance depots where skilled operator availability constrains automation adoption.
- Adjustable Reamers:Diameter-modifiable designs for job shops handling variable bore specifications.
- Expansion Reamers:Mechanically expandable geometries for finish-sizing applications in hydraulic manifold production.
Machine reamers lead volumes today; hand reamers are gaining share fastest in maintenance rebuild segments.
Material:
Cost tiers separate commodity high-speed steel from premium carbide substrates, with cobalt and titanium occupying intermediate performance positions.
- Carbide:Tungsten-carbide substrates deliver extended tool life in interrupted cuts and hardened steel aerospace applications. Stuttgart aerospace suppliers are accelerating procurement as REACH substance restrictions force reformulation timelines for alternative binder systems.
- High-Speed Steel:M2 and M7 grade substrates dominate general-purpose machining where tool cost amortization across shorter production runs favors lower unit economics.
- Cobalt:Enhanced heat resistance for stainless steel and titanium alloy machining in medical device component finishing.
- Titanium:Lightweight substrates for aerospace assembly tooling where operator fatigue limits manual reamer use.
Carbide commands the steepest expansion trajectory; high-speed steel retains volume leadership in cost-sensitive applications.
End User:
Application maturity varies sharply across end-use sectors, with aerospace demanding qualification-heavy supply relationships and construction tolerating spot purchasing.
- Aerospace:Tier-one engine and airframe manufacturers impose ISO 9001 and EU Machinery Directive compliance for H7-grade precision finishing. KBA and ANSM coordination on REACH enforcement is elevating documentation burdens for tooling exporters serving EU manufacturers.
- Automotive:Powertrain machining lines in Germany's Stuttgart corridor are consolidating vendor relationships around fleet management contracts with guaranteed availability clauses.
- Construction:Equipment rebuild and infrastructure maintenance drives intermittent demand for standard-grade reamers.
- Manufacturing:General industrial machinery production spans job shops to automated lines with heterogeneous tooling requirements.
Automotive leads absolute volumes; aerospace is climbing the fastest on per-unit value expansion.
Application:
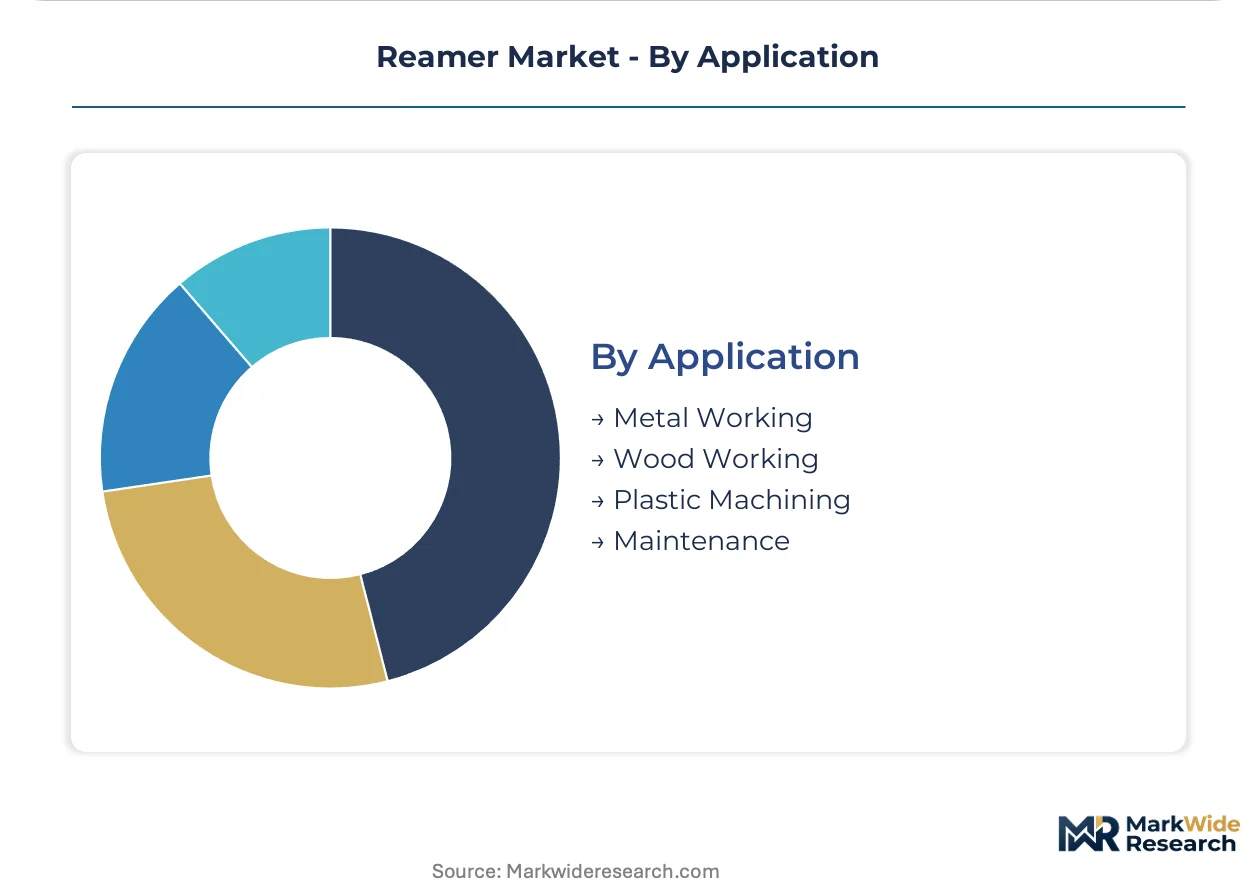
Volume concentration in metal working contrasts with emerging maintenance segments where aging infrastructure creates aftermarket rebuild demand.
- Metal Working:Engine block boring, hydraulic manifold finishing, and precision shaft machining constitute the core revenue base. Germany's automotive tooling corridor around Stuttgart and Aachen anchors procurement concentration.
- Maintenance:Gas turbine and nuclear component overhaul cycles in North America and Europe are creating precision hole restoration demand outside OEM production schedules.
- Wood Working:Furniture and millwork machinery manufacturers specify reamers for spindle and bearing housing finishing.
- Plastic Machining:Thermoset composite and engineering polymer applications in medical device housings.
Metal working dominates current procurement; maintenance is expanding most quickly as infrastructure age accumulates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium reamer procurement through its automotive tooling corridor, while the United States sustains volume demand across aerospace maintenance and power generation rebuild segments. China accelerates domestic precision cutting tool capacity under industrial upgrading mandates. India attracts tooling investments through production-linked incentive schemes for automotive component manufacturing.
United States
Aerospace engine overhaul facilities and gas turbine maintenance depots drive precision reamer consumption for bore restoration in aging infrastructure. FAA airworthiness directives and OSHA machining safety standards govern tooling qualification for defense and commercial aviation suppliers. The Midwest automotive belt around Detroit consolidates vendor relationships through fleet management contracts with integrated tool lifecycle partners.
Germany
Stuttgart-area powertrain machining lines and Aachen precision engineering clusters anchor European demand for H7-grade machine reamers. KBA enforcement of EU Machinery Directive safety mandates and REACH substance restrictions on cobalt-containing carbide grades filter supplier eligibility. Baden-Württemberg's automotive tooling corridor experiences acute supplier transition pressure as alternative binder systems undergo extended qualification timelines.
China
Domestic aerospace component finishing and automotive powertrain expansion propel carbide reamer procurement as import substitution accelerates. MIIT industrial upgrading guidelines and GB standards for cutting tool geometry establish baseline specifications for tier-one manufacturing contracts. Yangtze River Delta machining clusters integrate digital tool monitoring platforms to compress unplanned downtime in automated production environments.
India
Expanding automotive powertrain capacity and domestic precision component manufacturing attract cutting tool investments under PLI scheme incentives. BIS certification requirements and DGFT import regulations shape supplier qualification for OEM contracts. Maharashtra and Gujarat automotive corridors localize reamer procurement as multinational tier-one suppliers establish captive tooling partnerships.
Japan
Precision machining equipment exports and domestic aerospace component finishing sustain demand for application-engineered reamer systems. METI industrial technology roadmaps and JIS standards for cutting tool performance testing determine supplier eligibility for high-reliability manufacturing contracts. Nagoya-area aerospace machining clusters adopt sensor-embedded tooling with cloud-connected wear analytics for condition-triggered replacement logistics.
Reamer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated tooling systems vendors capturing premium positioning in automotive fleet management contracts while regional fabricators serve maintenance and job shop demand. Market structure tilts toward consolidation among digital platform operators and application-engineered solution providers, with commoditized high-speed steel reamers facing margin compression. Three archetypes dominate: subscription-based fleet managers, precision application specialists, and scale-driven carbide substrate producers. Competitive dynamics center on strategic partnerships with machine tool builders and backward integration into tungsten carbide powder processing.
Among German-based precision tooling specialists, MAPAL and HORN Cutting Tools exemplify the application-engineered tier that commands premium positioning through direct customer integration and customized bore-finishing systems. Kennametal Inc. anchors the North American service infrastructure archetype, representing subscription-based revenue models that monetize uptime guarantees rather than discrete unit sales. These three companies illustrate how competitive positioning diverges between geographic service density and technical specialization vectors.
| Leading Market Players |
|---|
| Kennametal Inc. |
| Sandvik Coromant |
| WIDIA |
| HORN Cutting Tools |
| MAPAL |
| Guhring Inc. |
| ISCAR Ltd. |
| Walter AG |
| Yankee Reamers |
| Others |
Value Network & Pricing Analysis
Sensor-embedded reamer adoption and cloud-connected wear analytics deployment simultaneously compress maintenance economics and concentrate procurement power among fleet management operators. Stuttgart automotive corridors and Detroit powertrain clusters now negotiate subscription contracts that bundle tool replacement logistics with uptime guarantees, displacing spot purchasing and flattening price transparency across traditional distributor networks.
Pricing Analysis
Capacity additions in China's Yangtze River Delta machining clusters are reshaping price floors for standard-grade carbide reamers. Three-tier pricing structure across premium, standard, and economy levels separates application-engineered systems with direct customer integration from commodity geometries. Cost compression in economy-tier high-speed steel runs through tungsten powder volatility and REACH-driven cobalt reformulation. Tier-one automotive OEMs exhibit lowest price sensitivity due to fleet contract lock-in, while job shops and maintenance depots remain highly price-elastic.
Supply Chain Analysis
Precision flute profile grinding specialist scarcity in Germany's Baden-Württemberg and Japan's Aichi prefecture constrains substrate finishing capacity. Tungsten carbide powder supply draws from concentrated mining jurisdictions in China and Vietnam, with cobalt binder chemistry facing ECHA substance restriction enforcement. Single-source vulnerability sits with specialized grinding wheel manufacturers serving aerospace-qualified reamer producers. Distribution runs through integrated tool lifecycle partners in automotive corridors and regional fabricators serving maintenance segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
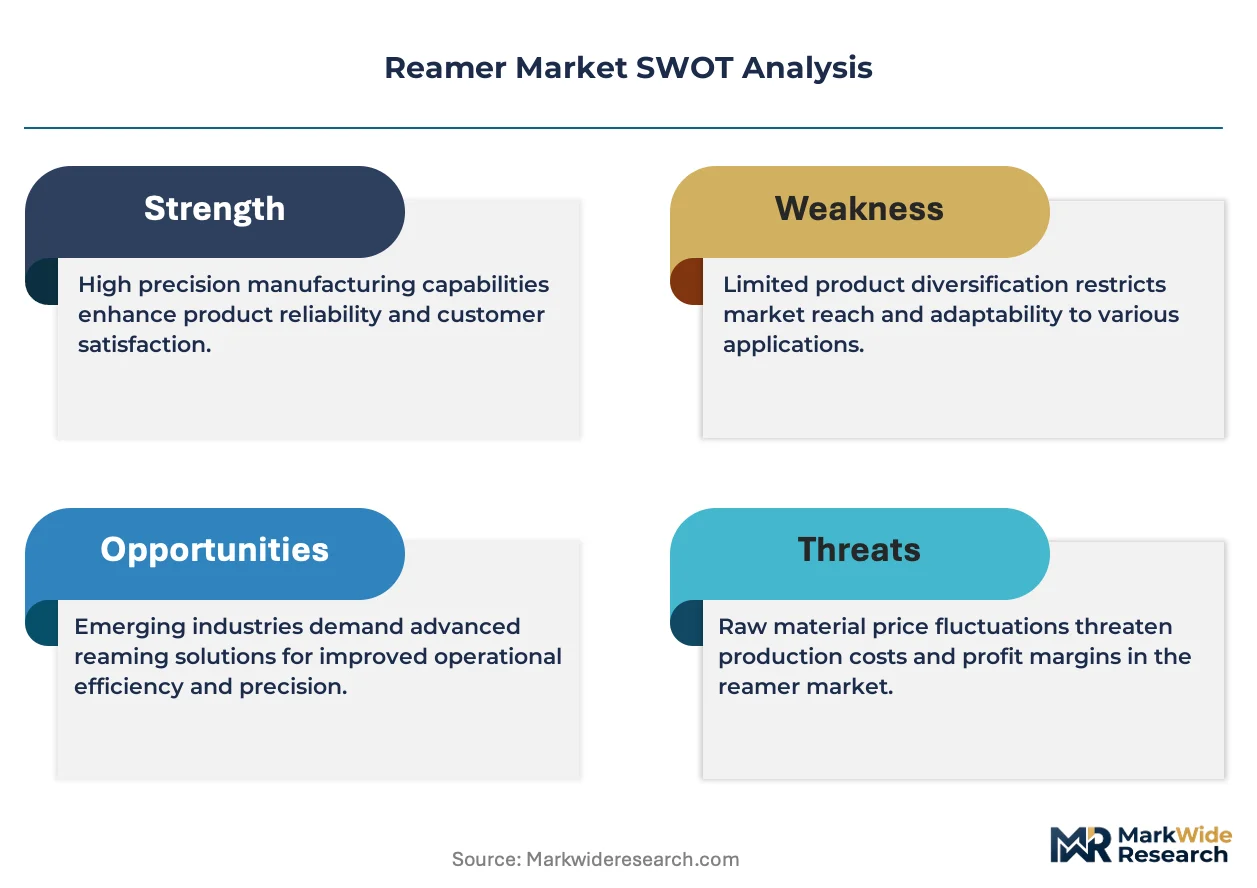
The reamer market functions as a regulatory compounder where EU Machinery Directive safety mandates and REACH substance restrictions continuously elevate qualification barriers and documentation burdens for tooling exporters.
For Market Incumbents: Deepen backward integration into tungsten carbide powder processing to insulate margin structures from raw material volatility. Anchor fleet management contract renewals through predictive maintenance platform stickiness, defending against emerging digital tool monitoring entrants. Prioritize ISO 9001 certification maintenance as KBA and ANSM enforcement coordination tightens supplier eligibility filters.
For New Entrants and Emerging Players: Begin with power generation maintenance rebuild segments in North American gas turbine depots where aging infrastructure creates precision hole restoration demand outside OEM production schedules. Target India's Maharashtra and Gujarat automotive corridors where PLI scheme incentives localize procurement away from established multinational service infrastructure. Lead with PCD-tipped reamer offerings for CFRP aerospace structures where Boeing and Airbus tier suppliers seek delamination-free composite machining solutions.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional carbide substrate producers lacking digital platform integration or fleet management contract exposure. Five-to-ten-year viability hinges on regulatory compliance infrastructure and machine tool builder partnership depth. Watch for REACH alternative binder qualification completion as inflection signal for European aerospace supply chain re-entry.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Tool Monitoring Platform Deployment | Sandvik Coromant and Kennametal infrastructure anchors recurring revenue through predictive wear analytics integration. |
| PCD-Tipped Reamer Capacity Expansion | Boeing and Airbus tier supplier adoption accelerates for carbon fiber reinforced polymer wing and fuselage finishing. |
| REACH-Compliant Binder System Qualification | Germany's KBA and France's ANSM enforcement coordination elevates documentation burden for cobalt-free substrate exporters. |
| Fleet Management Contract Consolidation | Stuttgart and Detroit automotive clusters displace spot purchasing through guaranteed availability clause integration. |
| India PLI Scheme Localization Partnership | Maharashtra and Gujarat automotive corridors attract captive tooling investments from multinational tier-one suppliers. |
Research Methodology
Direct dialogue with precision tooling procurement managers, plant engineers at automotive powertrain facilities, aerospace component finishing specialists, grinding equipment operators, and aftermarket maintenance directors grounded the qualitative foundation. Secondary validation drew from SEC filings of listed cutting tool manufacturers, ECHA substance restriction documentation, KBA enforcement bulletins, MIIT industrial upgrading guidelines, and customs trade data for tungsten carbide powder flows. Bottom-up and top-down triangulation cross-checked segment assumptions against OEM production schedules and infrastructure age demographics.
Bottom-up modeling aggregated reamer consumption by product type, material substrate, end-user sector, and application across the projection horizon. Top-down validation referenced machine tool installation rates, aerospace engine production forecasts, and automotive powertrain capacity expansion. CAGRs derived from regression analysis against historical tooling intensity ratios and substitution elasticity parameters for EDM hole-finishing alternatives. Forecast inputs incorporated REACH compliance timeline uncertainty and digital thread standards adoption curves.
Several conditions sit outside the modeled scope, including unannounced export restrictions on tungsten concentrates, abrupt EDM technology cost breakthroughs in superalloy machining, and geopolitical disruptions to machine tool builder supply partnerships. Forecasts reflect assumptions around sustained aerospace engine component finishing demand and gradual cobalt binder substitution pace. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Saw Blades Market
Tools
2D Laser Cutting Machine Market
Tools
3D Milling Machines Market
Tools
Manual Cutting Equipment Market
Tools
Cordless Power Drill Market
Tools
Sand Control Tools Market
Tools
Woodpecker Tools Market
Tools
Woodworking CNC Tools Market
Tools
Global Swaging Machine Market
Tools
Global Tool Holder Adapters Market
Tools
Fixed Cutter Bits Market
Tools
Surface Planer Market
Tools
Yard Scraper Market
Tools
Concrete Saw Market
Tools
Global Punch and Die Storage Cabinet Market
Tools
Squeegee Market