
 Europe IVD Regulatory Affairs Outsourcing Market | 2026-2036
Europe IVD Regulatory Affairs Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe IVD Regulatory Affairs Outsourcing Market Foresight
Mid-sized diagnostic manufacturers are collapsing their historical reliance on in-house regulatory teams as IVDR technical documentation demands outpace internal capabilities. Freyr Solutions leverages its dedicated European regulatory infrastructure to anchor compliance programs across multiple member states. PPD sustains competitive density through integrated clinical and regulatory service lines that span the full IVD lifecycle. Emergo specializes in notified body liaison work, a capability that differentiates its offering as conformity assessment bottlenecks persist across the continent.
Europe IVD regulatory affairs outsourcing encompasses the delegation of compliance strategy, technical documentation preparation, quality management system maintenance, and notified body engagement to third-party specialists operating under EU medical device regulations. The practice requires deep familiarity with IVDR Annex I general safety and performance requirements, post-market surveillance obligations, and EUDAMED registration protocols to secure and maintain CE marking for in vitro diagnostic devices. Regulatory consulting and clinical evaluation services command the strongest margin pools as manufacturers grapple with performance study design and benefit-risk justification under the new framework. Full-service outsourcing arrangements are expanding fastest among biopharmaceutical companies entering the companion diagnostic space, where dual regulatory pathways create layered compliance complexity.
EMA guidance documents, IVDR delegated acts, and national competent authority interpretations from Germany's BfArM and France's ANSM collectively shape service provider capability requirements and client procurement criteria. The transition from IVDD to IVDR has triggered a permanent elevation in documentation depth, forcing outsourcing partners to recruit former notified body reviewers and competent authority inspectors. Stakeholders must monitor how the European Commission's ongoing refinement of common specifications and implementing acts reshapes the boundary between consultative support and regulated legal manufacturer responsibilities.
Market Dynamics
The IVDR transition has permanently altered the economics of in-house regulatory staffing across European diagnostic manufacturers, compressing timelines while expanding documentation burdens beyond internal capacity.
Growth Catalysts
- IVDR Annex I technical documentation mandates:The expanded general safety and performance requirements under EMA oversight force manufacturers to externalize complex benefit-risk assessments and clinical evidence compilation.
- Companion diagnostic pipeline expansion:Biopharmaceutical companies developing CDx assays require simultaneous EMA and notified body engagement, creating layered demand for dual-pathway expertise.
- EUDAMED registration complexity:The phased rollout of actor registration, device registration, and post-market surveillance modules demands specialized database management capabilities that mid-sized manufacturers lack.
Market Restraints
- Notified body capacity scarcity:The limited number of IVDR-designated notified bodies creates approval bottlenecks that extend project timelines regardless of outsourcing investment.
- Former competent authority talent competition:Service providers compete intensely for ex-BfArM, ANSM, and Dutch IGJ inspectors, inflating specialist compensation and compressing margins.
- Legal manufacturer liability boundaries:Unclear delineation between consultative support and regulated legal manufacturer responsibilities under IVDR Article 10 creates contractual risk for outsourcing arrangements.
Strategic Opportunities
- Netherlands regulatory cluster expansion:The concentration of notified bodies and competent authority expertise around Utrecht and Amsterdam offers geographic arbitrage for pan-European service delivery.
- Software-as-a-medical-device convergence:The intersection of AI-driven diagnostic algorithms with IVDR scope creates unmet demand for combined technical and regulatory expertise.
- Post-market surveillance outsourcing:IVDR Article 78 periodic safety update report obligations and vigilance reporting requirements open recurring revenue streams beyond initial certification.
Industry Challenges
- Performance study design capability gaps:The shift from IVDD self-certification to IVDR conformity assessment demands clinical evidence generation skills that regulatory generalists rarely possess.
- Multi-member state variation management:Divergent national competent authority interpretations of IVDR implementing acts across Germany, France, and Benelux markets complicates standardized service delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe IVD Regulatory Affairs Outsourcing Market |
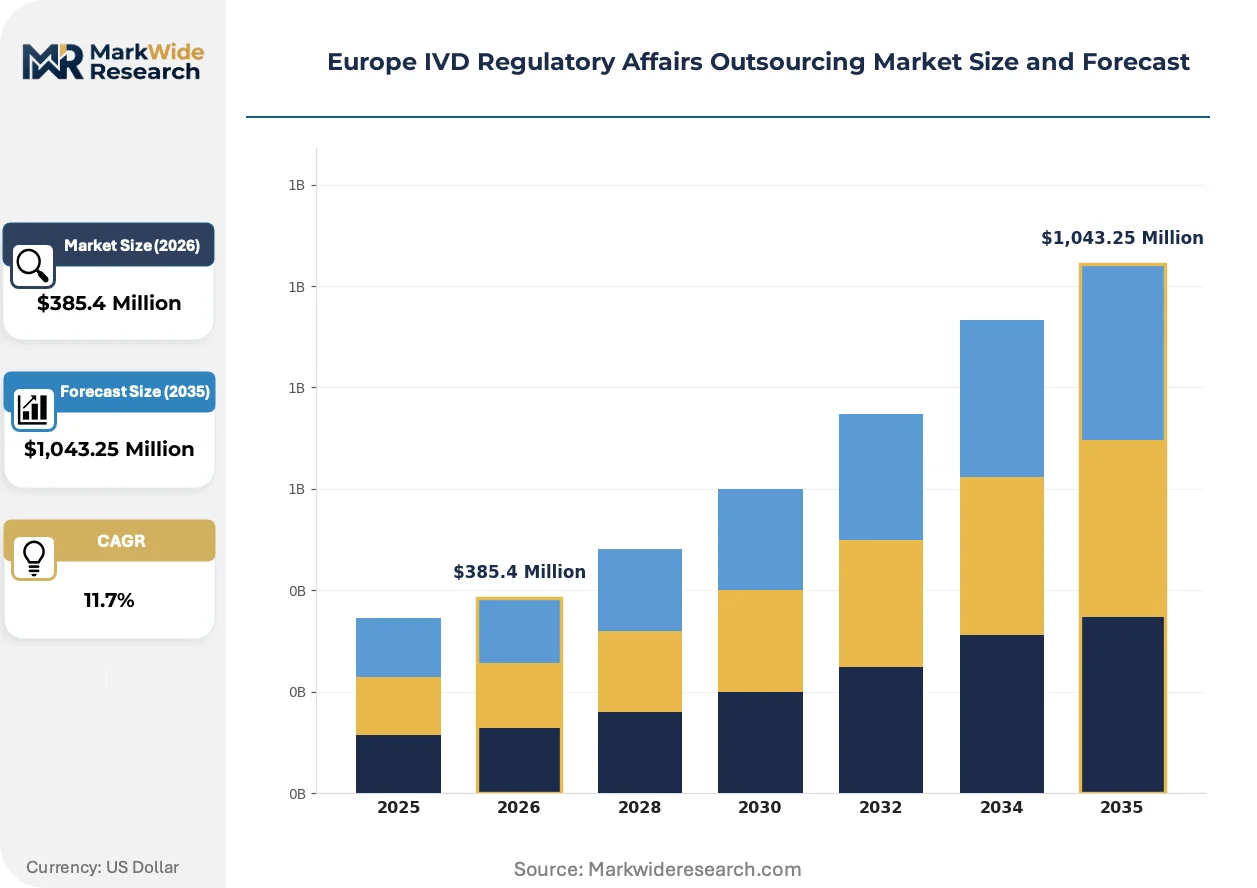
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,043.25 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Regulatory Consulting, Quality Management, Clinical Evaluation, Compliance Auditing End User: Medical Device Manufacturers, Diagnostic Laboratories, Biopharmaceutical Companies, Research Institutions Application: In Vitro Diagnostics, Medical Devices, Laboratory Instrumentation, Clinical Research Deployment: Onsite Services, Remote Services, Hybrid Services, Full-Service Outsourcing |
| Companies Covered | Freyr Solutions, PPD, Emergo, ICON, Parexel International Corporation, ProductLife Group, Labcorp Drug Development, WuXi AppTec, Qserve, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe IVD Regulatory Affairs Outsourcing Market Shifts & Advancements
Digital tooling is restructuring how regulatory intelligence flows between manufacturers, notified bodies, and competent authorities, compressing information asymmetries while elevating automation expectations.
Regulatory intelligence platforms are fragmenting traditional document-centric workflows by embedding IVDR requirement traceability matrices directly into product lifecycle management systems. Mid-sized IVD manufacturers in Germany and France are adopting these tools fastest, seeking to reduce manual technical documentation preparation hours. The technology is fragmenting the historical dominance of full-service consulting engagements, enabling unbundled subscription models for specific compliance modules.
EMA's ongoing refinement of IVDR common specifications and implementing acts is forcing service providers to maintain real-time regulatory monitoring capabilities that exceed static subscription services. The industrial consequence is permanent elevation of in-house regulatory affairs team sizes among outsourcing firms, particularly for performance evaluation and post-market clinical follow-up expertise. Companion diagnostic manufacturers face the steepest adaptation curve, as EMA scientific advice procedures now require synchronized notified body input that few internal teams can orchestrate.
Diagnostic manufacturers are consolidating vendor relationships around providers offering integrated clinical and regulatory capabilities rather than discrete document preparation services. The traditional separation between CRO and regulatory consulting engagements is dissolving, with biopharmaceutical CDx sponsors demanding single-accountability structures. This consolidation is most visible in the Netherlands and Belgium, where proximity to EMA and dense notified body presence enables tighter clinical-regulatory coordination.
Europe IVD Regulatory Affairs Outsourcing Market Segmentation
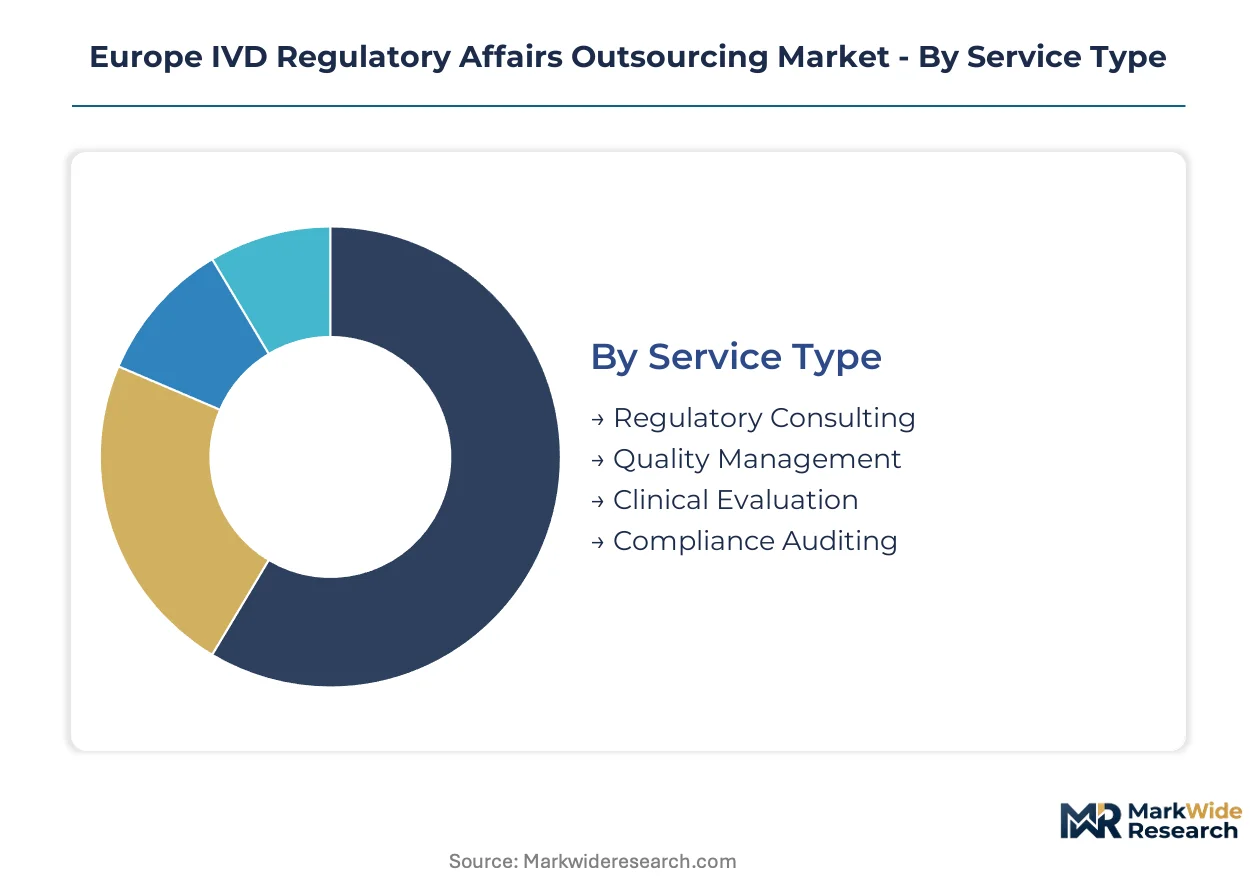
IVDR compliance complexity fragments demand across service modalities and customer profiles, with mid-sized manufacturers driving volume in consulting while biopharmaceutical sponsors concentrate spending on integrated clinical-regulatory bundles. Understanding segment boundaries clarifies where margin pools concentrate versus where commoditization pressures mount.
Service Type:
German and French domestic manufacturers dominate demand for regulatory consulting and quality management, while export-oriented Dutch and Belgian device sponsors drive clinical evaluation outsourcing for multi-market IVDR submissions.
- Regulatory Consulting:Strategic guidance on IVDR Annex I general safety and performance requirements, EUDAMED actor registration, and notified body selection. Demand concentrates among mid-sized IVD manufacturers in Germany's Baden-Württemberg and Bavaria clusters struggling with benefit-risk documentation depth. BfArM inspection experience commands premium pricing as former competent authority staff scarcity intensifies.
- Quality Management:ISO 13485 maintenance, post-market surveillance system design, and vigilance reporting infrastructure. Dutch diagnostic manufacturers expanding across Benelux markets represent the fastest-growing client base as Utrecht-Amsterdam regulatory cluster density enables localized service delivery.
- Clinical Evaluation:Performance study design, clinical evidence gap analysis, and PMCF protocol development. Biopharmaceutical CDx sponsors require synchronized EMA scientific advice and notified body engagement.
- Compliance Auditing:Internal audit execution, supplier qualification, and mock notified body inspection preparation. ANSM-interpretation expertise differentiates French market offerings.
Regulatory Consulting commands the established base. The steepest expansion runs through Clinical Evaluation.
End User:
Cost tier stratification separates enterprise biopharmaceutical engagements with integrated full-service contracts from mid-cap manufacturers purchasing unbundled compliance modules.
- Medical Device Manufacturers:IVD-specific sponsors navigating IVDR transition timelines with legacy IVDD certificates expiring. Germany absorbs the densest concentration as BfArM intensifies post-market surveillance enforcement.
- Diagnostic Laboratories:In-house assay developers requiring legal manufacturer designation under IVDR Article 10. French hospital laboratory networks drive demand as ANSM clarifies LDT regulatory boundaries.
- Biopharmaceutical Companies:Companion diagnostic developers requiring dual EMA-notified body pathway orchestration. Netherlands-based sponsors leverage proximity to EMA for scientific advice synchronization.
- Research Institutions:Academic medical centers commercializing translational diagnostics. Belgian and Dutch university hospitals represent emerging demand as technology transfer offices assume legal manufacturer responsibilities.
Medical Device Manufacturers anchor volume concentration. Biopharmaceutical Companies generate the steepest fee escalation as CDx pipeline density increases.
Application:
Application maturity separates established IVD segments with settled IVDR interpretation from emerging software-device convergence areas with evolving EMA guidance.
- In Vitro Diagnostics:Reagent systems, instrument platforms, and self-testing devices under IVDR Annex II technical documentation requirements. Class C and D devices drive the highest service intensity as notified body scrutiny of clinical evidence intensifies.
- Medical Devices:Borderline products requiring MDR-IVDR jurisdiction determination. German manufacturers face particular complexity as BfArM issues classification guidance for combined device systems.
- Laboratory Instrumentation:Analytical equipment with IVD and general lab dual use. Dutch manufacturers expanding into clinical markets require IVDR scope assessment.
- Clinical Research:Investigator-initiated studies and post-market clinical follow-up requiring regulatory support. French academic sponsors dominate as ANSM implements IVDR Article 74 performance study requirements.
In Vitro Diagnostics represents the established revenue base. Clinical Research applications are expanding most quickly as PMCF obligations proliferate.
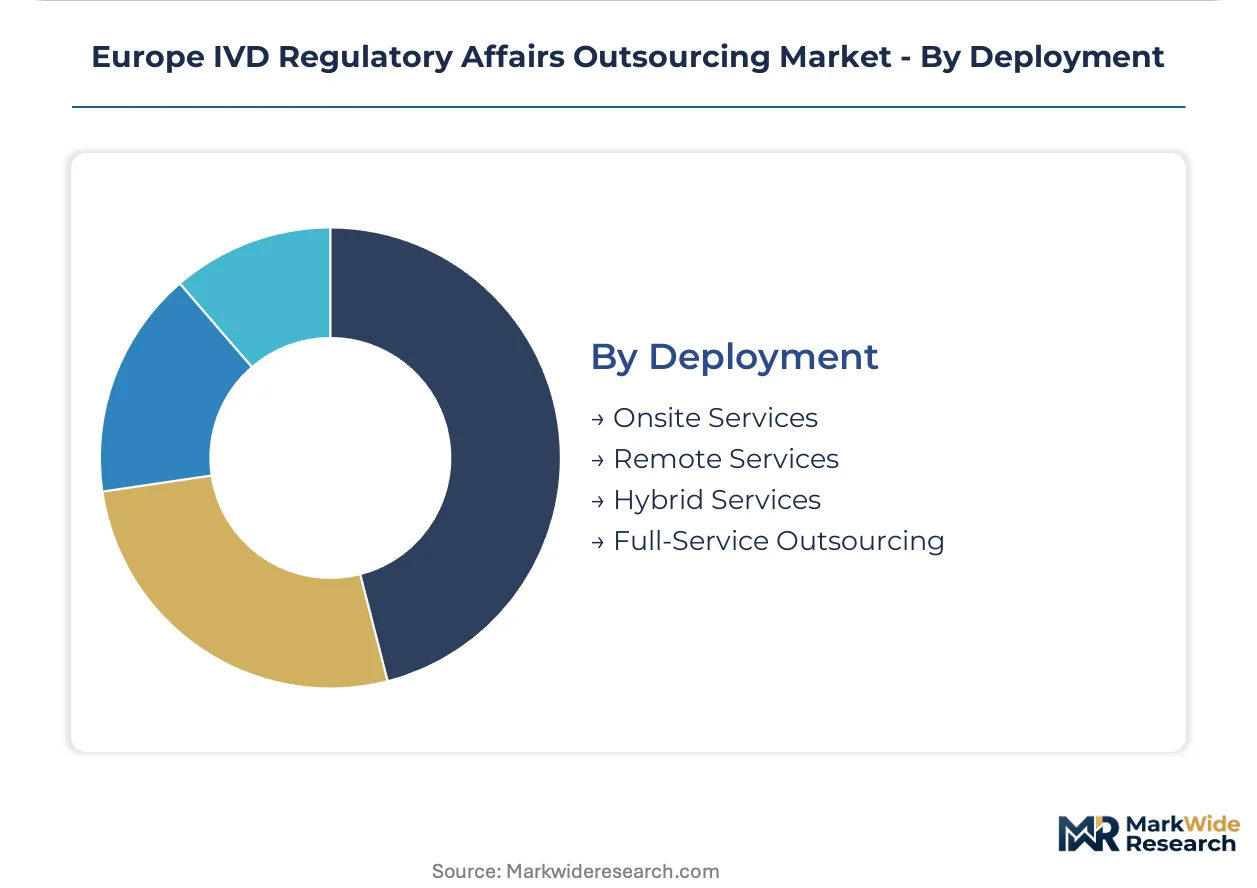
Deployment:
Deployment mode selection tracks customer scale and geographic dispersion, with hybrid models gaining traction as EMA guidance refinement demands real-time regulatory monitoring.
- Onsite Services:Embedded regulatory affairs staff placed at manufacturer facilities. German mid-caps in Tübingen and Freiburg clusters prefer this model for quality system integration.
- Remote Services:Document preparation, EUDAMED data entry, and regulatory intelligence delivered through secure collaboration platforms. Benelux manufacturers adopt fastest given cross-border operational structures.
- Hybrid Services:Rotating onsite presence with remote execution for technical documentation and post-market surveillance. French manufacturers favor this for ANSM inspection preparation combined with cost control.
- Full-Service Outsourcing:Comprehensive legal manufacturer responsibility assumption including notified body engagement and vigilance reporting. Biopharmaceutical CDx sponsors require this as internal regulatory bandwidth constraints tighten.
Hybrid Services command the established preference. Full-Service Outsourcing is climbing the fastest as CDx complexity exceeds internal capability development speed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service provider capabilities concentrate in regulatory clusters where notified body density and competent authority expertise overlap. Germany, France, the Netherlands, Belgium, and the United Kingdom absorb the dominant share of outsourcing demand as IVDR implementation timelines compress.
Germany
Baden-Württemberg and Bavaria host dense concentrations of mid-sized IVD manufacturers confronting IVDR Annex I documentation depth. BfArM intensifies post-market surveillance enforcement, accelerating demand for former inspector talent. Tübingen and Freiburg clusters favor embedded regulatory staff models for quality system integration.
France
Paris-based biopharmaceutical sponsors drive companion diagnostic regulatory complexity requiring ANSM-EMA dual pathway orchestration. ANSM clarifies laboratory-developed test boundaries, forcing hospital networks to assume legal manufacturer responsibilities. Île-de-France absorbs premium pricing for hybrid onsite-remote service delivery.
Netherlands
Utrecht-Amsterdam regulatory cluster density enables pan-European service delivery from a single base. Proximity to EMA accelerates scientific advice synchronization for CDx developers. Dutch manufacturers expanding across Benelux adopt remote service models fastest given cross-border operational structures.
Belgium
Leuven and Brussels anchor clinical-regulatory coordination for biopharmaceutical sponsors demanding single-accountability structures. Technology transfer offices at university hospitals assume legal manufacturer responsibilities for translational diagnostics. Belgian sponsors leverage EMA proximity for performance study protocol alignment.
United Kingdom
Post-Brexit divergence from IVDR creates parallel compliance pathways for manufacturers maintaining EU market access. MHRA recognition routes and UKCA marking requirements sustain demand for dual-competency regulatory partners. London and Cambridge clusters concentrate CDx development requiring synchronized EU-UK submissions.
Europe IVD Regulatory Affairs Outsourcing Market Competitive Landscape
Concentration sits with full-service clinical-regulatory integrators and specialized notified body liaison providers. The market structure tilts toward consolidation as biopharmaceutical sponsors demand single-accountability structures spanning EMA engagement and conformity assessment. Three archetypes dominate: integrated CRO-regulatory hybrids, pure-play regulatory specialists with former competent authority staff, and quality management system pure-plays. Competitive moves center on geographic cluster expansion around notified body concentrations and vertical capability integration into clinical evaluation.
Within the integrated service tier, PPD and ICON exemplify the CRO-regulatory hybrid model, occupying positions that span full IVD lifecycle support. Among specialized regulatory consultancies, Freyr Solutions and Emergo sit within the notified body liaison archetype, anchoring service delivery through dedicated European infrastructure. ProductLife Group represents the quality management pure-play segment. These three named entities illustrate how capability bundling separates premium-tier providers from document-preparation commoditization.
| Leading Market Players |
|---|
| Freyr Solutions |
| PPD |
| Emergo |
| ICON |
| Parexel International Corporation |
| ProductLife Group |
| Labcorp Drug Development |
| WuXi AppTec |
| Qserve |
| Others |
Supply & Pricing Matrix
Ninety-day notified body queue backlogs tether pricing power to geographic proximity with IVDR-designated conformity assessment bodies, compressing margins for remote service providers while amplifying premiums for Utrecht-Amsterdam cluster incumbents. Cost-to-serve differentials widen as BfArM and ANSM inspection expertise scarcity forces compensation inflation for former competent authority talent.
Pricing Analysis
IVDR Article 10 legal manufacturer obligations dictate the pricing tier structure across the European IVD regulatory outsourcing landscape. Project-based fee arrangements dominate for initial technical documentation compilation, while subscription models capture post-market surveillance and EUDAMED maintenance mandates. Pricing stratifies across premium, standard, and economy tiers based on former notified body reviewer involvement and multi-member state coverage breadth. Cost compression in standard-tier document preparation intensifies as automation tooling fragments unbundled compliance modules. Mid-sized German manufacturers exhibit acute price sensitivity, whereas Netherlands-based biopharmaceutical CDx sponsors prioritize pathway orchestration speed over fee minimization.
Supply Chain Analysis
Notified body designation bottlenecks in Germany, the Netherlands, and France concentrate service delivery capacity around regulatory cluster density. Human capital inputs draw from ex-BfArM, ANSM, and Dutch IGJ inspector pools, while technology infrastructure rests on regulatory intelligence platform subscriptions and secure EUDAMED data exchange protocols. Single-source vulnerability permeates the former competent authority talent pipeline as poaching intensity escalates among service providers. Distribution runs through direct enterprise sales for integrated clinical-regulatory bundles and channel partnerships for unbundled compliance modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among biopharmaceutical CDx sponsors demanding single-accountability structures, fragmenting procurement relationships for discrete document-preparation vendors. Consolidation among Netherlands and Belgium sponsors accelerates vendor rationalization toward integrated CRO-regulatory hybrids.
For Market Incumbents: Shield margin position by embedding former notified body reviewers into long-term retainer structures before talent scarcity intensifies further. Deepen backward integration into clinical evaluation capabilities to capture CDx pathway orchestration premiums. Prioritize certification investment in EUDAMED database management and performance study design to defend against pure-play regulatory specialists encroaching on full-service contracts. For New Entrants and Emerging Players: Anchor in post-market surveillance outsourcing as IVDR Article 78 periodic safety update report obligations create recurring revenue white space beyond initial certification. Target French hospital laboratory networks assuming legal manufacturer responsibilities under ANSM LDT clarifications. Pursue regulatory intelligence platform partnerships as the go-to-market angle to bypass entrenched consulting relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from mid-sized CROs with dormant European regulatory capabilities seeking clinical-regulatory integration. Long-term viability hinges on IVDR implementation permanence and companion diagnostic pipeline density sustaining dual-pathway complexity. Monitor notified body designation expansion velocity as the inflection signal for service provider capacity constraints easing.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Liaison Partnership | Direct engagement with BSI, DEKRA, or TÜV SÜD accelerates IVDR conformity assessment timelines for Class C and D devices. |
| Former Competent Authority Talent Acquisition | Ex-BfArM and ANSM inspector recruitment commands premium pricing power in German and French market segments. |
| Regulatory Intelligence Platform Integration | Embedded IVDR requirement traceability matrices fragment traditional document-centric consulting workflows. |
| Clinical-Regulatory Capability Merger | Single-accountability structures span EMA scientific advice synchronization and notified body performance study protocol alignment. |
| Post-Market Surveillance Infrastructure Buildout | IVDR Article 78 PSUR obligations and vigilance reporting open recurring revenue streams beyond initial CE marking. |
Research Methodology
The analysis maps regulatory consulting, quality management, clinical evaluation, and compliance auditing sub-sectors, each validated through regulatory affairs directors, notified body engagement leads, and biopharmaceutical CDx program managers. Primary interviews with quality system auditors and EUDAMED database administrators combined with secondary validation against EMA guidance documents, IVDR delegated acts, BfArM inspection reports, and ANSM regulatory clarifications. Bottom-up service provider capacity assessments and top-down manufacturer outsourcing spend estimates triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include service type, end user archetype, application maturity, and deployment mode preference. CAGRs derive from IVDR transition timeline compression, notified body capacity constraints, and companion diagnostic pipeline density trajectories. Forecast inputs incorporate EUDAMED module rollout schedules and national competent authority enforcement intensity variations.
Material uncertainties — notified body designation expansion delays, IVDR implementing act refinements, and biopharmaceutical CDx sponsor consolidation — sit outside the modeled envelope. Forecasts reflect assumptions regarding regulatory complexity permanence and outsourcing penetration ceilings. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Monkeypox Testing Market
Testing Services
Medical Device Testing, Inspection, and Certification Market
Testing Services
Global IVD Regulatory Affairs Outsourcing Market
Testing Services
ATP Assays Market
Testing Services
Mask Bacterial Filtration Efficiency Tester Market
Testing Services
Europe Esoteric Testing Market
Testing Services
Nicotine Testing Market
Testing Services
Fertility and Pregnancy Rapid Test Kits Market
Testing Services
Gastrointestinal Testing Panels Market
Testing Services
Lab Screening Test Kit Market
Testing Services
Biological Indicator Vials Market
Testing Services
Home Blood Testing Devices Market
Testing Services
Global Urinalysis Test Market
Testing Services
Platelet Function Testing Market
Testing Services
Europe Antimicrobial Susceptibility Testing Market
Testing Services
Drug Testing Systems Market