
 Monkeypox Testing Market | 2026-2036
Monkeypox Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Monkeypox Testing Market Intelligence
Hospital-based diagnostic programs is expanding as the primary end-use vertical for monkeypox testing infrastructure, overtaking earlier reliance on centralized public health laboratories. Thermo Fisher Scientific leverages its real-time PCR instrument installed base to anchor clinical workflow integration. Quest Diagnostics competes through its national specimen logistics network, while QIAGEN specializes in automated nucleic acid extraction systems that reduce turnaround times for orthopoxvirus confirmation.
Monkeypox testing encompasses molecular, immunological, and culture-based methods for detecting Orthopoxvirus species in human clinical specimens, with RT-PCR assays targeting conserved viral DNA regions such as the F3L gene achieving analytical sensitivity below 100 copies per reaction. RT-PCR tests dominate current revenue pools due to their established regulatory clearance and diagnostic accuracy during acute infection phases. Antigen tests represent the fastest-growing segment as manufacturers develop point-of-care formats for decentralized screening, though serology tests occupy a narrower niche in epidemiological surveillance and retrospective outbreak investigation.
The FDA governs premarket review and emergency use authorization for in vitro diagnostic platforms, while the WHO publishes target product profiles that influence procurement standards in low-resource settings. The EMA's CE-IVD framework shapes conformity requirements for manufacturers distributing across European member states, creating dual compliance obligations for multinational suppliers. Stakeholders must monitor evolving case definition criteria from national health agencies, as narrowed or expanded symptom thresholds directly alter testing volume forecasts and inventory planning assumptions.
Market Dynamics
Hospital diagnostic programs are absorbing molecular testing capacity previously concentrated in public health laboratories, creating a structural reconfiguration of specimen flow and procurement authority across clinical networks.
Growth Catalysts
- WHO orthopoxvirus surveillance guidance:Updated protocols expand mandatory testing triggers for member states, driving assay kit procurement volumes through national health ministries.
- Antigen test format development:Point-of-care manufacturers are compressing detection timelines from hours to minutes, enabling decentralized screening in emergency departments and urgent care settings.
- United States:FDA emergency use authorization pathways for PCR platforms accelerate commercial entry timelines for novel detection chemistries.
Market Restraints
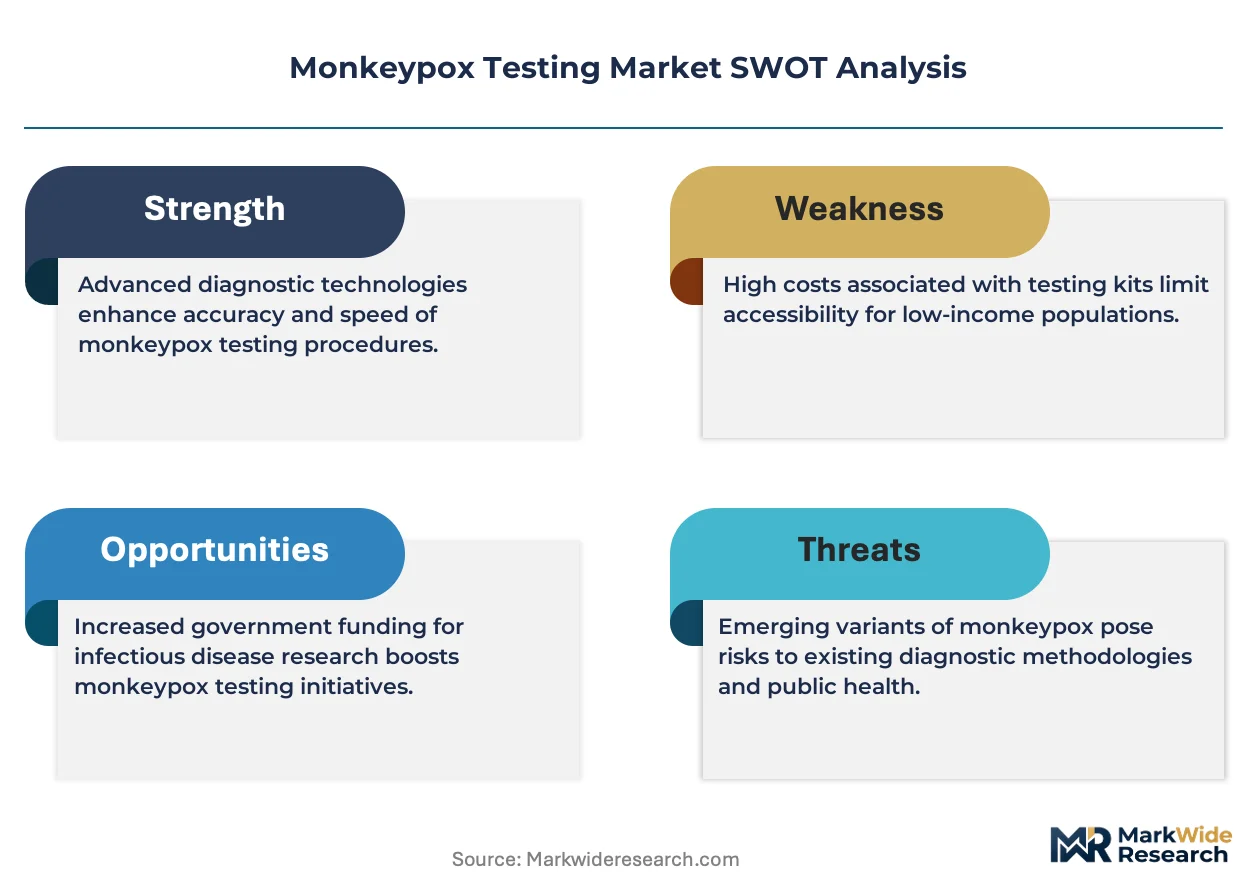
- Supply concentration in nucleic acid extraction reagents:Automated extraction consumables depend on a narrow supplier base concentrated in Germany and the United States, creating vulnerability to batch shortages.
- Technical limitation in serology cross-reactivity:Orthopoxvirus antibody assays cannot distinguish monkeypox from vaccinia or smallpox exposure, limiting diagnostic utility to epidemiological rather than clinical decision-making.
- Substitution threat from multiplex respiratory panels:Hospital laboratories prioritize syndromic testing platforms that bundle multiple pathogens, diverting capital from standalone poxvirus assays.
Strategic Opportunities
- Underpenetrated geography in sub-Saharan Africa:Surveillance infrastructure gaps in endemic regions create demand for portable molecular devices with battery-independent thermal cycling.
- Technology convergence of CRISPR diagnostics and smartphone readout:Field-deployable platforms bypass cold-chain logistics and laboratory infrastructure requirements entirely.
- EMA CE-IVD framework alignment:Harmonized conformity assessment across European member states reduces redundant certification costs for manufacturers seeking multi-country distribution.
Industry Challenges
- Specialized virology technologist shortage:Biosafety level 2+ handling requirements and orthopoxvirus-specific training curricula constrain laboratory workforce expansion.
- Validation timeline compression:Accelerated WHO target product profile updates force manufacturers to redesign analytical validation studies mid-development.
- Integration complexity with laboratory information systems:Disparate data standards between public health reporting networks and hospital EMR platforms create manual transcription bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monkeypox Testing Market |
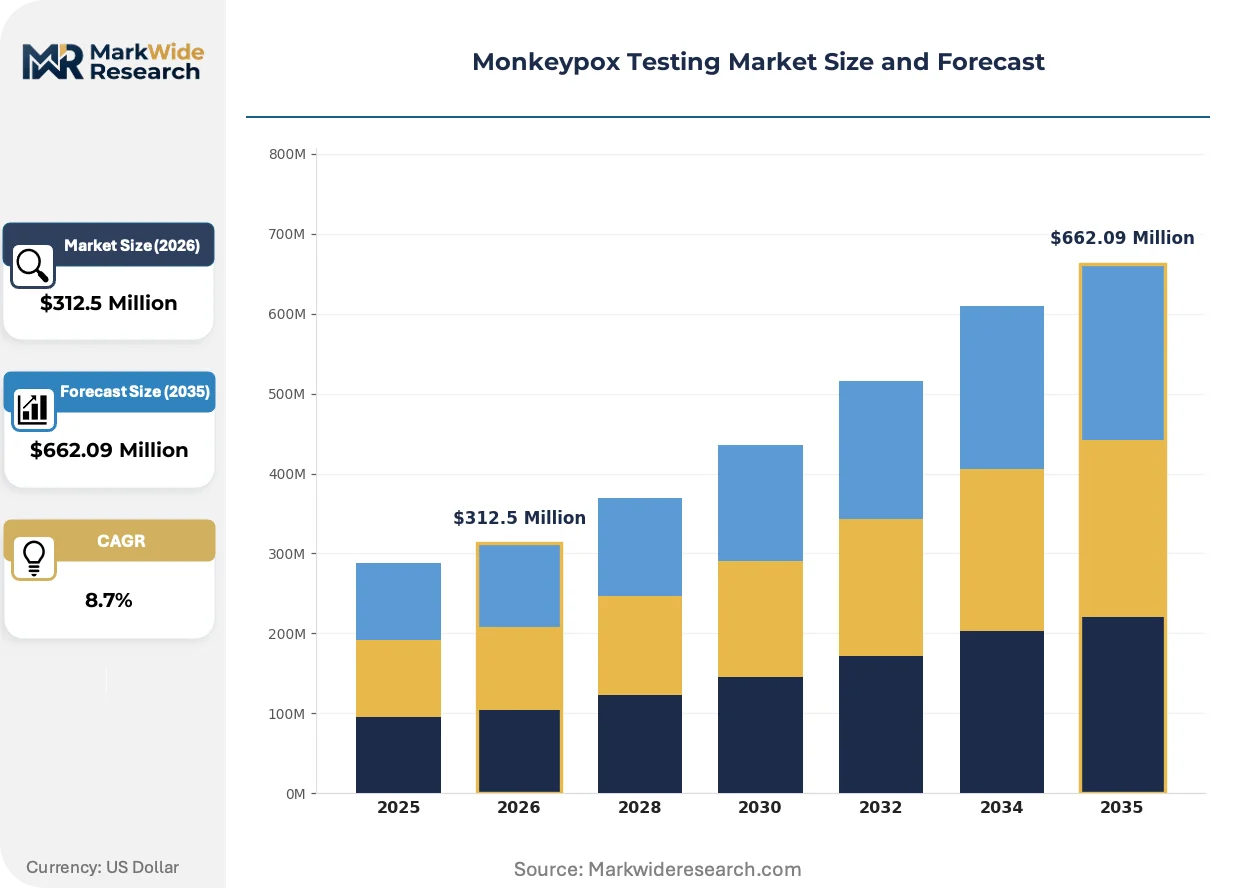
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RT-PCR Tests, Antigen Tests, Serology Tests, Viral Culture End User: Hospitals, Laboratories, Diagnostic Centers, Research Institutions Sample Type: Swab Samples, Blood Samples, Tissue Samples, Serum Samples Distribution Channel: Direct Sales, Online Sales, Third-Party Distributors, Healthcare Institutions |
| Companies Covered | Abbott Laboratories, Aegis Sciences Corporation, Quest Diagnostics, Laboratory Corporation of America Holdings, Thermo Fisher Scientific, Becton Dickinson and Company, QIAGEN, Sonic Healthcare, Mayo Clinic Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monkeypox Testing Market Strategic Shifts & Innovations
Detection chemistry platforms are converging with digital health infrastructure, compressing the interval between specimen collection and epidemiological notification while enabling real-time outbreak mapping.
Isothermal amplification methods are absorbing development investment from conventional thermal cycling approaches. Manufacturers targeting resource-limited settings are adopting loop-mediated amplification and recombinase polymerase amplification chemistries that operate at constant temperature without precision heating hardware. This technical trajectory is absorbing market share from laboratory-bound PCR workflows by eliminating instrument capital requirements and reducing power consumption.
EMA's In Vitro Diagnostic Medical Devices Regulation is reshaping conformity obligations for European distribution. Manufacturers previously operating under the IVDD directive face expanded clinical evidence requirements and notified body involvement for higher-risk class devices. Small and mid-sized assay developers are responding by prioritizing CE-IVD certification for automated extraction-instrument pairings rather than standalone reagent submissions.
Procurement authority is migrating from centralized public health agencies to hospital supply chain departments. Acute care networks are consolidating testing decisions under value-analysis committees that evaluate total cost-per-result rather than kit price alone. This behavioral shift is most pronounced in the United States, where integrated delivery networks negotiate multi-year sole-source agreements with preferred diagnostic vendors.
Monkeypox Testing Market Segmentation
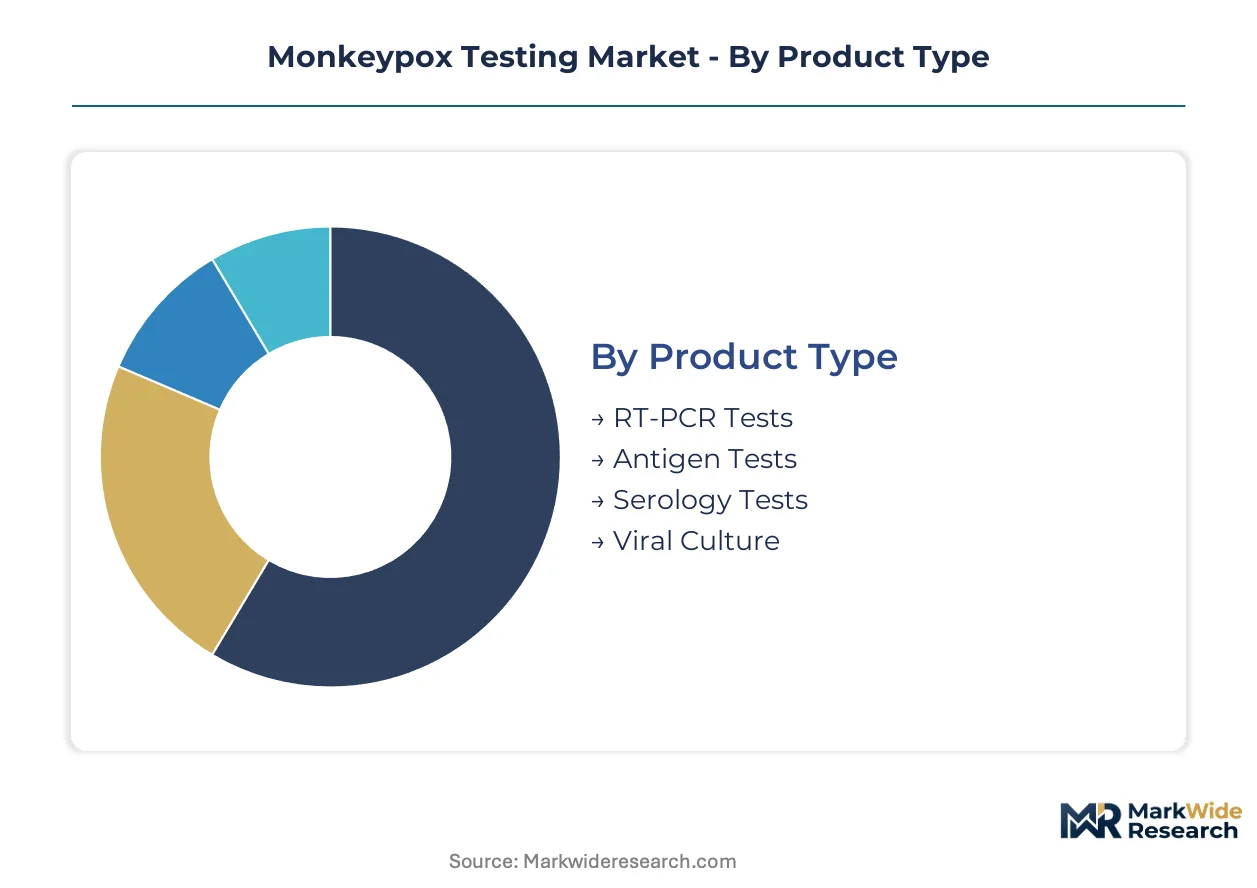
Testing modality selection determines workflow integration depth, capital requirements, and reimbursement pathways across clinical settings. Segment boundaries reflect divergent technical capabilities rather than interchangeable substitutes.
Product Type:
RT-PCR assays anchor laboratory-bound workflows with embedded extraction-automation systems, while antigen formats enable standalone point-of-care deployment without thermal cycling infrastructure.
- RT-PCR Tests:Real-time polymerase chain reaction platforms target conserved orthopoxvirus genomic regions with analytical sensitivity below 100 copies per reaction. Hospital diagnostic programs in the United States absorb the majority of placements, driven by FDA emergency use authorization pathways that accelerate commercial entry.
- Antigen Tests:Lateral flow and cartridge-based immunoassays detect viral surface proteins without nucleic acid amplification. Demand concentrates in emergency departments and urgent care settings where 15-minute turnaround displaces laboratory send-out workflows.
- Serology Tests:Antibody detection assays support retrospective outbreak investigation and epidemiological surveillance.
- Viral Culture:Biosafety level 3 containment requirements restrict use to specialized reference laboratories with advanced containment infrastructure.
Volume placements concentrate in RT-PCR Tests; the faster expansion belongs to Antigen Tests.
End User:
Procurement authority migration from public health agencies to hospital supply chains restructures segment economics around total cost-per-result metrics rather than kit price alone.
- Hospitals:Acute care networks consolidate testing under value-analysis committees negotiating multi-year sole-source agreements. Integrated delivery networks in the United States prioritize syndromic panel compatibility over standalone poxvirus assays.
- Laboratories:Reference and commercial laboratories compete on specimen logistics networks and automated throughput capacity.
- Diagnostic Centers:Decentralized facilities favor rapid antigen formats with minimal technical staffing requirements.
- Research Institutions:Academic medical centers drive validation studies for novel detection chemistries and CRISPR-based platforms.
Procurement volume tilts toward Hospitals; margin expansion favors Laboratories with scale economies.
Sample Type:
Collection methodology determines biosafety handling protocols, transport stability windows, and extraction chemistry compatibility across testing workflows.
- Swab Samples:Lesion and oropharyngeal swabs dominate acute-phase diagnostic protocols with established viral load correlation. WHO orthopoxvirus surveillance guidance mandates swab collection for member state reporting compliance.
- Blood Samples:EDTA plasma supports viremia detection during prodromal illness phases prior to lesion formation.
- Tissue Samples:Biopsy specimens enable histopathological confirmation in atypical presentations.
- Serum Samples:Paired acute-convalescent serology supports epidemiological linkage investigations.
Standardized workflows center on Swab Samples; Blood Samples gain traction for pre-lesion detection windows.
Distribution Channel:
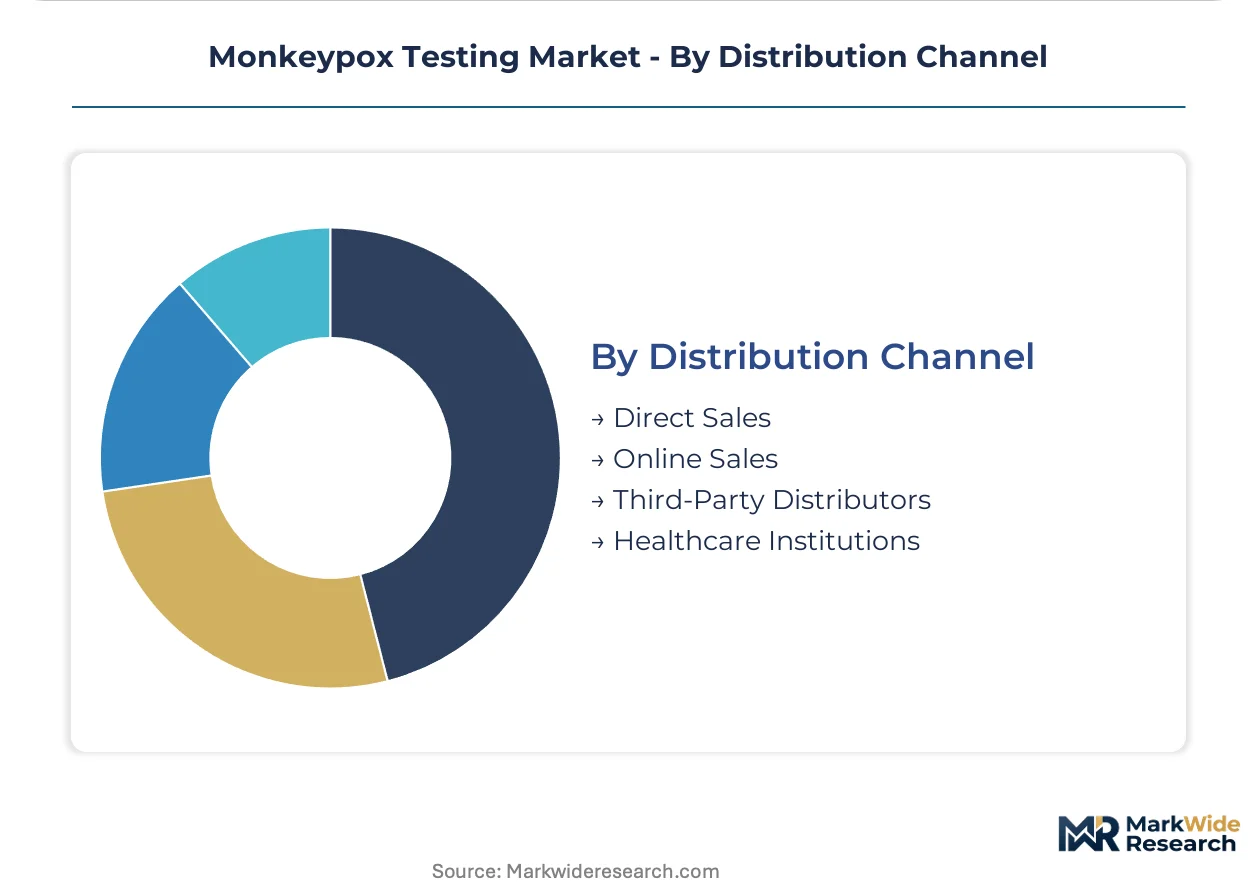
Channel selection reflects customer scale, technical support requirements, and cold-chain logistics dependencies for reagent stability.
- Direct Sales:Manufacturer field organizations serve high-volume hospital systems with integrated instrument-reagent contracts. Thermo Fisher Scientific and QIAGEN deploy dedicated clinical specialists for real-time PCR platform installations.
- Online Sales:E-commerce portals address research-use-only reagents and small-lot specialty consumables.
- Third-Party Distributors:Regional logistics networks extend reach to mid-tier diagnostic centers lacking direct manufacturer relationships.
- Healthcare Institutions:Group purchasing organizations aggregate demand across affiliated facilities for price leverage.
Revenue concentration sits with Direct Sales; channel expansion is accelerating fastest through Third-Party Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for life sciences manufacturing in Singapore and Ireland concentrate diagnostic reagent production, while tax incentives in Puerto Rico and Switzerland anchor regional distribution hubs for multinational suppliers.
United States
Hospital diagnostic programs absorb molecular testing capacity as FDA emergency use authorization pathways accelerate PCR platform commercial entry. The FDA streamlines premarket review timelines for orthopoxvirus detection assays. Boston-Cambridge biotech clusters host validation studies for novel CRISPR-based diagnostics with smartphone readout capabilities.
Germany
Automated nucleic acid extraction system demand concentrates in reference laboratories serving cross-border European specimen flows. The EMA's CE-IVD framework shapes conformity requirements for manufacturers distributing across member states. The Rhine-Main region houses notified body operations that certify higher-risk class diagnostic devices under expanded clinical evidence requirements.
United Kingdom
Integrated care systems consolidate procurement authority under value-analysis committees evaluating total cost-per-result metrics. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device regulations with retained EU law frameworks. London-Oxford-Cambridge golden triangle research institutions drive validation studies for isothermal amplification chemistries.
India
Diagnostic center expansion in tier-2 cities creates demand for point-of-care antigen formats with minimal technical staffing requirements. The Central Drugs Standard Control Organization regulates import and manufacture of in vitro diagnostics under the Medical Device Rules. Hyderabad-Genome Valley clusters specialize in contract research for multiplex respiratory panel integration with poxvirus detection modules.
Brazil
Public health laboratory networks in São Paulo and Rio de Janeiro prioritize syndromic testing platforms over standalone poxvirus assays. ANVISA governs premarket registration and quality certification for imported diagnostic reagents. The São Paulo state health secretariat operates the largest reference laboratory capacity for orthopoxvirus confirmation in Latin America.
Monkeypox Testing Market Key Industry Players
Top-tier vendors anchor instrument-reagent integrated contracts, while mid-tier specialists compete on specimen logistics and automated throughput capacity. The market structures around three tiers: multinational platform manufacturers with installed instrument bases, national reference laboratories with logistics networks, and point-of-care format developers compressing detection timelines. Strategic moves concentrate on M&A for molecular platform portfolios and capacity expansion in automated extraction consumables.
Within the multinational platform tier, Thermo Fisher Scientific and QIAGEN represent instrument-reagent integration archetypes, while Quest Diagnostics occupies a position exemplifying national logistics network scale. Abbott Laboratories anchors the point-of-care format development vector with lateral flow expertise. These three companies illustrate competitive positioning across workflow integration, specimen throughput, and rapid detection format specialization.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Aegis Sciences Corporation |
| Quest Diagnostics |
| Laboratory Corporation of America Holdings |
| Thermo Fisher Scientific |
| Becton Dickinson and Company |
| QIAGEN |
| Sonic Healthcare |
| Mayo Clinic Laboratories |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up diagnostic laboratory networks in the United States anchor procurement concentration, translating volume scale into reagent pricing leverage while channeling supply commitments toward automated extraction-instrument pairings that lock in multi-year contracts.
Pricing Analysis
Short lead-time premiums apply to emergency-use-authorized PCR platforms, while spot inventory of antigen test consumables trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared assays from CE-IVD equivalents and research-use-only reagents. Price differentiation hinges on certification tier and after-sales technical support bundling. Cost compression in the standard tier intensifies because hospital value-analysis committees prioritize total cost-per-result over kit price alone. Diagnostic centers exhibit highest price sensitivity; integrated delivery networks negotiate least.
Supply Chain Analysis
Automated nucleic acid extraction consumables rest on specialty chemical producers concentrated in Germany and the United States. Polymerase enzymes draw from recombinant protein foundries in Switzerland and South Korea. Magnetic bead chemistries hinge on ferrite nanoparticle suppliers in Japan. Single-source vulnerability concentrates in proprietary extraction buffer formulations. Distribution runs through direct sales field organizations serving high-volume hospital systems, supplemented by third-party regional logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Isothermal amplification chemistries are displacing legacy thermal cycling PCR workflows, compressing instrument capital requirements and power consumption thresholds across resource-limited deployment settings.
For Market Incumbents: Deploy backward integration into automated extraction consumables manufacturing to defend against batch shortage vulnerabilities and secure sole-source contract renewals. Fortify installed instrument bases with software companion development for laboratory information system integration, addressing manual transcription bottlenecks that erode hospital customer retention. Antigen test format substitution from point-of-care entrants threatens PCR volume retention in emergency department settings. For New Entrants and Emerging Players: Capture sub-Saharan African surveillance infrastructure gaps with portable molecular devices featuring battery-independent thermal cycling. Target tier-2 Indian diagnostic centers with minimal technical staffing requirements for rapid antigen format penetration. Pursue WHO target product profile alignment as the go-to-market angle for national health ministry procurement channels. For Investors and Strategic Acquirers: Distressed-cycle entries favor automated nucleic acid extraction specialists with EMA CE-IVD certification progress in the Rhine-Main corridor. Long-term viability over the coming decade centers on convergence with multiplex respiratory panel integration rather than standalone poxvirus assay positioning. Watch FDA emergency use authorization pathway streamlining as the inflection indicator for PCR platform valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVD Certification Pathway | EMA notified body involvement expands market access across European member states under MDR requirements. |
| Hospital System Partnership | Integrated delivery network sole-source agreements anchor multi-year reagent revenue visibility. |
| Software Companion Development | Laboratory information system integration eliminates manual transcription bottlenecks in public health reporting. |
| Reimbursement Strategy | CMS coding alignment for PCR-based detection secures favorable coverage determination for hospital diagnostic programs. |
| Backward Integration into Extraction Consumables | In-house production of magnetic bead chemistries reduces dependency on German and Japanese specialty suppliers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews spanning diagnostic laboratory directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. FDA emergency use authorization databases, EMA CE-IVD certification registers, WHO target product profile documentation, and hospital procurement databases supplied validation layers. Bottom-up instrument placement counts and top-down national health ministry expenditure estimates were triangulated.
Segment-level modeling addressed testing modality, end-user procurement authority, sample type collection methodology, and distribution channel structure across the analysis window. CAGRs were derived from logistic diffusion curves fitted to technology adoption patterns. Isothermal amplification chemistry penetration rates and syndromic panel integration timelines served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to WHO case definition criteria revisions and FDA authorization pathway modifications. Assumptions reflect current regulatory frameworks and technology trajectories. Regulatory restriction tightening, supply concentration disruption, and workforce shortage intensification warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
US & Europe Extractable and Leachable Testing Services Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Employer and Workplace Drug Testing Market
Testing Services
Global Cannabis Testing Market
Testing Services
Test Strips Market
Testing Services
Global Metabolic Testing Market
Testing Services
Fertility and Pregnancy Rapid Test Kits Market
Testing Services
Skin Perfusion Pressure Testing Devices Market
Testing Services
Warfarin Sensitivity Testing Market
Testing Services
Europe Endotoxin and Pyrogen Testing Market
Testing Services
Nucleic Acid Testing Market
Testing Services
Global Homocysteine Testing Market
Testing Services
Rapid Test Cards Market
Testing Services
Drug Screening Laboratory Service Market
Testing Services
Anticoagulant Therapeutic Drug Monitoring Assay Kits Market
Testing Services
Global Bioburden Testing Market