
 Global Direct to Consumer Laboratory Testing Market | 2026-2036
Global Direct to Consumer Laboratory Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Direct to Consumer Laboratory Testing Market Foresight
Test bundling into modular wellness panels is repositioning buyer choice away from single-marker purchases toward integrated health assessments. Everlywell, Inc. leverages this shift by packaging hormone, nutritional, and metabolic markers into unified offerings. Quest Diagnostics Incorporated anchors the market through its national laboratory infrastructure and physician-review capabilities. LetsGetChecked competes on subscription models that sustain recurring revenue from chronic condition monitoring.
Direct to consumer laboratory testing encompasses clinical-grade diagnostic assays performed on self-collected samples—saliva, finger-prick blood, or urine—analyzed in CLIA-certified laboratories with results delivered through encrypted digital portals. Genetic testing dominates the test type segment due to high consumer willingness to pay for ancestry and pharmacogenomic insights, while infectious disease screening represents the fastest-growing category as post-pandemic behavioral shifts normalize at-home pathogen detection. Online platforms control the distribution channel landscape, though telehealth services are capturing margin pools by embedding test ordering within virtual consultations.
FDA oversight of laboratory-developed tests, HIPAA privacy safeguards, and CLIA quality standards collectively determine market access and product liability exposure for participants. The EU In Vitro Diagnostic Regulation and GDPR impose parallel compliance burdens on European entrants, while China's NMPA accelerates domestic market development through streamlined innovation pathways. Stakeholders must monitor regulatory divergence between jurisdictions as a primary determinant of geographic expansion sequencing and partnership strategy.
Market Dynamics
Test bundling into modular wellness panels is compressing single-marker purchases and elevating integrated health assessments as the dominant transaction format. This structural shift rewards platforms with CLIA-certified laboratory networks and encrypted digital infrastructure.
Growth Catalysts
- Chronic disease self-monitoring:Individual consumers managing diabetes, thyroid disorders, and cardiovascular conditions generate recurring demand for at-home metabolic and hormonal panels.
- HIPAA-compliant digital infrastructure:Encrypted patient portals and telehealth integrations reduce friction in result delivery and physician consultation workflows across the United States.
- Post-pandemic pathogen detection normalization:Behavioral shifts from COVID-19 sustain infectious disease screening volumes in Germany and China.
Market Restraints
- FDA laboratory-developed test oversight:Pre-market notification requirements and enforcement discretion changes create compliance uncertainty for assay developers.
- CLIA certification concentration:High-complexity laboratory accreditation bottlenecks in metropolitan clusters limit geographic test availability.
- Physician-review mandate variability:State-level requirements for clinician involvement in result interpretation fragment operational models across United States jurisdictions.
Strategic Opportunities
- EU In Vitro Diagnostic Regulation transition:MDR compliance deadlines in 2026-2028 create first-mower advantage for CE-marked at-home testing platforms in Germany and France.
- Pharmacogenomic integration:Convergence of genetic testing with medication management protocols opens reimbursement pathways through pharmacy benefit managers.
- Subscription-based chronic monitoring:Recurring revenue models for HbA1c, lipid, and thyroid panels penetrate employer wellness programs and health plan preventive care incentives.
Industry Challenges
- CLIA high-complexity laboratory director recruitment:Pathologist and doctoral-level scientist scarcity constrains assay validation and quality control scaling.
- Sample stability logistics:Temperature-controlled shipping infrastructure for saliva, dried blood spot, and urine specimens requires capital-intensive cold chain partnerships.
- Interoperability with electronic health records:HL7 FHIR integration complexity delays seamless data exchange between consumer platforms and hospital systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Direct to Consumer Laboratory Testing Market |
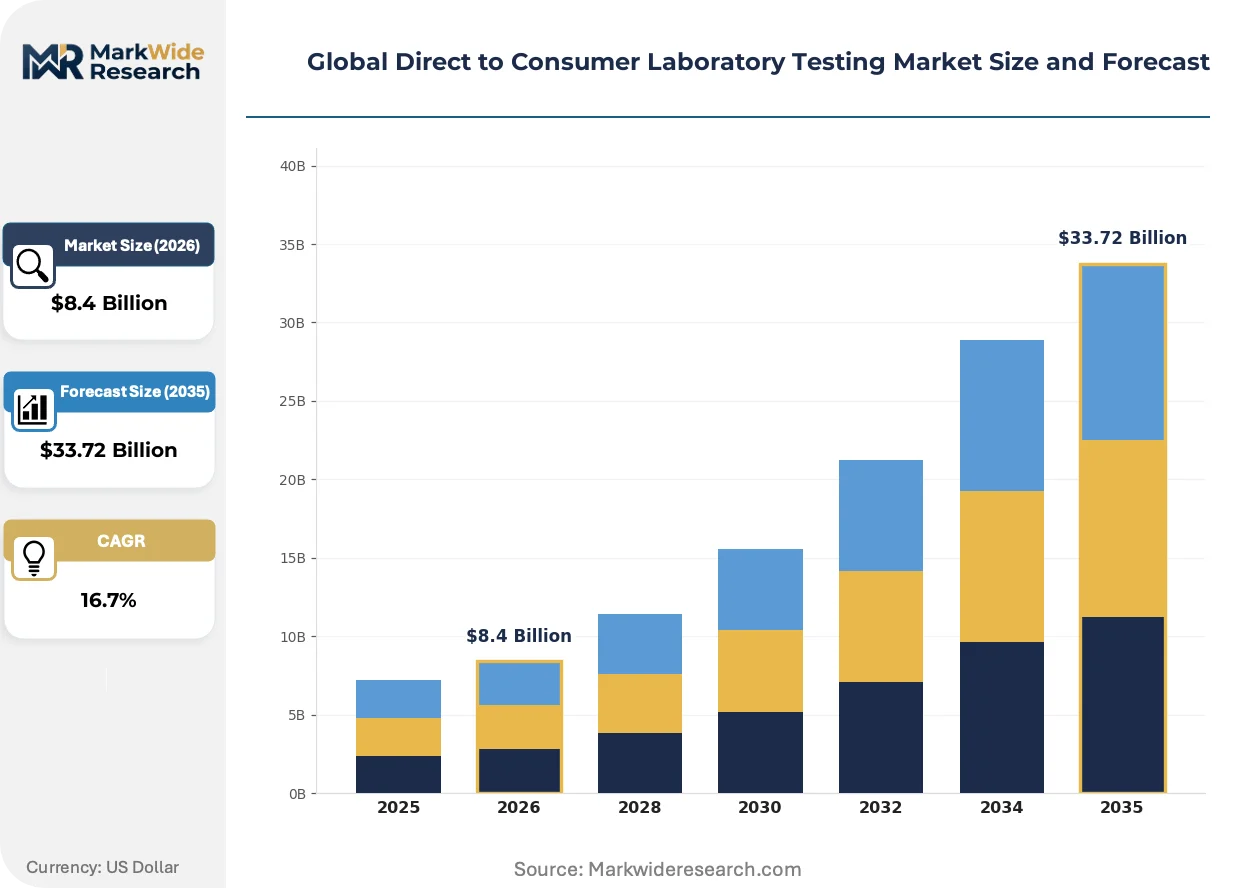
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $33.72 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Genetic Testing, Nutritional Analysis, Infectious Disease Screening, Hormone Levels, Allergy Testing, Toxicology Distribution Channel: Online Platforms, Pharmacies, Clinics & Wellness Centers, Mail-in Kits, Retail Health Outlets, Telehealth Services End User: Individual Consumers, Fitness Enthusiasts, Health Coaches, Workplace Wellness Programs, Insurance Customers, Academic Researchers Service Model: Subscription Plans, Pay-per-Test, Custom Panels, Physician-Reviewed Reports, Mobile App Integration, Real-Time Dashboard |
| Companies Covered | 23andMe, Inc., Everlywell, Inc., LetsGetChecked, Color Genomics, Ancestry.com LLC, Helix, Inc., Labcorp, Quest Diagnostics Incorporated, Any Lab Test Now, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Direct to Consumer Laboratory Testing Market Shifts & Advancements
Microfluidics and smartphone-connected biosensors are compressing sample-to-result timelines from days to minutes. These converging technologies reshape competitive positioning around speed, cost, and user experience rather than laboratory scale alone.
Microfluidic cartridge systems for finger-prick blood analysis is modularizing metabolic and infectious disease panels into pocket-sized devices. Early adopters in employer wellness and pharmacy retail channels deploy these platforms for point-of-collection screening. This technology is modularizing the traditional centralized laboratory model into distributed, consumer-controlled testing nodes.
China's NMPA streamlined innovation pathways for domestic in vitro diagnostic developers accelerate market entry timelines for at-home testing platforms. The regulatory shift compresses clinical validation requirements for Class II devices while maintaining post-market surveillance obligations. Domestic manufacturers in Beijing and Shanghai exploit this tailwind to expand genetic and infectious disease assay portfolios ahead of multinational competitors.
Employer-sponsored wellness programs are unbundling preventive screening from traditional health plan structures and contracting directly with testing platforms. This procurement pattern displaces broker-mediated insurance channels in United States metropolitan markets. Technology and financial services verticals in California and New York lead this behavioral shift, prioritizing population health data integration over conventional claims-based care models.
Global Direct to Consumer Laboratory Testing Market Segmentation
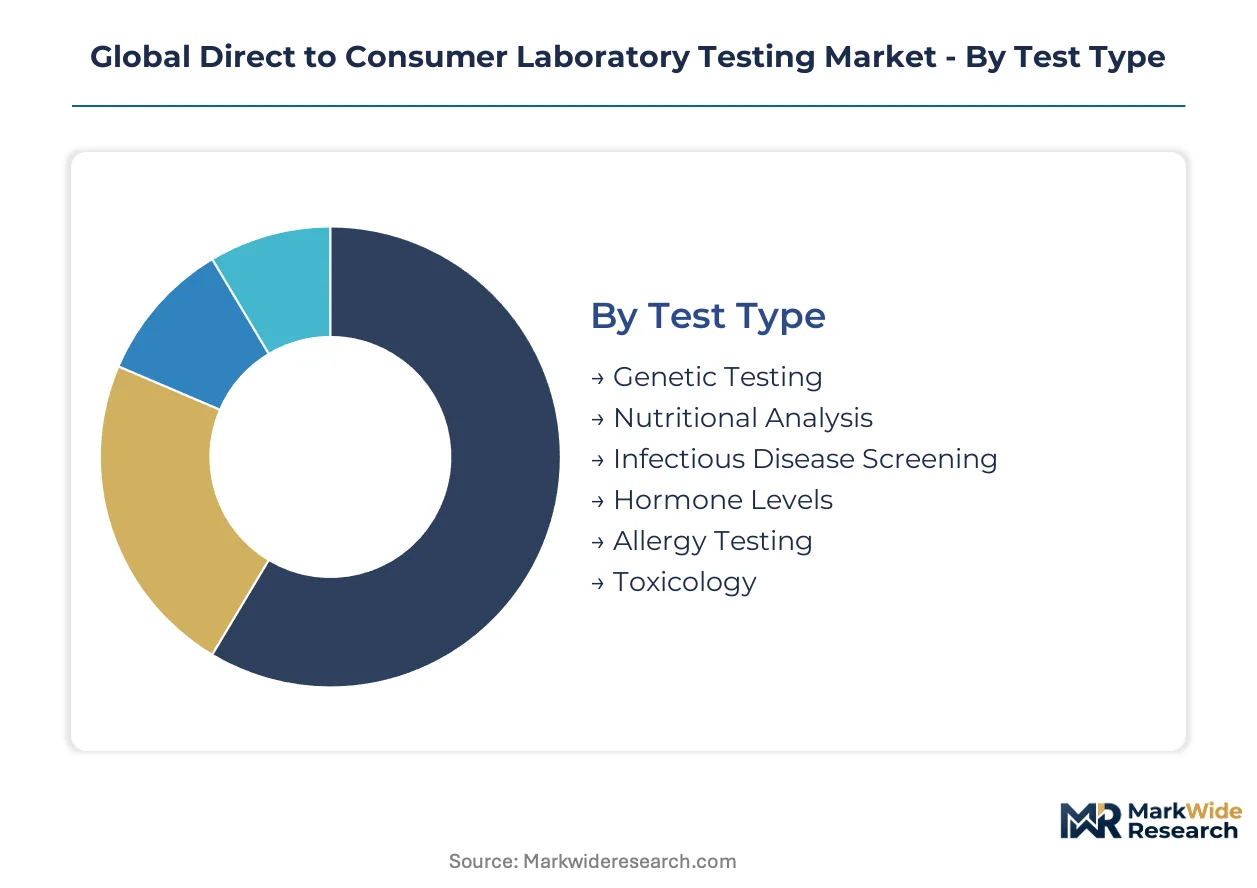
Test bundling into modular wellness panels is fragmenting traditional diagnostic categories and creating new purchase logic across the Global Direct to Consumer Laboratory Testing Market. Segmentation now tracks consumer control over sample collection, result delivery speed, and integration with ongoing health management rather than clinical site of service alone.
Test Type:
Replacement cycles accelerate where consumers upgrade from ancestry-only genetic panels to pharmacogenomic and health-risk assessments, compressing repurchase intervals from years to quarters.
- Genetic Testing:DNA-based assays covering ancestry, carrier status, and drug response prediction command premium pricing due to high consumer willingness to pay for personalized insights. Demand concentrates in the United States and China, where direct-to-consumer marketing bypasses traditional physician gatekeeping.
- Nutritional Analysis:Micronutrient and metabolite profiling identifies vitamin deficiencies and dietary optimization opportunities through blood or urine biomarkers. Fitness enthusiasts and health coaches in Germany drive volume through employer wellness program subsidies.
- Infectious Disease Screening:At-home pathogen detection for respiratory, sexual health, and gastrointestinal infections.
- Hormone Levels:Thyroid, reproductive, and stress hormone panels for chronic condition monitoring.
- Allergy Testing:IgE-mediated sensitivity screening using finger-prick blood or saliva samples.
- Toxicology:Heavy metal, environmental toxin, and substance exposure assessment.
Volume placements concentrate in Genetic Testing; the faster expansion belongs to Infectious Disease Screening.
Distribution Channel:
Cost tier stratification separates premium telehealth-integrated channels from economy mail-in alternatives, with mid-market online platforms capturing the largest transaction volume.
- Online Platforms:Direct-to-consumer websites and mobile applications handle test ordering, sample tracking, and encrypted result delivery. Individual consumers in the United States favor these channels for price transparency and subscription flexibility.
- Telehealth Services:Virtual consultations embedding test ordering within clinician workflows capture higher margins through physician-review mandates. China's NMPA streamlined approval pathways accelerate domestic platform expansion ahead of multinational entry.
- Pharmacies:Retail locations offering in-person kit pickup and sample collection support.
- Clinics & Wellness Centers:Physical sites integrating testing with preventive care services.
- Mail-in Kits:Lowest-cost channel with longest result turnaround times.
- Retail Health Outlets:Supermarket and big-box store placement for impulse wellness purchases.
Transaction density clusters in Online Platforms; margin capture concentrates in Telehealth Services.
End User:
Customer type maturity separates recurring subscription demand from one-off diagnostic purchases, with institutional buyers commanding volume discounts unavailable to individual consumers.
- Individual Consumers:Self-directed purchasers managing personal health information and chronic conditions through at-home sample collection. Germany's GDPR-compliant platform infrastructure supports privacy-sensitive adoption.
- Workplace Wellness Programs:Employer-sponsored preventive screening contracts displace traditional health plan channels in United States metropolitan markets. Technology and financial services verticals in California and New York prioritize population health data integration.
- Fitness Enthusiasts:Performance-optimization seekers tracking biomarkers for training adaptation.
- Health Coaches:Practitioners using test results to guide client dietary and lifestyle interventions.
- Insurance Customers:Policyholders accessing testing through preventive care incentives.
- Academic Researchers:Institutional buyers leveraging aggregated de-identified data for population studies.
Revenue recurrence is strongest among Workplace Wellness Programs; penetration depth is greatest among Individual Consumers.
Service Model:
Margin structure varies sharply between subscription recurring revenue and episodic pay-per-test transactions, with custom panels extracting premium pricing through personalization.
- Subscription Plans:Recurring delivery of metabolic, hormonal, or infectious disease panels sustains long-term customer relationships. Chronic disease self-monitoring in the United States generates predictable revenue streams from diabetes and thyroid management.
- Physician-Reviewed Reports:Clinician interpretation of results satisfies state-level mandate variability across United States jurisdictions. HIPAA-compliant digital infrastructure enables encrypted portal delivery and telehealth integration.
- Pay-per-Test:Single-transaction purchasing for episodic diagnostic needs.
- Custom Panels:User-configured biomarker combinations for specific health concerns.
- Mobile App Integration:Smartphone-connected biosensors and result tracking.
- Real-Time Dashboard:Continuous data visualization for longitudinal health monitoring.
Customer lifetime value peaks with Subscription Plans; regulatory compliance differentiation centers on Physician-Reviewed Reports.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Shanghai and Shenzhen accelerate domestic laboratory infrastructure concentration. Tax incentives for medical device innovation draw CLIA-equivalent certification investment. These zones reshape geographic sequencing for multinational platform entry.
United States
Employer wellness program procurement and chronic disease self-monitoring drive transaction density. FDA laboratory-developed test oversight and HIPAA privacy mandates shape compliance architecture. California and New York metropolitan clusters concentrate telehealth-integrated platform headquarters and high-complexity laboratory networks.
China
Post-pandemic pathogen detection normalization and genetic testing demand sustain volume expansion. NMPA streamlined innovation pathways compress Class II device approval timelines for domestic developers. Beijing and Shanghai manufacturing clusters scale microfluidic cartridge production for at-home metabolic panels.
Germany
GDP-compliant platform infrastructure and nutritional analysis adoption through employer subsidies elevate privacy-sensitive purchasing. EU In Vitro Diagnostic Regulation transition deadlines accelerate CE-marking investment for at-home testing platforms. Munich and Berlin laboratory networks specialize in hormone and allergy panel validation.
United Kingdom
Subscription-based chronic monitoring penetration and pharmacy retail channel expansion diversify distribution access. MHRA alignment with EU MDR transitional provisions creates regulatory continuity for assay developers. London fintech and health-tech clusters embed testing platforms within digital banking wellness offerings.
Japan
Aging population chronic condition management and pharmacogenomic integration open reimbursement negotiations with pharmacy benefit managers. PMDA streamlined review pathways for designated medical devices reduce market entry friction. Tokyo and Osaka metropolitan areas concentrate telehealth infrastructure and employer-sponsored preventive screening contracts.
Global Direct to Consumer Laboratory Testing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the Global Direct to Consumer Laboratory Testing Market. National laboratory networks with physician-review capabilities anchor the premium tier, while digital-native platforms capture recurring revenue through subscription models. Three strategic archetypes dominate: CLIA-certified infrastructure owners, telehealth-integrated service bundlers, and microfluidic technology licensors. M&A activity concentrates on laboratory network consolidation and encrypted digital portal acquisition.
Among diversified diagnostic conglomerates, Quest Diagnostics Incorporated and Labcorp occupy positions anchored by national laboratory infrastructure and clinician-review capabilities. Everlywell, Inc. exemplifies the digital-native archetype through modular wellness panel packaging and direct-to-consumer channel control. LetsGetChecked represents subscription-model specialization with recurring revenue architecture for chronic condition monitoring.
| Leading Market Players |
|---|
| 23andMe, Inc. |
| Everlywell, Inc. |
| LetsGetChecked |
| Color Genomics |
| Ancestry.com LLC |
| Helix, Inc. |
| Labcorp |
| Quest Diagnostics Incorporated |
| Any Lab Test Now, Inc. |
| Others |
Supply & Pricing Matrix
Backward integration into CLIA-certified laboratory networks anchors pricing power for platform operators while compressing margins for kit-only vendors dependent on third-party processing. This structural choice separates subscription-model incumbents from transactional competitors in the United States, Germany, and China.
Pricing Analysis
Short lead-time premiums reward telehealth-integrated platforms delivering physician-reviewed results within 48 hours, while mail-in alternatives trade at spot discounts for 5-7 day turnaround. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and clinical review depth. Cost compression in the economy tier intensifies as microfluidic device manufacturers bypass centralized laboratory markups. Individual consumers in Germany exhibit highest price sensitivity due to GDPR-compliant platform infrastructure costs, while employer wellness programs in the United States absorb premium pricing for population health data integration.
Supply Chain Analysis
Dual-sourcing requirements from large employers and health plans mandate multi-supplier qualification for microfluidic cartridge components and reagent chemistries. Manufacturing concentrates in China for device assembly, the United States for high-complexity laboratory processing, and Germany for hormone panel validation. Raw material dependencies span medical-grade plastics, dried blood spot substrates, and temperature-stable reagent formulations. Single-source vulnerability concentrates in CLIA-certified laboratory director recruitment, where pathologist scarcity constrains quality control scaling. Distribution runs through encrypted digital portals for result delivery, with cold chain partnerships handling specimen logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
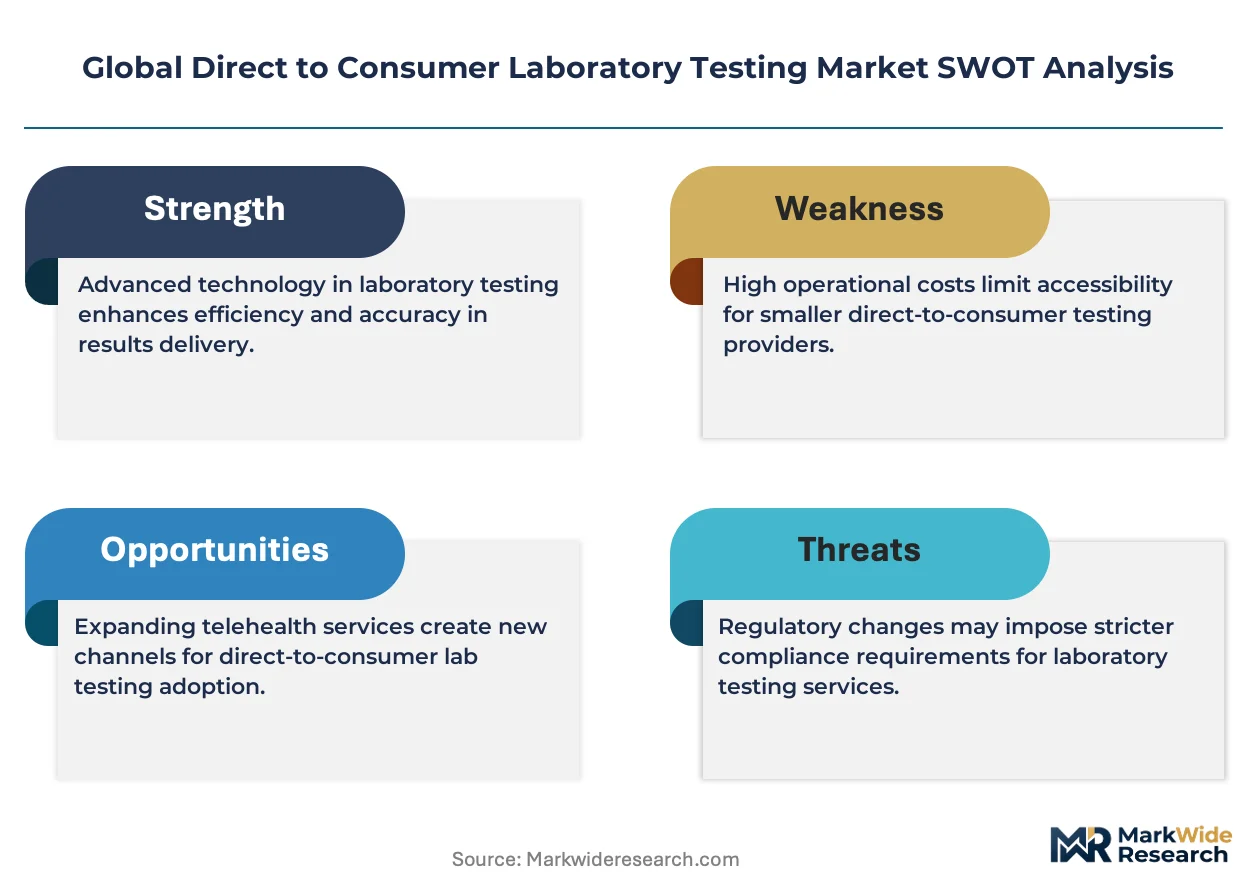
FDA laboratory-developed test oversight creates a cost-of-compliance moat that rewards incumbents with existing 510(k) portfolios while raising capital requirements for new entrants. This regulatory barrier-to-entry protects certified platforms from price erosion.
For Market Incumbents: Anchor defensive positioning through CLIA laboratory network consolidation in California and New York metropolitan clusters, offsetting emerging microfluidic device competitors that modularize testing away from centralized infrastructure. Deepen physician-review capabilities to satisfy state-level mandate variability across United States jurisdictions. Prioritize encrypted digital portal acquisition to lock in employer wellness program contracts before pharmacy retail channels capture point-of-collection screening volume. For New Entrants and Emerging Players: Employer-sponsored wellness programs in technology and financial services verticals represent the most penetrable buyer archetype, as these segments unbundle preventive screening from traditional health plan structures and prioritize data integration over established laboratory relationships. White-space targets include pharmacogenomic integration with pharmacy benefit managers and subscription-based chronic monitoring for diabetes and thyroid management. Deploy direct-to-consumer channel control with telehealth embedding to bypass incumbent laboratory infrastructure advantages. For Investors and Strategic Acquirers: Exit pathways concentrate in platform acquisition by diversified diagnostic conglomerates seeking encrypted digital infrastructure and recurring revenue architecture. Long-term viability favors targets with CLIA-certified laboratory ownership rather than kit-only models vulnerable to margin compression from microfluidic disruption. Watch NMPA approval timelines for Class II devices in China as the inflection indicator for domestic manufacturer competitive positioning against multinational entry.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Laboratory Network Consolidation | High-complexity accreditation in metropolitan clusters defends processing margins against microfluidic modularization. |
| Physician-Review Capability Investment | Clinician interpretation infrastructure satisfies HIPAA-compliant delivery mandates across fragmented United States jurisdictions. |
| Microfluidic Device Licensing | Smartphone-connected biosensor partnerships compress sample-to-result timelines from days to minutes for point-of-collection screening. |
| Employer Wellness Program Direct Contracting | Bypassing broker-mediated insurance channels captures population health data integration demand in California and New York. |
| EU MDR CE-Marking Pathway | Compliance investment ahead of 2026-2028 deadlines secures first-mover positioning in Germany and France privacy-sensitive markets. |
Research Methodology
Independent corroboration across laboratory operations executives, regulatory affairs specialists at CLIA-certified facilities, telehealth platform product managers, and employer benefits directors underwrites the qualitative findings. Secondary validation draws from FDA 510(k) filings, NMPA Class II device approvals, EU MDR notified body documentation, and hospital procurement database extracts. Bottom-up assay volume estimates triangulate against top-down market sizing from encrypted portal transaction data and subscription plan disclosures.
Comparable-period anchoring to pre-pandemic baselines and post-normalization trajectories structures the forecast window across the analysis window. Segmentation dimensions span test type, distribution channel, end user archetype, and service model with geographic regulatory cluster overlays. CAGRs derive from logistic adoption curves for microfluidic technology penetration and recurring revenue retention modeling for chronic condition monitoring subscriptions. Industry-specific inputs include CLIA laboratory capacity expansion timelines and NMPA streamlined pathway approval velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA enforcement discretion changes and CLIA high-complexity laboratory director availability. Deviation in NMPA domestic innovation pathway continuity or EU MDR transitional provision extensions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Beta-Hydroxybutyrate Testing Market
Testing Services
Global Cannabis Testing Market
Testing Services
Over-The-Counter Tests Market
Testing Services
US Pharmaceutical Analytical Testing Outsourcing Market
Testing Services
Irradiation Sterilization Services Market
Testing Services
Asia-Pacific Hereditary Cancer Testing Market
Testing Services
Bioprocess Integrity Testing Systems Market
Testing Services
Global Multiplex Assays Market
Testing Services
Platelet Function Testing Market
Testing Services
Pancreatic Elastase Testing Market
Testing Services
Blood Testing Market
Testing Services
Minimal Residual Disease Testing Market
Testing Services
Industrial Radiography Testing Market
Testing Services
South Korea GMP Testing Service Market
Testing Services
Global Anti Thrombin III Testing Market
Testing Services
Drug Testing Systems Market