
 Range Hood and Cooktop Market | 2026-2036
Range Hood and Cooktop Market Size, Share, and Industry Trends Forecast 2026-2036
Range Hood and Cooktop Market Analytics
Appliance technician certification gaps in advanced induction and smart ventilation diagnostics is bifurcating service capabilities between premium and mass-market channels. Elica S.p.A. leverages Italian design heritage to anchor the European premium segment for island and wall-mounted configurations. Whirlpool Corporation sustains North American volume leadership through captive distribution and in-house production of blower assemblies. Samsung Electronics competes on smart kitchen ecosystem integration, embedding Wi-Fi-enabled hood controls within connected home platforms.
Range hoods and cooktops constitute kitchen ventilation and thermal cooking appliances engineered around specified airflow rates measured in cubic feet per minute, burner BTU output or induction coil wattage, and grease filtration efficiency through baffle or mesh capture systems. Their primary commercial purpose centers on residential and foodservice environments where combustion byproduct extraction and precise heat control determine safety, air quality, and cooking performance. Wall-mounted and island range hood configurations command the highest margin pools due to architectural visibility and custom ducting requirements, while induction fuel sources represent the fastest-growing segment as energy efficiency mandates and consumer preference for responsive thermal control displace conventional gas burners. Smart technology features including automated speed adjustment and sensor-driven grease loading detection are shifting from premium tier exclusivity toward mid-market standard equipment.
The U.S. Department of Energy and the EPA shape product standards through minimum efficiency requirements and indoor air quality guidelines that determine eligibility for utility rebate programs. The EU Ecodesign Directive and F-Gas Regulation restrict refrigerant-based downdraft cooling systems and mandate energy labeling transparency across member states. China's GB standards and SAMR certification govern electromagnetic compatibility and safety for induction cooktop imports. Stakeholders must monitor regulatory divergence between efficiency testing protocols and ventilation performance metrics as these determine competitive market access and product development priority.
Market Dynamics
The U.S. Department of Energy appliance efficiency standards are compressing allowable ventilation airflow rates and cooktop energy consumption, forcing manufacturers to redesign blower assemblies and induction coil configurations while maintaining extraction performance.
Growth Catalysts
- Urban residential tower construction:China's high-rise development integrates built-in kitchen ventilation systems at scale, creating specification pull for ducted range hoods with centralized exhaust infrastructure.
- Induction technology maturation:Responsive thermal control and electromagnetic efficiency are displacing conventional gas burners in residential renovation projects, particularly where municipal gas hookup restrictions apply.
- IRA efficiency rebates:U.S. utility incentive programs tied to ENERGY STAR certification accelerate replacement cycles for aging ventilation equipment in single-family housing stock.
Market Restraints
- Copper and electrical steel volatility:Induction cooktop coil manufacturing depends on concentrated rare earth magnet supply chains subject to export quota fluctuations.
- Custom ducting cost inflation:Island and wall-mounted hood configurations require site-fabricated stainless steel ductwork, constraining margin expansion in premium architectural segments.
- F-Gas Regulation friction:EU restrictions on refrigerant-based downdraft cooling systems eliminate a ventilation alternative for open-plan kitchen layouts without overhead capture.
Strategic Opportunities
- Sensor-driven automation:Grease loading detection and automated speed adjustment technologies are migrating from premium exclusivity toward mid-market standard equipment.
- Smart home convergence:Wi-Fi-enabled hood controls integrated with connected home platforms create ecosystem lock-in and recurring service revenue potential.
- Appliance technician certification gaps:Advanced induction and smart ventilation diagnostics training scarcity creates service capability differentiation for authorized dealer networks.
Industry Challenges
- Diagnostic skill scarcity:Field service networks lack standardized certification for electromagnetic field troubleshooting and blower motor variable-frequency drive replacement.
- Regulatory testing protocol divergence:U.S. DOE efficiency metrics, EU Ecodesign ventilation performance standards, and China GB electromagnetic compatibility requirements impose redundant certification burdens.
- Legacy kitchen infrastructure retrofit complexity:Existing residential ductwork sizing and electrical panel capacity constrain induction cooktop and high-CFM hood upgrades without structural modification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Range Hood and Cooktop Market |
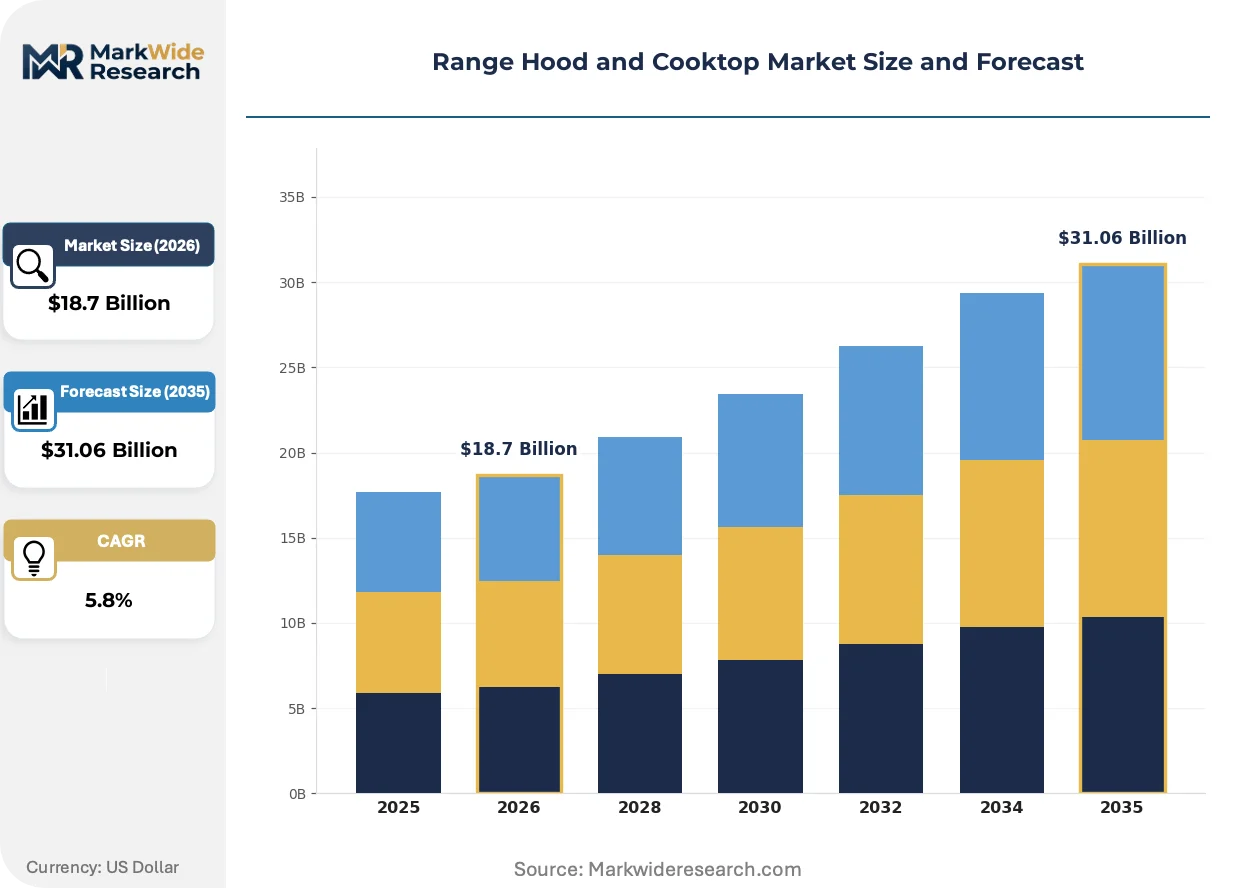
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Under-Cabinet, Downdraft, Island Fuel Source: Gas, Electric, Induction, Dual Fuel Design Style: Modern, Traditional, Professional, Minimalist Features: Smart Technology, Adjustable Speed, Noise Reduction, Energy Efficient |
| Companies Covered | Broan-NuTone LLC, Whirlpool Corporation, Elica S.p.A., Faber S.p.A., BSH Home Appliances, GE Appliances, Samsung Electronics, Zephyr Ventilation, Vent-A-Hood, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Range Hood and Cooktop Market Evolving Landscape
Three distinct vectors are reshaping competitive positioning: intelligent automation penetrating price tiers, regulatory efficiency mandates tightening technical specifications, and service capability fragmentation separating premium from mass-market channels.
Induction coil technology with precision wattage modulation and rapid thermal response is bifurcating the cooktop market. Residential kitchen renovation spending by millennial homeowners concentrates specification authority toward responsive, energy-efficient thermal control. Gas burner incumbents face displacement in markets with electrification mandates or carbon pricing, while induction specialists capture margin in replacement-driven renovation channels.
The EU Ecodesign Directive and F-Gas Regulation are compressing refrigerant-based downdraft system availability while mandating transparent energy labeling. Manufacturers must redesign ventilation architectures around passive capture efficiency rather than active cooling assistance. Wall-mounted and island configurations absorb regulatory pressure through architectural visibility that justifies premium pricing for compliant equipment.
Millennial homeowner renovation spending patterns concentrate replacement demand in specific metropolitan housing markets with aging stock and equity appreciation. Big-box retail and direct-to-consumer channels displace traditional appliance dealer networks for standard configurations. Specification complexity for custom ducting and smart integration preserves dealer relevance in premium island and wall-mounted segments where installation coordination determines outcomes.
Range Hood and Cooktop Market Segmentation
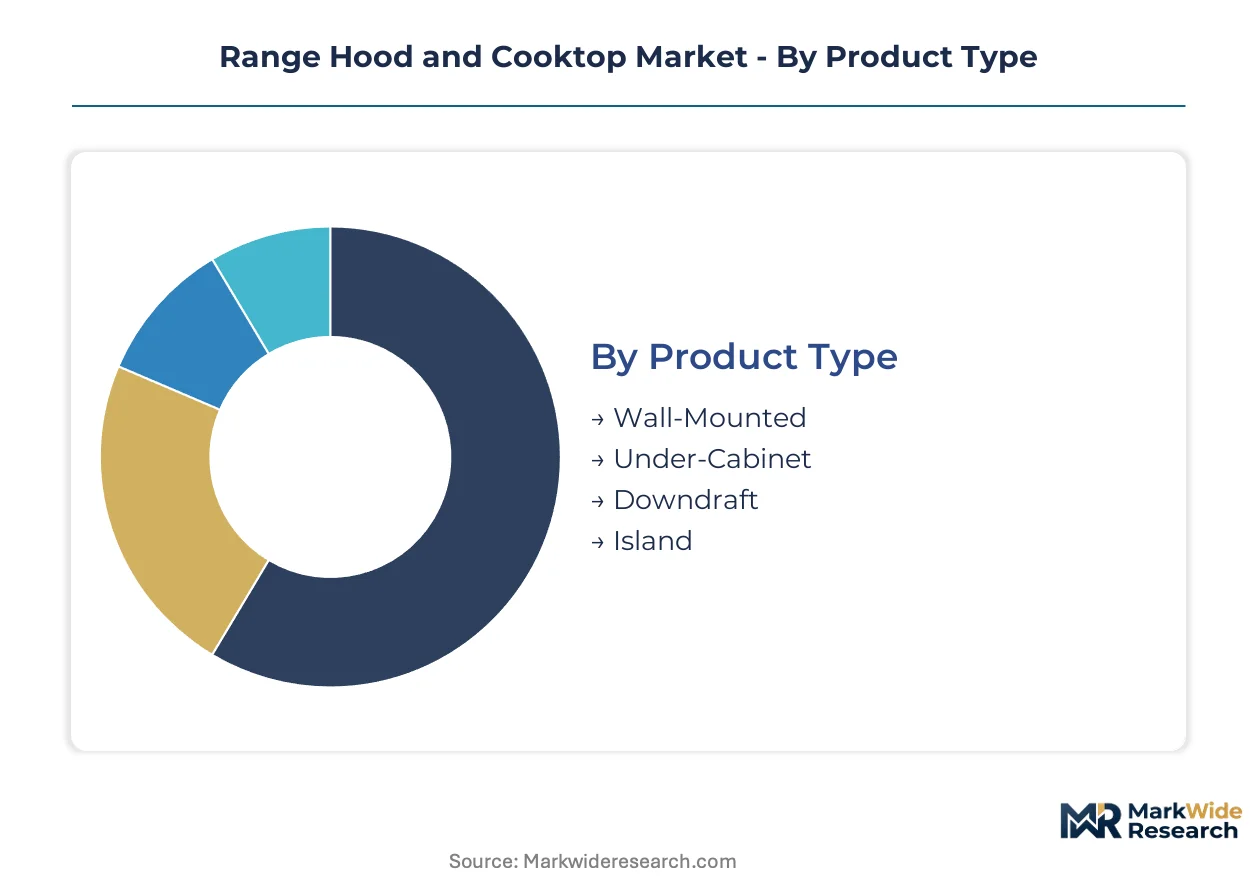
Segmentation in the range hood and cooktop market reflects divergent regulatory pressures across ventilation airflow standards, electromagnetic compatibility requirements, and energy labeling mandates. Manufacturers must architect product portfolios around distinct certification burdens and installation constraints that vary by configuration and fuel source.
Product Type:
Regulatory differentiation in ventilation performance testing protocols separates ducted wall-mounted and island configurations from recirculating under-cabinet alternatives, with DOE minimum efficiency standards applying asymmetrically across installation architectures.
- Wall-Mounted:Vertical chimney-style units with specified cubic-feet-per-minute ratings face tightening DOE airflow efficiency minimums. Demand concentrates in North American single-family renovation channels where existing ductwork infrastructure supports straightforward replacement without structural modification.
- Island:Suspended ceiling-mounted configurations require site-fabricated stainless steel ductwork and custom blower sizing. Residential kitchen renovation spending by millennial homeowners in equity-appreciated metropolitan markets drives specification authority toward these architecturally visible premium installations.
- Under-Cabinet:Compact integrated units dominate builder-specified new construction volumes where cost engineering takes precedence over extraction performance.
- Downdraft:Retractable cooktop-integrated ventilation faces regulatory compression from EU F-Gas Regulation restrictions on refrigerant-assisted cooling variants.
Under-cabinet configurations handle the majority of throughput; island designs are gaining share fastest among renovation-driven replacement cycles.
Fuel Source:
Cost tier stratification separates induction coil systems with rare-earth magnet dependencies from conventional gas burner architectures, with utility rebate eligibility creating mid-market access differentiation.
- Induction:Electromagnetic coil technology with precision wattage modulation and rapid thermal response carries premium positioning. China's GB electromagnetic compatibility standards and SAMR certification impose import compliance burdens that concentrate supply among vertically integrated manufacturers with in-house coil winding capabilities.
- Gas:Conventional burner systems with specified BTU output face displacement pressure from municipal electrification mandates and carbon pricing in coastal U.S. markets. Foodservice and high-heat cooking applications preserve residual demand where responsive thermal control requirements exceed induction responsiveness.
- Electric:Resistive coil cooktops occupy economy positioning in rental housing and budget renovation channels with minimal regulatory scrutiny.
- Dual Fuel:Hybrid configurations combining gas cooktops with electric ovens serve transitional renovation scenarios where existing electrical panel capacity constrains full induction conversion.
Gas retains the largest installed base; induction is climbing the fastest on share as efficiency rebates and electrification mandates reshape replacement preferences.
Design Style:
Application context determines margin structure, with professional-grade specifications commanding architectural specification fees in custom residential projects while minimalist aesthetics penetrate multifamily developer channels.
- Professional:Heavy-gauge stainless steel construction with commercial-equivalent BTU output or induction wattage targets residential renovation markets seeking restaurant-caliber performance. Custom metal fabrication requirements and dealer installation coordination preserve margin pools against mass-market commoditization.
- Modern:Clean-line geometries with glass and integrated control interfaces align with connected-home platform integration strategies. Big-box retail and direct-to-consumer displacement of traditional dealer networks concentrates volume in standard configurations lacking custom ducting complexity.
- Traditional:Ornate canopy and mantel hood styling serves heritage home renovation markets with aesthetic preservation requirements.
- Minimalist:Flush and concealed ventilation integration supports open-plan kitchen layouts where architectural visibility conflicts with design intent.
Modern styling ships the highest unit volumes; professional specifications carry the steepest expansion trajectory among equity-appreciated housing markets.
Features:
Technology maturity curves separate sensor-driven automation migrating toward mid-market standard equipment from ecosystem-integrated smart platforms remaining premium-exclusive.
- Smart Technology:Wi-Fi-enabled hood controls with connected-home platform integration require FCC certification for radio frequency emissions and create recurring service revenue potential through firmware update subscriptions. Samsung Electronics and ecosystem competitors leverage integration lock-in to defend margin against hardware commoditization.
- Energy Efficient:ENERGY STAR certification eligibility determines IRA rebate program access and utility incentive qualification in U.S. replacement channels. DOE test procedure compliance for ventilation airflow per watt constrains blower motor and variable-frequency drive selection.
- Adjustable Speed:Multi-stage blower control with manual or sensor-actuated modulation addresses varying cooking load intensities.
- Noise Reduction:Acoustic dampening and remote blower mounting targets open-plan layouts where kitchen-living integration elevates sonic comfort specifications.
Adjustable speed appears as baseline equipment across tiers; smart technology integration is expanding most quickly as platform ecosystems extend into kitchen appliance categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Department of Energy anchors the regulatory framework shaping ventilation efficiency standards, while China's urban construction policies concentrate specification demand for integrated kitchen systems across multiple metropolitan clusters.
United States
Millennial homeowner renovation spending and IRA efficiency rebates drive replacement demand for ENERGY STAR-certified ventilation equipment. The DOE appliance efficiency standards tighten minimum airflow requirements for ducted range hoods. Metropolitan markets in California, Texas, and the Northeast Corridor concentrate equity-appreciated housing stock where kitchen upgrades prioritize induction conversion.
China
Urban residential tower construction at scale creates specification pull for built-in kitchen ventilation with centralized exhaust infrastructure. SAMR certification and GB electromagnetic compatibility standards govern induction cooktop imports and domestic production. The Yangtze River Delta and Pearl River Delta clusters concentrate manufacturing capacity for coil winding and blower assembly integration.
Germany
The EU Ecodesign Directive and F-Gas Regulation restrict refrigerant-based downdraft alternatives while mandating transparent energy labeling. REACH compliance requirements shape material selection for stainless steel fabrication and electronic components. Industrial concentration in North Rhine-Westphalia and Bavaria supports precision metalworking for premium architectural hood configurations.
Italy
Design heritage anchors European premium positioning for island and wall-mounted range hood configurations. CE marking and EU energy labeling requirements apply asymmetrically across ducted versus recirculating installation architectures. Manufacturing clusters in Emilia-Romagna and Lombardy specialize in custom metal fabrication for architecturally visible ventilation systems.
Japan
METI efficiency guidelines and JIS standards govern electromagnetic field emissions from induction coil systems. Compact residential footprints in Tokyo and Osaka metropolitan areas favor space-integrated ventilation solutions. Kanto and Kansai industrial corridors concentrate electronics assembly for sensor-driven automation components migrating into mid-market equipment tiers.
Range Hood and Cooktop Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with design-driven specialists commanding premium margins in architectural segments while scale manufacturers defend volume through captive distribution networks. The market structure consolidates around three distinct tiers: heritage European fabricators with custom metalworking capabilities, North American volume producers with in-house blower assembly production, and Asian electronics conglomerates leveraging connected-home platform integration. Strategic moves concentrate on smart home ecosystem lock-in, technician certification program development, and backward integration into rare-earth magnet supply chains for induction coil manufacturing.
Within the heritage design tier, Elica S.p.A. and Faber S.p.A. exemplify Italian positioning anchored to architectural visibility and custom fabrication capabilities. Whirlpool Corporation occupies a scale-driven position with North American volume leadership through captive distribution infrastructure. Samsung Electronics represents the platform-integration archetype, embedding Wi-Fi-enabled controls within broader connected-home ecosystems to differentiate beyond hardware specifications.
| Leading Market Players |
|---|
| Broan-NuTone LLC |
| Whirlpool Corporation |
| Elica S.p.A. |
| Faber S.p.A. |
| BSH Home Appliances |
| GE Appliances |
| Samsung Electronics |
| Zephyr Ventilation |
| Vent-A-Hood |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for rare-earth magnet feedstock concentrate pricing power among vertically integrated induction coil manufacturers while compressing margins for assemblers dependent on spot-market procurement. China's SAMR certification requirements and EU F-Gas Regulation compliance costs amplify cost-to-serve differentials between ducted wall-mounted configurations and recirculating alternatives.
Pricing Analysis
Geographic price spreads between Italian custom-fabricated island hoods and Chinese mass-market under-cabinet units exceed three-to-one on a per-CFM basis. Three-tier pricing structure across premium, standard, and economy levels stratifies by blower assembly origin and ENERGY STAR certification eligibility. Cost compression in mid-market induction cooktops intensifies as IRA rebate programs normalize efficiency premiums into baseline expectations. Builder-specified new construction channels exhibit highest price sensitivity; equity-appreciated metropolitan renovation markets absorb premium positioning for architecturally visible configurations.
Supply Chain Analysis
China and Italy anchor global production for induction coil winding and custom metal fabrication respectively. Rare-earth magnet sourcing draws from concentrated Chinese export quotas; electrical steel for stator laminations hinges on Japanese and South Korean mill capacity. Single-source vulnerability in neodymium supply creates margin volatility for non-integrated manufacturers. Distribution runs through captive dealer networks for premium island configurations; big-box retail and direct-to-consumer channels displace intermediaries for standard under-cabinet volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Induction technology maturation and IRA efficiency rebate expansion constitute a dual inflection reshaping replacement demand trajectories. Manufacturers must recalibrate portfolio allocation between gas burner legacy support and electromagnetic coil capability buildout.
For Market Incumbents: Consolidate backward integration into rare-earth magnet supply chains and captive blower assembly production to defend margin against commodity volatility. Expand technician certification programs for advanced induction diagnostics to preserve dealer network relevance against direct-to-consumer displacement. Lock in ENERGY STAR certification breadth to maximize IRA rebate program access across U.S. metropolitan renovation channels. For New Entrants and Emerging Players: Differentiate on sensor-driven automation features migrating from premium exclusivity toward mid-market standard equipment. Target underpenetrated multifamily developer channels in China's Yangtze River Delta cluster with space-integrated minimalist ventilation solutions. Pursue white-label partnerships with connected-home platform providers to bypass capital-intensive distribution infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across induction coil manufacturing as rare-earth magnet dependencies demand upstream supply control. Long-term viability favors vertically integrated specialists with in-house electromagnetic compatibility testing capabilities. Monitor SAMR certification approval velocity as inflection indicator for Chinese market access competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Captive neodymium sourcing insulates induction coil margins from Chinese export quota volatility. |
| Technician Certification Program Development | Standardized electromagnetic field diagnostics training preserves dealer relevance against direct-to-consumer channels. |
| Smart Home Platform Integration | Wi-Fi-enabled hood controls embedded within Samsung and ecosystem platforms create recurring service revenue. |
| ENERGY STAR Certification Expansion | IRA rebate program eligibility accelerates replacement cycles in U.S. single-family renovation markets. |
| Custom Metal Fabrication Capacity Addition | Italian heritage design positioning commands architectural specification fees in equity-appreciated metropolitan housing. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with appliance manufacturing executives, HVAC contractor network managers, utility rebate program administrators, and residential kitchen renovation specialists; and secondary validation against DOE efficiency standard filings, ENERGY STAR certification databases, EU Ecodesign Directive implementation reports, and China customs trade data. Bottom-up unit shipment modeling triangulated against top-down construction spending and replacement cycle estimates.
Across the projection horizon, the analytical framework segmented volume and value outputs by product configuration, fuel source, design style, and feature tier. CAGRs derived from regression analysis of historical shipment patterns against regulatory milestone timelines and incentive program ramp schedules. Induction technology penetration curves and smart feature adoption rates served as industry-specific demand drivers.
The analysis sits within stated boundaries; outcomes outside sustained IRA rebate funding continuity or abrupt rare-earth export restriction scenarios would require recalibration. Forecasts reflect documented assumptions regarding electrification mandate adoption velocity and millennial homeowner equity extraction patterns. Recalibration cycles align with material shifts in DOE efficiency standard revision schedules and SAMR certification protocol updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Opalware Dinnerware and Crockery Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
Kitchen Faucets Market
Kitchen and Dining
Saudi Arabia Modular Kitchen Market
Kitchen and Dining
Global Kitchen Woks Market
Kitchen and Dining
Sweden Household Electric Grills Market
Kitchen and Dining
Europe Kitchen Hobs Market
Kitchen and Dining
Hobs Market
Kitchen and Dining
Saudi Arabia Kitchen Furniture Market
Kitchen and Dining
Outdoor Kitchen Market
Kitchen and Dining
North America Countertop Market
Kitchen and Dining
Australia Kitchen Furniture Market
Kitchen and Dining
Kitchen Sinks Market
Kitchen and Dining
Rainbow Flatware Market
Kitchen and Dining
Prep Tables Market
Kitchen and Dining
Quartz Sink Market