
 Kitchen Sinks Market | 2026-2036
Kitchen Sinks Market Size, Share, and Industry Trends Forecast 2026-2036
Kitchen Sinks Market Intelligence
A divergence between custom, integrated workstation sinks and basic, drop-in utility models is consolidating market share at the premium and economy ends. Franke leverages its European design heritage to command the high-end segment with feature-rich systems. In contrast, Kohler competes across the entire spectrum with a vast portfolio of materials and styles. Elkay specializes in durable stainless steel sinks, maintaining a strong position in both commercial and residential settings.
A kitchen sink is a plumbing fixture for washing in residential and commercial food preparation areas, fabricated from materials like 16-gauge stainless steel or fired ceramic. Its primary purpose is to provide a contained area for dishwashing, food prep, and general cleaning tasks. Stainless steel leads the material segment in volume, while composite materials see adoption in premium residential applications. Undermount styles dominate new high-end countertop installations, offering a seamless and easy-to-clean surface.
Product design and market access are governed by a matrix of regional and national standards. These include CE marking in Europe for health and safety conformity, ANSI standards in the United States for plumbing compatibility, and China's GB standards for material safety. Future profitability for manufacturers depends on navigating material cost volatility and adapting product lines to regional aesthetic preferences and water conservation mandates.
Market Dynamics
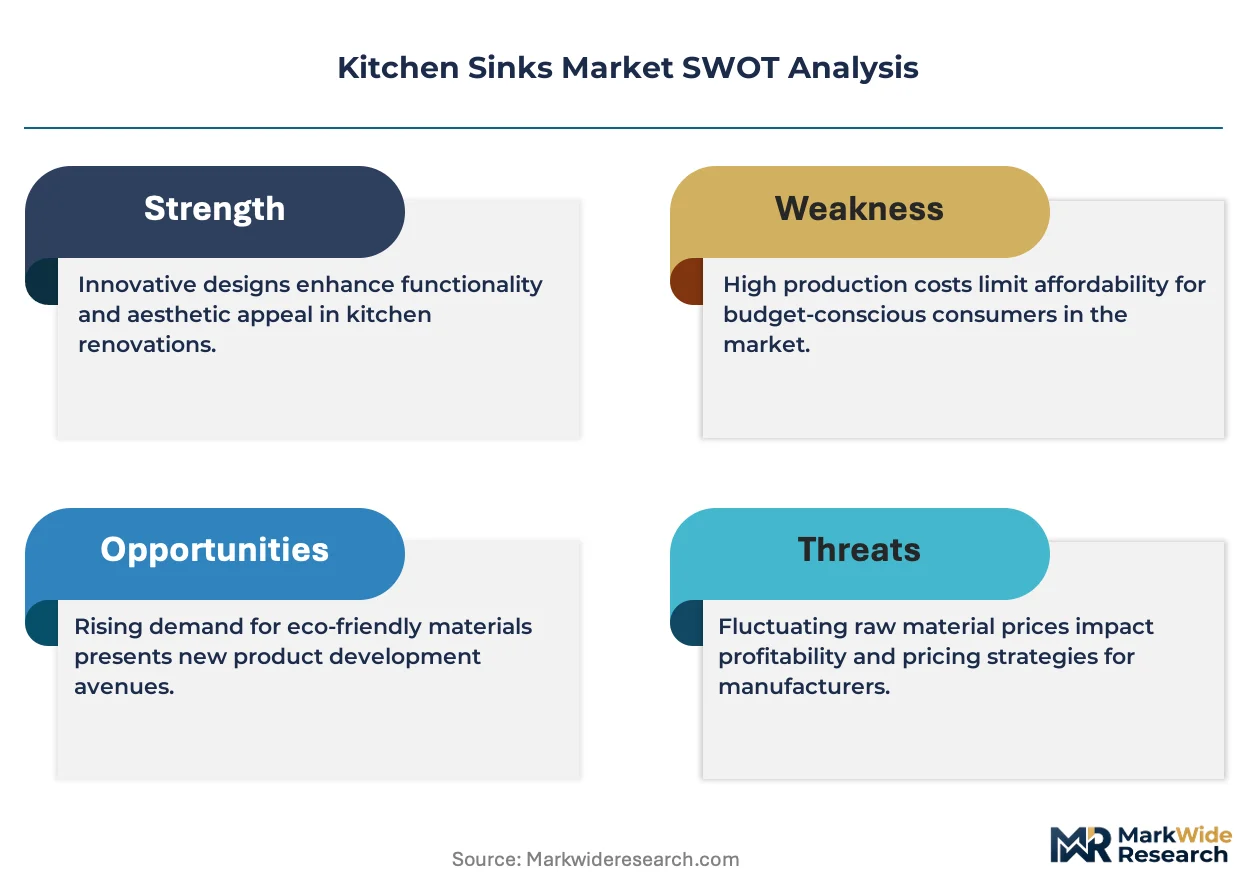
The kitchen sink market is defined by a structural divergence between premium, feature-rich workstation sinks and mass-market utility models. This bifurcation concentrates value at the high-end while driving volume competition in the economy segment, reshaping manufacturing and distribution strategies.
Growth Catalysts
- Urban Residential Construction:New housing projects and urbanization, particularly in high-growth construction hubs within India and Brazil, are creating sustained demand for basic and mid-range kitchen fixtures.
- Advanced Composite Materials:The development of anti-bacterial and scratch-resistant composite sinks, such as granite and quartz composites, is stimulating upgrades in the premium residential renovation sector across Europe and North America.
- Renovation and Remodeling Activity:A persistent focus on home improvement and kitchen remodeling in developed economies provides a stable demand base, with consumers prioritizing aesthetic upgrades and enhanced functionality.
Market Restraints
- Raw Material Price Volatility:Manufacturer margins are constrained by significant price fluctuations in key raw materials, especially nickel and scrap metal for 16-gauge stainless steel, which dominates the market by volume.
- Threat of Integrated Surfaces:The increasing adoption of solid surface and quartz countertops with seamlessly integrated, molded-in sinks presents a substitution threat, potentially bypassing the market for separate drop-in or undermount units.
- Regulatory Compliance Burden:Navigating a complex matrix of regional standards, from CE marking in Europe to ANSI plumbing specifications in the US, adds significant cost and lead time to product development and market entry.
Strategic Opportunities
- Water Conservation Systems:Developing and marketing integrated sink systems with water-efficient faucets and fixtures provides an opportunity to capitalize on stringent water conservation mandates in regions like California and Australia.
- Smart Kitchen Integration:There is a clear opportunity in embedding technology, such as hands-free faucets, integrated water filtration, and sensor-based controls, into high-end sink systems to appeal to the smart home market.
- Emerging Market Penetration:Targeting middle-class consumers in underpenetrated markets across Southeast Asia and Latin America with durable, aesthetically modern, and affordable sink options represents a significant volume opportunity.
Industry Challenges
- Adapting to Aesthetic Shifts:Manufacturers face the challenge of continuously adapting product lines to meet fast-changing regional design preferences, from the minimalist aesthetic in Europe to the farmhouse style popular in the United States.
- Supply Chain Resilience:Managing complex global supply chains for raw materials and components is a persistent operational challenge, exacerbated by fluctuating shipping costs and geopolitical trade friction.
- Multi-Jurisdictional Certification:Securing and maintaining material safety and performance certifications, such as those governed by NSF International or required by China's GB standards, is a costly and time-consuming process for new products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kitchen Sinks Market |
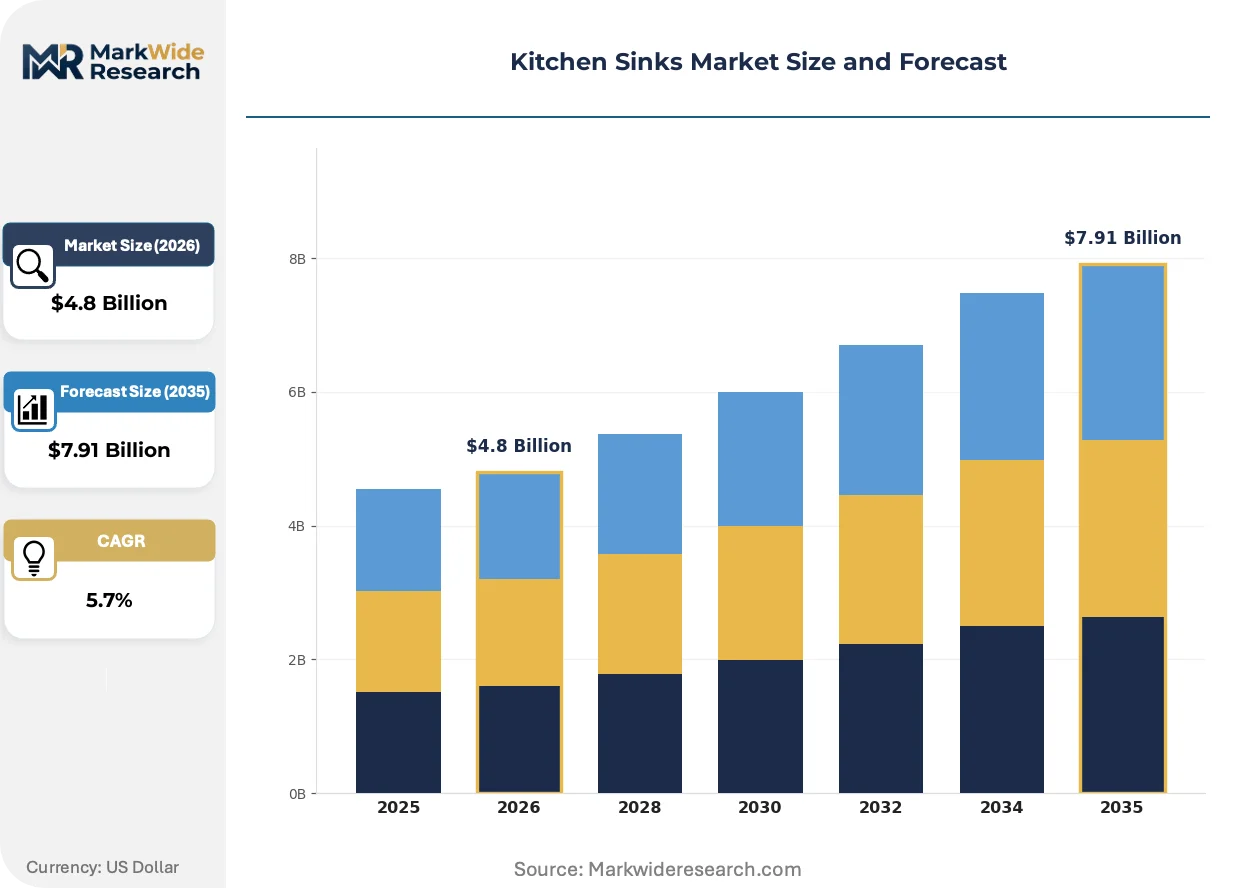
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Stainless Steel, Ceramic, Composite, Cast Iron Style: Undermount, Topmount, Apron Front, Wall Mounted Size: Single Bowl, Double Bowl, Triple Bowl, Compact Installation Type: Drop-in, Farmhouse, Flush Mount, Corner |
| Companies Covered | Franke, Kraus, Blanco, Reginox, Teka, Kohler, Ruvati, Moen, Elkay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kitchen Sinks Market Strategic Shifts & Innovations
Product evolution is centered on transforming the sink from a simple basin into a multifunctional, integrated kitchen hub. This shift is driven by advancements in material science and a consumer push for greater efficiency and space optimization in modern kitchen layouts.
Integrated workstation systems incorporate sliding accessories like cutting boards, colanders, and drying racks that fit over the sink basin. This design is primarily being adopted by the premium residential segment, especially in custom kitchen renovations. The technology is modularizing the food preparation zone, consolidating multiple tasks into a single fixture and reducing the need for separate countertop tools.
Regulations like Europe's REACH framework and China's GB standards are enforcing stricter rules for materials that come into contact with food. This compels manufacturers to invest heavily in validating the safety and durability of their material inputs, from stainless steel alloys to the resins used in composites. The composite sink category is most affected, facing pressure to document long-term material stability and prove the absence of harmful leaching.
A notable shift is occurring as consumers increasingly use direct-to-consumer (D2C) online platforms and social media influencers for product research and procurement. This trend disrupts traditional distribution channels that rely on kitchen showrooms and plumbing supply wholesalers. The change is most visible in the North American and European residential markets, where DIY enthusiasts and independent contractors source fixtures directly.
Kitchen Sinks Market Segmentation
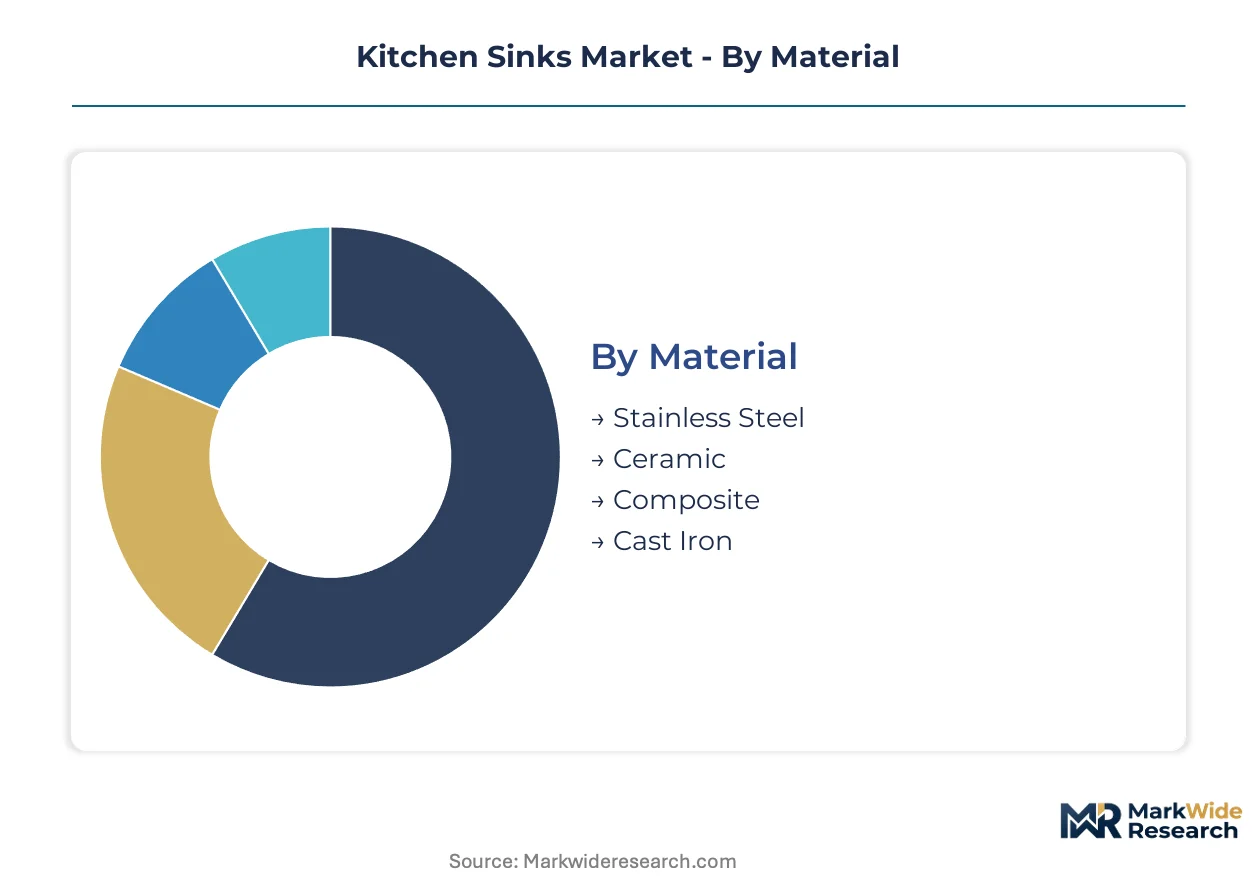
The kitchen sinks market segmentation illuminates the diverse product offerings and consumer preferences driving demand. This analysis categorizes fixtures by material, style, size, and installation type, reflecting the structural divergence between premium, feature-rich workstation sinks and mass-market utility models. Understanding these distinctions is crucial for manufacturers to align production with evolving market needs.
Material:
Material segmentation illustrates the tension between volume-driven cost efficiency and premium aesthetic appeal in kitchen sink manufacturing.
- Stainless Steel:16-gauge stainless steel offers durability and corrosion resistance, dominating commercial and residential installations. Demand concentrates in new urban residential construction in India and Brazil, driven by its cost-effectiveness and robustness.
- Composite:Engineered from quartz or granite particles bound by resin, composite sinks provide anti-bacterial properties and scratch resistance. Premium residential renovations in Europe and North America drive demand for these advanced material sinks, prioritizing aesthetics and enhanced functionality.
- Ceramic:Fired clay material offers a smooth, glossy finish, finding application in traditional and farmhouse kitchen designs in developed markets.
- Cast Iron:Heavy-duty material with an enamel coating provides exceptional durability and heat retention, favored in classic kitchen aesthetics.
Today's leader: Stainless Steel. Tomorrow's challenger: Composite.
Style:
Style segmentation reflects diverse aesthetic preferences and functional requirements across residential and commercial applications.
- Undermount:Installed beneath the countertop, creating a seamless and easy-to-clean surface. New high-end countertop installations globally drive demand for undermount styles, as consumers prioritize sleek aesthetics and integrated designs.
- Apron Front:Features an exposed front panel extending beyond the cabinetry, often associated with farmhouse or traditional styles. Residential remodeling activity in the United States and Canada sustains demand for apron front sinks, appealing to specific aesthetic preferences.
- Topmount:Dropped into a cutout from above, offering straightforward installation and a visible rim on the countertop surface.
- Wall Mounted:Attached directly to the wall, providing space-saving solutions primarily in commercial or utility room settings.
Undermount styles are rapidly gaining share in premium segments, while Topmount models maintain high volume in economy applications.
Size:
Size segmentation delineates consumer choices based on kitchen dimensions, usage patterns, and functional priorities.
- Single Bowl:Features one large basin, ideal for soaking large pots and pans or maximizing washing space. Urban residential construction in India and Brazil frequently specifies single bowl sinks due to space constraints and cost efficiency.
- Double Bowl:Divides the sink into two separate basins, facilitating multitasking like washing and rinsing simultaneously. Developed economies prioritize double bowl configurations in kitchen remodels, enhancing functionality for food preparation and dishwashing.
- Triple Bowl:Incorporates three distinct basins, offering advanced functionality for dedicated prep, wash, and rinse stations in larger kitchens.
- Compact:Designed for small spaces or secondary kitchen areas, providing essential washing functionality in limited footprints.
The market for Single Bowl sinks is driven by volume, while Triple Bowl units target niche high-end kitchen installations.
Installation Type:
Installation type segmentation highlights the varying degrees of complexity and aesthetic integration preferred by different consumer segments.
- Drop-in:Inserted from above into a countertop cutout, resting on its rim, which simplifies installation for DIY enthusiasts. This type sees high adoption in North American residential markets due to ease of replacement and broad availability.
- Farmhouse:Characterized by an exposed front apron, requiring specialized cabinetry for installation. Upscale kitchen renovations in European and North American residential sectors increasingly feature farmhouse sinks for their distinctive aesthetic appeal.
- Flush Mount:Installed level with the countertop surface, creating a sleek, integrated look often seen in contemporary kitchen designs.
- Corner:Specifically designed to fit into kitchen corners, optimizing space utilization in smaller or L-shaped kitchen layouts.
Drop-in installations maintain market breadth through accessibility, whereas Farmhouse types command premium segments through design differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled manufacturing workforces across diverse regions anchor the global kitchen sinks market. This talent concentration drives innovation and production efficiencies critical for meeting varied consumer demands. Regional economic growth and specific regulatory frameworks further shape market dynamics.
India
Demand for single bowl stainless steel sinks fuels urban residential construction in India. The Bureau of Indian Standards (BIS) mandates quality and safety for plumbing fixtures. Major construction clusters in Mumbai and Bangalore exhibit sustained demand for cost-effective, durable units.
Brazil
A rapidly expanding middle class and new housing projects drive demand for basic and mid-range kitchen sinks in Brazil. The country's national regulatory agencies ensure product conformity with local building codes. Urban centers like São Paulo and Rio de Janeiro represent significant volume markets for new installations.
United States
Extensive home renovation and kitchen remodeling activities underpin demand for premium composite and undermount sinks in the United States. ANSI standards govern plumbing compatibility and performance for all market entries. Specific water conservation mandates in California influence product development for water-efficient systems.
Germany
Germany's strong design heritage and focus on quality drive demand for advanced composite and integrated workstation sinks in Europe. CE marking ensures health and safety conformity for products sold across the European Union. Munich and Berlin's affluent residential sectors prioritize aesthetic upgrades and enhanced functionality.
China
China's vast residential construction market and rising consumer incomes generate substantial demand for both economy and mid-range kitchen sinks. GB standards enforce strict material safety and performance requirements for all manufactured products. Industrial zones in Guangdong and Zhejiang are major production hubs for global and domestic supply.
Kitchen Sinks Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the kitchen sinks market, creating a tiered competitive structure. The market exhibits both consolidation at the premium end, driven by brand reputation, and fragmentation in the economy segment, characterized by numerous regional players. Key strategic archetypes include design-centric innovators, volume-driven manufacturers, and specialized material providers focusing on durability or specific aesthetic finishes. Dominant competitive moves involve portfolio diversification across price points and strategic partnerships to expand market access in new construction hubs.
On the premium-tier vector, Franke exemplifies European design heritage, commanding the high-end segment with feature-rich systems and integrated workstation solutions that appeal to discerning consumers. Kohler, a major player, sits within the broad-portfolio archetype, offering a vast array of materials and styles across the entire market spectrum, from cost-effective drop-ins to advanced undermount models, thereby catering to diverse market needs. Elkay represents the specialized material provider archetype, maintaining a strong position through durable stainless steel sinks in both commercial and residential settings, known for their robustness and longevity, which underpins their market appeal. These distinct approaches underscore the competitive differentiation strategies employed by established market participants.
| Leading Market Players |
|---|
| Franke |
| Kraus |
| Blanco |
| Reginox |
| Teka |
| Kohler |
| Ruvati |
| Moen |
| Elkay |
| Others |
Cost & Logistics Intelligence
The development of anti-bacterial composite materials simultaneously reshapes cost economics and supply concentration in the kitchen sink market. This shift influences manufacturer margins and material sourcing strategies across product tiers.
Pricing Analysis
The bundled-vs-unbundled service split drives distinct pricing strategies across the kitchen sink market. Pricing stratifies across premium, standard, and economy tiers, reflecting material quality and brand heritage. Raw material price volatility, particularly for nickel and scrap metal, exerts downward pressure on manufacturer margins in the volume segment. Economy segment buyers exhibit high price sensitivity, while premium residential consumers prioritize aesthetic upgrades and enhanced functionality.
Supply Chain Analysis
Skilled manufacturing workforces in China, Germany, and India anchor global kitchen sink production. The supply chain draws from key raw materials including 16-gauge stainless steel, quartz and granite particles for composites, and specialized resins. Material cost volatility, especially for nickel and scrap metal, presents a persistent operational risk for manufacturers. Distribution runs through traditional kitchen showrooms and plumbing supply wholesalers, with increasing direct-to-consumer online platforms disrupting established channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kitchen sinks market presents a late-cycle quality story, driven by a pronounced demand-shift toward premium, feature-rich workstation sinks. Consumers prioritize aesthetic upgrades and enhanced functionality in modern kitchen layouts.
For Market Incumbents: Anchor brand reputation through continuous innovation in anti-bacterial composite materials and integrated workstation systems. Counter the threat of seamlessly integrated countertops by emphasizing the modularity and upgradeability of standalone units. Invest heavily in multi-jurisdictional certification to maintain market access and consumer trust. Consolidate market share in premium segments through strategic acquisitions of specialized design firms. For New Entrants and Emerging Players: Direct-to-consumer online platforms offer a cost-effective go-to-market angle for reaching DIY enthusiasts and independent contractors. Target underpenetrated middle-class consumers in Southeast Asia and Latin America with durable, aesthetically modern, and affordable sink options. Focus on basic, drop-in utility models to capture volume in new housing projects. Leverage social media influencers for product research and procurement to disrupt traditional distribution channels. For Investors and Strategic Acquirers: Valuations sit cheapest among volume-driven manufacturers in the economy segment, offering consolidation opportunities over the long term. The market exhibits robust viability driven by persistent renovation activity and urban construction. Identify design-centric innovators specializing in smart kitchen integration or advanced composite materials as strategic acquisition targets. The signal to watch is the tightening of water conservation mandates, indicating demand for integrated water-efficient systems.| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification | Kohler’s vast portfolio across materials and styles caters to diverse market needs, from economy to premium segments. |
| Advanced Material R&D | Investment in anti-bacterial composite materials drives adoption in premium residential applications, enhancing functionality and aesthetics. |
| Regional Certification Investment | Securing CE marking in Europe and ANSI standards in the US ensures market access and compliance for new product lines. |
| Direct-to-Consumer Channel Expansion | Leveraging online platforms disrupts traditional distribution, reaching DIY enthusiasts and independent contractors directly. |
| Smart Kitchen Integration | Embedding hands-free faucets and sensor-based controls appeals to the smart home market, enhancing high-end sink systems. |
Research Approach
Bottom-up residential construction modeling reconciled against top-down material supply tracking forms the analytical core of this study. Primary interviews with kitchen designers, plumbing wholesalers, material suppliers, and residential developers informed market understanding. Secondary validation drew from national construction statistics, material trade association reports, regulatory body publications, and company financial disclosures. This approach ensured comprehensive data triangulation.
The input-output matrix framing guided the quantitative projections across the analysis window. Segmentation dimensions modeled included material, style, size, installation type, and regional aesthetic preferences. Compound Annual Growth Rates were derived through a combination of regression analysis and expert consensus. Urbanization rates in emerging markets and renovation spending indices in developed economies served as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for integrated smart kitchen systems would alter the outlook. Forecasts reflect assumptions regarding material cost stability and consistent regulatory enforcement. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Built-In Cabinet Market
Kitchen and Dining
India Kitchen Sink and Other Related Market
Kitchen and Dining
US Tableware Market
Kitchen and Dining
Saudi Arabia Kitchen Hoods Market
Kitchen and Dining
North America Countertop Market
Kitchen and Dining
Sweden Household Electric Grills Market
Kitchen and Dining
United States Kitchen Furniture Market
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
Prep Tables Market
Kitchen and Dining
Flip-Top Tables Market
Kitchen and Dining
Household Slicer Market
Kitchen and Dining
Italy Cookware Market
Kitchen and Dining
Asia-Pacific Modular Kitchen Market
Kitchen and Dining
Kitchen Countertop Market
Kitchen and Dining
UK Ceramic Tableware Market
Kitchen and Dining
North America Kitchen Furniture Market