
 North America Countertop Market | 2026-2036
North America Countertop Market Size, Share, and Industry Trends Forecast 2026-2036
North America Countertop Market Analytics
Residential builder procurement is consolidating around fewer national distributors with direct mill relationships. Cambria leverages its Minnesota-based quartz manufacturing campus to sustain domestic supply security for large-scale multifamily developers. Wilsonart competes through laminate product specialization that anchors its position in cost-sensitive renovation segments. Cosentino differentiates via sintered stone technology leadership that extends its reach into premium commercial hospitality specifications.
North America countertops are horizontal work surfaces engineered from natural stone, engineered stone, solid surface, or laminate substrates, typically fabricated to thicknesses between two and three centimeters and finished to resist abrasion, moisture, and thermal shock in food preparation and service environments. Quartz surfaces now dominate value contribution across residential kitchens due to superior stain resistance and minimal maintenance requirements relative to natural granite. The polished finish category retains volume leadership, though leathered textures are gaining specification share in high-end residential and boutique hospitality applications where tactile differentiation commands price premiums.
EPA TSCA Title VI formaldehyde standards and California Air Resources Board (CARB) Phase 2 compliance requirements shape substrate selection and adhesive chemistry across laminate and engineered product lines. OSHA silica exposure limits for fabrication shops are accelerating wet-cutting equipment investment and influencing regional production economics. Stakeholders must monitor evolving state-level extended producer responsibility frameworks that could impose end-of-life recovery obligations on quartz and solid surface manufacturers serving the North American market.
Market Dynamics
EPA TSCA Title VI formaldehyde emission standards are compressing laminate substrate supply chains while accelerating quartz specification across residential renovation projects in the United States and Canada.
Growth Catalysts
- Sun Belt Housing Construction:New single-family and multifamily groundbreakings in Texas, Florida, and Arizona are pulling engineered stone volume through national distributor networks with direct mill relationships.
- OSHA Silica Rule Compliance:Fabrication shops across the United States are retrofitting with wet-cutting equipment, creating equipment upgrade cycles that favor consolidated producers with capital access.
- Leathered Texture Specification:Boutique hospitality and high-end residential designers are specifying tactile finishes that command price premiums over polished surfaces in urban renovation corridors.
Market Restraints
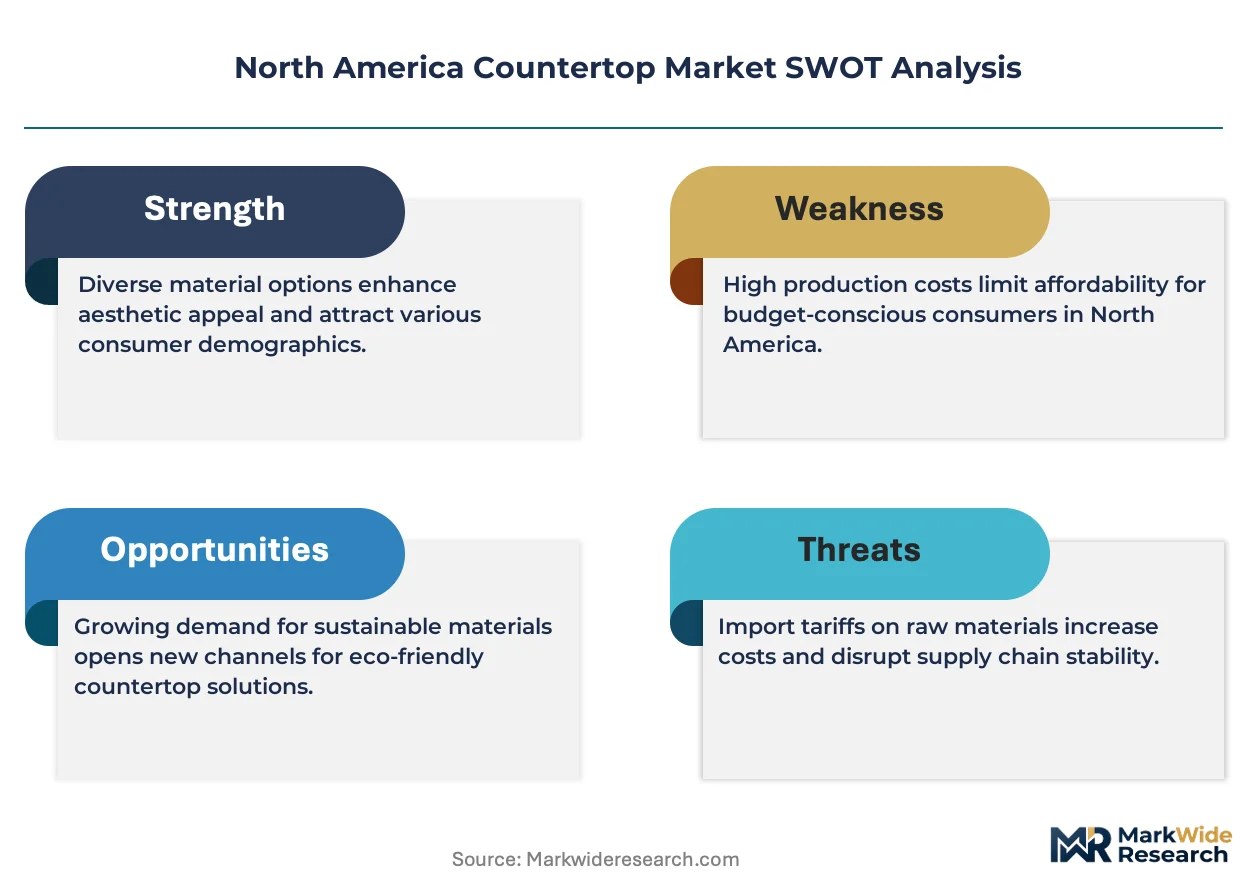
- Resin Input Cost Volatility:Polyester and epoxy resin prices fluctuate with petrochemical feedstock markets, compressing margin stability for engineered stone producers dependent on imported polymer binders.
- Quartz Supply Concentration:Domestic quartz slab production concentrates in Minnesota and Georgia facilities, creating geographic vulnerability to regional logistics disruptions or localized labor actions.
- Granite Substitution Threat:Natural granite retains specification share in luxury custom home segments where unique veining patterns and perceived authenticity sustain price inelastic demand.
Strategic Opportunities
- Canadian Market Underpenetration:Engineered stone adoption lags in Vancouver and Toronto renovation markets relative to U.S. metropolitan benchmarks, presenting volume expansion potential for distributors with cross-border logistics capabilities.
- Sintered Stone Convergence:Porcelain slab technology is penetrating premium commercial foodservice specifications where thermal shock resistance and large-format fabrication enable competitive displacement of natural stone.
- Direct-to-Builder Digital Channels:National multifamily developers are piloting specification platforms that bypass traditional distributor markup structures, compressing channel economics for incumbents.
Industry Challenges
- Fabrication Skill Shortage:CNC programming and seam-matching craftsmanship deficits constrain regional installer capacity, extending project timelines and creating bottlenecks during peak renovation seasons.
- CARB Phase 2 Certification Timelines:Laminate substrate suppliers face extended third-party testing intervals for California compliance, delaying product launches and inventory positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Countertop Market |
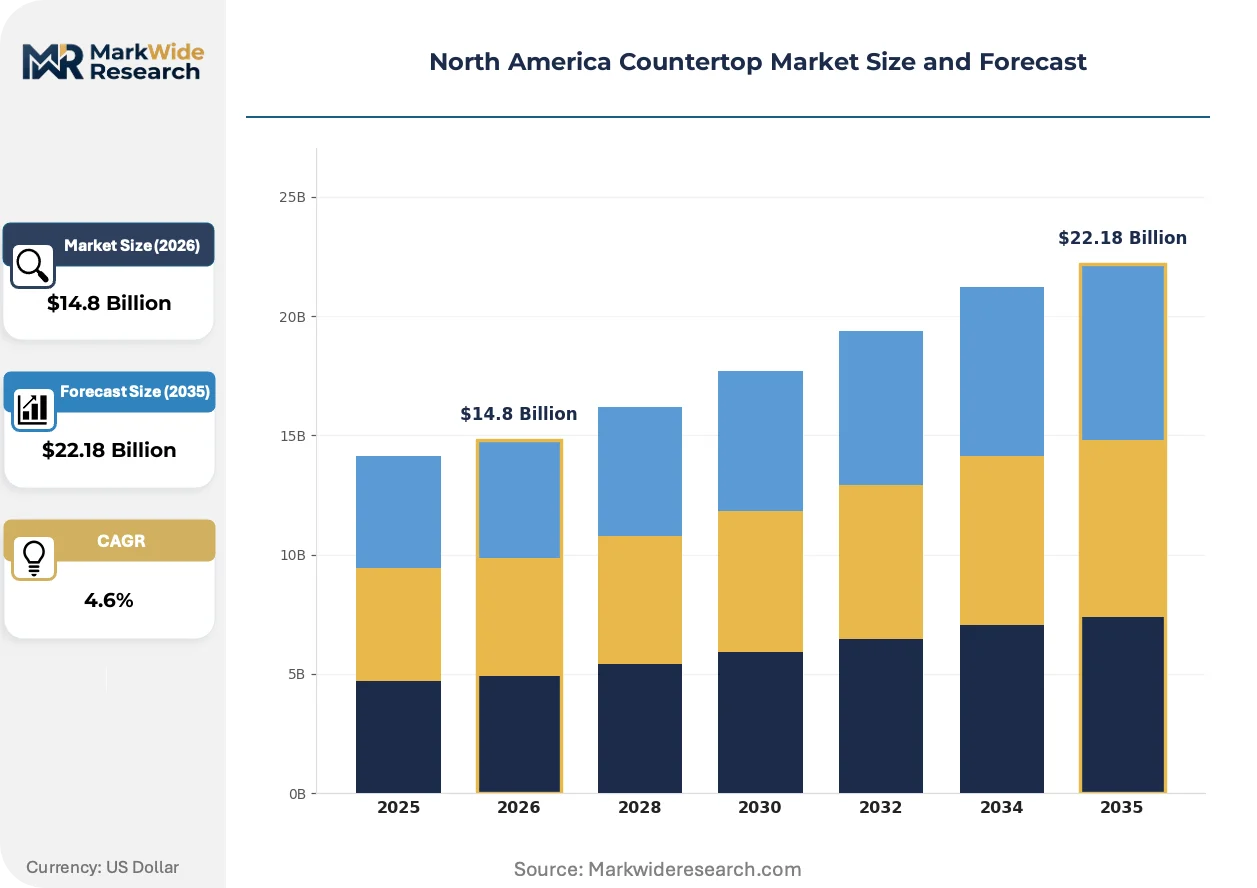
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Granite, Quartz, Marble, Laminate Application: Residential Kitchens, Commercial Spaces, Hospitality, Retail Finish Type: Polished, Honed, Leathered, Textured Size: Standard, Custom, Modular, Pre-fabricated |
| Companies Covered | Corian, LX Hausys, Cosentino, Polycor, LG Hausys, Cambria, Wilsonart, Levantina, Caesarstone, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Countertop Market Evolving Landscape
Material science advances and regulatory chemistry requirements are compressing traditional substrate hierarchies while enabling new performance categories to capture specification share across residential and commercial verticals.
Ultra-compact sintered stone is unifying the performance attributes of porcelain, quartz, and natural stone into single-surface specifications. Large-format hospitality designers in Miami and Los Angeles are specifying 12-millimeter slabs for vertical cladding and countertop continuity. This convergence is compressing the premium segment into fewer material categories with overlapping performance claims.
EPA formaldehyde emission testing protocols are reshaping adhesive chemistry across laminate and engineered wood substrate lines. Manufacturers serving California and national retail chains must reformulate urea-formaldehyde resins or source CARB Phase 2 certified cores. The compliance burden falls most heavily on mid-tier laminate producers without captive resin production.
Builder procurement consolidation is compressing distributor tiers as national multifamily developers establish direct mill relationships for quartz volume. Regional fabricators in Phoenix and Atlanta are responding by specializing in complex custom geometry that resists commoditization. This channel restructuring is most visible in Sun Belt metropolitan markets where new construction volume supports dedicated supply agreements.
North America Countertop Market Segmentation
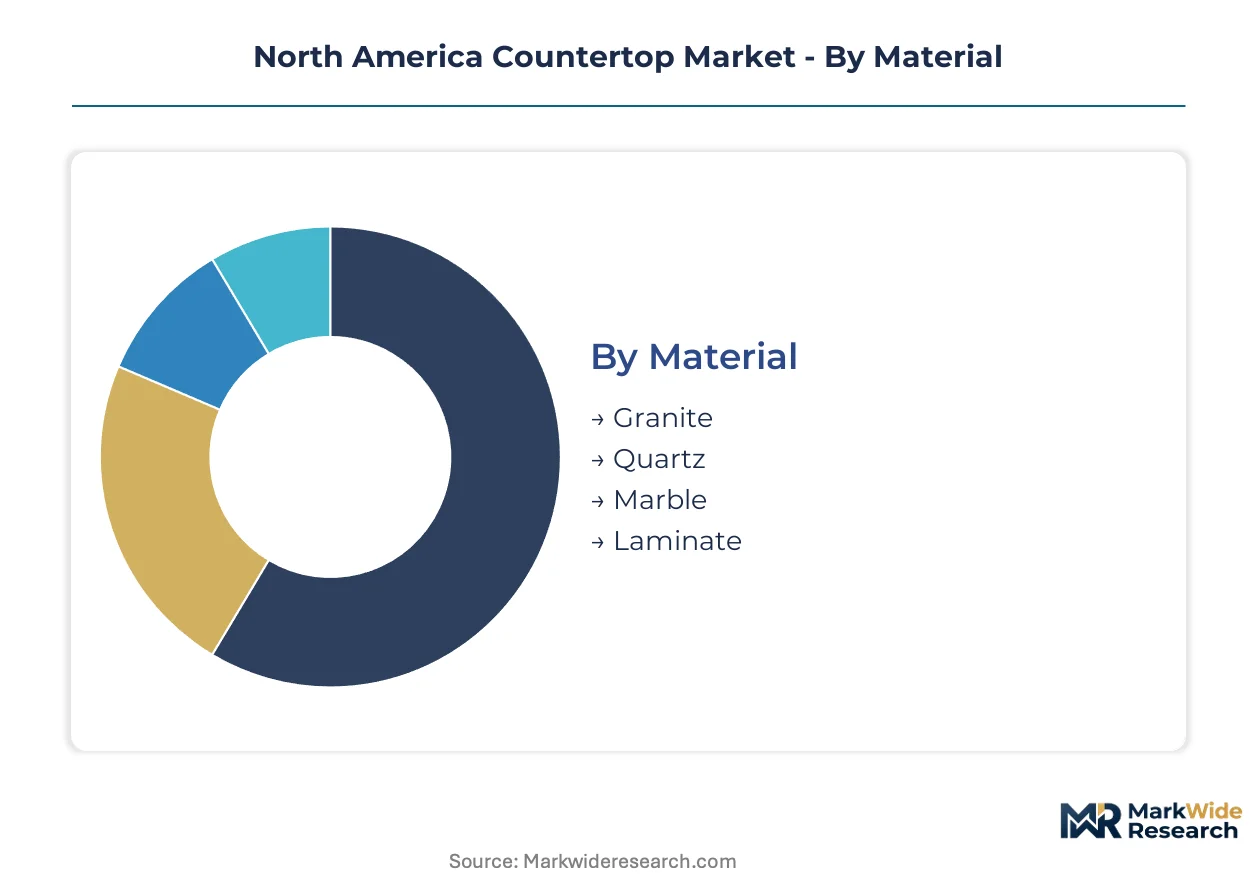
Countertop procurement decisions cascade through material selection, application requirements, and fabrication specifications that determine installation economics. Each segmentation dimension captures distinct trade-offs between performance, aesthetics, and regulatory compliance that reshape competitive positioning across the North American market.
Material:
Material selection determines whether surfaces function as standalone aesthetic statements or embedded structural components within kitchen systems.
- Quartz:Engineered stone combines crushed natural quartz with polymer resins to create non-porous surfaces that resist staining and etching. Demand concentrates in Sun Belt residential kitchens where EPA formaldehyde standards are compressing laminate specification. Minnesota and Georgia production facilities supply national distributors with direct mill relationships to large-scale multifamily developers.
- Granite:Igneous rock slabs offer unique veining patterns that sustain specification in luxury custom homes where perceived authenticity commands price inelasticity. Texas and Florida builders specify granite for high-end single-family installations where natural variation differentiates properties in competitive housing markets.
- Marble:Metamorphic limestone prized for luminous appearance and thermal conductivity in pastry preparation zones.
- Laminate:Paper-resin composite bonded to particleboard substrates, reformulating adhesive chemistry to meet CARB Phase 2 emission thresholds.
Volume placements concentrate in Quartz; the faster expansion belongs to engineered stone as formaldehyde regulations tighten.
Application:
Application segmentation separates surfaces specified for food preparation intensity from those serving display or transaction functions.
- Residential Kitchens:Primary food preparation environments demanding abrasion resistance, thermal shock tolerance, and moisture protection. Sun Belt housing construction in Texas, Florida, and Arizona pulls engineered stone volume through consolidated distributor networks with direct mill relationships.
- Hospitality:Boutique hotels in Miami and Los Angeles specify leathered textures and large-format sintered stone for tactile differentiation that commands rate premiums. OSHA silica compliance costs are accelerating wet-cutting equipment investment among regional fabricators serving this segment.
- Commercial Spaces:Corporate foodservice and breakroom installations prioritizing durability under high-traffic conditions.
- Retail:Transaction counters and display surfaces where visual impact outweighs functional performance requirements.
Residential kitchens absorb the greatest volume; hospitality applications are climbing the fastest as boutique property development intensifies.
Finish Type:
Finish specification mediates between gloss retention, tactile experience, and maintenance burden across installation environments.
- Polished:High-gloss surface achieved through mechanical grinding and resin infusion that maximizes reflectivity and perceived depth. Volume leadership persists across mass-market residential renovations where standardized fabrication minimizes cost.
- Leathered:Brushed texture preserving stone character while introducing tactile variation that commands specification premiums in high-end residential and hospitality contexts. Los Angeles and Miami designers specify leathered finishes for urban renovation corridors where differentiation justifies elevated pricing.
- Honed:Satin-smooth matte finish reducing glare in commercial environments with intensive artificial lighting.
- Textured:Mechanically or chemically altered surface topography for slip resistance and visual interest.
Polished finishes retain volume dominance; leathered textures are gaining share fastest among premium specifications.
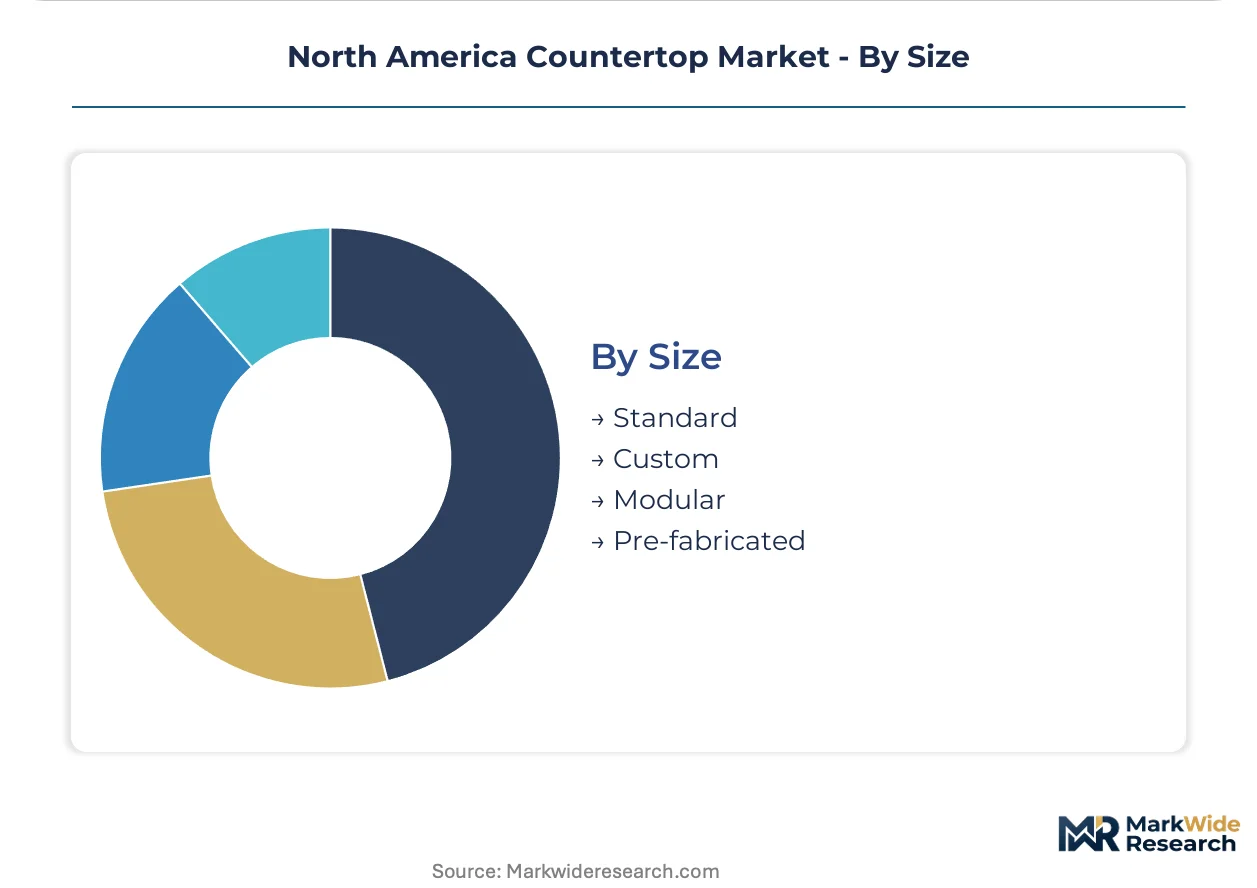
Size:
Size segmentation structures fabrication economics and installation logistics from standardized throughput to project-specific customization.
- Standard:Pre-dimensioned slabs in conventional widths and lengths that optimize material yield and CNC programming efficiency. National distributors stock standard dimensions for rapid fulfillment of renovation projects with predictable scope.
- Custom:Project-specific dimensions requiring dedicated templating, seam-matching craftsmanship, and extended lead times. Regional fabricators in Phoenix and Atlanta specialize in complex custom geometry that resists commoditization as builder procurement consolidates around national distributors.
- Modular:Interchangeable dimension sets enabling field adaptation with minimal cutting.
- Pre-fabricated:Dimensioned and edged surfaces for rapid installation in cost-sensitive renovation segments.
Standard sizes capture the greatest volume; custom fabrication is expanding most quickly as high-end residential projects demand unique geometries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential renovation demand concentrates in the United States Sun Belt, where new construction and kitchen upgrades pull engineered stone volume through consolidated distribution channels. Canada presents underpenetrated expansion potential as Toronto and Vancouver renovation markets lag U.S. metropolitan adoption rates. Mexico's northern border states are emerging as fabrication capacity nodes serving cross-border residential development.
United States
Texas, Florida, and Arizona groundbreakings drive engineered stone specification through national distributors with direct mill relationships. EPA TSCA Title VI formaldehyde standards compress laminate substrate availability while accelerating quartz adoption across residential renovation. Minnesota and Georgia production facilities anchor domestic quartz supply security for large-scale multifamily developers in Phoenix and Atlanta metropolitan corridors.
Canada
Toronto and Vancouver renovation markets exhibit engineered stone adoption gaps relative to U.S. metropolitan benchmarks, creating volume expansion potential. Health Canada and PMRA oversight of indoor air quality standards influences substrate selection in high-rise residential construction. Cross-border logistics capabilities from U.S. distributors are penetrating Ontario and British Columbia markets with quartz slab imports.
Mexico
Nuevo León and Baja California fabrication clusters are scaling wet-cutting capacity to serve residential development in Tijuana and Monterrey metro areas. Mexican federal environmental standards for industrial emissions shape adhesive chemistry and substrate sourcing decisions. Northern border states are positioning as secondary supply nodes for U.S. Southwest renovation contractors seeking alternative fabrication capacity.
California
CARB Phase 2 certification requirements impose extended third-party testing intervals on laminate substrate suppliers, delaying product launches. Los Angeles and San Francisco designers specify leathered textures and large-format sintered stone for boutique hospitality and high-end residential renovations. The state's regulatory stringency is compressing mid-tier laminate producer margins while favoring compliant engineered stone alternatives.
Texas
Dallas-Fort Worth and Houston single-family construction volumes pull granite specification for luxury custom homes where natural veining differentiates properties. OSHA silica exposure compliance costs are accelerating wet-cutting equipment investment among regional fabricators serving the state's residential builder market. Texas anchors one of the highest countertop installation rates per capita across the North American market.
North America Countertop Market Competitive Landscape
United States producers anchor one tier; Spanish and Israeli specialists hold premium engineered stone positioning through technology licensing and brand recognition. The vendor base structures around three concentration levels: consolidated quartz manufacturers with captive resin supply, mid-tier laminate specialists reformulating for CARB compliance, and regional fabricators competing on custom geometry craftsmanship. Two strategic archetypes dominate: domestic-scale producers leveraging geographic proximity to Sun Belt construction, and import-dependent specialists accessing sintered stone technology. Competitive moves center on direct-to-builder digital channel pilots and wet-cutting equipment retrofitting to meet OSHA silica limits.
Among domestic-scale manufacturers, Cambria exemplifies the integrated production archetype through its Minnesota-based quartz manufacturing campus. Wilsonart occupies a position within the laminate specialization tier, competing through cost-sensitive renovation segment focus. Cosentino represents the premium sintered stone technology vector, differentiating via large-format specifications for commercial hospitality applications. These three companies illustrate the competitive spectrum from domestic supply security to material science leadership.
| Leading Market Players |
|---|
| Corian |
| LX Hausys |
| Cosentino |
| Polycor |
| LG Hausys |
| Cambria |
| Wilsonart |
| Levantina |
| Caesarstone |
| Others |
Value Network & Pricing Analysis
CNC programming and seam-matching craftsmanship shortages in the U.S. Southwest and Southeast fabrication corridors widen labor-cost differentials between premium custom geometry and standardized slab production. These workforce concentration patterns translate into pricing-tier spreads that separate boutique residential renovations from mass-market multifamily specifications.
Pricing Analysis
Volume placements concentrate in standard quartz slabs where consolidated distributors leverage direct mill relationships to compress margins; premium leathered finishes and custom dimensions command elevated pricing through scarcity of qualified regional fabricators. Price differentiation rests on certification grade—EPA TSCA Title VI and CARB Phase 2 compliance tiers—and geographic delivery cost from Minnesota and Georgia production hubs. Pricing pressure stems from resin input cost volatility tied to petrochemical feedstock markets, compressing margin stability for engineered stone producers. Mass-market residential renovation segments exhibit highest price sensitivity; luxury custom home builders demonstrate lowest sensitivity where unique veining and tactile finishes justify premiums.
Supply Chain Analysis
Single-source vulnerability sits with Minnesota and Georgia as the dominant domestic quartz slab production concentrations, creating geographic exposure to regional logistics disruptions or localized labor actions. Raw material dependencies center on polyester and epoxy resins, crushed natural quartz feedstock, and CARB-certified particleboard substrates for laminate alternatives. Supply chain risk manifests as tariff exposure on imported polymer binders and sintered stone technology components. Distribution runs through consolidated national distributors with direct mill relationships to large-scale multifamily developers, bypassing traditional tiered markup structures in Sun Belt metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream control over resin production and captive quartz feedstock processing determines margin defense against petrochemical volatility.
For Market Incumbents: Hedge against laminate substitution erosion by accelerating wet-cutting equipment retrofitting to meet OSHA silica exposure limits, securing fabrication capacity advantages. Deepen backward integration into polymer resin production or establish long-term offtake agreements with petrochemical suppliers to buffer margin compression from feedstock volatility. Defensive consolidation around CARB Phase 2 certification capabilities will isolate mid-tier competitors lacking captive testing infrastructure. For New Entrants and Emerging Players: Boutique hospitality designers in Miami and Los Angeles represent an underserved buyer archetype seeking tactile leathered finishes and large-format sintered stone specifications that resist commoditization. Canadian metropolitan renovation markets—particularly Toronto and Vancouver—offer penetrable geography gaps relative to U.S. engineered stone adoption benchmarks. A direct-to-builder digital specification platform piloted with national multifamily developers bypasses incumbent distributor markups and captures volume through procurement consolidation. For Investors and Strategic Acquirers: The window for entry favors regional fabricators with CNC programming capabilities and established wet-cutting OSHA compliance in Phoenix and Atlanta metropolitan corridors. Long-term viability centers on acquisition targets with demonstrated custom geometry craftsmanship and cross-border logistics capabilities into Canadian markets. Watch EPA enforcement intensity on formaldehyde emission standards as the inflection signal determining laminate substrate viability and engineered stone substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Wet-Cutting Equipment Retrofit | OSHA silica compliance secures fabrication capacity and insulates against regulatory enforcement actions. |
| Direct Mill Relationship Expansion | Bypassing distributor tiers captures margin compression from national multifamily developer procurement consolidation. |
| CARB Phase 2 Certification Investment | Extended third-party testing capabilities accelerate California market access and isolate non-compliant competitors. |
| Sintered Stone Technology Licensing | Porcelain slab thermal shock performance opens premium commercial foodservice specifications against natural stone. |
| Cross-Border Logistics Capability Buildout | Toronto and Vancouver underpenetration creates volume expansion potential for U.S.-based quartz distributors. |
Research Methodology
Independent corroboration across distributor procurement leads, regional fabrication shop operators, and multifamily developer specification managers underwrites the qualitative findings in this study. Primary interviews with laminate substrate reformulation chemists, CNC programming technicians, and hospitality interior designers combined with secondary validation from EPA TSCA Title VI filing databases, CARB Phase 2 certification registries, and OSHA silica compliance inspection records. Bottom-up volume estimates from fabrication capacity utilization and top-down demand triangulation from housing construction permits anchored the analysis.
Rate-of-change decomposition across material substitution velocity, regulatory compliance cost trajectories, and channel restructuring intensity shaped the analytical framework. Segmentation dimensions modeled include material substrate, finish type, application vertical, and geographic production cluster. CAGRs derived from installed base turnover rates and new construction pull-through volumes across the projection horizon. Industry-specific forecast inputs incorporated Sun Belt housing starts volatility and resin price index sensitivity.
Revisions become necessary when EPA formaldehyde enforcement intensity exceeds baseline assumptions, OSHA silica rule implementation timelines accelerate, or petrochemical feedstock disruption alters resin economics. Forecasts reflect documented assumptions about housing construction cyclicality and regulatory compliance cost pass-through elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
UK Ceramic Tableware Market
Kitchen and Dining
Kitchen Faucets Market
Kitchen and Dining
Back Table and Cart Covers Market
Kitchen and Dining
GCC Modular Kitchen Market
Kitchen and Dining
Saudi Arabia Modular Kitchen Market
Kitchen and Dining
Pull Out and Down Kitchen Faucet Market
Kitchen and Dining
India Modular Kitchen Market
Kitchen and Dining
India Kitchen Furniture Market
Kitchen and Dining
Kitchen Sinks Market
Kitchen and Dining
US Tableware Market
Kitchen and Dining
Quartz Sink Market
Kitchen and Dining
Australia Kitchen Furniture Market
Kitchen and Dining
Asia-Pacific Kitchen Furniture Market
Kitchen and Dining
Egypt Kitchen Hood Market
Kitchen and Dining
Built-In Cabinet Market
Kitchen and Dining
Saudi Arabia Kitchen Furniture Market