
 Sweden Household Electric Grills Market | 2026-2036
Sweden Household Electric Grills Market Size, Share, and Industry Trends Forecast 2026-2036
Sweden Household Electric Grills Market Analytics
Apartment-dwelling singles and couples is collapsing the historical dominance of suburban family buyers in the Sweden household electric grills space. Weber Inc anchors its position through specialized distribution in Nordic outdoor retail channels. Groupe SEB differentiates via deep tabletop and smokeless grill portfolios calibrated to Swedish space constraints. Philips competes on integrated timer and adjustable temperature features that resonate with time-pressed urban consumers.
Sweden household electric grills comprise electrically heated cooking surfaces, typically employing resistive coil or infrared ceramic elements rated from 1000W to 2500W, designed for food preparation without combustion byproducts in indoor or balcony environments. The product category spans tabletop grills, indoor grills, portable grills, and smokeless grills, with smokeless variants capturing margin pools as Swedish rental regulations tighten on emissions in dense housing. End-user segmentation tilts toward families and singles, with singles representing the faster-expanding cohort as household formation patterns shift and compact-design features command price premiums over basic 1000W units.
Sweden's National Board of Housing, Building and Planning enforces fire safety codes that restrict open-flame appliances in multi-family structures, directly elevating electric alternatives. The Swedish Energy Agency's efficiency labeling requirements shape product development trajectories, while CE marking under EU electrical safety directives governs market access. Stakeholders must weigh whether to deepen R&D into sub-1500W compact formats or defend position in higher-wattage family segments as housing density trends and energy price trajectories diverge across Swedish metropolitan markets.
Market Dynamics
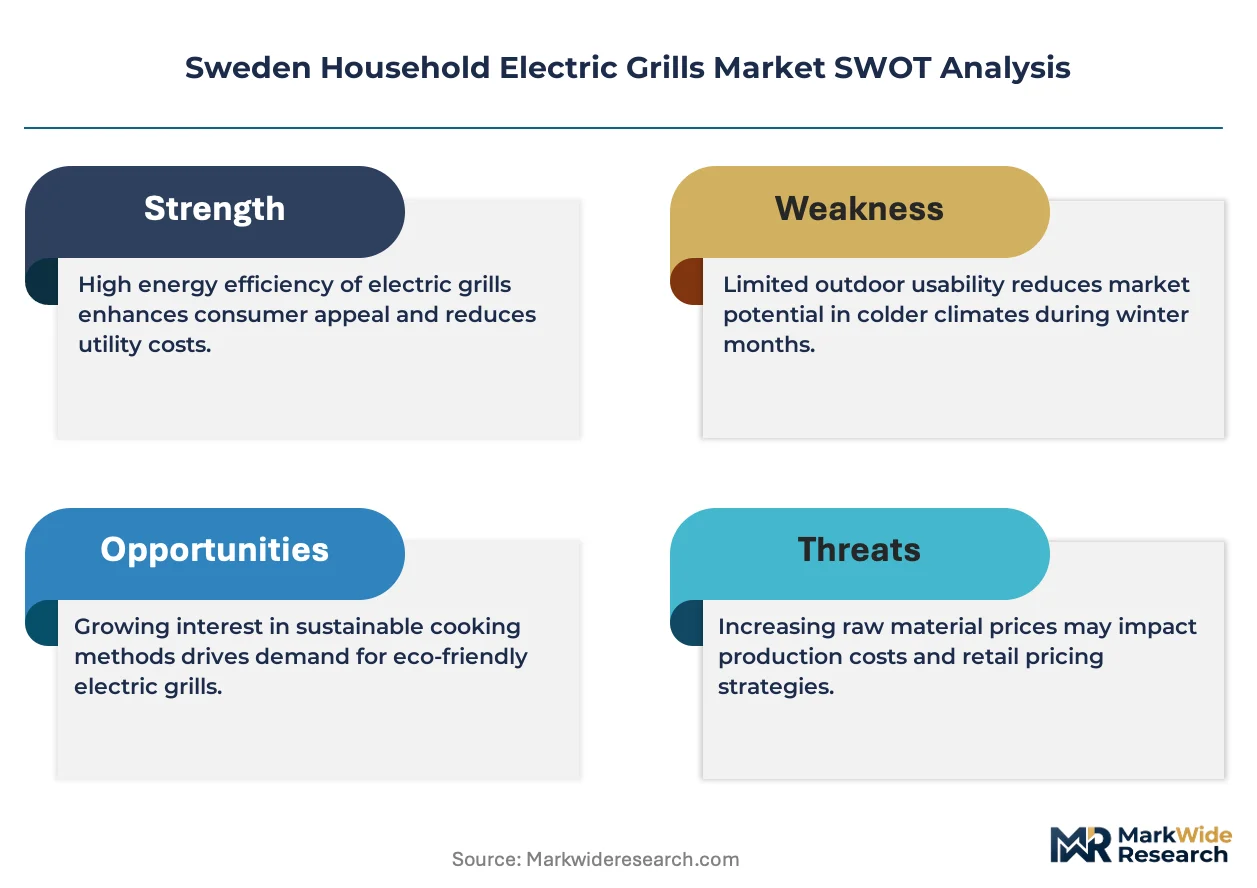
Sweden's National Board of Housing, Building and Planning fire safety codes restricting open-flame appliances in multi-family structures are compressing demand toward plug-in electric alternatives, while single-person household formation accelerates compact-format adoption across Stockholm, Gothenburg, and Malmö metropolitan zones.
Growth Catalysts
- Boverkets Byggregler (BBR):Sweden's building code restrictions on open-flame cooking in multi-unit residential buildings channel demand toward electric grills as the compliant default for apartment balconies and indoor kitchens.
- Single-person households:Demographic shifts toward solo living in urban centers drive preference for sub-1500W compact designs that fit constrained counter spaces and smaller balconies.
- Infrared ceramic heating elements:Energy-efficient ceramic technology reduces electricity consumption while delivering faster preheat times, aligning with Swedish Energy Agency efficiency labeling requirements.
Market Restraints
- Electricity price volatility:Nordic power market fluctuations create cost-of-ownership uncertainty for high-wattage grill models, particularly affecting 2000W+ family-format purchases.
- Supply concentration in East Asian component manufacturing:Dependence on imported resistive coils and ceramic heating elements exposes Swedish distributors to logistics disruptions and currency fluctuation risks.
- Outdoor balcony space constraints:Technical limitations on heat dissipation and ventilation in Swedish apartment balconies restrict maximum wattage deployment regardless of consumer preference.
Strategic Opportunities
- Gothenburg secondary-city premium segment:Underpenetrated high-income districts in Sweden's second-largest metropolitan area present whitespace for feature-rich smokeless grill models targeting affluent renters.
- Swedish Energy Agency efficiency labeling:Regulatory tailwinds favoring A-rated appliances create margin expansion potential for manufacturers investing in sub-1000W ultra-efficient designs.
- Specialty kitchen retailers:Channel innovation through dedicated Nordic outdoor living chains offers bypass of generalist electronics retailers and captures higher-margin direct sales.
Industry Challenges
- Electrical safety certification timelines:CE marking compliance under EU electrical safety directives requires extended testing protocols that delay product launch windows for new entrants.
- Integration complexity with legacy kitchen infrastructure:Older Swedish apartment stock with limited circuit capacity creates installation friction for 2500W premium models targeting family segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sweden Household Electric Grills Market |
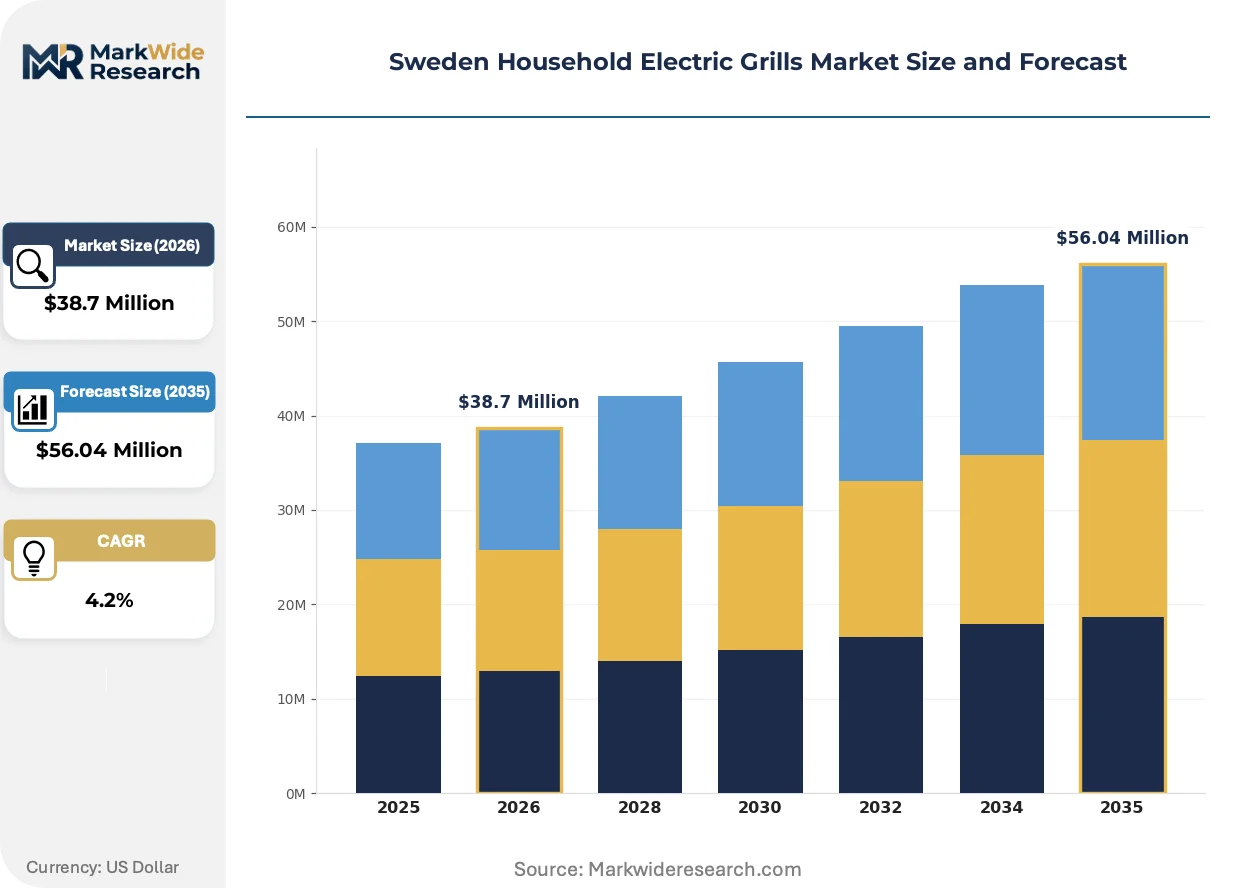
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $56.04 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tabletop Grills, Indoor Grills, Portable Grills, Smokeless Grills End User: Families, Singles, Restaurants, Catering Services Power Rating: 1000W, 1500W, 2000W, 2500W Feature: Non-Stick Surface, Adjustable Temperature, Compact Design, Integrated Timer |
| Companies Covered | DeLonghi, Weber Inc, Philips, Groupe SEB, Whirlpool, MPM AGD, Roller Grill International, Electrichef, Adler Europe, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sweden Household Electric Grills Market Evolving Landscape
Electrification of residential cooking appliances is decomposing traditional fuel-type boundaries in Swedish households, with smokeless infrared technology and smart temperature control systems emerging as the primary vectors of product differentiation in this space-constrained market.
Infrared ceramic heating technology is decomposing the historical dominance of resistive coil elements in Swedish electric grills. Single-person households in Stockholm's dense inner suburbs are adopting these systems at accelerated rates due to faster heat-up cycles and reduced energy draw. The structural consequence is compression of the addressable market for basic 1000W coil-based units as retailers reallocate shelf space toward premium ceramic models.
Sweden's National Board of Housing, Building and Planning continues tightening balcony fire safety enforcement, extending BBR restrictions to cover previously exempted housing stock built before 2011. This regulatory pressure forces property managers to prohibit charcoal and gas alternatives entirely, elevating electric grills to sole permissible outdoor cooking format. Premium smokeless variants capture disproportionate margin as rental regulations tighten on visible emissions in dense Malmö housing clusters.
Direct-to-consumer digital channels are fragmenting traditional Nordic outdoor retail gatekeeper relationships. Urban singles aged 25-40 increasingly research compact grill specifications through manufacturer websites before purchase, bypassing specialty retailers. This behavioral shift concentrates in Stockholm's tech-forward districts where apartment density and e-commerce penetration intersect most sharply.
Sweden Household Electric Grills Market Segmentation
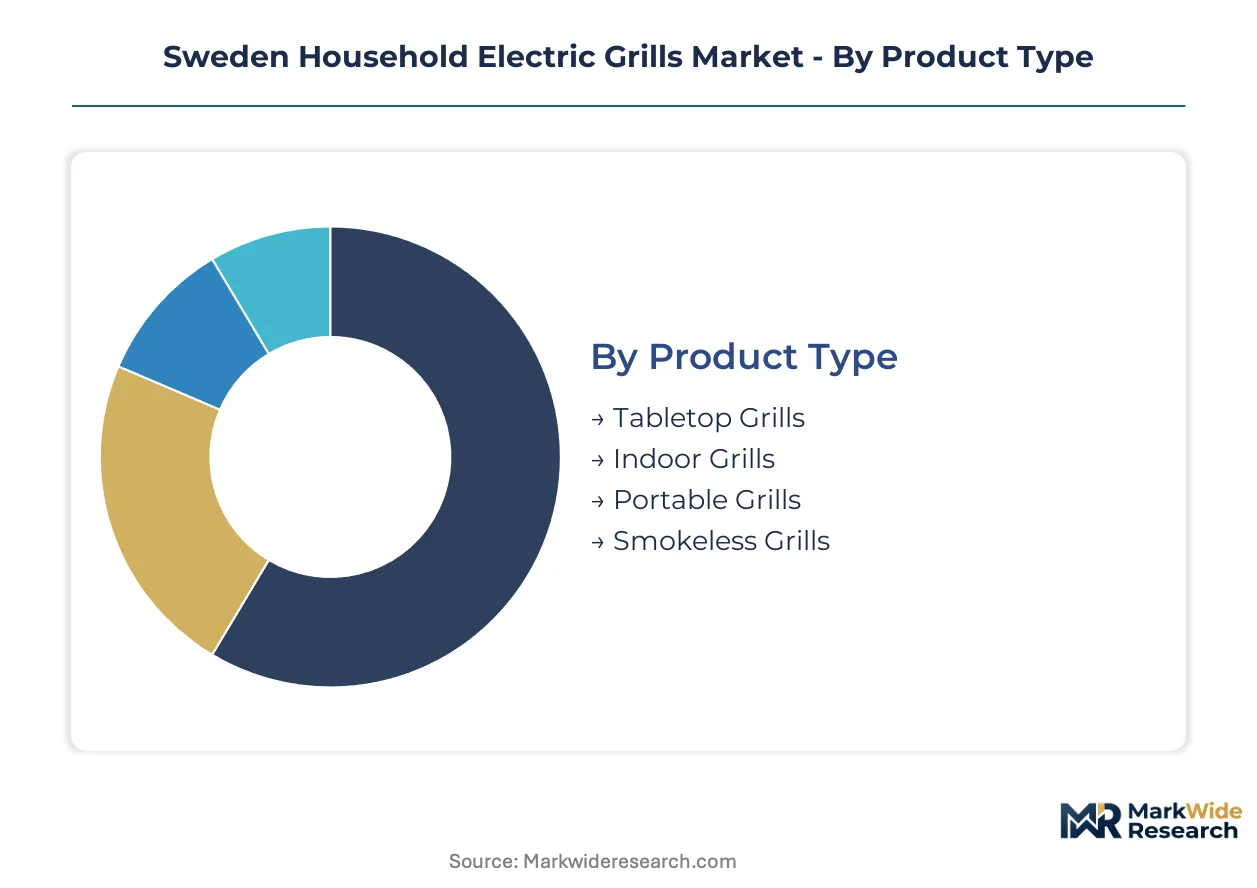
Segmentation in the Sweden household electric grills market reveals how regulatory constraints and household formation patterns split demand across distinct technical and user profiles. Understanding these divides exposes where manufacturers can defend margin against commoditization.
Product Type:
Margin pools concentrate in smokeless variants where BBR compliance commands price premiums, while basic formats face shelf-space compression.
- Tabletop Grills:Compact units designed for kitchen counter deployment, typically featuring 1000-1500W ceramic or coil elements. Demand clusters in Stockholm's dense inner suburbs where counter space constraints eliminate larger alternatives and rental regulations prohibit open-flame cooking.
- Smokeless Grills:Infrared ceramic systems with enclosed drip trays and catalytic filters that eliminate visible emissions. Malmö's high-density housing clusters drive disproportionate margin capture as property managers enforce strict balcony emission rules under tightening BBR interpretations.
- Indoor Grills:Stationary units optimized for kitchen ventilation systems, generally rated 1500-2000W.
- Portable Grills:Lightweight designs with carrying handles and detachable power cords for seasonal storage.
The dominant share belongs to tabletop grills, while smokeless grills are closing the gap fastest.
End User:
Volume splits sharply between household and commercial applications, with divergent purchasing criteria around duty cycle and warranty terms.
- Singles:Solo occupants in urban rental stock prioritize sub-1500W compact formats with rapid heat-up cycles. Gothenburg's expanding young professional districts show accelerated adoption of integrated timer features that accommodate irregular schedules.
- Families:Multi-person households in suburban owner-occupied units drive 2000W+ purchases with larger cooking surfaces. Circuit capacity limitations in pre-1990 Swedish apartment stock constrain penetration in older Malmö residential zones.
- Restaurants:Commercial operators seeking backup cooking capacity or code-compliant balcony service equipment.
- Catering Services:Mobile food service providers requiring transportable electric alternatives for indoor event venues with fire restrictions.
Families retain the largest installed base, though singles are expanding their share most rapidly.
Power Rating:
Swedish Energy Agency efficiency labeling creates tiered margin structure, with A-rated sub-1500W units capturing premium positioning.
- 1500W:Mid-range ceramic element systems balancing heat output with circuit compatibility. Stockholm's 1960s-1980s apartment stock—widespread in Södermalm and Vasastaden—drives preference for this ceiling to avoid breaker trips on shared circuits.
- 1000W:Entry-level resistive coil designs for basic grilling functions. Singles in micro-apartments accept slower preheat times to gain plug-and-play compatibility with standard Swedish 10A outlets.
- 2000W:Family-format units requiring dedicated 16A circuits, common in post-2000 construction.
- 2500W:Premium segment demanding kitchen infrastructure upgrades, limiting addressable market.
1500W holds the dominant position, while 1000W is gaining share fastest among new entrants.
Feature:
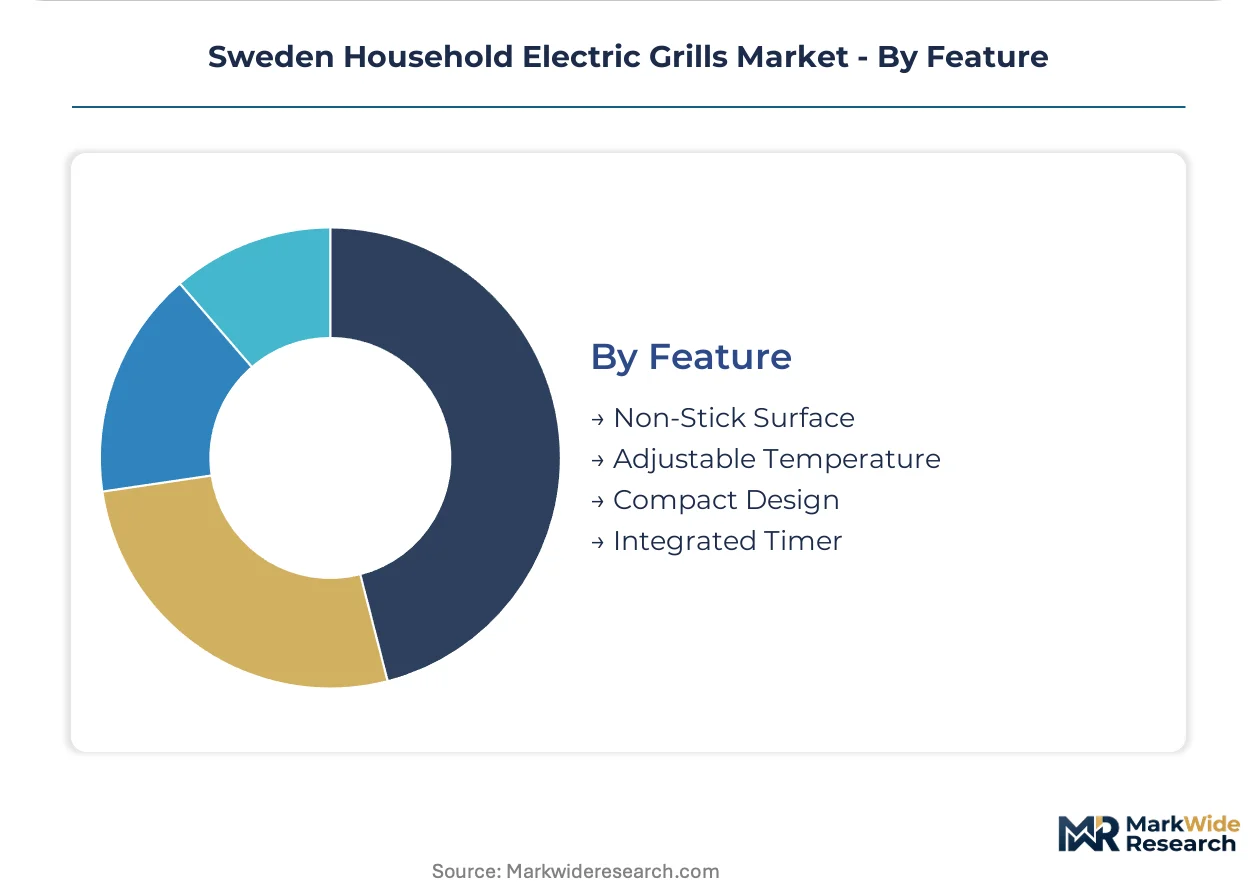
Technology bundling determines price realization, with multi-feature configurations defending margin against single-function commoditization.
- Compact Design:Space-optimized footprints under 30cm width with vertical storage capability. Gothenburg's secondary-city premium renters pay disproportionate premiums for balcony-suitable formats that stow in standard kitchen cabinets during winter months.
- Adjustable Temperature:Microprocessor-controlled heating with five or more discrete settings. Time-pressed urban consumers in Stockholm's tech-forward districts prioritize this capability for protein-specific cooking without supervision.
- Non-Stick Surface:Ceramic or PTFE-coated cooking plates for reduced oil requirements and simplified cleaning.
- Integrated Timer:Digital countdown systems with automatic shutoff functionality.
Compact design commands the dominant share, while adjustable temperature is climbing the fastest as a purchase determinant.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Öresund Bridge and the North Sea Link interconnect anchor Sweden's position within the Nordic-Baltic electricity grid, facilitating cross-border power trade that stabilizes operating costs for energy-intensive appliance manufacturing and consumer electrification trends across the region.
Stockholm County
Single-person households in Stockholm's inner suburbs drive compact-format demand as Södermalm and Vasastaden neighborhoods enforce strict Boverket interpretations on balcony emissions. The Swedish Energy Agency's efficiency labeling requirements shape local retailer assortment toward A-rated sub-1500W units. Premium smokeless grill penetration concentrates in Norrmalm's high-income rental stock where property managers prohibit all combustion alternatives.
Västra Götaland
Gothenburg's secondary-city status creates whitespace for feature-rich models targeting affluent young professionals in Linnéstaden and Majorna districts. BBR fire safety codes apply uniformly across Sweden's second-largest metropolitan area. The region's manufacturing heritage supports specialized distribution through Nordic outdoor retail chains rather than generalist electronics channels.
Skåne
Malmö's high-density housing clusters exhibit the tightest emission enforcement in Sweden, with smokeless infrared systems capturing disproportionate margin in Västra Hamnen and Möllevången rental zones. The Öresund Bridge connection enables Danish supply chain integration for component sourcing. Circuit capacity limitations in pre-1990 apartment stock constrain 2000W+ family-format deployment in older Södra Förstadskanalen residential areas.
South Sweden
Suburban owner-occupied units around Lund and Helsingborg sustain demand for larger cooking surfaces among multi-person households. The region's newer construction stock accommodates dedicated 16A circuits required for premium 2500W models. Local municipal building departments coordinate with Boverket on phased retrofitting of older residential complexes to support higher-wattage appliance installation.
Sweden Household Electric Grills Market Competitive Landscape
Concentration sits with diversified appliance conglomerates and specialized outdoor cooking manufacturers competing across distinct channel and feature vectors. The vendor base splits between Nordic-focused specialty retailers and pan-European electronics distributors, with smokeless technology capabilities emerging as the primary differentiation axis. Strategic archetypes include heritage grill specialists with outdoor retail penetration, diversified small-appliance manufacturers with kitchen channel access, and electronics brands leveraging smart-feature integration. Capacity expansion in ceramic heating element sourcing and geographic diversification of component supply chains represent the dominant competitive moves.
Among heritage outdoor cooking specialists, Weber Inc anchors the premium-tier position through specialized Nordic distribution relationships. Groupe SEB exemplifies the diversified small-appliance archetype with deep tabletop and indoor grill portfolios calibrated to Swedish space constraints. Philips occupies a position within the electronics-integrated segment, competing on timer and temperature control features that resonate with time-pressed urban consumers in Stockholm's tech-forward districts.
| Leading Market Players |
|---|
| DeLonghi |
| Weber Inc |
| Philips |
| Groupe SEB |
| Whirlpool |
| MPM AGD |
| Roller Grill International |
| Electrichef |
| Adler Europe |
| Others |
Value Network & Pricing Analysis
CE marking under EU electrical safety directives gates both supplier qualification and price differentiation simultaneously, forcing manufacturers to absorb extended testing costs while retailers use certification tiers to justify margin spreads between basic coil-element units and premium infrared ceramic systems.
Pricing Analysis
Volume-discount tiering structures separate premium smokeless infrared models from standard ceramic-element units and economy-grade resistive coil designs. Price differentiation rests on Swedish Energy Agency efficiency labeling grades and after-sales warranty bundling. Cost compression in the economy tier intensifies because East Asian component oversupply erodes manufacturer leverage. Singles in Stockholm's micro-apartments exhibit highest price sensitivity, while affluent renters in Gothenburg's Linnéstaden district accept premiums for compact-format smokeless systems.
Supply Chain Analysis
Inventory lead times for ceramic heating elements and catalytic filter assemblies have extended due to concentrated sourcing patterns. Component manufacturing draws from China, South Korea, and Vietnam, with resistive coils and infrared ceramics as critical inputs. Single-source vulnerability in ceramic element fabrication exposes Swedish distributors to logistics disruptions. Distribution runs through Nordic outdoor retail chains and generalist electronics retailers, with direct-to-consumer channels gaining share among urban singles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Stockholm's rental property managers who negotiate bulk procurement agreements for BBR-compliant appliances, fragmenting traditional individual-purchase patterns.
For Market Incumbents: Shield market position by deepening captive supply relationships with Taiwanese ceramic heating element specialists and accelerating sub-1000W ultra-efficient R&D to capture Swedish Energy Agency A-rated positioning. Emerging direct-to-consumer entrants threaten specialty retail channel control. Certification investment in enhanced smokeless filtration technology defends margin pools in Malmö's emission-restricted zones.
For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission consultations enables compressed launch timelines versus standard compliance pathways. Gothenburg's secondary-city premium segment offers the most penetrable whitespace, with affluent young professionals underserved by incumbent tabletop portfolios. Specialty kitchen retailer partnerships provide bypass of saturated electronics channels.
For Investors and Strategic Acquirers: BBR's extension to pre-2011 housing stock reshapes the acquisition landscape by elevating smokeless technology capabilities to primary valuation drivers. The five-to-ten year viability window favors targets with integrated ceramic element sourcing and Nordic distribution relationships. Acquisition target archetype: mid-cap specialists with Boverket compliance expertise and sub-1500W compact design portfolios. Monitor Swedish Energy Agency efficiency standard tightening as the key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Smokeless Technology Certification | Boverket compliance unlocks premium positioning in Stockholm's rental-restricted zones. |
| Ceramic Element Supply Agreement | Taiwanese sourcing partnerships reduce lead-time exposure and stabilize input costs. |
| Direct-to-Consumer Channel Launch | Manufacturer websites capture urban singles bypassing Nordic outdoor retail gatekeepers. |
| Sub-1000W Ultra-Efficient R&D | Swedish Energy Agency A-rated positioning commands margin expansion in efficiency-conscious segments. |
| Specialty Retailer Partnership | Nordic outdoor living chains enable higher-margin placement versus generalist electronics. |
Research Methodology
Initial hypotheses were tested against primary input from product development executives at appliance manufacturers, regulatory affairs specialists, category buyers at Nordic outdoor retail chains, and procurement managers at Swedish rental property management firms and refined through secondary validation against EU customs trade data, Swedish Energy Agency efficiency labeling databases, Boverket regulatory filings, and SEC 10-K disclosures from listed appliance conglomerates. Bottom-up demand modeling triangulated with top-down market sizing across product type, end-user, power rating, and feature segmentation.
Variance-decomposition analysis isolated drivers of forecast uncertainty across the projection horizon. Segmentation dimensions modeled include product format, household composition, wattage tier, and smokeless technology integration. CAGRs were derived from fitted growth curves applied to base-year estimates. Industry-specific forecast inputs encompassed BBR enforcement trajectory projections and Swedish household formation demographic shifts.
Decision-makers should treat outputs as directional under assumptions of continued BBR stringency and stable Nordic electricity pricing; material deviation in regulatory interpretation or power market volatility would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Kitchen and Dining Furniture Market
Kitchen and Dining
Dining Table Market
Kitchen and Dining
Europe Kitchen Hobs Market
Kitchen and Dining
Kitchen Cabinets Market
Kitchen and Dining
Modular Kitchen Market
Kitchen and Dining
Pull Out and Down Kitchen Faucet Market
Kitchen and Dining
Flip-Top Tables Market
Kitchen and Dining
Household Slicer Market
Kitchen and Dining
Interactive Tables Market
Kitchen and Dining
US Tableware Market
Kitchen and Dining
Kitchen Islands and Carts Market
Kitchen and Dining
UK Ceramic Tableware Market
Kitchen and Dining
Kitchen Faucets Market
Kitchen and Dining
Turkey Kitchen Furniture Market
Kitchen and Dining
Range Hood and Cooktop Market
Kitchen and Dining
Outdoor Kitchen Market