
 Rainbow Flatware Market | 2026-2036
Rainbow Flatware Market Size, Share, and Industry Trends Forecast 2026-2036
Rainbow Flatware Market Analytics
Titanium-nitride and PVD ceramic coatings are rebalancing cost structures across the rainbow flatware supply chain as manufacturers shift away from traditional electroplating. Oneida Limited leverages captive finishing capacity in its Upstate New York facilities to control coating consistency. Zwilling J.A. Henckels sustains premium positioning through Solingen-forged substrates paired with proprietary vapor-deposition protocols. WMF Group anchors its German manufacturing base with automated polishing lines that reduce labor intensity on iridescent surface treatments.
Rainbow flatware denotes eating and serving utensils finished with interference-color thin films, typically applied via physical vapor deposition at 200–400°C onto stainless steel 18/10 substrates, producing angle-dependent hues without organic dyes. The primary commercial purpose is to differentiate hospitality table settings and command visual premium in social-media-driven dining environments. Stainless steel dominates material value owing to substrate durability and coating adhesion, while serving utensils capture disproportionate margin as banquet and catering operators replace entire presentation tiers rather than individual pieces. Eco-friendly form factors are gaining fastest within institutional procurement as European hospitality groups phase single-use plastics under CSRD-linked supply chain mandates.
The US FDA regulates surface-contact metals under 21 CFR 175.300 for indirect food additives, while EPA oversight of hexavalent chromium emissions constrains legacy electroplating expansion. EU REACH and RoHS frameworks restrict cadmium and lead in decorative coatings, pushing finishers toward vacuum-arc PVD systems that eliminate wet-chemical baths. Stakeholders must monitor how California's Proposition 65 enforcement evolves for titanium-based colorants, as this will determine whether West Coast hospitality distributors qualify coated imports or demand third-party migration testing.
Market Dynamics
PVD ceramic coating technology is compressing production timelines while EU REACH and F-Gas Regulation frameworks force wet-chemical electroplating into regulatory retreat. This structural pivot reconfigures cost structures across substrate preparation, vacuum-arc deposition, and quality assurance stages.
Growth Catalysts
- CSRD-linked procurement mandates:European hospitality groups under Corporate Sustainability Reporting Directive obligations are phasing single-use plastics and redirecting capital toward durable, reusable tableware with certified surface treatments.
- Instagram-native dining formats:Specialty restaurants in the United States and Germany are expanding experiential table setting budgets to capture social-media-driven reservation demand.
- Titanium-nitride PVD systems:Vacuum-arc physical vapor deposition at 200–400°C is replacing hexavalent chromium electroplating, eliminating wet-chemical baths and reducing emission compliance burdens.
Market Restraints
- Substrate cost volatility:Stainless steel 18/10 alloy pricing fluctuates with nickel and chromium spot markets, compressing margin on mid-tier flatware lines.
- Solingen-Sheffield finishing concentration:Captive PVD capacity clusters in German and English cutlery heritage centers, creating supply bottlenecks for non-integrated distributors.
- Hexavalent chromium emission constraints:EPA oversight of Cr(VI) emissions under the Clean Air Act limits legacy electroplating expansion in North American manufacturing zones.
Strategic Opportunities
- Japanese ryokan and omakase formats:Premium hospitality procurement in Tokyo and Kyoto remains underpenetrated by European finishers despite resilient tableware budgets.
- Dual carbon policy convergence:China's MIIT dual carbon goals and EU Green Deal alignment are creating cross-border certification reciprocity for low-emission coating processes.
- Direct-to-hotelier digital platforms:Boutique hotel purchasing managers are bypassing traditional hospitality distributors through specialized B2B procurement portals.
Industry Challenges
- Vacuum technician scarcity:PVD chamber operation and thin-film diagnostics require specialized metallurgical training that outpaces vocational program output in traditional cutlery manufacturing regions.
- Proposition 65 migration testing:California's enforcement trajectory for titanium-based colorants creates qualification uncertainty for West Coast hospitality distributors sourcing coated imports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rainbow Flatware Market |
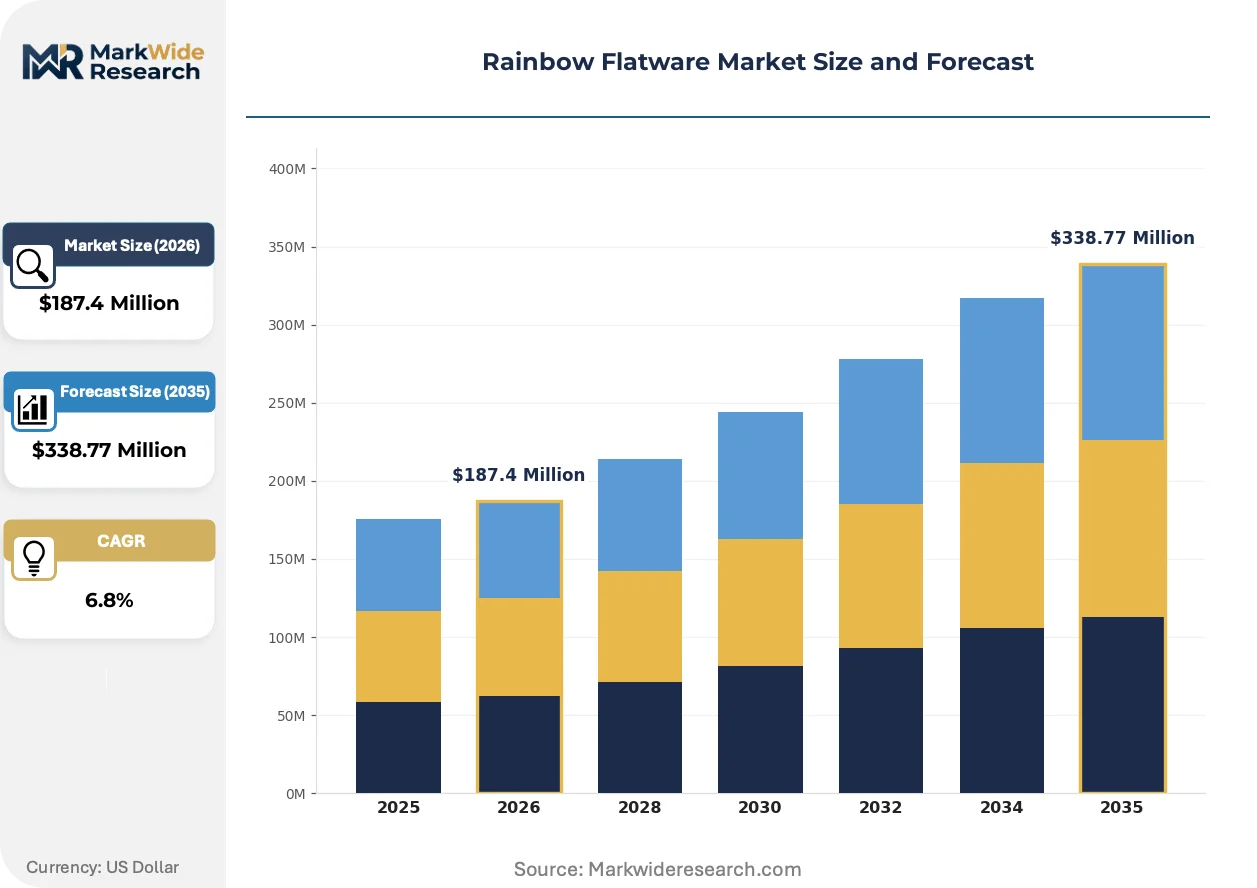
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forks, Knives, Spoons, Serving Utensils Material: Stainless Steel, Plastic, Wood, Bamboo Form: Sets, Individual Pieces, Disposable, Eco-Friendly End User: Households, Restaurants, Catering Services, Events |
| Companies Covered | Oneida Limited, Lenox Corporation, Zwilling J.A. Henckels, Elyon Tableware, Snb Enterprises Private Limited, Iqra Home Collection, Berglander Inc., WMF Group, Fortessa Tableware Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rainbow Flatware Market Evolving Landscape
Coating technology convergence and regulatory chemistry bans are compressing the competitive window for traditional finishers. Three developments are restructuring how rainbow flatware reaches hospitality buyers.
Hybrid PVD-ceramic deposition is unifying corrosion resistance and optical interference in single-chamber processes. Banquet operators in Germany and the United States are specifying these finishes for high-rotation serving utensils. The technology is unifying what previously required separate hard-coat and decorative steps, collapsing subcontractor layers in the supply chain.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant-dependent cooling system retrofits in coating facilities. This industrial consequence forces capital redeployment toward closed-loop vacuum systems. Solingen-area finishers are most affected, with several automated polishing lines now paired with regenerative thermal oxidizers to maintain throughput under tightening emission budgets.
Certification-driven preference rotation is elevating third-party migration testing from optional to mandatory in distributor qualification protocols. Hospitality procurement teams in California and New York are rejecting uncertified shipments. This behavior is most visible in West Coast boutique hotel chains, where purchasing managers now require ISO 17025-accredited laboratory reports before approving vendor onboarding.
Rainbow Flatware Market Segmentation
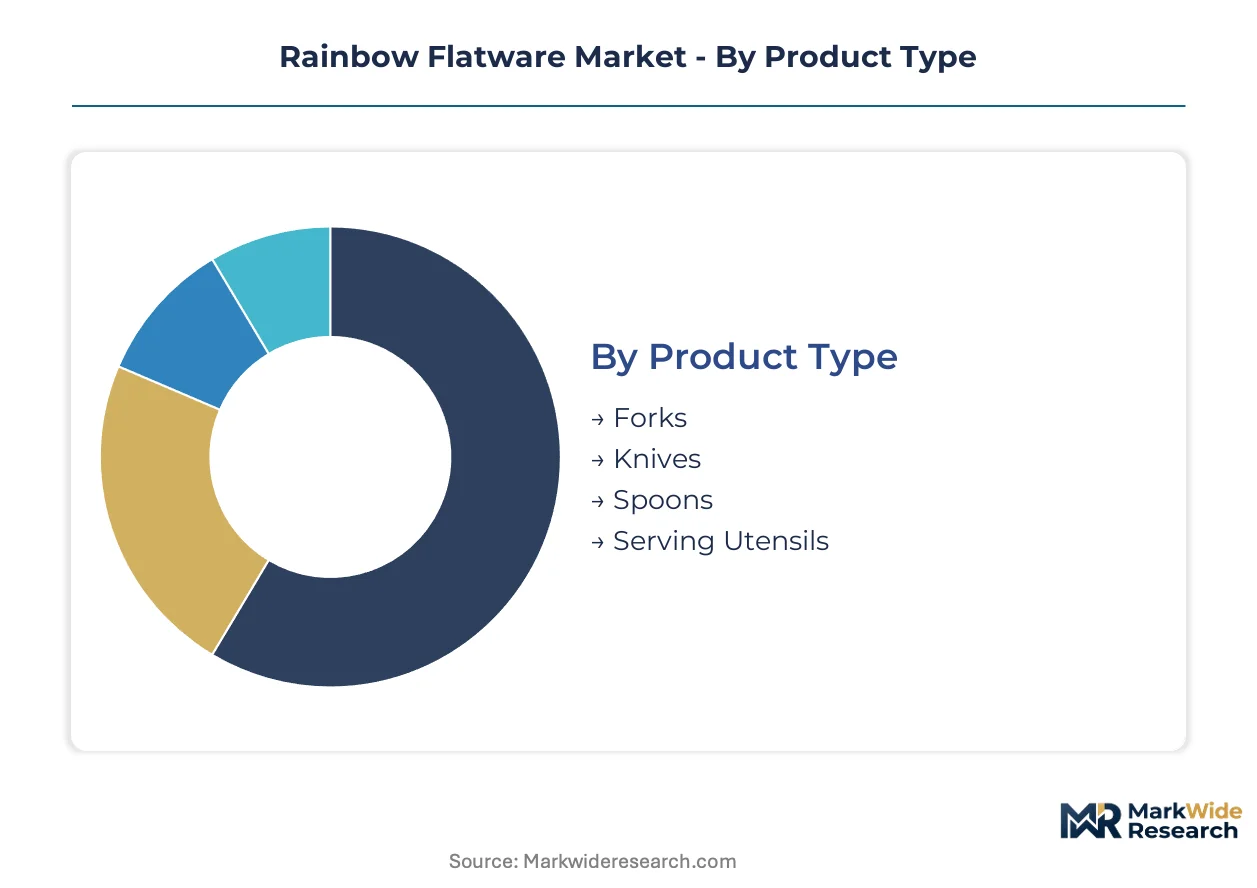
Rainbow flatware segmentation reveals how coating technology, material substrate, and procurement format intersect to determine margin capture. Each dimension carries distinct regulatory exposure and customer acquisition economics.
Product Type:
Forks, knives, spoons, and serving utensils each occupy different positions in the hospitality procurement hierarchy, with serving pieces commanding premium placement in experiential dining formats.
- Serving Utensils:Banquet and catering operators replace entire presentation tiers rather than individual pieces, concentrating demand in high-rotation serving spoons, ladles, and cake servers. German and US hospitality groups specify these for social-media-driven table settings where visual differentiation justifies per-piece premiums.
- Knives:Solingen-forged substrates paired with PVD ceramic coatings anchor premium positioning, with blade hardness requirements driving specification toward 18/10 stainless steel bases. Japanese omakase venues in Tokyo and Kyoto represent underpenetrated demand for this tier.
- Forks:Standard dining applications dominate volume, with tine geometry and coating uniformity determining supplier qualification.
- Spoons:Soup and dessert variants face commodity pressure in mid-tier hospitality procurement.
Serving utensils lead volumes today; knives are gaining share fastest through premium hospitality specification.
Material:
Substrate selection determines coating adhesion performance, regulatory compliance pathway, and end-use durability requirements across hospitality and household segments.
- Stainless Steel:18/10 alloy substrates dominate commercial value owing to coating adhesion properties and REACH-compliant surface treatment compatibility. PVD ceramic deposition at 200–400°C achieves optimal titanium-nitride thin-film formation on this base, with German and US finishers controlling captive capacity.
- Plastic:Single-use alternatives face phase-out under EU CSRD-linked procurement mandates, collapsing demand in European institutional channels.
- Wood:Natural substrates exclude PVD compatibility, limiting rainbow finish application to surface staining methods with inferior durability.
- Bamboo:Eco-friendly positioning attracts sustainability-focused household procurement, though coating technology constraints restrict commercial hospitality adoption.
Stainless steel leads volumes today; bamboo is climbing the fastest through sustainability-driven household substitution.
Form:
Packaging configuration shapes distribution economics and customer acquisition cost, with sets and individual pieces serving distinct procurement workflows in hospitality versus retail channels.
- Sets:Coordinated place settings dominate boutique hotel and specialty restaurant procurement, with 4-piece and 5-piece configurations standardizing experiential table presentation. Direct-to-hotelier digital platforms are bypassing traditional distributors for this format.
- Eco-Friendly:Reusable alternatives with certified surface treatments capture institutional procurement redirecting capital from single-use plastics under European sustainability mandates.
- Individual Pieces:Replacement demand and mix-and-match curation drive specialty retail and hospitality replenishment purchasing.
- Disposable:Regulatory retreat across EU and California markets compresses addressable volume for this format.
Sets lead volumes today; eco-friendly form factors are expanding most quickly through CSRD-aligned procurement redirection.
End User:
Customer type determines specification intensity, certification requirements, and price realization, with hospitality procurement carrying the most demanding surface treatment standards.
- Restaurants:Specialty dining formats in Germany, the United States, and Japan drive specification of PVD-coated 18/10 flatware with third-party migration testing. Instagram-native venues expand experiential table setting budgets to capture reservation demand through visual differentiation.
- Catering Services:High-rotation serving utensil replacement concentrates demand in banquet operators specifying hybrid PVD-ceramic finishes for durability.
- Households:Retail channel procurement favors set configurations with lower certification burden than hospitality specification.
- Events:One-time use applications face sustainability-driven demand erosion in European markets.
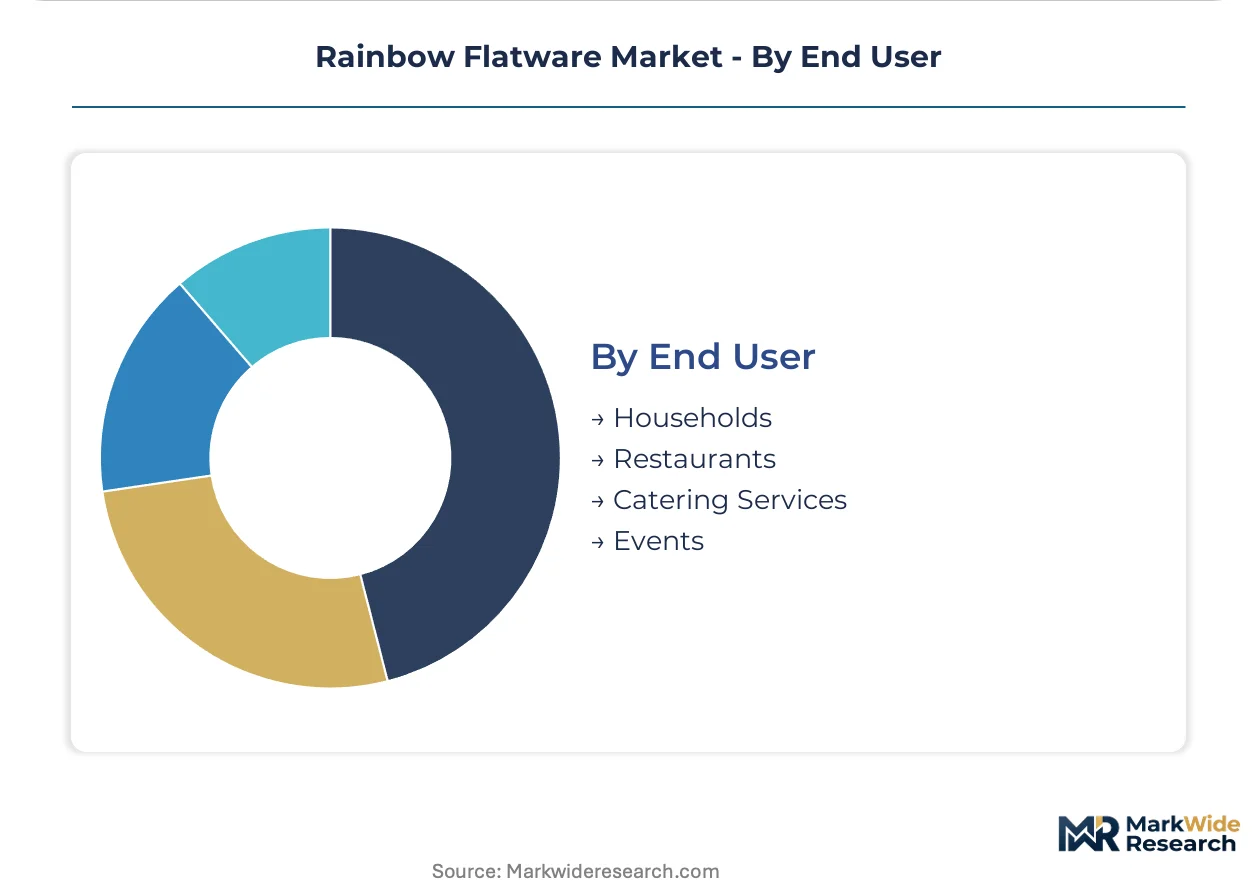
Restaurants lead volumes today; catering services are gaining share fastest through serving utensil tier replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Solingen anchors the European rainbow flatware supply chain through concentrated PVD finishing capacity and heritage cutlery manufacturing infrastructure. Specialty restaurants in Germany, the United States, and Japan are expanding procurement budgets for color-finished tableware. Regulatory frameworks in the EU and California are reshaping coating chemistry standards and import qualification protocols.
United States
Instagram-native dining formats in New York and Los Angeles are expanding experiential table setting budgets to capture reservation demand through visual differentiation. The FDA regulates surface-contact metals under 21 CFR 175.300, while EPA oversight of hexavalent chromium emissions constrains legacy electroplating expansion. Upstate New York hosts captive finishing facilities that control coating consistency for hospitality distributors.
Germany
Specialty restaurants and boutique hotels are redirecting capital toward durable, reusable tableware with certified surface treatments under CSRD-linked procurement mandates. EU REACH and F-Gas Regulation frameworks restrict cadmium and lead in decorative coatings, pushing finishers toward vacuum-arc PVD systems. Solingen-area manufacturers operate automated polishing lines paired with regenerative thermal oxidizers to maintain throughput under tightening emission budgets.
Japan
Premium hospitality procurement in Tokyo and Kyoto remains underpenetrated by European finishers despite resilient tableware budgets for omakase and ryokan formats. METI standards and JIS certification requirements create qualification barriers for imported coated flatware. Osaka-based hospitality distributors are specifying Solingen-forged substrates paired with proprietary vapor-deposition protocols for high-end venues.
China
MIIT dual carbon goals and EU Green Deal alignment are creating cross-border certification reciprocity for low-emission coating processes. The country's national environmental regulator enforces emission standards on metal finishing facilities in the Yangtze River Delta. Zhejiang and Guangdong provinces host subcontracting capacity for substrate preparation and vacuum-arc deposition equipment assembly.
France
Boutique hotel purchasing managers in Paris and Provence are bypassing traditional hospitality distributors through specialized B2B procurement portals. ECHA enforcement of REACH restrictions on titanium-based colorants creates qualification uncertainty for coated imports. Lyon-area catering operators are specifying hybrid PVD-ceramic finishes for high-rotation serving utensils in banquet presentations.
Rainbow Flatware Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers retrofit electroplating lines with closed-loop vacuum systems to meet tightening emission standards. The vendor base clusters around three tiers: heritage European finishers with captive PVD capacity, Asian substrate fabricators supplying unfinished blanks, and North American hospitality distributors controlling brand relationships. Strategic archetypes include vertically integrated cutlery specialists, technology-licensing finishers, and direct-to-hotelier digital platforms. M&A activity and geographic expansion into underpenetrated Japanese markets represent the dominant competitive moves.
Among heritage European fabricators, Zwilling J.A. Henckels and WMF Group exemplify the vertically integrated archetype through Solingen-based manufacturing infrastructure and proprietary finishing protocols. Oneida Limited occupies a position within the North American distributor tier, leveraging Upstate New York facilities for coating consistency control. These three companies represent contrasting strategic postures: German heritage positioning through forged substrates, automated polishing scale, and captive North American finishing capacity respectively.
| Leading Market Players |
|---|
| Oneida Limited |
| Lenox Corporation |
| Zwilling J.A. Henckels |
| Elyon Tableware |
| Snb Enterprises Private Limited |
| Iqra Home Collection |
| Berglander Inc. |
| WMF Group |
| Fortessa Tableware Solutions |
| Others |
Value Network & Pricing Analysis
PVD ceramic coating adoption is compressing production economics while concentrating supply control among German and US finishers with captive vacuum-arc capacity. This technology pivot simultaneously raises capital barriers for new entrants and tightens margin capture for integrated manufacturers serving hospitality procurement.
Pricing Analysis
Input-cost pass-through from nickel and chromium spot volatility runs through stainless steel 18/10 substrate pricing, compressing margins on mid-tier lines. Three-tier pricing structure across premium, standard, and economy levels separates Solingen-forged PVD finishes from outsourced ceramic coatings and legacy electroplated alternatives. Price differentiation hinges on certification grade and volume scale, with ISO 17025-accredited migration testing commanding hospitality premiums. Cost compression in standard tiers is intensifying because substrate volatility outpaces coating efficiency gains. Boutique hotel procurement shows least price sensitivity; institutional catering channels exhibit highest.
Supply Chain Analysis
Single-source vulnerability sits with Solingen-area PVD chamber operators, where vacuum technician scarcity constrains capacity expansion. Geographic supply concentration clusters in Germany, the United States, and Japan, with substrate preparation feeding from Chinese Zhejiang and Guangdong fabricators. Raw material dependencies rest on nickel-chromium alloy feedstock, titanium sputtering targets, and ceramic precursor chemicals. Supply chain risk centers on regulatory restriction as EU F-Gas and EPA emission frameworks phase out wet-chemical alternatives. Distribution runs through hospitality distributors and direct-to-hotelier digital platforms bypassing traditional wholesale tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rainbow flatware functions as a stable compounder, with experiential dining formats and CSRD-linked procurement redirection providing durable demand underpinnings across hospitality cycles.
For Market Incumbents: Cement Solingen-forged substrate positioning through proprietary vapor-deposition protocol investment, defending against Asian finishers acquiring European heritage brands. Prioritize captive PVD capacity addition in Upstate New York or Solingen to maintain coating consistency control as vacuum technician scarcity worsens. Channel control through direct-to-hotelier digital platforms protects margin from distributor consolidation.
For New Entrants and Emerging Players: Begin with Japanese omakase and ryokan format penetration, where METI standards and JIS certification barriers have left European finishers underrepresented despite resilient procurement budgets. Target white-space in hybrid PVD-ceramic serving utensils for German and US banquet operators replacing entire presentation tiers. Go-to-market through specialized B2B procurement portals serving boutique hotel purchasing managers.
For Investors and Strategic Acquirers: Roll-up economics work for technology-licensing finishers with vacuum-arc PVD chamber assets because regulatory chemistry bans are stranding electroplating capacity and creating forced seller dynamics. Long-term viability favors vertically integrated specialists with substrate forging and captive finishing under single ownership. Watch California Proposition 65 enforcement trajectory for titanium-based colorants as inflection indicator for West Coast hospitality distributor qualification requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive PVD Capacity Expansion | Solingen and Upstate New York facilities control coating consistency for hospitality distributors. |
| Third-Party Migration Testing Investment | ISO 17025-accredited laboratory reports now gate vendor onboarding for West Coast boutique hotels. |
| Direct-to-Hotelier Digital Platform Launch | Boutique hotel purchasing managers in Paris and Provence bypass traditional hospitality distributors. |
| Hybrid PVD-Ceramic Process Development | German and US banquet operators specify unified corrosion resistance and optical interference finishes. |
| Japanese Market Certification Pursuit | Tokyo and Kyoto omakase venues represent underpenetrated demand for Solingen-forged substrates. |
Research Methodology
Direct dialogue with hospitality procurement managers, PVD chamber operators, cutlery manufacturing plant managers, and regulatory compliance officers grounded this analysis in operational reality. Secondary validation drew from EU REACH substance databases, EPA Clean Air Act enforcement records, FDA 21 CFR 175.300 guidance documents, and hospitality sector trade publications. Bottom-up and top-down triangulation reconciled substrate shipment data with end-user procurement surveys.
Segment-level value and volume trajectories across the analysis window reflect modeled interactions between coating technology adoption curves, regulatory phase-in schedules, and hospitality capital expenditure cycles. Segmentation dimensions included product type, material substrate, form configuration, and end-user category. CAGRs were derived from fitted growth curves calibrated to historical procurement data and disclosed capacity expansion timelines. Industry-specific inputs incorporated nickel-chromium spot price volatility bands and EU F-Gas refrigerant phase-down schedules.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting German-US-Japanese supply corridors and unforeseen breakthroughs in alternative decorative coating chemistries. Forecasts reflect assumptions about regulatory enforcement continuity and hospitality sector capital access. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
Dining Table Market
Kitchen and Dining
Vietnam Kitchen Furniture Market
Kitchen and Dining
Kuwait Kitchen Hoods Market
Kitchen and Dining
Global Wooden Tableware Market
Kitchen and Dining
Outdoor Kitchen Market
Kitchen and Dining
Kitchen Sinks Market
Kitchen and Dining
Brightwood Tray Market
Kitchen and Dining
Egypt Kitchen Hood Market
Kitchen and Dining
Kitchen Islands and Carts Market
Kitchen and Dining
India Kitchen Sink and Other Related Market
Kitchen and Dining
India Kitchen Furniture Market
Kitchen and Dining
Hobs Market
Kitchen and Dining
GCC Modular Kitchen Market
Kitchen and Dining
Sweden Household Electric Grills Market
Kitchen and Dining
Back Table and Cart Covers Market
Kitchen and Dining
North America Kitchen Furniture Market