

Repurposed Human Immunosuppressants Market Size, Share, and Industry Trends Forecast 2026-2036
Repurposed Human Immunosuppressants Market Insights
The EU Green Deal is decoupling pharmaceutical manufacturing from carbon-intensive supply chains, forcing reformulation of corticosteroid and calcineurin inhibitor production processes. Novartis leverages its transplant medicine heritage to anchor repurposing programs in neurology and dermatology. Pfizer competes through geographic dominance in hospital formulary contracts across North America and Western Europe.
Repurposed human immunosuppressants comprise small-molecule and biologic agents originally developed for transplant rejection prophylaxis, now redirected toward T-cell modulation in autoimmune and inflammatory pathologies through mechanisms including cytokine suppression and lymphocyte signaling interruption. Corticosteroids and calcineurin inhibitors retain the largest revenue share due to established safety databases and abbreviated regulatory pathways, while biologics represent the fastest-expanding margin pool as biosimilar competition intensifies in transplant indications. The therapy area dimension shows autoimmune disorders occupying the deepest clinical pipeline, with neurological disorders following as investigators map neuroinflammatory mechanisms to existing immunomodulatory portfolios.
FDA accelerated approval and EMA adaptive pathways govern the evidentiary standards for indication expansion, while WHO prequalification shapes access dynamics in lower-income markets where repurposed generics address lupus nephritis and graft-versus-host disease. The EU AI Act introduces algorithmic scrutiny into patient stratification tools that identify repurposing candidates. Stakeholders must monitor how FDA and EMA convergence on real-world evidence requirements reshapes post-market commitment burdens for label expansion programs.
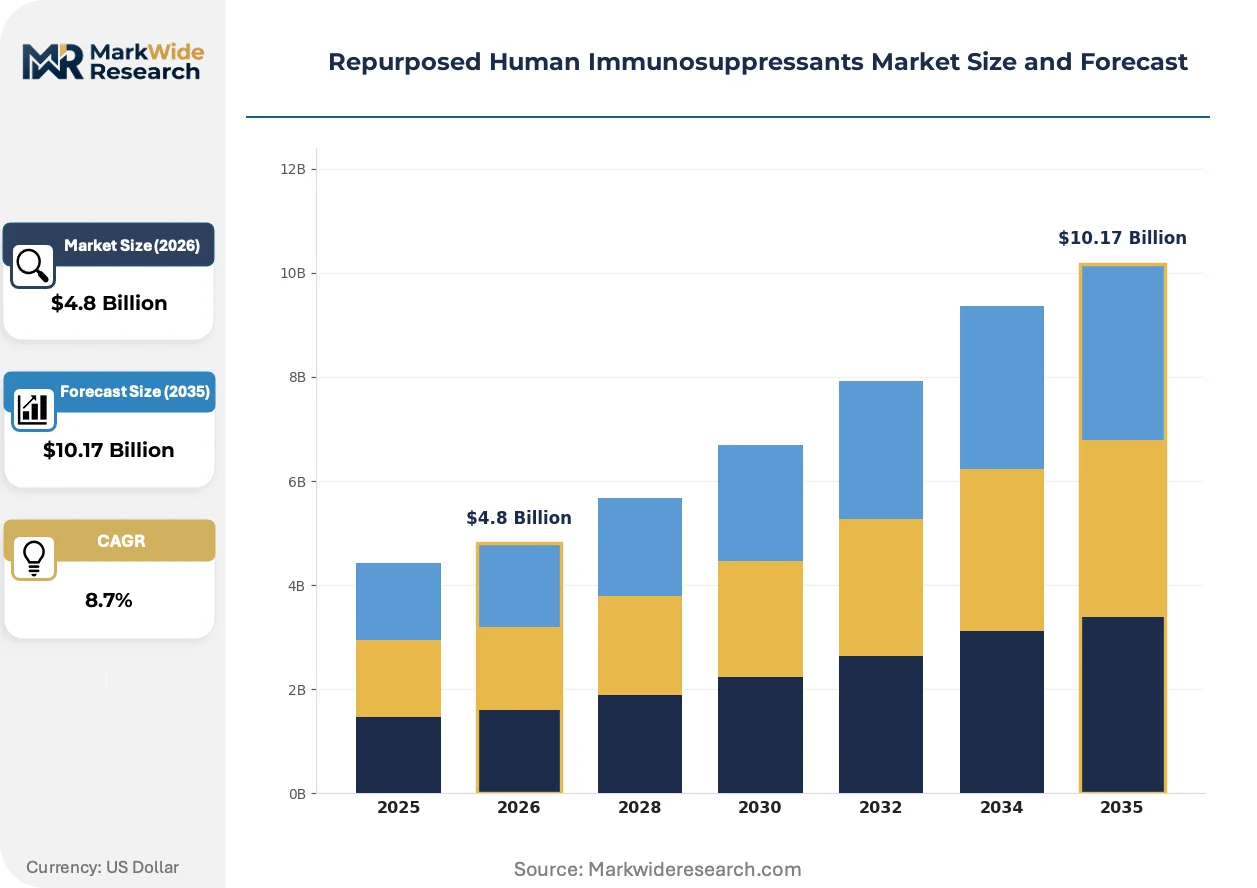
Market Dynamics
Real-world evidence requirements from FDA and EMA are compressing traditional clinical trial timelines for immunosuppressant label expansion, forcing sponsors to integrate electronic health record networks and patient registries into post-market surveillance architectures from protocol design forward.
Growth Catalysts
- EU MDR adaptive pathways:The European Medical Device Regulation's conditional approval mechanisms reduce evidentiary burdens for corticosteroid reformulations targeting dermatological indications, accelerating market entry timelines.
- Autoimmune disorder prevalence:Rising lupus, multiple sclerosis, and rheumatoid arthritis case volumes in aging populations create sustained demand for T-cell modulators with established transplant safety databases.
- Neuroinflammatory mechanism mapping:Academic medical centers in Germany and Japan are repurposing calcineurin inhibitors for Alzheimer's and Parkinson's disease through newly characterized microglial signaling pathways.
Market Restraints
- API supply concentration:Corticosteroid active pharmaceutical ingredient production clusters in India and China, exposing formulators to export restriction risks and quality inconsistency.
- Toxicity profile limitations:Nephrotoxicity and neurotoxicity associated with calcineurin inhibitors restrict dosing escalation in chronic autoimmune protocols versus acute transplant settings.
- Biologic substitution pressure:Monoclonal antibodies targeting specific cytokine pathways displace small-molecule immunosuppressants in psoriasis and inflammatory bowel disease treatment hierarchies.
Strategic Opportunities
- EU Green Deal manufacturing incentives:Carbon-neutral production process investments for corticosteroid synthesis unlock preferential procurement status within European hospital formulary systems.
- Real-world data monetization:Post-market surveillance networks in the United States generate evidence packages supporting off-label reimbursement negotiations with pharmacy benefit managers.
- Neurological indication white space:Amyotrophic lateral sclerosis and multiple sclerosis represent underpenetrated therapy areas where immunomodulatory mechanisms remain clinically validated but commercially undeveloped.
Industry Challenges
- Specialized immunology talent scarcity:Clinical development teams require expertise spanning transplant medicine, neurology, and dermatology simultaneously, creating recruitment bottlenecks in Boston and Basel talent markets.
- Legacy IT integration friction:Electronic data capture systems at investigative sites lack interoperability with sponsor real-world evidence platforms, corrupting data lineage for regulatory submissions.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Repurposed Human Immunosuppressants Market Trends and Innovations
Artificial intelligence patient stratification tools are embedding into immunosuppressant development workflows, compressing biomarker discovery timelines and enabling precision dosing algorithms that match drug mechanism to individual inflammatory phenotypes.
Multi-omics integration platforms are unifying genomics, proteomics, and metabolomics data streams to identify repurposing candidates with mechanistic coherence across transplant rejection and autoimmune pathologies. Academic consortia in the Netherlands and Sweden are deploying these platforms at scale. The technology is unifying previously siloed therapeutic area expertise into single development programs that span organ transplantation, dermatology, and neurology indications.
EMA's adaptive licensing framework is mandating iterative benefit-risk reassessment throughout product lifecycles, compelling sponsors to maintain active comparator arms in post-approval studies. This regulatory architecture favors established immunosuppressants with decades of safety data over novel molecular entities. Hospital pharmacists in France and Italy are leveraging these requirements to negotiate indication-specific pricing tiers.
Specialty pharmacy channel consolidation is reshaping how biologic immunosuppressants reach patients, with limited distribution networks displacing traditional wholesale relationships for high-cost therapies. Rheumatology and gastroenterology practices in the United States are migrating infusion administration to ambulatory settings. This channel compression is most visible in Medicare Part B reimbursement territories where site-of-care differentials drive prescribing behavior.
Repurposed Human Immunosuppressants Market Segmentation
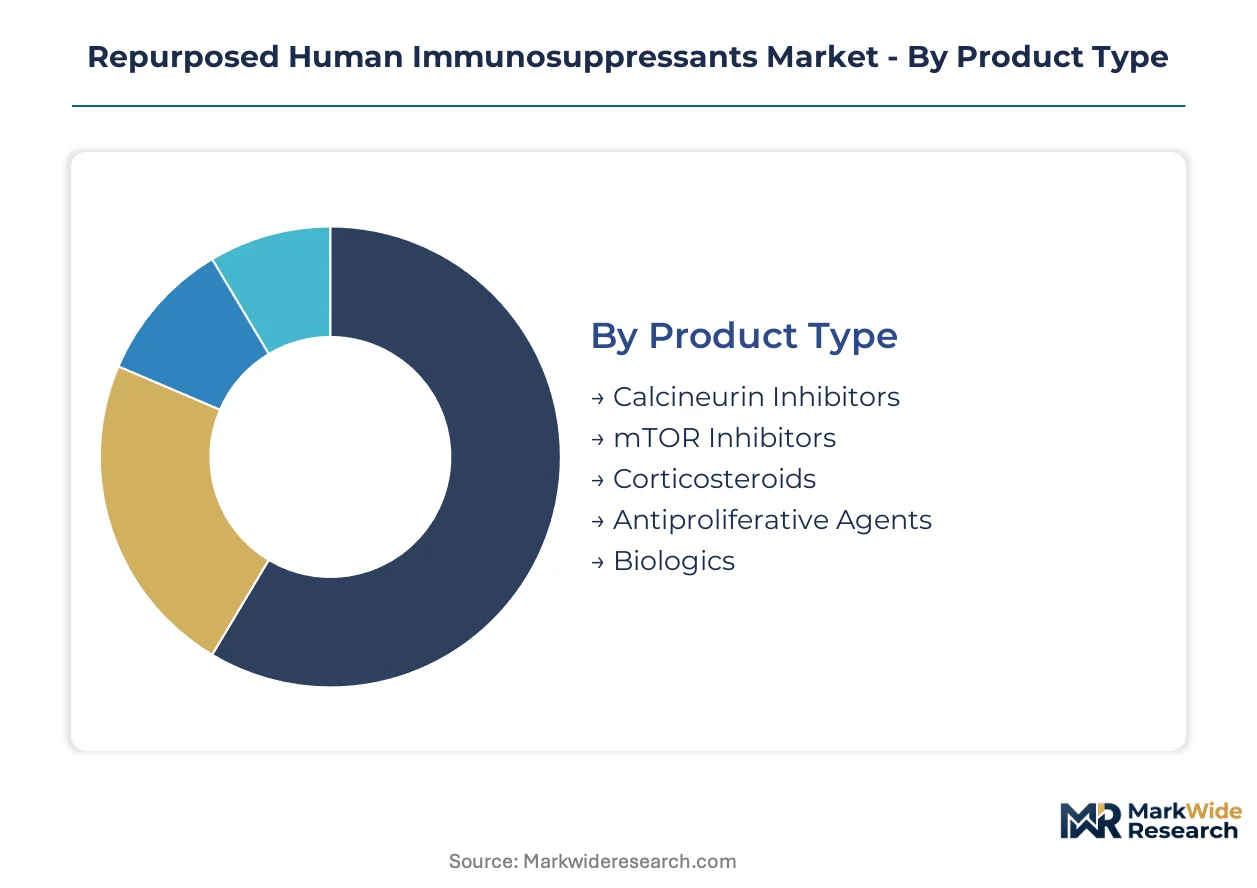
Segmentation in repurposed immunosuppressants determines regulatory pathway selection, pricing architecture, and channel strategy. Each dimension carries distinct certification burdens and real-world evidence requirements that reshape commercial timelines.
Product Type:
FDA accelerated approval and EMA adaptive pathways impose tiered evidentiary standards across molecular classes, with calcineurin inhibitors and corticosteroids leveraging decades of transplant safety data while biologics face intensifying biosimilar scrutiny.
- Calcineurin Inhibitors:Cyclosporine and tacrolimus formulations modulate T-cell activation through calcineurin-NFAT pathway interruption. German academic medical centers drive neuroinflammatory repurposing trials for Alzheimer's and Parkinson's disease, constrained by nephrotoxicity monitoring protocols in chronic dosing regimens.
- Corticosteroids:Prednisone and methylprednisolone derivatives suppress cytokine transcription via glucocorticoid receptor agonism. Demand concentrates in United States dermatology practices for psoriasis and atopic dermatitis, where abbreviated 505(b)(2) pathways accelerate label expansion versus de novo drug development.
- mTOR Inhibitors:Sirolimus and everolimus interrupt lymphocyte proliferation through mTORC1 signaling blockade.
- Antiproliferative Agents:Azathioprine and mycophenolate mofetil inhibit purine synthesis in rapidly dividing lymphocytes.
- Biologics:Monoclonal antibodies and fusion proteins targeting specific cytokine axes.
Corticosteroids sit at the top of the volume ranking, with biologics climbing the fastest as precision immunomodulation displaces small-molecule protocols in rheumatology and gastroenterology.
Therapy Area:
Application-specific dosing protocols and duration requirements create divergent margin profiles across therapeutic domains, with chronic autoimmune indications commanding premium pricing against acute transplant prophylaxis.
- Autoimmune Disorders:Lupus nephritis, rheumatoid arthritis, and multiple sclerosis protocols require sustained immunomodulation with biomarker-guided dose titration. United States rheumatology practices generate the deepest prescription volumes, though Japanese neurologists are expanding multiple sclerosis applications through PMDA-supported adaptive trials.
- Neurological Disorders:Amyotrophic lateral sclerosis and Alzheimer's disease represent mechanistically validated but commercially underdeveloped territory. Academic consortia in Sweden and the Netherlands deploy multi-omics platforms to stratify microglial activation phenotypes for calcineurin inhibitor matching.
- Organ Transplantation:Graft-versus-host disease and rejection prophylaxis remain the original indication anchor.
- Dermatological Conditions:Psoriasis and atopic dermatitis drive topical formulation innovation.
- Respiratory Diseases:Interstitial lung disease and severe asthma represent emerging inhaled delivery targets.
Autoimmune disorders command the largest revenue pool, with neurological disorders expanding most quickly as neuroinflammatory mechanisms yield validated drug repositioning targets.
End User:
Site-of-care reimbursement differentials and infusion infrastructure requirements fragment channel economics, with hospital outpatient departments and ambulatory settings competing for biologic administration volumes.
- Hospitals:Transplant centers and academic medical centers anchor complex immunosuppressant protocols requiring therapeutic drug monitoring. United States Medicare Part B reimbursement territories concentrate infusion administration in hospital outpatient departments, where site-of-care differentials drive prescribing behavior toward captive pharmacy networks.
- Specialty Clinics:Rheumatology, dermatology, and neurology practices manage chronic autoimmune protocols with biomarker surveillance. German and French clinics are migrating infusion administration to ambulatory settings under EMA adaptive licensing frameworks that mandate iterative benefit-risk reassessment.
- Research Institutes:Academic medical centers conduct mechanistic validation and repurposing trials.
- Ambulatory Care Centers:Standalone infusion centers compete on convenience and cost.
- Pharmacies:Specialty pharmacy networks manage oral immunosuppressant distribution and adherence programs.
Hospitals retain the highest patient acuity and reimbursement rates, with specialty clinics gaining share fastest as site-of-care migration accelerates under cost containment pressure.
Delivery Mode:
Route selection determines manufacturing complexity, cold chain requirements, and patient compliance architecture, with oral and subcutaneous formats competing on convenience against intravenous efficacy guarantees.
- Oral:Tablets and capsules dominate maintenance therapy for chronic autoimmune conditions, with corticosteroid and calcineurin inhibitor formulations benefiting from decades of generic competition that compresses pricing but expands access. Japanese and United States formularies prioritize oral options for outpatient lupus and rheumatoid arthritis management.
- Intravenous:Infusion delivery ensures bioavailability for acute transplant rejection and severe autoimmune flares. Hospital pharmacy procurement in Germany and France negotiates indication-specific pricing tiers under EMA post-approval commitment frameworks.
- Subcutaneous:Self-administered biologics reduce site-of-care dependency.
- Topical:Dermatological corticosteroid and calcineurin inhibitor creams target localized inflammation.
- Inhalation:Respiratory immunosuppressant delivery remains investigational for interstitial lung disease.
Oral formulations maintain volume leadership across all therapy areas, with subcutaneous biologics gaining share fastest as patient-administered alternatives displace hospital-based infusion dependence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transplant medicine originated in Boston and Paris during the 1950s and 1960s, establishing the clinical infrastructure that now anchors immunosuppressant repurposing programs. Specialist centers in these founding cities remain reference sites for adaptive trial design.
United States
Medicare Part B reimbursement differentials concentrate biologic infusion volumes in hospital outpatient departments across the Northeast and California. FDA accelerated approval pathways compress evidentiary timelines for corticosteroid label expansion in dermatology. The Mayo Clinic in Rochester anchors real-world evidence networks that feed post-market surveillance for neurological repurposing trials.
Germany
Academic medical centers in Heidelberg and Munich drive calcineurin inhibitor trials for Alzheimer's and Parkinson's disease through newly characterized microglial pathways. EMA adaptive licensing mandates iterative benefit-risk reassessment that favors established transplant drugs with decades of safety data. The BioRN cluster in Heidelberg unifies multi-omics platforms for patient stratification.
Japan
PMDA-supported adaptive trials expand multiple sclerosis applications for existing immunomodulators as neurologists address aging-population case growth. The Sakigake designation system accelerates repurposing programs for unmet neurological needs. Tokyo and Osaka academic hospitals anchor biomarker-guided dosing protocols.
Switzerland
Swissmedic's precision medicine frameworks align with Basel-area pharmaceutical manufacturing heritage in transplant medicine. The country's therapeutic drug monitoring infrastructure supports complex chronic autoimmune protocols requiring sustained immunomodulation. Geneva and Zurich specialist practices generate prescription volumes for biologic maintenance therapies.
Netherlands
Academic consortia in Leiden and Utrecht deploy multi-omics integration platforms to identify repurposing candidates across transplant rejection and autoimmune pathologies. The EU AI Act introduces algorithmic scrutiny into patient stratification tools developed at these centers. Dutch hospital pharmacists negotiate indication-specific pricing tiers under EMA post-approval commitment frameworks.
Repurposed Human Immunosuppressants Market Competitive Landscape
Capital-heavy producers with integrated manufacturing footprints compete with asset-light development specialists who license late-stage candidates. The market structure consolidates around transplant medicine heritage players with established safety databases and hospital formulary relationships. Three archetypes dominate: diversified pharmaceutical conglomerates leveraging immunology franchises, mid-cap specialists with neurology or dermatology focus, and biosimilar manufacturers exploiting patent cliffs in biologic transplant indications. Competitive dynamics center on M&A to acquire mechanistic validation platforms and strategic partnerships with academic medical centers for real-world evidence generation.
Among diversified pharmaceutical conglomerates, Novartis and Pfizer exemplify contrasting geographic strategies. Novartis anchors repurposing programs in neurology and dermatology through its Basel-based transplant medicine heritage. Pfizer occupies a position defined by hospital formulary contract density across North America and Western Europe. Astellas Pharma represents the mid-cap specialist archetype with concentrated presence in Japanese and European adaptive trial networks.
| Leading Market Players |
|---|
| Novartis |
| F. Hoffmann-La Roche |
| Astellas Pharma |
| Pfizer |
| Bristol Myers Squibb |
| AbbVie |
| Sanofi |
| GlaxoSmithKline |
| Viatris |
| Others |
Pricing and Supply Chain Analysis
Carbon-neutral corticosteroid synthesis mandated by the EU Green Deal is simultaneously elevating European manufacturing costs and decoupling production from Indian and Chinese API clusters, creating pricing power for compliant producers while compressing margins for legacy formulators tethered to carbon-intensive supply chains.
Pricing Analysis
Indication-specific pricing tiers separate transplant prophylaxis from chronic autoimmune maintenance, with corticosteroid and calcineurin inhibitor formulations commanding premium rates in neurology and dermatology where abbreviated 505(b)(2) pathways accelerate label expansion. Price differentiation rests on therapeutic drug monitoring infrastructure requirements and real-world evidence package completeness, with United States hospital outpatient departments least sensitive due to Medicare Part B reimbursement differentials while European ambulatory clinics face intensifying cost compression from EMA post-approval commitment frameworks.
Supply Chain Analysis
Dual-sourcing qualification requirements from FDA and EMA are compelling formulators to maintain active supplier relationships across Indian and Chinese API producers despite geographic concentration risks, with corticosteroid active pharmaceutical ingredient production drawing from Hyderabad and Zhejiang manufacturing hubs. Raw material dependencies encompass prednisolone intermediates, tacrolimus fermentation feedstocks, and sirolimus rapamycin precursors, exposing the chain to export restriction vulnerability from quality inconsistency events. Distribution runs through specialty pharmacy networks for biologics and wholesale channels for oral small-molecule formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
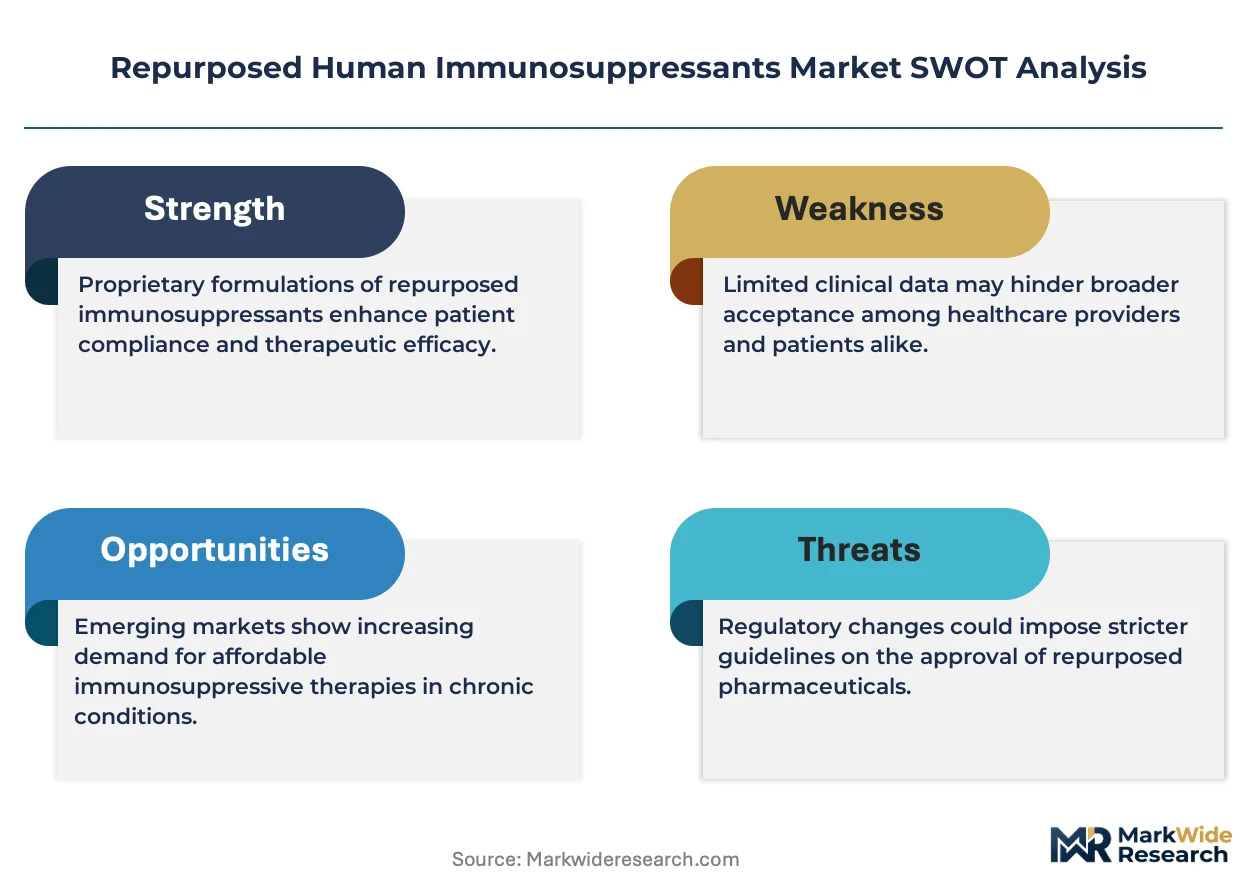
The repurposed human immunosuppressants market functions as a regulatory compounder where FDA accelerated approval and EMA adaptive pathways transform decades of transplant safety data into indication expansion currency, with the EU AI Act introducing algorithmic scrutiny that favors sponsors with embedded real-world evidence infrastructure.
For Market Incumbents: Lock in hospital formulary contract density across Medicare Part B territories by anchoring therapeutic drug monitoring services to calcineurin inhibitor protocols, while acquiring multi-omics patient stratification platforms to defend against biologic substitution pressure in psoriasis and inflammatory bowel disease hierarchies. For New Entrants and Emerging Players: Begin with amyotrophic lateral sclerosis and multiple sclerosis neurological indication white space where immunomodulatory mechanisms remain clinically validated but commercially undeveloped, leveraging academic medical center partnerships in Germany and Japan for mechanistic validation and adaptive trial enrollment. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light development specialists who license late-stage candidates without captive manufacturing, with long-term viability hinging on consolidation around transplant medicine heritage players; monitor FDA-EMA convergence on real-world evidence requirements as the inflection signal for post-market surveillance infrastructure premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Network Integration | Mayo Clinic's Rochester infrastructure feeds FDA post-market surveillance for neurological repurposing trials. |
| Carbon-Neutral Manufacturing Certification | EU Green Deal compliance unlocks preferential procurement status within French and Italian hospital formulary systems. |
| Multi-Omics Platform Acquisition | Leiden and Utrecht academic consortia unify genomics and proteomics data streams for patient stratification. |
| Specialty Pharmacy Channel Consolidation | Limited distribution networks displace wholesale relationships for high-cost biologic immunosuppressants in rheumatology. |
| EMA Adaptive Licensing Alignment | Iterative benefit-risk reassessment mandates favor established drugs with decades of transplant safety databases. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital formulary directors, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up prescription volume modeling and top-down revenue triangulation anchored segment-weighted forecasts.
Segment-weighting approaches distributed value across product type, therapy area, end user, and delivery mode dimensions, with CAGRs derived from patient population growth trajectories, regulatory pathway acceleration effects, and biosimilar penetration curves across the projection horizon. Forecast inputs incorporated PMDA Sakigake designation timelines, Medicare Part B reimbursement differentials, and EU MDR adaptive pathway certification burdens.
Several conditions sit outside the modeled scope, including novel molecular entity approvals that bypass repurposing pathways, abrupt API export restrictions from India or China, and algorithmic patient stratification tool regulatory rejections under the EU AI Act. Deviation in FDA-EMA real-world evidence requirement convergence would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.