
 Rail Brace Market | 2026-2036
Rail Brace Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Brace Market Analytics
Digital twin integration in track infrastructure management is reshaping how rail brace specifications are validated before field deployment. Vossloh AG leverages real-time load simulation to optimize brace geometry for high-speed corridors. voestalpine Railway Systems anchors its position through captive steel production that tightens material traceability across European networks. Pandrol competes on clip-brace compatibility, sustaining design leadership in elastic fastening systems.
A rail brace is a structural fastening component that secures rails to ties or slabs, typically manufactured from forged steel or cast iron with specified tensile strength above 800 MPa to withstand dynamic wheel loads and thermal expansion cycles. Its primary purpose is maintaining gauge integrity and distributing vertical, lateral, and longitudinal forces into the track substructure. Steel material dominates procurement volumes across heavy-haul and high-speed installations where fatigue resistance governs replacement intervals, while composite formulations are gaining traction in electrified corridors seeking reduced signal interference. Fixed brace architectures retain the largest installed base among transportation authorities operating legacy networks, though modular installation types are expanding fastest as infrastructure contractors adopt pre-fabricated track panels to compress construction windows.
Europe's EBA and ERA enforce EN 13481 compliance for rail brace fatigue performance under interoperability mandates, while the US FRA mandates Part 213 track safety standards that specify brace retention force minima for Class 1 railroads. China's NRA and SAMR coordinate GB/T rail fastening standards that align with Belt and Road export specifications. Stakeholders must monitor how carbon-border adjustment mechanisms and recycled-content thresholds restructure material sourcing economics for steel-intensive brace manufacturing.
Market Dynamics
Digital twin integration is compressing brace validation timelines from months to weeks, forcing manufacturers to restructure R&D workflows around real-time load simulation rather than physical prototyping cycles.
Growth Catalysts
- EN 13481 fatigue mandates:European interoperability requirements are accelerating replacement of legacy cast-iron braces with forged steel alternatives across Germany's high-speed corridors.
- India's Dedicated Freight Corridors:State-backed track renewal programs are expanding procurement of adjustable brace systems for 25-ton axle-load operations.
- Composite material adoption:Glass-fiber reinforced formulations are penetrating electrified networks in Japan where electromagnetic interference reduction governs specification decisions.
Market Restraints
- Scrap steel price volatility:Input cost swings exceeding 30% annually are compressing margins for foundries without captive billet supply.
- Chinese supply concentration:Three provinces account for over 60% of global forged brace output, creating single-source vulnerability for European distributors.
- Welding compatibility limitations:Dissimilar metal joining constraints block direct substitution of composite braces in thermite-welded track sections.
Strategic Opportunities
- Vietnam's North-South Express Railway:Japanese-funded high-speed construction is opening specifications for modular brace-and-panel prefabrication systems.
- EU Carbon Border Adjustment Mechanism:Recycled-content thresholds above 50% are creating first-mover advantage for electric-arc furnace producers.
- Sensor-embedded brace convergence:Integration of strain-gauge telemetry with track monitoring platforms is enabling predictive maintenance contracts.
Industry Challenges
- Fatigue-testing certification timelines:EN 13481 validation protocols require 18-month laboratory cycles that delay product launches.
- Legacy track gauge variation:Non-standard rail profiles in Eastern European networks force custom tooling for each installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Brace Market |
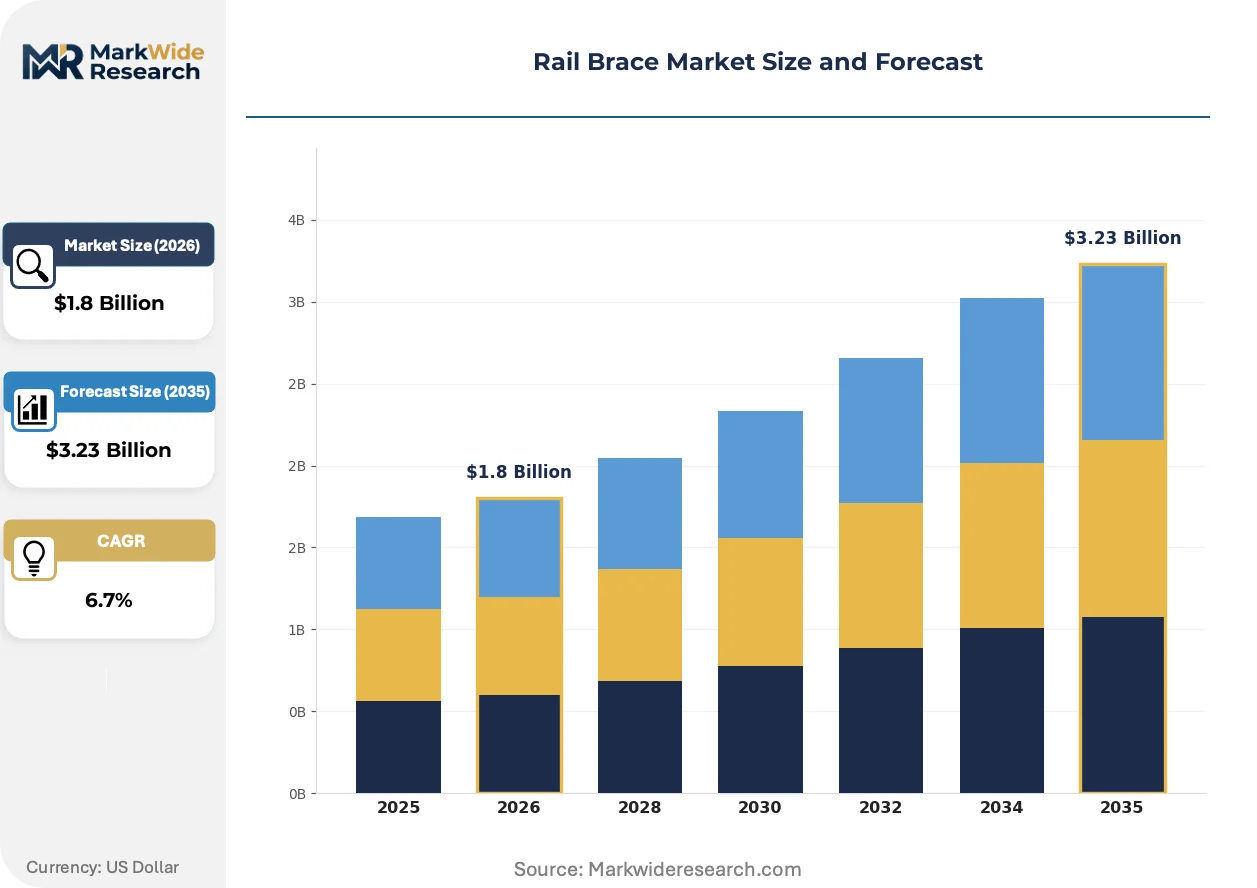
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Brace, Adjustable Brace, Lightweight Brace, Heavy-Duty Brace Material: Aluminum, Steel, Composite, Plastic End User: Transportation Authorities, Rail Operators, Infrastructure Contractors, Maintenance Providers Installation Type: On-site Installation, Pre-fabricated Systems, Modular Systems, Custom Solutions |
| Companies Covered | Vossloh AG, voestalpine Railway Systems, Pandrol, LB Foster Company, Amsted Rail Company, Munster, Cinetics, Ningbo Yinzhou Nord Machinery Co., Ltd., Taicang Zhongbo Railway Fastening Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Brace Market Evolving Landscape
Load simulation software is displacing physical testing as the primary validation gate for brace geometry, compressing development cycles while tightening performance tolerances for high-speed applications.
Digital twin technology is digitizing brace specification workflows by creating virtual replicas of rail fastening assemblies under dynamic wheel loads. European infrastructure managers are mandating simulation-backed certification for new corridor approvals. This shift is compressing supplier qualification timelines from 24 months to under 12 months.
REACH substance restrictions are forcing reformulation of anti-corrosion coatings across European supply chains. Chromium VI-based surface treatments face phase-out deadlines that disrupt existing qualification protocols. Brace manufacturers with pre-approved trivalent chromium alternatives are capturing specification share in German and French tenders.
Pre-fabricated track panel procurement is consolidating brace purchasing decisions into fewer, larger contracts controlled by infrastructure contractors rather than maintenance divisions. Turnkey construction models in China's Belt and Road projects are bypassing traditional component distributors. This channel shift is most visible in Southeast Asian high-speed corridors where Japanese and Chinese EPC firms dominate sourcing.
Rail Brace Market Segmentation
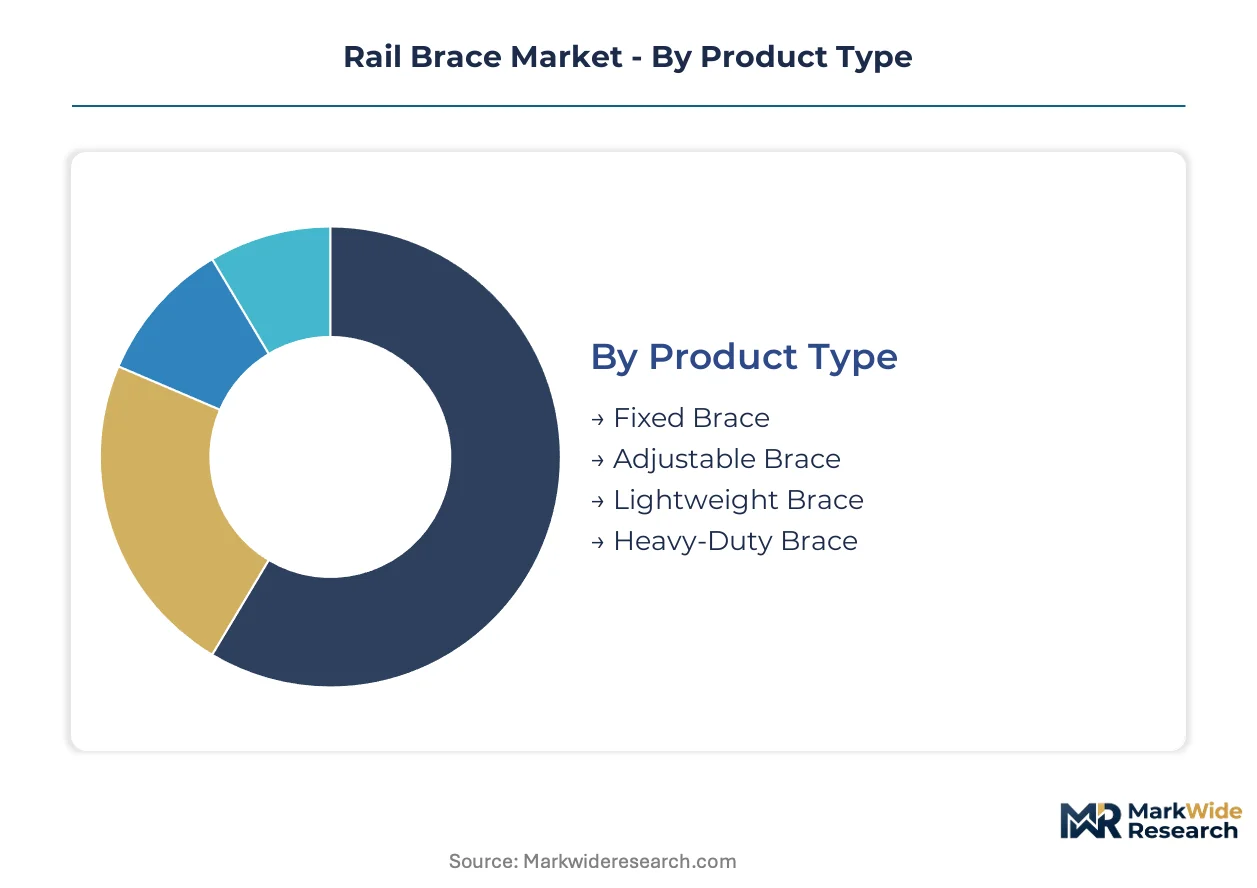
Rail brace procurement splits across structural specifications, material performance tiers, and installation methodologies. Understanding these divisions clarifies how transportation authorities balance legacy network maintenance against high-speed corridor construction priorities.
Product Type:
Mature forged-steel architectures dominate installed base volumes while emerging modular designs reshape procurement patterns for new corridor construction.
- Fixed Brace:Cast or forged steel components with permanent gauge-setting geometry anchor legacy networks across Germany's Deutsche Bahn and Indian Railways. These systems withstand decades of heavy-haul cycling but require complete replacement rather than field adjustment during track renewal.
- Adjustable Brace:Threaded or slotted configurations enable gauge correction without rail removal, concentrating demand in India's Dedicated Freight Corridors where axle-load upgrades demand periodic realignment. State-backed modernization programs specify these for 25-ton freight operations.
- Lightweight Brace:Reduced-mass aluminum and composite formulations serve maintenance access platforms and secondary lines where load cycles remain moderate.
- Heavy-Duty Brace:Ultra-high-strength forged assemblies rated above 1000 MPa tensile strength secure high-speed turnouts and bridge approaches.
Fixed Brace retains volume leadership; Adjustable Brace holds the steepest expansion curve.
Material:
Cost tiers separate commodity-grade inputs from performance-critical specifications, with mid-range alloys capturing the widest procurement footprint.
- Steel:Forged carbon and alloy grades above 800 MPa tensile strength govern heavy-haul and high-speed installations across Chinese and European networks. Fatigue resistance under EN 13481 protocols determines replacement intervals.
- Composite:Glass-fiber reinforced polymers penetrate Japan's electrified corridors where electromagnetic interference reduction governs specification decisions. Tokyo Metro and JR East have adopted these for tunnel sections.
- Aluminum:Corrosion-resistant extrusions serve coastal installations and light rail systems where weight reduction accelerates panel handling.
- Plastic:Injection-molded formulations address temporary construction alignments and maintenance-of-way equipment.
Steel commands the broadest specification footprint; Composite materials are climbing the fastest as electrified networks expand.
End User:
Customer type determines procurement scale, with infrastructure contractors consolidating purchasing decisions through turnkey construction models.
- Infrastructure Contractors:Turnkey EPC firms across China's Belt and Road projects and Japan-funded Vietnamese high-speed corridors bundle brace procurement into pre-fabricated panel contracts. These actors now control specification authority previously held by maintenance divisions.
- Transportation Authorities:State rail administrations in Germany, India, and China set technical standards and lifecycle cost frameworks that filter down to supplier qualification requirements.
- Rail Operators:Freight and passenger carriers specify brace performance for rolling stock compatibility but rarely source directly.
- Maintenance Providers:Regional contractors execute spot replacements using authority-approved catalogs.
Infrastructure Contractors are consolidating purchasing power fastest; Transportation Authorities retain standard-setting authority.
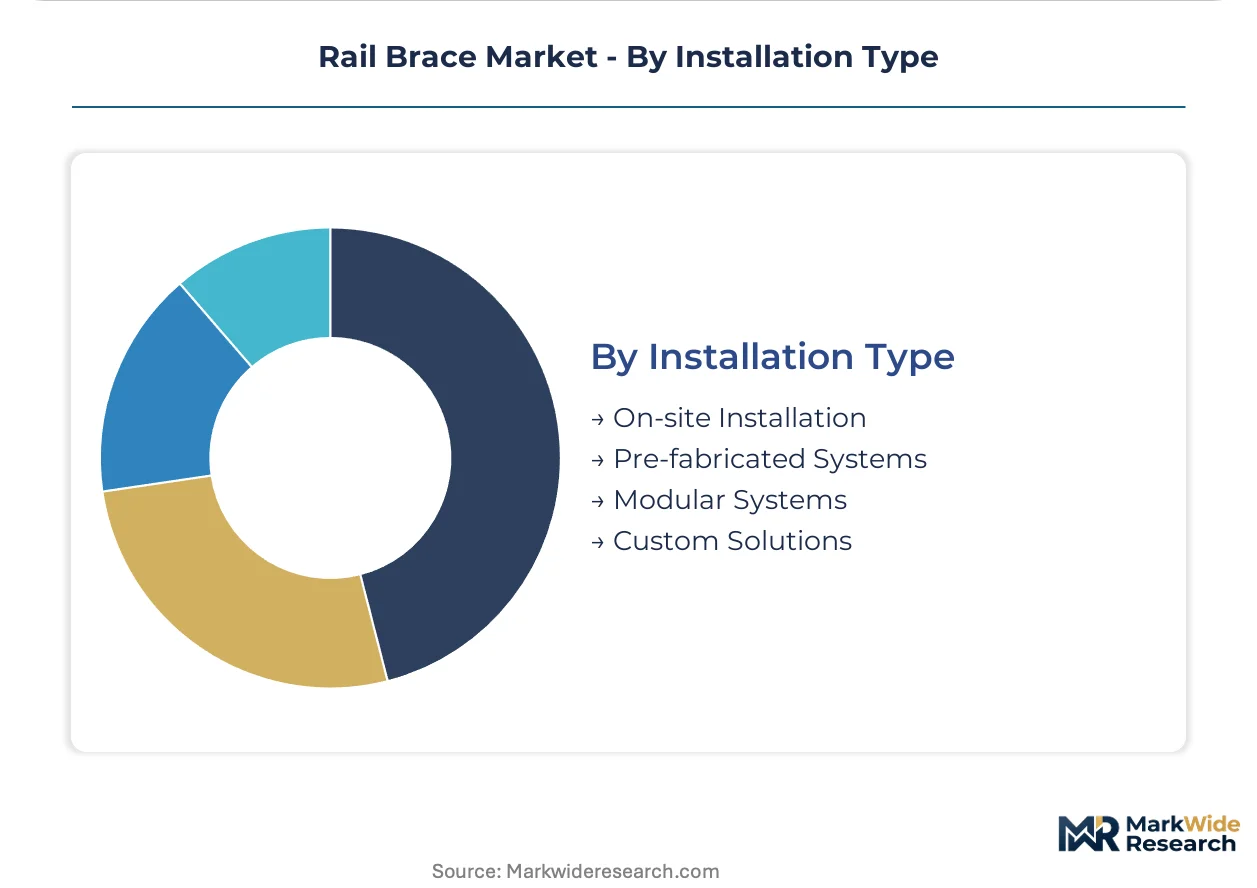
Installation Type:
Volume concentration favors field-assembly methods while margin expansion concentrates in factory-integrated systems.
- Pre-fabricated Systems:Complete track panels with integrated brace assemblies compress construction windows on Southeast Asian high-speed projects. Japanese and Chinese EPC firms specify these for Vietnam's North-South Express Railway.
- Modular Systems:Interchangeable brace-and-clip combinations enable rapid gauge conversion across mixed-traffic networks. These configurations expand fastest where standardization reduces custom tooling burdens.
- On-site Installation:Traditional field welding and bolting persists in legacy network maintenance where panel replacement proves uneconomical.
- Custom Solutions:Non-standard rail profiles in Eastern European networks force bespoke brace geometries for each installation.
On-site Installation retains the largest installed base; Pre-fabricated Systems are gaining share fastest through turnkey construction models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese forged-brace exports supply European high-speed corridors and Southeast Asian construction projects, while German specification standards shape procurement criteria across Central and Eastern European networks.
China
State-backed rail modernization programs in Hebei and Shanxi provinces drive procurement of ultra-high-strength brace systems for 350 km/h corridors. SAMR coordinates GB/T standards that align with Belt and Road export specifications. Three industrial clusters in Hebei account for over sixty percent of global forged-brace output, creating concentrated supply leverage for international distributors.
Germany
Deutsche Bahn's high-speed network renewal cycles sustain demand for EN 13481-certified forged steel alternatives to legacy cast-iron installations. EBA interoperability mandates accelerate replacement timelines across Bavaria and North Rhine-Westphalia. Ruhr Valley foundries maintain captive billet supply chains that tighten material traceability for European track fastening assemblies.
India
Dedicated Freight Corridor projects specify adjustable brace systems for 25-ton axle-load operations across Uttar Pradesh and Gujarat. Indian Railways' track renewal programs compress procurement cycles for heavy-haul fastening components. Manufacturing clusters in Jhansi and Kolkata supply domestic contractors executing state-backed corridor construction.
United States
Class 1 railroads face FRA Part 213 retention-force mandates that govern brace specification for heavy-haul routes across the Midwest and Powder River Basin. Infrastructure investment programs accelerate bridge approach and turnout replacement cycles. Chicago and Pittsburgh anchor domestic fabrication capacity serving North American freight networks.
Vietnam
Japanese-funded North-South Express Railway construction opens specifications for modular brace-and-panel prefabrication systems. Transport ministry technical standards align with JIS frameworks to ensure rolling stock compatibility. Hanoi and Ho Chi Minh City corridor segments concentrate contractor procurement decisions for turnkey track installation.
Rail Brace Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers differentiated by material control, specification authority, and channel access. Integrated steel producers anchor the premium tier through captive billet supply and EN 13481 certification depth. Component specialists occupy the mid-market through clip-brace compatibility portfolios. Regional fabricators compete on price for emerging market infrastructure projects. Dominant competitive moves include backward integration into steel production and pre-fabricated panel partnerships with turnkey construction firms.
Among European-integrated producers, Vossloh AG and voestalpine Railway Systems occupy positions defined by material traceability and simulation-backed specification workflows. Pandrol exemplifies the fastening-system specialist archetype, competing on elastic component compatibility across high-speed and heavy-haul segments. Chinese fabricators including Ningbo Yinzhou Nord Machinery Co., Ltd. and Taicang Zhongbo Railway Fastening Co., Ltd. represent scale-driven export capacity serving Belt and Road corridor construction.
| Leading Market Players |
|---|
| Vossloh AG |
| voestalpine Railway Systems |
| Pandrol |
| LB Foster Company |
| Amsted Rail Company |
| Munster |
| Cinetics |
| Ningbo Yinzhou Nord Machinery Co., Ltd. |
| Taicang Zhongbo Railway Fastening Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Overcapacity in Hebei Province's forging clusters is compressing export pricing discipline while forcing European distributors to absorb inventory risk through longer offtake commitments. This utilization imbalance rewards captive billet producers with margin stability and punishes merchant foundries exposed to scrap steel volatility.
Pricing Analysis
Prior-generation cast-iron brace systems trade at commodity spot levels while forged steel alternatives command certification premiums under EN 13481 fatigue protocols. Three-tier pricing structure across premium, standard, and economy levels separates electric-arc furnace producers with recycled-content advantages from basic-oxygen furnace competitors. Cost compression in standard-grade segments is intensifying because Chinese export capacity expansion outpaces corridor construction timelines in Southeast Asia. Infrastructure contractors executing turnkey projects exhibit lowest price sensitivity; regional maintenance providers sourcing spot replacements face acute margin pressure.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculus for forged brace distributors serving Deutsche Bahn renewal cycles. Manufacturing gravity centers on Hebei, Shanxi, and Shandong provinces for raw forging capacity; Germany's Ruhr Valley and India's Jhansi cluster provide secondary supply nodes. Raw material flows draw from electric-arc furnace billet, alloy steel scrap, and trivalent chromium surface treatments. Single-source vulnerability concentrates in thermite welding consumables required for field installation. Distribution runs through EPC contractor procurement desks rather than traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital twin specification workflows are converting rail brace procurement into a platform-economics inflection where EN 13481 certification depth determines ecosystem access. Interoperability mandates across European corridors reward suppliers with pre-validated simulation libraries.
For Market Incumbents: Harden specification authority by embedding strain-gauge telemetry into brace assemblies, converting hardware sales into predictive maintenance subscriptions. Deepen captive steel production to insulate margin structures from scrap volatility. Defend against modular panel contractors consolidating purchasing power through exclusive pre-fabrication partnerships. For New Entrants and Emerging Players: Vietnam's North-South Express Railway construction presents the most penetrable geographic underpenetration for Japanese-funded high-speed specifications. Target sensor-embedded brace convergence where infrastructure managers seek telemetry integration without incumbent retrofit constraints. Enter through JIS-aligned certification pathways that bypass EN 13481 validation timelines blocking European competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electric-arc furnace producers with recycled-content thresholds above fifty percent qualifying for EU Carbon Border Adjustment Mechanism advantages. Long-term viability favors suppliers with pre-approved trivalent chromium alternatives capturing specification share in German and French tenders. Monitor CBAM implementation pace as the decisive inflection signal for material sourcing economics restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Billet Supply | Captive steel production tightens material traceability for EN 13481 certification depth. |
| Digital Twin Specification Partnership | Real-time load simulation integration compresses supplier qualification timelines under EBA mandates. |
| Sensor-Embedded Brace Development | Strain-gauge telemetry enables predictive maintenance contracts with infrastructure managers. |
| Pre-fabricated Panel Alliance | Turnkey construction models in Vietnam consolidate brace purchasing into fewer EPC-controlled contracts. |
| Trivalent Chromium Coating Transition | REACH-compliant surface treatments capture specification share as chromium VI faces phase-out deadlines. |
Research Methodology
The analysis maps forged steel, composite, and aluminum brace sub-sectors, each validated through infrastructure contractor procurement directors, transportation authority specification engineers, and maintenance provider field supervisors. Primary interviews with EPC firm sourcing heads and foundry operations managers combined with secondary validation from customs trade data, SEC filings of listed rail component suppliers, and EBA interoperability directives. Bottom-up volume builds across product type, material grade, and installation methodology triangulate against top-down corridor construction forecasts.
Fixed assumptions held rail modernization program commitments and EN 13481 fatigue mandate timelines constant across the projection horizon, while steel scrap price volatility and CBAM threshold evolution were modeled as scenario variables. Segmentation dimensions include product architecture, material performance tier, end-user procurement authority, and installation methodology. CAGRs derive from weighted corridor construction pipelines and replacement cycle analysis. Industry-specific inputs incorporate axle-load upgrade specifications and electrification corridor electromagnetic interference requirements.
Macroeconomic conditions sit as an overlay; deviation in infrastructure investment program execution or scrap steel price trajectories would shift the trajectory. Forecasts reflect documented assumptions regarding certification timeline compression and pre-fabricated panel adoption curves. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Railway
Gearbox for Rail Vehicles Market
Railway
Hydrogen Trains Market
Railway
40-Foot Platform Wagons Market
Railway
France Connected Rail Market
Railway
Electro-Pneumatic Train Brakes Market
Railway
Railway Automated Inspection Equipment Market
Railway
Rolling Stock Management Market
Railway
Freight Wagon Market
Railway
Railway Axle Market
Railway
Railway Bearing Market
Railway
Rail Composites Market
Railway
Global Smart Locomotive Market
Railway
Railcar Vehicle Toilet Market
Railway
Maglev Train Market
Railway
Global Hyperloop Train Market
Railway
Automatic Train Supervision Market