
 Antimycobacterial Drugs Market | 2026-2036
Antimycobacterial Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Antimycobacterial Drugs Market Outlook
Hospital procurement of tuberculosis and non-tuberculous mycobacterial therapies is hardening as multidrug-resistant strains proliferate. Johnson & Johnson anchors its position through bedaquiline access programs in high-burden settings. Pfizer leverages its injectable manufacturing scale to supply institutional buyers. Lupin competes on cost-engineered oral fixed-dose combinations for national treatment programs.
Antimycobacterial drugs comprise synthetic and natural-product-derived agents that inhibit mycolic acid synthesis, DNA-dependent RNA polymerase, or arabinosyl transferase in Mycobacterium species, formulated as single agents or combination tablets with defined bioequivalence specifications. Their primary purpose is to achieve sputum culture conversion in active tuberculosis and to suppress nontuberculous mycobacterial pulmonary disease progression. Rifampin-containing regimens occupy the dominant share of first-line protocols, while the injectable delivery mode captures premium positioning for drug-resistant cases requiring directly observed therapy. The immunocompromised patient type represents the fastest-expanding addressable subset, driven by HIV co-infection and biologic immunosuppression.
FDA orphan drug incentives and WHO prequalification standards shape product development priorities and market access pathways for manufacturers targeting endemic regions. EMA's clinical trial guidance on tuberculosis endpoints and India's CDSCO accelerated approval track for anti-TB agents create divergent regulatory compliance burdens across supply footprints. Stakeholders must monitor evolving resistance surveillance data and regulatory exclusivity timelines to align portfolio investments with shifting standard-of-care protocols.
Market Dynamics
Multidrug-resistant tuberculosis strains are hardening hospital procurement standards and forcing manufacturers to revalidate supply chains for second-line injectables and oral fixed-dose combinations across endemic regions.
Growth Catalysts
- WHO Prequalification Standards:Manufacturers achieving WHO prequalification for rifampin-containing regimens gain automatic eligibility for Global Fund and national program tenders in high-burden countries.
- India DOTS Program Scale:India's government-run Directly Observed Treatment Short-course program generates predictable volume demand for first-line combination tablets under centralized procurement.
- Injectable Manufacturing:Institutional buyers in South Africa and Indonesia are consolidating orders for capreomycin and amikacin vials to secure directly observed therapy compliance.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:China and India control over 80% of rifampin and pyrazinamide API supply, creating single-source vulnerability for European formulators.
- EMA Clinical Trial Guidance:EMA's stringent endpoint requirements for tuberculosis trials extend development timelines and inflate patient recruitment costs for novel agents.
- Biosimilar Substitution Pressure:Off-patent first-line regimens face price erosion from domestic manufacturers in Brazil and Russia, compressing margins for originator portfolios.
Strategic Opportunities
- Immunocompromised Patient Expansion:HIV co-infection and biologic immunosuppression in the United States and Western Europe are expanding the addressable population for nontuberculous mycobacterial therapies.
- CDSCO Accelerated Approval:India's CDSCO fast-track pathway for anti-TB agents reduces time-to-market for novel combinations targeting multidrug-resistant strains.
- Point-of-Care Diagnostics Convergence:Integration of GeneXpert molecular testing with treatment initiation protocols in Kenya and Philippines is compressing diagnostic-treatment gaps and expanding regimen capture.
Industry Challenges
- Pharmacovigilance Infrastructure:Post-market surveillance for hepatotoxicity and QT prolongation requires dedicated safety databases that strain mid-cap manufacturers' regulatory affairs capacity.
- Cold Chain Integrity:Bedaquiline and delamanid distribution in Nigeria and Pakistan demands validated 2-8°C logistics that national immunization programs struggle to extend.
- Patent Thicket Navigation:Fixed-dose combination formulations trigger complex licensing negotiations across multiple rifamycin derivative patent estates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antimycobacterial Drugs Market |
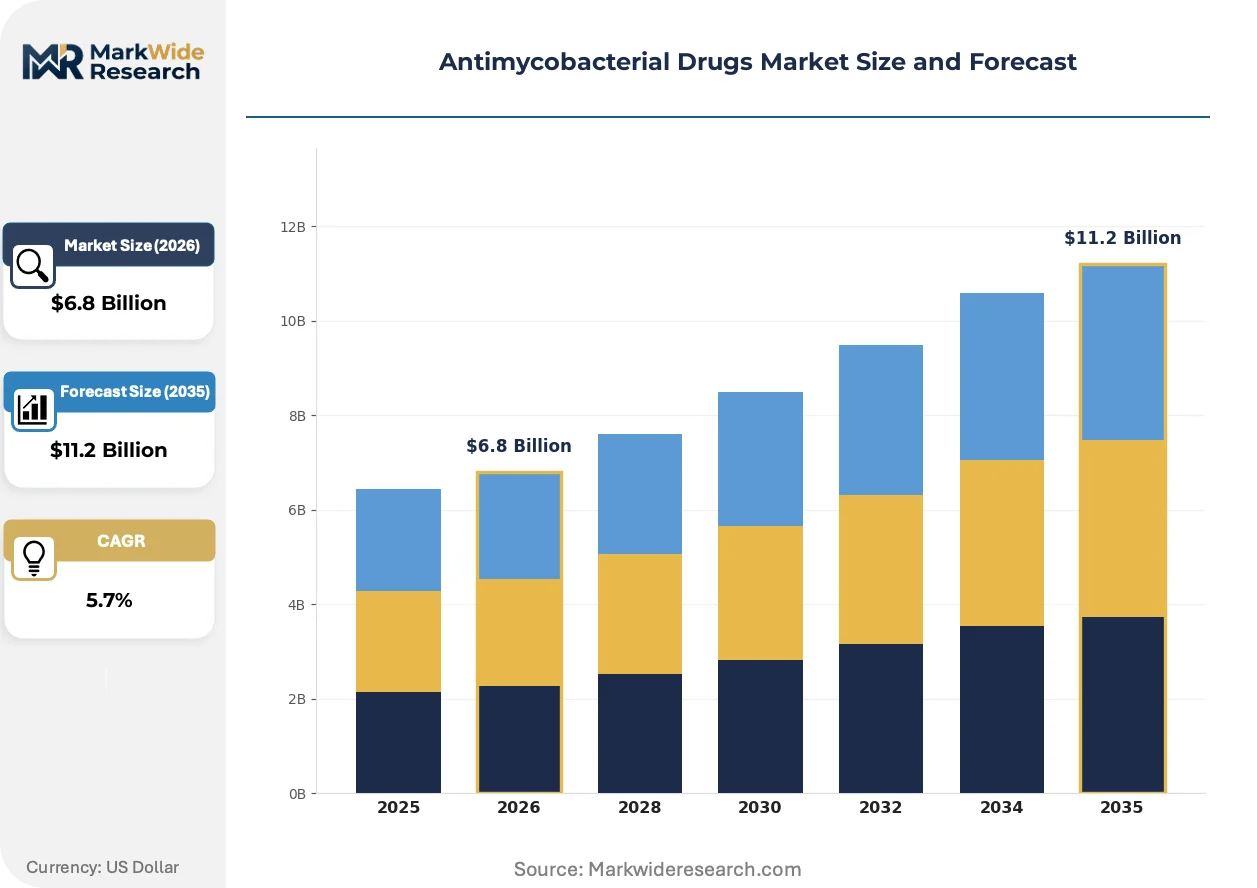
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Rifampin, Isoniazid, Pyrazinamide, Ethambutol Delivery Mode: Oral, Injectable, Topical, Inhalation Patient Type: Adults, Children, Immunocompromised, Pregnant Women Treatment Setting: Hospitals, Outpatient Clinics, Home Care, Specialty Pharmacies |
| Companies Covered | Pfizer, Sanofi, Novartis, Merck & Co., GlaxoSmithKline, Lupin, Macleods Pharmaceuticals, Johnson & Johnson, Otsuka, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antimycobacterial Drugs Market Strategic Shifts
Antimycobacterial development is pivoting toward shorter oral regimens and companion diagnostics that compress treatment duration while preserving efficacy against evolving resistance patterns.
All-oral bedaquiline-pretomanid-linezolid regimens are consolidating clinical practice for multidrug-resistant tuberculosis by eliminating injectable requirements and reducing hospitalization duration. National tuberculosis programs in South Africa and Bangladesh are adopting these protocols at accelerated pace. The shift is consolidating procurement around oral solid dosage forms and displacing legacy injectable tenders.
EMA's clinical trial guidance on tuberculosis endpoints is reshaping Phase III design by mandating culture conversion at 8 weeks as a primary efficacy measure. Sponsors must now power studies for noninferiority against standard-of-care rather than superiority, altering sample size calculations and site selection. European developers are responding by partnering with high-incidence country investigators to meet enrollment targets.
Institutional buyers are consolidating supplier relationships through multi-year framework agreements that bundle diagnostics, drugs, and adherence monitoring. Hospital procurement departments in India and Indonesia are displacing spot purchasing with centralized tendering that awards volume commitments to prequalified manufacturers. This concentration is most visible in Maharashtra state and Jakarta province, where state-level tuberculosis control societies negotiate directly with three to four approved suppliers.
Antimycobacterial Drugs Market Segmentation
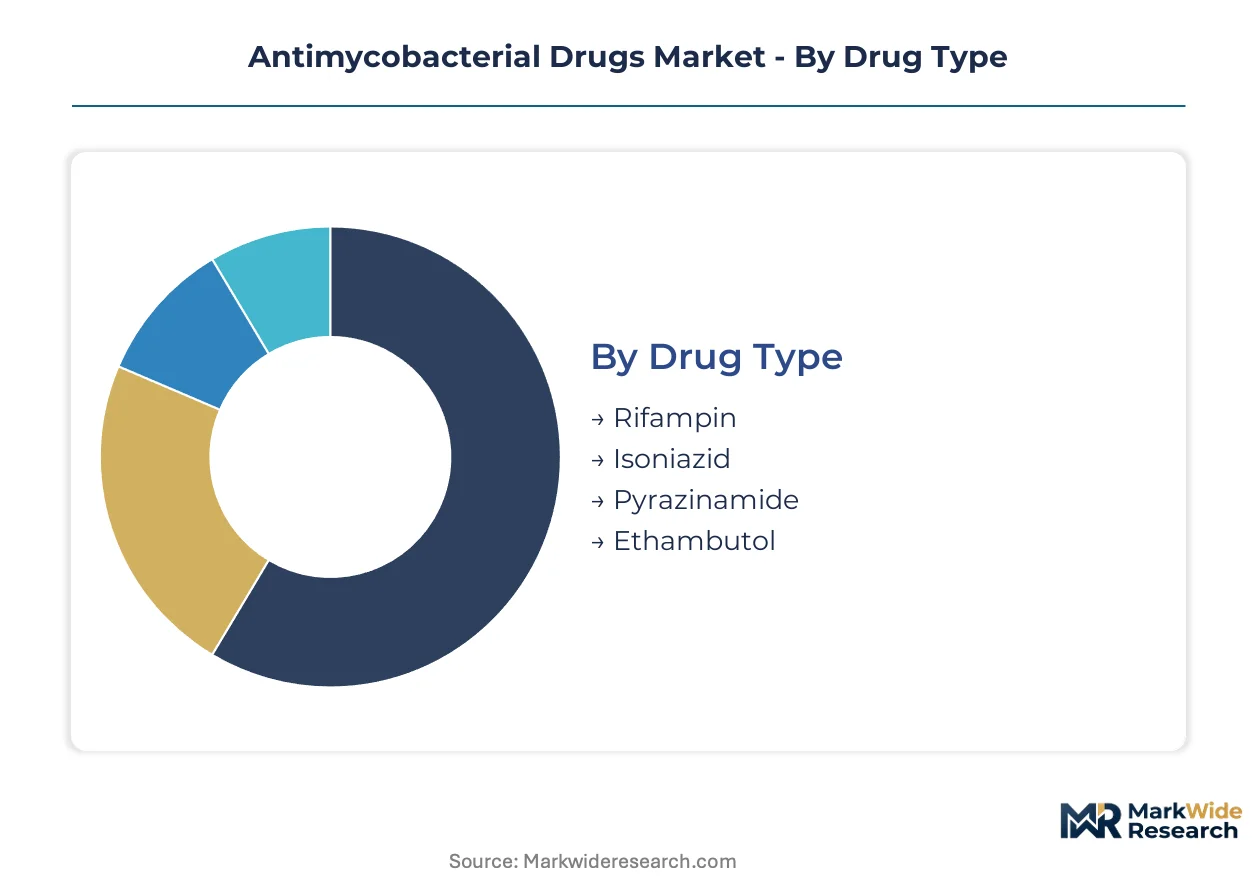
Antimycobacterial drug manufacturers align portfolio investments with distinct patient risk profiles and procurement channels. Segmentation reveals where formulation complexity commands premium positioning versus where cost-engineered scale dominates tender economics.
Drug Type:
The standardization spectrum runs from single-agent commodity APIs to precision-engineered combination tablets with defined bioequivalence windows.
- Rifampin:Semisynthetic ansamycin derivative that inhibits DNA-dependent RNA polymerase in Mycobacterium tuberculosis. Demand concentrates in India's government DOTS program procurement, where BIS-mandated quality specifications filter out substandard suppliers.
- Isoniazid:First-line synthetic hydrazide that disrupts mycolic acid synthesis through InhA enzyme inhibition. Hospital formularies in South Africa and Indonesia specify this agent for directly observed therapy protocols, driving volume through institutional procurement frameworks.
- Pyrazinamide:Pyrazine analogue prodrug activated by mycobacterial pyrazinamidase.
- Ethambutol:Synthetic ethylenediamine derivative targeting arabinosyl transferase in cell wall assembly.
Most installed capacity flows through rifampin. Expansion is steepest in pyrazinamide as shorter-course regimens gain protocol adoption.
Delivery Mode:
Route selection trades patient compliance convenience against the cold chain and clinical supervision requirements that institutional buyers must absorb.
- Oral:Fixed-dose combination tablets and single-agent capsules dominate first-line tuberculosis protocols across high-burden countries. India's centralized state procurement in Maharashtra and Uttar Pradesh channels volume through prequalified manufacturers meeting CDSCO stability specifications.
- Injectable:Capreomycin and amikacin vials for multidrug-resistant cases require healthcare worker administration in directly observed therapy settings. South Africa's provincial health departments consolidate tenders for these products to secure supply security against resistant strain surges.
- Topical:Limited to cutaneous nontuberculous mycobacterial infections with localized lesion presentation.
- Inhalation:Investigational dry powder and nebulized formulations targeting pulmonary disease with reduced systemic exposure.
Oral solid dosage forms capture the dominant procurement share. Injectable formats are gaining share fastest as bedaquiline access programs displace legacy second-line regimens.
Patient Type:
Risk stratification drives divergence between mass treatment programs and specialized therapeutic protocols requiring enhanced safety monitoring.
- Adults:Standard-weight band dosing protocols support national tuberculosis program scale across endemic regions. WHO prequalification status determines eligibility for Global Fund financing in Kenya and Philippines procurement cycles.
- Children:Weight-based fractionated dosing and palatable dispersible formulations address pharmacokinetic variability in pediatric populations. India's RNTCP program generates predictable demand for child-friendly fixed-dose combinations.
- Immunocompromised:HIV co-infection and biologic immunosuppression expand the addressable population for nontuberculous mycobacterial therapies in the United States and Western Europe. Drug-drug interaction management with antiretroviral regimens requires specialized clinical pharmacy oversight.
- Pregnant Women:Risk-benefit reassessment of hepatotoxic agents shapes trimester-specific prescribing patterns.
Adult patient protocols absorb most manufacturing capacity. Immunocompromised segments are climbing the fastest as biologic immunosuppression prevalence rises.
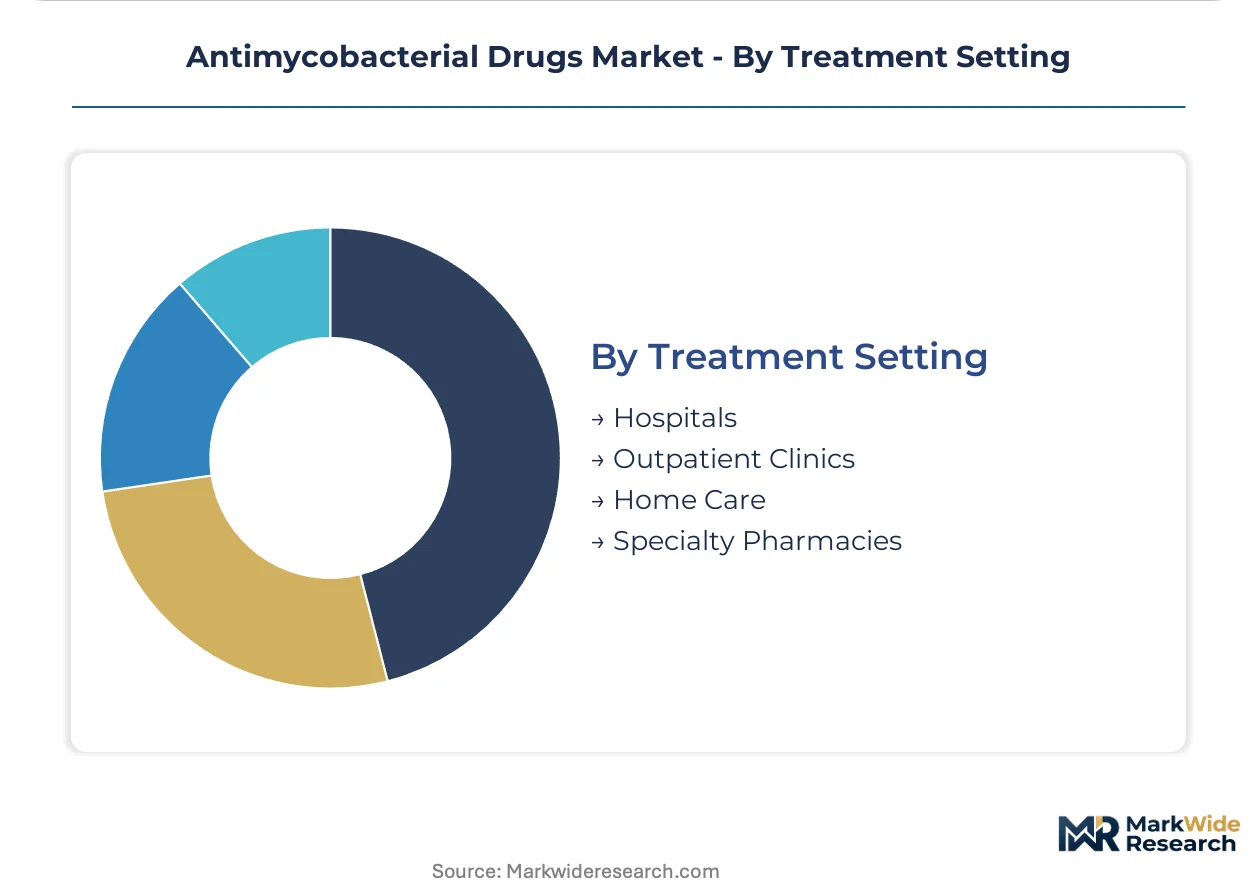
Treatment Setting:
Channel selection reflects the institutional capability to manage adverse event surveillance and medication adherence verification.
- Hospitals:Inpatient departments manage multidrug-resistant tuberculosis initiation and severe adverse event stabilization. Indonesia's Jakarta province consolidates procurement through provincial tuberculosis control societies negotiating multi-year framework agreements.
- Outpatient Clinics:Primary health centers administer directly observed therapy for drug-susceptible cases under national program protocols. Bangladesh's network of DOTS centers channels first-line regimen demand through centralized tendering.
- Home Care:Family-member observed therapy and community health worker support extend treatment access to rural and remote populations.
- Specialty Pharmacies:Limited distribution networks manage bedaquiline and delamanid dispensing with mandatory adverse event reporting to pharmacovigilance databases.
Hospital and outpatient clinic procurement together dominate institutional purchasing. Home care channels are expanding most quickly as community-based treatment models gain protocol endorsement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost-of-compliance gaps are redistributing antimycobacterial manufacturing capacity toward jurisdictions with streamlined API oversight and government-backed procurement scale. Formulators migrate production to exploit divergence between EMA trial endpoint requirements and accelerated approval pathways in high-burden endemic markets.
India
Maharashtra and Gujarat absorb the bulk of rifampin and pyrazinamide API manufacturing, supplying domestic DOTS program demand and export markets. CDSCO's accelerated approval track for anti-TB agents compresses time-to-market for novel combinations. Mumbai's pharmaceutical cluster houses formulators serving both India's RNTCP and WHO prequalification pipelines.
South Africa
Provincial health departments in Gauteng and KwaZulu-Natal consolidate tenders for second-line injectables as multidrug-resistant strain surveillance intensifies. The national tuberculosis control program mandates directly observed therapy compliance through centralized procurement frameworks. Cape Town's clinical trial infrastructure supports Phase III enrollment for shortened oral regimens.
United States
HIV co-infection and biologic immunosuppression expand the addressable population for nontuberculous mycobacterial therapies in urban hospital systems. FDA priority review vouchers for anti-infectives reshape manufacturer incentives toward novel mechanism agents. Boston's academic medical centers anchor pharmacovigilance databases tracking hepatotoxicity and QT prolongation signals.
Indonesia
Jakarta province negotiates multi-year framework agreements bundling diagnostics, drugs, and adherence monitoring through provincial tuberculosis control societies. The national health insurance scheme channels first-line regimen demand toward prequalified domestic suppliers. Surabaya's manufacturing base produces fixed-dose combinations meeting BIS-equivalent stability specifications.
Germany
EMA's stringent endpoint requirements for tuberculosis trials extend development timelines for sponsors targeting European market authorization. Frankfurt's regulatory consultancy cluster supports noninferiority study design against standard-of-care protocols. Bavaria's chemical manufacturing base supplies specialized excipients for heat-stable oral solid dosage forms.
Antimycobacterial Drugs Market Competitive Environment
Capacity expansion dominates the current landscape as manufacturers revalidate supply chains for second-line injectables and oral fixed-dose combinations across endemic regions. The market structure consolidates around three tiers: originator multinationals with bedaquiline access programs, mid-cap formulators competing on DOTS program tenders, and domestic API producers controlling rifamycin derivative supply. Strategic archetypes include WHO prequalification specialists, government contract aggregators, and cold chain logistics integrators. Vertical integration into API production and diagnostic-drug bundling represent the dominant competitive moves.
Within the originator tier, Johnson & Johnson and Pfizer exemplify divergent positioning strategies. Johnson & Johnson anchors access program architecture in high-burden settings through bedaquiline distribution. Pfizer occupies the institutional procurement vector by leveraging injectable manufacturing scale for capreomycin and amikacin vial supply. Among mid-cap formulators, Lupin represents the cost-engineered oral combination archetype, competing on national program tender economics in India and Southeast Asia.
| Leading Market Players |
|---|
| Pfizer |
| Sanofi |
| Novartis |
| Merck & Co. |
| GlaxoSmithKline |
| Lupin |
| Macleods Pharmaceuticals |
| Johnson & Johnson |
| Otsuka |
| Others |
Value Chain & Pricing Dynamics
WHO prequalification status versus domestic tender eligibility creates a sharp bifurcation in both procurement economics and supplier network configuration across endemic markets. Originators with bedaquiline access programs command premium positioning through cold chain infrastructure and pharmacovigilance bundling, while cost-engineered oral combinations compete on volume scale within national DOTS frameworks.
Pricing Analysis
Distributor margin compression runs through first-line rifampin-containing regimens as India's centralized state procurement consolidates volume around three to four prequalified suppliers. Three-tier pricing structure across premium bedaquiline-delamanid regimens, standard second-line injectables, and economy first-line combinations reflects WHO prequalification tier and cold chain capability. Price erosion intensifies in off-patent fixed-dose combinations as domestic manufacturers in Brazil and Russia expand capacity. Government tender buyers exhibit highest price sensitivity; specialty pharmacy channels for limited-distribution novel agents show lowest.
Supply Chain Analysis
Reverse-logistics flows for temperature-exposed bedaquiline and delamanid vials require validated returns protocols that strain national immunization program infrastructure in Nigeria and Pakistan. API manufacturing concentrates in Maharashtra and Gujarat for rifampin, with pyrazinamide feedstock anchored in Shandong province. Supply chain risk centers on single-source vulnerability for ansamycin derivative fermentation capacity. Distribution runs through provincial tuberculosis control societies in Indonesia and South Africa consolidating multi-year framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in antimycobacterial therapeutics rests on backward integration into API production and premium-tier shift toward all-oral multidrug-resistant regimens displacing legacy injectables.
For Market Incumbents: Hedge against biosimilar substitution pressure in first-line DOTS markets by securing captive rifamycin derivative supply through API facility investments in Gujarat or Maharashtra. Prioritize WHO prequalification maintenance for automatic Global Fund eligibility while building pharmacovigilance databases to support novel combination labeling extensions. For New Entrants and Emerging Players: Point-of-care diagnostic integration with treatment initiation protocols offers entry into Kenya and Philippines procurement cycles where GeneXpert convergence compresses diagnostic-treatment gaps. Target immunocompromised nontuberculous mycobacterial segments in United States urban hospital systems through specialty pharmacy limited-distribution partnerships with mandatory adverse event reporting infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap formulators possessing CDSCO accelerated approval track records and established Maharashtra state tender relationships. Long-term viability over the projection horizon favors suppliers with demonstrated cold chain validation for bedaquiline distribution. Monitor EMA clinical trial guidance revisions on tuberculosis endpoints as inflection indicator for European market authorization feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Achievement | Unlocks automatic Global Fund and national program tender eligibility across high-burden endemic markets. |
| API Backward Integration | Captures rifampin and pyrazinamide margin compression while securing supply against single-source disruption. |
| All-Oral Regimen Development | Displaces injectable requirements in South Africa and Bangladesh national protocols, consolidating procurement share. |
| Diagnostic-Drug Bundling | Aligns with Indonesia and Maharashtra state framework agreements consolidating supplier relationships. |
| Pharmacovigilance Infrastructure Buildout | Enables bedaquiline and delamanid limited-distribution networks with mandatory FDA and EMA adverse event reporting. |
Study Parameters
Direct dialogue with drug development executives, regulatory affairs leads at CDSCO and FDA, hospital procurement managers in Maharashtra and Jakarta, and formulary directors at South African provincial health departments grounded qualitative assessment. Secondary validation drew from FDA priority review voucher filings, EMA clinical trial guidance documents, WHO prequalification product lists, and Global Fund tender archives. Bottom-up patient population modeling and top-down procurement spend analysis triangulated market sizing.
Segmented outputs across drug type, delivery mode, patient risk profile, and treatment setting informed the analytical framework over the projection horizon. CAGRs derived from regression against DOTS program enrollment trajectories, multidrug-resistant strain surveillance data, and immunocompromised population epidemiology. Forecast inputs incorporated CDSCO accelerated approval pathway utilization rates and EMA noninferiority trial design adoption patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to resistance surveillance data revisions and regulatory exclusivity timeline shifts. Practitioners should monitor WHO prequalification pipeline additions and EMA endpoint guidance amendments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Gosling Plague Vaccine Market
Biopharmaceuticals
India Insulin Drug and Delivery Device Market
Biopharmaceuticals
Next Generation Antibody Therapeutics Market
Biopharmaceuticals
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market
Biopharmaceuticals
Global Cytokine Market
Biopharmaceuticals
Global Breast Cancer Drugs Market
Biopharmaceuticals
North America Monoclonal Antibody Market
Biopharmaceuticals
Human Chorionic Gonadotropin Market
Biopharmaceuticals
Global Vaccine Conjugate Market
Biopharmaceuticals
Global Bioengineered Protein Drugs Market
Biopharmaceuticals
Phenylketonuria (PKU) Market
Biopharmaceuticals
US Generic Injectables Market
Biopharmaceuticals
Global Actinic Keratosis Drugs Market
Biopharmaceuticals
Influenza Vaccine Market
Biopharmaceuticals
Plasma Protease C1-Inhibitor Market
Biopharmaceuticals
Laband Syndrome Therapeutics Market