
 Russia Insulin Drugs and Delivery Devices Market | 2026-2036
Russia Insulin Drugs and Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Insulin Drugs and Delivery Devices Market Analytics
Import substitution mandates from the Russian Ministry of Health are rebalancing the cost-of-entry calculus for foreign insulin manufacturers. Novo Nordisk navigates these barriers through established local partnerships and manufacturing scale. Geropharm anchors domestic supply with backward integration into active pharmaceutical ingredient production. Eli Lilly competes via specialized biologics expertise and differentiated rapid-acting analog portfolios.
Insulin drugs and delivery devices comprise recombinant human insulin and insulin analog formulations packaged with mechanical or electronic injection systems, typically requiring cold-chain storage at two to eight degrees Celsius to preserve protein stability. The primary purpose is glycemic control in type one and type two diabetes mellitus through precise dose administration. Insulin pens dominate volume due to patient convenience and dosing accuracy, while smart devices represent the fastest-growing form factor segment driven by connected dose tracking and Bluetooth-enabled glucose integration. Subcutaneous delivery sustains the largest share of drug delivery methods, though inhalation routes attract development interest for needle-averse patient populations.
Russia's national pharmaceutical regulator, the Ministry of Health, and the Eurasian Economic Union's harmonized technical regulations collectively shape product registration, GMP certification requirements, and pricing controls for insulin therapies. BIS-equivalent national standards and the EAEU's common pharmaceutical market rules determine import eligibility and local manufacturing incentives. Stakeholders must monitor evolving reimbursement list revisions and domestic production quotas that determine market access trajectories.
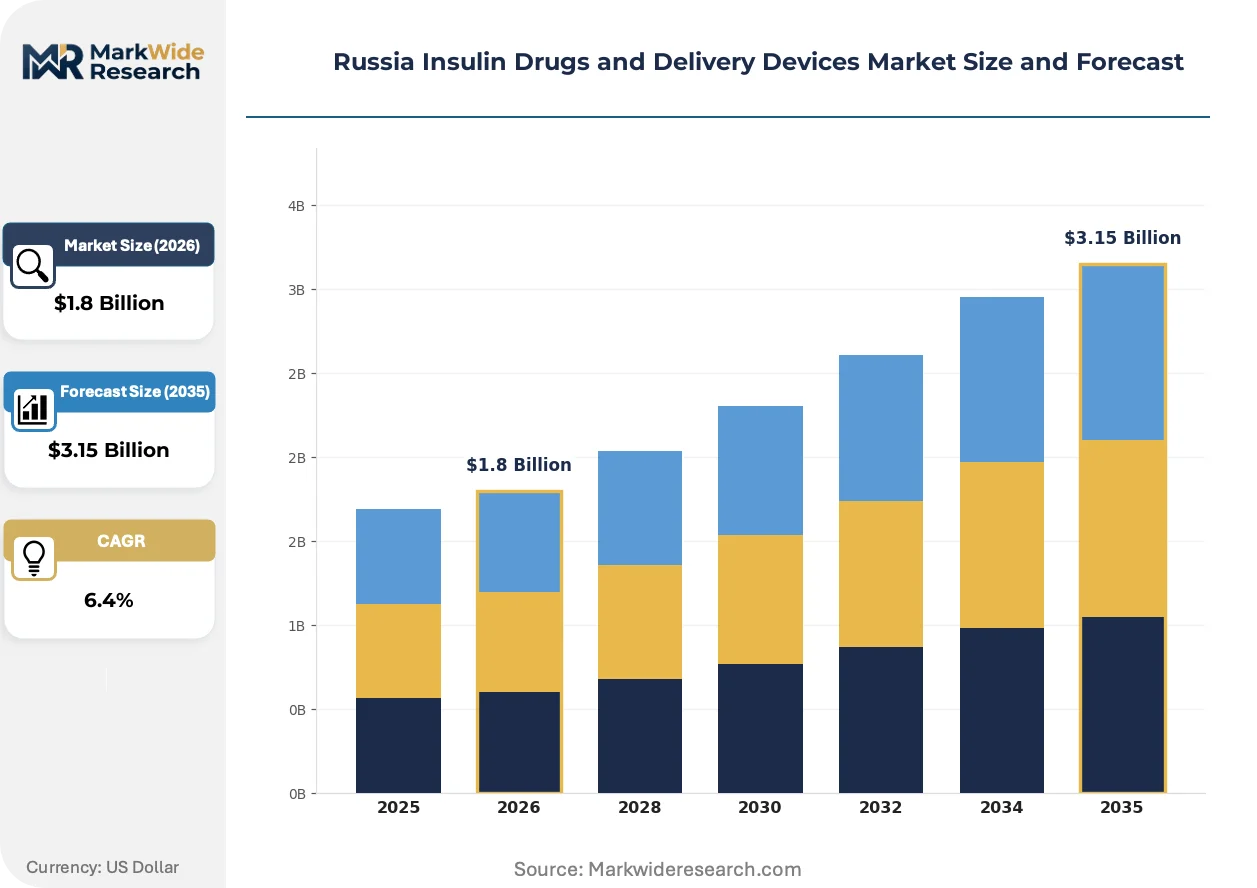
Market Dynamics
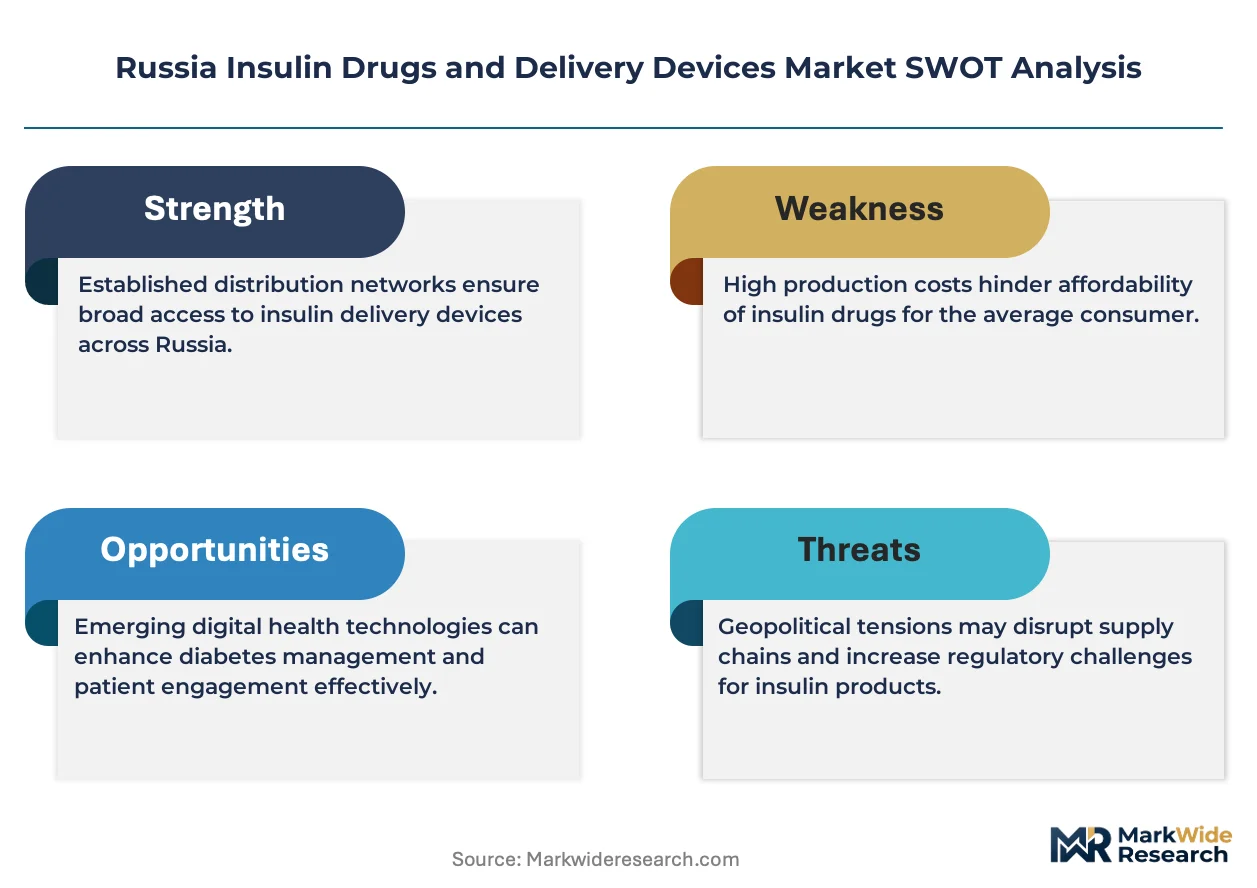
Import substitution mandates from the Ministry of Health are forcing foreign insulin manufacturers to restructure local manufacturing partnerships or exit procurement tenders entirely, while domestic producers capture volume through backward integration into active pharmaceutical ingredient synthesis.
Growth Catalysts
- Moscow-Saint Petersburg demand concentration:Specialized endocrinology centers in these two metropolitan clusters generate disproportionate prescription volume and anchor regional reimbursement negotiations.
- Homecare provider expansion:Outpatient diabetes management programs are accelerating insulin pen adoption over traditional vial-and-syringe methods for patient convenience.
- Eurasian Economic Union harmonization:Common pharmaceutical market rules streamline registration across member states and reduce duplicate certification burdens for compliant manufacturers.
Market Restraints
- Import substitution procurement quotas:Ministry of Health mandates reserve increasing tender share for domestic producers, constraining foreign manufacturer market access regardless of price competitiveness.
- Cold-chain infrastructure gaps:Temperature-controlled distribution networks remain underdeveloped outside major urban corridors, threatening protein stability during last-mile delivery.
- Biologics manufacturing complexity:Recombinant insulin production requires specialized fermentation capacity and GMP-certified facilities that concentrate among limited domestic suppliers.
Strategic Opportunities
- Smart connected devices:Bluetooth-enabled insulin pens with integrated dose logging represent unpenetrated white space as patient data integration becomes reimbursable.
- Siberian and Far Eastern regions:Underserved patient populations in these federal districts present expansion potential for telemedicine-integrated diabetes management programs.
- Inhalation delivery development:Needle-averse patient segments are driving clinical interest in non-invasive insulin administration routes currently absent from commercial portfolios.
Industry Challenges
- Bioprocess engineering talent scarcity:Domestic manufacturers face recruitment constraints for fermentation specialists and biologics quality control personnel with EAEU GMP certification experience.
- Reimbursement list revision timelines:Ministry of Health formulary updates operate on unpredictable schedules, complicating launch planning and inventory commitments for new formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Insulin Drugs and Delivery Devices Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Syringes, Insulin Pens, Insulin Pumps, Inhalers Form Factor: Disposable, Reusable, Smart Devices, Conventional Drug Delivery Method: Subcutaneous, Intravenous, Inhalation, Transdermal End User: Hospitals, Clinics, Homecare Providers, Pharmacies |
| Companies Covered | Pharmstandart, Eli Lilly, Sanofi, Becton Dickinson, Medtronic, Novo Nordisk, Medsintez, Ypsomed, Geropharm, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Insulin Drugs and Delivery Devices Market Evolving Landscape
Device connectivity and data integration are reshaping competitive differentiation in insulin delivery, moving the basis of competition from mechanical reliability toward digital health ecosystem participation and patient outcome documentation.
Smart insulin pens with embedded dose sensors and Bluetooth transmission are overtaking conventional mechanical devices in premium segments. Endocrinology centers in Moscow are piloting these systems for remote patient monitoring. The technology is compressing differentiation timelines for legacy manufacturers lacking software development capabilities.
EAEU technical regulations are harmonizing GMP certification requirements across member state borders. This regulatory convergence reduces redundant facility inspections for multi-national producers. Russian manufacturers with EAEU-compliant facilities are capturing tender volume in Kazakhstan and Belarus that previously flowed to European-registered competitors.
Patient self-monitoring data is restructuring prescriber-pharmacy relationships in urban diabetes care. Endocrinologists in Saint Petersburg are prioritizing insulin brands with compatible digital platforms over established clinical preferences. This behavioral shift is most visible in private healthcare channels where reimbursement flexibility permits formulary experimentation.
Russia Insulin Drugs and Delivery Devices Market Segmentation
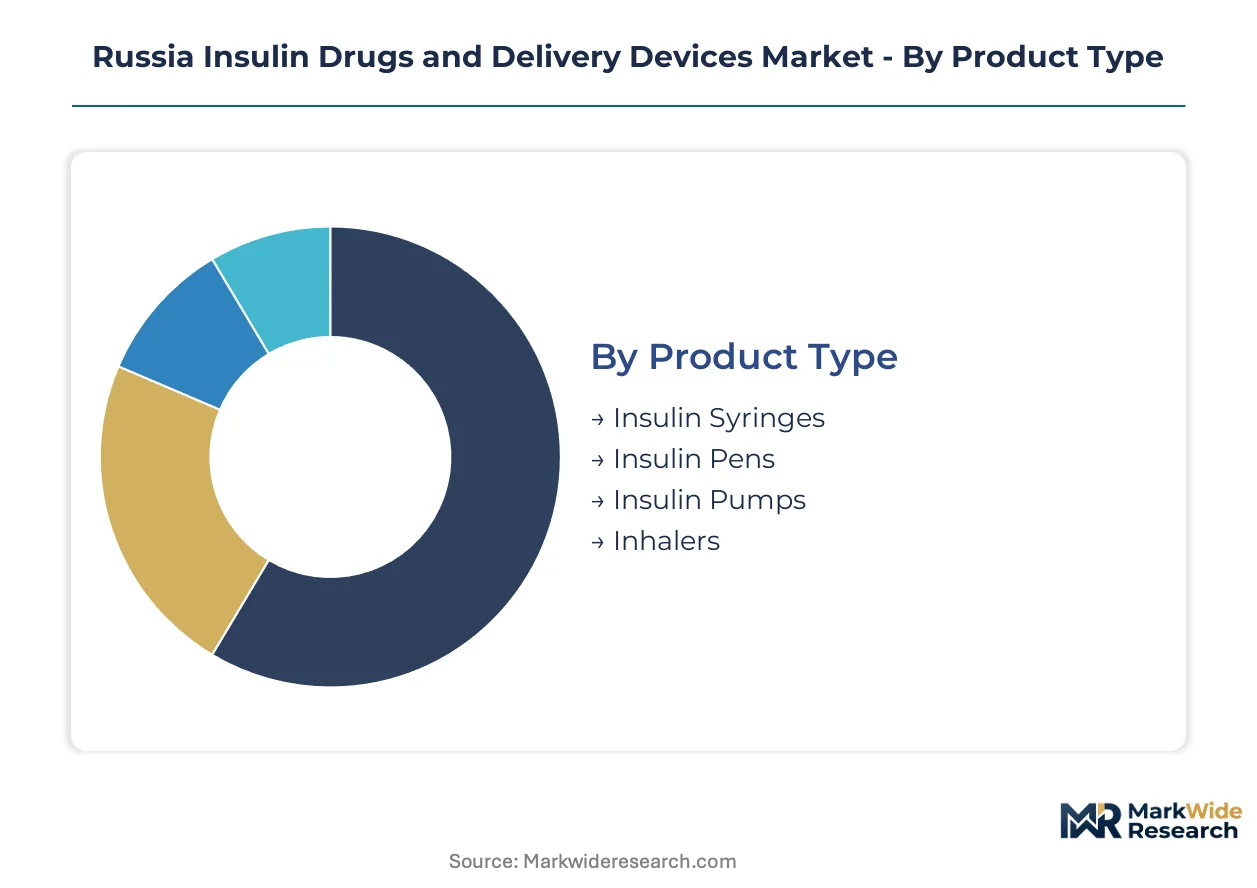
Insulin delivery in Russia fragments across device technologies, reimbursement tiers, and care settings that determine procurement patterns. Understanding these segment boundaries clarifies where domestic manufacturers capture volume versus where foreign competitors retain premium positioning.
Product Type:
Volume deployment concentrates in established mechanical systems, while premium expansion targets electronic and connected delivery platforms.
- Insulin Pens:Pre-filled or cartridge-based devices with integrated dose-dialing mechanisms dominate outpatient prescribing across Moscow and Saint Petersburg endocrinology centers. Homecare providers are accelerating pen adoption over vial-and-syringe methods for patient convenience and dosing accuracy.
- Insulin Syringes:Conventional U-40 and U-100 calibrated syringes retain significant volume in rural districts and budget-constrained procurement tenders. Cold-chain infrastructure gaps outside major urban corridors reinforce syringe persistence where pen refrigeration cannot be guaranteed.
- Insulin Pumps:Continuous subcutaneous infusion devices with programmable basal-bolus algorithms serve type one diabetes patients in specialized regional centers. Reimbursement list restrictions limit pump penetration to specific patient categories with documented glycemic variability.
- Inhalers:Needle-free pulmonary delivery systems remain in clinical development with no commercial availability in the Russian Federation. Patient preference surveys indicate substantial interest among needle-averse populations if regulatory registration and cold-chain requirements can be resolved.
Mature deployment sits with insulin syringes. Newer deployment is concentrated in insulin pens.
Form Factor:
Cost tier differentiation separates single-use disposables from capital-intensive reusable systems, with connectivity emerging as a distinct premium layer.
- Disposable:Single-use pens and syringes eliminate sterilization burden and cross-contamination risk in homecare settings. Ministry of Health procurement quotas favor domestic disposable production for tender participation.
- Reusable:Durable pen bodies with replaceable insulin cartridges reduce per-dose cost for high-volume patients in private healthcare channels. Saint Petersburg specialty clinics are piloting reusable systems with integrated dose logging for remote monitoring programs.
- Smart Devices:Bluetooth-enabled pens with embedded sensors and smartphone connectivity represent the steepest expansion trajectory in premium urban markets. EAEU technical regulation harmonization is streamlining registration pathways for connected devices across member state borders.
- Conventional:Mechanical devices without electronic components dominate state reimbursement channels where acquisition cost determines formulary placement. Geropharm and other domestic manufacturers anchor supply in this tier through backward integration into pen component production.
Standard procurement runs through conventional devices. Smart device adoption is climbing the fastest in private-pay segments.
Drug Delivery Method:
Application context determines method selection, with subcutaneous administration anchoring ambulatory care and alternative routes targeting specific patient constraints.
- Subcutaneous:Abdominal, thigh, or deltoid injection of insulin formulations via pen, syringe, or pump constitutes the standard of care across Russian diabetes management guidelines. This method captures overwhelming volume in both hospital discharge protocols and homecare provider training programs.
- Intravenous:Hospital-based intensive care units and surgical services deploy IV insulin protocols for acute hyperglycemic crises and perioperative glucose management. Specialized endocrinology wards in Moscow maintain IV capability for diabetic ketoacidosis stabilization.
- Inhalation:Pulmonary insulin absorption via dry powder or aerosol devices attracts development interest for patient populations with severe needle phobia or lipohypertrophy complications. No commercial inhalation products are currently registered with the Ministry of Health.
- Transdermal:Iontophoretic or microneedle patch technologies for non-invasive insulin delivery remain preclinical with no active clinical trials in the Russian Federation. Academic research partnerships are exploring transdermal approaches for basal insulin analogs.
Established practice centers on subcutaneous delivery. Development investment is concentrating in inhalation routes.
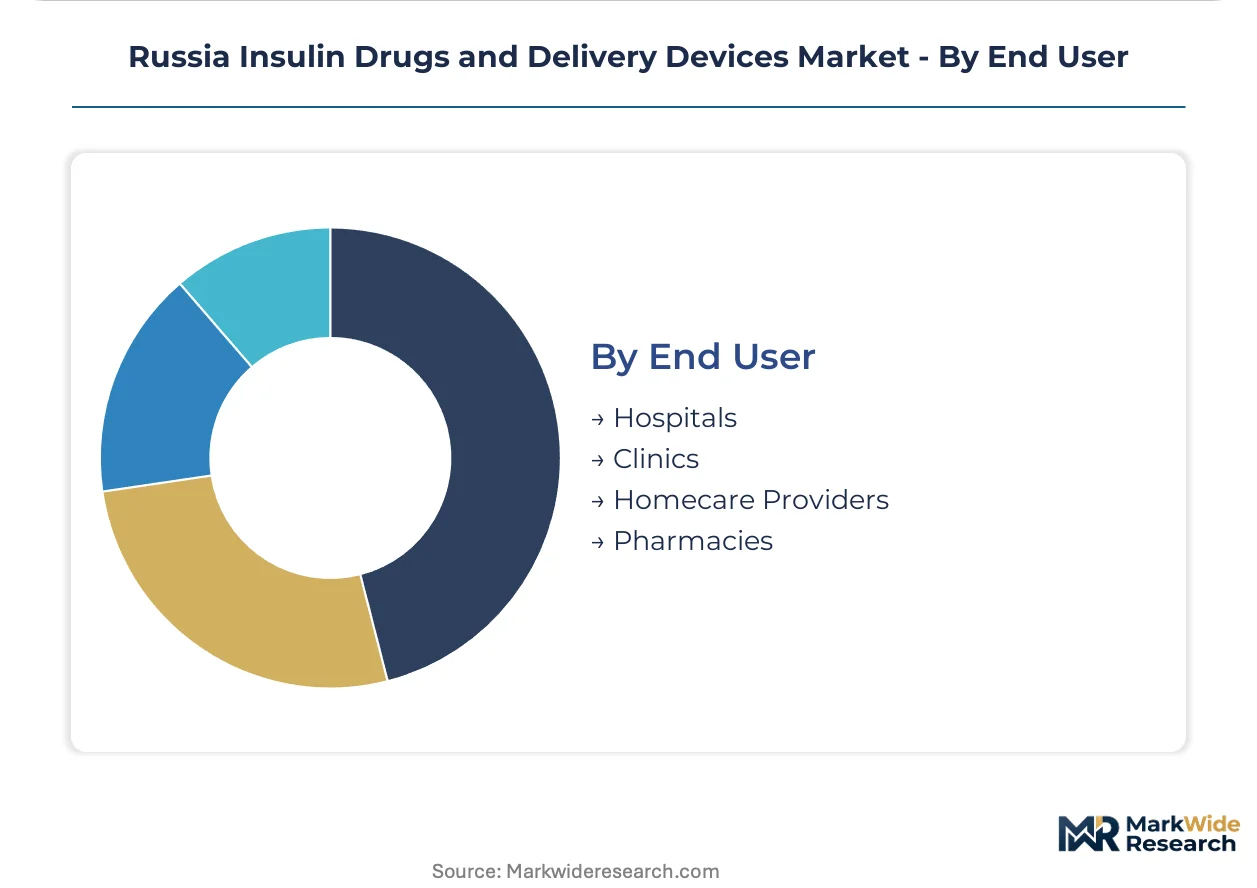
End User:
Customer type segmentation maps to reimbursement channel structure, with institutional procurement operating under distinct pricing and qualification rules versus retail pharmacy distribution.
- Homecare Providers:Outpatient diabetes management programs and visiting nurse services are expanding pen-based insulin delivery for patient self-administration training. These providers negotiate directly with manufacturers for volume contracts outside centralized tender processes.
- Hospitals:Federal and regional inpatient facilities procure insulin through Ministry of Health tenders with mandatory domestic content quotas. Specialized endocrinology hospitals in Moscow anchor high-complexity care and generate disproportionate influence on prescriber preferences.
- Clinics:Polyclinic-based endocrinology departments manage stable type two diabetes patients with formulary constraints tied to regional reimbursement lists. Saint Petersburg municipal clinics are piloting connected pen programs for remote patient monitoring.
- Pharmacies:Retail dispensing channels serve cash-pay patients and supplemental prescriptions outside hospital discharge protocols. Pharmacy chains in major urban centers are expanding cold-chain storage capacity to support analog insulin distribution.
Institutional volume concentrates in hospitals. Patient-directed expansion is gaining share fastest through homecare providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diabetes care demand concentrates in Russia's two dominant metropolitan clusters, while federal districts beyond the Central Federal District present expansion corridors for telemedicine-integrated delivery models. The Ministry of Health's regional procurement quotas create divergent market access conditions across federal subjects. Cold-chain infrastructure maturity varies sharply between established urban corridors and developing territories.
Central Federal District
Moscow anchors prescription volume through specialized endocrinology hospitals and private diabetes management centers. The Ministry of Health maintains centralized tender processes that favor domestic manufacturers meeting import substitution thresholds. Research institutes in the capital pilot connected insulin pen programs for remote patient monitoring.
Northwestern Federal District
Saint Petersburg municipal clinics generate disproportionate influence on prescriber preferences across the wider region. Regional reimbursement lists here permit greater formulary experimentation than federal procurement channels. The city's pharmacy chains are expanding cold-chain storage capacity to support analog insulin distribution.
Siberian Federal District
Underserved patient populations in Novosibirsk and Krasnoyarsk present expansion potential for homecare provider networks. Temperature-controlled distribution networks remain underdeveloped, threatening protein stability during last-mile delivery. Regional health authorities are negotiating direct manufacturer contracts outside centralized tender systems.
Far Eastern Federal District
Vladivostok and Khabarovsk anchor diabetes care capacity in this sparsely served territory. The Eurasian Economic Union's common pharmaceutical market rules enable cross-border supply relationships with neighboring member states. Telemedicine infrastructure investments are accelerating to bridge specialist access gaps.
Volga Federal District
Kazan and Nizhny Novgorod host regional endocrinology centers that anchor procurement influence for surrounding republics and oblasts. Domestic manufacturers with EAEU-compliant facilities capture tender volume through backward integration into active pharmaceutical ingredient production. Federal subject-level procurement autonomy creates pricing variation across the district.
Russia Insulin Drugs and Delivery Devices Market Competitive Landscape
Domestic Russian producers anchor the state procurement tier; Western multinational specialists hold premium positioning in private channels. Market structure reflects bifurcated access: consolidated domestic supply for tender participation versus fragmented international competition for cash-pay segments. Three archetypes dominate—vertically integrated domestic API manufacturers, multinational biologics specialists with local partnerships, and device-focused European suppliers. Competitive moves center on manufacturing joint ventures to satisfy localization mandates and connected device portfolio assembly for private healthcare differentiation.
Within the domestic integrated tier, Geropharm anchors supply through captive active pharmaceutical ingredient production. Among Western biologics specialists, Novo Nordisk and Eli Lilly occupy positions shaped by established local partnerships and differentiated formulation portfolios. European device suppliers including Ypsomed and Becton Dickinson represent the delivery technology vector, with connectivity features driving premium positioning in urban private channels.
| Leading Market Players |
|---|
| Pharmstandart |
| Eli Lilly |
| Sanofi |
| Becton Dickinson |
| Medtronic |
| Novo Nordisk |
| Medsintez |
| Ypsomed |
| Geropharm |
| Others |
Value Network & Pricing Analysis
Domestic-foreign supply bifurcation separates state tender winners from premium private-channel competitors, with Ministry of Health procurement quotas anchoring cost structures for local manufacturers while import substitution mandates force foreign players into joint-venture localization. This divergence concentrates API production within Russian Federation borders for budget-tier insulin, while cold-chain distribution investments determine margin capture for analog formulations in metropolitan retail.
Pricing Analysis
Volume-margin splits separate mechanical disposable pens from connected smart devices, with three-tier pricing structure across premium, standard, and economy levels dominating procurement channels. Price differentiation hinges on GMP certification tier and EAEU compliance status, with domestic producers capturing economy-tier tenders through backward integration into API synthesis. Cost compression in standard-tier vial-and-syringe segments is intensifying because regional health authorities negotiate direct manufacturer contracts outside federal tender systems. Cash-pay patients in Moscow private clinics exhibit lowest price sensitivity for Bluetooth-enabled dose-logging systems.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale institutional demand through Ministry of Health centralized tenders, while retail pharmacy chains serve outpatient prescription volume. Geographic supply concentration centers on Russian Federation domestic fermentation capacity, with API precursor dependencies drawing from India and China for recombinant protein raw materials. Cold-chain infrastructure gaps outside Central and Northwestern Federal Districts create single-source vulnerability for last-mile temperature-controlled delivery. Distribution runs through federal tender aggregators for institutional volume and regional pharmacy distributors for retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's insulin market functions as a cost-of-compliance story where EAEU GMP certification and Ministry of Health localization mandates erect formidable barriers to tender participation, rewarding manufacturers with captive production infrastructure and compliant quality systems.
For Market Incumbents: Anchor tender eligibility through backward integration into active pharmaceutical ingredient fermentation capacity and EAEU-certified manufacturing facilities. Deepen channel control in Siberian and Far Eastern Federal Districts via direct regional health authority contracts that bypass centralized procurement. Defend against smart device displacement by accelerating software development partnerships for connected pen platforms. For New Entrants and Emerging Players: Needle-averse patient segments in private Saint Petersburg and Moscow clinics represent the most penetrable white-space opportunity for differentiated delivery technologies. Homecare provider networks in underserved federal districts offer partnership pathways outside tender-dominated procurement. Pursue reimbursement strategy development for connected dose-logging systems as telemedicine integration becomes eligible for remote patient monitoring codes. For Investors and Strategic Acquirers: Exit pathways concentrate in domestic API manufacturers with EAEU-compliant facilities and established Ministry of Health tender relationships. Long-term viability favors vertically integrated players with captive fermentation capacity across the analysis window. Monitor reimbursement list revision timelines for analog insulin inclusion as the primary inflection signal for premium formulation demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EAEU GMP Certification Investment | Unlocks tender participation across Russian Federation, Kazakhstan, and Belarus procurement channels. |
| Connected Device Platform Development | Captures premium private-pay segments in Moscow endocrinology centers piloting remote monitoring. |
| Regional Distribution Partnership | Bridges cold-chain gaps in Siberian and Far Eastern Federal Districts for analog insulin stability. |
| API Fermentation Capacity Expansion | Satisfies Ministry of Health localization thresholds for state procurement quota eligibility. |
| Telemedicine Integration Program | Aligns with homecare provider expansion for outpatient diabetes management reimbursement. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across endocrinology department heads, hospital procurement managers, pharmaceutical regulatory affairs leads, and homecare provider network directors. Ministry of Health tender documentation, EAEU technical regulation databases, and regional health authority procurement disclosures supplied quantitative foundations. Bottom-up patient population estimates and top-down pharmaceutical market sizing were reconciled through iterative triangulation.
Data-stream reconciliation across volume prescriptions, device shipment records, and reimbursement claim patterns informed the analytical framework. Segmentation dimensions modeled include product type, form factor connectivity tier, drug delivery method, and end-user procurement channel across the projection horizon. CAGRs were derived from patient prevalence projections, analog insulin adoption curves, and connected device penetration assumptions. Forecast inputs incorporated cold-chain infrastructure development timelines and EAEU harmonization implementation progress.
Revisions become necessary when Ministry of Health reimbursement list revisions, EAEU regulatory amendments, or domestic API production capacity expansions materialize outside modeled trajectories. Forecasts reflect assumptions regarding import substitution mandate enforcement consistency and telemedicine reimbursement policy evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Amphotericin B Market
Biopharmaceuticals
Mammalian Derived Proteins Market
Biopharmaceuticals
Global Bovine Blood Plasma Derivatives Market
Biopharmaceuticals
Plasma Protease C1-Inhibitor Market
Biopharmaceuticals
Global Human Recombinant Insulin Market
Biopharmaceuticals
Gosling Plague Vaccine Market
Biopharmaceuticals
Global Biopharmaceuticals Market
Biopharmaceuticals
Global Interferons Market
Biopharmaceuticals
Generic Oncology Drugs Market
Biopharmaceuticals
Anti-Neprilysin Market
Biopharmaceuticals
Triptorelin Market
Biopharmaceuticals
Bio-Identical Hormones Replacement Therapy Market
Biopharmaceuticals
Anti-Inflammatory Cytokines Market
Biopharmaceuticals
Antibody Drug Conjugates Market
Biopharmaceuticals
Tuberculosis Biomarkers Market
Biopharmaceuticals
Human Chorionic Gonadotropin Market