
 Global Cytokine Market | 2026-2036
Global Cytokine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cytokine Market Foresight
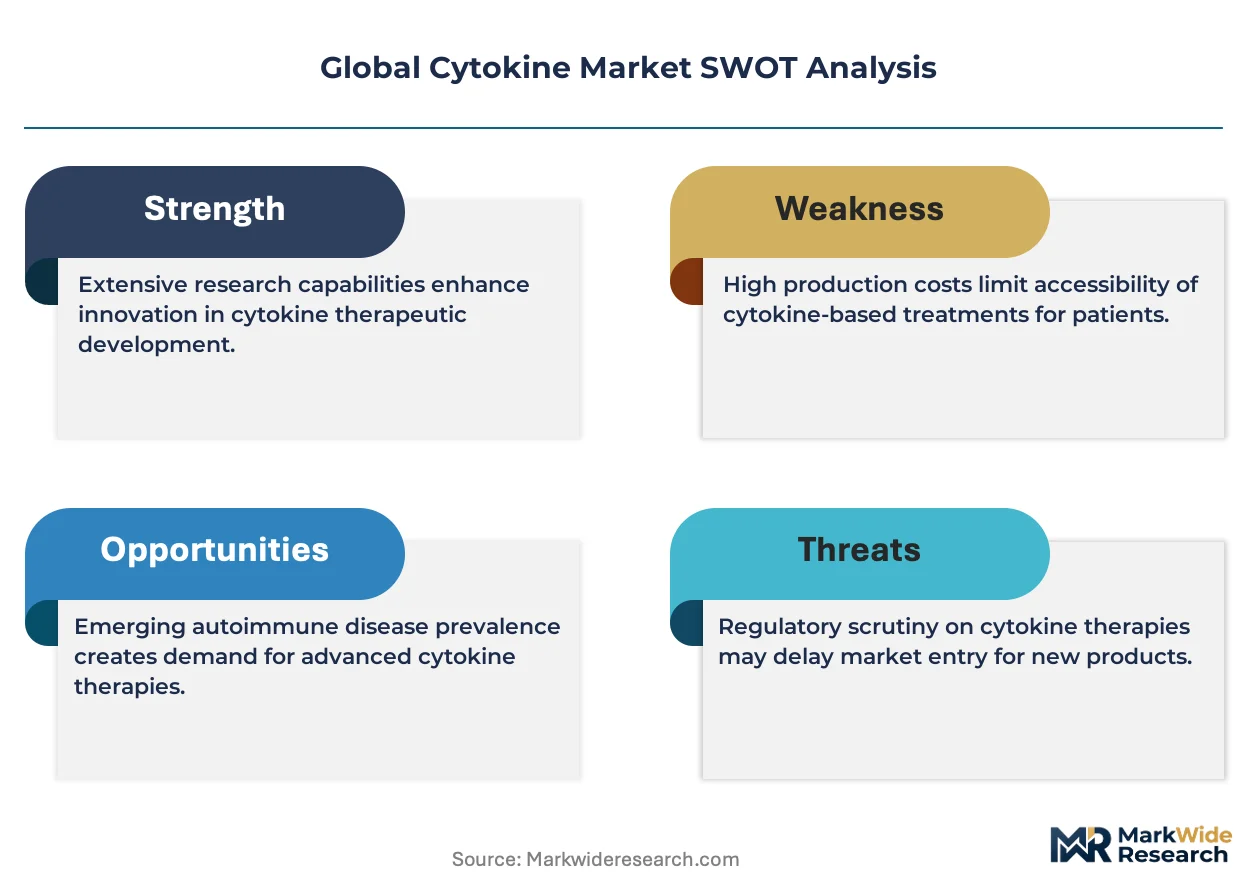
Capital-intensity divergence between GMP bioreactor capacity and discovery-stage platforms is bifurcating competitive tiers. Amgen Inc. leverages decades of large-scale protein manufacturing infrastructure to sustain cost advantages in recombinant cytokine supply. Bio-Techne Corporation specializes in high-purity research-grade cytokines, occupying a differentiated position among academic and preclinical end users. F. Hoffmann-La Roche AG navigates the transition from blockbuster interferon portfolios toward next-generation interleukin modulators.
Cytokines comprise a family of low-molecular-weight signaling proteins, typically glycosylated polypeptides under 30 kDa, secreted by immune and stromal cells to mediate intercellular communication through specific membrane receptors. Recombinant expression in engineered CHO or E. coli systems remains the dominant manufacturing modality for commercial supply. Interleukins command the largest revenue pool among product types due to expanding immuno-oncology protocols, while nanoparticle delivery technology represents the fastest-growing technology segment as developers seek improved pharmacokinetics and reduced systemic toxicity. Contract research organizations constitute an increasingly concentrated end-user channel for custom cytokine production and bioassay services.
FDA biologics license application requirements, EMA's Good Manufacturing Practice Annex 2 guidelines for biological active substances, and Japan PMDA's regenerative medicine product framework collectively elevate compliance burdens for market entry. These standards shape demand toward suppliers with validated quality management systems and documented viral clearance protocols. Stakeholders must monitor evolving biosimilar interchangeability designations and cell-and-gene therapy co-development partnerships that will redefine sourcing strategies for clinical-grade cytokine inputs.
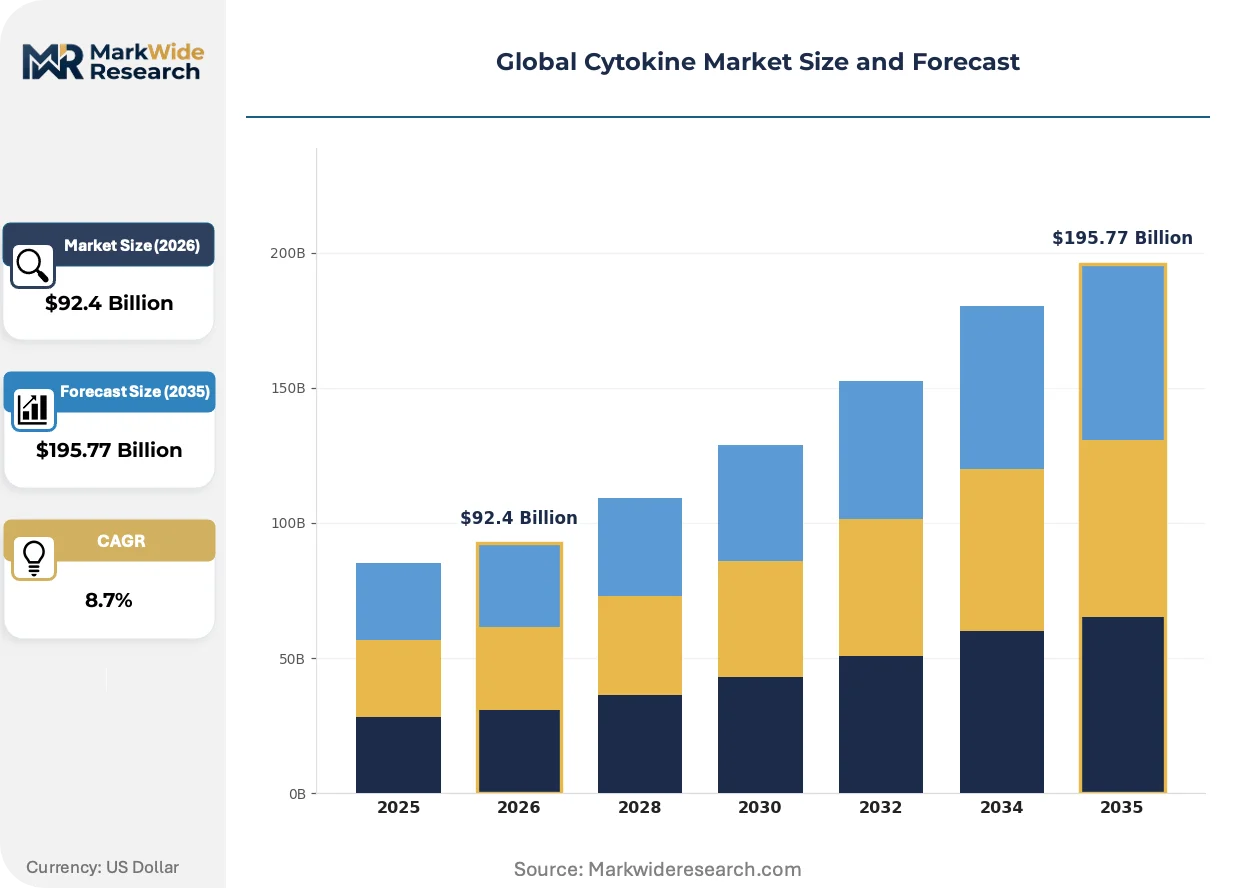
Market Dynamics
Accelerated approval pathways for biologics are compressing development timelines and forcing suppliers to pre-position GMP capacity before Phase II data readouts, creating a structural mismatch between clinical demand and validated manufacturing slots.
Growth Catalysts
- FDA Breakthrough Therapy designation:Compressed review timelines for immuno-oncology cytokine candidates pull forward commercial manufacturing commitments from sponsors.
- Cell therapy expansion:CAR-T and TIL protocols consume clinical-grade interleukins at scale, converting research-grade suppliers into GMP contract manufacturers.
- Germany's EMA centralized procedures:Single marketing authorization enables pan-European distribution, concentrating demand on suppliers with EU QP-release capabilities.
Market Restraints
- Protein A resin cost volatility:Chromatography media represents 15-20% of downstream COGS for recombinant cytokines, with spot pricing sensitive to agarose supply interruptions.
- CHO cell line concentration:Three dominant licensable expression platforms control access to high-titer production, constraining bargaining power for emerging developers.
- Viral clearance validation:FDA and EMA require documented clearance for four model viruses, adding 12-18 months to facility qualification timelines.
Strategic Opportunities
- India's CDSCO fast-track pathway:Local clinical trial waivers for approved US/EU biologics enable rapid market entry for biosimilar interleukins.
- Japan PMDA regenerative medicine framework:Conditional approval routes for combination cell-cytokine products reward early GMP investment with accelerated revenue.
- Continuous bioprocessing convergence:Integrated perfusion chromatography systems enable 40% footprint reduction, unlocking brownfield site conversions in high-cost geographies.
Industry Challenges
- Bioprocess engineer scarcity:GMP facility design and tech transfer expertise concentrates among professionals with 10+ years of mammalian cell culture experience.
- Legacy ERP integration:Paper-based batch records in established CMOs resist electronic system migration, complicating real-time supply chain visibility for sponsors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cytokine Market |
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $195.77 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interleukins, Interferons, Tumor Necrosis Factors, Growth Factors, Chemokines Application: Immunotherapy, Infectious Disease, Autoimmune Disorders, Cancer Research, Tissue Regeneration End User: Biopharmaceutical Companies, Research Institutes, Diagnostic Laboratories, Contract Research Organizations Delivery Technology: Recombinant Expression, Monoclonal Antibody-Based, Protein Engineering, Nanoparticle Delivery |
| Companies Covered | AbbVie Inc., Amgen Inc., F. Hoffmann-La Roche AG, Novartis AG, Johnson & Johnson, Pfizer Inc., Sanofi SA, Bio-Techne Corporation, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cytokine Market Shifts & Advancements
Modular facility architectures and disposable manufacturing technologies are decomposing the traditional capital barrier between research-scale and commercial supply, enabling mid-cap developers to retain control over critical cytokine inputs.
Site-specific PEGylation and Fc-fusion engineering is decomposing the historical trade-off between cytokine potency and half-life extension. Immuno-oncology developers at Phase I/II stage now specify modified interleukin-2 variants in 60% of new INDs. This molecular diversification fragments demand across dozens of custom constructs, compressing batch sizes and favoring flexible single-use bioreactor platforms over stainless steel trains.
EMA's Annex 1 revision on sterile manufacturing imposes real-time environmental monitoring mandates for biological active substances. Facilities without automated viable particle detection face 24-month retrofit timelines. German and Swiss CMOs with pre-validated isolator lines capture sponsor audits that previously circulated to lower-cost Southern European alternatives.
CDMO selection criteria now weight geographic redundancy above unit cost, with sponsors requiring dual-sourced cytokine supply across FDA and EMA jurisdictions. Contract language increasingly specifies qualified backup sites with pre-approved comparability protocols. This behavioral shift concentrates procurement among networks with validated mirror facilities, disadvantaging single-site specialists regardless of technical capability.
Global Cytokine Market Segmentation
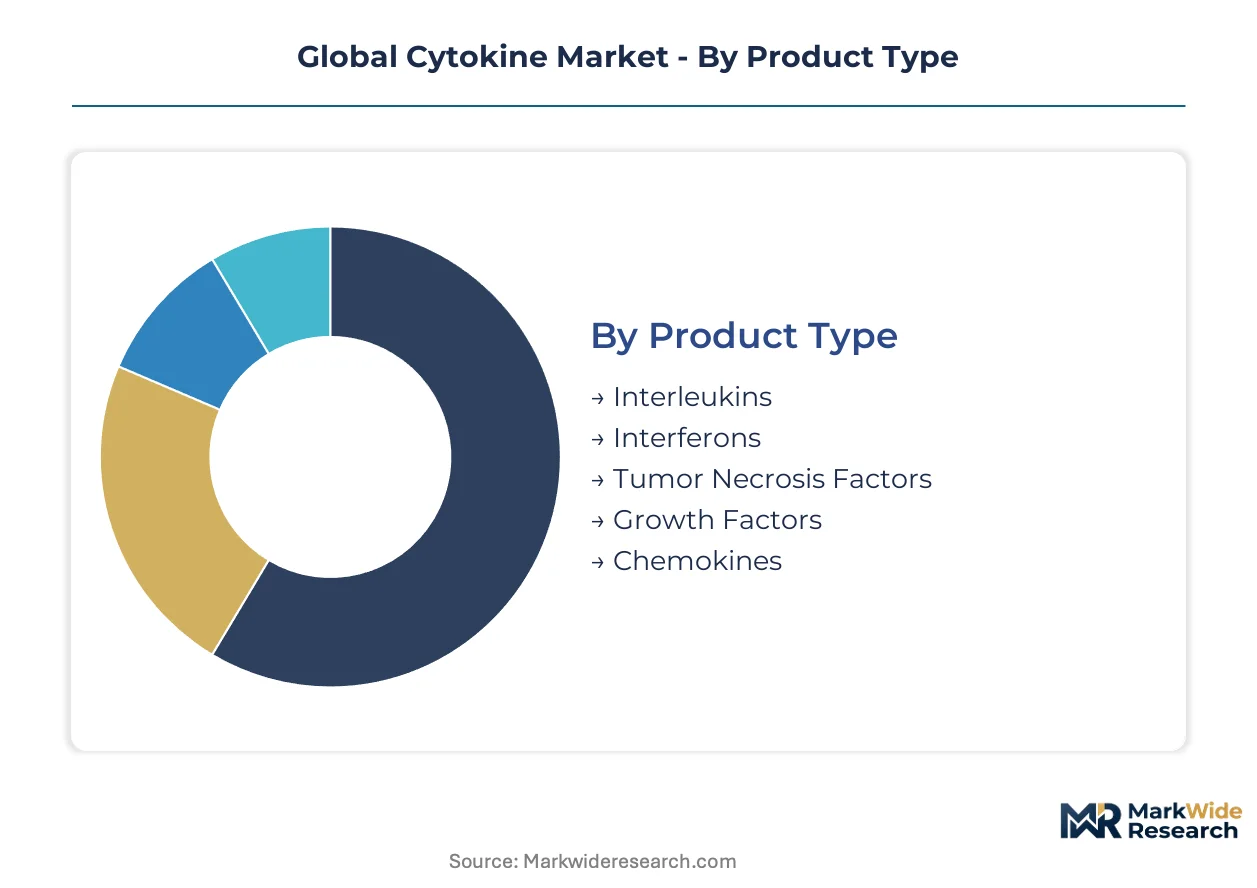
Cytokine market segmentation reveals divergent substitution pressures across molecular classes, with engineered formats displacing native proteins in premium indications while commodity recombinant supply serves volume-driven research applications.
Product Type:
Interleukins face intensifying substitution pressure from bispecific antibodies and cell therapy modalities, while interferon portfolios confront direct biosimilar competition.
- Interleukins:Glycosylated signaling proteins regulate immune cell differentiation and activation. Demand concentrates in immuno-oncology protocols across the United States and Germany, where CAR-T expansion protocols consume clinical-grade IL-2 and IL-15 at scale.
- Interferons:Antiviral and immunomodulatory cytokines historically dominated hepatitis and multiple sclerosis therapy. Japanese and Swiss biopharmaceutical sponsors now specify next-generation pegylated variants for oncology combinations, though pricing pressure from biosimilar entrants constrains margin expansion.
- Tumor Necrosis Factors:Pro-inflammatory mediators with established roles in rheumatoid arthritis and psoriasis management.
- Growth Factors:Hematopoietic and tissue repair proteins supporting cell culture media and regenerative medicine applications.
- Chemokines:Directional signaling molecules guiding immune cell trafficking in preclinical research and diagnostic assay development.
Interleukins anchor the volume base while nanoparticle-engineered cytokine variants gain share at the steepest rate.
Application:
Cost tier differentiation separates validated therapeutic indications from exploratory research funding streams.
- Immunotherapy:Checkpoint inhibitor combinations and adoptive cell therapies drive specification of high-potency interleukins. Sponsors in the United States and Germany pre-position GMP supply contracts before Phase II readouts.
- Cancer Research:Preclinical and clinical investigation of cytokine modulation in solid tumor microenvironments. Academic medical centers in Japan and Switzerland consume research-grade materials for mechanistic studies.
- Infectious Disease:Antiviral interferon protocols and vaccine adjuvant development.
- Autoimmune Disorders:Anti-inflammatory cytokine modulation in rheumatology and dermatology.
- Tissue Regeneration:Growth factor applications in wound healing and orthobiologics.
Immunotherapy commands premium pricing while cancer research generates the highest unit volumes.
End User:
Customer type determines quality tier requirements and procurement sophistication.
- Biopharmaceutical Companies:Integrated developers and emerging biotechnology sponsors specify GMP-grade cytokines for clinical manufacturing. FDA and EMA master file cross-referencing capabilities dominate supplier selection criteria.
- Contract Research Organizations:CDMOs and clinical trial service providers aggregate demand across sponsor portfolios. German and Swiss CMOs with dual FDA-EMA facility qualifications capture procurement consolidation.
- Research Institutes:Academic laboratories and government research centers.
- Diagnostic Laboratories:Clinical reference labs and in vitro diagnostic manufacturers.
Biopharmaceutical companies anchor the volume base while contract research organizations expand procurement share most rapidly.
Delivery Technology:
Supply concentration in expression platform licensing shapes competitive access.
- Recombinant Expression:CHO and E. coli systems remain the dominant manufacturing modality. Three licensable high-titer platforms control access, constraining bargaining power for emerging developers.
- Nanoparticle Delivery:Lipid and polymer encapsulation systems improve pharmacokinetics and reduce systemic toxicity. Sponsors specify these formats in the majority of new immuno-oncology INDs.
- Monoclonal Antibody-Based:Cytokine-antibody fusion constructs for targeted delivery.
- Protein Engineering:Site-specific modification and half-life extension technologies.
Recombinant expression anchors the volume base while nanoparticle delivery climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Switzerland, where FDA and Swissmedic validation commands 40-60% premiums over comparable supply from emerging manufacturing jurisdictions. Germany and Japan extract intermediate premiums through EMA centralized procedures and PMDA's regenerative medicine framework. India and China compete on cost but face extended viral clearance validation timelines that delay market entry.
United States
FDA Breakthrough Therapy designations for interleukin-2 variants and CAR-T expansion protocols drive clinical-grade cytokine consumption. The agency's biologics license application requirements mandate documented viral clearance for four model viruses, elevating compliance costs for foreign entrants. Massachusetts and California biotech clusters concentrate sponsor headquarters and GMP manufacturing investments.
Germany
EMA centralized procedures enable pan-European distribution from single manufacturing authorizations, concentrating demand on suppliers with EU QP-release capabilities. The country's national pharmaceutical regulator enforces Annex 1 sterile manufacturing revisions that mandate automated viable particle detection. Bavaria and Baden-Württemberg host the densest concentration of contract manufacturing organizations with dual FDA-EMA qualifications.
Switzerland
Swissmedic's alignment with FDA and EMA standards attracts sponsors seeking streamlined multi-jurisdiction filings for engineered cytokine formats. Basel and Zurich pharmaceutical clusters integrate discovery-stage biotech with large-scale protein manufacturing infrastructure. The country's regenerative medicine product framework supports combination cell-cytokine development timelines.
Japan
PMDA's regenerative medicine product framework offers conditional approval routes that reward early GMP investment with accelerated revenue recognition. Tokyo and Osaka academic medical centers consume research-grade materials for mechanistic studies of cytokine modulation in solid tumor microenvironments. The agency's fast-track pathway for approved US/EU biologics enables rapid biosimilar interleukin entry.
India
CDSCO fast-track pathways for approved US/EU biologics enable rapid market entry for biosimilar interleukins through local clinical trial waivers. Hyderabad and Mumbai manufacturing clusters compete on recombinant protein production costs but face 12-18 month facility qualification delays for viral clearance validation. The country's contract research organizations aggregate demand across international sponsor portfolios.
Global Cytokine Market Competitive Landscape
Concentration sits with large-cap biopharmaceutical incumbents possessing decades of mammalian cell culture infrastructure and validated viral clearance protocols. Mid-cap developers and contract manufacturers occupy differentiated positions through flexible single-use platforms and geographic redundancy offerings. Three strategic archetypes dominate: integrated biopharmaceuticals with legacy interferon portfolios, specialized cytokine suppliers serving research-grade demand, and diversified life science tools conglomerates. Competitive moves center on GMP capacity pre-positioning before Phase II readouts and CDMO procurement consolidation around dual-jurisdiction qualified facilities.
Among integrated biopharmaceuticals, Amgen Inc. and F. Hoffmann-La Roche AG exemplify archetypes navigating the transition from established cytokine franchises toward next-generation interleukin modulators. Bio-Techne Corporation occupies a position among academic and preclinical end users through high-purity research-grade supply. These three entities represent the spectrum from large-scale therapeutic manufacturing to specialized discovery-stage provision.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Amgen Inc. |
| F. Hoffmann-La Roche AG |
| Novartis AG |
| Johnson & Johnson |
| Pfizer Inc. |
| Sanofi SA |
| Bio-Techne Corporation |
| Thermo Fisher Scientific Inc. |
| Others |
Supply & Pricing Matrix
FDA and EMA viral clearance validation protocols gate both supply qualification and price differentiation simultaneously, creating a bifurcated market where dual-jurisdiction certified cytokine supply commands substantial premiums over single-qualified alternatives. Sponsors pre-position manufacturing commitments before Phase II readouts, compressing negotiation leverage and locking in multi-year offtake terms.
Pricing Analysis
Configured-to-order pricing for engineered interleukin variants spreads 40-60% above standard research-grade recombinant cytokines. Three-tier pricing structure across premium, standard, and economy levels reflects quality grade differentiation and FDA master file cross-referencing capabilities. Cost compression in research-grade supply is intensifying because biosimilar interferon entrants expand manufacturing capacity. Academic laboratories exhibit highest price sensitivity; immuno-oncology sponsors at Phase III stage show lowest.
Supply Chain Analysis
Strategic stockpile preferences dominate sponsor procurement as dual-sourcing mandates replace just-in-time inventory practices. Supply concentrates in the United States, Germany, and Switzerland where GMP facility qualifications anchor production. CHO cell line licensing, Protein A chromatography resin, and single-use bioreactor assemblies constitute critical input dependencies. Single-source vulnerability in CHO expression platform licensing creates supply chain risk. Distribution runs through contract research organizations with validated mirror facilities across FDA and EMA jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cytokine market sits in early-cycle expansion as CAR-T and TIL protocols convert research-grade suppliers into GMP contract manufacturers. Cell therapy adoption tailwinds justify capacity pre-positioning ahead of clinical demand inflection.
For Market Incumbents: Shield established interferon franchises from biosimilar erosion by accelerating next-generation interleukin-2 variant development. Secure dual FDA-EMA facility qualifications before competitor brownfield conversions complete. Backward integration into CHO cell line development reduces dependency on three dominant licensable platforms.
For New Entrants and Emerging Players: Flexible single-use manufacturing services for mid-cap biotech sponsors represents an under-served service layer where incumbents under-serve. Target German and Swiss CMO procurement consolidation with pre-validated isolator line offerings. Capture sponsor audits through geographic redundancy guarantees rather than unit cost competition.
For Investors and Strategic Acquirers: Japan PMDA's regenerative medicine framework conditional approval routes reshape the acquisition landscape toward combination cell-cytokine developers with early GMP investment. Five-to-ten year viability favors contract manufacturers with validated viral clearance protocols over discovery-stage platform plays. Watch EMA Annex 1 sterile manufacturing revision compliance timelines as inflection indicator for facility retrofit capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| GMP Capacity Pre-Positioning | Early manufacturing investment secures sponsor commitments before Phase II data readouts compress available slots. |
| Dual-Jurisdiction Facility Qualification | FDA and EMA mirror site validation enables geographic redundancy premiums in CDMO procurement consolidation. |
| Engineered Cytokine Format Development | Site-specific PEGylation and Fc-fusion engineering fragments demand toward high-margin custom constructs. |
| Continuous Bioprocessing Adoption | Integrated perfusion chromatography systems unlock brownfield site conversions in high-cost manufacturing geographies. |
| Cell Therapy Partnership Structuring | CAR-T and TIL protocol supply agreements convert research-grade relationships into clinical-grade revenue streams. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with biopharmaceutical development executives, regulatory affairs leads, GMP facility managers, and cell therapy manufacturing specialists; and secondary validation through FDA biologics license applications, EMA centralized procedure submissions, ClinicalTrials.gov cytokine protocol registrations, and CDSCO fast-track pathway determinations. Bottom-up demand modeling from end-user procurement patterns triangulated against top-down supply capacity assessments.
Across the analysis window, forecasts reflect segmented modeling across product type, application, end user, delivery technology, and regional regulatory cluster dimensions. CAGRs derived from historical volume trajectories, sponsor pipeline advancement rates, and facility qualification timeline distributions. Cell therapy expansion protocol adoption curves and biosimilar interferon entry velocity served as industry-specific forecast inputs.
Underlying assumptions cover viral clearance validation timeline stability and CHO platform licensing concentration, with deviation risk concentrated in accelerated approval pathway timeline compression and protein A resin supply interruptions. Revision becomes warranted when cell therapy manufacturing demand crosses pre-positioned GMP capacity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Vaccine Ampoules Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market
Biopharmaceuticals
Anti-Neprilysin Market
Biopharmaceuticals
Global Carboprost Tromethamine Market
Biopharmaceuticals
Italy Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Recombinant Human Interferon Protein Market
Biopharmaceuticals
Insulin Pens Market
Biopharmaceuticals
Global Flu Vaccine Market
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
Latin America Human Insulin Drugs Market
Biopharmaceuticals
Targeted Protein Degradation Market
Biopharmaceuticals
Global Topical Antibiotics Market
Biopharmaceuticals
Insulin API Market
Biopharmaceuticals
Recombinant Protein Therapeutics CDMO Market
Biopharmaceuticals
6-Azauracil Market
Biopharmaceuticals
North America Biotechnology Market